
 Metamitron Herbicides Market | 2026-2036
Metamitron Herbicides Market Size, Share, and Industry Trends Forecast 2026-2036
Metamitron Herbicides Market Analytics
EU REACH is rebalancing the cost-of-entry calculus for metamitron manufacturers seeking active substance renewal in Europe. ADAMA leverages its integrated synthesis capabilities to navigate regulatory dossier requirements across multiple member states. Syngenta anchors its position through deep formulation expertise in suspension concentrate technologies. UPL Limited extends its reach via established distribution partnerships with agricultural cooperatives in Eastern European beet-growing territories.
Metamitron is a selective triazinone herbicide with a molecular weight of 202.2 g/mol, functioning through photosystem II inhibition to control broadleaf weeds and grasses in sugar beet and fodder beet crops. The compound requires precise soil moisture conditions for activation, with application timing critical during pre-emergence to early post-emergence crop stages. Liquid formulations occupy the largest volume share among product types due to ease of tank-mixing and uniform field coverage. Suspension concentrate variants represent the fastest-expanding formulation segment as farmers prioritize reduced dust exposure and improved operator safety. Cereals application trails sugar beet in absolute volume but shows structural growth from off-label use in minor grain markets.
EMA, EFSA, and the EU Green Deal collectively govern metamitron's continued market access through residue limit setting, ecological risk assessment, and sustainable use directive alignment. The F-Gas Regulation indirectly pressures formulation facilities to adopt lower-emission manufacturing processes for solvent-based emulsifiable concentrates. Stakeholders must monitor the pending renewal assessment timeline for metamitron's inclusion in EU-approved active substance lists.
Market Dynamics
EU REACH renewal timelines for metamitron are compressing manufacturer decision windows, forcing active substance dossier investments before 2025 regulatory deadlines while beet sugar farmers accelerate pre-buying to hedge supply continuity risks.
Growth Catalysts
- REACH compliance urgency:German sugar beet cooperatives are stockpiling metamitron ahead of potential regulatory gaps, creating near-term demand spikes independent of acreage expansion.
- Suspension concentrate adoption:Eastern European farm operators are prioritizing water-based formulations over emulsifiable concentrates to reduce solvent exposure and simplify tank-cleaning protocols.
- Nord-Pas-de-Calais cultivation intensity:France's dominant sugar beet region maintains per-hectare herbicide application rates above EU averages, anchoring volume commitments.
Market Restraints
- Active substance concentration:Manufacturing capacity for triazinone chemistry concentrates in China and India, exposing buyers to freight volatility and currency fluctuation risks.
- Soil moisture dependency:Metamitron's photosystem II inhibition requires precise pre-emergence moisture conditions, limiting reliable application windows in drought-prone beet-growing districts.
- EU F-Gas Regulation:Solvent-based formulation facilities face capital-intensive emission control retrofits, pressuring margin structures for emulsifiable concentrate producers.
Strategic Opportunities
- Poland's beet expansion:Eastern European sugar beet acreage growth outpaces Western EU replacement rates, creating distribution partnership openings for established suppliers.
- Off-label cereal applications:Minor grain markets in Romania and Bulgaria are experimenting with metamitron for broadleaf weed control in winter wheat, expanding addressable crop portfolios.
- EU Green Deal alignment:Farmers achieving sustainable use directive compliance through precision application technologies gain preferential access to cooperative procurement channels.
Industry Challenges
- Formulation chemist scarcity:Suspension concentrate development requires specialized expertise in particle size distribution and stabilizer systems that outpaces current training pipeline output.
- Dossier compilation timelines:EU active substance renewal submissions demand multi-year toxicological and ecotoxicological studies that strain R&D budgeting cycles.
- Cooperative buying consolidation:Agricultural purchasing groups are centralizing metamitron tenders, compressing supplier margins through volume-based negotiation leverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metamitron Herbicides Market |
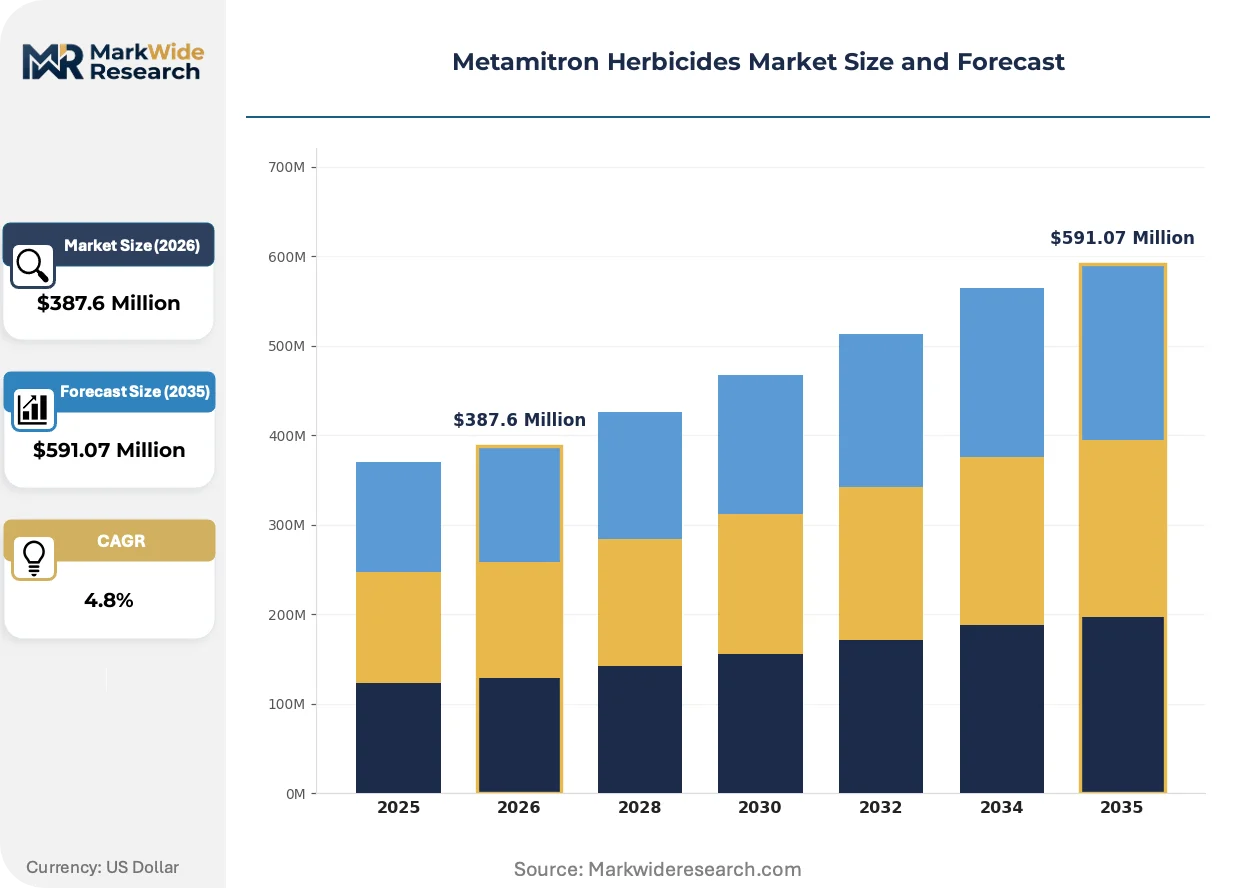
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Liquid, Powder, Suspension Concentrate Application: Cereals, Vegetables, Fruits, Industrial Crops Formulation: Emulsifiable Concentrate, Soluble Powder, Wettable Powder, Suspension End User: Farmers, Agricultural Cooperatives, Distributors, Retailers |
| Companies Covered | ADAMA, UPL Limited, Syngenta, Sumitomo Chemical, FMC Corporation, BASF, Nufarm, Shandong Weifang Rainbow Chemical, Corteva Agriscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metamitron Herbicides Market Evolving Landscape
Formulation chemistry and application precision are converging to reshape metamitron deployment patterns. Water-based delivery systems are gaining preference over solvent carriers. Regulatory compliance tooling is becoming a competitive differentiator.
Suspension concentrate technology is overtaking emulsifiable concentrate formats in European sugar beet applications. French and German farm operators are adopting SC variants at accelerating rates to eliminate solvent handling hazards and reduce drift potential. This shift is compressing demand for traditional EC formulations while rewarding manufacturers with integrated aqueous processing capabilities.
The EU F-Gas Regulation is mandating solvent emission reductions across agrochemical formulation facilities. Manufacturing sites producing emulsifiable concentrates face retrofit requirements for vapor recovery and closed-system transfer. Eastern European production facilities serving beet-growing markets are most affected, with several operators accelerating aqueous formulation line investments to maintain market access.
Cooperative procurement consolidation is altering distribution channel economics. Agricultural purchasing groups in Germany and France are centralizing metamitron tenders and demanding extended payment terms from suppliers. This concentration is most visible in the Nord-Pas-de-Calais region, where sugar beet-dedicated cooperatives now control the majority of crop protection procurement decisions and are unbundling technical advisory services from product supply.
Metamitron Herbicides Market Segmentation
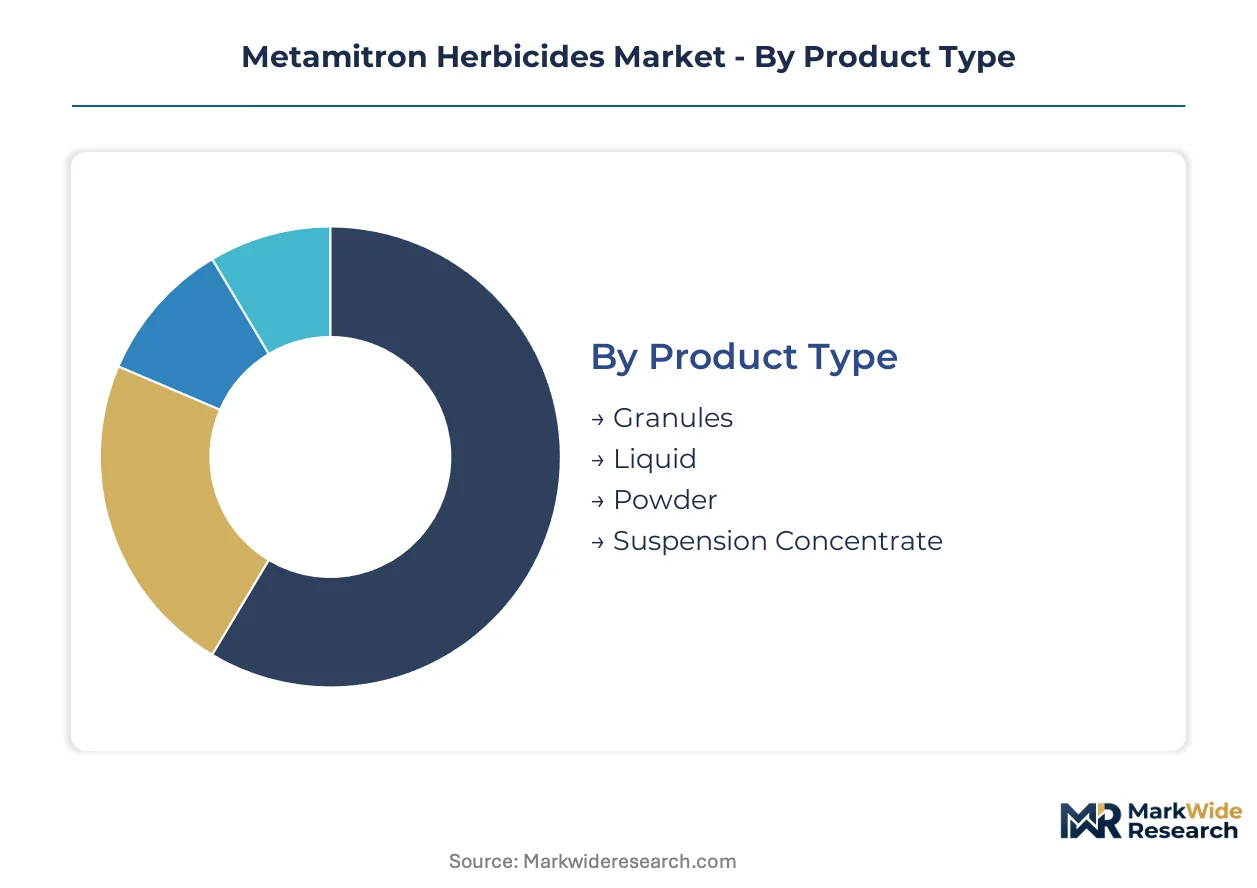
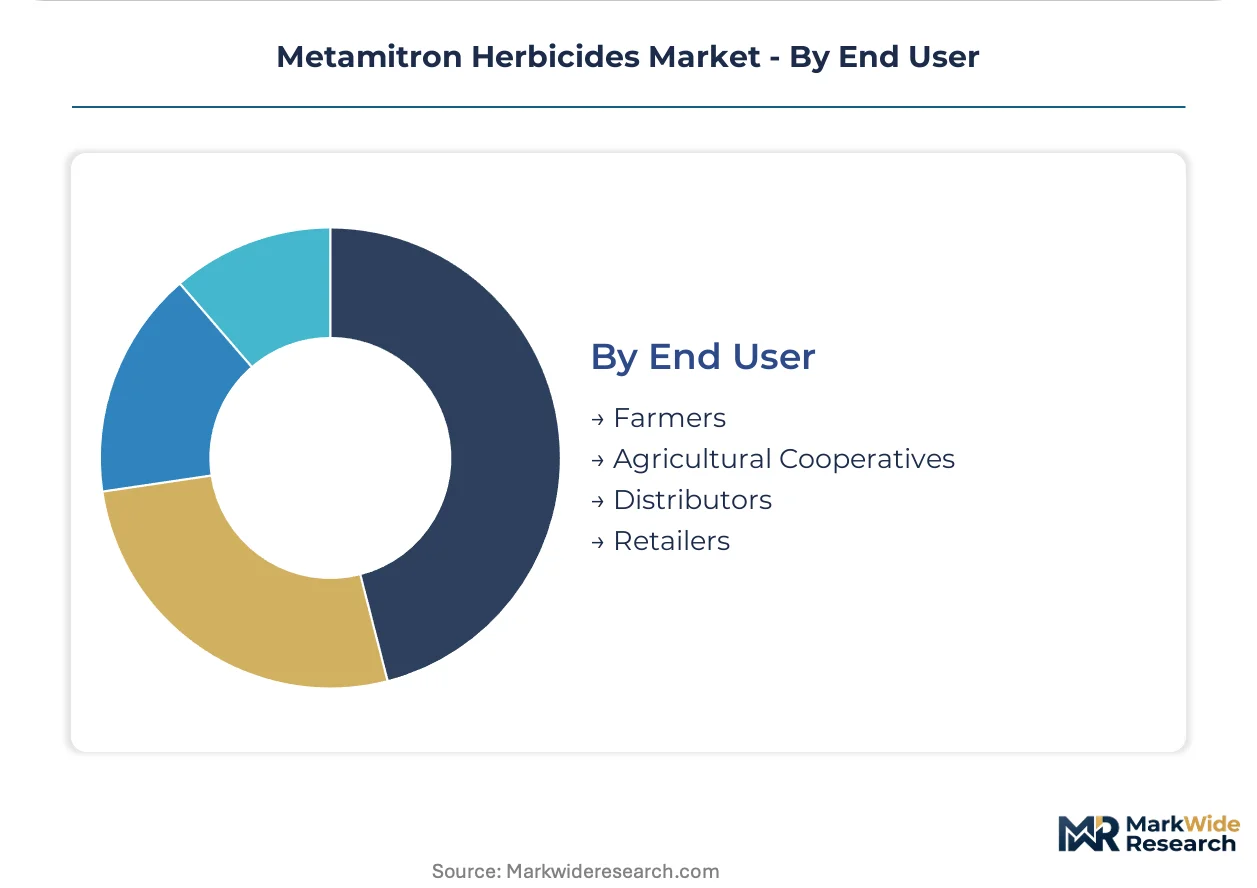
Segmentation in the metamitron herbicides market reveals how formulation chemistry and procurement channel structures determine competitive positioning. Product type and end-user concentration patterns expose where supply bottlenecks and margin compression risks concentrate.
Product Type:
Manufacturing capacity for metamitron concentrates in aqueous and solvent-based systems, with facility investments tilting toward water-compatible processing lines.
- Liquid:Emulsifiable concentrate and suspension concentrate variants dominate procurement volumes due to ease of tank-mixing compatibility with sugar beet spray programs. Demand clusters in France's Nord-Pas-de-Calais region where cooperative purchasing groups specify liquid delivery for mechanized application fleets.
- Suspension Concentrate:Water-based formulations displace solvent carriers as ECHA REACH compliance tightens volatile organic compound thresholds. Eastern European beet farmers prioritize SC variants to reduce operator exposure and simplify equipment cleaning protocols between crop rotations.
- Granules:Solid carrier systems serve specialized pre-emergence applications requiring precise soil incorporation.
- Powder:Dry formulation demand concentrates in manual application segments with limited mechanization.
Liquid formulations absorb the bulk of installed capacity; Suspension Concentrate is expanding most quickly.
Application:
Cost tier differentiation separates commodity grain uses from high-value industrial crop protections where per-hectare spending permits premium formulation sourcing.
- Industrial Crops:Sugar beet and fodder beet cultivation anchor metamitron demand through photosystem II inhibition requirements for broadleaf weed control. Germany's beet cooperatives stockpile inventory ahead of EU REACH renewal deadlines, creating procurement surges independent of planted acreage trends.
- Cereals:Off-label experimentation in Romanian and Bulgarian winter wheat programs expands addressable volume beyond registered uses. Minor grain markets test metamitron against resistant broadleaf populations where standard chemistries fail.
- Vegetables:Specialty crop applications remain limited by residue limit constraints and harvest interval requirements.
- Fruits:Tree and vine crops show minimal adoption due to phytotoxicity risks and restrictive maximum residue limits.
Industrial Crops command the highest per-hectare application rates; Cereals demonstrate the steepest expansion trajectory from off-label adoption.
Formulation:
Customer type segmentation distinguishes cooperative procurement consolidation from fragmented retailer distribution in determining margin capture.
- Emulsifiable Concentrate:Solvent-based formulations face EU F-Gas Regulation pressure requiring vapor recovery retrofits at manufacturing facilities. Production economics deteriorate as aqueous processing lines achieve scale advantages.
- Suspension:Water-based delivery systems gain preference through reduced drift potential and simplified waste handling.
- Soluble Powder:Dry concentrate formats serve specific tank-mix compatibility requirements in custom application services.
- Wettable Powder:Dust exposure liabilities limit adoption despite lower per-unit material costs.
Emulsifiable Concentrate retains legacy volume commitments; Suspension gains share fastest from regulatory alignment.
End User:
Geographic concentration of sugar beet cultivation determines where procurement power aggregates and supplier negotiation leverage shifts.
- Agricultural Cooperatives:Purchasing groups in Germany and France centralize metamitron tenders and unbundle technical advisory from product supply. Nord-Pas-de-Calais cooperatives now control majority procurement decisions for crop protection inputs.
- Farmers:Direct procurement persists among larger beet operations with independent spray equipment and storage infrastructure.
- Distributors:Eastern European territories rely on established distribution partnerships for supply security amid regulatory uncertainty.
- Retailers:Fragmented point-of-sale channels face margin compression from cooperative buying consolidation.
Agricultural Cooperatives concentrate procurement volume; Distributors retain fastest channel expansion in Poland's beet-growing districts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's Nord-Pas-de-Calais sugar beet zone concentrates metamitron procurement through cooperative purchasing power. ECHA REACH renewal timelines compress supply security decisions across European beet-growing territories.
Germany
Lower Saxony's beet cooperatives stockpile metamitron ahead of active substance renewal deadlines. ECHA dossier requirements force manufacturers into multi-year toxicological investments. The Magdeburg-Börde district anchors pre-emergence herbicide application intensity for industrial sugar beet cultivation.
France
Nord-Pas-de-Calais maintains per-hectare metamitron application rates above EU averages through intensive sugar beet monoculture. EFSA residue limit assessments govern harvest interval compliance for export-bound production. Lille-based cooperatives now control majority procurement decisions and unbundle technical advisory from product supply.
Poland
Greater Poland Voivodeship drives Eastern European beet acreage expansion outpacing Western EU replacement rates. EU Green Deal sustainable use directives reward precision application technology adoption. Poznań-region distributors secure supply partnerships amid regulatory uncertainty from REACH renewal gaps.
Romania
Off-label metamitron experimentation in winter wheat programs expands addressable volume beyond registered sugar beet uses. National agricultural regulator phytosanitary approvals lag Western EU harmonization timelines. The Banat plain tests photosystem II inhibition against resistant broadleaf populations where standard chemistries fail.
India
Maharashtra and Gujarat concentrate triazinone manufacturing capacity for export formulation. CDSCO pesticide registration requirements diverge from EU dossier standards, creating parallel compliance tracks. Mumbai-Pune chemical corridor facilities face freight volatility and currency fluctuation exposure serving European beet markets.
Metamitron Herbicides Market Competitive Landscape
European formulators anchor one tier; Asian synthesis specialists hold upstream concentration. The vendor base stratifies across integrated multinationals with dossier capabilities, regional formulation specialists with distribution depth, and contract manufacturers serving active ingredient supply. Three archetypes dominate: REACH-compliant integrated players, cooperative-anchored distribution specialists, and cost-positioned Asian suppliers. Competitive moves concentrate on aqueous formulation line investments and cooperative procurement consolidation.
Within the integrated multinational tier, ADAMA leverages synthesis-to-distribution integration across multiple EU member states. Syngenta anchors suspension concentrate expertise through formulation technology positions. UPL Limited occupies cooperative distribution depth in Eastern European beet territories. These three exemplify how regulatory dossier capabilities, aqueous processing investments, and agricultural cooperative relationships determine competitive positioning amid REACH renewal compression.
| Leading Market Players |
|---|
| ADAMA |
| UPL Limited |
| Syngenta |
| Sumitomo Chemical |
| FMC Corporation |
| BASF |
| Nufarm |
| Shandong Weifang Rainbow Chemical |
| Corteva Agriscience |
| Others |
Value Network & Pricing Analysis
Formulation chemist scarcity in the Mumbai-Pune chemical corridor amplifies labor-cost differentials between suspension concentrate specialists and commodity emulsifiable concentrate producers, widening pricing spreads across premium aqueous and economy solvent-based tiers.
Pricing Analysis
Short lead-time premiums command significant markups as German beet cooperatives stockpile metamitron ahead of ECHA REACH renewal deadlines. Three-tier pricing structure across premium suspension concentrate, standard emulsifiable concentrate, and economy technical-grade levels separates formulation sophistication from basic active ingredient supply. Cost compression in the economy tier is intensifying because Chinese and Indian manufacturers face freight volatility and currency fluctuation exposure. Agricultural cooperatives in France's Nord-Pas-de-Calais region exhibit the lowest price sensitivity due to centralized procurement power, while fragmented Eastern European retailers face the highest margin pressure.
Supply Chain Analysis
Single-source vulnerability sits with triazinone active ingredient synthesis concentrated in Maharashtra and Gujarat, India, and select coastal provinces in China. Manufacturing draws from aniline-derived intermediates, cyanuric chloride coupling agents, and specialized suspension stabilizers. Regulatory restriction risk from EU F-Gas Regulation solvent emission mandates threatens legacy emulsifiable concentrate production economics. Distribution runs through agricultural cooperative purchasing groups in Western Europe and established distributor partnerships in Poland's expanding beet-growing districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH compliance functions as a formidable barrier-to-entry moat, with active substance renewal dossiers demanding multi-year toxicological investments that strain R&D budgeting cycles for non-integrated players.
For Market Incumbents: Lock in cooperative procurement relationships through extended formulation advisory services bundled with supply contracts. Prioritize aqueous processing line investments in Eastern European facilities to preempt F-Gas Regulation retrofit requirements. Threat of cooperative buying consolidation compresses supplier margins through volume-based negotiation leverage. For New Entrants and Emerging Players: The premium-to-economy price-point gap in suspension concentrate formulations offers white-space entry for mid-tier aqueous specialists. Poland's beet acreage expansion outpaces Western EU replacement rates, creating distribution partnership openings. Romania and Bulgaria's off-label cereal experimentation presents the most penetrable application expansion. Go-to-market through precision application technology bundling aligns with EU Green Deal sustainable use directive rewards. For Investors and Strategic Acquirers: Re-rating potential sits with integrated synthesis-to-formulation players given ECHA dossier capability scarcity. Long-term viability favors REACH-compliant multinationals with captive triazinone production and established cooperative channel depth. Acquisition target archetype: regional formulation specialists with suspension concentrate expertise and underutilized aqueous processing capacity. Signal to watch: ECHA renewal assessment timeline announcements for metamitron's inclusion in EU-approved active substance lists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Synthesis | Captive triazinone supply secures ECHA dossier continuity against Indian and Chinese manufacturing concentration risks. |
| Aqueous Formulation Line Expansion | Water-based processing aligns with F-Gas Regulation emission mandates and cooperative procurement preferences in Germany. |
| Cooperative Procurement Partnership Deepening | Lille-based and Lower Saxony purchasing groups now control majority crop protection procurement decisions. |
| Precision Application Technology Bundling | EU Green Deal compliance rewards create preferential access to sustainable use directive-aligned procurement channels. |
| Eastern European Distribution Network Extension | Poland's Greater Poland Voivodeship beet expansion outpaces Western EU replacement rates for volume growth. |
Research Methodology
Independent corroboration across regulatory affairs directors at EU agrochemical formulators, procurement leads at German and French sugar beet cooperatives, and technical R&D managers at suspension concentrate specialists underwrites the qualitative findings. Secondary validation draws from ECHA active substance dossier submissions, EFSA residue limit assessments, EU customs trade data for triazinone imports, and SEC filings of publicly traded agrochemical multinationals. Bottom-up volume modeling from beet acreage and application rate assumptions triangulates against top-down market sizing from manufacturer capacity disclosures.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. Segmentation dimensions modeled include formulation chemistry tier, end-use crop application, procurement channel structure, and regional regulatory cluster alignment. CAGRs derive from trend-line extrapolation of historical volume trajectories adjusted for REACH renewal uncertainty and cooperative buying consolidation intensity. Industry-specific forecast inputs incorporate ECHA assessment timeline scenarios and Poland beet acreage expansion trajectories.
Inputs from ECHA pre-submission consultations and cooperative procurement managers were available through the study window; gaps in private manufacturer cost-structure data introduce uncertainty bands around margin compression estimates. Forecasts reflect assumptions regarding REACH renewal continuity and F-Gas Regulation implementation pacing. Regulatory denial, active substance substitution acceleration, or cooperative tender centralization beyond modeled thresholds could materially revise projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Iprodione Market
Crop Protection
Europe Insecticides Market
Crop Protection
China Insecticide Market
Crop Protection
Global Insecticide Seed Treatment Market
Crop Protection
Tembotrione Market
Crop Protection
Azoxystrobin Market
Crop Protection
North America Molluscicides Market
Crop Protection
Low-Odor, Enclosed-Greenhouse Foliar Protection Market
Crop Protection
India Herbicide Market
Crop Protection
Nematicides Market
Crop Protection
South America Fungicide Market
Crop Protection
Pest Resistant Crops Market
Crop Protection
North America Insecticide Market
Crop Protection
Inorganic Fungicide Market
Crop Protection
Fumigation Service Market
Crop Protection
Seed Treatment Materials Market