
 Poland Crop Protection Chemicals Market | 2026-2036
Poland Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Crop Protection Chemicals Market Analytics
Poland's agricultural buyer base is consolidating as commercial farming cooperatives expand acreage and centralize chemical procurement. Bayer CropScience AG leverages its established herbicide portfolio to anchor relationships with these consolidated buyers across Masovia and Lower Silesia. BASF SE competes through differentiated fungicide formulations targeting Poland's expanding rapeseed cultivation. UPL Limited sustains its position via broad-spectrum insecticide distribution through regional agrochemical distributors.
Crop protection chemicals encompass synthetic and biological formulations engineered to control weeds, insect pests, and fungal pathogens in agricultural systems, typically delivered as active ingredients suspended in liquid carriers or bound to granular clay matrices at specified concentrations. Herbicides dominate Poland's product type landscape as cereal monocultures drive volume demand for selective weed control agents. Fungicides represent the fastest-expanding segment as oilseed rape and winter wheat acreage intensifies disease pressure across Polish growing regions. Liquid formulations command preference among large-scale operators for precision application compatibility with modern sprayer fleets.
Poland's crop protection sector operates under EU REACH chemical registration requirements and the EU Farm to Fork Strategy's pesticide reduction mandates, enforced through the country's national plant protection service aligned with EFSA standards. Polish regulators are tightening groundwater monitoring protocols for atrazine metabolites and neonicotinoid residues, compelling reformulation investments from incumbent suppliers. Stakeholders must monitor the pace of EU Green Deal implementation in Warsaw's transposition timeline to calibrate portfolio transitions between conventional chemistry and biopesticide alternatives.
Market Dynamics
Poland's crop protection sector is undergoing structural recalibration as EU Farm to Fork Strategy pesticide reduction mandates force manufacturers to accelerate biopesticide portfolio transitions while maintaining efficacy benchmarks for cereal and oilseed growers.
Growth Catalysts
- EU Green Deal transposition:Poland's national plant protection service is channeling subsidy flows toward integrated pest management adoption, creating procurement pull from grain cooperatives in Greater Poland Voivodeship.
- Precision application hardware:Modern sprayer fleets equipped with GPS-guided variable-rate technology are expanding addressable market for liquid formulation compatibility.
- Rapeseed cultivation expansion:Oilseed rape acreage intensification across Masovia and Lower Silesia is generating fungicide demand for sclerotinia and phoma control.
Market Restraints
- Active ingredient cost volatility:Glyphosate and neonicotinoid precursor supply concentration in Chinese manufacturing creates input price instability for Polish formulators.
- Groundwater monitoring protocols:EFSA-aligned atrazine metabolite detection thresholds are forcing reformulation investments that compress margin structures for legacy herbicide portfolios.
- Biological substitute performance gap:Biopesticide efficacy consistency in Polish climatic conditions lags synthetic chemistry, limiting grower switching willingness in high-pressure disease years.
Strategic Opportunities
- Sub-regional distributor consolidation:Regional agrochemical distributors in Podlaskie and Lublin Voivodeships remain fragmented, creating acquisition targets for national platform buildout.
- Drone-based application services:Unmanned aerial systems paired with micro-encapsulated formulations are opening precision spot-spray channels for smaller Polish holdings.
- Carbon credit alignment:EU Common Agricultural Policy eco-scheme payments for reduced pesticide use are creating price-premium capture potential for certified sustainable formulations.
Industry Challenges
- Regulatory compliance timeline compression:REACH registration renewal cycles for existing active ingredients are shortening, straining Polish regulatory affairs capacity.
- Application technician certification:EU Sustainable Use Directive mandating professional user training is creating bottlenecks in qualified sprayer operator availability across rural Poland.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Crop Protection Chemicals Market |
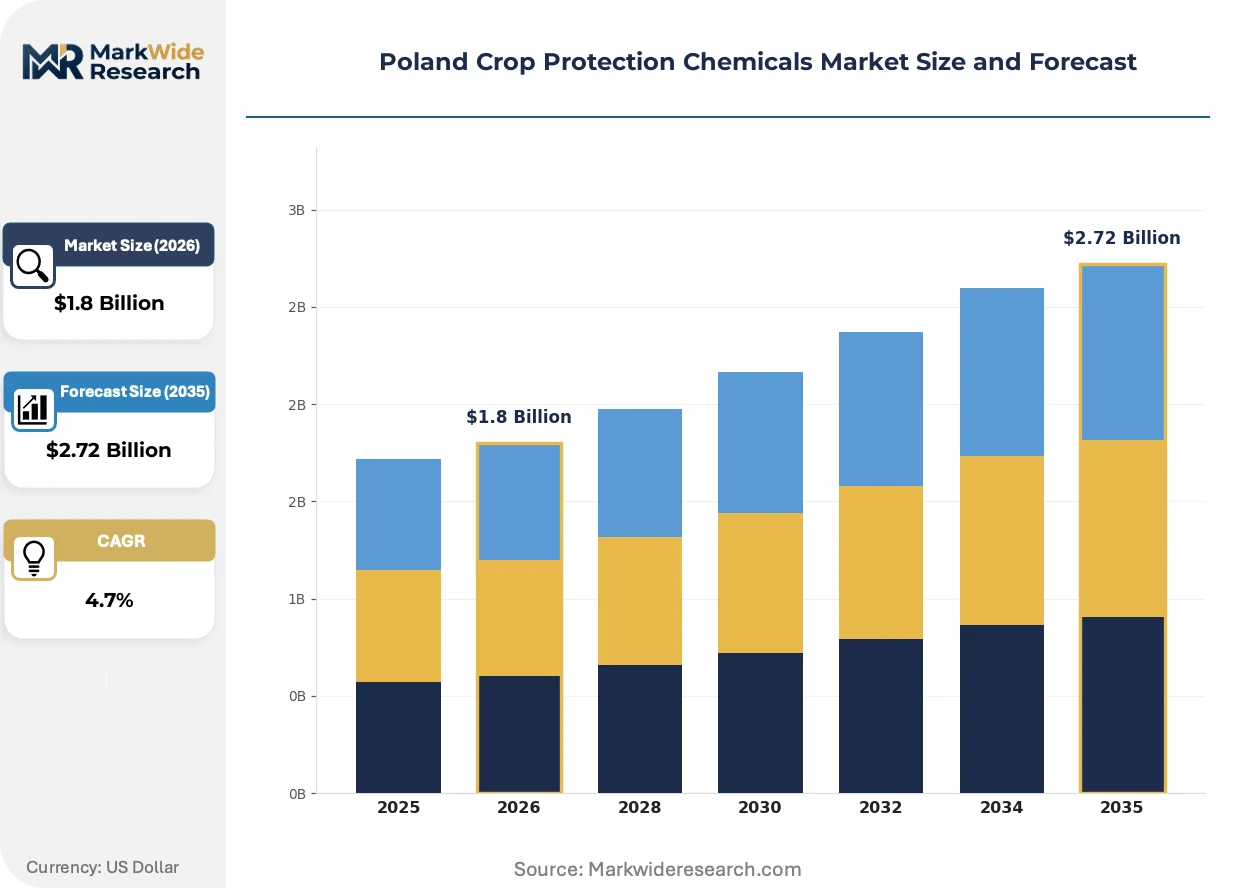
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Pesticides Application: Cereals, Oilseeds, Fruits, Vegetables Form: Granules, Liquids, Powders, Emulsifiable Concentrates Distribution Channel: Retail, E-commerce, Direct Sales, Distributors |
| Companies Covered | UPL Limited (Arysta LifeScience), Corteva Agriscience, Syngenta International AG, CIECH Group, Bayer CropScience AG, BASF SE, FMC Corporation, Synthos S A, Adama Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Crop Protection Chemicals Market Evolving Landscape
Formulation chemistry and application methodology are converging to address the tension between yield protection requirements and environmental compliance pressures in Polish agriculture.
Micro-encapsulation technology is integrating sustained-release active ingredient delivery with reduced drift characteristics. Large-scale cereal farming operations in Greater Poland Voivodeship are adopting these formulations at accelerating pace to maintain weed control windows while satisfying buffer zone restrictions. This integration is compressing demand for conventional emulsifiable concentrates in high-value crop segments.
EU Farm to Fork Strategy pesticide reduction targets are tightening maximum residue limits across import-sensitive commodities. Polish rapeseed exporters are facing reinforced third-country market access barriers, compelling fungicide program adjustments toward lower-residue chemistries. Winter wheat and malting barley growers are responding fastest, prioritizing pre-harvest interval compliance over absolute cost minimization.
Cooperative procurement centralization is consolidating chemical purchasing decisions into fewer professional buyers. Regional grain cooperatives are displacing individual farm input selection, shifting volume leverage toward integrated program suppliers and compressing distributor margins. This concentration is most visible in Masovia, where three procurement alliances now control over half of cereal protection chemical spending.
Poland Crop Protection Chemicals Market Segmentation
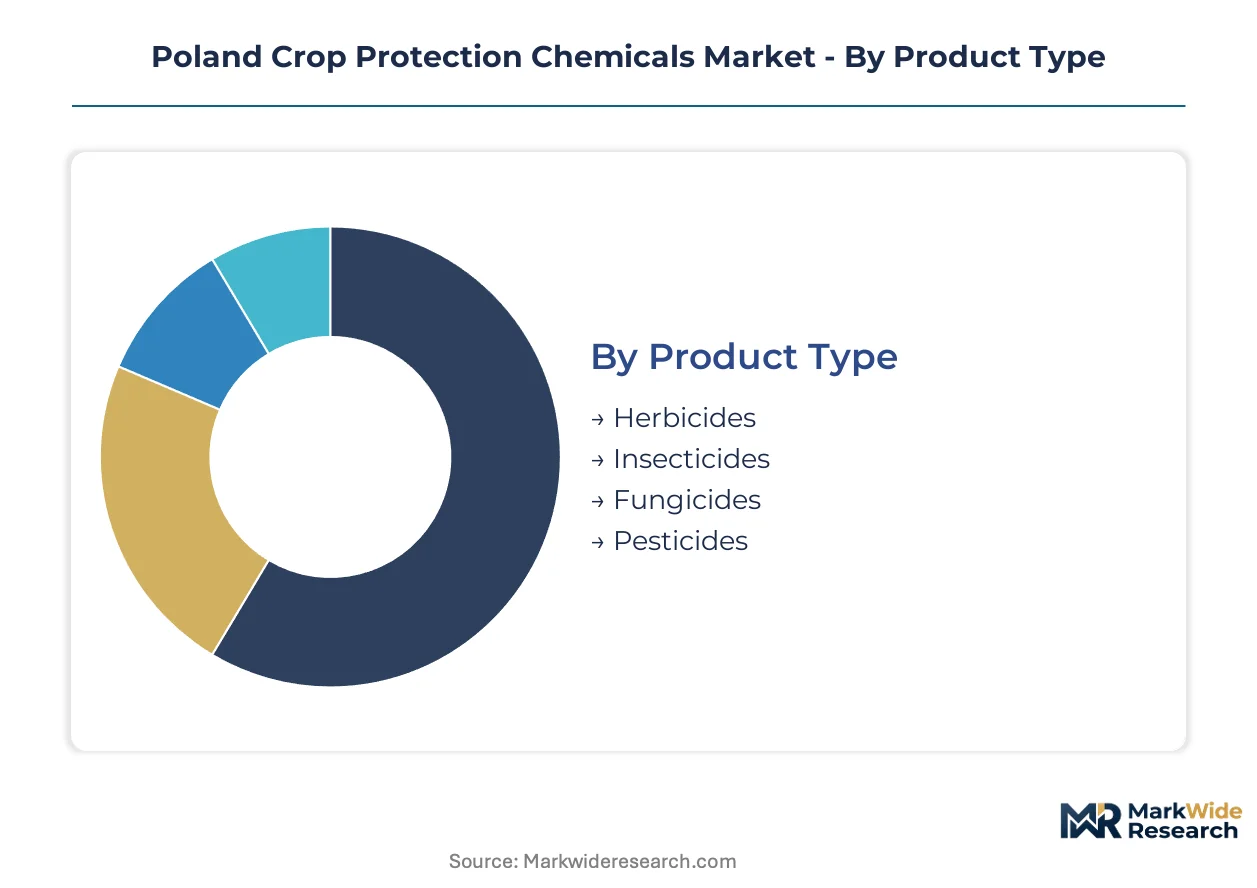
Poland's crop protection chemicals market fragments across four critical dimensions that shape procurement patterns and manufacturer strategy. Understanding these segment boundaries reveals where volume concentrates, how application technology evolves, and which channels capture margin in a market consolidating around cooperative purchasing.
Product Type:
Supply concentration among active ingredient manufacturers in China and India directly shapes which chemistry families dominate Polish formulator portfolios.
- Herbicides:Selective and non-selective weed control agents formulated around glyphosate, atrazine, and sulfonylurea chemistry. Volume demand concentrates in Greater Poland Voivodeship's cereal monocultures where cooperative procurement alliances prioritize cost-efficient broad-acre programs. EFSA-aligned groundwater monitoring protocols for atrazine metabolites are forcing reformulation investments that compress legacy portfolio margins.
- Fungicides:Systemic and contact formulations targeting sclerotinia, phoma, and septoria pathogens in oilseed and cereal systems. Demand is climbing fastest across Masovia and Lower Silesia as rapeseed acreage expansion intensifies disease pressure and growers prioritize pre-harvest interval compliance for export market access.
- Insecticides:Neonicotinoid, pyrethroid, and biological formulations for pest suppression in diverse cropping systems. Polish regulators are tightening residue thresholds for legacy chemistries under EU Sustainable Use Directive implementation.
- Pesticides:Broad-spectrum synthetic and bio-based formulations encompassing acaricides, nematicides, and molluscicides for specialized crop protection needs. Niche applications in high-value vegetable production around Warsaw and Krakow sustain limited volume.
Today's leader: Herbicides. Tomorrow's challenger: Fungicides.
Application:
Cost tier differentiation separates commodity grain protection from premium horticultural programs where residue compliance commands price premiums.
- Cereals:Winter wheat, spring barley, and triticale dominate Poland's arable landscape. Large-scale operations in Greater Poland Voivodeship drive herbicide volume through centralized cooperative procurement, while malting barley growers prioritize fungicide programs that satisfy brewing industry maximum residue limits.
- Oilseeds:Winter rapeseed cultivation generates intensive fungicide demand for sclerotinia stem rot and phoma leaf spot control. Masovia's expanding oilseed acreage is pulling manufacturer technical support resources toward disease monitoring and resistance management protocols.
- Fruits:Apple, cherry, and berry production in Podlaskie and Lublin Voivodeships requires integrated pest management programs with extended pre-harvest intervals. Polish orchardists face reinforced EU Farm to Fork Strategy residue targets on export-bound consignments.
- Vegetables:Protected and open-field production of brassicas, root crops, and solanaceous vegetables around Warsaw and Krakow demands specialized insecticide and fungicide rotations. Smaller holding structures sustain distributor channel relevance in this fragmented segment.
Cereals anchor current volume. Oilseeds are gaining share fastest as crop rotation economics shift.
Form:
Application technology compatibility determines formulation preference as precision agriculture hardware penetrates Polish farming operations.
- Liquids:Suspension concentrates and soluble liquids engineered for compatibility with GPS-guided variable-rate sprayer fleets. Greater Poland Voivodeship's large-scale cereal operators are standardizing on liquid delivery systems that enable section control and drift reduction.
- Granules:Clay-bound active ingredient matrices for soil-incorporated application in row crops and horticultural systems. Persistent demand in vegetable production around Krakow where mechanical incorporation replaces aerial or broadcast methods.
- Powders:Wettable powder and water-dispersible granule formulations for dry blending and tank-mix flexibility. Regional distributors in Podlaskie maintain powder inventories for smaller holdings with limited storage infrastructure.
- Emulsifiable Concentrates:Traditional solvent-based formulations facing displacement as environmental buffer zone restrictions tighten and operators seek reduced-drift alternatives. Legacy demand persists among cost-sensitive cooperative members in Lower Silesia.
Liquids lead precision adoption. Micro-encapsulated variants are climbing fastest as buffer zone compliance intensifies.
Distribution Channel:
Customer type concentration into cooperative procurement alliances is reshaping channel power and margin capture across Polish agrochemical distribution.
- Distributors:Regional agrochemical specialists providing technical support, credit terms, and logistics to farm enterprises. National platform consolidation targets in Podlaskie and Lublin Voivodeships where fragmentation sustains independent distributor relevance.
- Direct Sales:Manufacturer-to-cooperative contracts bypassing intermediary margins for volume commitments. Masovia's three dominant procurement alliances now transact directly with multinational suppliers for cereal protection programs.
- Retail:Farm supply stores and cooperative outlets serving smaller holdings and horticultural producers. Physical presence remains critical in vegetable-growing clusters around Krakow where immediate availability outweighs price optimization.
- E-commerce:Digital platforms emerging for standardized product categories with established specifications. Limited penetration in crop protection due to regulatory consultation requirements and application timing constraints.
Distributors retain horticultural access. Direct sales are capturing grain cooperative volume fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's crop protection sector operates at roughly triple Poland's scale, yet Warsaw's regulatory implementation timeline for EU Farm to Fork mandates is accelerating faster than Berlin's transposition pace. This divergence creates distinct competitive dynamics across Central European agricultural input markets.
Greater Poland Voivodeship
Cereal monocultures spanning Poznań and Kalisz drive Poland's highest herbicide procurement volumes through centralized cooperative purchasing. EFSA-aligned groundwater monitoring protocols for atrazine metabolites are forcing legacy product reformulations. Large-scale farming operations in Konin County are standardizing on liquid formulations compatible with GPS-guided variable-rate sprayer fleets.
Masovia Voivodeship
Expanding winter rapeseed acreage around Warsaw intensifies fungicide demand for sclerotinia stem rot control. Poland's national plant protection service channels CAP eco-scheme subsidies toward integrated pest management adoption. Three dominant procurement alliances now control over half of cereal protection chemical spending in the region.
Lower Silesia
Oilseed cultivation growth near Wrocław generates parallel fungicide requirements alongside established cereal protection programs. REACH registration renewal cycles are shortening for existing active ingredients, straining local regulatory affairs capacity. Distributor consolidation remains incomplete in peripheral districts, sustaining independent channel relevance.
Podlaskie Voivodeship
Apple and berry production clusters near Białystok require extended pre-harvest interval programs for export compliance. EU Sustainable Use Directive mandates for professional sprayer operator certification are creating qualified technician bottlenecks. Regional agrochemical distributors maintain powder formulation inventories for smaller holdings with limited storage infrastructure.
Lublin Voivodeship
Horticultural operations around Lublin and Zamość sustain specialized insecticide demand for protected vegetable production. Fragmented distributor networks present acquisition targets for national platform buildout. E-commerce penetration remains limited due to regulatory consultation requirements and application timing constraints.
Poland Crop Protection Chemicals Market Competitive Landscape
German and Swiss producers anchor the premium chemistry tier; Indian and Israeli specialists hold cost-competitive manufacturing positions. Poland's crop protection sector exhibits consolidated multinational dominance at the top, with regional distributors retaining fragmented horticultural access. Two strategic archetypes define competitive positioning: integrated program suppliers capturing cooperative procurement alliances, and formulation specialists serving crop-specific disease pressures. Dominant competitive moves include direct manufacturer-to-cooperative contract structures and micro-encapsulation technology licensing for buffer zone compliance.
Within the integrated multinational tier, Bayer CropScience AG and BASF SE exemplify archetypes anchored by broad herbicide and fungicide portfolios respectively. UPL Limited occupies a position bridging cost-efficient manufacturing scale with regional distribution reach. These three entities represent the competitive spectrum from premium chemistry leadership through value-optimized supply, each calibrated to distinct buyer consolidation stages across Polish agricultural cooperatives.
| Leading Market Players |
|---|
| UPL Limited (Arysta LifeScience) |
| Corteva Agriscience |
| Syngenta International AG |
| CIECH Group |
| Bayer CropScience AG |
| BASF SE |
| FMC Corporation |
| Synthos S A |
| Adama Ltd |
| Others |
Value Network & Pricing Analysis
Micro-encapsulation technology adoption across Greater Poland Voivodeship's cereal cooperatives is simultaneously elevating formulation costs and concentrating procurement leverage among buyers with precision application fleets. This dual compression squeezes legacy emulsifiable concentrate margins while rewarding suppliers who integrate sustained-release chemistry with buffer zone compliance.
Pricing Analysis
Capacity additions in China's glyphosate precursor manufacturing are reshaping price floors for Polish formulators sourcing sulfonylurea and neonicotinoid active ingredients. Three-tier pricing structure across premium micro-encapsulated, standard suspension concentrate, and economy emulsifiable concentrate levels stratifies by application technology compatibility and residue compliance certification. Cost compression in the economy tier intensifies because EFSA-aligned groundwater monitoring protocols force reformulation investments. Grain cooperatives in Masovia exhibit highest price sensitivity, while malting barley growers prioritize pre-harvest interval compliance over absolute cost minimization.
Supply Chain Analysis
REACH registration renewal cycles and EU Farm to Fork Strategy compliance certifications gate supplier access to Poland's national plant protection service procurement channels. Active ingredient manufacturing concentrates in China, India, and Germany, with Polish formulators drawing from Chinese glyphosate and Indian pyrethroid production. Raw material dependencies span atrazine precursors, neonicotinoid intermediates, and biological fermentation substrates. Single-source vulnerability in Chinese glyphosate precursor supply creates input price instability. Distribution runs through regional agrochemical specialists in peripheral voivodeships and direct manufacturer-to-cooperative contracts in consolidated grain regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's crop protection sector represents a late-cycle quality story as EU Farm to Fork Strategy residue targets redirect demand toward certified low-residue formulations that command price premiums in export-bound rapeseed and malting barley channels.
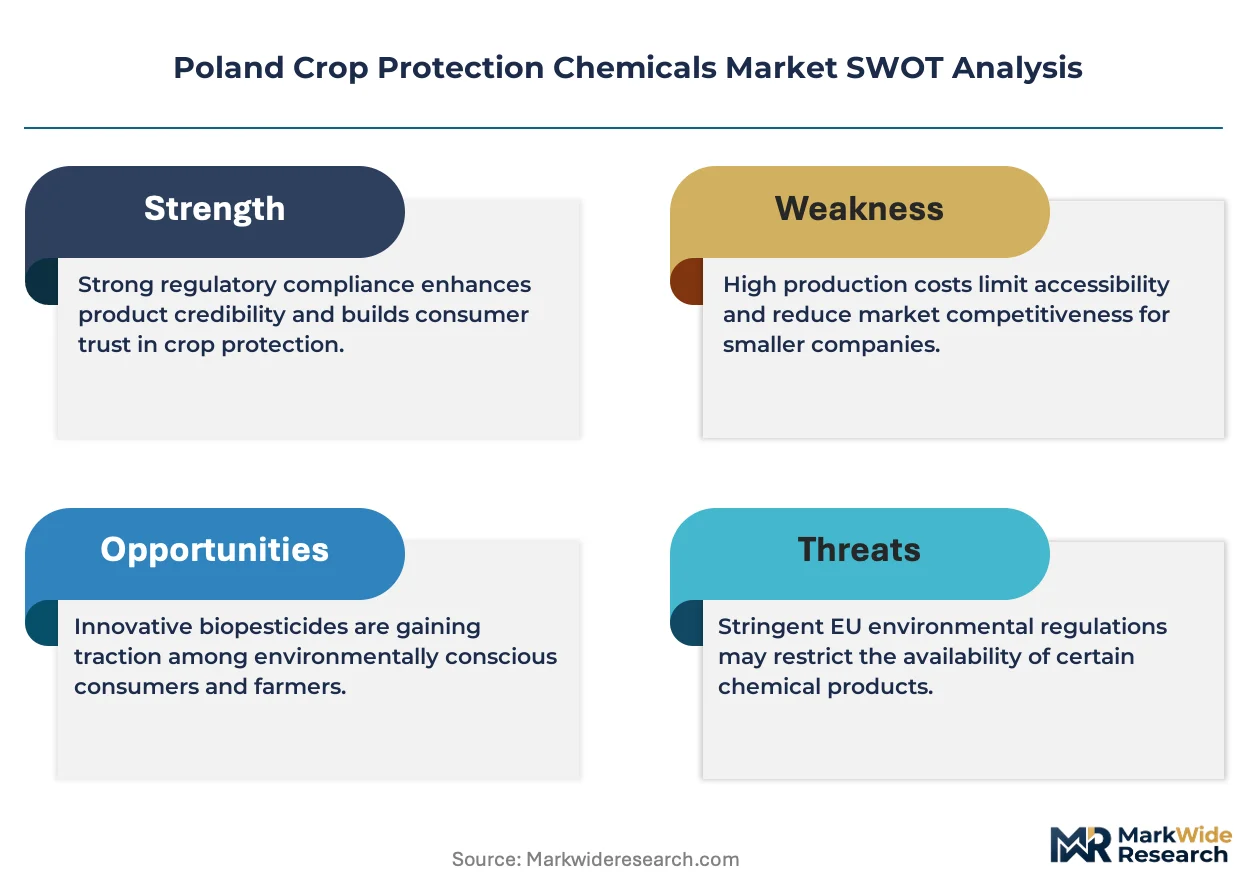
For Market Incumbents: Hedge synthetic chemistry margin erosion by accelerating biopesticide portfolio transitions and securing backward integration into biological fermentation capacity. Biological substitute performance gaps in Polish climatic conditions threaten grower switching willingness during high-pressure disease years. Micro-encapsulation technology licensing offers defensive positioning against buffer zone restriction tightening. For New Entrants and Emerging Players: Launch via drone-based application service partnerships targeting Podlaskie and Lublin Voivodeship orchardists and vegetable growers with fragmented distributor access. White-space concentration sits in precision spot-spray channels for smaller Polish holdings under 50 hectares. Regulatory consultation bundling with micro-encapsulated formulations provides differentiated go-to-market positioning against commodity suppliers. For Investors and Strategic Acquirers: Roll-up economics work for regional agrochemical distributors because fragmentation in Podlaskie and Lublin sustains independent channel relevance while national cooperative procurement centralizes volume leverage elsewhere. Five-to-ten year viability hinges on biopesticide formulation capability acquisition. Acquisition target archetype: regional distributors with established biological product registration portfolios. The signal to watch is Warsaw's transposition pace for EU Green Deal pesticide reduction mandates as inflection indicator for portfolio transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biological Fermentation | Captures margin from biopesticide demand growth under EU Farm to Fork Strategy mandates. |
| Micro-Encapsulation Technology Licensing | Enables buffer zone compliance for Greater Poland cereal operators facing EFSA-aligned restrictions. |
| Regional Distributor Acquisition | Builds national platform presence in fragmented Podlaskie and Lublin horticultural channels. |
| Direct Manufacturer-to-Cooperative Contracts | Bypasses intermediary margins for volume commitments from Masovia procurement alliances. |
| Drone-Based Application Service Partnerships | Opens precision spot-spray channels for smaller Polish holdings with limited sprayer infrastructure. |
Research Methodology
Multiple input streams — structured interviews with agrochemical formulator technical directors, cooperative procurement managers, and regional distributor principals; secondary validation through EU REACH registration databases, Polish Central Statistical Office agricultural input surveys, and EFSA pesticide residue monitoring reports; plus customs trade data on active ingredient imports — were reconciled through bottom-up volume modeling and top-down market sizing triangulation.
Historical volume trajectories were cross-referenced against expert panel assessments of regulatory implementation pace and technology adoption curves across the projection horizon. Segmentation dimensions modeled include product type chemistry family, application crop category, formulation physical state, and distribution channel structure. CAGRs were derived from growth driver quantification and constraint boundary analysis. Industry-specific forecast inputs encompassed rapeseed acreage expansion rates and precision agriculture hardware penetration in cooperative fleets.
Several conditions sit outside the modeled scope, including abrupt regulatory reversals in EU Farm to Fork Strategy implementation, geopolitical disruption of Chinese active ingredient supply corridors, and breakthrough biological efficacy improvements that collapse synthetic chemistry demand. Forecasts reflect underlying assumptions about subsidy continuity and grower behavior stability. Deviation in Warsaw's transposition timeline for EU Green Deal mandates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Pest Control Products Market
Crop Protection
Canada Crop Protection Chemicals Market
Crop Protection
Acetochlor Herbicide Market
Crop Protection
Global Home and Garden Pesticides Market
Crop Protection
South America Molluscicides Market
Crop Protection
Corn Preemergence Herbicide Market
Crop Protection
Low-Odor, Enclosed-Greenhouse Foliar Protection Market
Crop Protection
India Crop Protection Chemicals Market
Crop Protection
Global Aquatic Herbicides Market
Crop Protection
Rodent Control Pesticides Market
Crop Protection
Metamifop Market
Crop Protection
Global Algaecides Market
Crop Protection
Chile Crop Protection Chemicals Market
Crop Protection
Tebuconazole Epoxide Market
Crop Protection
Europe Herbicide Market
Crop Protection
South Korea Crop Protection Chemicals Market