
 Corn Preemergence Herbicide Market | 2026-2036
Corn Preemergence Herbicide Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Preemergence Herbicide Market Insights
Aftermarket service revenue for agronomic advisory and resistance management programs is fragmenting across distributor networks and input manufacturers. BASF leverages its digital farming platform to bundle herbicide prescriptions with soil monitoring services. Corteva Agriscience anchors its position through proprietary seed-trait combinations that lock in preemergence chemistry pairings. Syngenta competes by extending its agronomic support infrastructure into co-op and independent retail channels.
Corn preemergence herbicides are soil-applied crop protection chemicals formulated with active ingredients such as acetochlor or S-metolachlor, designed to form a residual chemical barrier at the soil surface that inhibits weed seedling emergence before crop germination. These products function through root and shoot absorption by germinating weed seeds, providing 4-8 weeks of control against grass and broadleaf species in conventional tillage and no-till systems. Atrazine-based formulations still occupy the largest volume share in field corn applications due to cost efficiency and broad-spectrum efficacy, though S-metolachlor and flumioxazin are gaining fastest in banding and soil application methods where resistance management protocols require rotation. Sweet corn and seed corn segments sustain premium pricing for specialized low-residue chemistries that meet processor and export certification standards.
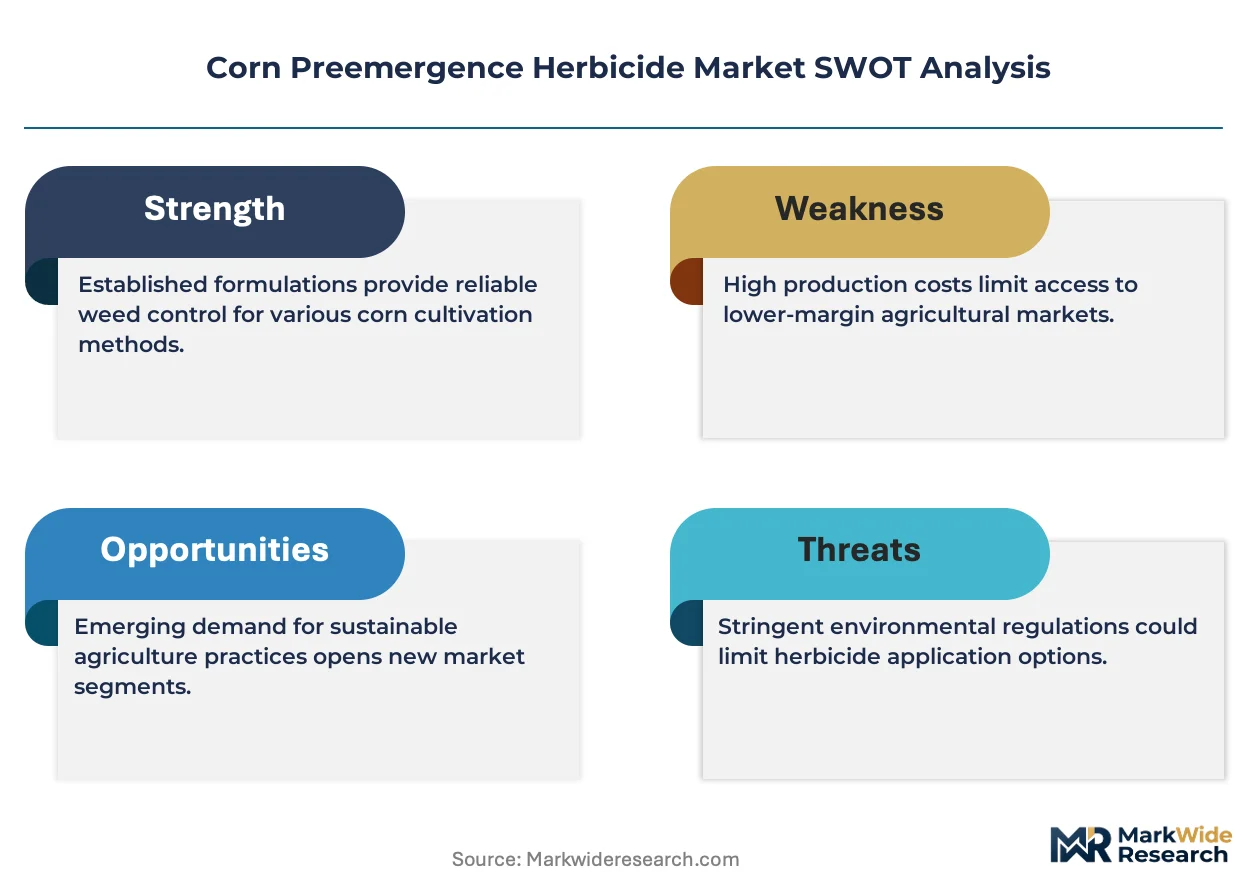
EPA re-registration timelines under the Federal Insecticide, Fungicide, and Rodenticide Act constrain acetanilide herbicide labels and drive reformulation investments, while state-level pesticide agencies in Iowa, Illinois, and Nebraska impose additional buffer zone requirements near water bodies. Brazil's national health surveillance agency and China's Ministry of Agriculture and Rural Affairs are tightening maximum residue limits for export-bound grain, forcing manufacturers to validate new active ingredient combinations. Stakeholders must monitor regulatory divergence between importing and producing countries when building regional product portfolios and resistance stewardship commitments.
Market Dynamics
Residual herbicide programs are consolidating around reduced-rate formulation technologies as EPA re-registration timelines force manufacturers to redesign acetanilide chemistries for lower application volumes per acre.
Growth Catalysts
- No-till corn expansion in Brazil:Mato Grosso state farmers are intensifying preemergence applications to manage glyphosate-resistant weed populations in continuous no-till systems.
- US EPA re-registration requirements:Chloroacetamide herbicide label renewals are accelerating investment in micro-encapsulation and safener-enhanced formulations that maintain efficacy at reduced rates.
- Soil application method innovation:Banding equipment retrofits allow precise herbicide placement that cuts per-acre active ingredient use while preserving weed control windows.
Market Restraints
- Active ingredient cost volatility:Fluctuations in petroleum-derived chemical feedstocks squeeze formulation margins and destabilize distributor pricing agreements.
- Supply concentration in Chinese manufacturing:Reliance on concentrated technical-grade production creates vulnerability to export licensing delays and freight cost spikes.
- Atrazine regulatory friction:State-level buffer zone expansions in Iowa, Illinois, and Nebraska restrict application windows and reduce treated acreage in high-density corn regions.
Strategic Opportunities
- Digital agronomy bundling:Soil monitoring platforms paired with prescription herbicide services capture recurring revenue from commercial operations seeking resistance management protocols.
- Export certification chemistries:Low-residue formulations for sweet corn and seed corn segments command premium positioning in processor contracts bound for EU and Japanese markets.
- Co-op channel infrastructure:Independent retail and agricultural cooperative networks in the US Midwest remain underpenetrated by integrated advisory-herbicide service models.
Industry Challenges
- Resistance stewardship compliance:Multi-site herbicide rotation protocols require field-level data collection that strains agronomist staffing at distributor and manufacturer levels.
- Legacy formulation registration:Older acetochlor and metolachlor labels face renewal complexity as EPA demands expanded environmental fate studies, extending product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Preemergence Herbicide Market |
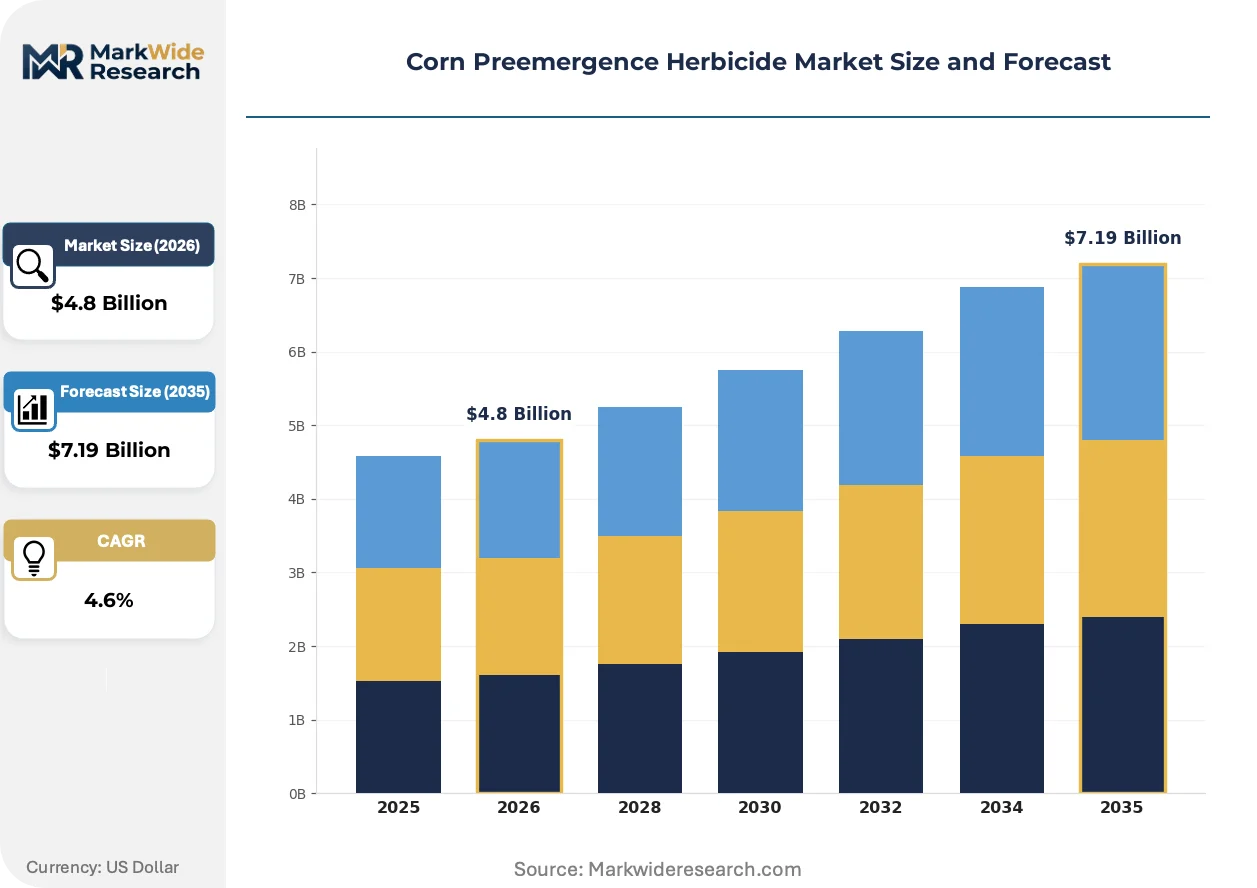
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atrazine, Metolachlor, S-Metolachlor, Flumioxazin Active Ingredient: Glyphosate, Isoxaflutole, Pendimethalin, Acetochlor Application Method: Pre-emergent, Banding, Soil Application, Granular Crop Type: Field Corn, Sweet Corn, Seed Corn, Organic Corn |
| Companies Covered | BASF, Corteva Agriscience, Syngenta, Bayer, FMC Corporation, DuPont, Nufarm Limited, ADAMA Agricultural Solutions, UPL Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Preemergence Herbicide Market Trends and Innovations
Formulation chemistry and application precision are converging to reduce per-acre active ingredient loads while maintaining residual control duration. Manufacturers are racing to embed biological safeners and micro-encapsulation into next-generation products.
Micro-encapsulated acetanilide delivery systems are virtualizing traditional emulsifiable concentrate formulations by enabling controlled release that extends efficacy windows. Large-scale Midwest operations adopting precision banding equipment are driving uptake of these advanced chemistries. The technology is virtualizing competitive positioning around application flexibility rather than raw efficacy metrics.
EPA's Federal Insecticide, Fungicide, and Rodenticide Act re-registration timelines are compressing label durations for chloroacetamide herbicides and mandating expanded groundwater monitoring. Manufacturers are responding with accelerated reformulation investments targeting reduced-rate technologies. Field corn applications face the most acute pressure as atrazine combination labels undergo simultaneous state-level buffer reviews.
Input procurement is consolidating through distributor-led agronomic advisory bundles that displace standalone chemical transactions. Commercial farming operations are shifting toward annual service contracts incorporating soil testing, prescription mapping, and resistance monitoring. This pattern concentrates most visibly in Iowa and Illinois, where co-op networks have built integrated digital infrastructure.
Corn Preemergence Herbicide Market Segmentation
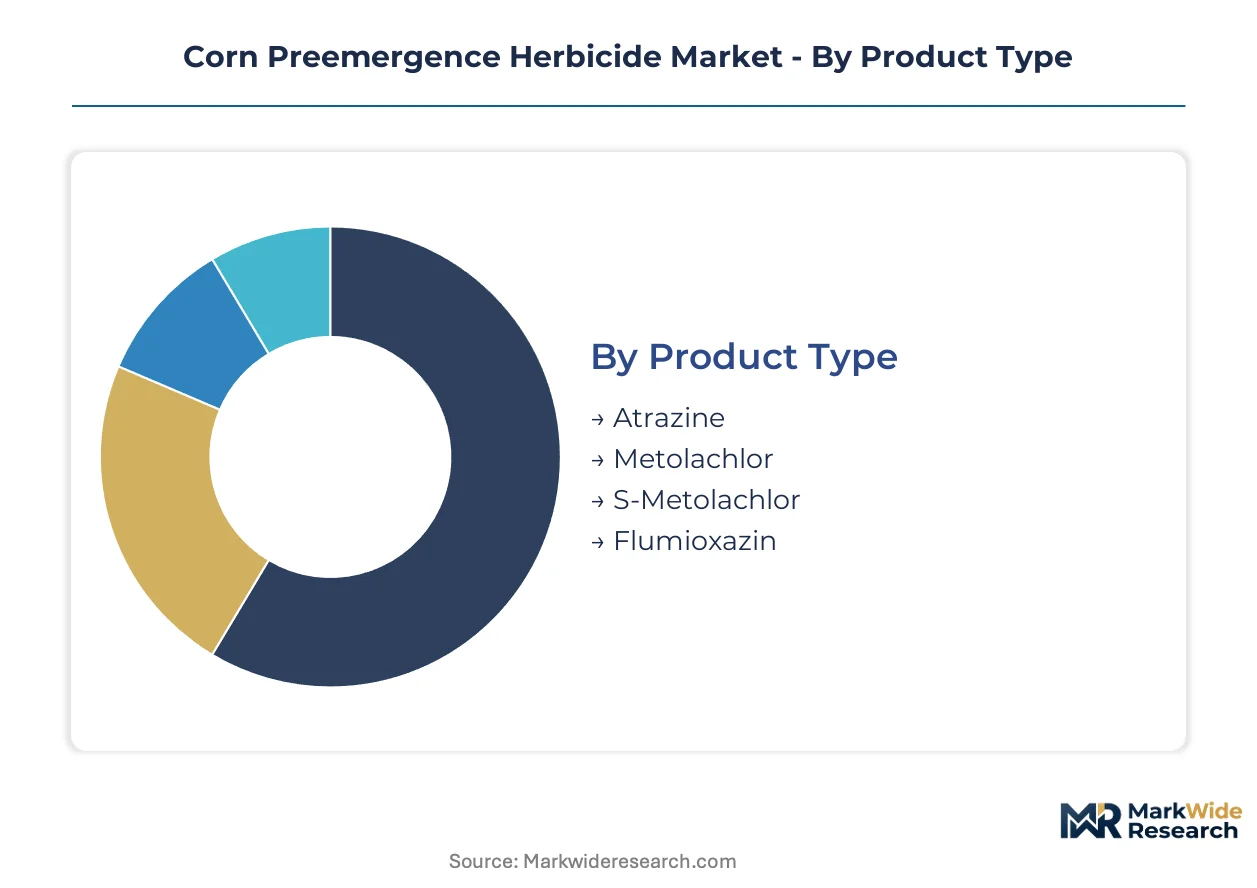
Corn preemergence herbicide segmentation reflects divergent efficacy requirements across tillage systems, residue constraints, and regulatory exposure. Manufacturers align formulation portfolios to specific crop value tiers and application equipment capabilities rather than pursuing universal chemistry platforms.
Product Type:
Product type segmentation spans the use-case spectrum from commodity cost control to resistance management premium positioning.
- Atrazine:Triazine chemistry delivers broad-spectrum grass and broadleaf control at the lowest cost per treated acre. Field corn operations in Iowa and Illinois sustain dominant volume despite EPA re-registration pressures and expanding state buffer mandates.
- S-Metolachlor:The resolved isomer formulation achieves equivalent weed control at reduced application rates compared to racemic metolachlor. Mato Grosso no-till expansion and US Midwest resistance rotation protocols drive fastest adoption among chloroacetamide alternatives.
- Metolachlor:Racemic mixture chemistry maintains cost positioning in price-sensitive distributor channels with established label registrations. Generic manufacturer competition concentrates supply in technical-grade production clusters.
- Flumioxazin:PPO-inhibitor chemistry provides residual broadleaf control and rotational flexibility for resistance management programs. Sweet corn and seed corn segments absorb premium pricing for low-residue export certification compliance.
Established volume favors Atrazine; emerging adoption favors S-Metolachlor.
Active Ingredient:
Active ingredient segmentation maps to formulation complexity tiers and regulatory renewal timelines.
- Acetochlor:Chloroacetamide chemistry with established micro-encapsulation platforms enables reduced-rate label claims. EPA re-registration demands accelerate manufacturer investment in safener-enhanced delivery systems.
- Glyphosate:Non-selective systemic herbicide functions in preemergence tank-mix combinations for burndown-plus-residual programs. Glyphosate-resistant weed proliferation in continuous no-till systems constrains standalone utility.
- Isoxaflutole:HPPD-inhibitor chemistry provides soil-applied grass and broadleaf control with rotational crop flexibility. Banding application precision expands uptake in reduced-tillage corn-soybean rotations.
- Pendimethalin:Dinitroaniline chemistry delivers preemergence grass control with low water solubility reducing leaching risk. State-level groundwater protection regulations in Nebraska elevate preference over more mobile alternatives.
Revenue concentration sits with Acetochlor; regulatory pressure is concentrating most intensely on Glyphosate.
Application Method:
Application method segmentation reflects equipment capital intensity and per-acre chemistry precision.
- Pre-emergent:Broadcast soil-surface application establishes residual chemical barrier before crop and weed emergence. Conventional tillage systems in the US Corn Belt sustain dominant equipment investment and operator training infrastructure.
- Banding:Concentrated herbicide placement in crop row zones cuts active ingredient volume by 30-50% versus broadcast. Precision agriculture retrofit adoption in Illinois and Iowa accelerates uptake of micro-encapsulated formulations optimized for narrow placement.
- Soil Application:Incorporated or surface-applied delivery without crop presence requirement accommodates varied tillage intensities. Equipment compatibility spans from conventional field cultivators to no-till drills.
- Granular:Physical formulation eliminates spray drift concerns and enables application without calibrated liquid equipment. Sweet corn and seed corn segments absorb premium positioning for processor contract compliance.
Equipment-installed base locks in Pre-emergent; precision agriculture retrofit demand is expanding Banding most quickly.
Crop Type:
Crop type segmentation separates commodity volume from certification-constrained premium positioning.
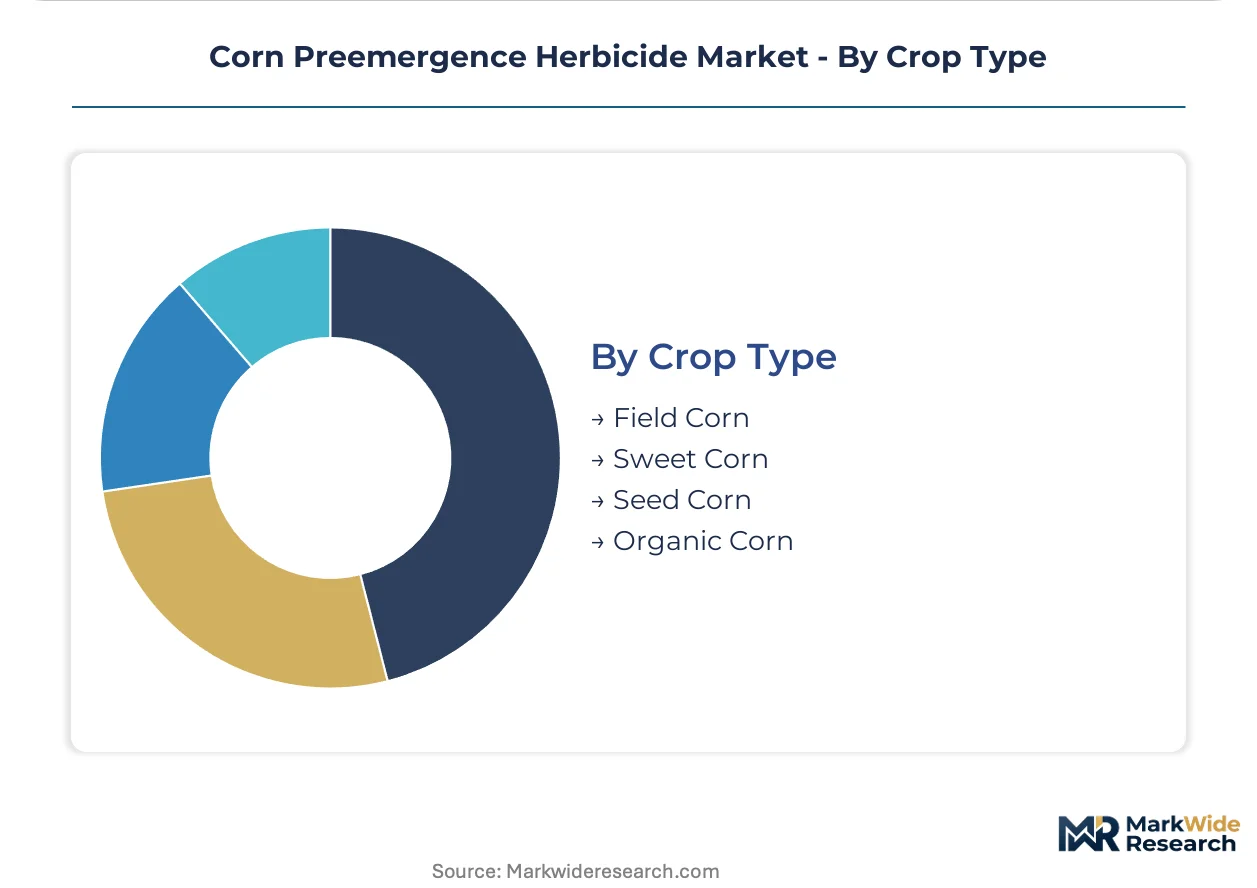
- Field Corn:Commodity grain production sustains maximum treated acreage with cost-optimized chemistry selection. Iowa, Illinois, and Nebraska operations drive formulation volume through distributor and co-op procurement channels.
- Seed Corn:Genetic purity requirements and processor export contracts mandate specialized low-residue chemistries with full traceability documentation. Premium pricing absorbs resistance stewardship and certification compliance costs.
- Sweet Corn:Processor contract specifications for EU and Japanese export markets impose maximum residue limits stricter than field corn tolerances. Regional concentration in Minnesota, Washington, and Wisconsin shapes localized formulation demand.
- Organic Corn:Synthetic herbicide prohibition eliminates conventional preemergence chemistry from certified production systems. Mechanical cultivation and approved biological inputs substitute for chemical residual control.
Volume dominance remains with Field Corn; margin extraction concentrates in Seed Corn.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between intensive no-till systems in Brazil's Mato Grosso and the buffer-constrained Corn Belt of the United States, where regulatory fragmentation reshapes formulation choices.
United States
Iowa and Illinois sustain dominant acreage treated with atrazine-based combinations, though EPA re-registration timelines under FIFRA compress label durations for chloroacetamide herbicides. State-level buffer zone expansions near water bodies in Nebraska and Indiana restrict application windows. The Des Moines-Lincoln corridor anchors distributor-led bundling of soil monitoring with prescription services.
Brazil
Mato Grosso state farmers intensify preemergence applications to manage glyphosate-resistant weed populations in continuous no-till corn expansion. ANVISA tightening of maximum residue limits for export-bound grain forces validation of new active ingredient combinations. The Sorriso-Sinop cluster concentrates procurement through integrated co-op networks serving commercial operations above 10,000 hectares.
China
Technical-grade production clusters in Jiangsu and Shandong provinces supply concentrated active ingredient volumes to global formulation manufacturers. The Ministry of Agriculture and Rural Affairs imposes stricter export licensing timelines for herbicide intermediates. Nantong and Lianyungang port infrastructure shapes freight cost volatility affecting distributor pricing agreements.
Argentina
Cordoba and Buenos Aires provinces drive residual herbicide uptake in corn-soybean rotations confronting resistant weed pressure. The national agricultural technology institute promotes resistance stewardship protocols requiring field-level data collection. Rosario trading hub concentration influences input procurement timing for the upcoming planting window.
Germany
Formulation R&D facilities in Ludwigshafen and Leverkusen anchor micro-encapsulation innovation for reduced-rate delivery systems. ECHA REACH compliance demands expanded environmental fate documentation for acetanilide chemistries. The Rhine-Ruhr industrial corridor concentrates safener-enhanced product development serving EU export certification requirements.
Corn Preemergence Herbicide Market Competitive Landscape
Capability concentration sits with integrated agronomic service platforms; scale advantage sits with technical-grade production networks. The vendor base stratifies between multinational input manufacturers bundling digital prescriptions, generic formulators competing on cost positioning, and regional distributors building advisory infrastructure. Three archetypes dominate: chemistry-integrated seed-trait platforms, standalone formulation specialists, and co-op channel service aggregators. Competitive moves center on micro-encapsulation licensing partnerships and precision application equipment retrofit alliances.
Within the integrated platform tier, BASF and Corteva Agriscience exemplify archetypes combining proprietary chemistry with digital farming infrastructure, while Syngenta occupies a position emphasizing agronomic support extension into independent retail channels. These three anchors represent divergent responses to EPA re-registration pressures—BASF through soil monitoring bundling, Corteva through seed-trait lock-ins, and Syngenta through co-op network penetration. Their positioning reflects the broader industry tension between manufacturing scale and service-layer differentiation.
| Leading Market Players |
|---|
| BASF |
| Corteva Agriscience |
| Syngenta |
| Bayer |
| FMC Corporation |
| DuPont |
| Nufarm Limited |
| ADAMA Agricultural Solutions |
| UPL Limited |
| Others |
Pricing and Supply Chain Analysis
Nantong-Lianyungang port infrastructure cost volatility feeds directly into distributor pricing power across Brazilian and US Midwest markets, compressing margins for generic formulators while amplifying premium positioning for integrated advisory-herbicide bundles. Technical-grade production concentration in Jiangsu and Shandong provinces concentrates supply-side leverage among multinational manufacturers with captive sourcing arrangements.
Pricing Analysis
Long-term offtake agreements between Mato Grosso co-ops and integrated manufacturers anchor volume pricing, while spot procurement through independent Iowa and Illinois distributors captures seasonal volatility. Three-tier pricing structure across premium, standard, and economy levels separates seed corn certification-grade formulations from commodity field corn bundles and generic racemic metolachlor. Cost compression in standard-tier chloroacetamide formulations is intensifying because EPA re-registration timelines force accelerated reformulation investments. Field corn operations exhibit highest price sensitivity; seed corn processors absorb premium positioning for residue compliance.
Supply Chain Analysis
Contract-manufacturing concentration among Jiangsu and Shandong technical-grade producers holds capacity for acetanilide and triazine active ingredients, with formulation finishing distributed across US, Brazilian, and German facilities. Petroleum-derived chemical feedstocks and specialized safener compounds constitute critical input dependencies. Single-source vulnerability in Chinese export licensing creates structural exposure to freight cost spikes and regulatory delays. Distribution runs through co-op networks in Iowa and Illinois, integrated retail channels in Mato Grosso, and independent agronomic advisory platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Micro-encapsulation formulation expertise and precision banding equipment integration represent acute capability gaps that will determine competitive survival as reduced-rate technologies displace legacy chemistries.
For Market Incumbents: Insulate proprietary chemistry positions through accelerated safener-enhanced micro-encapsulation R&D investments and exclusive precision equipment retrofit partnerships with Illinois and Iowa implement dealers. Lock in seed-trait combination pipelines before EPA label compressions force portfolio restructuring. Deepen backward integration into technical-grade production through Jiangsu province joint ventures to neutralize Chinese export licensing exposure.
For New Entrants and Emerging Players: Independent agronomic advisory infrastructure in Nebraska and Indiana co-op networks represents the most penetrable entry point, given underinvestment in soil monitoring-herbicide prescription bundling by established distributors. Sweet corn processor certification compliance services offer a second white-space target, with EU and Japanese maximum residue limit documentation as the go-to-market anchor.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors micro-encapsulation licensing specialists with EPA reduced-rate label approvals already secured. Long-term viability hinges on formulation platforms that survive atrazine regulatory friction and chloroacetamide re-registration compression. Watch for ANVISA residue limit tightening announcements as the inflection signal for accelerated Mato Grosso formulation switching.
| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Encapsulation Platform Licensing | EPA reduced-rate label claims enable 30-50% active ingredient reduction while preserving efficacy windows. |
| Precision Banding Equipment Alliance | Illinois and Iowa retrofit partnerships lock in application-method loyalty for commercial operations above 5,000 acres. |
| Seed-Trait Chemistry Lock-In | Proprietary germplasm-herbicide combinations defend share against generic formulators in field corn segments. |
| Co-Op Channel Advisory Infrastructure | Nebraska and Indiana distributor networks remain underpenetrated by integrated soil monitoring-prescription services. |
| Export Certification Chemistry Validation | ANVISA and EU maximum residue limit compliance opens premium positioning in Mato Grosso and seed corn segments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing agronomic advisors at Iowa and Illinois co-ops, procurement leads at Mato Grosso commercial operations, formulation R&D directors at German and US technical centers, and regulatory affairs specialists navigating EPA FIFRA and ANVISA re-registration timelines. Secondary validation drew from EPA label databases, ANVISA residue limit notifications, US customs import records for technical-grade herbicide intermediates, and SEC filings of listed agricultural input manufacturers. Bottom-up acreage and application-rate modeling was triangulated against top-down manufacturer revenue disclosures.
Calibration against historical label renewal timelines and no-till adoption curves anchored the projection framework across the analysis window. Segmentation dimensions modeled included active ingredient chemistry tier, application method equipment type, crop value segment, and regional regulatory cluster. CAGRs were derived from weighted scenario analysis of EPA re-registration outcomes and Brazilian no-till expansion trajectories. Forecast inputs incorporated petroleum feedstock price elasticity and Chinese export licensing delay frequencies.
Stress conditions across EPA label compression severity, ANVISA residue limit tightening pace, and Nantong port freight cost volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about resistance stewardship compliance adoption and precision agriculture equipment penetration. Quarterly review of EPA registration decision timelines and Brazilian co-op procurement contract announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
North America Insecticide Market
Crop Protection
Metamitron Herbicides Market
Crop Protection
Asia Pacific Insecticide Market
Crop Protection
US Herbicide Market
Crop Protection
Global Insect Pest Control Market
Crop Protection
Tembotrione Market
Crop Protection
Vietnam Fungicide Market
Crop Protection
Miticides Market
Crop Protection
Soil Sterilizers Market
Crop Protection
Pest Management Services Market
Crop Protection
Asia Pacific Herbicide Market
Crop Protection
Global Chlorpyrifos Market
Crop Protection
Fogger Market
Crop Protection
North America Acaricides Market
Crop Protection
United States Crop Protection Chemicals Market
Crop Protection
IPM Pheromones Market