
 Fogger Market | 2026-2036
Fogger Market Size, Share, and Industry Trends Forecast 2026-2036
Fogger Market Foresight
EPA equipment certification rules are consolidating the cost-of-entry calculus for new fogger manufacturers entering North American channels. Curtis Dyna-Fog leverages its thermal fogger heritage to sustain defense and vector-control contracts across federal procurement networks. IGEBA Gerätebau GmbH anchors European public health authority supply chains through German-engineered ULV precision systems.
A fogger is a mechanical dispersal device that converts liquid formulations into fine aerosol droplets, typically ranging from 5 to 50 microns, using thermal energy, cold air shearing, or ultra-low volume (ULV) rotary atomization; its primary industrial purpose is uniform chemical distribution across large, irregular, or enclosed spaces. Thermal foggers dominate military and mosquito abatement budgets where oil-based carrier penetration matters, while battery-operated foggers are capturing fastest growth in greenhouse and indoor agricultural settings where emission restrictions limit combustion options. Cold foggers occupy the broad commercial cleaning middle ground, competing on maintenance simplicity against electric alternatives.
FDA food-contact surface sanitation guidelines, EPA pesticide application equipment standards, and OSHA worker respiratory protection mandates collectively shape product design, droplet validation protocols, and operator training requirements across the installed base. The EU's REACH chemical authorization framework and F-Gas Regulation constrain thermal fogger refrigerant and propellant choices in European markets. Stakeholders must monitor evolving battery chemistry regulations and emerging droplet drift liability standards before committing to platform investments or geographic expansion.
Market Dynamics
EPA's revised pesticide application equipment standards are forcing droplet size verification into every fogger design cycle, compressing development timelines and raising certification costs for manufacturers targeting North American distribution channels.
Growth Catalysts
- Precision agriculture protocols:Brazilian soybean operators are expanding thermal fogger deployment for targeted pesticide application across irregular terrain. The technology reduces chemical runoff into watersheds while maintaining coverage density.
- REACH chemical authorization:European greenhouse horticulture is accelerating battery-operated cold fogger adoption to satisfy emission restrictions on oil-based thermal carriers. Dutch tomato cultivation clusters are driving regional procurement volume.
- Vector-control mandates:Municipal mosquito abatement programs in India's western states are scaling ULV rotary atomization systems. Maharashtra's public health infrastructure is prioritizing droplet uniformity for dengue suppression campaigns.
Market Restraints
- Lithium-ion cell cost volatility:Battery-operated fogger manufacturers face margin compression from cathode material price swings. Supply concentration in Chinese processing facilities amplifies input unpredictability.
- Thermal fogger refrigerant constraints:The EU's F-Gas Regulation is phasing down hydrofluorocarbon propellants used in oil-based carrier systems. Equipment retrofits add capex burden for existing installed bases.
- Electrostatic sprayer substitution:Surface disinfection buyers in commercial cleaning are pivoting toward charged-particle systems for indoor applications. Fogger suppliers lose share where dwell-time requirements favor wraparound coverage.
Strategic Opportunities
- Greenhouse horticulture scaling:India's protected cultivation area is expanding fastest in Gujarat and Maharashtra. Fogger OEMs can establish service networks before equipment standardization solidifies.
- Battery chemistry regulatory tailwinds:Emerging solid-state cell standards promise energy density gains for portable cold foggers. Early platform alignment captures performance differentiation.
- Direct-to-grower digital channels:Precision agriculture marketplaces are disintermediating traditional dealer networks. Manufacturers can capture margin and usage data through integrated IoT-enabled fogger sales.
Industry Challenges
- Droplet validation technician shortage:EPA certification requires specialized laser diffraction analysis skills. Training pipelines have not scaled with equipment testing demand.
- Legacy thermal fogger integration:Oil-based system operators face stranded asset risk as emission zones expand. Retrofit economics rarely justify platform conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fogger Market |
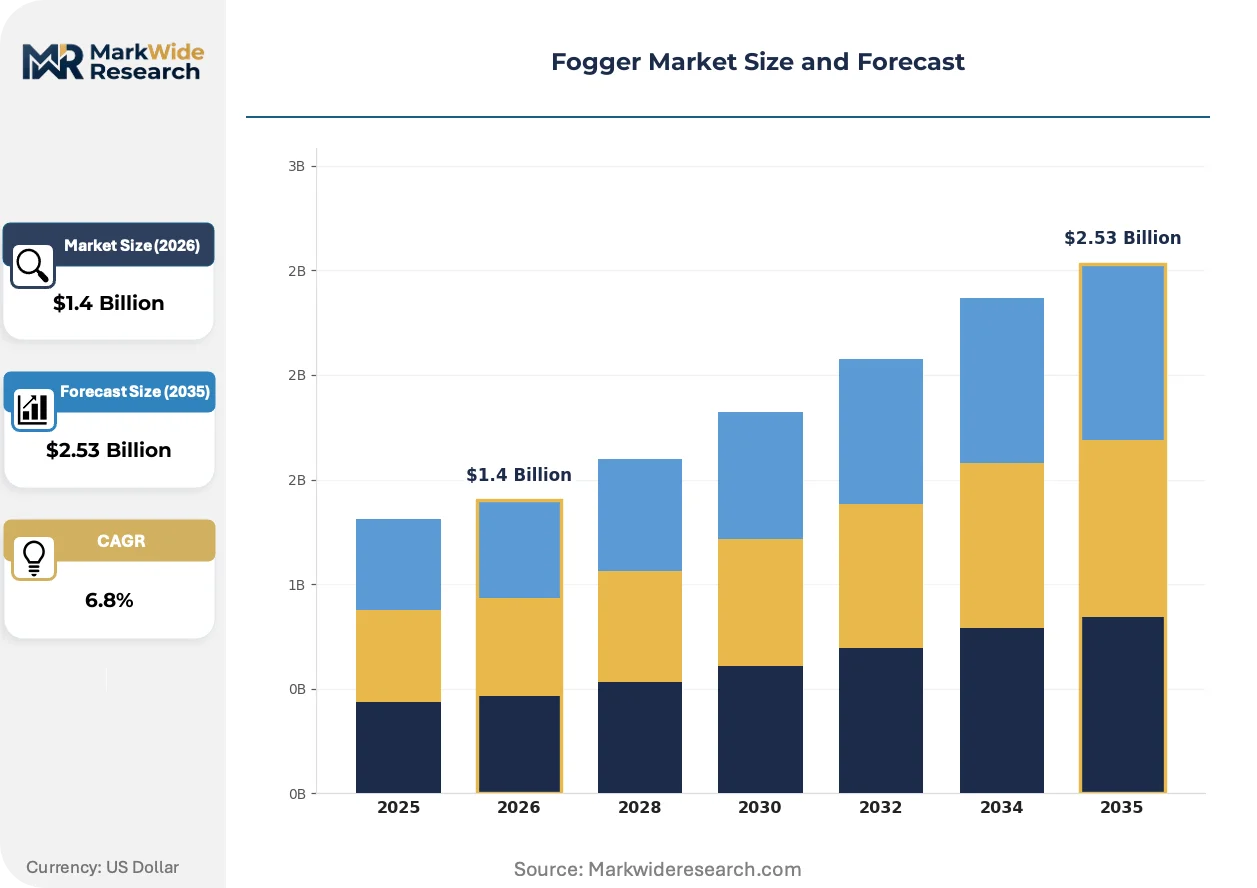
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Foggers, Cold Foggers, ULV Foggers, Battery-Operated Foggers, Electric Foggers Application: Pest Control, Disinfection, Humidification, Odor Control, Mold Remediation End User: Agricultural Operators, Commercial Cleaning Services, Public Health Authorities, Food Processing Units, Greenhouse Managers Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Industrial Suppliers, Wholesale Distributors |
| Companies Covered | Curtis Dyna-Fog, IGEBA Gerätebau GmbH, pulsFOG Dr. Stahl & Sohn GmbH, Vectorfog, TTS Group, UNA Corporation, Conic Systems, B&G Equipment Company, Shouguang Jiafu Agricultural Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fogger Market Shifts & Advancements
Electrification of atomization systems is reconfiguring competitive advantage around battery management and connected diagnostics rather than combustion engineering heritage. Three developments are compressing the innovation cycle.
Brushless DC motor-driven rotary atomizers are expanding into greenhouse and indoor agricultural settings where thermal emission restrictions previously blocked fogger deployment. Dutch and Spanish protected cultivation operators are adopting these systems for integrated pest management programs. The technology is expanding into segments that combustion platforms could not serve, creating new addressable market space for cold fogger specialists.
The EU's F-Gas Regulation is accelerating refrigerant transition timelines for thermal fogger propellant systems. Equipment manufacturers must reformulate carrier fluids or redesign heat-exchange architectures to maintain penetration performance. German-engineered ULV systems are most exposed given their dominance in European public health authority supply chains.
Outcome-based equipment leasing is displacing outright purchase in Brazilian large-scale soybean operations. Fogger OEMs are bundling droplet monitoring sensors with per-hectare service contracts. The model is concentrating in Mato Grosso and Goiás states where precision agriculture adoption is deepest.
Fogger Market Segmentation
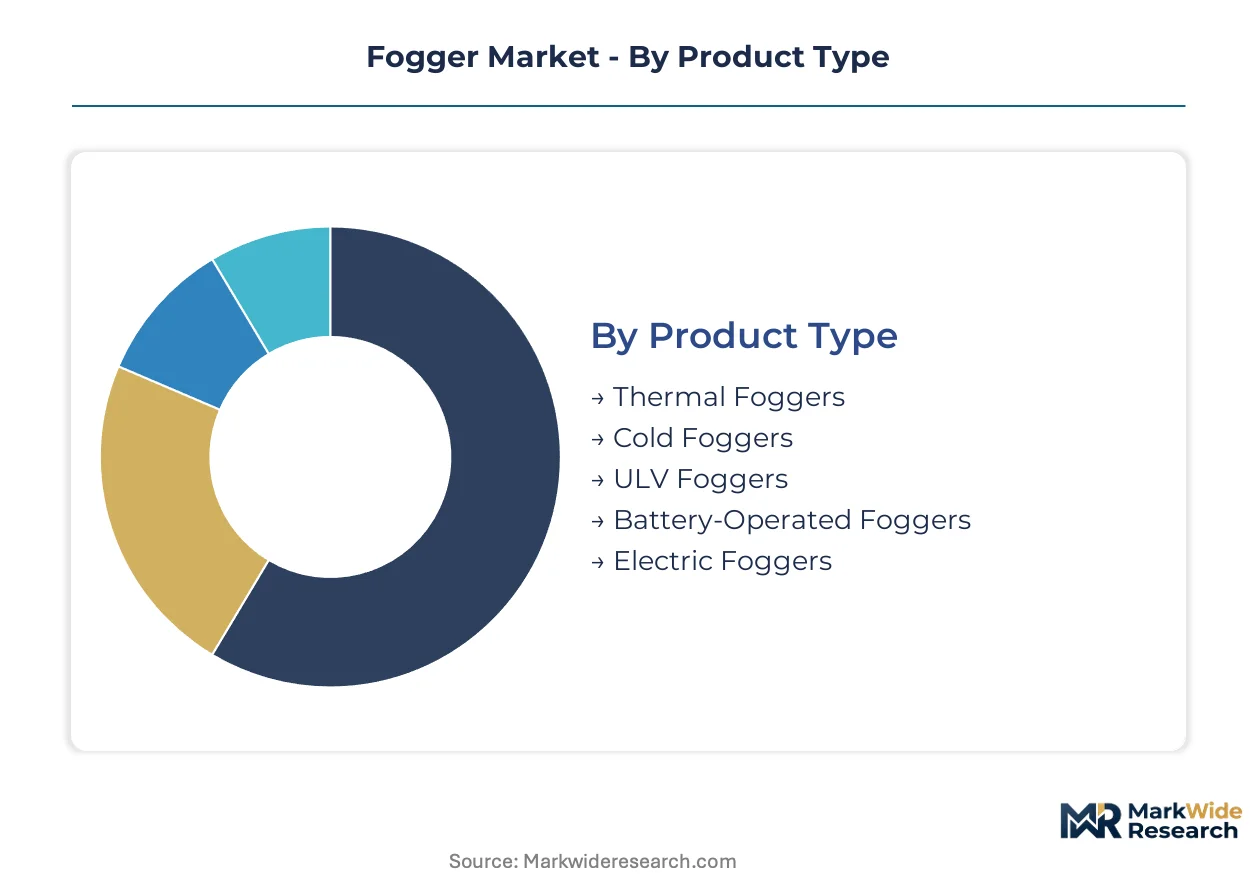
Fogger market segmentation reveals divergent engineering requirements across thermal, cold, and electrified atomization platforms. Equipment specifications must align with carrier fluid chemistry, emission constraints, and droplet size validation protocols that vary sharply by end-use environment.
Product Type:
Customization intensity spans from standardized thermal units to modular battery systems with swappable atomizer heads.
- Thermal Foggers:These systems heat oil-based carriers to 400-600°C, producing dense 0.5-5 micron aerosols that penetrate dense vegetation. Brazilian soybean operators in Mato Grosso deploy these for irregular terrain coverage where carrier penetration outweighs emission concerns. EPA droplet verification requirements now mandate laser diffraction testing for every thermal unit entering US channels.
- Cold Foggers:High-velocity air shearing generates 10-30 micron droplets without combustion, satisfying EU F-Gas Regulation constraints on propellant emissions. Dutch greenhouse clusters favor these for integrated pest management where thermal oil residues threaten crop certification.
- ULV Foggers:Rotary atomization achieves ultra-low volume application with precise droplet control.
- Battery-Operated Foggers:Lithium-ion powered portability enables cordless operation in confined agricultural spaces.
- Electric Foggers:Grid-tethered systems offer continuous operation for fixed installation humidification.
Leading the category by volume: Thermal Foggers. Growing fastest: Battery-Operated Foggers.
Application:
Margin profiles separate commodity disinfection contracts from precision agriculture services with sensor-validated outcomes.
- Pest Control:Vector suppression programs in Maharashtra deploy ULV systems for dengue abatement with municipal procurement backing. Droplet uniformity metrics now determine contract renewal terms.
- Disinfection:Surface sanitation protocols in US healthcare facilities favor cold fogging for food-contact compliance under FDA guidelines. Electrostatic sprayer substitution threatens share in indoor commercial cleaning.
- Humidification:Controlled environment agriculture in Gujarat greenhouses drives demand for continuous moisture management.
- Odor Control:Waste management and industrial processing facilities deploy masking agent dispersion.
- Mold Remediation:Restoration contractors apply biocide fogs in water-damaged structures.
Pest Control commands the largest equipment installed base. Disinfection shows the steepest expansion trajectory post-regulatory tightening on surface sanitation.
End User:
Procurement sophistication ranges from federal vector-control tenders to decentralized grower cooperatives.
- Agricultural Operators:Brazilian soybean estates in Goiás pioneered outcome-based fogger leasing with per-hectare service contracts. Bundled droplet monitoring sensors validate coverage density for precision chemical application.
- Public Health Authorities:German-engineered ULV systems anchor European municipal mosquito abatement supply chains. REACH chemical authorization constrains carrier formulation choices.
- Commercial Cleaning Services:Facility management contractors purchase cold foggers for contract sanitation services.
- Food Processing Units:FDA-compliant surface sanitation drives specification requirements.
- Greenhouse Managers:Protected cultivation expansion in Maharashtra and Gujarat concentrates demand for emission-restricted equipment.
Agricultural Operators represent the deepest equipment penetration. Public Health Authorities maintain the most stable replacement cycles.
Distribution Channel:
Channel economics fragment between high-touch specification sales and automated replenishment platforms.
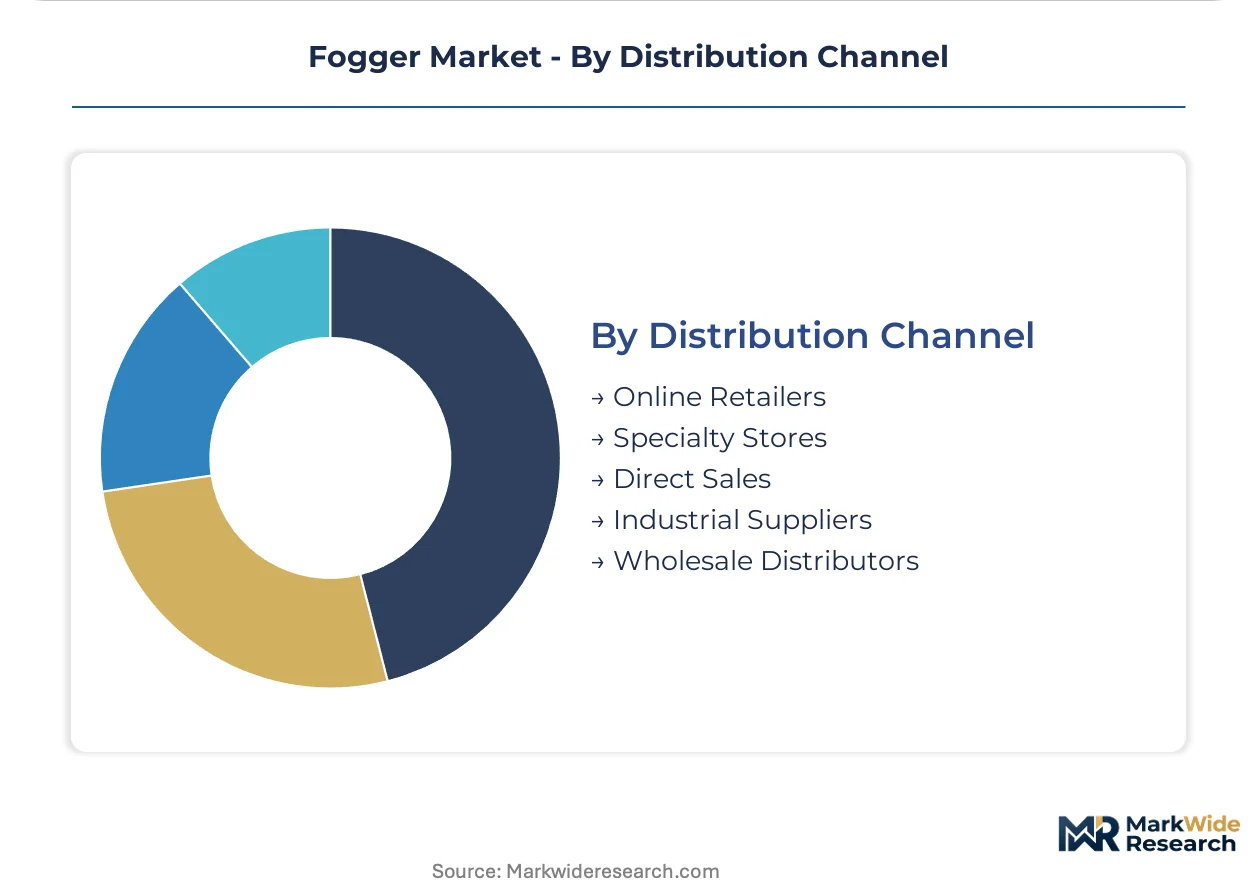
- Direct Sales:OEM field engineers configure thermal fogger systems for Brazilian agricultural estates with terrain-specific nozzle calibration. Service bundling captures margin that wholesale channels forfeit.
- Online Retailers:Battery-operated units for greenhouse operators migrate to precision agriculture marketplaces with IoT integration. Digital channels disintermediate traditional dealer networks in Indian western states.
- Specialty Stores:Regional equipment dealers serve pest control contractors with maintenance parts.
- Industrial Suppliers:Broad-line distributors reach commercial cleaning and facility maintenance buyers.
- Wholesale Distributors:Volume aggregation serves price-sensitive municipal procurement.
Direct Sales captures the highest-margin contracts. Online Retailers are climbing the fastest as digital procurement penetrates agricultural supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for fogger equipment concentrates in agricultural corridors and public health infrastructure zones across five countries. Brazil's precision spraying programs, India's greenhouse expansion, and stringent EPA certification requirements in the United States are redrawing procurement patterns. European emission regulations and Asian vector-control mandates complete the geographic map.
United States
Soybean and corn operators in Iowa and Illinois deploy thermal foggers for irregular terrain coverage where carrier penetration matters. EPA's revised pesticide application equipment standards now mandate laser diffraction droplet verification for every unit entering distribution channels. Curtis Dyna-Fog maintains defense and federal vector-control contracts through established procurement networks.
Brazil
Mato Grosso and Goiás estates pioneered outcome-based fogger leasing with per-hectare service contracts bundling droplet monitoring sensors. ANVISA's agrochemical application guidelines shape equipment specification requirements for large-scale operators. Precision agriculture adoption runs deepest in the Cerrado agricultural frontier where chemical runoff reduction commands regulatory attention.
India
Maharashtra's public health infrastructure prioritizes ULV rotary atomization systems for dengue suppression campaigns with municipal procurement backing. Gujarat's protected cultivation area expands fastest in greenhouse horticulture clusters around Ahmedabad and Vadodara. BIS equipment certification standards are tightening as western states scale emission-restricted battery-operated systems.
Germany
IGEBA Gerätebau GmbH anchors European public health authority supply chains through ULV precision systems engineered for municipal mosquito abatement. REACH chemical authorization and the F-Gas Regulation constrain thermal fogger refrigerant choices and carrier formulation options. Dutch and Spanish protected cultivation operators source German-engineered cold foggers for integrated pest management programs.
China
Shouguang Jiafu Agricultural Machinery exemplifies domestic equipment fabrication serving protected cultivation expansion in Shandong Province. MIIT battery chemistry standards and emerging solid-state cell regulations promise energy density gains for portable cold fogger platforms. Yangtze River Delta greenhouse clusters drive regional procurement volume for cordless emission-restricted systems.
Fogger Market Competitive Landscape
German and American producers anchor the premium tier; Chinese fabricators hold volume positions in emerging market channels. The vendor structure splits between combustion-engine heritage specialists and electrified-platform entrants. Three archetypes dominate: thermal fogger incumbents with defense contract legacies, battery-operated system specialists capturing greenhouse demand, and diversified agricultural equipment conglomerates. Competitive moves concentrate on droplet validation certification acceleration and direct-to-grower digital channel construction.
Within the German-engineered precision tier, IGEBA Gerätebau GmbH and pulsFOG Dr. Stahl & Sohn GmbH exemplify ULV system specialization for European public health authority supply chains. Curtis Dyna-Fog occupies a position representing thermal fogger heritage sustained through federal procurement networks. Shouguang Jiafu Agricultural Machinery anchors the Chinese fabrication segment serving domestic protected cultivation expansion. These three entities represent distinct geographic and technological archetypes without overlapping strategic positioning.
| Leading Market Players |
|---|
| Curtis Dyna-Fog |
| IGEBA Gerätebau GmbH |
| pulsFOG Dr. Stahl & Sohn GmbH |
| Vectorfog |
| TTS Group |
| UNA Corporation |
| Conic Systems |
| B&G Equipment Company |
| Shouguang Jiafu Agricultural Machinery |
| Others |
Supply & Pricing Matrix
Captive lithium-ion cell production in Chinese processing facilities anchors both supply security and pricing leverage for battery-operated fogger OEMs. This vertical integration pattern insulates tier-one manufacturers from cathode material volatility while compressing margins for assembler-only competitors dependent on spot market cells.
Pricing Analysis
Volume leaders in thermal fogging equipment capture thin margins on standardized military and municipal contracts, while precision ULV specialists in Germany command premium pricing through REACH-certified carrier compatibility and droplet validation services. Price differentiation rests on EPA certification tier and bundled sensor diagnostics rather than hardware alone. Pricing pressure stems from electrostatic sprayer substitution in commercial disinfection segments. Municipal procurement teams in India exhibit highest price sensitivity; Brazilian soybean estates leasing per-hectare service contracts show lowest.
Supply Chain Analysis
Freight cost volatility from Chinese battery component hubs to Indian greenhouse clusters and Brazilian Cerrado estates is reshaping regional inventory positioning. Supply concentrates in China for lithium-ion cells, Germany for precision rotary atomizers, and the United States for thermal fogger combustion engines. Raw material dependencies span cobalt cathodes, aluminum atomizer housings, and oil-based carrier formulations. Single-source vulnerability in Chinese cell processing amplifies disruption risk. Distribution runs through OEM direct sales for large agricultural estates and precision agriculture marketplaces for greenhouse operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in certified droplet validation technicians prop pricing power for incumbents with in-house testing capacity. This bottleneck limits new entrant certification velocity and consolidates margin capture among established EPA-approved manufacturers.
For Market Incumbents: To counter electrostatic sprayer encroachment in commercial disinfection, thermal fogger specialists should accelerate cold fogger platform development with brushless DC rotary atomization. Certification investment in emerging solid-state battery standards captures performance differentiation before chemistry regulations solidify. Channel control through direct-to-grower IoT-enabled leasing in Brazil and India locks in replacement cycles. For New Entrants and Emerging Players: Greenhouse managers in Gujarat and Maharashtra represent an underserved buyer archetype demanding emission-restricted battery systems before equipment standardization freezes design choices. Precision agriculture marketplaces enable bypass of entrenched dealer networks with integrated droplet monitoring subscriptions. White-space concentration in Indian western states offers fastest path to volume before BIS certification requirements tighten. For Investors and Strategic Acquirers: Exit pathways concentrate in platform specialists with captive certification infrastructure and recurring service revenue. Long-term viability favors OEMs bundling hardware with per-hectare outcome contracts over transactional equipment sellers. The signal to watch is EPA acceleration of droplet drift liability standards, which would force consolidation among uncertified assemblers and reward pre-positioned testing capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Buildout | In-house laser diffraction testing capacity accelerates EPA entry and commands premium pricing tiers. |
| Battery Chemistry Platform Alignment | Early solid-state cell integration captures energy density gains for cordless greenhouse deployment. |
| Direct-to-Grower Digital Channel | Precision agriculture marketplaces disintermediate dealer networks and capture usage data streams. |
| Outcome-Based Leasing Model | Per-hectare service contracts with sensor validation lock in Brazilian soybean estate loyalty. |
| Geographic Service Network Pre-positioning | Western India greenhouse clusters offer first-mover advantage before BIS standardization solidifies. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this fogger market analysis. Primary interviews with agricultural equipment procurement managers, greenhouse operations directors, municipal vector-control coordinators, EPA certification engineers, and precision agriculture marketplace executives validated demand patterns. Secondary sources included EPA pesticide equipment standards documentation, REACH chemical authorization databases, ANVISA agrochemical guidelines, and BIS equipment certification records. Bottom-up equipment shipment tracking and top-down agricultural chemical application spend estimates were triangulated for cross-validation.
Data-stream reconciliation across thermal, cold, ULV, and battery-operated platform shipments enabled segment-level modeling across the analysis window. Segmentation dimensions included atomization technology, carrier fluid chemistry, end-use environment, and geographic regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and precision agriculture adoption curve fitting. Forecast inputs incorporated lithium-ion cell cost trajectories and evolving droplet drift liability exposure.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery chemistry regulatory shifts and electrostatic sprayer substitution rates in commercial cleaning. Forecasts reflect documented assumptions about certification timeline acceleration and greenhouse horticulture scaling trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
China Crop Protection Chemicals Market
Crop Protection
Latin America Crop Protection Chemicals Market
Crop Protection
Vietnam Insecticide Market
Crop Protection
South America Fungicide Market
Crop Protection
Soil Fumigant Market
Crop Protection
Africa Crop Protection Chemicals Market
Crop Protection
Global Seed Treatment Chemicals Market
Crop Protection
Europe Crop Protection Chemicals Market
Crop Protection
Urban Rooftop Farm-Safe Pest Management Chemistry Market
Crop Protection
Europe Nematicide Market
Crop Protection
Global Acephate Market
Crop Protection
Larvicides Market
Crop Protection
United Kingdom Crop Protection Chemicals Market
Crop Protection
Pest Control Products Market
Crop Protection
Brazil Crop Protection Chemical Market
Crop Protection
Chile Crop Protection Chemicals Market