
 Africa Agricultural Tractor Market | 2026-2036
Africa Agricultural Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Agricultural Tractor Market Outlook
The gap between premium four-wheel tractors and commodity two-wheel units is broadening across African markets. Massey Ferguson leverages its southern African assembly footprint to sustain competitive positioning in mid-horsepower categories. V.S.T Tillers Tractors Ltd. anchors the low-power segment with cost-optimized designs purpose-built for smallholder terrain conditions. Escorts Ltd competes through localized dealer networks that extend spare-parts availability into remote agricultural zones.
An agricultural tractor is a self-propelled vehicle engineered to deliver traction and power for tillage, planting, harvesting, and transport operations, typically rated by engine horsepower and hitch-lift capacity. Four-wheel-drive configurations dominate commercial farm applications where traction requirements exceed 75 horsepower, while compact two-wheel variants serve intercropping systems on plots below five hectares. Smart farming technology integration is gaining fastest in the commercial farm segment, where precision guidance and telemetry command premium pricing. The smallholder farmer end-user category remains the largest volume pool, though margins concentrate in utility-class machines sold to agricultural cooperatives with centralized maintenance capabilities.
Kenya's Agricultural Finance Corporation, Nigeria's Central Bank anchor borrower schemes, and South Africa's Department of Agriculture, Land Reform and Rural Development collectively shape equipment finance access and import tariff structures. BIS-equivalent national standards in Ghana and Ethiopia are tightening emissions thresholds for diesel engines, pressuring suppliers to certify powertrain configurations. Stakeholders must monitor how currency volatility and localized assembly incentives reshape sourcing decisions between fully built unit imports and knocked-down kit assembly.
Market Dynamics
Diesel-to-electric powertrain conversion programs are redrawing capital allocation patterns across African tractor markets, as national agricultural modernization policies in Kenya, Nigeria, and Ethiopia channel subsidy flows toward electrification-ready equipment categories.
Growth Catalysts
- Federal Tractor-Hire Schemes:Nigeria's northern grain belt is accelerating replacement cycles for aging two-wheel machines through state-level farm equipment subsidies that reduce upfront capital barriers for smallholder cooperatives.
- Smallholder Mechanization:East African farmer cooperatives are expanding mechanized cultivation coverage as diesel-to-electric conversion programs gain operational traction under Kenya's Agricultural Finance Corporation lending frameworks.
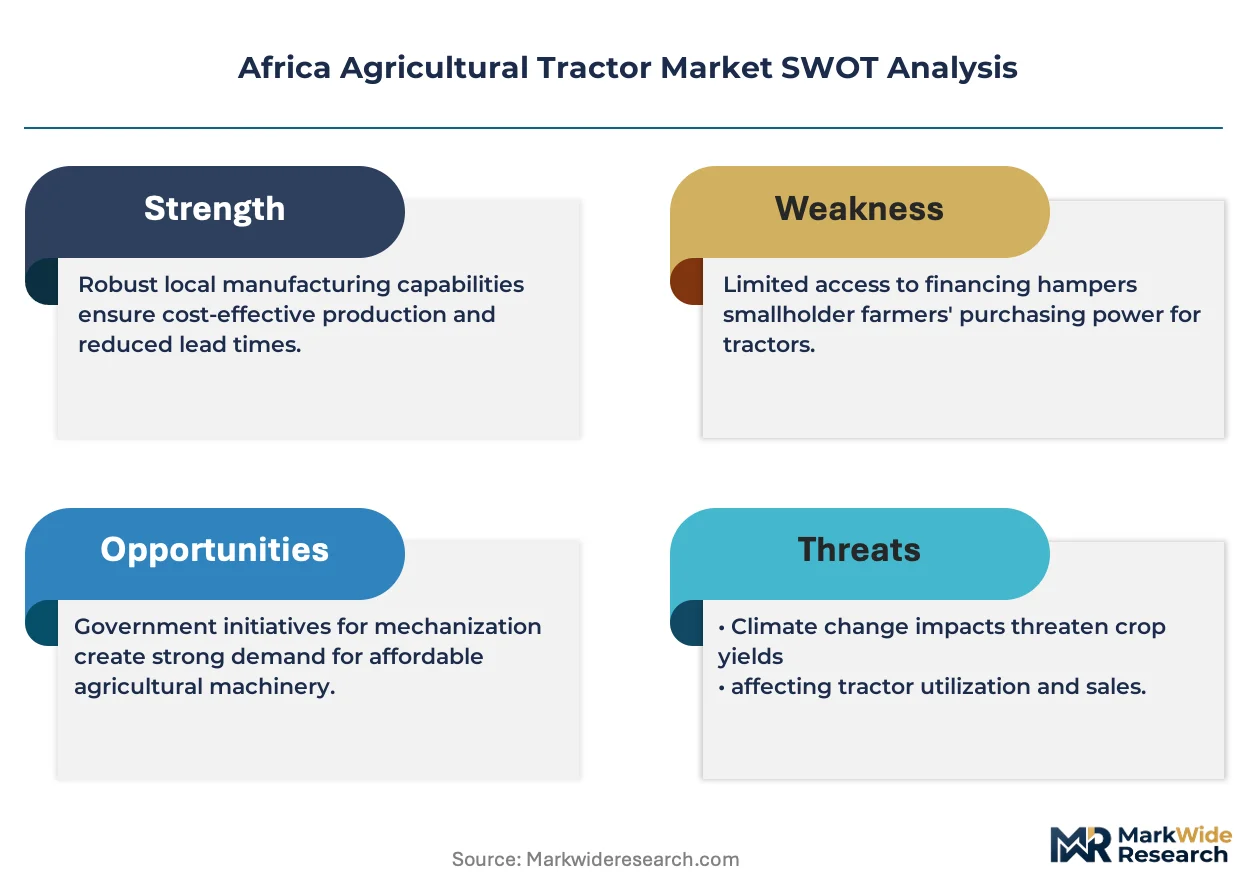
- Emissions Threshold Tightening:BIS-equivalent national standards in Ghana and Ethiopia are pressuring suppliers to certify cleaner powertrain configurations, creating compliance-driven demand for next-generation equipment.
Market Restraints
- Currency Volatility Exposure:Import-dependent supply chains face margin erosion when local currencies depreciate against dollar-denominated component sourcing, particularly affecting fully built unit importers in Nigeria and Kenya.
- Spare Parts Distribution Gaps:Remote agricultural zones outside South Africa's established dealer networks suffer extended equipment downtime due to fragmented logistics infrastructure for critical replacement components.
- Two-Wheel Commodity Trap:Aging machine pools in the low-power segment resist premium pricing capture, compressing manufacturer margins on cost-optimized designs purpose-built for smallholder terrain.
Strategic Opportunities
- Knocked-Down Kit Assembly:Localized assembly incentives in Ethiopia and Ghana are reshaping sourcing decisions, creating captive production footholds for suppliers willing to establish regional kit-assembly operations.
- Smart Farming Integration:Precision guidance and telemetry systems command premium pricing in South Africa's commercial farm segment, where tractor-plus-technology bundling opens recurring revenue streams.
- Cooperative Maintenance Centralization:Agricultural cooperatives with centralized maintenance capabilities represent a concentrated buyer pool for utility-class machines, enabling aftermarket service contract penetration.
Industry Challenges
- Electrification Skill Shortfalls:Technician training pipelines for high-voltage powertrain diagnostics remain underdeveloped across East and West African markets, constraining dealer service capacity for electric conversion programs.
- Import Tariff Navigation:Divergent customs classifications between fully built units and component kits create compliance complexity for suppliers operating across multiple national jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Agricultural Tractor Market |
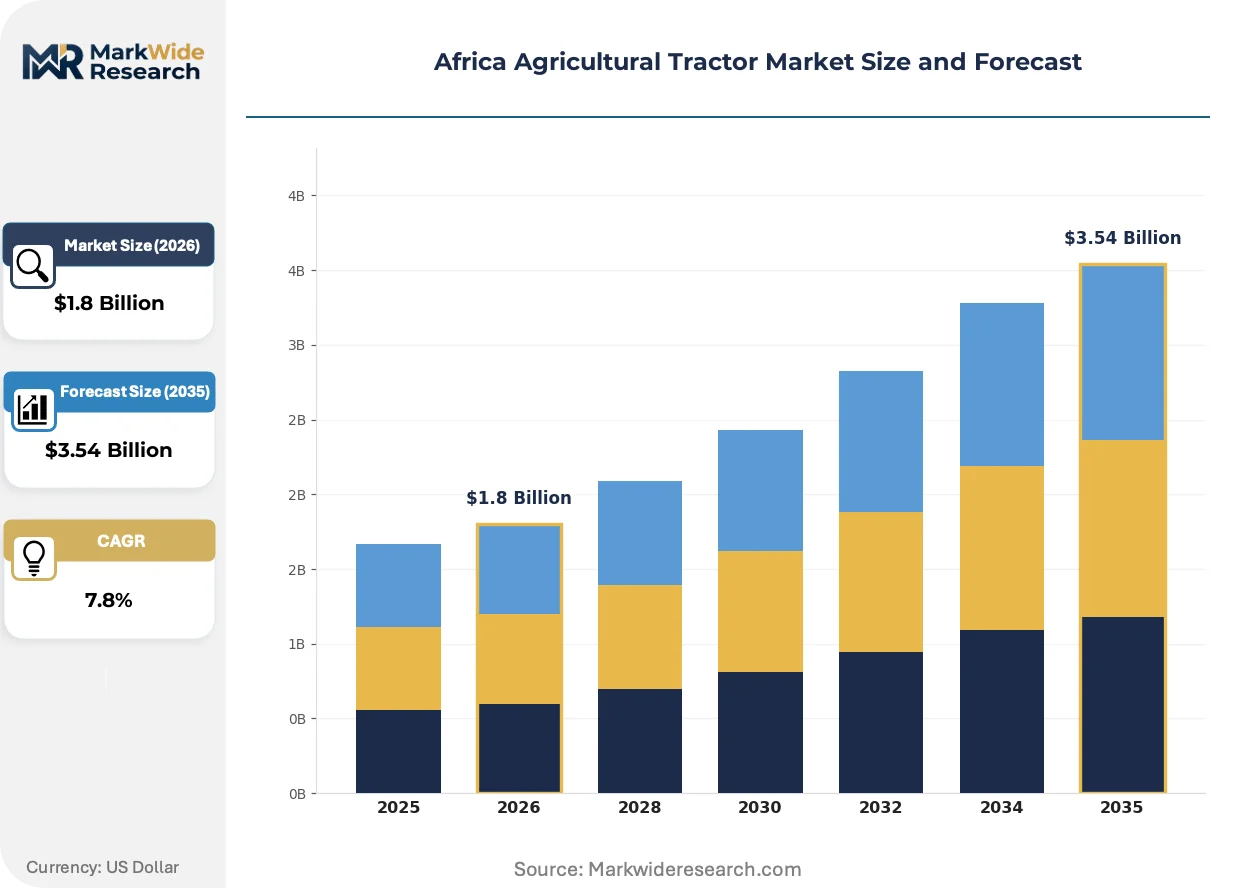
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Wheel, Four-Wheel, Compact, Utility End User: Smallholder Farmers, Commercial Farms, Agricultural Cooperatives, Government Agencies Technology: Conventional, Smart Farming, Electric, Automated Distribution Channel: Direct Sales, Dealers, Online Platforms, Rental Services |
| Companies Covered | Kubota Corporation, Massey Ferguson, Deere & Company, V.S.T Tillers Tractors Ltd., Escorts Ltd, CNH Industrial N.V., Mahindra & Mahindra Limited, Argo Tractors SpA, AGCO Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Agricultural Tractor Market Strategic Shifts
Telematics-enabled fleet management is penetrating African tractor markets from the commercial farm tier downward, rewiring how equipment utilization and maintenance decisions are made across dispersed agricultural operations.
Electric powertrain retrofits for existing diesel tractors are rewriting the capital efficiency calculus for smallholder cooperatives in Kenya and Ethiopia. The retrofit approach preserves chassis investments while enabling compliance with tightening emissions thresholds. Adoption concentrates among cooperatives with centralized workshop facilities capable of managing battery system integration.
Kenya's BIS-equivalent standards and Ethiopia's national emissions frameworks are accelerating powertrain certification requirements for diesel engines. Manufacturers must now navigate multi-jurisdictional type-approval processes. The commercial farm segment in South Africa is responding fastest, leveraging existing technical compliance infrastructure to maintain import access.
Cooperative procurement consortia are displacing individual smallholder purchases as the dominant acquisition channel in East Africa. These aggregators negotiate volume pricing and centralized maintenance agreements with suppliers. Nigeria's northern grain belt and Kenya's Rift Valley farming clusters exhibit the most advanced cooperative buying structures.
Africa Agricultural Tractor Market Segmentation
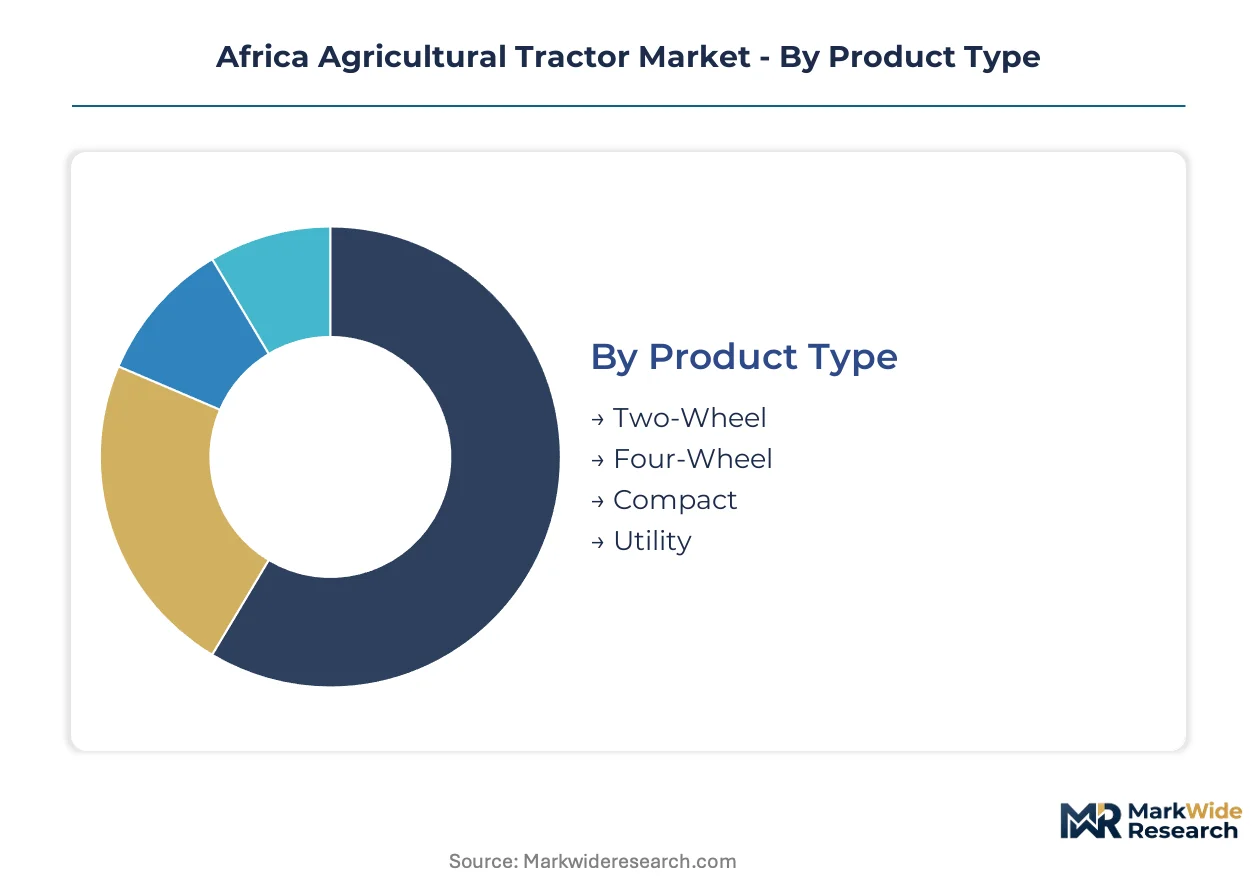
Tractor demand across Africa fragments sharply across power classes and procurement channels, with supply concentration determining which configurations reach smallholders versus commercial operators. Understanding these divides reveals where margin pools form and which technology transitions face adoption barriers.
Product Type:
Supply concentrates in low-horsepower fabrication for East African markets, while South African commercial demand pulls four-wheel configurations through established dealer networks.
- Two-Wheel:Lightweight machines rated below 20 horsepower dominate Nigeria's northern grain belt and Ethiopia's highland smallholdings. Aging machine pools resist premium pricing capture, compressing manufacturer margins on cost-optimized designs purpose-built for smallholder terrain.
- Four-Wheel:Heavy-duty configurations exceeding 75 horsepower serve commercial grain operations and cooperative fleets across South Africa's maize belt. Traction requirements and tillage depth specifications drive specification decisions in this tier.
- Compact:Mid-range powertrains bridge intercropping systems on plots below five hectares, concentrated in Kenya's Rift Valley farming clusters.
- Utility:Versatile chassis designs with three-point hitch flexibility anchor cooperative procurement consortia in Nigeria and Ethiopia.
Today's leader: Two-Wheel. Tomorrow's challenger: Four-Wheel.
End User:
Cost tier stratification separates individual smallholder purchases from volume-negotiated cooperative acquisitions, with government schemes occupying a distinct subsidy-dependent tier.
- Smallholder Farmers:Individual operators managing plots below five hectares constitute the largest volume pool. Diesel-to-electric conversion programs gain traction among this cohort where centralized workshop facilities exist.
- Commercial Farms:Large-scale grain and horticulture operations in South Africa's commercial farm segment command precision guidance and telemetry bundling. Smart farming technology integration commands premium pricing in this tier.
- Agricultural Cooperatives:Aggregated buyers negotiate volume pricing and centralized maintenance agreements across Kenya's Rift Valley and Nigeria's northern grain belt.
- Government Agencies:Federal tractor-hire schemes and state-level farm equipment subsidies in Nigeria accelerate replacement cycles through capital barrier reduction.
Volume concentrates with Smallholder Farmers. Margin concentrates with Commercial Farms.
Technology:
Application maturity varies dramatically, with conventional diesel retaining infrastructure advantages while electric retrofits rewrite capital efficiency calculus for cooperative workshops.
- Conventional:Diesel powertrains with mechanical transmission systems retain dominance across remote agricultural zones lacking technician training pipelines. Spare parts distribution gaps favor proven mechanical architectures.
- Smart Farming:Telematics-enabled fleet management and precision guidance systems penetrate from South Africa's commercial tier downward. Recurring revenue streams emerge from tractor-plus-technology bundling.
- Electric:Battery powertrain retrofits for existing diesel chassis preserve capital investments while enabling emissions compliance in Kenya and Ethiopia. Adoption concentrates among cooperatives with centralized workshop facilities.
- Automated:Autonomous guidance and implement control systems remain nascent, constrained by electrification skill shortfalls across East and West African markets.
Conventional holds installed base. Electric climbs the fastest on retrofit economics.
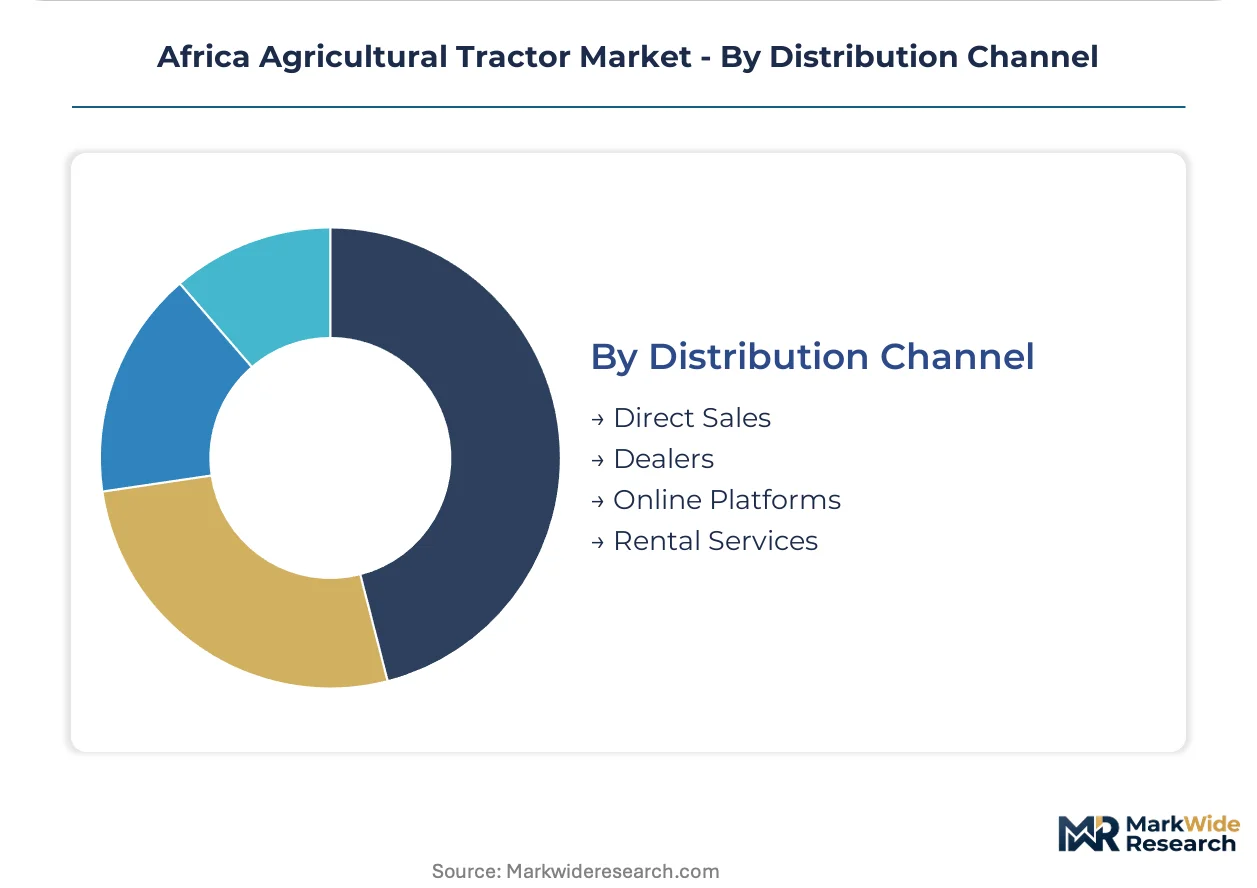
Distribution Channel:
Customer type and geography dictate channel viability, with rental services displacing ownership models where capital access remains constrained.
- Direct Sales:Manufacturer-to-farm transactions occur for large commercial fleets in South Africa with established technical compliance infrastructure.
- Dealers:Localized networks extend spare-parts availability into remote agricultural zones, particularly critical for Massey Ferguson's southern African assembly footprint.
- Online Platforms:Digital procurement channels emerge for standardized two-wheel configurations, though logistics infrastructure limits penetration outside urban proximity.
- Rental Services:Federal tractor-hire schemes and cooperative equipment pools reduce upfront capital barriers for smallholder mechanization in Nigeria and Kenya.
Dealers dominate service-intensive segments. Rental services expand fastest where credit access lags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nigeria pulls ahead in mechanization subsidies while Kenya concentrates electric conversion pilots, creating divergent technology pathways across East and West African markets.
Nigeria
Federal tractor-hire schemes and state-level farm equipment subsidies accelerate replacement cycles for aging two-wheel machines in the northern grain belt. The Central Bank anchors borrower schemes that reduce upfront capital barriers for smallholder cooperatives. Kano and Kaduna states exhibit the most advanced cooperative buying structures, with aggregated procurement consortia negotiating volume pricing.
Kenya
The Agricultural Finance Corporation channels lending frameworks toward diesel-to-electric conversion programs gaining operational traction among smallholder farmer cooperatives. BIS-equivalent national standards tighten emissions thresholds for diesel engines, pressuring suppliers to certify cleaner powertrain configurations. The Rift Valley farming clusters concentrate mid-range compact tractor demand for intercropping systems on plots below five hectares.
Ethiopia
National emissions frameworks accelerate powertrain certification requirements while localized assembly incentives reshape sourcing decisions toward knocked-down kit operations. The country's agricultural modernization policies channel subsidy flows toward electrification-ready equipment categories. Highland smallholdings concentrate demand for lightweight two-wheel machines purpose-built for smallholder terrain conditions.
South Africa
The Department of Agriculture, Land Reform and Rural Development shapes equipment finance access and import tariff structures for commercial grain operations. Established dealer networks extend spare-parts availability into remote agricultural zones, sustaining four-wheel-drive configurations exceeding 75 horsepower. The maize belt commands precision guidance and telemetry bundling where smart farming technology integration commands premium pricing.
Ghana
BIS-equivalent national standards tighten emissions thresholds for diesel engines, creating compliance-driven demand for next-generation equipment. Import tariff structures favor knocked-down kit assembly over fully built unit imports, creating captive production footholds for regional suppliers. Agricultural cooperatives with centralized maintenance capabilities negotiate utility-class machine procurement with aftermarket service contract penetration.
Africa Agricultural Tractor Market Competitive Environment
Top-tier vendors anchor premium four-wheel configurations, while cost-optimized specialists dominate two-wheel commodity segments. The market exhibits tiered structure with Japanese and Indian manufacturers pressing mid-horsepower categories against European legacy brands. Strategic archetypes separate scale-driven assemblers with southern African footprints from low-power fabricators purpose-built for smallholder terrain. Competitive moves concentrate on localized kit-assembly incentives and precision technology bundling for commercial farm segments.
Among Japanese-origin manufacturers, Kubota Corporation and Yanmar represent the mid-horsepower consolidation archetype. Deere & Company and CNH Industrial N.V. occupy positions within the premium-tier commercial farm vector. Indian fabricators including Mahindra & Mahindra Limited, V.S.T Tillers Tractors Ltd., and Escorts Ltd. exemplify cost-optimized design specialization for smallholder markets. Massey Ferguson anchors competitive positioning through regional assembly presence. AGCO Corporation and Argo Tractors SpA sit within diversified portfolio structures spanning multiple power classes.
| Leading Market Players |
|---|
| Kubota Corporation |
| Massey Ferguson |
| Deere & Company |
| V.S.T Tillers Tractors Ltd. |
| Escorts Ltd |
| CNH Industrial N.V. |
| Mahindra & Mahindra Limited |
| Argo Tractors SpA |
| AGCO Corporation |
| Others |
Value Chain & Pricing Dynamics
Steel and cast iron component costs originating from Indian fabrication centers flow through to landed price tiers in African markets, with tariff differentials between fully built units and knocked-down kits reshaping procurement economics for buyers in Nigeria and Kenya.
Pricing Analysis
Capacity additions in Ethiopia and Ghana are reshaping price floors for utility-class tractors across East and West African markets. Three-tier pricing structure across premium, standard, and economy levels separates commercial farm configurations with telemetry bundling from bare-chassis two-wheel units for smallholder cooperatives. Cost compression in the low-power segment intensifies because aging machine pools resist premium capture, while commercial farm buyers in South Africa exhibit lowest price sensitivity due to precision agriculture ROI requirements.
Supply Chain Analysis
Workforce availability constraints in Indian manufacturing hubs and southern African assembly zones are pressuring kit-assembly throughput for electrification-ready equipment categories. Geographic supply concentration centers on India for cost-optimized powertrain components, China for battery systems, and South Africa for regional distribution infrastructure. Raw material dependencies draw from steel mills in India, semiconductor controllers from East Asian suppliers, and rubber compounds for tire production. Single-source vulnerability around high-voltage powertrain electronics creates exposure for electric conversion programs. Distribution runs through established dealer networks extending spare-parts availability into remote agricultural zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Africa's agricultural tractor market functions as a geographic-arbitrage play where localized assembly incentives in Ethiopia and Ghana offset currency volatility exposure that erodes margins for fully built unit importers in Nigeria and Kenya.
For Market Incumbents: Anchor competitive positioning through backward integration into powertrain component sourcing from Indian fabrication centers to defend against margin compression from emerging Indian cost-optimized specialists. Prioritize certification investment for BIS-equivalent emissions standards in Ghana and Ethiopia to maintain import access as regulatory thresholds tighten.
For New Entrants and Emerging Players: Capture white-space opportunity in electric powertrain retrofit services for existing diesel chassis, targeting Kenya's Agricultural Finance Corporation lending frameworks and Ethiopia's cooperative procurement consortia with centralized workshop capabilities. Deploy rental-service go-to-market models to bypass capital barriers constraining individual smallholder purchases.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented spare-parts distribution infrastructure creates extended downtime costs for remote agricultural operations. Long-term viability favors acquirers of regional kit-assembly operations with captive access to electrification subsidy flows. Watch cooperative procurement consortia displacement of individual smallholder purchases as the inflection signal for channel control value.
| Strategic Initiative | Industry Significance |
|---|---|
| Knocked-Down Kit Assembly Establishment | Captures Ethiopian and Ghanaian tariff incentives while reducing currency exposure for Nigeria and Kenya operations. |
| Electric Powertrain Retrofit Service Launch | Preserves smallholder cooperative chassis investments while enabling Kenya and Ethiopia emissions compliance. |
| Cooperative Maintenance Centralization | Concentrates buyer power for utility-class machines through Nigeria's northern grain belt and Kenya's Rift Valley clusters. |
| Precision Technology Bundling | Commands premium pricing in South Africa's commercial farm segment through telemetry and guidance system integration. |
| Dealer Network Extension | Extends spare-parts availability into remote agricultural zones beyond South Africa's established infrastructure. |
Study Parameters
Bottom-up cooperative procurement modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with agricultural cooperative procurement managers, dealer network operators, central bank agricultural lending officers, and aftermarket service heads combined with secondary validation from customs and trade data, central bank borrower scheme disclosures, and national agricultural modernization policy documents. Triangulation between demand-side cooperative buying patterns and supply-side kit-assembly capacity announcements ensures coverage consistency.
Historical trendline analysis of replacement cycles for aging two-wheel machines and federal tractor-hire scheme disbursement patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include power class configuration, end-user archetype, technology tier, and distribution channel, with CAGRs derived from equipment finance access expansion rates and electrification subsidy flow trajectories. Forecast inputs incorporate currency volatility exposure coefficients and emissions threshold compliance timelines.
Currency devaluation against dollar-denominated component sourcing, electrification skill shortfalls constraining service capacity, and divergent customs classification rulings are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding subsidy continuation and kit-assembly incentive durability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Turkey Agricultural Tractor Market
Agricultural Machinery
United States Agricultural Tractor Market
Agricultural Machinery
Agricultural Haying and Forage Machinery Market
Agricultural Machinery
South America Agricultural Machinery Market
Agricultural Machinery
Autonomous Farm Equipment Market
Agricultural Machinery
Asia-Pacific Agricultural Tractors Market
Agricultural Machinery
Canada Agricultural Machinery Market
Agricultural Machinery
India Tractor Market
Agricultural Machinery
Netherlands Hydrogen Powered Tractor Market
Agricultural Machinery
Automated Turf Harvester Market
Agricultural Machinery
Autonomous Electric Tractor Market
Agricultural Machinery
Power Tiller Market
Agricultural Machinery
Australia Agricultural Machinery Market
Agricultural Machinery
Agriculture Sprayers Market
Agricultural Machinery
Agriculture and Farm Machinery Market
Agricultural Machinery
Tiller Machine Market