
 Europe Insecticides Market | 2026-2036
Europe Insecticides Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Insecticides Market Insights
Project finance for precision spraying fleets is tilting competitive advantage toward well-capitalized operators. Bayer AG leverages its biologicals pipeline to offset synthetic chemistry restrictions. BASF SE anchors its position through formulation technology leadership in emulsifiable concentrates. Syngenta Group competes via integrated seed-and-crop-protection bundles across Western European distribution networks.
Europe insecticides comprise synthetic and biological active ingredients formulated to disrupt arthropod nervous systems or metabolic pathways, with pyrethroids and neonicotinoids dominating conventional portfolios while microbial proteins gain share under tightening residue protocols. These compounds protect yield and quality in agriculture, public health vectors, and stored commodities. Biologicals represent the fastest-expanding product type as regulatory pressure on organophosphates intensifies margin pool migration toward bio-based alternatives. Liquid formulations maintain volume leadership through ease of aerial and ground-based application, though granular formats grow in conservation agriculture systems.
EMA and EFSA jointly govern residue tolerances and environmental risk assessments for agrochemical approvals, while REACH and the EU Green Deal mandate hazard-based cutoffs that exclude several organophosphate chemistries from renewal. National regulators in France and Germany enforce additional buffer zone requirements that reshape product selection and application timing. Stakeholders must monitor the EU AI Act's impending classification of autonomous spraying drones as high-risk systems, which will alter equipment investment and operator certification requirements.
Market Dynamics
Precision application hardware is concentrating procurement power among Spain and Italy's specialty crop cooperatives, compressing margins for distributors unable to finance fleet upgrades.
Growth Catalysts
- EU Green Deal residue protocols:Tightening maximum residue limits under the Farm to Fork Strategy are accelerating biological product registrations and expanding addressable market for microbial proteins.
- France and Germany arable cooperatives:Deep integrated pest management adoption among large-scale farming operations is creating pull-through demand for bundled biocontrol-synthetic programs.
- Drone-based variable-rate spraying:Autonomous aerial platforms are collapsing application labor costs and enabling real-time prescription adjustments based on field-level pest pressure mapping.
Market Restraints
- Active ingredient supply concentration:Pyrethroid and neonicotinoid precursor manufacturing concentrates in Chinese chemical clusters, exposing European formulators to input volatility and trade friction.
- REACH hazard-based cutoffs:The regulation's renewal exclusion criteria for organophosphate chemistries are forcing portfolio abandonment before patent expiry, eroding R&D amortization schedules.
- Biologicals stability limitations:Microbial proteins require cold-chain distribution infrastructure that remains underdeveloped in Eastern European markets, constraining geographic expansion.
Strategic Opportunities
- Poland and Romania conservation agriculture:Granular formulation demand is expanding in reduced-tillage systems where soil-incorporated biologicals replace foliar synthetics.
- EU AI Act autonomous equipment classification:Pending high-risk system designation for spraying drones will create certification barriers that favor incumbents with compliance resources.
- Stored commodity protection:Public health vector control programs and grain elevator fumigation represent underpenetrated channels with shorter regulatory pathways than agricultural uses.
Industry Challenges
- Precision agriculture technician scarcity:Fleet operators in Spain and Italy face recruitment gaps for drone pilots capable of integrating NDVI imagery with prescription maps.
- EMA-EFSA parallel review timelines:Divergent residue tolerance and environmental risk assessment schedules are extending time-to-market for novel active ingredients by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Insecticides Market |
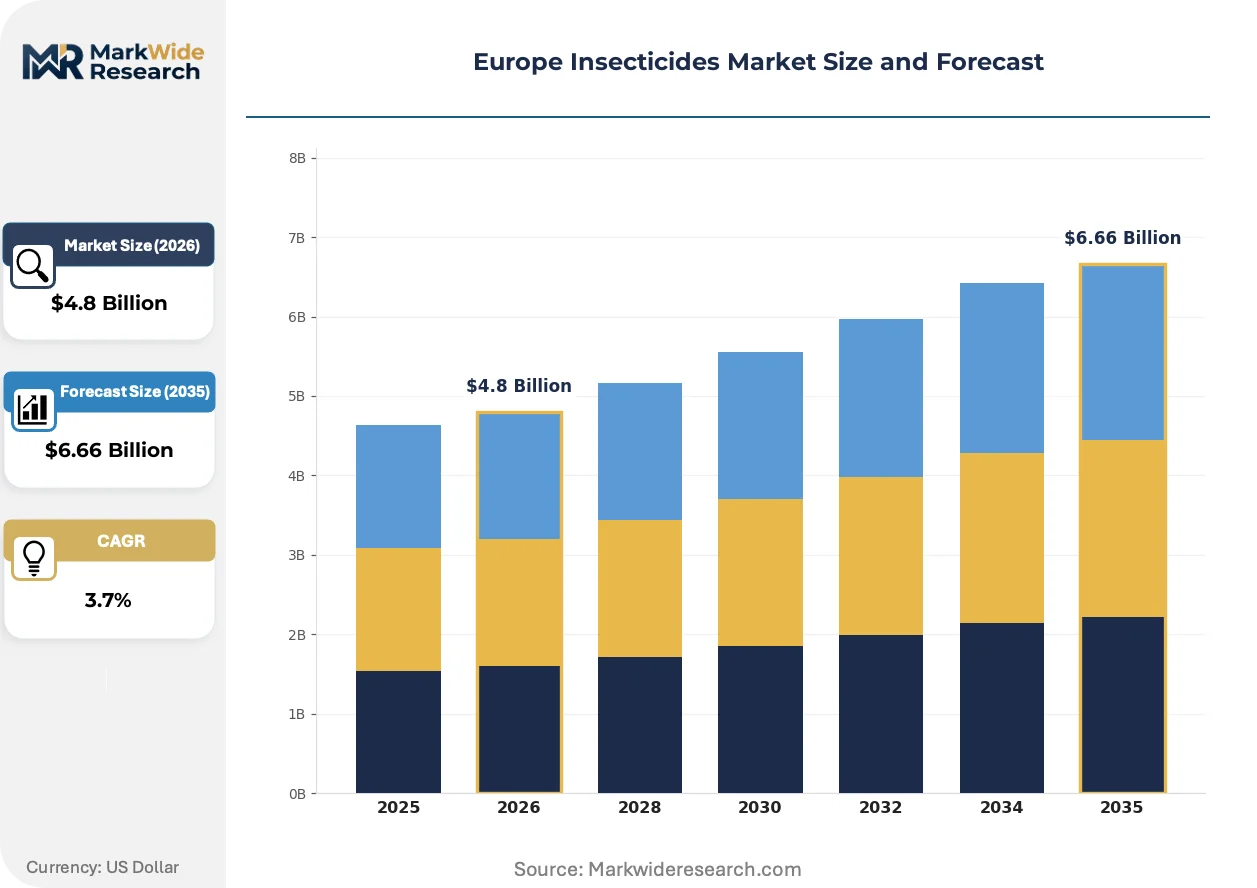
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organophosphates, Pyrethroids, Neonicotinoids, Biologicals Application: Agriculture, Public Health, Turf & Ornamentals, Food Storage Formulation Type: Liquid, Granular, Emulsifiable Concentrate, Wettable Powder Distribution Channel: Online, Distributors, Retailers, Direct Sales |
| Companies Covered | BASF SE, Bayer AG, Syngenta Group, FMC Corporation, Nufarm Ltd, Corteva Agriscience, ADAMA Agricultural Solutions, UPL Limited, Sumitomo Chemical Co. Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Insecticides Market Trends and Innovations
Formulation chemistry and application hardware are converging to reduce chemical load per hectare while maintaining efficacy under tightening residue surveillance.
RNA interference pesticides are collapsing the historical tradeoff between target specificity and spectrum breadth. Spanish citrus and olive growers are piloting sprayable dsRNA formulations against piercing-sucking pests. Bayer AG and BASF SE are repositioning R&D spend toward nucleic acid delivery systems that bypass developing insect resistance pathways.
REACH authorization sunset clauses are compressing the commercial lifespan of organophosphate and carbamate chemistries. ECHA's 2024-2027 evaluation roadmap identifies multiple actives for non-renewal based on endocrine disruption hazard profiles. French and German national regulators are imposing additional buffer zone requirements that reshape product selection and application timing windows.
Cooperative procurement consortia are displacing distributor-led sales relationships in France's grain belt. Large arable farming operations are consolidating annual insecticide purchases through direct manufacturer negotiations, extracting volume discounts and technical service commitments previously captured by agrochemical retailers. This concentration is most visible in the Paris Basin and Champagne-Ardenne cereal districts.
Europe Insecticides Market Segmentation
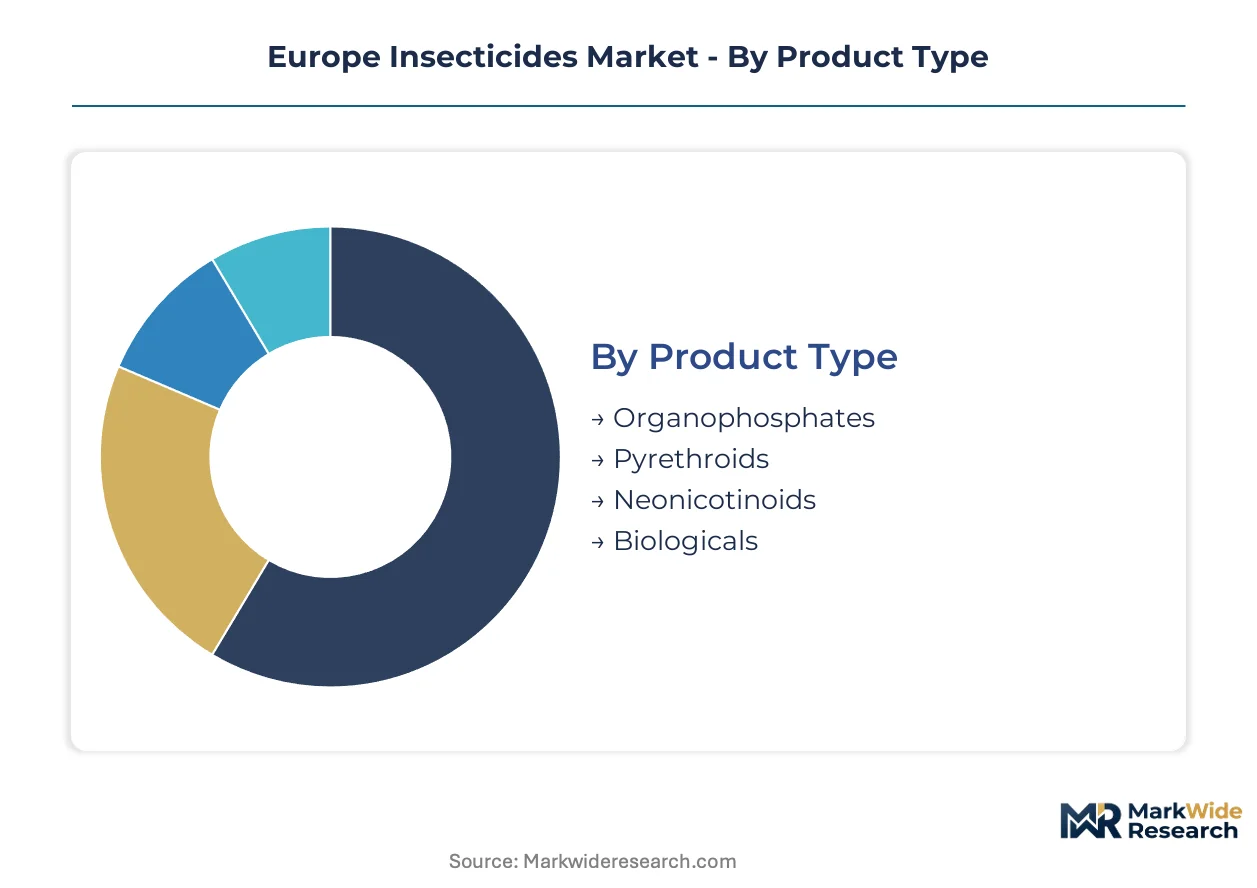
Segmentation in the Europe insecticides market reveals how regulatory pressure and application technology reshape procurement patterns across distinct customer archetypes. Formulation chemistry and distribution channel choices increasingly determine competitive positioning as residue protocols tighten.
Product Type:
Active ingredient chemistry spans synthetic neurotoxins and emerging biological modes of action, with regulatory renewal timelines fragmenting competitive stability across the category.
- Organophosphates:Cholinesterase-inhibiting compounds face REACH hazard-based non-renewal exclusions that compress commercial lifespans before patent expiry erodes R&D amortization schedules. French and German buffer zone restrictions further constrain application windows in arable districts.
- Biologicals:Microbial proteins and fermentation-derived actives require cold-chain infrastructure that remains underdeveloped in Eastern European markets, limiting geographic expansion despite accelerating registration pathways under EU Green Deal protocols. Specialty crop growers in Spain and Italy are expanding precision application programs for these products.
- Pyrethroids:Sodium channel modulators dominate conventional portfolios with established manufacturing economies, though precursor supply concentration in Chinese chemical clusters exposes European formulators to input volatility.
- Neonicotinoids:Nicotinic acetylcholine receptor agonists face pollinator risk assessments that restrict outdoor agricultural uses while preserving greenhouse and seed-treatment applications.
Established volume favors Pyrethroids; emerging adoption favors Biologicals.
Application:
End-use concentration determines regulatory pathway complexity and technical service intensity required for market access.
- Agriculture:Field crop and specialty production systems generate the deepest integrated pest management adoption among France and Germany's large-scale farming cooperatives, creating pull-through demand for bundled biocontrol-synthetic programs. Cooperative procurement consortia are displacing distributor-led sales relationships in cereal districts.
- Public Health:Vector control programs for mosquitoes and other disease carriers operate under shorter regulatory pathways than agricultural uses, with municipal procurement cycles favoring established active ingredient portfolios.
- Turf & Ornamentals:Golf course and landscape maintenance applications face heightened scrutiny for non-target organism impacts in urban watersheds.
- Food Storage:Grain elevator fumigation and commodity protection represent underpenetrated channels with distinct residue tolerance frameworks.
Margin concentration sits with Agriculture; regulatory simplicity favors Public Health.
Formulation Type:
Physical delivery systems determine compatibility with precision application hardware and conservation agriculture tillage practices.
- Liquid:Solution and suspension concentrates maintain volume leadership through compatibility with aerial and ground-based spray equipment, though drift mitigation requirements reshape nozzle selection and boom height protocols.
- Emulsifiable Concentrate:Oil-in-water systems anchor BASF SE's formulation technology leadership, enabling lipophilic active penetration of waxy cuticles in target pests.
- Granular:Soil-incorporated formats gain share in Poland and Romania's reduced-tillage systems where biologicals replace foliar synthetics.
- Wettable Powder:Dry flowable formulations serve specialty applications requiring extended residual activity without organic solvent carriers.
Application flexibility sustains Liquid; conservation agriculture tailwinds favor Granular.
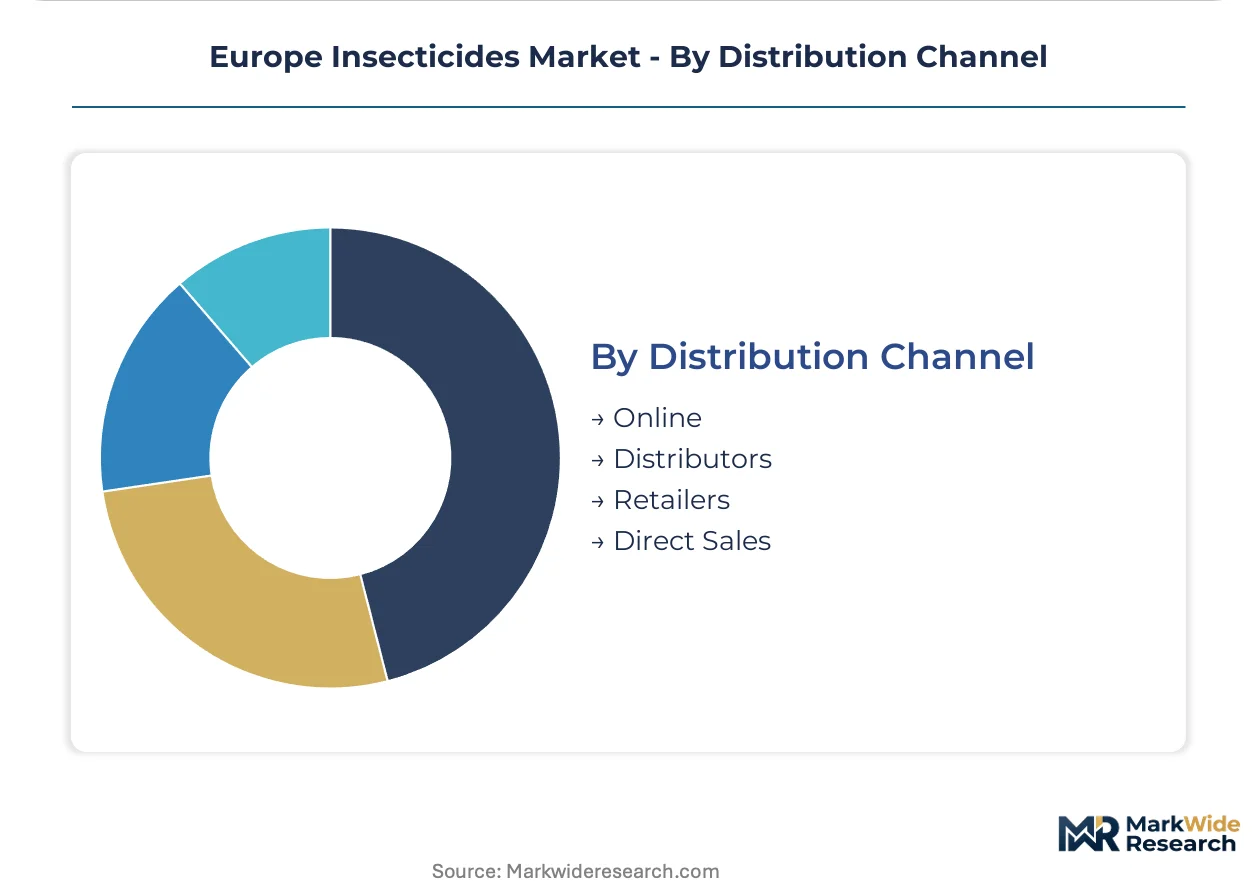
Distribution Channel:
Channel structure reflects capital requirements for inventory holding and technical advisory capacity.
- Distributors:Traditional agrochemical retailers face margin compression as precision application hardware procurement concentrates among well-capitalized cooperative operators unable to finance fleet upgrades.
- Direct Sales:Manufacturer-to-farmer relationships extract volume discounts previously captured by intermediaries, most visible in France's Paris Basin and Champagne-Ardenne cereal districts.
- Online:Digital procurement platforms emerge for standard product replenishment with limited technical service content.
- Retailers:Garden center and farm supply outlets serve smallholder and amenity segments with packaged consumer formats.
Scale economics favor Direct Sales; service intensity preserves Distributor relevance in biologicals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's insecticide trade flows reveal a structural deficit in active ingredient precursors, with formulation capacity concentrated in Western economies dependent on imported chemical intermediates from Asian manufacturing clusters.
France
Paris Basin and Champagne-Ardenne cereal districts host cooperative procurement consortia displacing traditional distributor relationships through direct manufacturer negotiations. ANSM enforces additional buffer zone requirements beyond EFSA baselines, compressing application windows for organophosphate chemistries. Large arable farming operations in these regions drive deepest integrated pest management adoption across the continent.
Germany
North Rhine-Westphalia's agrochemical formulation cluster anchors BASF SE's emulsifiable concentrate technology leadership. KBA and federal environmental agencies impose stricter drift mitigation protocols than EU minimums, reshaping nozzle selection and boom height standards. The Rhine-Ruhr industrial corridor concentrates precision application equipment manufacturing serving cross-border export markets.
Spain
Valencian Community and Andalusian specialty crop zones expand precision application programs for biological insecticides in citrus and olive production. Spanish national regulators align with EU Green Deal residue protocols while accelerating microbial product registrations through streamlined evaluation pathways. Drone-based variable-rate spraying adoption concentrates among well-capitalized cooperative operators in these Mediterranean growing regions.
Italy
Emilia-Romagna and Lombardy vegetable and fruit cooperatives drive demand for bundled biocontrol-synthetic programs in protected cultivation systems. Italian environmental ministry buffer zone designations exceed EU standards for neonicotinoid applications near pollinator habitats. Precision agriculture technician scarcity in these northern districts constrains fleet expansion for autonomous spraying platforms.
Poland
Greater Poland and Lower Silesia reduced-tillage systems generate expanding demand for granular biological formulations replacing foliar synthetics. Polish national agricultural inspectors enforce REACH compliance timelines for active ingredient renewals while cold-chain distribution infrastructure remains underdeveloped for microbial protein products. Conservation agriculture adoption in these central plains creates tailwinds for soil-incorporated application formats.
Europe Insecticides Market Competitive Landscape
On the supply side, the industry is consolidating around integrated crop protection platforms, with formulation technology leadership and biologicals pipelines serving as primary differentiation vectors. Strategic archetypes include diversified agrochemical conglomerates with seed-and-crop-protection bundles, pure-play biologicals specialists leveraging accelerated registration pathways, and generic manufacturers competing on cost-position in maturing synthetic chemistries. Dominant competitive moves encompass portfolio diversification into nucleic acid delivery systems and strategic partnerships for precision application hardware integration.
Within the diversified agrochemical tier, BASF SE, Bayer AG, and Syngenta Group exemplify competing approaches to regulatory pressure on conventional chemistries. BASF SE anchors its position through formulation technology leadership in emulsifiable concentrates. Bayer AG leverages its biologicals pipeline to offset synthetic chemistry restrictions under tightening EU protocols. Syngenta Group competes via integrated seed-and-crop-protection bundles across Western European distribution networks.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta Group |
| FMC Corporation |
| Nufarm Ltd |
| Corteva Agriscience |
| ADAMA Agricultural Solutions |
| UPL Limited |
| Sumitomo Chemical Co. Ltd |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Antwerp chemical corridor's freight cost dynamics amplify pricing power for pyrethroid and neonicotinoid precursors sourced from Chinese manufacturing clusters, compressing margins for European formulators while enabling tiered pricing across cooperative buyers, independent distributors, and smallholder retail channels.
Pricing Analysis
France and Germany's arable cooperative buyers anchor contract-based long-term offtake structures with volume-scaled discounts and embedded technical service commitments. Pricing stratifies across premium biological formulations with cold-chain guarantees, standard emulsifiable concentrates from established manufacturers, and economy-tier generics in maturing chemistries. Cost compression in the economy segment is intensifying because REACH non-renewal exclusions accelerate patent cliff dynamics for organophosphates. Smallholder retailers in Eastern Europe exhibit highest price sensitivity due to limited working capital for inventory holding.
Supply Chain Analysis
Pyrethroid and neonicotinoid precursor manufacturing concentrates in Chinese chemical clusters, with secondary formulation capacity in India and limited European captive production. European formulators draw from imported active ingredients, specialized solvent carriers, and precision application hardware components. Single-source vulnerability in Chinese intermediate supply exposes formulators to trade friction and input volatility. Distribution runs through cooperative procurement consortia displacing traditional agrochemical retailers in Western European cereal districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biological insecticide adoption sits at early-cycle expansion, with EU Green Deal residue protocols accelerating penetration beyond specialty crops into mainstream arable systems.
For Market Incumbents: Pre-empt biologicals pipeline gaps by acquiring microbial protein specialists before accelerated registration pathways close valuation windows. Defend formulation technology leadership through backward integration into nucleic acid delivery systems. Anchor capacity in North Rhine-Westphalia's chemical cluster to exploit KBA drift mitigation protocols as a regulatory moat against generic competitors. For New Entrants and Emerging Players: Poland and Romania's conservation agriculture systems represent the most penetrable entry point for granular biological formulations where cold-chain infrastructure gaps deter incumbent geographic expansion. Stored commodity protection channels in grain elevator networks offer shorter regulatory pathways than agricultural uses. Partner with precision application hardware OEMs to bypass distributor margin capture in cooperative-led procurement environments. For Investors and Strategic Acquirers: Formulation technology specialists with emulsifiable concentrate expertise and biologicals registration capabilities command premium positioning as portfolio diversification accelerates. The long-term viability window favors platforms bridging synthetic and bio-based chemistries under tightening EFSA residue protocols. Watch EMA-EFSA parallel review timeline convergence as an inflection signal for novel active ingredient time-to-market compression.| Strategic Initiative | Industry Significance |
|---|---|
| Biologicals Pipeline Acquisition | Accelerated EU Green Deal registration pathways compress competitive entry windows for microbial protein assets. |
| Precision Application Hardware Partnership | Drone-based variable-rate spraying integration locks in cooperative procurement relationships across Spain and Italy. |
| Backward Integration into Precursor Manufacturing | Captive pyrethroid intermediate production mitigates Chinese supply concentration risk for European formulators. |
| Conservation Agriculture Formulation Development | Granular biological formats align with Poland and Romania's reduced-tillage system expansion. |
| Stored Commodity Channel Expansion | Grain elevator fumigation applications bypass agricultural residue surveillance complexity for faster market access. |
Research Methodology
Initial hypotheses were tested against primary input from agrochemical procurement managers at French and German cooperatives, formulation technology directors at BASF SE and Bayer AG, precision agriculture equipment operators in Spain's Valencian Community, and biologicals registration specialists at EFSA, then refined through secondary validation against customs trade data, ECHA evaluation roadmaps, SEC 10-K filings, and EU Farm to Fork Strategy implementation reports. Bottom-up volume estimates from active ingredient consumption patterns were triangulated against top-down market sizing from manufacturer revenue disclosures.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation by product type, application end-use, formulation chemistry, and distribution channel structure. CAGRs were derived from regression analysis of historical volume trends adjusted for regulatory phase-out schedules and biologicals adoption curves. Industry-specific forecast inputs incorporated EMA-EFSA parallel review timeline assumptions and REACH authorization sunset clause implementation pacing.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, energy costs for chemical synthesis, and euro-yuan exchange rates would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement consistency and biologicals stability technology advancement. Cross-checking against Cefic chemical industry production statistics and national agricultural ministry pesticide usage surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Vietnam Insecticide Market
Crop Protection
Captan Fungicide Market
Crop Protection
France Crop Protection Chemicals Market
Crop Protection
Vietnam Herbicide Market
Crop Protection
United Kingdom Crop Protection Chemicals Market
Crop Protection
US Herbicide Market
Crop Protection
Global Seed Treatment Fungicides Market
Crop Protection
India Insecticide Market
Crop Protection
Agricultural Pheromones Market
Crop Protection
Azoxystrobin Market
Crop Protection
Spain Crop Protection Chemicals Market
Crop Protection
Middle East and Africa Turf and Ornamental Grass Protection Market
Crop Protection
Specialty Pesticides Market
Crop Protection
Avicides Market
Crop Protection
Asia-Pacific Crop Protection Chemicals Market
Crop Protection
Hungary Crop Protection Chemicals Market