
 Thailand Crop Protection Chemicals Market | 2026-2036
Thailand Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Crop Protection Chemicals Market Intelligence
Biological formulation integration is rewriting product development pipelines across Thailand's agrochemical sector. Syngenta Group leverages its global biologicals portfolio to anchor premium positioning in the Northeast's corn-growing districts. Bayer AG sustains deep distributor relationships through agricultural cooperative networks that dominate rural procurement. Corteva Agriscience specializes in next-generation herbicide molecules tailored to combat resistant weed populations in paddy systems.
Crop protection chemicals encompass synthetic and biological agents formulated to prevent, destroy, or control pests, diseases, and weeds affecting agricultural productivity, typically delivered as emulsifiable concentrates, granules, or liquid suspensions with specified active ingredient concentrations measured in grams per hectare. These compounds serve the essential commercial purpose of safeguarding yield volumes and quality grades across Thailand's export-oriented rice, rubber, and fruit sectors. Herbicides command the largest product type position due to labor scarcity driving mechanized weed control adoption across field crops. Emulsifiable concentrates retain formulation dominance where farmer familiarity and spray equipment compatibility sustain repeat purchases, though liquid formulations gain ground in horticultural zones requiring precision application. Field crops absorb the majority of volume throughput, with permanent crops generating higher margin pools per treated hectare through specialized fungicide and insecticide blends.
Thailand's Hazardous Substance Act, administered by the Department of Agriculture, mandates rigorous toxicity evaluations and re-registration cycles that filter out legacy chemistries and elevate compliance costs for market entrants. The Ministry of Agriculture and Cooperatives enforces maximum residue limits aligned with EU and Japanese import standards, directly shaping product portfolios for export-bound fruit and vegetable growers. Stakeholders must monitor regulatory divergence between Thai national standards and destination market requirements, as compliance gaps threaten market access for treated commodities entering premium European and East Asian channels.
Market Dynamics
Thailand's Hazardous Substance Act amendments are compressing active ingredient registration timelines, forcing formulators to accelerate biological pipeline investments while retiring legacy chemistries ahead of re-registration deadlines.
Growth Catalysts
- Biological formulation mandates:The Thai Ministry of Agriculture and Cooperatives incentivizes microbial inoculants and botanical extracts through reduced registration fees for low-toxicity alternatives.
- Labor scarcity in the Central Plains:Mechanized rice cultivation spreads pre-emergent herbicide applications as farm wages rise and seasonal worker availability tightens.
- EU MRL alignment pressure:Exporters of durian, longan, and mangosteen to European markets drive fungicide portfolio upgrades to meet residue thresholds.
Market Restraints
- Active ingredient import concentration:Over seventy percent of technical-grade synthetics originate from Chinese chemical parks, exposing formulators to shipping volatility and yuan fluctuation.
- Toxicology data requirements:The Department of Agriculture mandates chronic exposure studies for novel molecules, extending registration costs beyond mid-tier domestic players.
- Glyphosate substitution pressure:Paraquat bans in neighboring ASEAN markets accelerate farmer experimentation with mechanical weeding and cover cropping.
Strategic Opportunities
- Isaan corn belt biological penetration:Fall armyworm resistance to pyrethroids creates openings for Bacillus thuringiensis formulations in Nakhon Ratchasima and Khon Kaen provinces.
- Drone application services:Agricultural cooperatives in the North deploy UAV spraying fleets, demanding ultra-low-volume formulations incompatible with legacy emulsifiable concentrates.
- Organic transition premiums:The Thai Organic Agriculture Standard certification commands price multiples in domestic retail and Japanese export channels.
Industry Challenges
- Resistance management expertise gaps:Extension services lack personnel trained in herbicide rotation protocols and integrated weed management.
- Cold chain biological viability:Baculovirus and entomopathogenic nematode products degrade in ambient storage conditions prevalent across rural distributor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Crop Protection Chemicals Market |
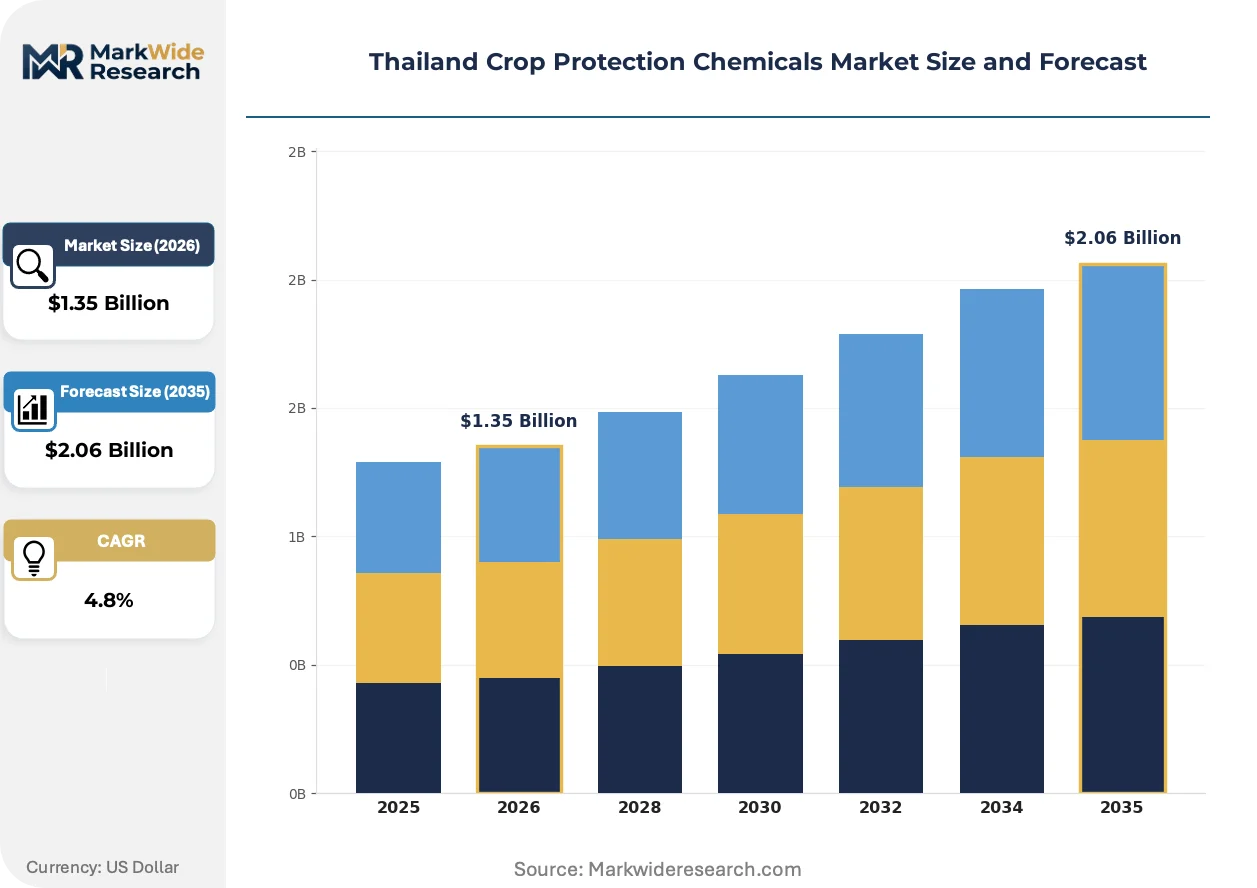
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.06 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Rodenticides Application: Field Crops, Horticultural Crops, Permanent Crops, Turf & Ornamental Formulation: Granules, Liquids, Solids, Emulsifiable Concentrates Distribution Channel: Online Retail, Conventional Stores, Distributors, Agricultural Cooperatives |
| Companies Covered | Corteva Agriscience, Sumitomo Chemical Co. Ltd., Syngenta Group, Sahaikaset Agrochemicals Co Ltd, UPL Ltd., BASF SE, ADAMA Agriculture Solutions, Sotus International Co Ltd, Bayer AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Crop Protection Chemicals Market Strategic Shifts & Innovations
Formulation chemistry and application hardware are converging to displace established farmer practices. Three developments dominate product pipeline investments and channel restructuring across the Thai agrochemical sector.
RNA interference technology targets specific pest metabolic pathways without broad-spectrum collateral damage. Vegetable seedling producers in Chiang Mai and Phetchabun provinces trial sprayable dsRNA against diamondback moth populations. This precision mechanism is rendering obsolete calendar-based insecticide rotations that accelerate resistance evolution.
The Hazardous Substance Act amendments shorten re-registration cycles from fifteen to ten years, compelling formulators to sunset organophosphate and carbamate chemistries. Exporters to Japanese markets face dual compliance burdens as Thai MRLs diverge from CODEX standards for chili and okra. Fruit growers in Rayong and Chanthaburi provinces consolidate procurement through cooperative buying groups to access residue-tested proprietary blends.
Cooperative-led input purchasing displaces independent retailer relationships across the Northeast. Corn and cassava growers in Ubon Ratchathani and Surin provinces aggregate hectare volumes to negotiate direct manufacturer pricing, bypassing provincial distributor markups. This concentration shifts technical advisory responsibility from retail staff to cooperative-employed agronomists with resistance monitoring training.
Thailand Crop Protection Chemicals Market Segmentation
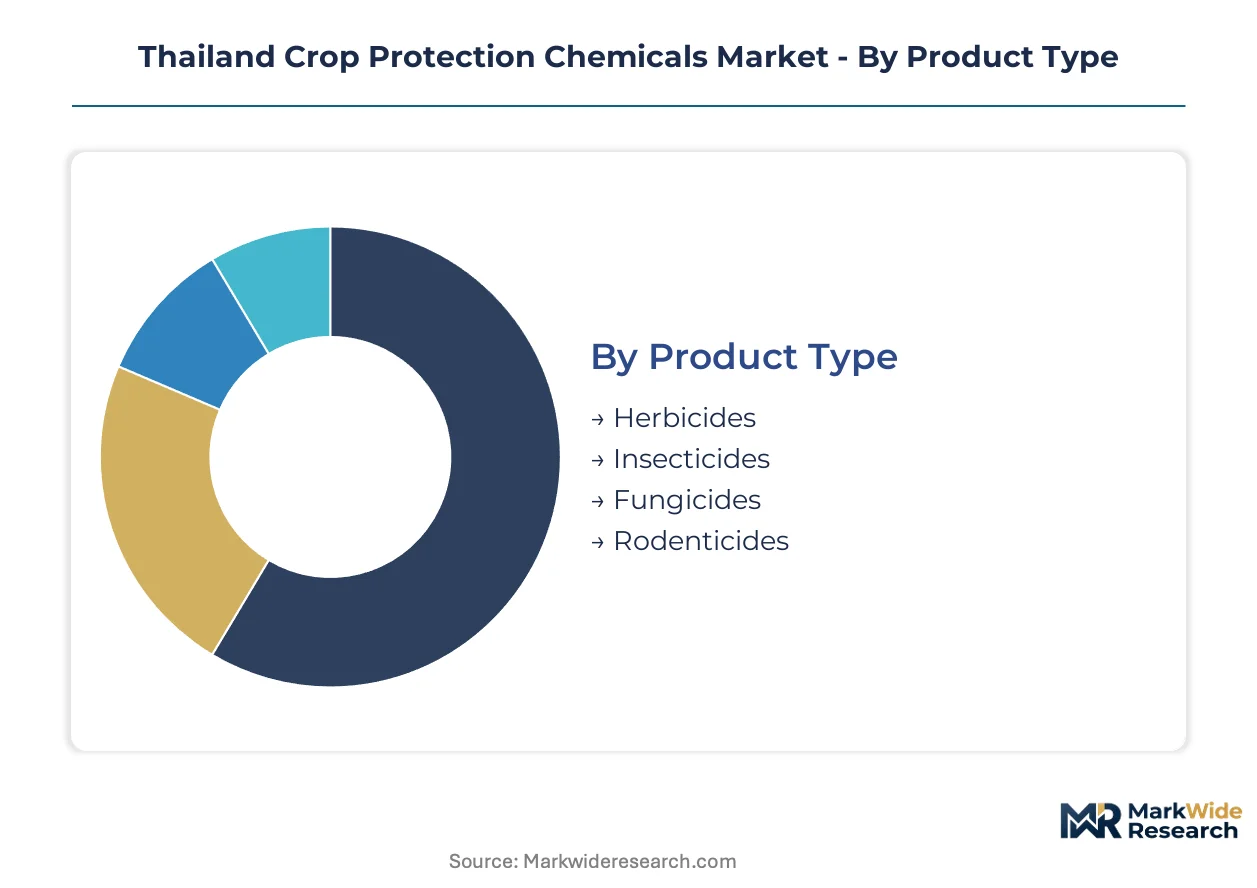
Segmentation in Thailand's crop protection chemicals market reveals how formulation chemistry, crop-specific requirements, and procurement channel evolution create distinct competitive battlegrounds. Each dimension exposes different margin structures and regulatory exposure profiles that shape strategic positioning.
Product Type:
Mature chemistries dominate volume flows while biological alternatives accelerate pipeline investment.
- Herbicides:Pre-emergent and post-emergent formulations containing glyphosate, 2,4-D, and paraquat alternatives control grassy and broadleaf weeds across mechanized rice systems. Demand concentrates in the Central Plains where labor scarcity forces chemical substitution for manual weeding, though resistance pressure in Nakhon Pathom and Suphan Buri drives rotation complexity.
- Insecticides:Pyrethroid, neonicotinoid, and organophosphate compounds target lepidopteran and sucking pest complexes in corn and fruit orchards. Fall armyworm outbreaks across the Isaan corn belt sustain volume, while pollinator toxicity concerns under the Hazardous Substance Act amendments threaten legacy molecule reregistration timelines.
- Fungicides:Triazole, strobilurin, and dithiocarbamate active ingredients manage rice blast, citrus black spot, and durian Phytophthora infections.
- Rodenticides:Anticoagulant and acute toxicant baits protect stored grain and field crops from rodent population surges during monsoon cycles.
Herbicides retain volume leadership; insecticides hold the steepest expansion curve amid resistance-driven product turnover.
Application:
Volume concentration varies sharply between commodity field systems and high-value permanent crop zones.
- Field Crops:Rice, corn, sugarcane, and cassava cultivation absorbs bulk formulation volumes through broadcast spraying and soil incorporation methods. The Northeast's corn belt and Central Plains rice districts generate repeat purchase cycles tied to planting calendars, with cooperative procurement consolidating hectare-scale orders.
- Horticultural Crops:Chili, tomato, cabbage, and leafy vegetable production demands precise fungicide and insecticide timing to meet EU and Japanese MRL thresholds for export consignments. Chiang Mai and Phetchabun provinces drive specialized blend demand where residue-tested protocols command price premiums.
- Permanent Crops:Durian, longan, mangosteen, and rubber estates require multi-year disease management programs with distinct chemical rotations.
- Turf & Ornamental:Golf course maintenance and ornamental nursery operations utilize selective herbicides and systemic fungicides for aesthetic quality standards.
Field crops anchor absolute volume; horticultural crops generate the highest margin per treated hectare through export compliance premiums.
Formulation:
Physical form selection reflects equipment compatibility, storage infrastructure, and precision application requirements.
- Emulsifiable Concentrates:Oil-in-water emulsion systems containing solvent-dissolved active ingredients deliver reliable efficacy across conventional knapsack and tractor-mounted sprayers. Farmer familiarity in the Central Plains sustains repeat purchases despite higher dermal exposure risks compared to aqueous alternatives.
- Liquids:Suspension concentrates and soluble liquids enable rapid tank mixing and reduced drift in orchard applications. Drone spraying adoption across northern agricultural cooperatives demands ultra-low-volume liquid compatibility that legacy emulsifiable formulations cannot satisfy.
- Granules:Clay or polymer carrier matrices release active ingredients through soil moisture activation for root zone pest control.
- Solids:Wettable powders and water-dispersible granules address storage stability needs in humid tropical conditions.
Emulsifiable concentrates maintain installed base dominance; liquids gain share fastest through precision application hardware adoption.
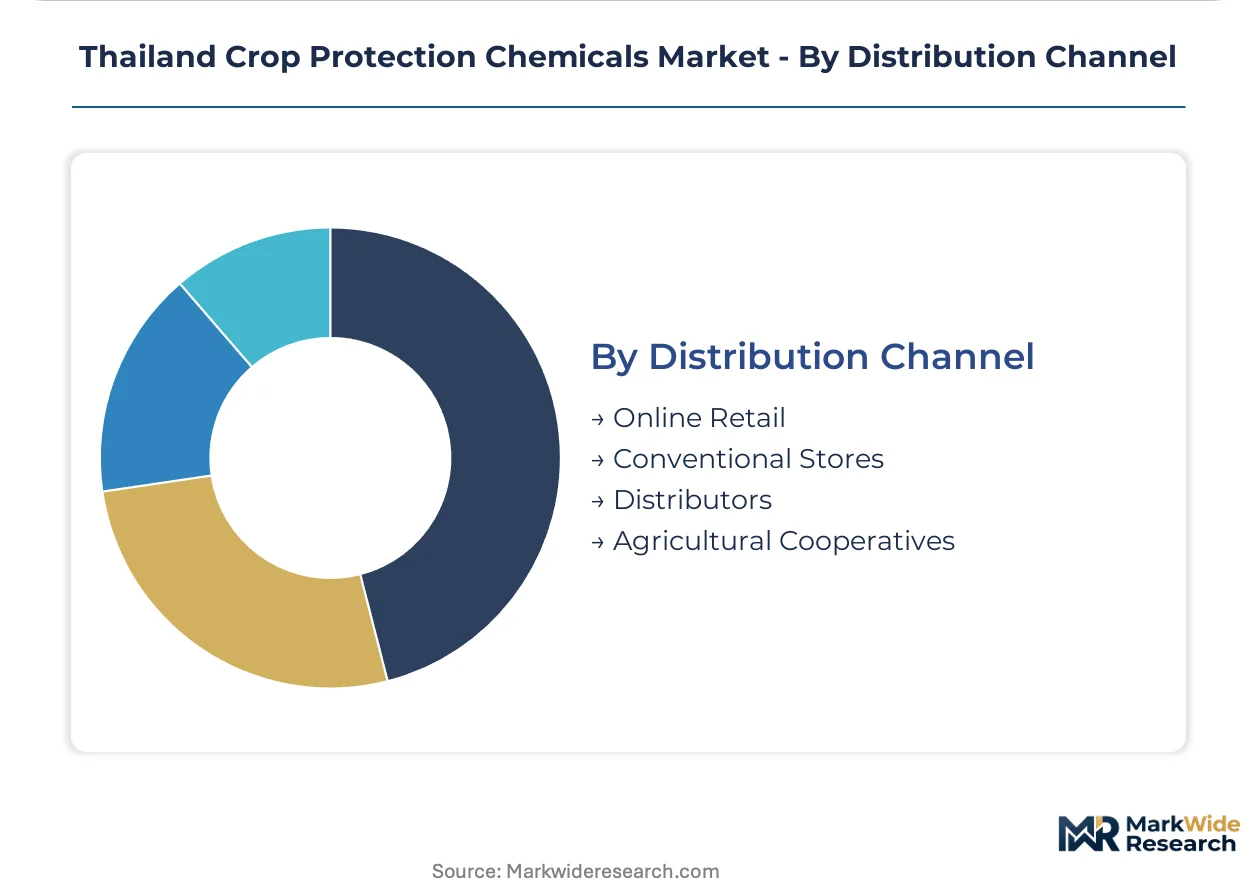
Distribution Channel:
Channel structure is fragmenting as cooperative buying power displaces traditional retail relationships.
- Agricultural Cooperatives:Member-owned procurement bodies in Ubon Ratchathani, Surin, and Nakhon Ratchasima provinces aggregate hectare volumes to negotiate direct manufacturer pricing and technical advisory services. Cooperative-employed agronomists assume resistance monitoring responsibilities that independent retailers cannot match.
- Distributors:Provincial-level stockists maintain inventory breadth and credit terms for smaller landholders outside cooperative catchment areas. Margin compression from cooperative bypass threatens mid-tier distributor viability in high-concentration farming zones.
- Conventional Stores:Rural agro-input retailers serve emergency purchase needs and small-plot farmers with limited storage capacity.
- Online Retail:E-commerce platforms enable price transparency and technical documentation access for progressive growers.
Agricultural cooperatives capture volume leadership; online retail posts the steepest expansion trajectory among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai crop protection chemical exports flow primarily to ASEAN neighbors and East Asian processing hubs, with cross-border trade corridors linking Bangkok-formulated products to Vietnamese rice deltas and Indonesian palm estates.
Central Plains
Rice monoculture across Nakhon Pathom and Suphan Buri provinces consumes pre-emergent herbicide volumes as mechanized transplanting displaces manual labor. The Ministry of Agriculture enforces EU-aligned MRL protocols for export-bound fragrant rice varieties. Formulation plants in Ayutthaya and Pathum Thani distribute emulsifiable concentrates through cooperative networks serving hectare-scale paddy operations.
Northeast Region
Fall armyworm pressure across Nakhon Ratchasima and Khon Kaen corn belts sustains insecticide turnover amid pyrethroid resistance spread. The Hazardous Substance Act amendments accelerate biological registration for Bacillus thuringiensis alternatives. Agricultural cooperatives in Ubon Ratchathani aggregate procurement volumes to negotiate direct manufacturer pricing, bypassing provincial distributor margins.
Northern Region
Chiang Mai and Phetchabun vegetable seedling producers trial RNA interference sprays against diamondback moth populations in protected cultivation systems. The Department of Agriculture mandates residue testing for chili and tomato consignments bound for Japanese supermarkets. Drone spraying cooperatives in Lampang deploy ultra-low-volume formulations incompatible with legacy emulsifiable concentrates.
Eastern Region
Durian and mangosteen orchards across Rayong and Chanthaburi provinces drive fungicide demand for Phytophthora and anthracnose management in premium export segments. The Thai Organic Agriculture Standard certification creates price multiples in domestic retail channels. Cooperative buying groups consolidate procurement of residue-tested proprietary blends to satisfy EU import thresholds.
Southern Region
Rubber estates in Surat Thani and Nakhon Si Thammarat apply multi-year disease management programs with distinct chemical rotations for powdery mildew and leaf fall control. The Hazardous Substance Act shortens re-registration cycles for legacy fungicide chemistries. Smallholder fragmentation across Krabi and Trang provinces sustains conventional retail channel relevance for emergency purchase needs.
Thailand Crop Protection Chemicals Market Key Industry Players
Channel-controlling players compete with product-specialist players across a moderately consolidated vendor base. Multinational agrochemical groups anchor volume leadership through cooperative network penetration, while domestic formulators defend niche positions in regional crop segments. Three archetypes dominate: global integrated majors with biological pipeline investments, regional distributors with provincial stockholding capacity, and cooperative-aligned local blenders with resistance monitoring capabilities. Competitive moves concentrate on distributor acquisition to secure cooperative procurement channels and biological formulation licensing to preempt regulatory phase-outs.
Within the global integrated tier, Syngenta Group and Bayer AG exemplify channel-controlling strategies through agricultural cooperative network dominance. Corteva Agriscience occupies a product-specialist position emphasizing next-generation herbicide molecules for resistant weed management. Among Asia-Pacific headquartered players, Sumitomo Chemical Co. Ltd. and UPL Ltd. represent regional scale archetypes with ASEAN distribution infrastructure. BASF SE and ADAMA Agriculture Solutions sit within the diversified chemical conglomerate category, leveraging backward integration into active ingredient supply.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Sumitomo Chemical Co. Ltd. |
| Syngenta Group |
| Sahaikaset Agrochemicals Co Ltd |
| UPL Ltd. |
| BASF SE |
| ADAMA Agriculture Solutions |
| Sotus International Co Ltd |
| Bayer AG |
| Others |
Cost & Logistics Intelligence
Chonburi and Rayong chemical parks concentrate technical-grade active ingredient formulation capacity, and this geographic clustering grants incumbent blenders pricing leverage over provincial distributors serving fragmented smallholder networks. Cooperative procurement consolidation in the Northeast and Central Plains compresses distributor margins while elevating manufacturer-direct negotiation power.
Pricing Analysis
Legacy emulsifiable concentrate formulations trade at commodity price points against premium liquid suspension concentrates and next-generation biological alternatives. Three-tier pricing structure across premium, standard, and economy levels separates residue-tested export-grade blends from domestic-use generics and unbranded imports. Pricing pressure stems from cooperative volume aggregation that eliminates distributor markups in corn and rice belts. Smallholder farmers outside cooperative catchment areas exhibit highest price sensitivity, while export-oriented durian and mangosteen growers absorb premium fungicide costs to secure EU market access.
Supply Chain Analysis
Extended payment terms from Chinese chemical parks to Thai formulators stretch working capital cycles and amplify exposure to yuan fluctuation. Over seventy percent of technical-grade synthetics originate from Chinese, Indian, and Vietnamese manufacturing hubs. Formulation chemistry draws from imported active ingredients, domestic solvent supplies, and specialized microbial culture substrates. Single-source vulnerability concentrates in paraquat alternative sourcing as neighboring ASEAN bans reshape regional trade flows. Distribution runs through agricultural cooperative networks that displace independent provincial stockists in high-volume farming zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's crop protection sector faces substitution pressure from mechanical weeding adoption and cover cropping expansion as paraquat bans in Vietnam and Malaysia normalize non-chemical alternatives. Incumbents must defend formulation volumes against this behavioral shift while capturing biological registration windows.
For Market Incumbents: Entrench cooperative advisory relationships by embedding resistance monitoring agronomists within Ubon Ratchathani and Surin procurement bodies. Secure backward integration into Bacillus thuringiensis culture production to preempt biological formulation shortages. Accelerate ultra-low-volume liquid R&D to match drone spraying hardware adoption across northern agricultural cooperatives.
For New Entrants and Emerging Players: Southern Region rubber estate fungicide programs present underpenetrated white space where smallholder fragmentation sustains conventional retail channel relevance. Target durian Phytophthora management in Rayong with residue-tested proprietary blends certified for EU import thresholds. Pursue direct technical service partnerships with provincial Department of Agriculture extension offices to bypass cooperative procurement concentration.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biological pipeline specialists with Hazardous Substance Act registration expertise over legacy synthetic formulators facing re-registration compression. Acquisition targets should demonstrate cooperative network penetration in the Isaan corn belt or drone-compatible formulation portfolios. Monitor fall armyworm resistance spread as inflection indicator for pyrethroid substitution velocity and Bacillus thuringiensis adoption curves.
| Strategic Initiative | Industry Significance |
|---|---|
| Biological Formulation Licensing | Secures regulatory runway under Hazardous Substance Act amendment timelines for low-toxicity alternatives. |
| Cooperative Network Acquisition | Captures volume aggregation in Nakhon Ratchasima and Khon Kaen corn belts displacing distributor intermediaries. |
| Drone-Compatible Formulation Development | Aligns product portfolios with UAV spraying adoption across Lampang and Chiang Mai agricultural cooperatives. |
| Residue Testing Infrastructure Investment | Enables EU and Japanese MRL compliance premiums for durian and mangosteen export consignments. |
| Active Ingredient Backward Integration | Reduces exposure to Chinese chemical park shipping volatility and yuan-denominated input costs. |
Research Approach
Two parallel data streams informed the analysis: structured interviews with formulation plant managers, agricultural cooperative procurement officers, Department of Agriculture extension specialists, and provincial distributor principals; and secondary validation through Thai customs trade records, Hazardous Substance Act registration databases, EU MRL compliance documentation, and ASEAN cross-border chemical movement reports. Bottom-up volume triangulation across crop-specific treatment rates and hectare estimates converged with top-down manufacturer shipment data.
Forecast inputs incorporated mechanization adoption curves, labor scarcity indices in the Central Plains, and re-registration timelines under amended toxicology requirements. Segmentation modeling spanned product chemistry generations, formulation physical states, crop application categories, and channel structure evolution. CAGRs derived from slope analysis across projected annual volume and value outputs throughout the forecast period, with biological penetration rates and drone spraying hardware deployment as key sensitivity variables.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese generic manufacturers or cooperative-led backward integration initiatives would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Fumigation Market
Crop Protection
Dicamba Market
Crop Protection
Global Phosphine Fumigation Market
Crop Protection
Vietnam Insecticide Market
Crop Protection
North America Crop Protection Chemicals Market
Crop Protection
Global Integrated Pest Management (IPM) Pheromones Market
Crop Protection
Indonesia Fungicide Market
Crop Protection
Russia Crop Protection Chemicals Market
Crop Protection
Global Seed Treatment Fungicides Market
Crop Protection
Herbicide Safeners Market
Crop Protection
Europe Nematicide Market
Crop Protection
Vietnam Herbicide Market
Crop Protection
IPM Pheromones Market
Crop Protection
Europe Crop Protection Chemicals Market
Crop Protection
China Crop Protection Chemicals Market
Crop Protection
Synthetic Pesticide Market