
 Global Aquatic Herbicides Market | 2026-2036
Global Aquatic Herbicides Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aquatic Herbicides Market Foresight
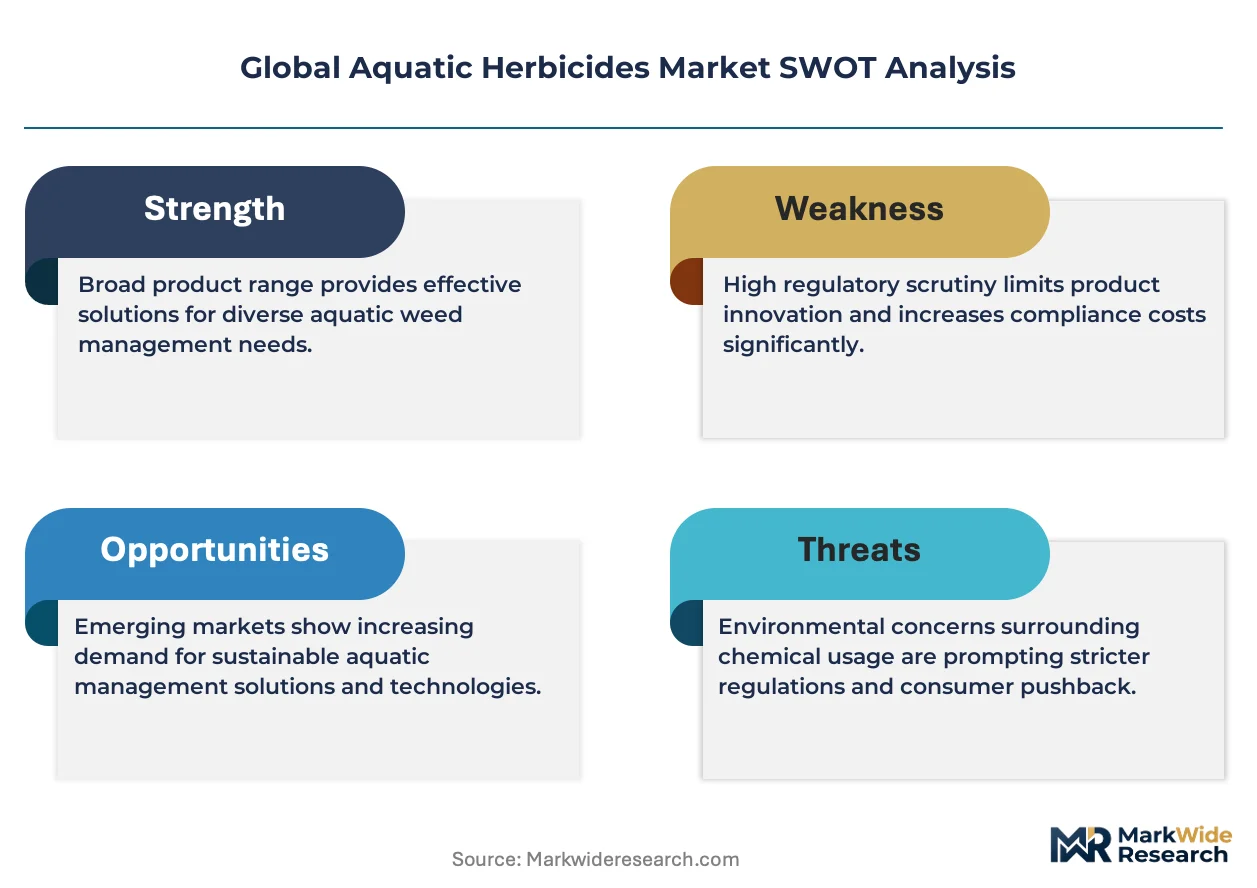
ISO 17025 accreditation for aquatic toxicity testing laboratories is rotating the competitive landscape toward credentialed suppliers. Syngenta AG leverages its global formulation network to supply glyphosate and diquat-based products across multiple continents. BASF SE anchors European supply through its Ludwigshafen manufacturing complex, sustaining regional distribution density for fluridone and triclopyr chemistries. SePRO Corporation specializes in proprietary fluridone formulations, dominating the U.S. lake and pond maintenance channel through technical service bundling.
Aquatic herbicides comprise synthetic or biological chemical formulations designed to control submerged, emergent, or floating vegetation in water bodies, typically applied at concentrations between 0.1 and 10 parts per million depending on target species and water volume. Their primary commercial purpose is to restore navigability, protect irrigation infrastructure, and maintain ecological balance in managed freshwater systems. Systemic herbicides command the largest value share because fluridone and glyphosate require lower application frequencies for deep-rooted plants, concentrating margin pools with technical-grade suppliers. Contact herbicides compete on speed of visible results for municipal contracts with performance-based payment terms. Application through irrigation canals represents the fastest-expanding segment as drought-stressed regions prioritize water conveyance efficiency.
The EPA regulates all aquatic herbicides under FIFRA, requiring extensive ecotoxicology data that extends registration timelines and elevates development costs for new active ingredients. The EU's REACH framework and Biocidal Products Regulation restrict certain copper-based and synthetic chemistries, redirecting formulation investment toward bio-based alternatives in European markets. China's MEE enforces discharge standards for chemical runoff into watersheds, conditioning market access on environmental compliance documentation. Stakeholders must monitor evolving residue limits in drinking water sources and align product pipelines with jurisdictions tightening aquatic pesticide buffers.
Market Dynamics
EPA's tightening FIFRA registration timelines are compressing active ingredient pipelines while municipal water authorities accelerate invasive species treatment cycles, creating a structural squeeze between supply rigidity and demand recurrence.
Growth Catalysts
- Submerged vegetation proliferation:Hydrilla and water hyacinth infestations in southeastern United States waterways force recurring municipal treatment contracts with multi-year renewal structures.
- REACH biocidal product streamlining:ECHA's consolidated authorization pathways for existing chemistries reduce re-registration friction for copper-based and synthetic formulations in European lake management programs.
- Irrigation conveyance efficiency mandates:Drought-stressed agricultural districts in Australia and Spain prioritize canal clearance protocols, expanding herbicide application frequency in water infrastructure maintenance.
Market Restraints
- Technical-grade supply concentration:Glyphosate and diquat active ingredient manufacturing clusters in eastern China create geographic vulnerability to environmental compliance disruptions under MEE discharge enforcement.
- Ecotoxicology data requirements:EPA's expanded chronic toxicity studies for non-target aquatic species extend development timelines and elevate registration costs for novel active ingredients.
- Biological control substitution:Grass carp and weevil biocontrol programs in Florida and Texas public water bodies displace chemical treatment for certain macrophyte species.
Strategic Opportunities
- Bio-based formulation development:EU Green Deal chemical sustainability targets redirect R&D investment toward pelargonic acid and other plant-derived herbicides for European pond maintenance channels.
- Precision application technology:Drone-based spot-spraying systems enable targeted treatment of floating mats without whole-lake dosing, opening municipal contracts with strict buffer requirements.
- Technical service bundling:Water quality monitoring and post-treatment efficacy verification create recurring revenue attachments beyond product supply in U.S. lake management markets.
Industry Challenges
- Aquatic toxicology certification scarcity:ISO 17025-accredited laboratories capable of conducting standardized fish and invertebrate exposure studies remain limited, creating testing bottlenecks for new product submissions.
- Residue monitoring infrastructure gaps:Drinking water utilities lack standardized protocols for detecting fluridone and triclopyr metabolites at sub-ppb thresholds, complicating regulatory compliance verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aquatic Herbicides Market |
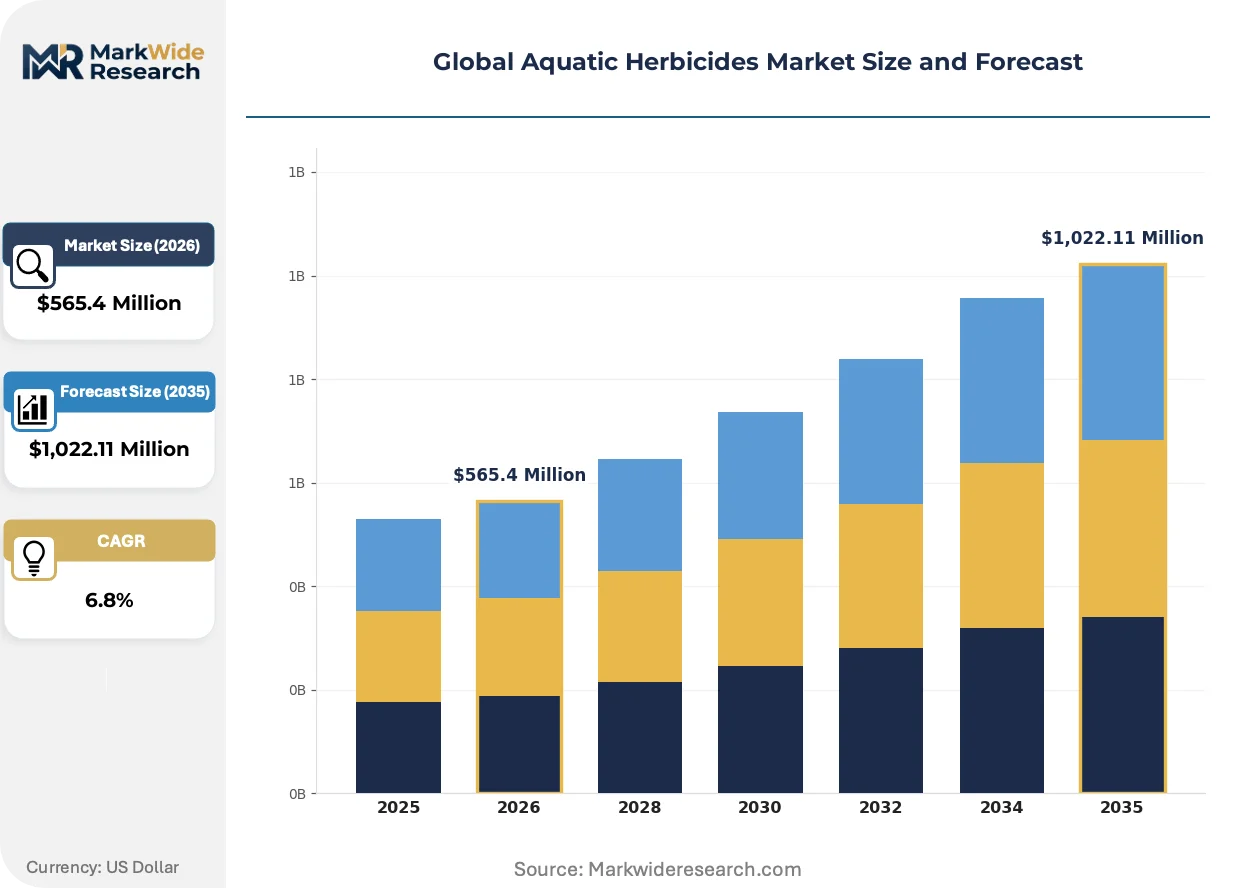
| Market Size in 2026 | $565.4 Million |
| Market Size in 2035 | $1,022.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Herbicides, Systemic Herbicides, Selective Herbicides, Non-Selective Herbicides Application: Weed Control in Lakes, Pond Maintenance, Irrigation Canals, Reservoir Treatment, Waterways Management Form: Liquid, Granular, Pellet, Emulsifiable Concentrate End User: Municipal Water Authorities, Agricultural Farms, Aquaculture Operations, Environmental Agencies |
| Companies Covered | Syngenta AG, BASF SE, UPL Limited, Nufarm Limited, Corteva Inc., SePRO Corporation, FMC Corporation, Dow Chemical, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aquatic Herbicides Market Shifts & Advancements
Formulation chemistry and application precision are converging to reduce environmental load while maintaining treatment efficacy, reshaping how water authorities evaluate vendor capabilities beyond active ingredient cost.
Encapsulated release formulations are decomposing the traditional trade-off between treatment persistence and ecological safety. SePRO Corporation and specialty manufacturers deploy polymer-coated fluridone granules that sink through water columns for targeted root-zone delivery. Municipal lake managers in Minnesota and Wisconsin adopt these systems to reduce dosing frequency while satisfying state agency non-target species concerns.
REACH authorization reviews are compressing copper-based herbicide availability across European Union member states. ECHA's 2024 substance evaluation conclusions on copper sulfate pentahydrate restrict agricultural and aquatic applications unless comprehensive environmental exposure assessments are submitted. Formulators accelerate pelargonic acid and diquat dibromide alternatives for French and Italian pond maintenance channels previously dependent on copper chemistries.
Performance-based contracting is displacing traditional product-supply arrangements in U.S. municipal procurement. Florida water management districts now specify vegetation-free surface area outcomes rather than gallons applied, forcing applicators to absorb efficacy risk and invest in monitoring technology. This shift concentrates contract awards with integrated service providers capable of real-time biomass assessment and adaptive dosing protocols.
Global Aquatic Herbicides Market Segmentation
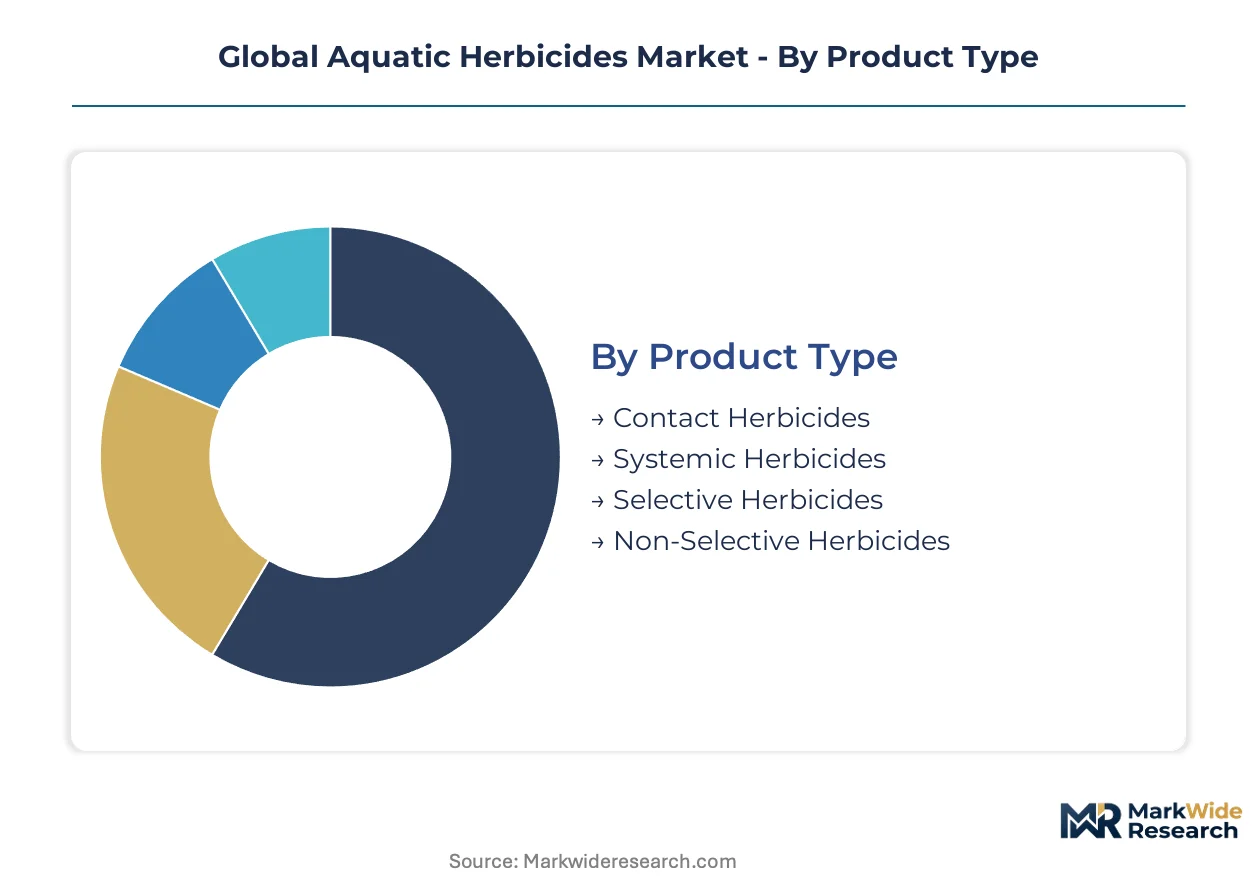
Product formulation and application method determine channel access and pricing power in aquatic herbicide markets. Technical service bundling concentrates margin in systemic formulations, while commodity contact products compete through distributor volume rebates.
Product Type:
Channel mix varies sharply by mode of action—systemic herbicides flow through technical service providers, contact products through agricultural distributors.
- Contact Herbicides:Diquat and endothall formulations disrupt cellular membranes upon contact, delivering visible necrosis within 48-72 hours. Demand clusters in Florida municipal contracts with performance-based payment terms tied to surface clearance metrics. By volume, Contact Herbicides lead. By growth pace, Systemic Herbicides is ahead.
- Systemic Herbicides:Fluridone and glyphosate translocate through vascular tissues to root systems, enabling single-treatment control of deep-rooted macrophytes. Minnesota lake management districts prioritize these formulations to reduce application frequency and labor mobilization costs.
- Selective Herbicides:Species-specific chemistries like 2,4-D target broadleaf vegetation while sparing monocot grasses, serving Texas reservoir operators managing mixed aquatic communities.
- Non-Selective Herbicides:Broad-spectrum copper sulfate and diquat formulations eliminate all vegetation classes, deployed in California irrigation canal maintenance where total biomass clearance is required.
Margin pools concentrate with systemic chemistries requiring lower application frequency; contact products compete on speed of visible results.
Application:
End-use setting dictates regulatory scrutiny intensity and formulation specification—drinking water sources face residue monitoring mandates absent in irrigation systems.
- Weed Control in Lakes:Whole-lake fluridone treatments target hydrilla and Eurasian watermilfoil in recreational water bodies, with Wisconsin lake associations representing concentrated procurement volume. By volume, Weed Control in Lakes leads. By growth pace, Irrigation Canals is expanding most quickly.
- Pond Maintenance:Golf course and residential pond managers apply pelletized copper complexes and diquat for filamentous algae control, with seasonal treatment cycles concentrated in southeastern states.
- Irrigation Canals:Flowing-water glyphosate and 2,4-D applications prevent conveyance obstruction in Australia Murray-Darling Basin and Spain Ebro watershed infrastructure.
- Reservoir Treatment:Municipal drinking water sources require EPA-approved formulations with established maximum residue limits, extending procurement timelines through toxicology review requirements.
- Waterways Management:Navigable river and harbor authorities deploy rapid-action contact herbicides for emergency clearance of shipping channels, with US Army Corps of Engineers representing structured bidding opportunities.
Recurring revenue potential is highest in lake and pond channels; infrastructure applications concentrate volume in fewer, larger contracts.
Form:
Physical formulation determines application equipment requirements and labor intensity—liquid concentrates dominate professional applicator channels, pellets penetrate residential markets.
- Liquid:Ready-to-use and concentrate formulations enable calibrated spraying through boat-mounted or shoreline equipment, serving commercial applicators with EPA certification requirements. By volume, Liquid leads. By growth pace, Granular is climbing the fastest.
- Granular:Sinking polymer-coated particles release active ingredients at root zones, reducing non-target exposure and enabling spot treatment of submerged vegetation beds.
- Pellet:Compressed formulations simplify homeowner application without specialized equipment, penetrating retail channels in Florida and Texas recreational lake communities.
- Emulsifiable Concentrate:Oil-based carriers improve foliar penetration for emergent vegetation control, specified in California invasive species management contracts targeting water hyacinth.
Professional channels favor liquid and granular forms; pellet formats expand addressable market through retail accessibility.
End User:
Procurement sophistication varies by end user—municipal authorities employ technical specifications and multi-year contracts, farms prioritize unit economics.
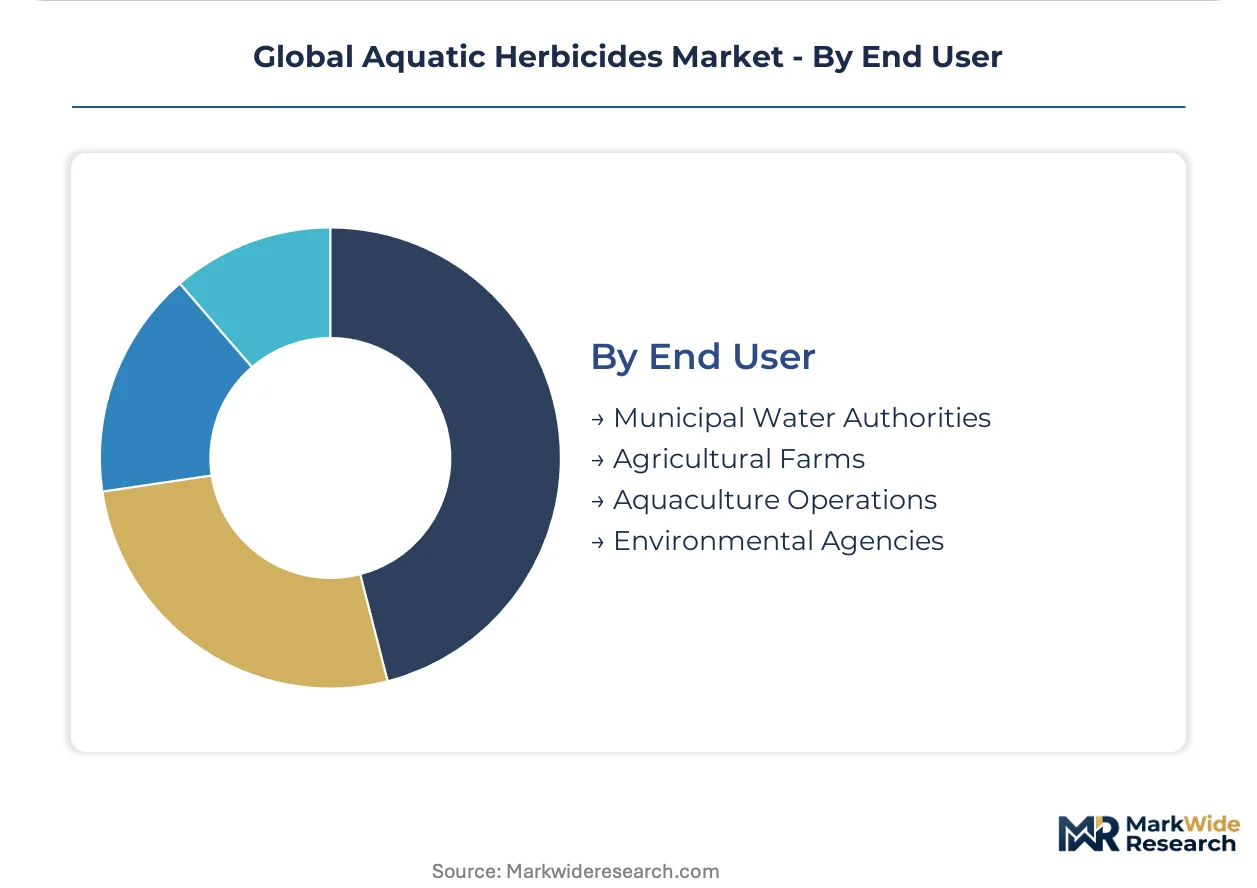
- Municipal Water Authorities:Cities and water management districts issue RFPs requiring ISO 17025-accredited laboratory support and post-treatment monitoring, concentrating supplier relationships with integrated service providers. By volume, Municipal Water Authorities lead. By growth pace, Aquaculture Operations is gaining share fastest.
- Agricultural Farms:Irrigation district members purchase through cooperative buying arrangements, with Australia and Spain drought-stressed regions expanding treatment frequency for conveyance efficiency.
- Aquaculture Operations:Fish and shrimp producers deploy species-safe formulations for pond vegetation management, with Southeast Asian markets driving formulation registration for aquaculture-specific labels.
- Environmental Agencies:State and federal restoration programs fund invasive species eradication, with US Fish and Wildlife Service grants supporting treatment in protected wetland systems.
Municipal contracts concentrate value through technical service attachments; agricultural and aquaculture segments expand volume through recurring maintenance cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA's FIFRA registration tightening and EU REACH biocidal reviews are redirecting formulation investment toward jurisdictions with streamlined authorization pathways, compressing commercialization timelines for suppliers with multi-regional portfolios.
United States
Hydrilla and water hyacinth infestations across Florida, Texas, and Louisiana waterways sustain recurring municipal treatment contracts with multi-year renewal structures. EPA's expanded chronic toxicity studies for non-target aquatic species extend development timelines for novel active ingredients. SePRO Corporation dominates the southeastern lake management channel through proprietary fluridone formulations bundled with technical service.
China
Technical-grade glyphosate and diquat manufacturing clusters in eastern provinces supply global formulation networks. MEE discharge enforcement under watershed protection mandates conditions market access on environmental compliance documentation. Zhejiang and Jiangsu chemical parks face production suspensions during environmental inspection campaigns, creating supply volatility for international herbicide blenders.
Germany
BASF SE anchors European supply through its Ludwigshafen manufacturing complex, sustaining regional distribution density for fluridone and triclopyr chemistries. ECHA's REACH authorization reviews compress copper-based herbicide availability, redirecting pond maintenance demand toward diquat dibromide alternatives. Bavarian lake associations drive procurement volume for submerged vegetation control in recreational water bodies.
Australia
Drought-stressed agricultural districts in the Murray-Darling Basin prioritize canal clearance protocols, expanding herbicide application frequency in water infrastructure maintenance. The country's national agricultural chemical regulator enforces residue limits in drinking water sources, conditioning product registration on environmental fate data. New South Wales irrigation authorities represent concentrated demand for flowing-water glyphosate applications.
Spain
Ebro watershed infrastructure operators deploy 2,4-D and glyphosate formulations to prevent conveyance obstruction in drought-affected regions. EU Green Deal chemical sustainability targets redirect R&D investment toward bio-based alternatives for European pond maintenance channels. Andalusian and Catalonian agricultural cooperatives expand treatment cycles to maintain irrigation efficiency under water scarcity mandates.
Global Aquatic Herbicides Market Competitive Landscape
Player mix skews toward integrated agrochemical conglomerates with captive active ingredient supply, compressing margin capture for standalone formulation specialists. Technical service bundling and ISO 17025-accredited laboratory support are concentrating municipal contract awards with full-service providers. Three archetypes dominate: global agrochemical majors with multi-continent manufacturing footprints, regional specialists with proprietary formulation platforms, and technical service integrators bundling monitoring with product supply. Competitive dynamics center on M&A-driven portfolio diversification into bio-based chemistries and precision application technology licensing.
Within the global agrochemical tier, Syngenta AG and BASF SE exemplify scale-driven supply architectures spanning multiple continents. SePRO Corporation occupies a specialist position in proprietary fluridone formulations for the U.S. lake and pond channel. UPL Limited represents the mid-tier integrated model with formulation networks across emerging and developed markets. These three anchors illustrate how competitive positioning stratifies between captive manufacturing depth and technical service intensity.
| Leading Market Players |
|---|
| Syngenta AG |
| BASF SE |
| UPL Limited |
| Nufarm Limited |
| Corteva Inc. |
| SePRO Corporation |
| FMC Corporation |
| Dow Chemical |
| Bayer AG |
| Others |
Supply & Pricing Matrix
Ninety-day technical-grade inventory cycles in glyphosate and diquat feedstocks compress margin buffers for formulation blenders while amplifying price volatility transmission from eastern Chinese manufacturing clusters to municipal procurement offices in Florida and Texas.
Pricing Analysis
Certification level creates the primary spread between municipal-grade and agricultural-grade formulations. Three-tier pricing structure across premium, standard, and economy levels segments the market by EPA registration tier and ISO 17025 laboratory support bundling. Cost compression in contact herbicide tiers is intensifying because glyphosate technical-grade oversupply from Zhejiang producers forces spot-price discounting. Agricultural farms exhibit highest price sensitivity due to cooperative buying leverage, while municipal water authorities absorb premium pricing for integrated monitoring services.
Supply Chain Analysis
Ninety-day technical-grade inventory cycles expose formulation networks to disruption cascades when MEE environmental inspections suspend production at Jiangsu and Zhejiang chemical parks. Active ingredient manufacturing draws from glyphosate and diquat technical-grade clusters in China, fluridone production at BASF's Ludwigshafen complex, and copper sulfate processing in Chile. Single-source vulnerability concentrates in Chinese technical-grade supply, where watershed discharge enforcement triggers unplanned output suspensions. Distribution runs through agricultural distributor networks for contact herbicides and direct technical service contracts for systemic formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone-based precision application and encapsulated release formulations are disrupting treatment economics, compressing the advantage of volume-based suppliers while elevating service-integrated providers as EPA residue monitoring requirements tighten.
For Market Incumbents: Secure captive supply of fluridone technical-grade through backward integration into Ludwigshafen-scale manufacturing or long-term offtake agreements with European suppliers. Defend municipal contract renewals by embedding ISO 17025-accredited water quality monitoring into standard service bundles, neutralizing price-only competition from agricultural distributors. For New Entrants and Emerging Players: Differentiate on bio-based formulation platforms targeting EU Green Deal compliance deadlines for French and Italian pond maintenance channels. Pelargonic acid and plant-derived chemistries represent the most penetrable white space, with ECHA's copper sulfate restrictions eliminating incumbent alternatives. Pursue aquaculture-specific label registrations in Southeast Asian markets where species-safe vegetation management lacks dedicated suppliers. For Investors and Strategic Acquirers: Carve-out targets emerge from agrochemical majors divesting non-core aquatic portfolios to concentrate on row-crop herbicides. Five-to-ten-year viability hinges on regulatory moat depth around novel active ingredient registrations. Watch for EPA chronic toxicity study completion announcements as inflection indicators for pipeline asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulated Formulation Development | Polymer-coated fluridone granules enable root-zone delivery while reducing non-target exposure in Minnesota lake districts. |
| ISO 17025 Laboratory Accreditation | Certified aquatic toxicity testing unlocks municipal contract eligibility as EPA extends data requirements for novel chemistries. |
| Drone-Based Spot-Spraying Deployment | Precision application technology satisfies buffer restrictions in Florida water management districts with performance-based contracting. |
| Backward Integration into Technical-Grade Supply | Captive glyphosate or diquat manufacturing insulates margin from MEE enforcement volatility in Chinese chemical parks. |
| Bio-Based Chemistry Registration | Pelargonic acid formulations secure EU pond maintenance share as ECHA restricts copper sulfate pentahydrate applications. |
Research Methodology
Cross-validation between primary interviews with municipal water authority procurement officers, aquatic herbicide formulation technical directors, and EPA registration consultants and secondary validation through FIFRA registration databases, ECHA authorization filings, and customs trade data anchors the qualitative findings. Bottom-up triangulation across product formulation volumes and top-down reconciliation against municipal treatment contract values ensures segmentation integrity.
Sensitivity analysis around EPA chronic toxicity study timelines and MEE enforcement intensity brackets the forecast envelope. Segmentation dimensions modeled include herbicide mode of action, application setting, physical formulation type, and end-user procurement sophistication across the analysis window. CAGRs derive from treatment cycle frequency projections in drought-stressed irrigation districts and invasive species infestation recurrence patterns in southeastern United States waterways.
Material uncertainties — regulatory authorization delays, technical-grade supply disruptions, biological control substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions about EPA registration pathway stability and EU biocidal product authorization continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Asia-Pacific Acaricides Market
Crop Protection
Larvicides Market
Crop Protection
Global Chlorpyrifos Market
Crop Protection
Poland Crop Protection Chemicals Market
Crop Protection
Europe Molluscicides Market
Crop Protection
Fosthiazate Market
Crop Protection
IPM Pheromones Market
Crop Protection
Fumigation Service Market
Crop Protection
Spain Crop Protection Chemicals Market
Crop Protection
United States Crop Protection Chemicals Market
Crop Protection
Asia-Pacific Nematicides Market
Crop Protection
Avicides Market
Crop Protection
Asia-Pacific Molluscicides Market
Crop Protection
Global Acephate Market
Crop Protection
Indonesia Insecticide Market
Crop Protection
South America Acaricides Market