
 NB-IoT Chipset Market | 2026-2036
NB-IoT Chipset Market Size, Share, and Industry Trends Forecast 2026-2036
NB-IoT Chipset Market Intelligence
3GPP Release 13 certification is rotating vendor eligibility across the NB-IoT chipset supply base, forcing second-tier suppliers to retest or exit. Qualcomm Technologies leverages its 5G modem IP to anchor premium integrated module designs. Nordic Semiconductor sustains dominance in ultra-low-power standalone chipsets through R&D intensity in Oslo. Huawei Technologies competes on manufacturing scale for multi-band variants serving domestic smart city rollouts.
An NB-IoT chipset is a narrowband radio-frequency integrated circuit operating in licensed sub-GHz spectrum with 200 kHz channel bandwidth, designed for battery-constrained devices requiring decade-long deployment cycles. These chipsets translate sensor data into cellular packets for cloud ingestion, primarily serving telemetry and command-and-control loops in distributed infrastructure. Power-efficient chips command margin concentration due to their suitability for unpowered remote endpoints, while secure element embedded variants are capturing fastest growth as OEMs confront firmware vulnerability exposure. Edge computing enabled architectures remain nascent but attract capital from industrial system integrators seeking localized anomaly detection.
CE marking under the EU Radio Equipment Directive gates European market access for transmitters, while China's MIIT enforces GB standard compliance for domestic frequency allocation. The FCC in the United States certifies emissions profiles for unlicensed-adjacent operation, creating a tri-regulatory compliance burden for multi-territory suppliers. Stakeholders must monitor spectrum refarming announcements from national regulators to anticipate chipset architecture obsolescence risks.
Market Dynamics
The NB-IoT chipset market is experiencing structural compression as 3GPP Release 14 compliance requirements force supplier consolidation while smart metering procurement accelerates across Asian utilities. This dual pressure is reshaping competitive positioning between integrated module specialists and standalone ultra-low-power vendors.
Growth Catalysts
- Smart Metering Mandates:China's State Grid and Southern Power Grid are deploying tens of millions of connected meters, creating sustained module demand. Utilities in India and Indonesia are following with tender programs.
- EU Radio Equipment Directive:CE marking requirements for sub-GHz transmitters are filtering non-compliant suppliers from European procurement channels. Industrial OEMs favor pre-certified chipsets to accelerate product launches.
- Industrial Automation Corridors:Manufacturing clusters in Guangdong and Jiangsu provinces are integrating NB-IoT for predictive maintenance. Battery-constrained sensors in unpowered locations require decade-long operational lifecycles.
Market Restraints
- Silicon Wafer Supply Concentration:Advanced node production for integrated modem-RF designs concentrates among Taiwan and South Korea foundries. Geopolitical friction creates allocation risk for fabless chipset vendors.
- Spectrum Refarming Uncertainty:National regulators in Brazil and Mexico are reallocating sub-GHz bands for 5G expansion. Chipset architectures face obsolescence if multi-band flexibility is not designed in.
- LPWAN Protocol Substitution:LoRaWAN and Sigfox networks compete for unlicensed spectrum applications. Municipal smart city projects in France and Spain have selected LoRa for certain use cases.
Strategic Opportunities
- Secure Element Integration:OEMs confronting firmware vulnerability exposure are demanding hardware-rooted trust architectures. Chipsets with embedded secure elements capture fastest growth in financial and critical infrastructure applications.
- Edge Computing Convergence:Industrial system integrators are investing in NB-IoT modules with localized anomaly detection. This technology convergence reduces cloud ingress costs for distributed manufacturing sites.
- India Smart City Mission:The government's AMRUT 2.0 program is funding water and waste management sensor networks. Domestic manufacturing incentives under PLI schemes attract chipset localization investments.
Industry Challenges
- RF Engineering Talent Scarcity:Narrowband modem design requires specialized expertise in interference mitigation and power optimization. European and North American vendors face recruitment competition from automotive radar and 5G baseband teams.
- Multi-Territory Certification Complexity:Suppliers targeting simultaneous FCC, CE, and MIIT compliance encounter divergent emissions testing protocols. Certification timeline compression strains quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NB-IoT Chipset Market |
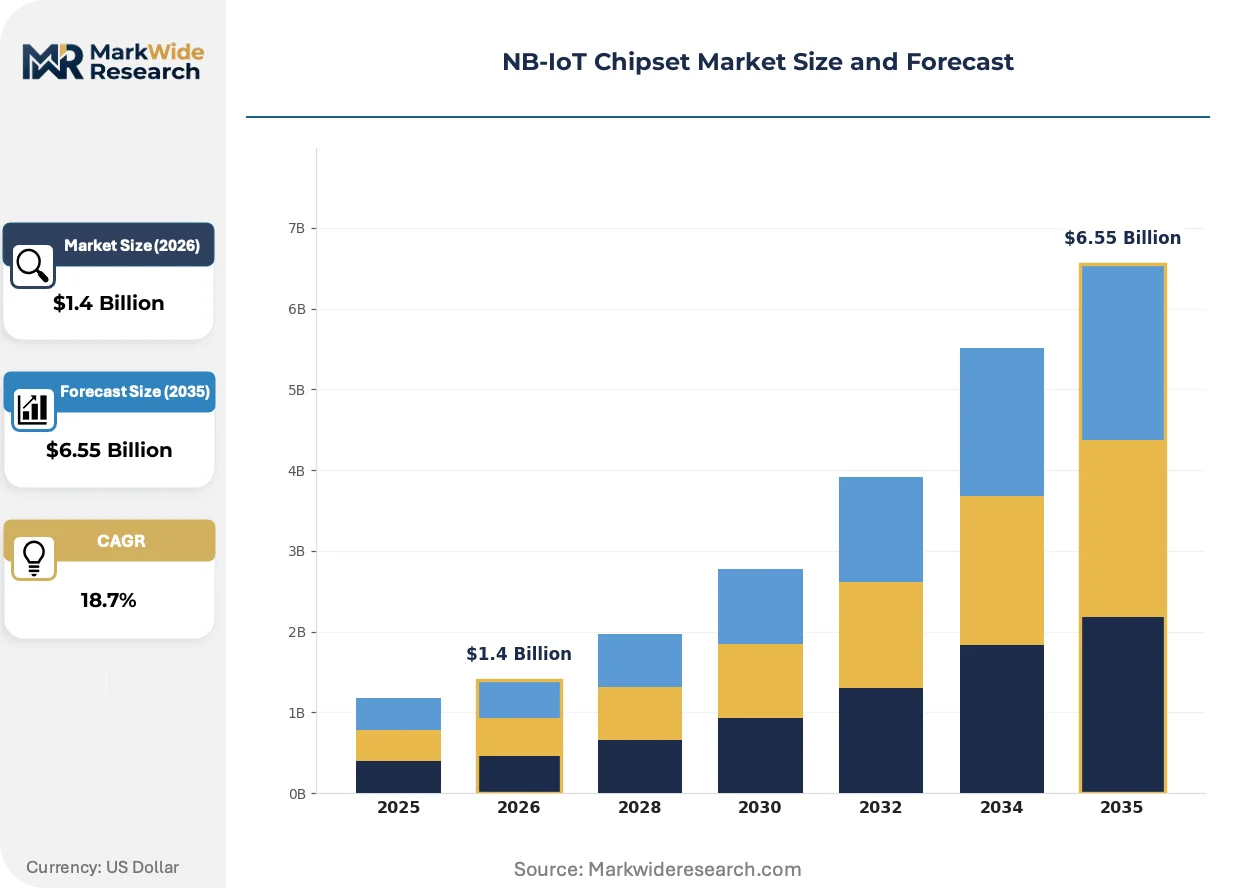
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $6.55 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Chipsets, Integrated Modules, Power-Efficient Chips, Multi-Band Chipsets, Low-Latency Chips Technology: LPWAN, 5G Compatible, Edge Computing Enabled, Secure Element Embedded, Frequency Division Duplex Application: Smart Metering, Asset Tracking, Environmental Monitoring, Smart Agriculture, Industrial Automation End User: Telecom Equipment Manufacturers, Smart City Developers, Utilities Providers, Agriculture Technology Companies, Industrial System Integrators |
| Companies Covered | Nordic Semiconductor ASA, Renesas Electronics Corporation, Huawei Technologies Co. Ltd., Sercomm Corporation, u-blox AG, Qualcomm Technologies Inc., MediaTek Inc., SIMCom Wireless Solutions Limited, Samsung Electronics Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NB-IoT Chipset Market Strategic Shifts & Innovations
NB-IoT chipset architectures are bifurcating between premium integrated designs and ultra-low-power standalone variants. This technical schism reflects diverging end-use requirements across industrial telemetry and consumer asset tracking.
Integrated modem-RF system-on-chip designs are bifurcating the premium tier of the market. Smart city infrastructure developers in Germany and Japan are selecting these modules for multi-band flexibility and reduced bill-of-materials complexity. The structural consequence is compressing margin pools for discrete component suppliers unable to match functional integration.
China's MIIT is tightening GB standard compliance enforcement for domestic frequency allocation. This policy shift is accelerating chipset architecture redesigns to support Band 5 and Band 8 variants simultaneously. Domestic OEMs serving state-backed smart city rollouts are prioritizing MIIT pre-certified modules to avoid deployment delays.
Utility procurement departments are consolidating vendor relationships around full-stack solution providers. This behavioral shift is displacing component-only suppliers in favor of module integrators offering cloud connectivity platforms. The transformation is most visible in Asia-Pacific markets where state-owned utilities dominate smart metering deployment timelines.
NB-IoT Chipset Market Segmentation
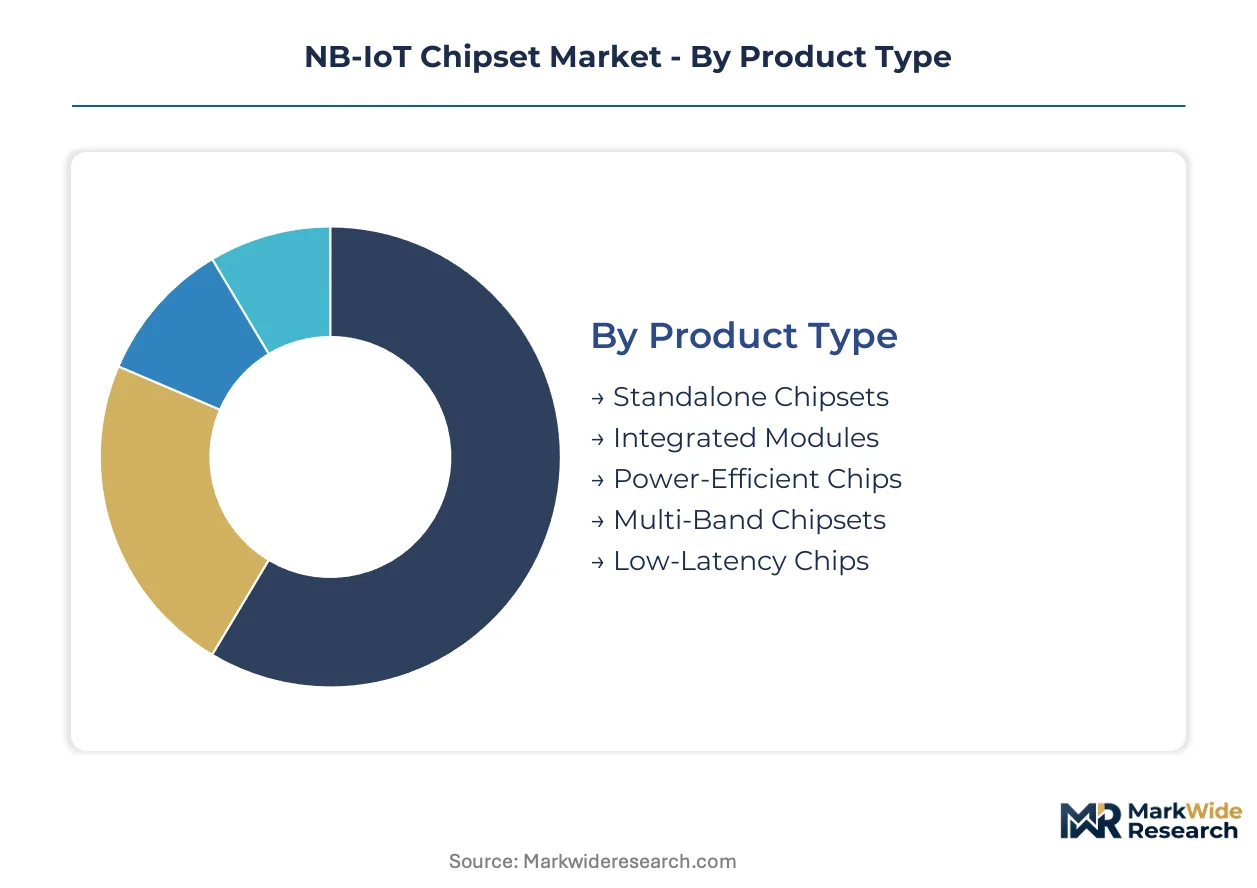
NB-IoT chipset procurement patterns diverge sharply across technical specifications, with regulatory compliance requirements and deployment environment constraints determining vendor selection criteria. Understanding these segment boundaries clarifies where margin pools concentrate and which architectural approaches capture volume.
Product Type:
CE marking under the EU Radio Equipment Directive and China's MIIT GB standards enforcement create divergent certification burdens that reshape product type demand.
- Standalone Chipsets:Discrete narrowband modem ICs requiring external RF front-end components. Nordic Semiconductor dominates this tier through R&D intensity in Oslo, serving battery-constrained sensors in unpowered remote endpoints across Scandinavian environmental monitoring networks.
- Integrated Modules:System-in-package designs combining modem, RF transceiver, and power management. Smart city infrastructure developers in Germany and Japan select these for multi-band flexibility and reduced bill-of-materials complexity in dense urban deployments.
- Power-Efficient Chips:Sub-milliampere sleep current designs for decade-long battery life. These address agricultural sensors and pipeline monitors in Australia's remote infrastructure corridors.
- Multi-Band Chipsets:Architectures supporting Band 5, Band 8, and Band 20 simultaneously. China's MIIT tightening drives redesigns for simultaneous domestic and export market compliance.
- Low-Latency Chips:Reduced transmission time interval variants for command-and-control applications. Industrial automation corridors in Guangdong province deploy these for predictive maintenance loops.
Established volume favors integrated modules; emerging adoption favors power-efficient chips.
Technology:
Cost tier differentiation separates premium architectures with hardware security from baseline LPWAN implementations.
- LPWAN:Core narrowband physical layer implementations per 3GPP Release 13/14. Baseline technology capturing volume in India's AMRUT 2.0 water management sensor networks funded through central government programs.
- 5G Compatible:Dual-mode designs supporting NB-IoT and NR-RedCap transition paths. Qualcomm leverages 5G modem IP to anchor premium integrated designs for telecom equipment manufacturers preparing network evolution.
- Edge Computing Enabled:On-chip microcontrollers with localized inference capability. Industrial system integrators in Japan's manufacturing clusters invest here for anomaly detection without cloud ingress.
- Secure Element Embedded:Hardware-rooted trust architectures with tamper-resistant credential storage. Financial and critical infrastructure OEMs confronting firmware vulnerability exposure drive steepest expansion trajectory in this tier.
- Frequency Division Duplex:Asymmetric uplink-heavy designs optimizing for telemetry-dominant traffic patterns. Utilities providers favor these for smart metering where sensor-to-cloud data flows exceed downlink commands.
Procurement concentrates on LPWAN for scale deployments; pilot budgets flow toward edge computing enabled variants.
Application:
Customer type determines whether chipsets ship as components or as part of full-stack solution contracts.
- Smart Metering:Electricity, gas, and water meter connectivity representing the largest procurement volume globally. China's State Grid and Southern Power Grid deployments create sustained module demand across tens of millions of endpoints.
- Asset Tracking:Container, vehicle, and equipment location monitoring. Logistics operators in Singapore and Rotterdam port complexes drive multi-band chipset requirements for cross-border visibility.
- Environmental Monitoring:Air quality, water level, and seismic sensors. Brazil's national water agency implements these for Amazon basin hydrological data collection despite spectrum refarming uncertainty.
- Smart Agriculture:Soil moisture, livestock health, and irrigation control. Indonesia's palm oil plantations and Netherlands' greenhouse complexes represent contrasting deployment scales.
- Industrial Automation:Predictive maintenance and safety monitoring in manufacturing. Jiangsu province clusters integrate battery-constrained sensors requiring decade-long operational lifecycles.
Smart metering commands procurement volume; industrial automation captures fastest technology refresh cycles.
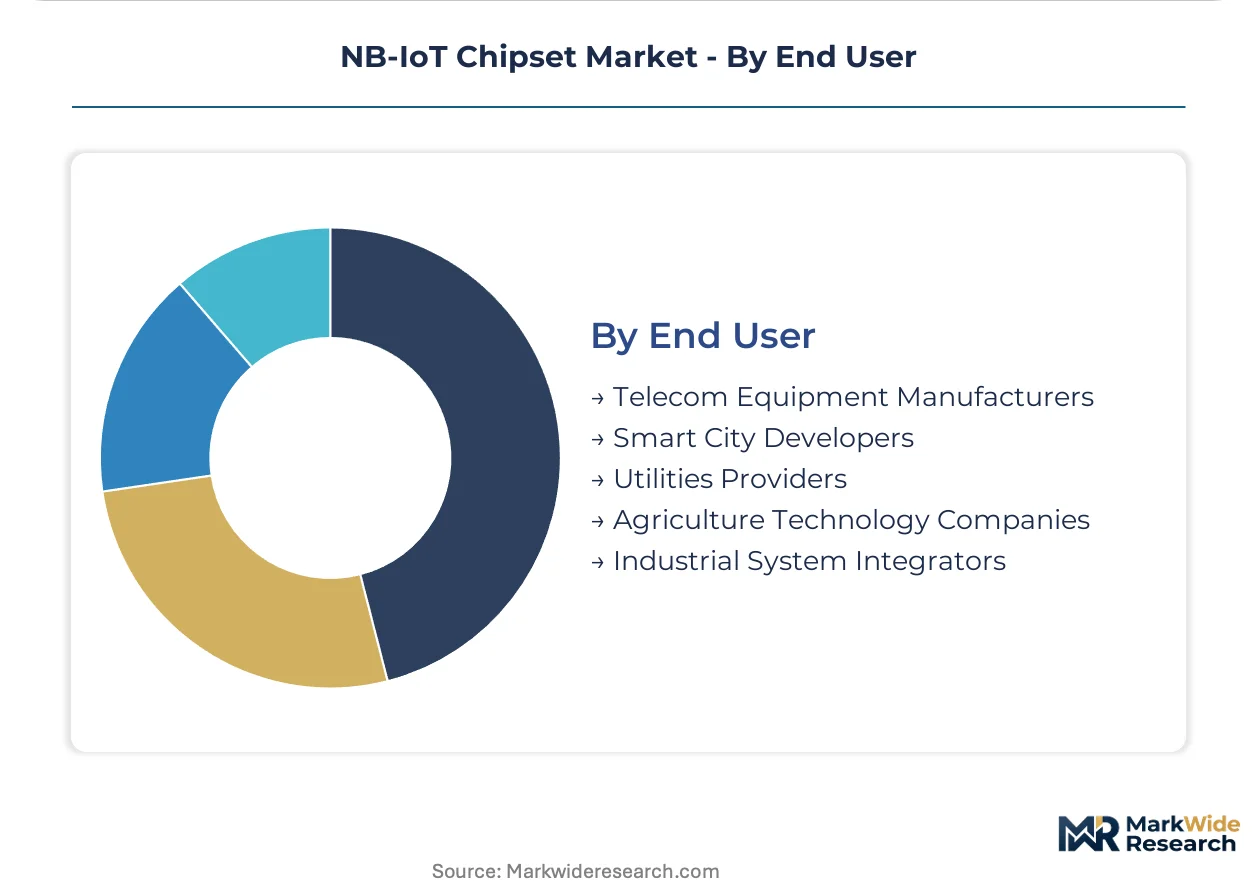
End User:
Supply concentration among Taiwan and South Korea foundries shapes which end users secure allocation during capacity constraints.
- Telecom Equipment Manufacturers:Base station and core network vendors integrating NB-IoT into cellular infrastructure. These buyers prioritize 5G compatible architectures for roadmap alignment.
- Smart City Developers:Municipal and state-level project implementers. German cities selecting pre-certified modules to accelerate launches under EU Radio Equipment Directive timelines.
- Utilities Providers:Electricity, water, and gas distribution companies. Consolidating vendor relationships around full-stack solution providers, displacing component-only suppliers.
- Agriculture Technology Companies:Precision farming system vendors. India's PLI scheme domestic manufacturing incentives attract localization investments for this customer segment.
- Industrial System Integrators:Manufacturing automation specialists. These buyers invest in edge computing enabled architectures for localized anomaly detection reducing cloud ingress costs.
Utilities providers anchor procurement volume; industrial system integrators drive architecture innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's State Grid transmission backbone underwrites the geography's dominance in NB-IoT module procurement. Utility-scale smart metering deployments across Asia concentrate demand in manufacturing corridors with established cellular infrastructure ecosystems.
China
State Grid and Southern Power Grid are deploying tens of millions of connected electricity meters, creating sustained chipset demand. MIIT enforces GB standard compliance for domestic frequency allocation, forcing architecture redesigns for Band 5 and Band 8 support. Manufacturing clusters in Guangdong and Jiangsu provinces integrate battery-constrained sensors for predictive maintenance loops.
Germany
Smart city infrastructure developers select integrated modules for multi-band flexibility in dense urban deployments. CE marking under the EU Radio Equipment Directive filters non-compliant suppliers from procurement channels. Industrial OEMs in Bavaria favor pre-certified chipsets to accelerate product launches under regulatory timelines.
United States
Logistics operators at the Port of Los Angeles and Long Beach drive multi-band chipset requirements for cross-border container visibility. FCC certifies emissions profiles for unlicensed-adjacent operation, creating compliance burden for multi-territory suppliers. Telecom equipment manufacturers prioritize 5G compatible architectures for network evolution roadmaps.
India
The AMRUT 2.0 program funds water and waste management sensor networks across municipal jurisdictions. PLI scheme domestic manufacturing incentives attract chipset localization investments for agriculture technology companies. Procurement is consolidating around full-stack solution providers serving state-level utilities.
Japan
Industrial system integrators in the Nagoya manufacturing cluster invest in edge computing enabled architectures for localized anomaly detection. METI standards shape procurement criteria for critical infrastructure applications. Battery-constrained sensors in remote pipeline monitors require decade-long operational lifecycles.
NB-IoT Chipset Market Key Industry Players
Listed leaders compete with private specialists across integrated versus standalone design philosophies. The supplier base compresses into two tiers: premium integrated module vendors and ultra-low-power discrete specialists. Three archetypes dominate: fabless semiconductor designers with 5G IP leverage, European R&D-intensive standalone vendors, and Asian scale manufacturers serving domestic rollouts. Competitive moves center on secure element integration partnerships and multi-territory certification pre-qualification.
Within the integrated module tier, Qualcomm Technologies Inc. and MediaTek Inc. exemplify premium architecture positioning, while Nordic Semiconductor ASA anchors the ultra-low-power standalone segment. Huawei Technologies Co. Ltd. occupies a scale-driven position serving state-backed deployments. These three represent divergent strategic bets on whether chipset value concentrates at the high-integration or power-optimization frontier.
| Leading Market Players |
|---|
| Nordic Semiconductor ASA |
| Renesas Electronics Corporation |
| Huawei Technologies Co. Ltd. |
| Sercomm Corporation |
| u-blox AG |
| Qualcomm Technologies Inc. |
| MediaTek Inc. |
| SIMCom Wireless Solutions Limited |
| Samsung Electronics Co. Ltd. |
| Others |
Cost & Logistics Intelligence
3GPP Release 14 compliance requirements are displacing legacy Release 13 architectures at the premium tier while compressing margins for uncertified suppliers, simultaneously shifting procurement toward Taiwan and South Korea foundries and forcing price stratification around certification tiers rather than raw performance metrics.
Pricing Analysis
Certification level under the EU Radio Equipment Directive and China's MIIT GB standards creates the primary spread between premium and baseline tiers. Three-tier pricing structure across pre-certified integrated modules, standard discrete chipsets, and economy unverified components dominates procurement. Cost compression in the economy tier is intensifying because utilities providers in Asia are consolidating vendor relationships around full-stack solution contracts. Industrial system integrators exhibit lowest price sensitivity due to decade-long operational lifecycle requirements, while municipal smart city developers in emerging markets demonstrate highest sensitivity to per-unit chipset costs.
Supply Chain Analysis
Taiwan and South Korea anchor advanced node wafer fabrication for integrated modem-RF designs, while China concentrates backend testing and module assembly. Silicon wafer supply draws from concentrated foundry capacity, with photolithography equipment and specialty substrate materials feeding from German and Japanese precision engineering clusters. Single-source vulnerability in EUV lithography systems creates allocation risk during geopolitical friction periods. Distribution runs through module integrators offering cloud connectivity platforms rather than component-only channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NB-IoT chipset market functions as a defensive-moat arena where regulatory entrenchment through multi-territory certification pre-qualification creates switching costs that protect incumbent positions against new entrants.
For Market Incumbents: Secure multi-territory certification pre-qualification across FCC, CE, and MIIT compliance regimes before spectrum refarming announcements accelerate. Anchor premium positioning through secure element integration partnerships with financial and critical infrastructure OEMs confronting firmware vulnerability exposure. Capacity addition in India under PLI scheme incentives captures localization demand from agriculture technology companies.
For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany opens European procurement channels filtered by EU Radio Equipment Directive compliance. India's AMRUT 2.0 water management sensor networks represent the most penetrable geography given domestic manufacturing incentives and consolidating vendor relationships around full-stack providers. Position as edge computing enabled module specialists serving industrial system integrators in Japan's manufacturing clusters.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors fabless designers with 5G modem IP leverage and established certification portfolios. Long-term viability over the next decade hinges on multi-band architecture flexibility as national regulators reallocate sub-GHz spectrum. Acquisition target archetype: ultra-low-power standalone specialists with R&D intensity in narrowband modem design. Spectrum refarming announcements from Brazil and Mexico regulators signal inflection risk for single-band architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure Element Integration Partnership | Hardware-rooted trust architectures address firmware vulnerability exposure in financial infrastructure deployments. |
| Multi-Territory Certification Pre-Qualification | Simultaneous FCC, CE, and MIIT compliance accelerates product launches for smart city developers in Germany. |
| Edge Computing Module Development | Localized anomaly detection reduces cloud ingress costs for industrial system integrators in Japan. |
| India PLI Scheme Localization | Domestic manufacturing incentives attract chipset investments serving AMRUT 2.0 water sensor networks. |
| Multi-Band Architecture Redesign | Band 5, Band 8, and Band 20 support anticipates MIIT enforcement and spectrum refarming in Brazil. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with RF engineering directors at fabless semiconductor designers, procurement leads at state-owned utilities in China and India, regulatory affairs specialists navigating EU Radio Equipment Directive compliance, and industrial system integrators deploying predictive maintenance sensors. Secondary validation drew from 3GPP specification releases, MIIT GB standard filings, FCC equipment authorization databases, and customs trade data for module shipments. Bottom-up shipment modeling and top-down market sizing triangulated volume estimates.
Across the analysis window, forecasts incorporate product type segmentation across standalone chipsets and integrated modules, technology tiers spanning LPWAN through secure element embedded variants, application splits between smart metering and industrial automation, and end user categories from utilities providers to telecom equipment manufacturers. CAGRs were derived from regression analysis against utility deployment timelines and manufacturing cluster sensor integration rates. Forecast inputs include State Grid procurement announcements, spectrum auction schedules from national regulators, and foundry capacity allocation disclosures.
Underlying assumptions cover sustained smart metering deployment momentum in Asia and stable geopolitical conditions for Taiwan and South Korea foundry access, with deviation risk concentrated in spectrum refarming decisions and LPWAN protocol substitution by LoRaWAN networks. Recalibration cycles align with material shifts in 3GPP release schedules and national regulator spectrum allocation announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Global Battery Management IC Market
Chipset and Processors
8-Bit MCU Market
Chipset and Processors
Airbag Chip Market
Chipset and Processors
South Korea Edge AI Processor Market
Chipset and Processors
Wearable Processor Market
Chipset and Processors
High Performance Computing (HPC) Chipset Market
Chipset and Processors
Global Multimedia Chipsets Market
Chipset and Processors
Wi-Fi Chipset Market
Chipset and Processors
Secure Microcontrollers/Processors Market
Chipset and Processors
Brazil Data Center Processor Market
Chipset and Processors
PC Processor Market
Chipset and Processors
Germany Data Center Processor Market
Chipset and Processors
Power Architecture Market
Chipset and Processors
Japan Data Center Processor Market
Chipset and Processors
AI Chipsets Market
Chipset and Processors
Nano Chip Market