
 NB-IoT Module Market | 2026-2036
NB-IoT Module Market Size, Share, and Industry Trends Forecast 2026-2036
NB-IoT Module Market Insights
Capital-intensity divergence between in-house chip design capacity and outsourced assembly is rotating competitive advantage toward vertically integrated module vendors. Quectel leverages captive test facilities across multiple continents to sustain margin control on high-volume cellular module contracts. Fibocom Wireless anchors its position through dedicated R&D centers focused on ultra-low-power firmware stacks. Telit Cinterion differentiates via software-defined radio architectures that reduce certification cycles for regional variants.
NB-IoT modules are narrowband radio transceivers operating in licensed spectrum below 200 kHz bandwidth, engineered for decade-long battery life and deep indoor penetration in machine-to-machine networks. Cellular modules carry the dominant revenue share within product type segmentation due to their direct integration into original equipment manufacturer designs across utility and logistics hardware. Smart agriculture represents the fastest-expanding end user category as soil moisture and livestock monitoring networks migrate from unlicensed alternatives to carrier-managed NB-IoT subscriptions with guaranteed quality of service.
3GPP Release 13 and subsequent specifications govern NB-IoT air interfaces, while national regulators including the FCC in the United States, MIIT in China, and ETSI across European member states enforce spectrum allocation and electromagnetic compliance thresholds that determine module certification timelines. The EU AI Act and emerging cybersecurity frameworks for connected infrastructure are extending compliance burdens beyond radio performance into firmware update mechanisms and data governance. Stakeholders must monitor whether carrier aggregation requirements in future 3GPP releases force hardware redesigns that obsolete current module form factors before depreciation cycles complete.
Market Dynamics
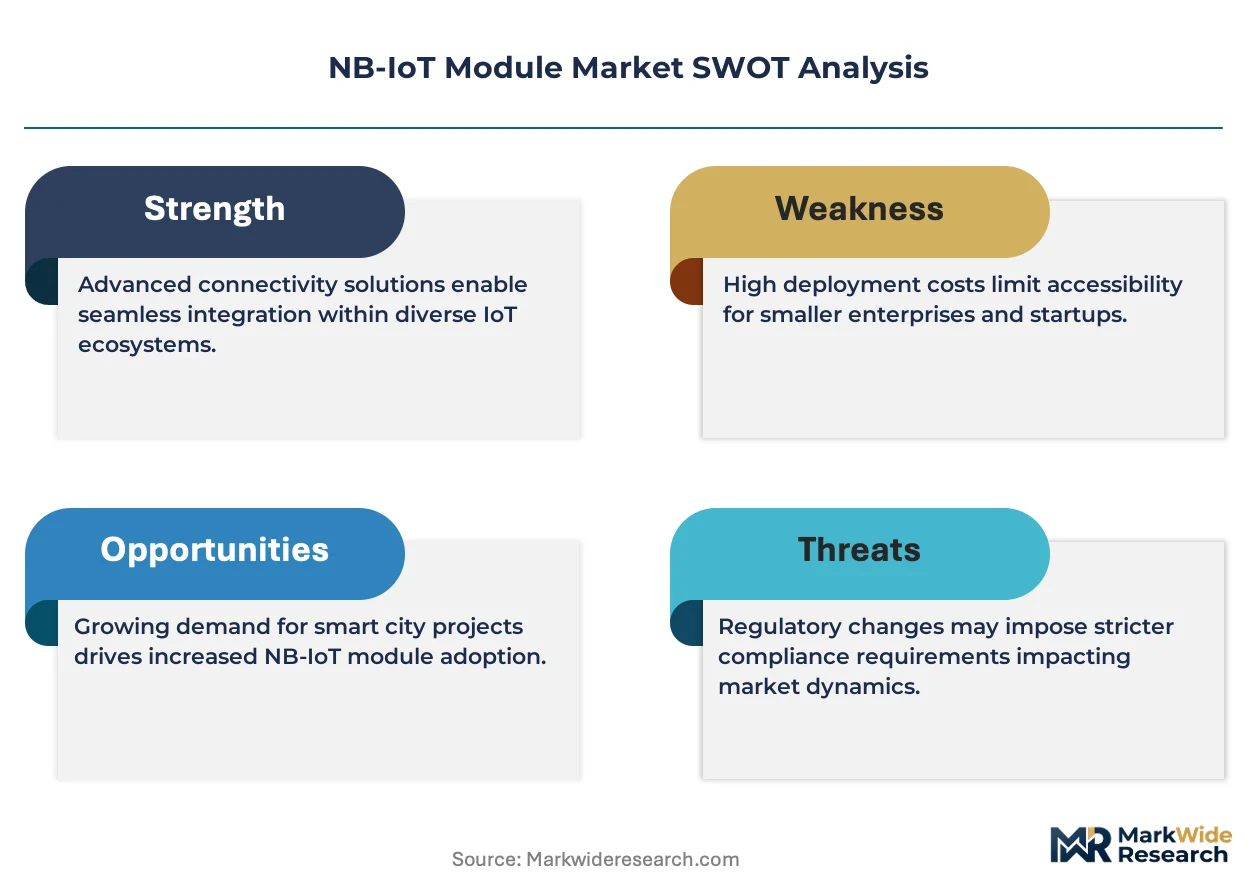
Carrier-managed NB-IoT subscriptions are displacing unlicensed LPWAN alternatives as utilities and agriculture operators prioritize guaranteed quality of service over deployment cost minimization.
Growth Catalysts
- EU Green Deal digital energy mandates:Germany's smart metering rollout accelerates module procurement as utilities face binding 2030 electrification targets.
- 3GPP Release 14 eDRX enhancements:Extended discontinuous reception protocols extend battery life beyond ten years, enabling remote sensor networks previously uneconomical.
- China's eastern manufacturing corridor:Module production co-locates with domestic semiconductor foundries, compressing lead times for Asia-Pacific OEM supply chains.
Market Restraints
- Licensed spectrum access costs:Recurring carrier subscription fees accumulate over decade-long deployments, eroding total-cost-of-ownership advantages against Sigfox and LoRa.
- Certification timeline fragmentation:FCC, MIIT, and ETSI testing requirements diverge on electromagnetic compliance thresholds, forcing region-specific hardware variants.
- LTE-M substitution pressure:Mid-tier mobility use cases migrate toward higher-bandwidth cellular IoT standards that share infrastructure investments.
Strategic Opportunities
- Indian agricultural sensor networks:TRAI's 2022 spectrum harmonization for NB-IoT in 800 MHz and 900 MHz bands opens subcontinent-scale deployment potential for soil monitoring.
- EU AI Act firmware governance:Compliance mandates for over-the-air update mechanisms create service revenue streams for module vendors with secure boot architectures.
- NB-IoT and satellite backhaul convergence:Hybrid modules integrating terrestrial cellular with LEO satellite links address coverage gaps in maritime and remote mining applications.
Industry Challenges
- RF firmware engineering scarcity:Deep expertise in narrowband physical layer optimization concentrates among legacy 2G baseband teams nearing retirement.
- Carrier aggregation hardware redesign risk:Future 3GPP releases may mandate multi-band support that obsoletes current single-channel module form factors mid-depreciation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NB-IoT Module Market |
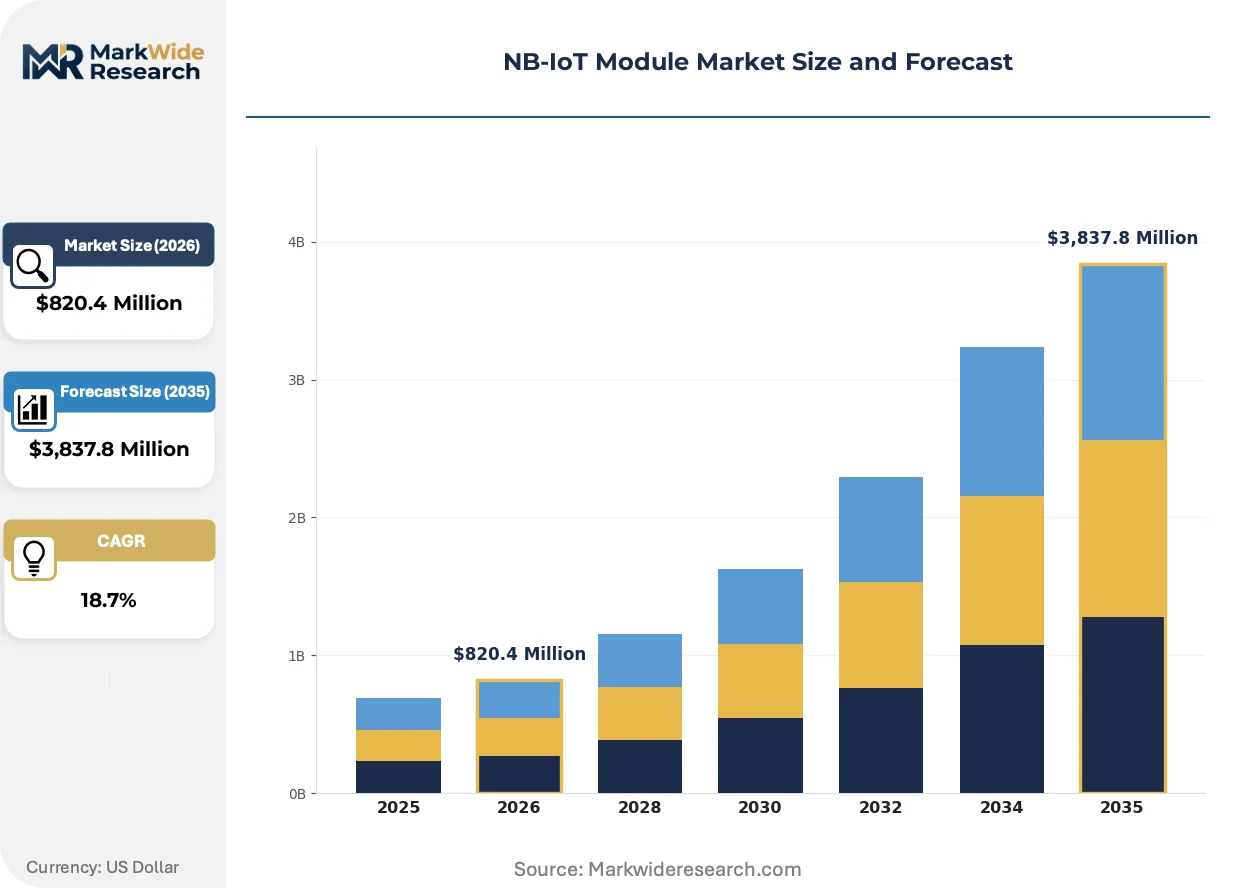
| Market Size in 2026 | $820.4 Million |
| Market Size in 2035 | $3,837.8 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellular Modules, Sensors, Gateways, Routers Technology: Low Power Wide Area, LTE-M, Sigfox, LoRaWAN End User: Smart Metering, Asset Tracking, Smart Agriculture, Industrial IoT Deployment: Private Networks, Public Networks, Hybrid Networks, Cloud-Based |
| Companies Covered | Quectel, Fibocom Wireless, Telit Cinterion, u-blox Holding, Thales Group, China Mobile IoT, SunSea, Lierda, MeiG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NB-IoT Module Market Trends and Innovations
NB-IoT module architectures are converging toward software-defined radio platforms that compress certification cycles while enabling post-deployment feature activation through firmware updates.
Integrated power management units with sub-microamp sleep states are displacing discrete component designs in utility metering applications. European smart grid operators specify these consolidated chipsets for decade-long maintenance-free operation. The consolidation is displacing second-tier module vendors lacking analog mixed-signal design partnerships.
ETSI's evolving EN 303 645 cybersecurity standard for consumer IoT is extending into industrial cellular modules through national implementations in France and Germany. Hardware security element integration now precedes radio certification in EU-bound product development. Agricultural OEMs in the Netherlands and Denmark accelerate procurement timelines to lock pre-compliant inventory ahead of enforcement deadlines.
Subscription-based module provisioning is replacing upfront hardware purchases among mid-sized European water utilities. Managed connectivity contracts bundle device management, firmware maintenance, and carrier negotiation into per-meter monthly fees. This model concentrates procurement authority with system integrators in Germany and Scandinavia, marginalizing direct module distributor relationships.
NB-IoT Module Market Segmentation
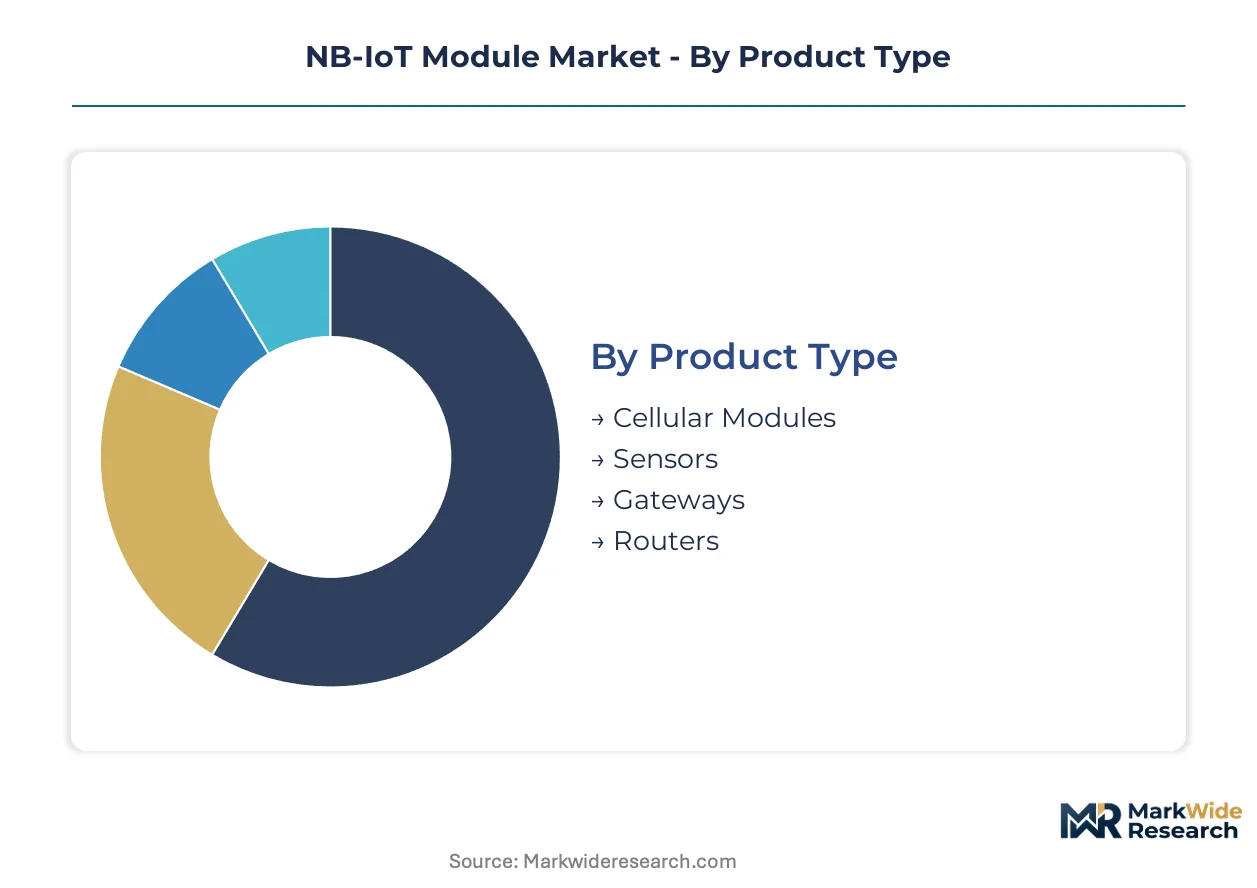
NB-IoT module procurement patterns diverge sharply between utility-scale deployments with decade-long amortization horizons and agricultural networks requiring rapid field scalability. Segmentation reveals how carrier-managed subscription models are concentrating demand within specific product configurations while displacing unlicensed alternatives.
Product Type:
Cellular modules dominate export-led procurement from China's eastern manufacturing corridor, while sensors and gateways concentrate in domestic European smart grid deployments under EU Green Deal mandates.
- Cellular Modules:Narrowband radio transceivers operating in licensed spectrum below 200 kHz bandwidth, engineered for deep indoor penetration and decade-long battery cycles. Demand concentrates in Germany's smart metering rollout, where utilities face binding electrification targets and specify direct OEM integration into meter hardware.
- Sensors:Ultra-low-power environmental and positional measurement endpoints with integrated NB-IoT modems. Soil moisture and livestock monitoring networks in the Netherlands and Denmark drive fastest expansion as agricultural operators migrate from LoRa to carrier-managed subscriptions with guaranteed quality of service.
- Gateways:Edge aggregation devices bridging NB-IoT sensor clusters to backhaul infrastructure.
- Routers:Multi-protocol cellular routing equipment for industrial site deployments.
Cellular modules command the established base. The steepest expansion runs through sensors.
Technology:
Cost-tier stratification separates premium licensed-cellular deployments from economy unlicensed alternatives, with mid-tier hybrid configurations gaining traction in asset tracking.
- Low Power Wide Area:Licensed NB-IoT implementations governed by 3GPP Release 13 and subsequent specifications. Germany's Federal Network Agency enforces electromagnetic compliance thresholds that extend certification timelines, favoring vendors with established regulatory relationships.
- LTE-M:Higher-bandwidth cellular IoT standard sharing infrastructure investments with NB-IoT. Mid-tier mobility use cases in logistics and fleet management drive substitution pressure as carriers optimize spectrum allocation between narrowband and enhanced machine-type communication.
- Sigfox:Proprietary ultra-narrowband unlicensed technology with subscription economics eroded by carrier-managed NB-IoT.
- LoRaWAN:Open-standard unlicensed LPWAN facing displacement in quality-of-service-sensitive applications.
Low Power Wide Area anchors current procurement volumes. LTE-M is climbing the fastest as mobility requirements harden.
End User:
Application maturity separates decade-long utility amortization from rapidly scaling agricultural sensor networks with shorter replacement cycles.
- Smart Metering:Electric, gas, and water meter integration requiring maintenance-free operation across 10-15 year deployment horizons. German utilities under EU Green Deal digital energy mandates accelerate module procurement to meet binding 2030 targets, specifying consolidated power management chipsets for remote installation sites.
- Smart Agriculture:Soil moisture, livestock health, and equipment monitoring networks. TRAI's spectrum harmonization for NB-IoT in India's 800 MHz and 900 MHz bands opens subcontinent-scale deployment potential, with Dutch and Danish OEMs locking pre-compliant inventory ahead of ETSI cybersecurity enforcement deadlines.
- Asset Tracking:Container, vehicle, and equipment location monitoring with intermittent mobility requirements.
- Industrial IoT:Manufacturing equipment monitoring and predictive maintenance applications.
Smart metering commands the established base. Smart agriculture is gaining share fastest as subscription economics improve.
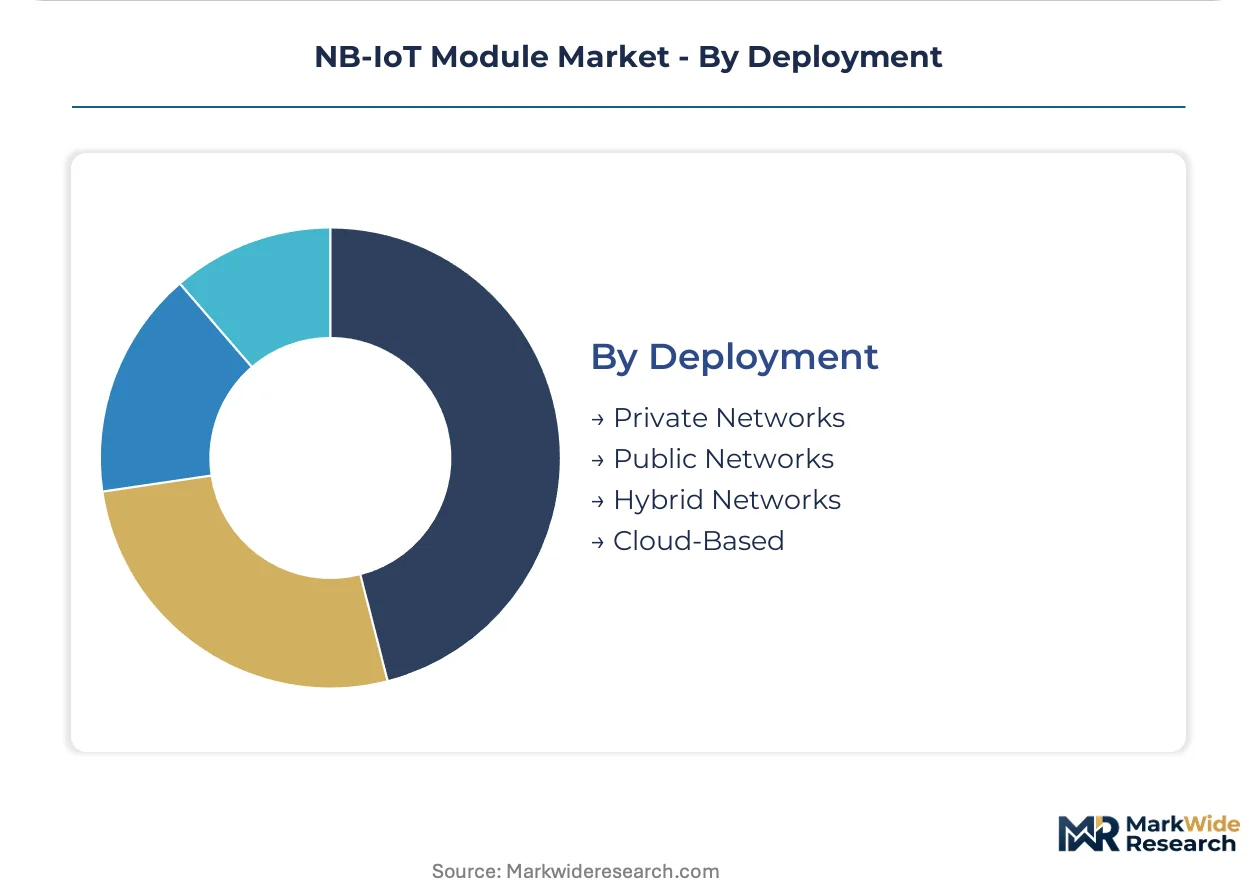
Deployment:
Customer-type stratification separates carrier-dependent public network subscribers from infrastructure-owning private network operators with distinct total-cost-of-ownership calculations.
- Public Networks:Carrier-managed NB-IoT subscriptions bundling device management, firmware maintenance, and spectrum access into per-device monthly fees. Mid-sized European water utilities concentrate procurement authority with German and Scandinavian system integrators, marginalizing direct module distributor relationships.
- Private Networks:Enterprise-owned base station infrastructure for sites with coverage or security requirements exceeding public carrier offerings. Mining and maritime operators in remote geographies deploy hybrid configurations integrating terrestrial cellular with LEO satellite backhaul.
- Hybrid Networks:Dual-mode deployments switching between public carrier and private infrastructure based on availability.
- Cloud-Based:Fully managed connectivity platforms abstracting radio layer complexity from end-user operations.
Public networks command the established base. Hybrid networks show the steepest expansion trajectory as coverage requirements diversify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between Germany's utility-centric procurement and China's manufacturing-integrated supply chains, with India and the Netherlands carving distinct agricultural sensor niches.
Germany
Federal Network Agency mandates under the EU Green Deal drive smart metering module procurement for binding 2030 electrification targets. ETSI electromagnetic compliance thresholds extend certification timelines, favoring established regulatory relationships. North Rhine-Westphalia utilities specify consolidated power management chipsets for remote installation sites.
China
Domestic semiconductor foundries in the eastern manufacturing corridor compress lead times for Asia-Pacific OEM supply chains. MIIT spectrum allocation governs module certification timelines alongside electromagnetic compliance thresholds. Shanghai and Shenzhen anchor production gravity for export-led cellular module procurement.
Netherlands
Agricultural OEMs accelerate procurement timelines to lock pre-compliant inventory ahead of ETSI cybersecurity enforcement deadlines. EN 303 645 hardware security element integration now precedes radio certification in EU-bound product development. Dutch soil moisture monitoring networks migrate from LoRa to carrier-managed subscriptions.
India
TRAI's 2022 spectrum harmonization for NB-IoT in 800 MHz and 900 MHz bands opens subcontinent-scale deployment potential for agricultural sensor networks. Central Electricity Authority smart grid directives complement agricultural digitization programs. Maharashtra and Gujarat field trials validate soil monitoring economics at scale.
United States
FCC electromagnetic compliance thresholds diverge from ETSI and MIIT requirements, forcing region-specific hardware variants. Utility metering deployments concentrate in Texas and California deregulated markets with independent system operator structures. Smart city pilots in Chicago and Los Angeles test hybrid public-private network configurations.
NB-IoT Module Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive test facilities and dedicated R&D centers separating margin-sustainable scale players from distribution-dependent assemblers. The vendor base clusters around three strategic archetypes: vertically integrated module fabricators with in-house semiconductor partnerships, firmware-focused specialists with ultra-low-power optimization capabilities, and software-defined radio architects compressing certification cycles. Dominant competitive moves include geographic expansion through captive test facilities across multiple continents and portfolio diversification into hybrid satellite-terrestrial configurations.
Within the integrated tier, Quectel leverages captive test facilities across multiple continents to sustain margin control on high-volume cellular module contracts. Fibocom Wireless anchors its position through dedicated R&D centers focused on ultra-low-power firmware stacks. Telit Cinterion occupies a distinct software-defined radio position that reduces certification cycles for regional variants.
| Leading Market Players |
|---|
| Quectel |
| Fibocom Wireless |
| Telit Cinterion |
| u-blox Holding |
| Thales Group |
| China Mobile IoT |
| SunSea |
| Lierda |
| MeiG |
| Others |
Pricing and Supply Chain Analysis
Long-term managed connectivity contracts lock in both module supply access and subscription price visibility for European water utilities bundling firmware maintenance into per-meter monthly fees. Germany's Federal Network Agency mandates compress procurement timelines, forcing buyers to pre-commit volumes before ETSI cybersecurity enforcement deadlines harden supplier negotiating leverage.
Pricing Analysis
Post-deployment firmware update revenue drives lifetime value for vendors with secure boot architectures compliant with EU AI Act mandates. Three-tier pricing structure across premium certified, standard industrial, and economy volume tiers separates module vendors by electromagnetic compliance grade and carrier pre-certification status. Cost compression in economy tiers intensifies because China's eastern manufacturing corridor feeds oversupply into export markets. Mid-sized European utilities show highest price sensitivity due to subscription fee accumulation over decade-long deployments, while German smart metering operators under binding electrification targets demonstrate lowest sensitivity.
Supply Chain Analysis
Strategic stockpiling of pre-certified inventory dominates procurement behavior ahead of ETSI EN 303 645 enforcement deadlines in France and Germany. Module production concentrates in China, with Taiwan and South Korea feeding semiconductor wafer supply. Supply chains draw from domestic foundries in Shanghai and Shenzhen, NOR flash memory from Taiwanese suppliers, and RF front-end components from South Korean vendors. Single-source vulnerability concentrates in 3GPP Release 14 baseband firmware engineering expertise held by legacy cellular teams. Distribution runs through German and Scandinavian system integrators consolidating procurement authority for public network deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward system integrators in Germany and Scandinavia as subscription-based provisioning concentrates procurement authority and marginalizes direct distributor relationships.
For Market Incumbents: Shield margin sustainability by deepening captive test facility networks across multiple continents to compress certification cycles for regional variants. Lock in analog mixed-signal design partnerships for consolidated power management chipsets before second-tier vendors secure capacity. LTE-M substitution pressure in mid-tier mobility use cases threatens volume erosion in logistics applications.
For New Entrants and Emerging Players: ETSI fast-track certification for EN 303 645 hardware security element integration opens white-space in Dutch and Danish agricultural OEM procurement. Target India's subcontinent-scale agricultural sensor networks under TRAI spectrum harmonization with localized firmware stacks optimized for 800 MHz and 900 MHz bands. Partner with German system integrators on managed connectivity contracts rather than competing for direct module sales.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated module fabricators with in-house semiconductor partnerships and established regulatory relationships across FCC, MIIT, and ETSI jurisdictions. Long-term viability hinges on software-defined radio architectures enabling post-deployment feature activation without hardware redesign. Watch for carrier aggregation mandates in future 3GPP releases that could obsolete single-channel module form factors mid-depreciation.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Satellite-Terrestrial Module Development | Addresses coverage gaps in maritime and remote mining applications beyond terrestrial carrier reach. |
| Software-Defined Radio Platform Migration | Compresses FCC, MIIT, and ETSI certification cycles while enabling firmware-based feature activation. |
| Secure Boot Architecture Investment | Captures EU AI Act compliance service revenue streams for over-the-air firmware governance. |
| Captive Test Facility Geographic Expansion | Sustains margin control on high-volume cellular module contracts through reduced third-party dependency. |
| Ultra-Low-Power Firmware Stack R&D | Extends battery life beyond ten years for soil moisture and livestock monitoring networks in agriculture. |
Research Methodology
A standing panel of module vendor product managers, carrier network planning engineers, smart metering procurement leads at German utilities, and agricultural OEM technical directors provided ongoing calibration across primary fieldwork. Secondary validation drew from 3GPP specification releases, FCC equipment authorization databases, ETSI harmonized standards, MIIT radio transmission equipment type approval records, and customs trade data for cellular module exports. Bottom-up unit economics for sensor deployments were triangulated against top-down carrier subscription revenue projections.
Consistency checks validated volume and value outputs against carrier-managed IoT connection forecasts and semiconductor foundry capacity disclosures across the analysis window. The analytical framework modeled segmentation across product type, technology standard, end-user application, and deployment model, with regional regulatory cluster as an additional dimension. CAGRs were derived from installed base amortization curves and replacement cycle dynamics. Forecast inputs included utility electrification target compliance deadlines and agricultural digitization program rollout schedules.
The analysis sits within stated boundaries; outcomes outside sustained carrier investment in licensed spectrum infrastructure or accelerated ETSI cybersecurity enforcement would require recalibration. Forecasts reflect assumptions on 3GPP release timing and carrier aggregation roadmap decisions. Revision becomes warranted when LTE-M substitution rates in mobility use cases cross thresholds that erode NB-IoT spectrum allocation priority.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Swarm Intelligence Market
Emerging and Next Generation Technologies
Edge Computing Market
Emerging and Next Generation Technologies
Laser Technology Market
Emerging and Next Generation Technologies
Hyperscale Computing Market
Emerging and Next Generation Technologies
Global Flexible and Printed Electronics Market
Emerging and Next Generation Technologies
North America Wigig Market
Emerging and Next Generation Technologies
1550nm LiDAR Pulsed Fiber Laser Market
Emerging and Next Generation Technologies
Metal Additive Manufacturing Systems Market
Emerging and Next Generation Technologies
Global Terahertz Components and Systems Market
Emerging and Next Generation Technologies
Transparent Solar Cells Market
Emerging and Next Generation Technologies
Ultra-Fine Ath Market
Emerging and Next Generation Technologies
Global Next Generation Computing Market
Emerging and Next Generation Technologies
North America Quantum Computing Market
Emerging and Next Generation Technologies
Internet of Nano Things Market
Emerging and Next Generation Technologies
Global High-Performance Computing (HPC) Market
Emerging and Next Generation Technologies
Global Metamaterials Technologies Market