
 South Korea Edge AI Processor Market | 2026-2036
South Korea Edge AI Processor Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Edge AI Processor Market Insights
Buyer concentration among Seoul metropolitan transit authorities is realigning how edge AI processor vendors structure municipal contracts. Samsung Electronics leverages its captive foundry capacity to anchor large-scale smart infrastructure deployments. Rebellions competes through specialized neural processing units optimized for low-latency inference workloads.
A South Korea edge AI processor is a semiconductor device fabricated on advanced nodes, typically integrating CPU cores with dedicated tensor or matrix multiplication engines to execute inference tasks locally without cloud dependency. System on Chip designs dominate the product landscape, as Korean OEMs prioritize single-die integration that reduces board area and power budgets for robotics and smart appliance applications. Deep Learning technology leads the technology split, while Computer Vision commands the fastest expansion within the application dimension due to manufacturing quality-inspection retrofit cycles and retail loss-prevention upgrades.
MFDS, the Korea Communications Commission, and the Ministry of Trade, Industry and Energy collectively shape certification timelines, data sovereignty requirements, and domestic content thresholds for edge AI procurement. The Personal Information Protection Act, as enforced by the Personal Information Protection Commission, mandates on-device processing for biometric data captured by smart cameras, directly expanding addressable demand for localized inference silicon. Stakeholders must monitor how K-Netz sovereignty criteria evolve for public-sector edge deployments, as compliance prequalification will determine vendor eligibility before technical specifications enter bid evaluation.
Market Dynamics
Municipal procurement centralization around Seoul Metropolitan Government's smart transit infrastructure is compressing vendor qualification timelines and forcing fabless designers to pre-certify silicon against K-Netz sovereignty criteria before technical bid submission.
Growth Catalysts
- Personal Information Protection Act mandates:On-device biometric processing requirements for smart camera networks eliminate cloud-reliant alternatives, expanding localized inference silicon procurement.
- Computer Vision retrofit cycles:Manufacturing quality-inspection system upgrades across Gyeonggi Province's electronics assembly plants accelerate NPU deployment for defect detection pipelines.
- Gyeonggi Province cluster density:Foundry-adjacent fabless designers co-located with system integrators reduce time-to-tapeout for robotics and smart appliance OEMs.
Market Restraints
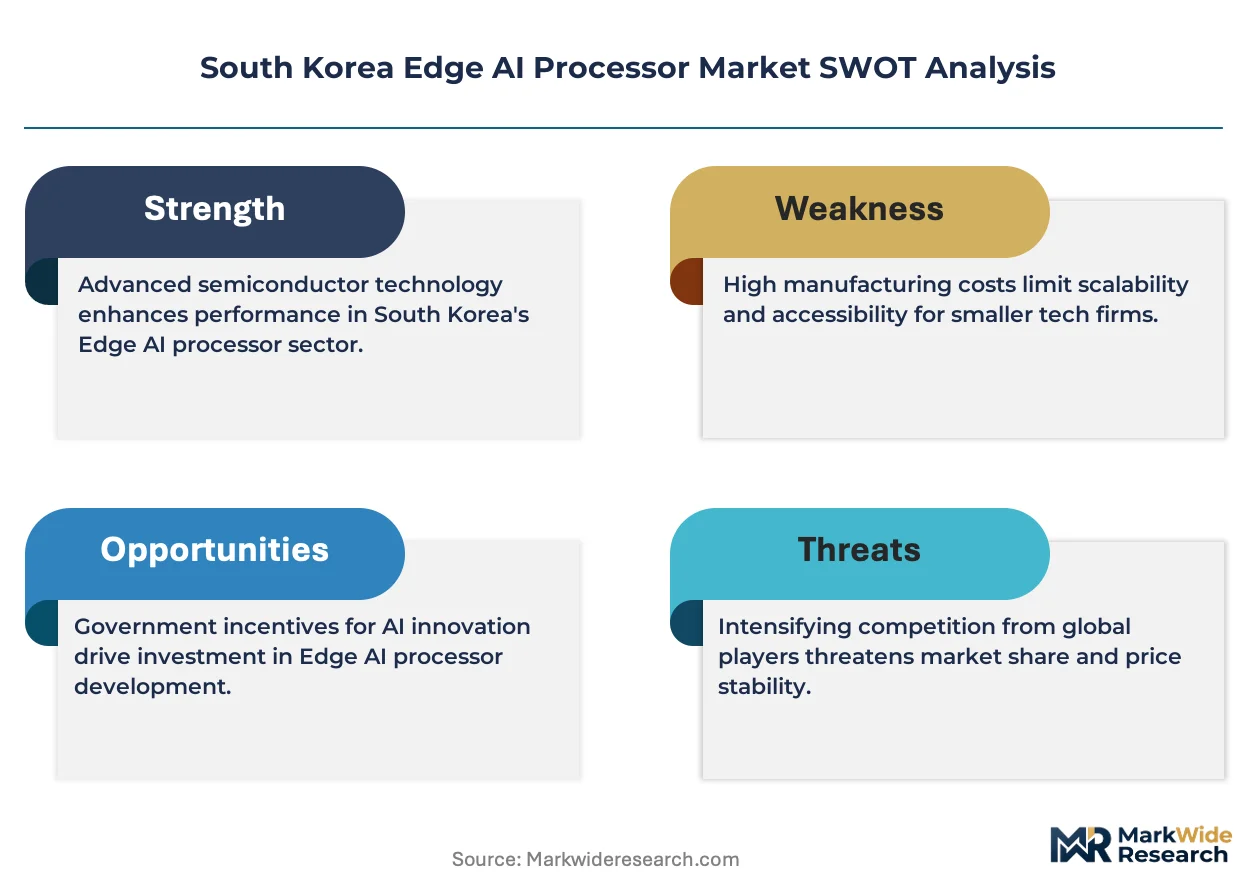
- Advanced node capacity concentration:Domestic foundry availability for sub-7nm edge AI designs remains captive to Samsung Electronics' internal allocation priorities.
- MFDS data-localization compliance costs:Healthcare edge device certification timelines extend 8-14 months for foreign silicon vendors lacking domestic testing infrastructure.
- Legacy ARM ISA licensing:Royalty stacking for CPU+NPU heterogeneous designs erodes margin structures for mid-volume fabless entrants.
Strategic Opportunities
- Busan-Ulsan manufacturing corridor:Shipbuilding and heavy machinery automation retrofits remain underpenetrated for vision-guided robotic welding systems.
- Chiplets heterogeneous integration:2.5D packaging convergence with embedded DRAM enables new performance-per-watt tiers for battery-constrained drones.
- Korea Communications Commission edge spectrum allocation:28GHz local 5G licenses for private industrial networks mandate on-premise inference hardware procurement.
Industry Challenges
- Post-silicon verification talent scarcity:Functional safety certification for automotive edge AI requires ISO 26262 expertise concentrated among Seoul National University and KAIST alumni networks.
- Legacy PLC integration friction:Smart factory retrofits demand protocol translation layers between new vision systems and existing Mitsubishi Electric or Siemens control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Edge AI Processor Market |
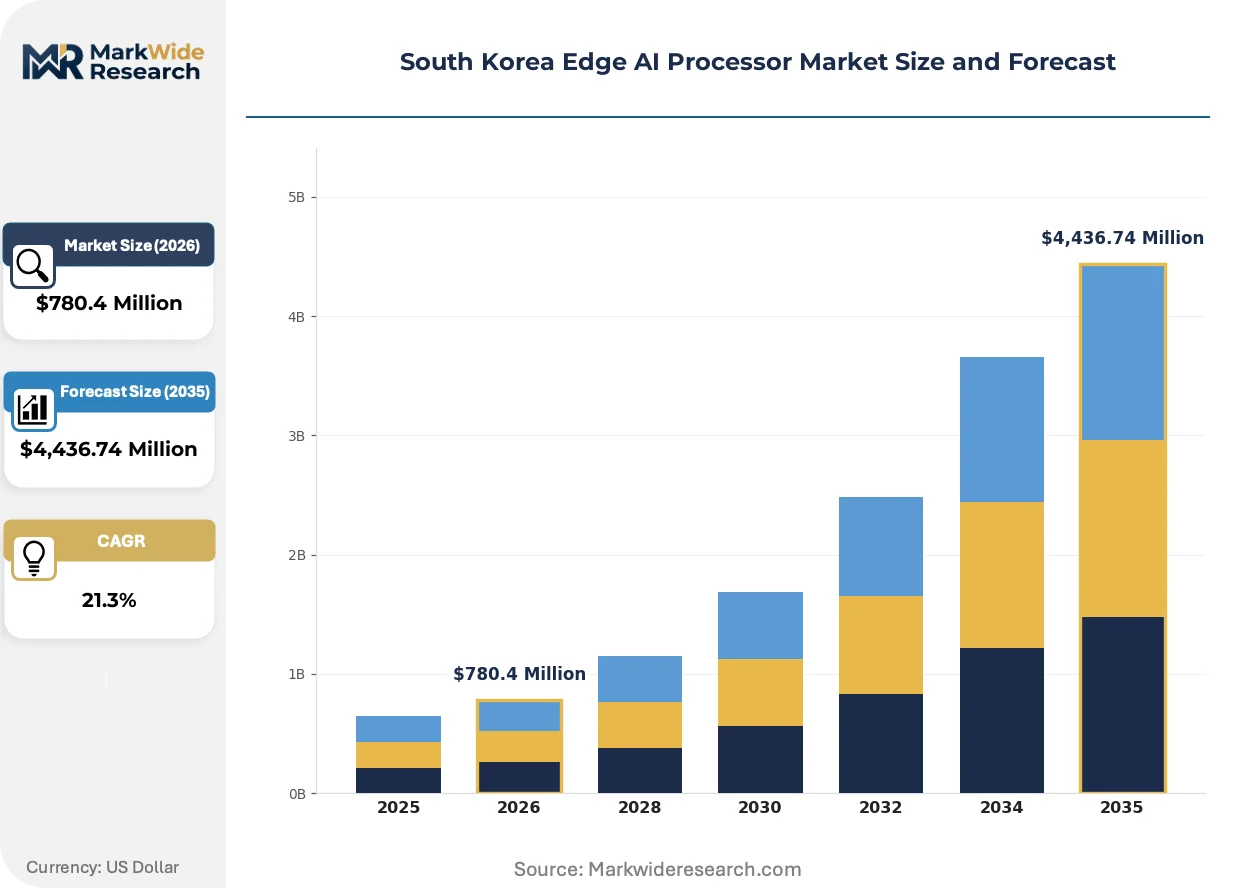
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $4,436.74 Million |
| CAGR (2026 – 2036) | 21.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Circuits, System on Chip, Hardware Accelerators, AI Modules Application: Smart Cameras, Robotics, Industrial Automation, Smart Appliances End User: Manufacturing, Retail, Transportation, Healthcare Technology: Machine Learning, Deep Learning, Natural Language Processing, Computer Vision |
| Companies Covered | Samsung Electronics, SK Hynix, LG Electronics, Rebellions, OPENEDGES Technology, SoyNet, Point2 Technology, Sapeon Korea, SiliconArts, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Edge AI Processor Market Trends and Innovations
Neural architecture search automation and analog in-memory computing prototypes are compressing the traditional digital-NPU performance roadmap, forcing incumbent vendors to defend position through software stack differentiation rather than raw TOPS benchmarks alone.
Compute-in-memory arrays based on ReRAM and MRAM bitcells is rewriting the power-latency tradeoff for always-on voice and gesture recognition endpoints. Smart appliance OEMs in Suwon and Gwangju are sampling these devices for 2026 product cycles. The technology is compressing standby power budgets below 100 microwatts, enabling battery-less energy harvesting designs.
MFDS cybersecurity pre-certification requirements for Class III medical edge devices took effect in early 2024, mandating hardware root-of-trust and encrypted model storage. Diagnostic imaging equipment vendors in Seongnam are redesigning system architectures to isolate inference engines from host processors. The regulation is accelerating domestic secure-enclave IP licensing from Korea Information Certificate Authority affiliates.
Seoul metropolitan transit authorities consolidated camera procurement under the Intelligent Transport System 2.0 framework, displacing fragmented district-level purchasing. System integrators now bid turnkey perception stacks rather than discrete hardware. The concentration is visible in Songpa-gu and Gangnam-gu pilot deployments where single-vendor accountability clauses dominate contract structures.
South Korea Edge AI Processor Market Segmentation
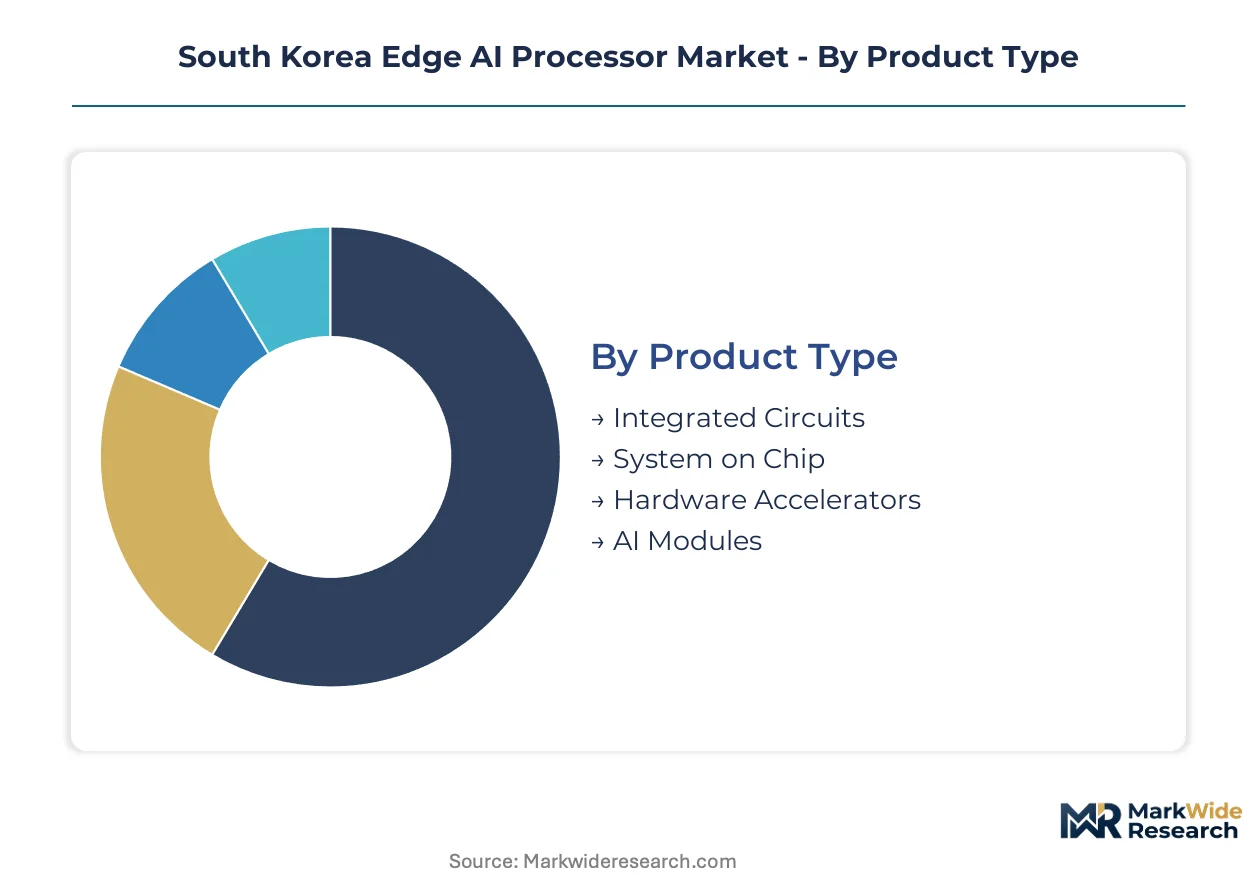
Edge AI processor procurement in South Korea splits across hardware form factors, inference workloads, and compliance regimes that shape vendor qualification timelines. Municipal buyers and industrial OEMs prioritize different integration levels depending on deployment scale and data sovereignty obligations.
Product Type:
Standardization decreases from discrete hardware accelerators toward fully integrated system-on-chip designs, with customization depth inversely tracking volume scalability across Korean OEM procurement patterns.
- System on Chip:Single-die integration of CPU cores with dedicated tensor engines dominates robotics and smart appliance designs from Suwon and Gwangju manufacturers. Samsung Electronics leverages captive foundry capacity to anchor large-scale municipal deployments where board area constraints eliminate multi-chip alternatives.
- Integrated Circuits:Discrete logic devices fabricated on advanced nodes serve high-volume manufacturing quality-inspection retrofits across Gyeonggi Province electronics assembly plants. Rebellions competes through specialized neural processing units optimized for low-latency inference workloads in this tier.
- Hardware Accelerators:PCIe-based inference cards target data center edge nodes requiring thermal headroom beyond mobile power envelopes.
- AI Modules:Pre-certified system-in-package designs accelerate procurement timelines for mid-tier OEMs lacking in-house RF and power management expertise.
Most installed capacity flows through System on Chip. Expansion is steepest in Hardware Accelerators as private 5G industrial networks mandate on-premise inference clusters.
Application:
Deployment maturity varies from established computer vision pipelines to emerging multimodal robotics stacks, with retrofit economics driving adoption sequencing across Korean industrial corridors.
- Computer Vision:Defect detection and retail loss-prevention systems command the steepest expansion trajectory within the application dimension. Manufacturing quality-inspection upgrades across Gyeonggi Province electronics assembly plants accelerate NPU deployment for vision-guided pipelines.
- Smart Cameras:Seoul Metropolitan Government's Intelligent Transport System 2.0 framework consolidated district-level procurement under single-vendor accountability clauses. Personal Information Protection Act mandates for on-device biometric processing eliminate cloud-reliant alternatives, expanding localized inference silicon procurement.
- Robotics:Vision-guided welding systems remain underpenetrated in the Busan-Ulsan manufacturing corridor despite heavy machinery automation retrofit demand.
- Smart Appliances:Compute-in-memory prototypes from Suwon OEMs compress standby power below 100 microwatts for battery-less energy harvesting designs.
- Industrial Automation:Legacy PLC integration friction with Mitsubishi Electric and Siemens control architectures constrains retrofit velocity in smart factory deployments.
Computer Vision captures the dominant revenue share. Robotics is gaining share fastest as shipbuilding automation retrofits accelerate in coastal industrial zones.
End User:
Procurement centralization intensity separates municipal transit authorities from fragmented manufacturing SME demand, with compliance burden scaling alongside data sensitivity classification.
- Transportation:Seoul metropolitan transit authorities anchor demand concentration through consolidated camera procurement under unified technical specifications. System integrators now bid turnkey perception stacks rather than discrete hardware.
- Healthcare:MFDS data-localization requirements for Class III medical edge devices extend certification timelines 8-14 months for foreign silicon vendors lacking domestic testing infrastructure.
- Manufacturing:Electronics assembly plants in Gyeonggi Province drive volume demand for quality-inspection inference hardware.
- Retail:Loss-prevention upgrades in Seoul metropolitan area deploy smart camera networks subject to Personal Information Protection Commission biometric processing mandates.
Manufacturing holds the largest installed base. Healthcare is climbing the fastest as diagnostic imaging equipment vendors in Seongnam redesign architectures to isolate inference engines under MFDS cybersecurity pre-certification requirements.
Technology:
Computational complexity separates training-capable silicon from pure inference engines, with Korean foundry allocation priorities favoring heterogeneous designs that maximize die yield per wafer.
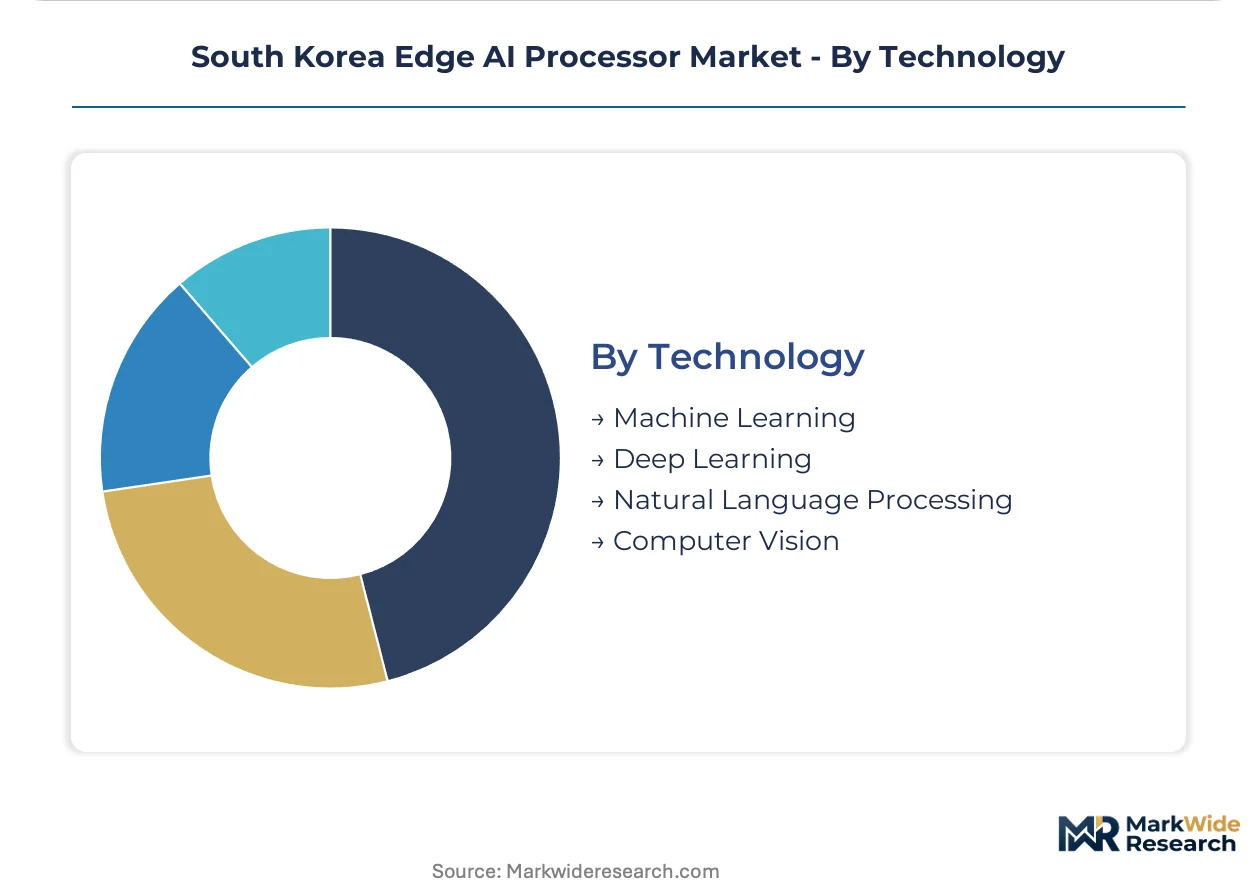
- Deep Learning:Tensor and matrix multiplication engines dominate the technology split across Korean edge AI deployments. Neural architecture search automation compresses traditional digital-NPU performance roadmaps, forcing incumbent vendors to defend position through software stack differentiation.
- Machine Learning:Classical algorithm acceleration serves legacy industrial control systems with deterministic latency requirements.
- Computer Vision:Convolution-optimized datapaths target manufacturing defect detection with sub-millisecond inference deadlines.
- Natural Language Processing:Transformer-based edge inference remains nascent in Korean deployments, constrained by model size and DRAM bandwidth limitations.
Deep Learning accounts for the dominant technology share. Computer Vision represents the fastest-growing trajectory as manufacturing quality-inspection retrofit cycles accelerate NPU deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's edge AI processor deployment density exceeds Japan's by a factor of three in smart transit applications, while both markets trail Taiwan's semiconductor-adjacent integration depth. This disparity reflects varying industrial cluster maturities and sovereign data regulations across Northeast Asian economies.
Seoul Capital Area
Seoul Metropolitan Government's Intelligent Transport System 2.0 framework consolidates district-level camera procurement under unified technical specifications. The Personal Information Protection Commission enforces on-device biometric processing mandates for smart camera networks. System integrators in Songpa-gu and Gangnam-gu bid turnkey perception stacks with single-vendor accountability clauses dominating contract structures.
Gyeonggi Province
Electronics assembly plants drive volume demand for manufacturing quality-inspection inference hardware with sub-millisecond defect detection deadlines. The Ministry of Trade, Industry and Energy coordinates domestic content thresholds for public-sector edge procurement. Foundry-adjacent fabless designers in Suwon co-locate with system integrators, reducing time-to-tapeout for robotics OEMs.
Busan-Ulsan
Shipbuilding and heavy machinery automation retrofits remain underpenetrated for vision-guided robotic welding systems despite latent demand. The Korea Communications Commission's 28GHz local 5G licenses for private industrial networks mandate on-premise inference hardware procurement. Heavy machinery clusters in Ulsan Mipo Industrial Park pilot private network edge nodes for predictive maintenance.
Daejeon-Sejong
Research institutions anchor pre-commercial compute-in-memory prototyping for always-on voice and gesture recognition endpoints. Korea Information Certificate Authority affiliates license secure-enclave IP for MFDS cybersecurity pre-certification requirements. KAIST spinouts in Daedeok Innopolis test ReRAM bitcell arrays compressing standby power below 100 microwatts.
South Korea Edge AI Processor Market Competitive Landscape
Seoul-based producers anchor the integrated-system tier; Gwangju and Seongnam specialists hold positions in discrete neural processing units. The vendor structure concentrates around captive foundry capacity and fabless design houses, with municipal procurement centralization compressing qualification timelines for new entrants. Three archetypes dominate: diversified electronics conglomerates with captive silicon, venture-backed NPU specialists, and system integrators bundling hardware with perception software. Competitive moves center on pre-certification against K-Netz sovereignty criteria and heterogeneous packaging partnerships for chiplets integration.
Within the diversified conglomerate tier, Samsung Electronics and LG Electronics exemplify integrated-system providers leveraging captive supply chains. Among venture-backed specialists, Rebellions occupies a position representing the fabless NPU archetype optimized for low-latency inference workloads. These three companies collectively illustrate the competitive spectrum from full-stack integration to focused neural acceleration.
| Leading Market Players |
|---|
| Samsung Electronics |
| SK Hynix |
| LG Electronics |
| Rebellions |
| OPENEDGES Technology |
| SoyNet |
| Point2 Technology |
| Sapeon Korea |
| SiliconArts |
| Others |
Pricing and Supply Chain Analysis
Compute-in-memory prototyping based on ReRAM and MRAM bitcells is compressing standby power budgets below 100 microwatts, simultaneously lowering silicon area requirements for always-on endpoints and shifting procurement economics toward single-die integration. This technology transition concentrates cost advantages among foundry-adjacent designers with captive advanced-node access, tightening margin structures for fabless entrants lacking heterogeneous packaging partnerships.
Pricing Analysis
Capacity additions in Samsung Electronics' Pyeongtaek foundry complex are reshaping price floors for sub-7nm edge AI silicon, compressing premiums on legacy 10nm designs. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels dominates procurement contracts, with MFDS cybersecurity pre-certification extending premium tiers by 8-14 months. Pricing pressure stems from ARM ISA royalty stacking on CPU+NPU heterogeneous designs. Municipal transit authorities show lowest price sensitivity due to consolidated single-vendor accountability clauses; mid-tier robotics OEMs in Suwon exhibit highest sensitivity to per-unit silicon costs.
Supply Chain Analysis
Freight costs for advanced packaging substrates from Japan and Taiwan feed into landed cost calculations for Gyeonggi Province system integrators, compressing margins on low-volume AI module shipments. Wafer supply concentrates in South Korea, Taiwan, and the USA for sub-7nm logic; specialty DRAM for 2.5D chiplets integration draws from SK Hynix domestic fabs and Micron Singapore. Single-source vulnerability around EUV lithography equipment from ASML Netherlands creates chokepoint exposure. Distribution runs through direct foundry partnerships for Samsung Electronics and authorized distributor networks for fabless specialists serving mid-tier OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korea edge AI processor market reads as a late-cycle quality story, with municipal procurement consolidation under Intelligent Transport System 2.0 frameworks shifting demand toward pre-certified, high-reliability silicon. This specification creep favors vendors with domestic testing infrastructure and K-Netz sovereignty compliance already in place.
For Market Incumbents: Hedge against analog in-memory computing disruption by accelerating secure-enclave IP licensing from Korea Information Certificate Authority affiliates before ReRAM-based prototypes reach commercial scale. Defensive consolidation should prioritize backward integration into 2.5D packaging capacity in Suwon and Gwangju to capture chiplets heterogeneous integration premiums. Channel control through exclusive system integrator partnerships in Seoul Capital Area transit deployments protects against fabless specialist encroachment. For New Entrants and Emerging Players: Shipbuilding automation retrofits in the Busan-Ulsan manufacturing corridor represent the most penetrable white-space target, with vision-guided robotic welding systems remaining underpenetrated despite latent demand from heavy machinery clusters. Private 5G industrial network deployments under Korea Communications Commission 28GHz licenses create second-entry opportunity for on-premise inference hardware without competing against Samsung Electronics municipal dominance. Go-to-market angle should emphasize turnkey perception stack bundling with legacy PLC protocol translation layers. For Investors and Strategic Acquirers: Valuations sit cheapest among fabless NPU specialists with ISO 26262 functional safety certification gaps, as post-silicon verification talent scarcity concentrated among Seoul National University and KAIST alumni networks creates acquisition arbitrage. Long-term viability over the projection horizon hinges on heterogeneous integration capabilities rather than raw TOPS benchmarks alone. Watch MFDS Class III medical edge device cybersecurity pre-certification timelines as inflection indicator for domestic secure-enclave IP licensing demand.| Strategic Initiative | Industry Significance |
|---|---|
| Secure-Enclave IP Licensing | MFDS cybersecurity mandates for Class III devices accelerate Korea Information Certificate Authority affiliate revenue streams. |
| 2.5D Chiplets Packaging Partnership | Embedded DRAM integration enables new performance-per-watt tiers for battery-constrained drone OEMs in Gwangju. |
| K-Netz Sovereignty Pre-Certification | Compliance prequalification determines vendor eligibility before technical specifications enter Seoul Metropolitan Government bid evaluation. |
| Legacy PLC Protocol Translation | Mitsubishi Electric and Siemens control architecture integration unlocks smart factory retrofit velocity in Gyeonggi Province electronics plants. |
| Compute-in-Memory Prototyping | ReRAM bitcell arrays from KAIST spinouts compress standby power below 100 microwatts for Suwon smart appliance OEMs. |
Research Methodology
Multiple input streams — primary interviews with fabless design house CTOs, foundry planning executives, and municipal transit procurement officers; secondary validation through MFDS regulatory filings, Korea Communications Commission spectrum allocation records, and Samsung Electronics SEC disclosures; plus customs data on advanced packaging substrate imports — were reconciled through bottom-up and top-down triangulation. Stakeholder roles spanned system integrators in Songpa-gu, diagnostic imaging equipment vendors in Seongnam, and robotics OEM procurement teams in Suwon.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation modeled by product type, application workload, end-user compliance regime, and technology complexity tier. CAGRs were derived from installed base growth rates and replacement cycle compression in manufacturing quality-inspection retrofits. Industry-specific forecast inputs included private 5G network deployment timelines under Korea Communications Commission licensing frameworks and MFDS medical device certification queue lengths.
Inputs from Seoul Metropolitan Government procurement databases and Gyeonggi Province industrial cluster surveys were available through the study window; gaps in Busan-Ulsan shipbuilding automation retrofit spending introduce uncertainty bands around coastal regional projections. Forecasts reflect assumptions about K-Netz sovereignty criteria evolution and foundry capacity allocation priorities; stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Envelope Tracking Chips Market
Chipset and Processors
Netherlands Data Center Processor Market
Chipset and Processors
Automotive Chip Market
Chipset and Processors
Connecting Chiplets Market
Chipset and Processors
Displayport IP Market
Chipset and Processors
Advanced Audio Processor Market
Chipset and Processors
Protein Chip Market
Chipset and Processors
China Edge AI Processor Market
Chipset and Processors
United Kingdom Data Center Processor Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
IPC Soc Front-End Chip Market
Chipset and Processors
Artificial Intelligence (AI) Chipsets Market
Chipset and Processors
Global Battery Management IC Market
Chipset and Processors
Europe Neuromorphic Chip Market
Chipset and Processors
Data Processing Neuromorphic Chip Market
Chipset and Processors
Cockpit Soc Chip Market