
 Global Multimedia Chipsets Market | 2026-2036
Global Multimedia Chipsets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Multimedia Chipsets Market Outlook
Taiwan's foundry capacity expansion is reshaping supply dynamics for multimedia chipsets. Qualcomm leverages vertical integration to control premium smartphone application processor supply. MediaTek sustains cost leadership across mid-tier television SoC segments. NVIDIA dominates discrete graphics chipset architecture for gaming and professional visualization workloads.
Multimedia chipsets are integrated semiconductor devices that process, encode, decode, and render audio-visual content across multiple interfaces, typically manufactured on advanced CMOS nodes with dedicated DSP and GPU cores. These components enable real-time media processing in consumer electronics, automotive displays, and streaming infrastructure. Graphics chipsets command the highest margin pool due to complex IP licensing and performance-tier differentiation. Consumer electronics absorbs the largest volume share, though automotive systems represent the fastest-expanding end user category as cabin digitization accelerates. HDMI and USB-C connectivity standards now define technology selection criteria across television sets and streaming devices.
FCC equipment authorization requirements govern US market access for wireless-enabled multimedia chipsets, while EU REACH and RoHS frameworks restrict hazardous substances in semiconductor packaging materials. China's SAMR enforces national standards for electromagnetic compatibility in display-integrated devices. EMA and CE marking protocols apply to automotive-grade chipsets deployed in European vehicle platforms. Stakeholders must monitor evolving interface standards and regional certification timelines to secure design wins across fragmented OEM procurement cycles.
Market Dynamics
Automotive cabin digitization is compressing product lifecycles as OEMs demand chipsets supporting 8K displays and real-time AI inference within unified cockpit domains.
Growth Catalysts
- MIIT GB Standards:China's electromagnetic compatibility mandates for consumer electronics are accelerating chipset redesigns with integrated shielding architectures, pulling demand from domestic display manufacturers.
- HDMI 2.1 Proliferation:The interface standard's bandwidth requirements are forcing upgrades across television SoC portfolios, expanding addressable silicon content per unit.
- South Korea Cluster Effect:Concentrated semiconductor fabrication serving Samsung Display and LG Display is creating captive demand pools for locally sourced multimedia silicon.
Market Restraints
- Advanced Node Access:Sub-5nm CMOS capacity constraints at TSMC and Samsung Foundry are throttling supply for premium graphics chipsets, extending lead times beyond 26 weeks.
- EU REACH Compliance:RoHS substance restrictions on semiconductor packaging materials are forcing costly substrate redesigns and qualification cycles.
- Discrete GPU Substitution:Integrated graphics in CPU dies are capturing notebook and entry desktop segments, compressing discrete chipset volumes in sub-premium tiers.
Strategic Opportunities
- India PLI Incentives:Production-linked schemes for electronics manufacturing are attracting chipset packaging investments to serve domestic television and smartphone assembly.
- Automotive AI Convergence:Fusion of neural processing units with traditional video pipelines is opening architecture wins in driver monitoring and occupant experience systems.
- USB-C Universal Mandate:EU common charger regulations are consolidating connectivity requirements across streaming devices, enabling single-chip solutions replacing multi-interface legacy designs.
Industry Challenges
- SerDes IP Licensing:Complex royalty stacks for high-speed display interface cores are eroding margins and triggering litigation exposure across mid-tier suppliers.
- Automotive Qualification Timelines:AEC-Q100 stress testing and ISO 26262 functional safety certification cycles spanning 18-24 months are misaligning with consumer electronics pace expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Multimedia Chipsets Market |
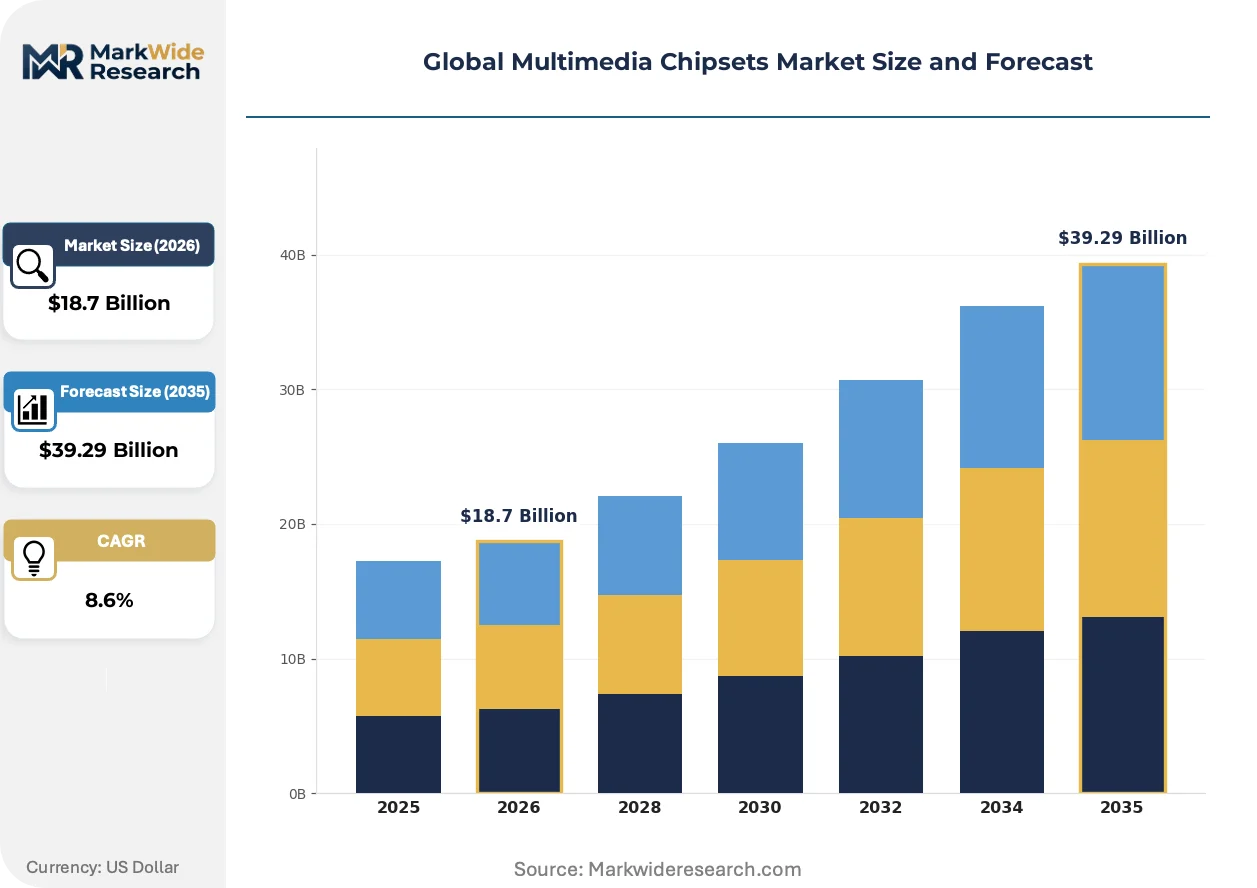
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Audio Processors, Video Encoder, Graphics Chipsets, Integrated Circuits End User: Consumer Electronics, Automotive Systems, Telecommunication, Industrial Equipment Technology: HDMI, DisplayPort, MHL, USB-C Application: Television Sets, Smartphones, Gaming Consoles, Streaming Devices |
| Companies Covered | Qualcomm, MediaTek, Intel, NVIDIA, Broadcom Corporation, STMicroelectronics, NXP Semiconductors, Samsung Electronics, Marvell Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Multimedia Chipsets Market Strategic Shifts
Chipset architectures are fragmenting into domain-specific accelerators as general-purpose GPU designs prove thermally and economically mismatched to edge inference workloads.
Chiplets with dedicated media engines are collapsing the traditional monolithic SoC model. Automotive Tier-1s are adopting these disaggregated designs for cockpit consolidation. This approach is collapsing silicon development costs by enabling mix-and-match IP blocks across process nodes.
REACH substance restrictions are tightening permissible materials in flip-chip underfills and mold compounds. Semiconductor packaging houses are qualifying halogen-free alternatives. European television manufacturers are prioritizing suppliers with pre-certified green material portfolios to preempt compliance risk.
Fleet procurement of streaming hardware is displacing retail channel dominance. Hospitality and multi-dwelling unit operators are contracting directly with chipset vendors for customized firmware and extended lifecycle guarantees. This shift is most pronounced in North American cable operator deployments seeking decade-long supply commitments.
Global Multimedia Chipsets Market Segmentation
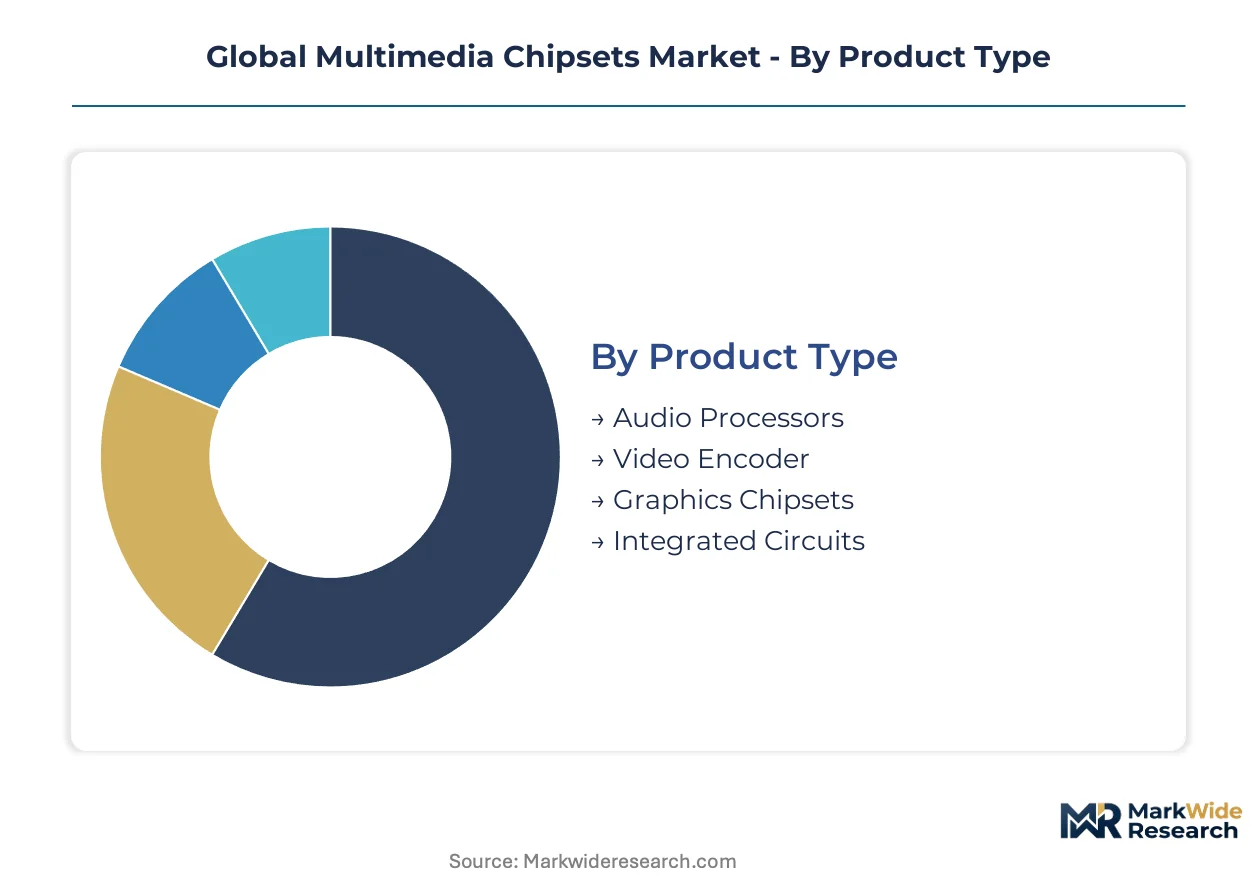
Multimedia chipset procurement patterns diverge sharply across technical specifications and deployment contexts. OEMs prioritize interface compatibility and thermal envelopes over raw performance in mass-market categories, while premium tiers reward architectural differentiation.
Product Type:
Mature process nodes dominate volume production, though advanced lithography concentrates in graphics and integrated categories where margin structures justify investment.
- Audio Processors:Dedicated DSP architectures handle real-time spatial audio rendering and noise cancellation algorithms. Smart speaker OEMs in Shenzhen and Dongguan are pulling silicon with ultra-low power envelopes for battery-operated form factors.
- Video Encoder:Hardware-accelerated compression engines support H.266/VVC and AV1 standards at broadcast bitrates. Cloud streaming infrastructure operators are specifying these for edge transcoding nodes to reduce datacenter load.
- Graphics Chipsets:Discrete GPU designs with dedicated VRAM controllers target gaming and professional visualization workloads.
- Integrated Circuits:Combined audio-video processing blocks with shared memory subsystems serve cost-constrained television and streaming device platforms.
Integrated Circuits handle the majority of throughput; Graphics Chipsets are climbing the fastest on share.
End User:
Application requirements span consumer-grade reliability to automotive functional safety, with procurement cycles stretching from six months to three years depending on qualification burden.
- Consumer Electronics:Television and streaming hardware manufacturers demand chipsets with multi-decade supply guarantees for replacement part ecosystems. Samsung Display and LG Display procurement teams in South Korea are consolidating vendor lists to three qualified sources per socket.
- Automotive Systems:Cockpit domain controllers require AEC-Q100 Grade 2 or Grade 1 temperature ratings with ISO 26262 ASIL-B minimum safety integrity. German OEMs are mandating local content shares that favor European packaging houses for final test and burn-in.
- Telecommunication:Baseband and edge processing equipment uses multimedia silicon for video analytics and subscriber content delivery.
- Industrial Equipment:Machine vision and human-machine interface panels specify extended temperature ranges and long-term firmware support.
Consumer Electronics commands the volume base; Automotive Systems is gaining share fastest as cabin digitization accelerates.
Technology:
Interface standardization is collapsing legacy differentiation, with USB-C mandates in Brussels and Beijing forcing convergence across previously fragmented connectivity portfolios.
- HDMI:The 2.1 specification's 48 Gbps bandwidth enables uncompressed 8K60 or 4K120 with dynamic HDR metadata. Television SoC roadmaps in Japan and Taiwan are prioritizing HDMI 2.1 transmitters as table stakes for premium tier positioning.
- DisplayPort:Embedded DisplayPort (eDP) dominates notebook panel interfaces with panel self-refresh for power reduction. Dell and HP procurement specifications are requiring DisplayPort 2.0 readiness for workstation-class mobile platforms launching in 2025-2026 windows.
- MHL:Mobile High-Definition Link enables smartphone-to-display connectivity over micro-USB or USB-C alternate modes.
- USB-C:Alternate mode implementations carry DisplayPort or HDMI signaling over reversible connectors with power delivery up to 240W.
HDMI carries the installed base; USB-C is expanding most quickly as regulatory mandates consolidate connector ecosystems.
Application:
Device form factors dictate thermal design power ceilings and integration complexity, with handheld platforms favoring monolithic integration and set-top boxes accommodating discrete component architectures.
- Television Sets:System-on-chip designs integrate CPU, GPU, audio DSP, and demodulator functions with AI upscaling engines. TCL and Hisense engineering teams in China are specifying chipsets with 4K120 MEMC and near-field voice processing for mid-tier price bands.
- Smartphones:Application processors with integrated graphics and media engines dominate, though dedicated image signal processors handle computational photography pipelines. Apple and Qualcomm vertical integration strategies are compressing third-party multimedia chipset attach rates in flagship tiers.
- Gaming Consoles:Custom AMD silicon powers Sony PlayStation and Microsoft Xbox platforms with unified memory architectures.
- Streaming Devices:Compact form factors prioritize thermal efficiency and cost-optimized 4K60 decode capabilities.
Television Sets anchor volume shipments; Streaming Devices are advancing fastest on unit growth as cord-cutting accelerates replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced lithography capacity clusters in Taiwan and South Korea are conditioning supply availability across downstream markets. Foundry utilization rates in these jurisdictions directly propagate into lead time volatility for fabless multimedia chipset designers. Regulatory divergence across major economies is fragmenting certification requirements and complicating unified product roadmaps.
United States
Data center streaming infrastructure and gaming console refresh cycles are absorbing high-margin graphics silicon. FCC equipment authorization mandates govern wireless-enabled chipset variants entering the market. Austin and Raleigh-Durham semiconductor corridors are attracting packaging investments to shorten time-to-certification for domestic OEMs.
China
Domestic television manufacturing scale and automotive cockpit localization programs are pulling silicon volumes. MIIT GB electromagnetic compatibility standards and SAMR display-integrated device regulations are accelerating redesign cycles with integrated shielding. Shenzhen and Dongguan electronics clusters are consolidating procurement around qualified local chipset packaging houses.
South Korea
Samsung Display and LG Display procurement teams are sourcing multimedia silicon for advanced panel integration. The national semiconductor fabrication base serves these captive demand pools with prioritized capacity allocation. Seoul Capital Area foundry complexes are expanding 8-inch and 12-inch lines dedicated to display driver and timing controller chipsets.
Germany
Automotive OEM cockpit digitization programs are specifying AEC-Q100 Grade 2 chipsets with ISO 26262 ASIL-B certification. KBA type approval processes and EU REACH substance restrictions are extending qualification timelines and forcing substrate material transitions. Bavaria-based Tier-1 suppliers are mandating local content shares that favor European packaging houses for final test.
Japan
Television SoC roadmaps are prioritizing HDMI 2.1 transmitters as table stakes for premium tier positioning. METI industrial standards and JIS electromagnetic compatibility frameworks govern consumer electronics market access. Tokyo and Osaka engineering centers are specifying chipsets with 4K120 MEMC and near-field voice processing for domestic OEMs.
Global Multimedia Chipsets Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in discrete functional blocks. The vendor base stratifies between consolidated application processor architects and fragmented specialty encoder suppliers. Two archetypes dominate: fabless semiconductor designers leveraging foundry partnerships, and integrated device manufacturers with captive fabrication. Capacity reservation agreements and IP licensing consortia represent the primary competitive vectors for securing design wins.
Among fabless platform architects, Qualcomm and MediaTek exemplify divergent tier strategies. NVIDIA occupies a position at the performance-intensive end of graphics specialization. These three anchors illustrate how competitive positioning splits between premium smartphone vertical integration and cost-optimized television SoC volume plays.
| Leading Market Players |
|---|
| Qualcomm |
| MediaTek |
| Intel |
| NVIDIA |
| Broadcom Corporation |
| STMicroelectronics |
| NXP Semiconductors |
| Samsung Electronics |
| Marvell Technology Group |
| Others |
Value Chain & Pricing Dynamics
The Kaohsiung-Taichung semiconductor logistics corridor anchors cost dynamics for multimedia chipset distribution, with freight consolidation fees amplifying margin pressure at foundry-adjacent packaging houses while downstream price differentiation stratifies across automotive-grade certification tiers and consumer electronics volume bands.
Pricing Analysis
EU REACH substance restrictions dictate the pricing tier structure across substrate material categories, separating halogen-free packaging portfolios from legacy compound alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects AEC-Q100 Grade 1 certification premiums versus consumer-grade thermal ratings. Cost compression in mid-tier television SoC segments intensifies because integrated graphics substitution erodes discrete GPU attach rates. Automotive OEM procurement teams exhibit lowest price sensitivity due to decade-long supply guarantees, while streaming device manufacturers prioritize unit economics above architectural differentiation.
Supply Chain Analysis
300mm silicon wafer feedstock draws from Taiwan, South Korea, and Japan as primary ingot sourcing regions for advanced CMOS nodes. Photoresist chemicals, high-purity gases, and sputtering targets rest on concentrated Japanese and German specialty material suppliers. Single-source vulnerability permeates extreme ultraviolet lithography equipment dependency on ASML's Dutch manufacturing base. Distribution runs through South Korean display panel clusters and Shenzhen electronics assembly corridors before reaching global OEM integration lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive cabin digitization represents a high-growth disruption as 8K display mandates and AI inference fusion compress legacy chipset refresh cycles. MIIT GB electromagnetic compatibility standards accelerate this inflection by forcing shielding architecture redesigns across domestic Chinese supply chains.
For Market Incumbents: Build captive foundry capacity moats through reservation agreements at TSMC and Samsung Foundry to throttle emerging fabless competitors. Deepen backward integration into SerDes IP portfolios to deflect royalty stack litigation exposure. Prioritize AEC-Q100 Grade 2 pre-certification investments to capture cockpit domain controller sockets ahead of German OEM localization requirements. For New Entrants and Emerging Players: India PLI electronics manufacturing incentives represent the most penetrable entry point for packaging-stage investments serving domestic television and smartphone assembly. Automotive AI convergence in driver monitoring systems offers white-space architecture wins outside incumbent GPU-dominated visualization pipelines. Contract directly with hospitality fleet operators seeking customized firmware and extended lifecycle guarantees as a channel bypass strategy. For Investors and Strategic Acquirers: Fabless specialty encoder suppliers with AV1 and H.266/VVC hardware acceleration cores anchor acquisition target archetypes as cloud streaming infrastructure scales. Long-term viability hinges on 5-10 year interface standard durability through HDMI 2.1 and USB-C alternate mode consolidation. Monitor USB-C universal mandate enforcement timelines in Brussels and Beijing as inflection indicators for single-chip solution displacement of multi-interface legacy designs.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | TSMC and Samsung Foundry allocation agreements secure sub-5nm node access for premium graphics portfolios. |
| Automotive Safety Certification | AEC-Q100 Grade 2 and ISO 26262 ASIL-B pre-qualification opens German OEM cockpit digitization programs. |
| IP Licensing Consortium | SerDes royalty pool participation defends margins against litigation exposure in high-speed display interfaces. |
| Chiplets Architecture Transition | Disaggregated media engine designs reduce silicon development costs for automotive Tier-1 cockpit consolidation. |
| India Packaging Investment | PLI scheme utilization captures domestic television and smartphone assembly demand with shortened logistics loops. |
Study Parameters
The analysis maps audio processors, video encoders, graphics chipsets, and integrated circuits, each validated through foundry operations executives, automotive Tier-1 procurement directors, television OEM platform engineers, and streaming device firmware architects. Primary interview findings triangulate against SEMI equipment billings data, MIIT GB standard filings, FCC equipment authorization databases, and EU REACH substance restriction updates. Bottom-up unit shipment modeling reconciles with top-down semiconductor revenue aggregation across the analysis window.
Fixed assumptions include continued sub-5nm capacity constraints at leading foundries, sustained HDMI 2.1 interface proliferation, and unaltered EU common charger regulations. Modeled segmentation spans product type, end user category, connectivity technology, and application form factor. CAGRs derive from regression analysis against historical foundry utilization rates and panel manufacturer procurement cycles. Automotive AI convergence penetration and cloud streaming infrastructure capex trajectories inform scenario-weighted outcomes.
Practitioners should monitor TSMC and Samsung Foundry capacity allocation announcements, MIIT GB standard revision timelines, and EU REACH substance restriction updates for early signals of forecast revision. Cross-checking against SEMI silicon wafer shipment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Superconducting Quantum Chip Market
Chipset and Processors
Indonesia Data Center Processor Market
Chipset and Processors
United States Data Center Processor Market
Chipset and Processors
India Data Center Processor Market
Chipset and Processors
Global ARM Microcontrollers Market
Chipset and Processors
Display Driver Market
Chipset and Processors
Machine Learning Chip Market
Chipset and Processors
Microserver Market
Chipset and Processors
DNA Sequencing Chip Market
Chipset and Processors
Consumer Electronics Chip Market
Chipset and Processors
United Arab Emirates Data Center Processor Market
Chipset and Processors
Automotive Infotainment SOC Market
Chipset and Processors
5G Processor Market
Chipset and Processors
Optical Microcontrollers Market
Chipset and Processors
Global Merchant Embedded Computing Market
Chipset and Processors
Artificial Intelligence (AI) Chipsets Market