
 High Performance Computing (HPC) Chipset Market | 2026-2036
High Performance Computing (HPC) Chipset Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Computing (HPC) Chipset Market Analysis
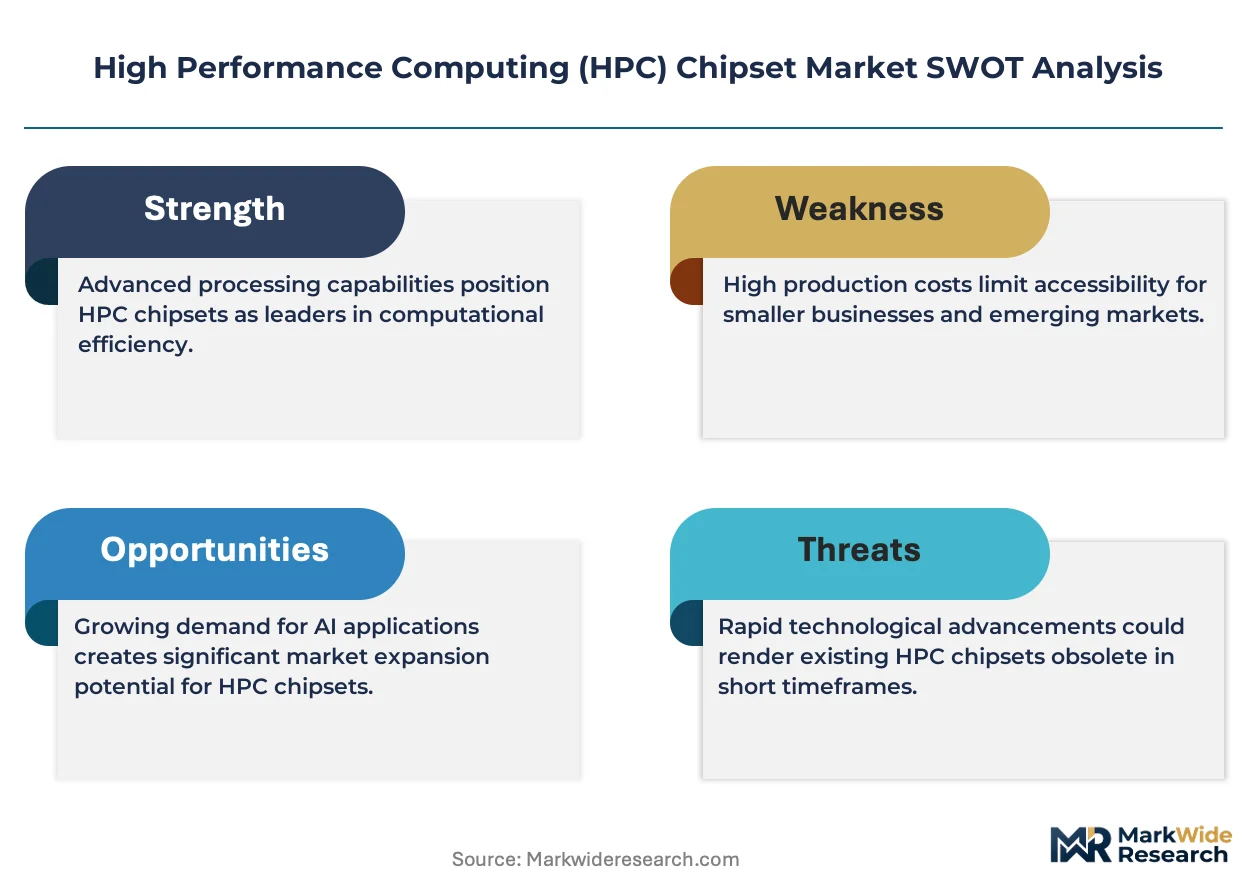
The premium HPC chipset tier is decoupling from commodity silicon in terms of process node access, packaging complexity, and thermal design power thresholds. NVIDIA Corporation dominates the accelerator segment through its vertically integrated CUDA ecosystem and advanced packaging roadmaps. Intel Corporation leverages its IDM model to sustain captive wafer supply for Xeon-based HPC platforms. Advanced Micro Devices, Inc. competes aggressively in data-center CPU sockets with its Zen architecture and chiplet-based designs.
High performance computing chipsets are integrated circuits engineered for teraflop-scale throughput, sub-nanosecond interconnect latency, and power envelopes exceeding 400 watts, purpose-built to execute parallelized workloads in scientific simulation and artificial intelligence training. GPU product types capture the dominant share of accelerator attach rates as generative artificial intelligence training clusters expand. Quantum computing technology remains nascent but occupies the highest-margin R&D channel as government laboratories fund fault-tolerant qubit development. Artificial intelligence application demand is reshaping foundry allocation, with leading-edge nodes prioritizing HPC tape-outs over mobile and consumer silicon.
The U.S. CHIPS and Science Act and the EU Chips Act collectively redirect subsidy flows toward domestic advanced-node fabrication, tightening market access for non-aligned foundry customers. China's MIIT imposes GB standards and dual carbon goals that constrain data-center power density, indirectly capping chipset thermal design power ceilings for deployments within that jurisdiction. Stakeholders must monitor how export control lists from the U.S. Department of Commerce and European Commission evolve to restrict lithography equipment and design software access, as these instruments determine which chipset architectures can reach production at scale.
Market Dynamics
Exascale procurement timelines are compressing foundry allocation windows, forcing chipset vendors to secure advanced node capacity years ahead of tape-out as national laboratories accelerate supercomputer refresh cycles.
Growth Catalysts
- Generative AI training clusters:Hyperscale datacenters in the United States and Taiwan are expanding GPU attach rates for large language model workloads, pulling wafer starts toward HPC priority queues.
- EU Chips Act subsidies:Brussels is directing capital toward domestic advanced-node fabrication, creating new foundry options for European supercomputing consortia seeking supply chain resilience.
- MIIT dual carbon mandates:China's efficiency standards for datacenter power density are accelerating demand for high-performance-per-watt silicon architectures.
Market Restraints
- TSMC foundry concentration:Leading-edge 3nm and 2nm capacity remains concentrated in Taiwan's Hsinchu Science Park, exposing procurement pipelines to seismic and geopolitical disruption risk.
- EUV lithography equipment scarcity:ASML's extreme ultraviolet machine output limits annual wafer starts for sub-5nm HPC designs regardless of design readiness.
- High-bandwidth memory supply:HBM3E and HBM4 stack availability from Samsung and SK Hynix is constraining accelerator package yields.
Strategic Opportunities
- India's semiconductor PLI scheme:New Delhi's production-linked incentives are attracting assembly and test capacity for HPC packaging, offering a secondary geography for supply chain diversification.
- Quantum-classical hybrid systems:Convergence of cryogenic control electronics with conventional GPU clusters is opening R&D procurement channels at national laboratories.
- Advanced substrate technologies:Glass core and embedded silicon bridge interposers are enabling new 2.5D/3D packaging architectures that decouple logic from memory supply constraints.
Industry Challenges
- Packaging thermomechanical engineering:Sub-50 micron bump pitch and thermal interface material selection require specialized talent pools concentrated in Taiwan and South Korea.
- Export control compliance:U.S. Department of Commerce entity list restrictions are forcing architecture segmentation between licensable and restricted performance tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Performance Computing (HPC) Chipset Market |
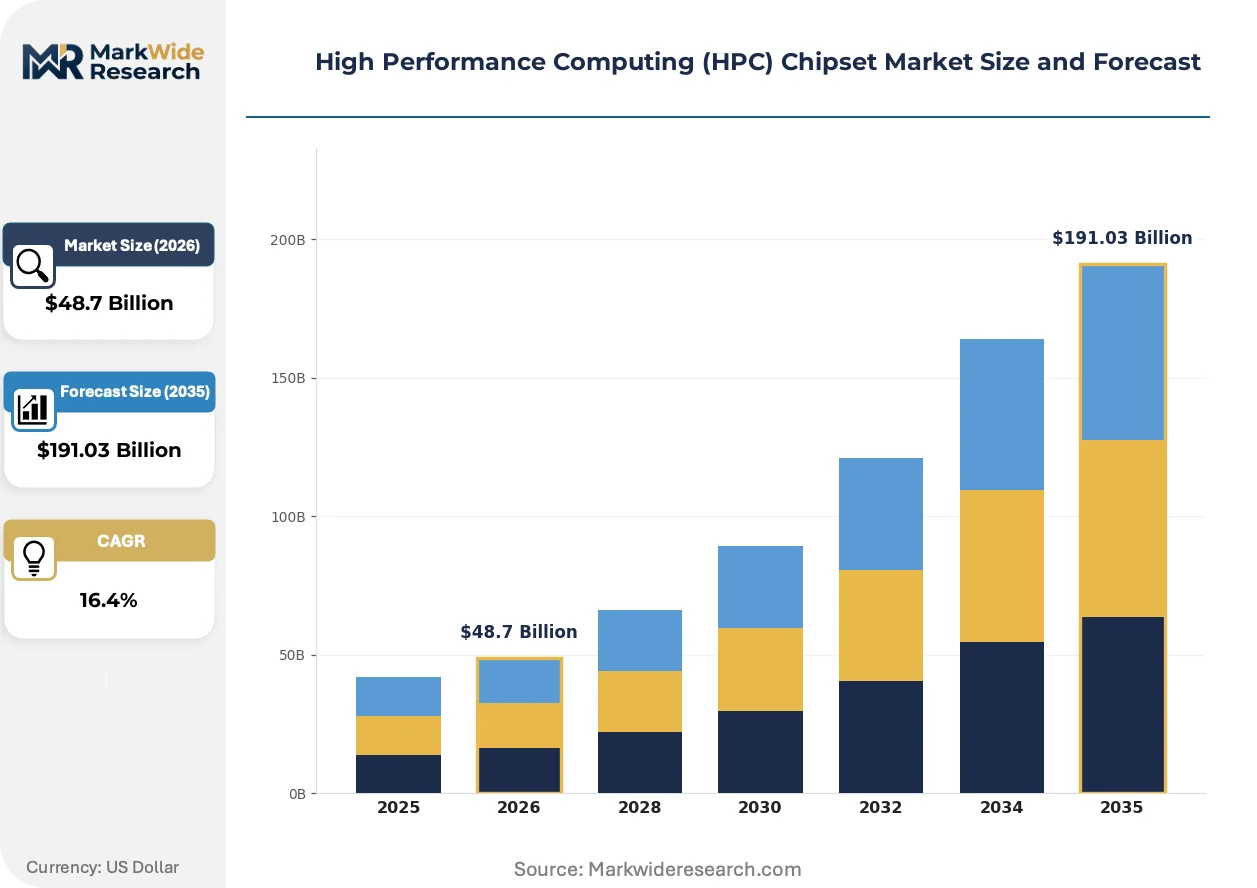
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $191.03 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CPU, GPU, FPGA, ASIC Technology: Parallel Computing, Quantum Computing, Cluster Computing, Grid Computing End User: Aerospace, Automotive, Healthcare, Research Institutions Application: Weather Simulation, Molecular Modeling, Financial Modeling, Artificial Intelligence |
| Companies Covered | Hewlett Packard Enterprise Company, Cisco Systems, Inc., Intel Corporation, Achronix Semiconductor Corporation, Lattice Semiconductor Corporation, NVIDIA Corporation, IBM Corporation, MediaTek, Inc., Advanced Micro Devices, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Computing (HPC) Chipset Market Emerging Trajectories
Chiplet disaggregation is redrawing the boundary between logic, memory, and I/O silicon, enabling modular accelerator designs that mix process nodes within a single package substrate.
Coherent optical interconnects between GPU clusters are rewriting rack-scale power budgets and latency floors. Hyperscale operators in the United States are deploying CPO-enabled backplanes in training pods exceeding ten thousand accelerators. This photonic integration is compressing the economic viability of copper-only electrical signaling beyond 51.2 Tbps switch capacities.
The EU AI Act's risk-based classification system is mandating traceability and energy disclosure for high-performance training hardware sold into European supercomputing centers. Brussels is requiring documentation of datacenter carbon intensity per petaflop-hour. German and French procurement agencies are now weighting sustainability certifications in tender evaluations alongside raw compute density.
Hyperscale buyers are consolidating accelerator purchases through direct foundry partnerships rather than traditional distributor channels. Amazon Web Services, Microsoft Azure, and Google Cloud are negotiating multi-year wafer commitments that bypass semiconductor trading houses entirely. This disintermediation is most pronounced in the United States, where cloud operators now account for the dominant share of leading-edge GPU wafer demand.
High Performance Computing (HPC) Chipset Market Segmentation
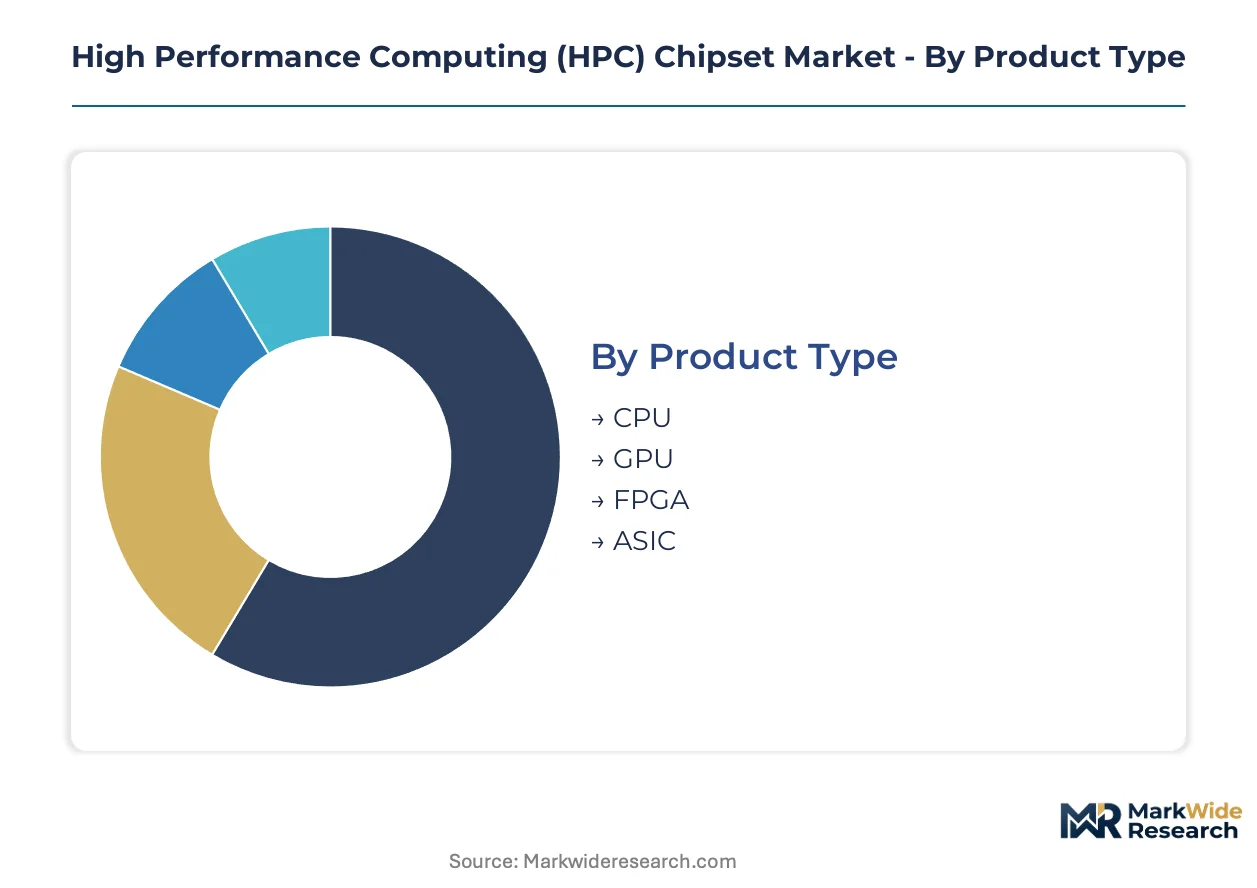
HPC chipset procurement diverges sharply across workload types, with accelerator architectures commanding premium foundry allocation while legacy sockets face extended refresh cycles. Segmentation reveals how thermal envelopes, interconnect protocols, and software ecosystem lock-in reshape vendor selection criteria at exascale deployment scales.
Product Type:
Certification burdens concentrate on GPU and CPU segments, where FCC Part 15 emissions testing and EU CE marking for electromagnetic compatibility add six to nine months to qualification timelines. FPGA and ASIC categories navigate lighter regulatory overhead but face stricter foundry NDA requirements for custom tape-outs.
- GPU:Massively parallel streaming multiprocessors with HBM3E memory stacks dominate generative AI training clusters. Hyperscale datacenters in the United States and Taiwan account for dominant wafer demand as large language model parameters scale past one trillion.
- CPU:High-core-count x86 and ARM designs with AVX-512 or SVE instruction sets anchor traditional supercomputing sockets. National laboratories in Germany and Japan prioritize CPU-accelerator hybrid nodes for weather and fusion simulation workloads.
- FPGA:Reconfigurable logic arrays from Xilinx and Intel enable low-latency financial matching engines and adaptive signal processing.
- ASIC:Custom silicon for cryptocurrency hashing and AI inference delivers superior performance-per-watt at the cost of architectural inflexibility.
Leading the category by volume: GPU. Growing fastest: ASIC.
Technology:
Cost tier stratification separates mature parallel computing deployments from experimental quantum systems requiring dilution refrigeration infrastructure. Grid computing occupies the lowest capital intensity band, leveraging commodity Ethernet rather than proprietary interconnects.
- Parallel Computing:SIMD and MIMD architectures with MPI or OpenMP programming models execute across thousands of homogeneous cores. Research institutions in France and the United States maintain the largest installed base of x86-based parallel clusters.
- Quantum Computing:Superconducting and trapped-ion qubit systems demand cryogenic control ASICs operating at millikelvin temperatures. Government laboratories in Canada and Australia fund fault-tolerant quantum error correction roadmaps.
- Cluster Computing:Beowulf-style commodity node aggregation with InfiniBand or RoCE interconnects serves mid-scale academic workloads.
- Grid Computing:Federated resource sharing across geographically distributed sites supports high-throughput screening and volunteer computing projects.
Parallel computing claims the largest installed base. Quantum systems are climbing the fastest.
End User:
Application-specific margin profiles vary dramatically, with aerospace and automotive segments requiring DO-254 and ISO 26262 safety certifications that inflate non-recurring engineering costs by forty to sixty percent. Healthcare and research institutions operate under lighter regulatory frameworks but face stringent procurement transparency mandates.
- Aerospace:Radiation-hardened processors for satellite payload processing and computational fluid dynamics for airframe design. European Space Agency programs in France and Germany drive qualification requirements for extreme temperature cycling.
- Automotive:ADAS simulation and autonomous vehicle training clusters require deterministic latency guarantees. OEMs in Japan and Germany are building dedicated HPC facilities for crash simulation and battery thermal modeling.
- Healthcare:Genomic sequencing pipelines and molecular dynamics for drug discovery. Research hospitals in the United States and Switzerland deploy GPU clusters for protein folding prediction.
- Research Institutions:National laboratories and university supercomputing centers with diverse workload portfolios spanning climate, materials, and fundamental physics.
Research institutions lead procurement volume. Automotive is expanding most quickly.
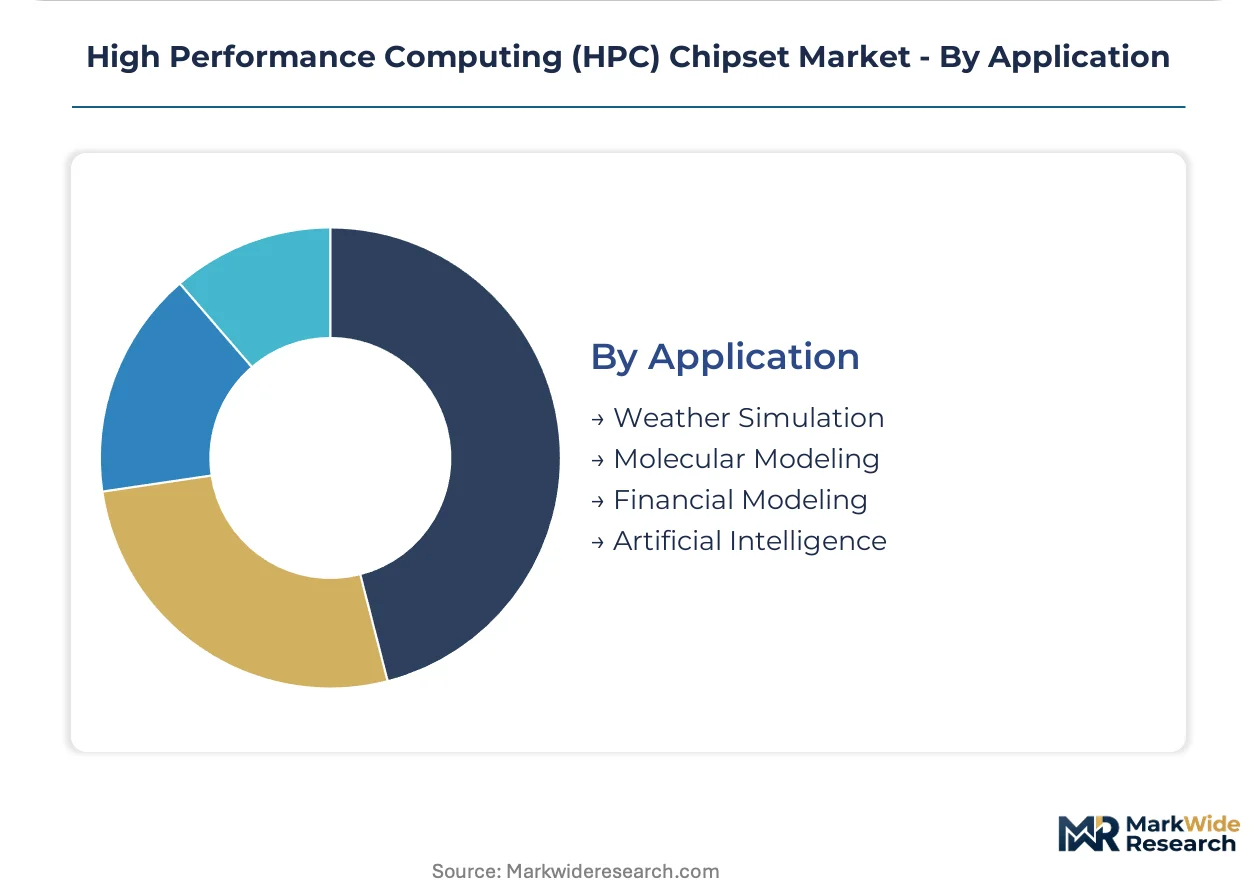
Application:
Customer type concentration shapes pricing architecture, with artificial intelligence workloads commanding annual contracts tied to accelerator availability while weather simulation follows multi-year supercomputer procurement cycles with fixed-price milestones.
- Artificial Intelligence:Deep learning training and inference at scales requiring ten-thousand-plus GPU pod configurations. Cloud operators in the United States negotiate direct foundry capacity reservations, bypassing traditional semiconductor distribution.
- Weather Simulation:Numerical weather prediction with kilometer-scale resolution demands CPU-heavy architectures with strict MPI scaling efficiency. National meteorological services in the United Kingdom and Japan drive exascale procurement timelines.
- Molecular Modeling:Quantum chemistry and materials science simulations using density functional theory and molecular dynamics. Pharmaceutical companies in Switzerland and Germany prioritize accuracy over raw throughput.
- Financial Modeling:Monte Carlo risk simulation and real-time derivatives pricing with sub-microsecond latency requirements. Investment banks in the United States and Singapore deploy FPGA-accelerated tick-to-trade systems.
Artificial intelligence dominates current demand. Financial modeling shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors the world's leading-edge wafer fabrication for HPC processors, concentrating 3nm and 2nm capacity within a single metropolitan corridor. National laboratories across three continents are accelerating exascale procurement timelines, reshaping foundry allocation windows and regional competitive positioning.
United States
Hyperscale datacenters in Virginia and Oregon are expanding GPU attach rates for generative AI training clusters. The CHIPS and Science Act directs federal subsidies toward domestic advanced-node fabrication in Arizona and Texas. Intel Corporation maintains captive wafer supply through its IDM facilities in New Mexico and Oregon for Xeon-based HPC platforms.
China
MIIT dual carbon mandates are capping datacenter power density in Beijing and Shanghai, indirectly constraining thermal design power ceilings for domestic deployments. GB standards impose efficiency requirements that accelerate demand for high-performance-per-watt silicon architectures. Yangtze Memory Technologies and local design houses are advancing domestic alternatives despite export control restrictions on lithography equipment.
Germany
Forschungszentrum Jülich and Leibniz Supercomputing Centre are driving exascale procurement for weather and fusion simulation workloads. The EU Chips Act redirects capital toward domestic advanced-node fabrication, creating foundry options for European supercomputing consortia. Bavaria's semiconductor cluster around Munich is attracting advanced packaging R&D investments from international vendors.
Japan
RIKEN and national meteorological services are prioritizing CPU-accelerator hybrid nodes for kilometer-scale weather prediction. METI funding programs support domestic development of cryogenic control electronics for quantum-classical hybrid systems. Kyushu's silicon foundry corridor is expanding capacity for specialty HPC components serving regional supercomputing centers.
South Korea
Samsung Electronics and SK Hynix dominate high-bandwidth memory supply for GPU accelerators, though HBM3E and HBM4 stack availability is constraining package yields. Government-backed semiconductor initiatives are expanding advanced packaging capacity in the Seoul Capital Area. Pangyo Techno Valley hosts design centers developing next-generation interconnect IP for exascale architectures.
High Performance Computing (HPC) Chipset Market Vendor Landscape
Premium-margin players sit above commodity-margin players across packaging complexity, thermal design power thresholds, and foundry node access. The vendor base stratifies into three tiers: vertically integrated IDMs with captive wafer supply, fabless designers dependent on TSMC allocation, and specialized packaging houses bridging logic and memory supply constraints. Dominant competitive moves include securing multi-year foundry capacity reservations and developing proprietary interconnect ecosystems that lock in hyperscale procurement.
Within the vertically integrated tier, Intel Corporation exemplifies captive supply chain control through in-house fabrication. NVIDIA Corporation and Advanced Micro Devices, Inc. occupy positions as fabless designers negotiating direct wafer commitments with Taiwan-based foundries. These three companies anchor the competitive structure, with NVIDIA representing the accelerator-focused archetype and AMD exemplifying chiplet-based modular design strategies.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise Company |
| Cisco Systems, Inc. |
| Intel Corporation |
| Achronix Semiconductor Corporation |
| Lattice Semiconductor Corporation |
| NVIDIA Corporation |
| IBM Corporation |
| MediaTek, Inc. |
| Advanced Micro Devices, Inc. |
| Others |
Supply Flow & Price Mechanics
Advanced packaging roadmaps with sub-50 micron bump pitches and thermal interface material innovations are simultaneously inflating cost structures and concentrating procurement leverage among hyperscale buyers with direct foundry access. This technology transition favors vertically integrated incumbents who can amortize fixed costs across captive wafer supply while fabless competitors face allocation uncertainty at leading-edge nodes.
Pricing Analysis
Value-based pricing anchored to petaflop-hour throughput and training workload completion time dominates accelerator procurement contracts. Three-tier pricing structure across premium, standard, and economy levels separates exascale-qualified silicon from datacenter-grade and edge inference tiers, with certification burdens for FCC Part 15 and EU CE marking adding six to nine months to qualification timelines. Cost compression in the standard tier is intensifying because hyperscale operators are consolidating purchases through direct foundry partnerships that bypass semiconductor distribution channels. Research institutions with fixed-budget procurement cycles exhibit the highest price sensitivity, while cloud operators negotiating multi-year wafer commitments demonstrate the lowest.
Supply Chain Analysis
Regional distribution centers in Hsinchu Science Park, Seoul Capital Area, and Phoenix anchor hub-and-spoke patterns for advanced packaging components and finished accelerators. Wafer fabrication concentrates in Taiwan and South Korea, with high-bandwidth memory supply anchored in South Korea and specialty substrate development spreading to Germany and Japan. The supply chain draws from EUV lithography equipment, HBM3E memory stacks, and glass core interposers as critical inputs. Single-source vulnerability at the 3nm and 2nm node level exposes procurement pipelines to seismic and geopolitical disruption risk. Distribution runs through direct foundry partnerships rather than traditional semiconductor trading houses for hyperscale buyers, while national laboratories and research institutions retain distributor channels for smaller-volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EUV lithography equipment scarcity and foundry allocation constraints is forcing weaker fabless players toward exit or acquisition, concentrating market share among incumbents with secured capacity reservations.
For Market Incumbents: Acquire advanced packaging engineering talent pools concentrated in Taiwan and South Korea to defend against chiplet disaggregation threats from modular competitors. Secure multi-year wafer commitments at TSMC and Samsung Foundry before national laboratory exascale procurement accelerates allocation competition, while investing in proprietary interconnect ecosystems that lock in hyperscale procurement through software-hardware co-optimization.
For New Entrants and Emerging Players: The price-point gap between premium exascale-qualified silicon and economy-tier edge inference accelerators offers white-space entry for specialized ASIC designers targeting cryptocurrency hashing and adaptive signal processing workloads. India's semiconductor PLI scheme presents the most penetrable geography for assembly and test capacity investments, with production-linked incentives reducing capital intensity for packaging-focused entrants. A go-to-market angle emphasizing high-performance-per-watt architectures for MIIT dual carbon compliance in China can bypass direct competition with CUDA-locked hyperscale incumbents.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by hyperscale cloud operators seeking vertical integration into accelerator design, with NVIDIA and AMD representing comparable archetypes for strategic value. Long-term viability across the analysis window favors fabless designers with secured foundry allocation and proprietary interconnect IP over commodity packaging houses facing margin compression. The signal to watch is ASML's annual EUV machine output announcements, which constrain total addressable wafer starts regardless of design readiness or demand intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Foundry Partnership | Hyperscale operators in Virginia and Oregon bypass distributors to secure multi-year wafer commitments for GPU clusters. |
| Advanced Packaging R&D Investment | Bavaria's semiconductor cluster attracts glass core interposer development from international vendors serving European consortia. |
| Proprietary Interconnect Ecosystem | CUDA and ROCm software-hardware integration locks in procurement from national laboratories and cloud training pod deployments. |
| Chiplet Disaggregation Architecture | Modular designs mixing process nodes within single package substrates reduce dependency on unified leading-edge capacity. |
| Quantum-Classical Hybrid Development | Cryogenic control electronics convergence with GPU clusters opens R&D procurement channels at Canadian and Australian government laboratories. |
Methodological Framework
Document review covered SEC 10-K filings from Intel, NVIDIA, and AMD, hyperscaler capex disclosures from Amazon Web Services and Microsoft Azure, and national laboratory procurement records, complemented by interviews with supercomputing center procurement directors, foundry account managers, and advanced packaging engineering leads. Secondary validation drew from EIA datacenter power consumption data, EU Chips Act implementation reports, and MIIT GB standard filings. Bottom-up wafer demand modeling triangulated against top-down market sizing from foundry capacity announcements and accelerator shipment tracking.
Segmentation outputs across product type, technology node, end user category, and application workload were produced through cross-referencing procurement timelines with foundry allocation windows. CAGRs were derived from exascale refresh cycle acceleration and generative AI training cluster expansion curves, with inputs including EUV lithography equipment delivery schedules, HBM3E yield trajectories from Samsung and SK Hynix, and CHIPS Act subsidy disbursement flows across Arizona and Texas fabrication facilities.
Inputs from hyperscale operator procurement committees and national laboratory technical directors were available through the study window; gaps in classified government supercomputer specifications and foundry yield data at the 2nm node introduce uncertainty bands around accelerator volume forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
United Arab Emirates Data Center Processor Market
Chipset and Processors
Edge AI Chipset Market
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
Global Digital Light Processing Chipset Market
Chipset and Processors
Processor for Smartphones Market
Chipset and Processors
Global Neural Processors Market
Chipset and Processors
Global Wireless Chipsets Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
Protein Chip Market
Chipset and Processors
Canada Data Center Processor Market
Chipset and Processors
Displayport IP Market
Chipset and Processors
South Korea Edge AI Processor Market
Chipset and Processors
Nano Chip Market
Chipset and Processors
Multi-Mode Chipset Market
Chipset and Processors
Japan Data Center Processor Market