
 AI Chipsets Market | 2026-2036
AI Chipsets Market Size, Share, and Industry Trends Forecast 2026-2036
AI Chipsets Market Analysis
Taiwan is fragmenting as the primary geography where foundry capacity expansion for AI accelerators concentrates, with TSMC extending its lead in advanced CoWoS packaging while Samsung Electronics competes through its own 3nm GAA process development. NVIDIA Corporation leverages vertical integration in software-hardware co-design to sustain pricing power in data center GPUs. Intel Corporation anchors its position through foundry ambitions and U.S.-based manufacturing investments, though it navigates yield challenges at the most advanced nodes.
AI chipsets comprise purpose-built silicon architectures optimized for matrix multiplication and parallel tensor operations, typically fabricated on sub-5nm process nodes with high-bandwidth memory integration to minimize data movement bottlenecks. GPU segments dominate current revenue flows due to their programmability advantage in training workloads, while ASIC designs occupy the fastest-expanding niche for inference-at-scale deployments where power efficiency dictates total cost of ownership. FPGA technology leads in prototyping and low-volume edge applications where reconfigurability offsets unit economics.
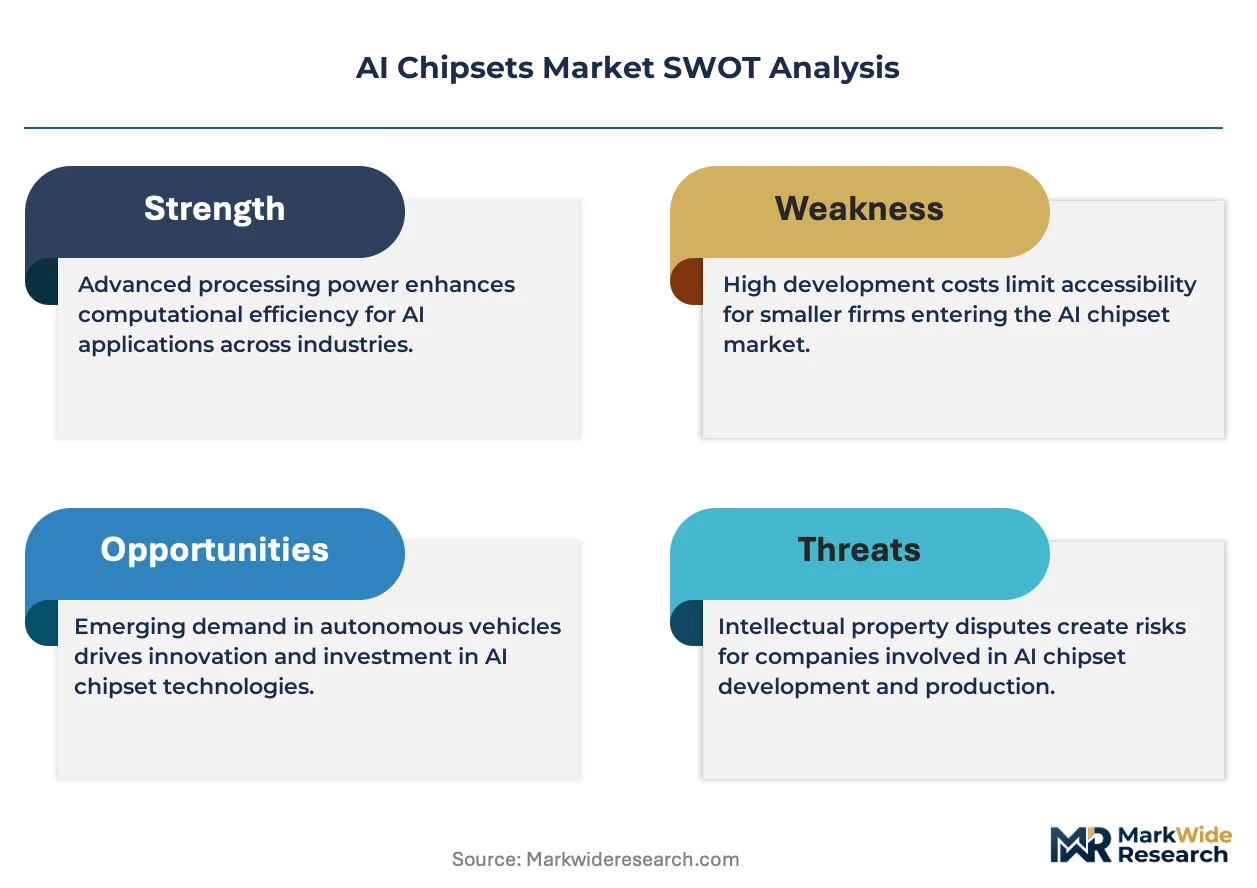
The U.S. Department of Commerce's Bureau of Industry and Security export controls restrict advanced AI chip sales to specific destinations, forcing architecture modifications and geographic market segmentation. The EU AI Act's risk-based classification system imposes conformity requirements on high-stakes AI deployments, creating demand for traceable, auditable hardware provenance. China's MIIT domestic substitution mandates and SAMR standard-setting accelerate parallel supply chain development outside Western technology ecosystems. Stakeholders must monitor how jurisdictional fragmentation of semiconductor policy reshapes customer qualification pathways and foundry partner selection criteria.
Market Dynamics
Foundry capacity concentration in Taiwan is creating structural dependency for advanced AI accelerators, as TSMC's CoWoS packaging dominance locks in supply-side leverage while geopolitical fragmentation forces customers to qualify secondary sources.
Growth Catalysts
- Cloud hyperscaler capex cycles:Microsoft, Amazon, and Google are expanding AI training clusters, pulling silicon demand forward through multi-year infrastructure commitments.
- EU AI Act hardware provenance rules:Risk-based classification for high-stakes AI deployments mandates auditable supply chains, creating preference for traceable foundry partnerships.
- Sub-5nm process maturation:Yield improvements at 3nm and impending 2nm ramps enable larger reticle sizes and higher transistor density for transformer architectures.
Market Restraints
- High-bandwidth memory supply constraints:SK Hynix and Samsung Electronics control HBM3E output, creating input bottlenecks for advanced accelerators regardless of logic wafer availability.
- US BIS export control architecture:Performance density thresholds restrict shipment of advanced AI chips to China, forcing product segmentation and architecture downgrades for excluded markets.
- CoWoS packaging capacity scarcity:TSMC's advanced packaging lines operate at committed allocation, extending lead times for AI accelerator customers without pre-paid capacity reservations.
Strategic Opportunities
- India's semiconductor PLI scheme:Government incentives for domestic chip design and packaging are attracting AI accelerator fabless players to establish development centers in Bangalore and Hyderabad.
- Edge inference ASIC penetration:Autonomous vehicles and industrial vision systems require low-latency, power-constrained silicon, opening demand outside data center concentration.
- Photonic interconnect convergence:Co-packaged optics with electronic chiplets promises bandwidth density beyond electrical I/O limitations, enabling new system architectures.
Industry Challenges
- Advanced node physical design talent scarcity:Expertise in 3nm floorplanning and thermal-aware placement resides with limited engineering teams, constraining customer chip development velocity.
- Multi-die integration complexity:Chiplet-based designs require new EDA workflows and interposer qualification protocols, extending time-to-tapeout for AI accelerator startups.
- Cross-border IP licensing friction:RISC-V and proprietary ISA disputes complicate architecture licensing for new entrants building training-class silicon.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Chipsets Market |
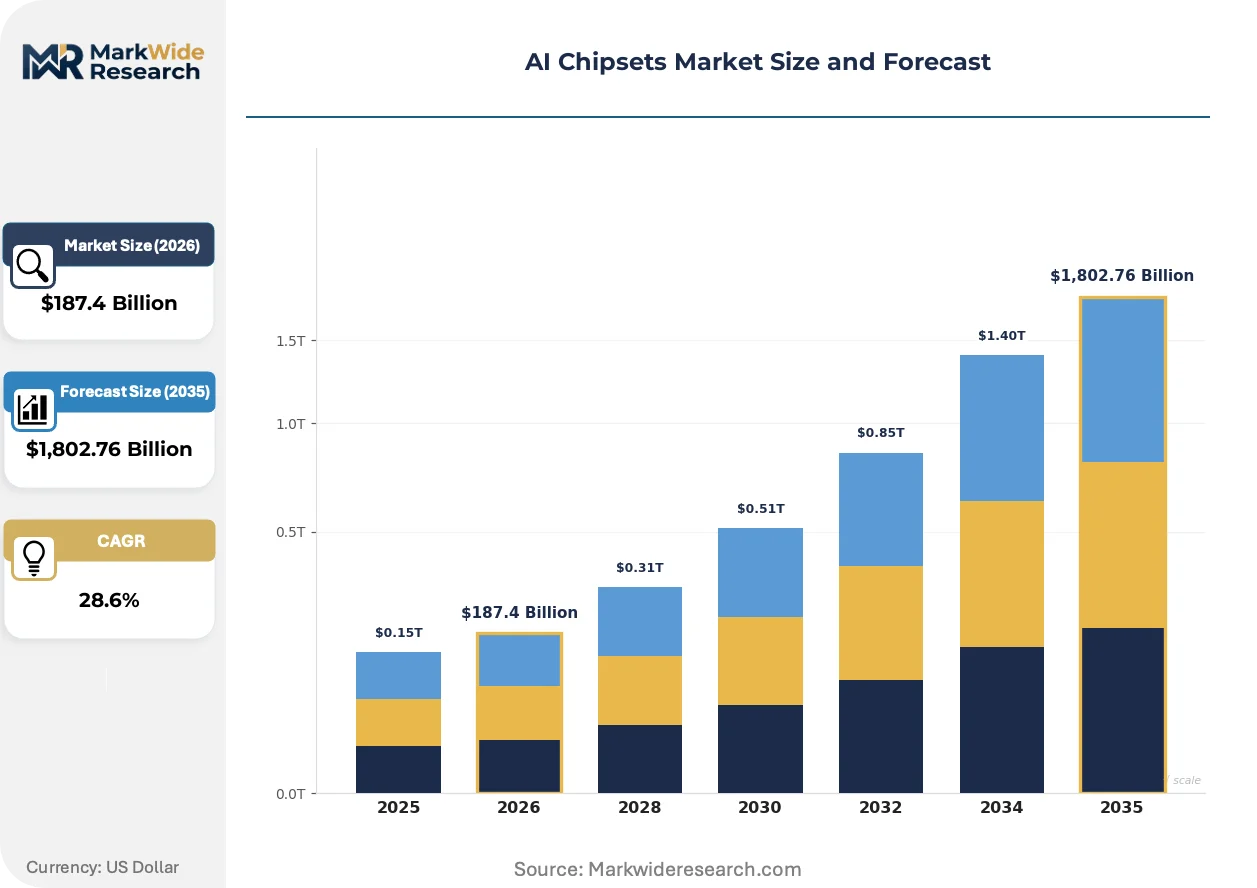
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $1,802.76 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FPGA, ASIC, GPU, DSP End User: Cloud Service Providers, Automotive Manufacturers, Consumer Electronics, Data Centers Technology: Deep Learning, Machine Learning, Neural Networks, Computer Vision Application: Natural Language Processing, Robotics, Image Recognition, Predictive Analytics |
| Companies Covered | NVIDIA Corporation, Advanced Micro Devices (AMD), Intel Corporation, Alphabet (Google), Taiwan Semiconductor Manufacturing Company (TSMC), Samsung Electronics, Qualcomm Technologies, Micron Technology, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Chipsets Market Emerging Trajectories
Silicon architecture is fragmenting into specialized compute engines as general-purpose GPUs face power-efficiency limits, while regulatory jurisdictions impose divergent compliance requirements on hardware provenance and deployment transparency.
Chiplet-based disaggregation is collapsing the monolithic die paradigm for AI accelerators. AMD and Intel are shipping multi-tile products with active interposers, while NVIDIA's Blackwell generation adopts multi-reticle designs. Hyperscalers now specify chiplet interfaces in procurement requirements, compressing time-to-market for custom silicon programs by decoupling memory, logic, and I/O development timelines.
The EU AI Act's conformity assessment framework is mandating hardware-level audit trails for high-risk AI systems. CE marking requirements now extend to training infrastructure documentation, forcing foundry customers to maintain wafer-level provenance records. European cloud providers are qualifying chips based on supply chain transparency scores, not solely performance-per-watt metrics.
Hyperscalers are consolidating silicon procurement around vertically integrated stack requirements. Buyers now specify software-hardware co-optimization, compiler maturity, and multi-generational roadmap alignment as table stakes, displacing point-product benchmarking. This behavioral shift concentrates design wins among vendors with full-stack capabilities, most visible in North American cloud provider RFP structures.
AI Chipsets Market Segmentation
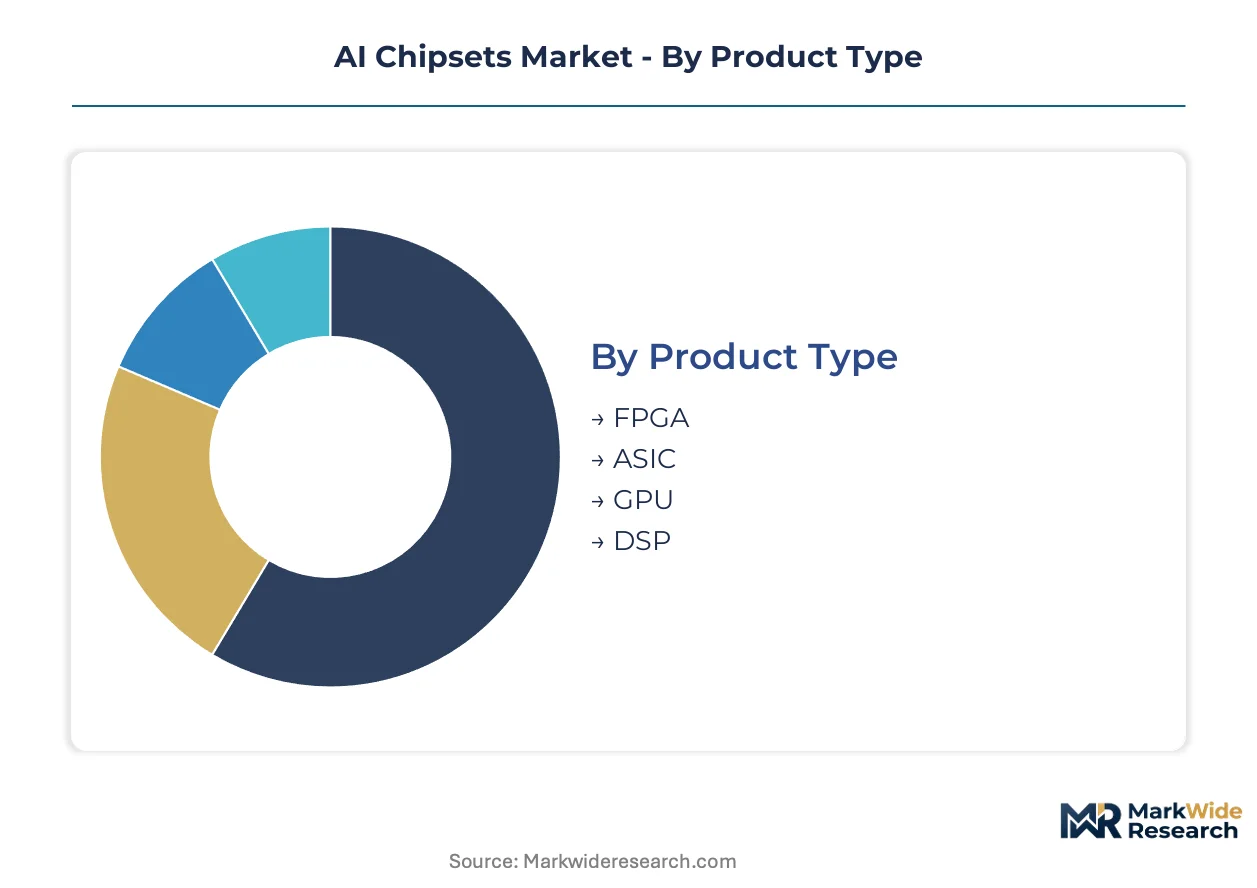
AI chipset procurement varies sharply by deployment context, with hyperscalers prioritizing training throughput while edge applications optimize for thermal constraints and unit economics. Segmentation reveals how architectural choices map to divergent customer qualification pathways and foundry capacity allocation priorities.
Product Type:
After-sales service intensity escalates with silicon complexity, as GPU deployments demand sustained driver optimization and ASIC programs require dedicated field application engineering for workload tuning.
- GPU:Programmable parallel processors built on sub-5nm nodes with HBM integration dominate training workloads. Cloud service providers in the United States and Taiwan absorb the majority of leading-edge wafer starts, constrained by TSMC CoWoS packaging allocation and NVIDIA's full-stack software moat.
- ASIC:Purpose-built matrix multiplication engines sacrifice flexibility for power efficiency in inference-at-scale. Google, Amazon, and Microsoft deploy custom silicon through internal design teams, qualifying secondary foundries outside Taiwan to mitigate concentration risk.
- FPGA:Reconfigurable logic arrays from Xilinx and Intel enable rapid prototyping for computer vision and signal processing applications where volume economics prohibit mask costs.
- DSP:Digital signal processors with fixed-function vector units serve audio processing and telecommunications infrastructure with mature software toolchains and lower NRE barriers.
By volume, GPU leads. By growth pace, ASIC is ahead.
End User:
Cost tier stratification separates qualification requirements, with cloud hyperscalers commanding dedicated foundry capacity and automotive buyers accepting longer lead times for safety-certified silicon.
- Cloud Service Providers:Microsoft, Amazon, Google, and Meta procure AI accelerators through multi-year capex cycles with pre-paid capacity reservations. These buyers specify chiplet interfaces and compiler maturity as procurement criteria, consolidating design wins among full-stack vendors.
- Data Centers:Enterprise and colocation facilities deploy inference-optimized silicon for private AI workloads, with European buyers prioritizing EU AI Act hardware provenance documentation over raw performance metrics.
- Automotive Manufacturers:Tesla, BMW, and Toyota integrate AI chipsets for autonomous driving and cabin monitoring, subject to ISO 26262 functional safety certification and AEC-Q100 automotive qualification.
- Consumer Electronics:Smartphone and PC OEMs embed neural processing units for on-device inference, with Apple and Samsung capturing value through vertical silicon design.
Cloud service providers command the largest wafer allocation. Automotive applications are expanding most quickly.
Technology:
Application maturity determines software ecosystem depth, with deep learning frameworks enjoying broad optimization while computer vision toolchains remain fragmented across verticals.
- Deep Learning:Multi-layer neural network training and inference drives demand for matrix multiplication density and high-bandwidth memory integration. Transformer architectures for large language models concentrate procurement among NVIDIA and custom ASIC programs at Google.
- Machine Learning:Traditional statistical methods and gradient-boosted decision trees run on commodity hardware with lower precision requirements, serving fraud detection and recommendation systems.
- Neural Networks:Biologically-inspired architectures with spiking or recurrent topologies target neuromorphic computing research and low-power edge applications.
- Computer Vision:Convolutional and vision transformer architectures process image and video streams for industrial inspection, medical imaging, and autonomous navigation.
Deep learning absorbs the majority of training-class silicon. Computer vision is gaining share fastest in edge deployments.
Application:
Customer type fragmentation separates buyers by latency tolerance, with natural language processing demanding synchronous response and predictive analytics accepting batch processing.
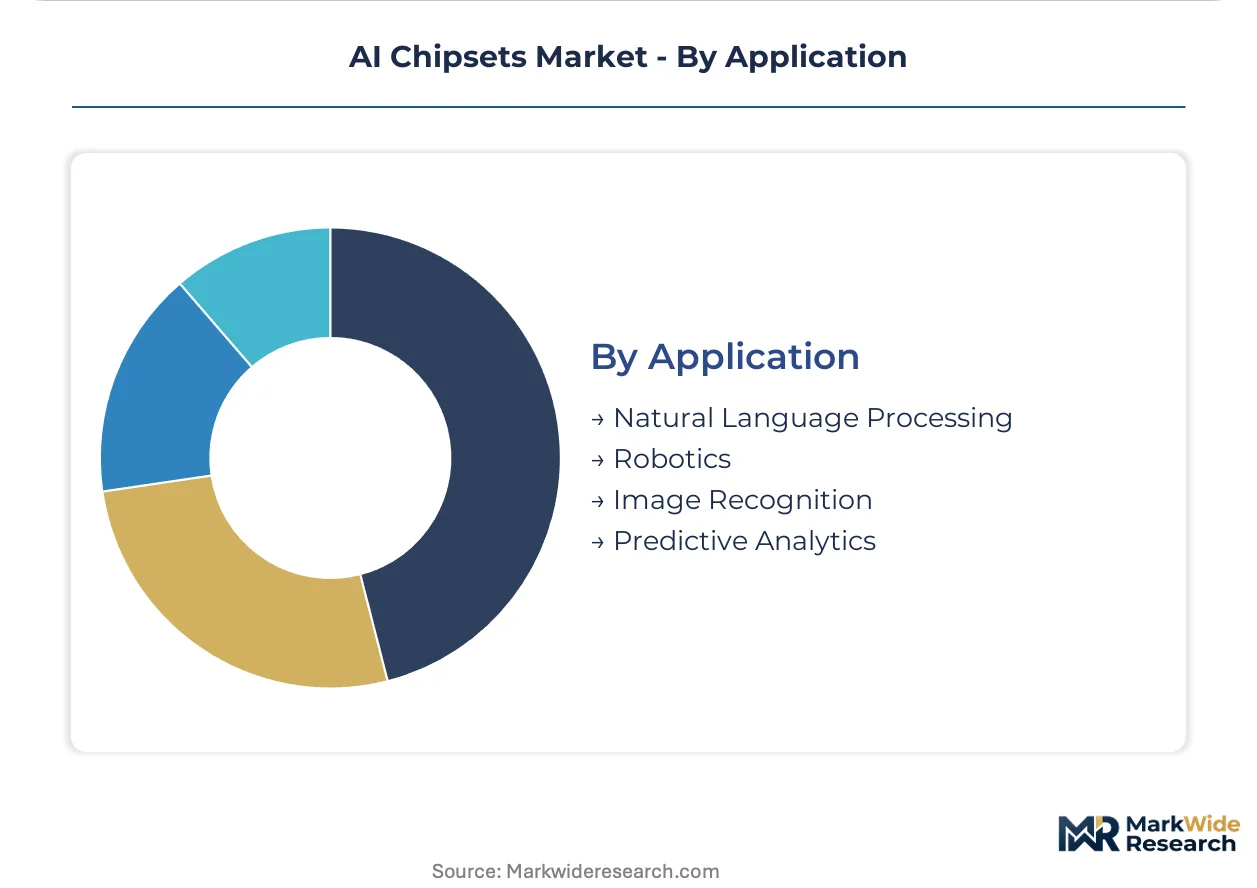
- Natural Language Processing:Large language model inference and fine-tuning consumes the highest memory bandwidth per watt, driving HBM3E adoption and multi-reticle chiplet designs. OpenAI, Anthropic, and enterprise API providers scale deployment through cloud infrastructure.
- Image Recognition:Facial authentication, quality inspection, and medical diagnosis deploy CNN and ViT accelerators with INT8 quantization for power-constrained environments.
- Robotics:Real-time control and sensor fusion for industrial automation and humanoid platforms requires deterministic latency and functional safety certification.
- Predictive Analytics:Time-series forecasting and anomaly detection in financial services and manufacturing runs on commodity GPUs with mature CUDA toolchains.
Natural language processing commands premium pricing. Robotics shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Bureau of Industry and Security anchors the dominant geography through export control architecture that fragments procurement patterns across jurisdictions. Taiwan concentrates foundry capacity for advanced accelerators. Germany and South Korea operate as secondary supply nodes with packaging and memory specialization.
United States
Cloud hyperscalers Microsoft, Amazon, and Google drive domestic absorption of training-class silicon through multi-year infrastructure commitments. The Department of Commerce's Bureau of Industry and Security maintains performance density thresholds restricting advanced AI chip shipments to China. Austin and Phoenix host expanding packaging facilities as Intel pursues foundry ambitions with U.S.-based manufacturing investments.
Taiwan
TSMC controls leading-edge CoWoS packaging capacity, creating structural dependency for AI accelerator supply chains worldwide. The National Science and Technology Council coordinates domestic semiconductor policy amid geopolitical pressure to diversify geographic risk. Hsinchu Science Park anchors advanced node development with 3nm and impending 2nm process ramps.
China
Domestic substitution mandates from MIIT accelerate parallel supply chain development outside Western technology ecosystems. SAMR standard-setting and GB compliance frameworks impose localization requirements on high-stakes AI deployments. Shanghai and Beijing clusters concentrate design house activity for inference-optimized architectures subject to export control limitations.
South Korea
SK Hynix and Samsung Electronics control HBM3E output, creating input bottlenecks for advanced accelerators regardless of logic wafer availability. The Ministry of Trade, Industry and Energy oversees semiconductor competitiveness programs targeting advanced packaging capabilities. Pyeongtaek and Yongin host memory fabrication complexes with dedicated HBM capacity expansion.
Germany
Automotive manufacturers BMW and Volkswagen integrate AI chipsets for autonomous driving systems subject to EU AI Act conformity requirements. The KBA and EU AI Act risk-based classification framework mandate auditable supply chains for high-risk AI deployments. Dresden and Munich concentrate semiconductor manufacturing with Infineon and expanding foundry investments.
AI Chipsets Market Vendor Landscape
Fabless designers and integrated device manufacturers split the market along capability specialization lines. The vendor base concentrates around full-stack software-hardware integration and captive foundry capacity. Dominant archetypes include vertically integrated platform vendors, memory-integrated logic suppliers, and custom silicon deployers. Competitive moves center on multi-year capacity reservations and compiler ecosystem maturity investments.
Within the vertically integrated platform tier, NVIDIA Corporation exemplifies software-hardware co-design dominance, while Intel Corporation anchors U.S.-based manufacturing ambitions through foundry expansion. Taiwan Semiconductor Manufacturing Company occupies a position as the critical foundry intermediary whose CoWoS packaging allocation shapes customer qualification timelines across the industry.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Advanced Micro Devices (AMD) |
| Intel Corporation |
| Alphabet (Google) |
| Taiwan Semiconductor Manufacturing Company (TSMC) |
| Samsung Electronics |
| Qualcomm Technologies |
| Micron Technology |
| Huawei Technologies |
| Others |
Supply Flow & Price Mechanics
Taiwan's chokehold on CoWoS advanced packaging capacity concentrates margin capture upstream while downstream AI accelerator vendors absorb cost pass-throughs through multi-year capacity reservations. NVIDIA's full-stack software moat enables value-based pricing for training-class GPUs, whereas inference-optimized ASICs compete on power-efficiency metrics that compress unit economics.
Pricing Analysis
Geographic price spreads separate North American cloud hyperscaler contracts from European enterprise procurement governed by EU AI Act hardware provenance documentation. Three-tier pricing structure across premium training GPUs, standard inference accelerators, and economy edge ASICs reflects certification grade and after-sales service bundling. Cost compression in mid-tier inference silicon is intensifying because Google, Amazon, and Microsoft are bringing custom ASIC programs in-house. Cloud service providers exhibit lowest price sensitivity due to captive demand, while automotive manufacturers face stringent margin pressure from ISO 26262 certification costs.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk architecture through BIS export control enforcement on advanced logic and HBM shipments. Taiwan, South Korea, and the United States anchor geographic supply concentration for leading-edge wafer fabrication, high-bandwidth memory output, and advanced packaging capacity. Raw material dependencies rest on neon gas from Ukraine, fluorspar from Mexico, and high-purity silicon from Germany. Single-source vulnerability concentrates in TSMC's CoWoS packaging lines. Distribution runs through direct foundry relationships with pre-paid capacity reservations rather than merchant channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI chipsets sit in an early-cycle expansion phase as transformer architecture adoption pulls training infrastructure investment forward through multi-year hyperscaler capex commitments. Cloud service providers are consolidating procurement around vertically integrated stack requirements that favor full-stack vendors with compiler maturity and multi-generational roadmaps.
For Market Incumbents: Harden foundry capacity lock-in through pre-paid CoWoS reservations at TSMC and secondary qualification at Samsung's 3nm GAA lines. Invest in software-hardware co-optimization to defend against emerging ASIC programs at hyperscalers. Prioritize EU AI Act hardware provenance documentation to capture European cloud provider demand that weights traceability over raw performance metrics.
For New Entrants and Emerging Players: Pursue edge inference ASIC opportunities in autonomous vehicles and industrial vision systems where latency constraints and thermal budgets create white-space outside data center concentration. Target India's semiconductor PLI scheme for domestic design center establishment in Bangalore and Hyderabad. Lead with deterministic latency guarantees and functional safety certification as the go-to-market angle against GPU incumbents.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fabless AI accelerator startups that have taped out 3nm designs but lack hyperscaler qualification. Long-term viability favors companies with secured foundry capacity and compiler ecosystem investments over point-product silicon plays. Watch BIS export control threshold adjustments as the signal for geographic market segmentation shifts that would redirect capital toward architecture modifications for excluded markets.
| Strategic Initiative | Industry Significance |
|---|---|
| CoWoS Capacity Reservation | TSMC packaging allocation locks in supply-side leverage for training-class GPU vendors. |
| Custom ASIC Program Launch | Google TPU and Amazon Trainium displace merchant silicon through in-house design teams. |
| EU AI Act Compliance Investment | CE marking and wafer-level provenance records qualify European cloud provider procurement. |
| Secondary Foundry Qualification | Samsung 3nm GAA and Intel 18A reduce Taiwan concentration risk for AI accelerator customers. |
| Photonic Interconnect Development | Co-packaged optics with electronic chiplets enable bandwidth density beyond electrical I/O limits. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cloud hyperscaler silicon procurement directors, foundry customer management executives, fabless AI accelerator CTOs, automotive Tier 1 semiconductor buyers, and EDA tool product managers. Secondary validation drew from SEC 10-K filings, TSMC investor day disclosures, hyperscaler capex reporting, BIS export control rulemaking dockets, and EU AI Act implementing regulation texts. Bottom-up wafer start estimates and top-down cloud infrastructure spending trajectories were triangulated to anchor volume and value outputs.
Calibration against historical hyperscaler GPU deployment cycles and foundry capacity utilization rates informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, end-use deployment context, process technology node, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and supply-constrained shipment ceilings. Industry-specific forecast inputs incorporated CoWoS packaging capacity expansion timelines and HBM3E yield ramp trajectories.
Sensitivities concentrate around BIS export control threshold adjustments, TSMC advanced packaging allocation rebalancing, and EU AI Act hardware provenance enforcement intensity. Forecasts reflect assumptions about foundry yield maturation at 2nm nodes and hyperscaler capex commitment durability. Macroeconomic contraction, geopolitical escalation, or breakthrough neuromorphic architecture displacement would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Europe MPU Market
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Global Battery Management IC Market
Chipset and Processors
Global Digital Light Processing Chipset Market
Chipset and Processors
Connecting Chiplets Market
Chipset and Processors
Japan Microprocessor (MPU) Market
Chipset and Processors
Global Merchant Embedded Computing Market
Chipset and Processors
Poe Chipsets Market
Chipset and Processors
Europe Neuromorphic Chip Market
Chipset and Processors
Optical Microcontrollers Market
Chipset and Processors
Power Over Ethernet (Poe) Chipsets Market
Chipset and Processors
China Microprocessor (MPU) Market
Chipset and Processors
G Fast Chipset Market
Chipset and Processors
Server Microprocessor Market
Chipset and Processors
Global Neural Processors Market
Chipset and Processors
Power Architecture Market