
 Airbag Chip Market | 2026-2036
Airbag Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Airbag Chip Market Insights
Multi-source procurement is consolidating across Tier-1 airbag system suppliers as OEMs seek redundant semiconductor supply chains. Robert Bosch leverages captive foundry partnerships to secure MEMS sensor die capacity for integrated airbag modules. Autoliv anchors North American deployment volumes through long-term supply agreements with domestic vehicle assemblers. Infineon Technologies competes on silicon-germanium process leadership for high-g-force accelerometer chips.
An airbag chip is a purpose-built integrated circuit that processes collision sensor data and triggers pyrotechnic inflator deployment within milliseconds, typically fabricated on automotive-grade CMOS or BCD processes rated from negative forty to one hundred fifty degrees Celsius. Analog chips dominate unit shipments for front-impact systems where continuous voltage signal conditioning from capacitive accelerometers remains the baseline architecture. Digital chips are capturing share in side-curtain and knee-bag applications where multi-axis sensor fusion demands faster arithmetic throughput. FPGA-based prototyping platforms are accelerating validation cycles for OEMs developing zonal safety architectures before committing to ASIC tape-outs.
NHTSA Federal Motor Vehicle Safety Standard 208 and UN ECE R94 govern minimum occupant protection thresholds, compelling chip vendors to certify devices under AEC-Q100 Grade 0 stress-test protocols. The EPA and California Air Resource Board impose material restrictions on inflator propellant chemistry, indirectly constraining chip-inflator interface designs. Stakeholders must monitor how NHTSA proposed updates to side-pole crash requirements will recalibrate sensor threshold algorithms and trigger new qualification cycles for mixed-signal architectures.
Market Dynamics
The airbag chip market is experiencing structural pressure from zonal safety architectures that consolidate sensor processing into domain controllers, compressing discrete chip volumes while demanding higher arithmetic density per unit.
Growth Catalysts
- UN ECE R94 mandates:European crash-test protocols now require multi-point sensor calibration for side-impact scenarios, forcing automakers to deploy additional accelerometer channels per vehicle platform.
- Multi-channel airbag standardization:Passenger vehicle OEMs in China and Germany are expanding knee-bag and center-curtain deployments as baseline equipment rather than optional trims.
- Silicon-germanium process migration:Advanced BCD-on-SiGe fabrication is enabling single-die integration of high-g accelerometers with digital signal paths, reducing module part counts.
Market Restraints
- 300mm wafer capacity concentration:Automotive-grade MEMS foundry capacity clusters in Taiwan and South Korea, creating single-source vulnerability for MEMS sensor die.
- Propellant chemistry restrictions:EPA and California Air Resource Board material constraints on azide-free inflator formulations complicate chip-inflator interface standardization.
- AEC-Q100 Grade 0 qualification timelines:Extended stress-test protocols for negative-forty to one-hundred-fifty-degree Celsius operation add eighteen-to-twenty-four months to new product introduction cycles.
Strategic Opportunities
- India vehicle safety mandate phase-in:Bharat NCAP adoption and proposed airbag minimums for all passenger vehicle categories create greenfield demand for cost-optimized analog architectures.
- Zonal controller convergence:Integration of airbag logic into broader vehicle safety domains permits chip vendors to bundle collision processing with ADAS sensor fusion on shared compute substrates.
- FPGA-to-ASIC transition services:Prototyping platforms are compressing OEM validation cycles, allowing semiconductor houses to capture value through early design-in partnerships before volume production commitments.
Industry Challenges
- Mixed-signal verification expertise scarcity:The intersection of high-voltage pyrotechnic drive circuits and sub-micron digital logic requires specialized talent pools concentrated in Munich, Detroit, and Tokyo engineering clusters.
- Legacy vehicle platform retrofit complexity:Older electrical architectures lack the data bandwidth and power conditioning to support digital airbag module upgrades, fragmenting product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airbag Chip Market |
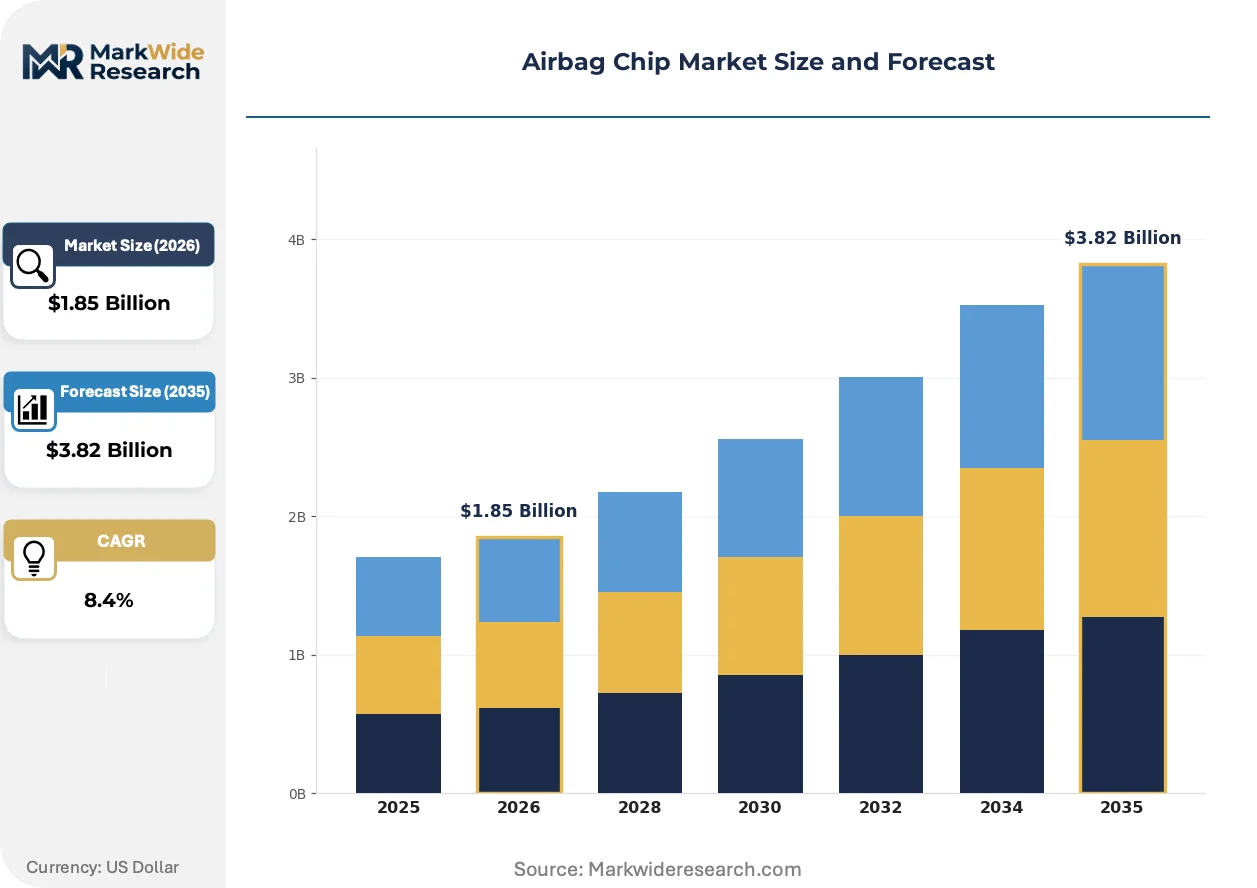
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Chips, Digital Chips, Hybrid Chips, ASIC Technology: Microcontroller, MEMS Sensors, RF Systems, FPGA End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, All-Terrain Vehicles |
| Companies Covered | Robert Bosch, Autoliv, Continental AG, NXP Semiconductors, Infineon Technologies, Denso Corporation, ST Microelectronics, ZF Friedrichshafen AG, Joyson Safety Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airbag Chip Market Trends and Innovations
Functional consolidation and edge-compute migration are redefining how collision data is processed, with implications for chip architecture, supplier margins, and OEM sourcing strategies.
Time-of-flight proximity sensing is electrifying occupant classification systems by enabling real-time position tracking without mechanical pressure mats. German luxury automakers are adopting these optical modules for adaptive airbag deployment profiles. The technology is electrifying the traditional weight-sensor supply chain and compressing module assembly steps.
NHTSA proposed updates to Federal Motor Vehicle Safety Standard 214 side-pole crash requirements are recalibrating lateral-impact detection thresholds. These revisions will force accelerometer vendors to widen dynamic range specifications and validate new trigger algorithms. Side-curtain and far-side protection modules face the steepest requalification burdens under the pending rulemaking.
Long-term supply agreements with domestic vehicle assemblers are displacing spot-market purchasing for critical safety semiconductors. North American Tier-1 suppliers are locking in three-to-five-year die capacity reservations directly with foundry partners. This pattern is most pronounced in Detroit-area sourcing offices managing pickup truck and SUV platform volumes.
Airbag Chip Market Segmentation
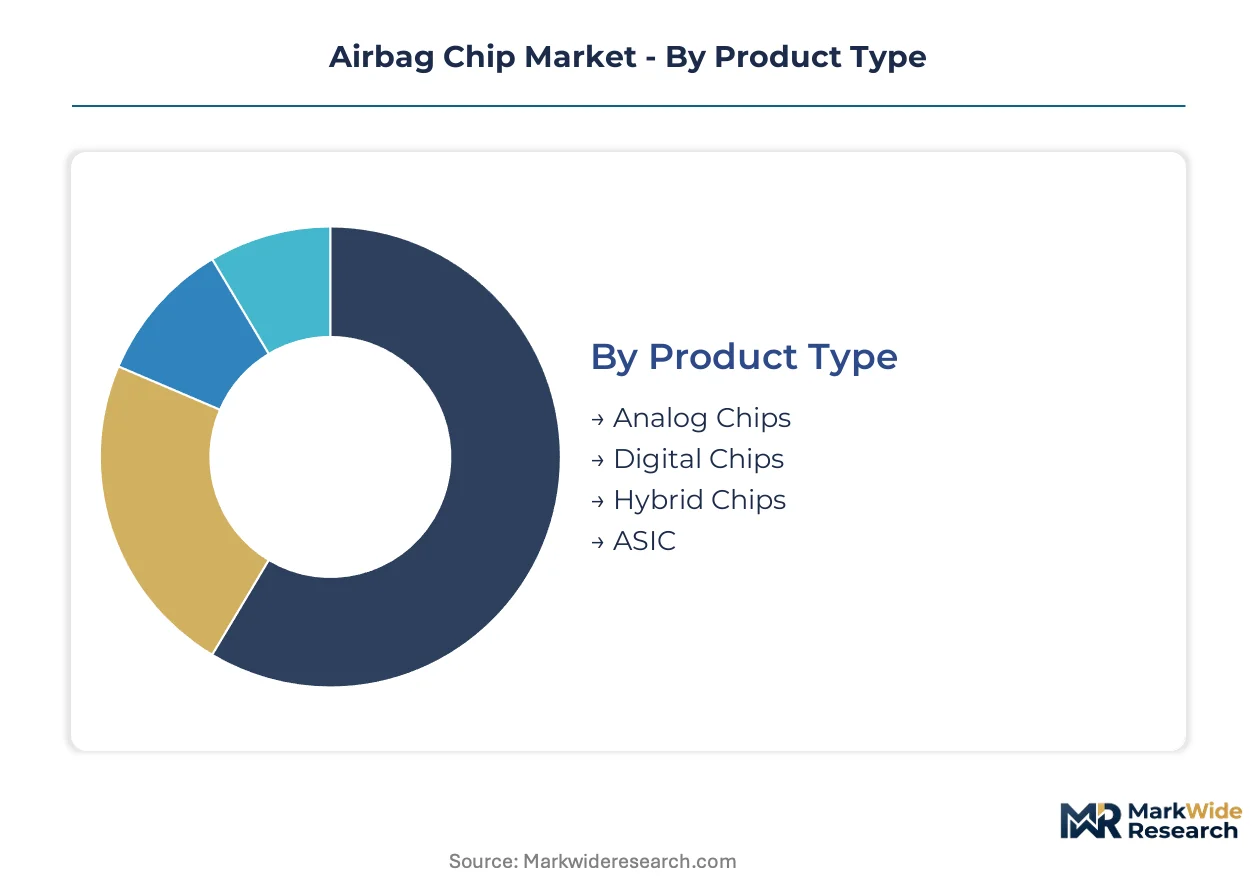
Airbag chip architectures diverge sharply across signal processing paradigms, fabrication nodes, and vehicle electrical topologies. Procurement patterns cluster around discrete analog solutions for legacy platforms while digital integration accelerates in zonal safety domains.
Product Type:
Process geometry and signal fidelity requirements partition the component landscape into distinct qualification tiers.
- Analog Chips:Continuous voltage signal conditioning circuits fabricated on BCD processes handle capacitive accelerometer outputs for front-impact systems. Passenger vehicle OEMs in Germany specify these for baseline driver and passenger deployments where millisecond latency tolerances remain forgiving.
- Digital Chips:ARM Cortex-M based architectures with dedicated DSP blocks execute multi-axis sensor fusion algorithms for side-curtain and knee-bag modules. Tier-1 suppliers in the United States are consolidating procurement around these devices as NHTSA side-pole crash requirements tighten detection thresholds.
- Hybrid Chips:Mixed-signal integration combining precision analog front-ends with programmable digital cores.
- ASIC:Full-custom tape-outs for high-volume platform commitments with frozen specifications.
Mature deployment sits with Analog Chips. Newer deployment is concentrated in Digital Chips.
Technology:
Sensor integration density and computational throughput define competitive positioning across the technology stack.
- Microcontroller:Automotive-grade 32-bit cores with lockstep execution and ECC memory serve as the primary decision engine for pyrotechnic firing circuits. Foundry capacity for these devices concentrates in Taiwan and South Korea, creating qualification bottlenecks for new entrants.
- MEMS Sensors:Surface-micromachined accelerometers with capacitive transduction achieve high-g measurement ranges up to 500g for crash detection. Bosch and STMicroelectronics dominate wafer supply for these elements, with captive fabs securing capacity for integrated airbag modules.
- RF Systems:Wireless triggering architectures for steerable column and seat-mounted bags.
- FPGA:Prototyping platforms for algorithm validation before ASIC commitment.
Volume concentration rests with Microcontroller. Technology leadership is migrating toward MEMS Sensors.
End User:
Supply chain position determines specification authority and volume aggregation scale.
- OEMs:Vehicle manufacturers with captive semiconductor engineering teams define system-level requirements and qualify alternative sources. German luxury automakers maintain direct relationships with foundry partners for MEMS die capacity.
- Tier-1 Suppliers:Autoliv, ZF, and Joyson Safety Systems integrate chips into complete airbag modules and manage regulatory certification. These firms anchor North American procurement volumes through long-term supply agreements with domestic vehicle assemblers.
- Aftermarket Providers:Independent distributors serving collision repair and retrofit segments.
- Vehicle Assemblers:Contract manufacturers without full OEM status.
Procurement authority concentrates with Tier-1 Suppliers. Direct sourcing is expanding among OEMs.
Application:
Crash dynamics and occupant kinematics dictate sensor channel count and deployment force calibration.
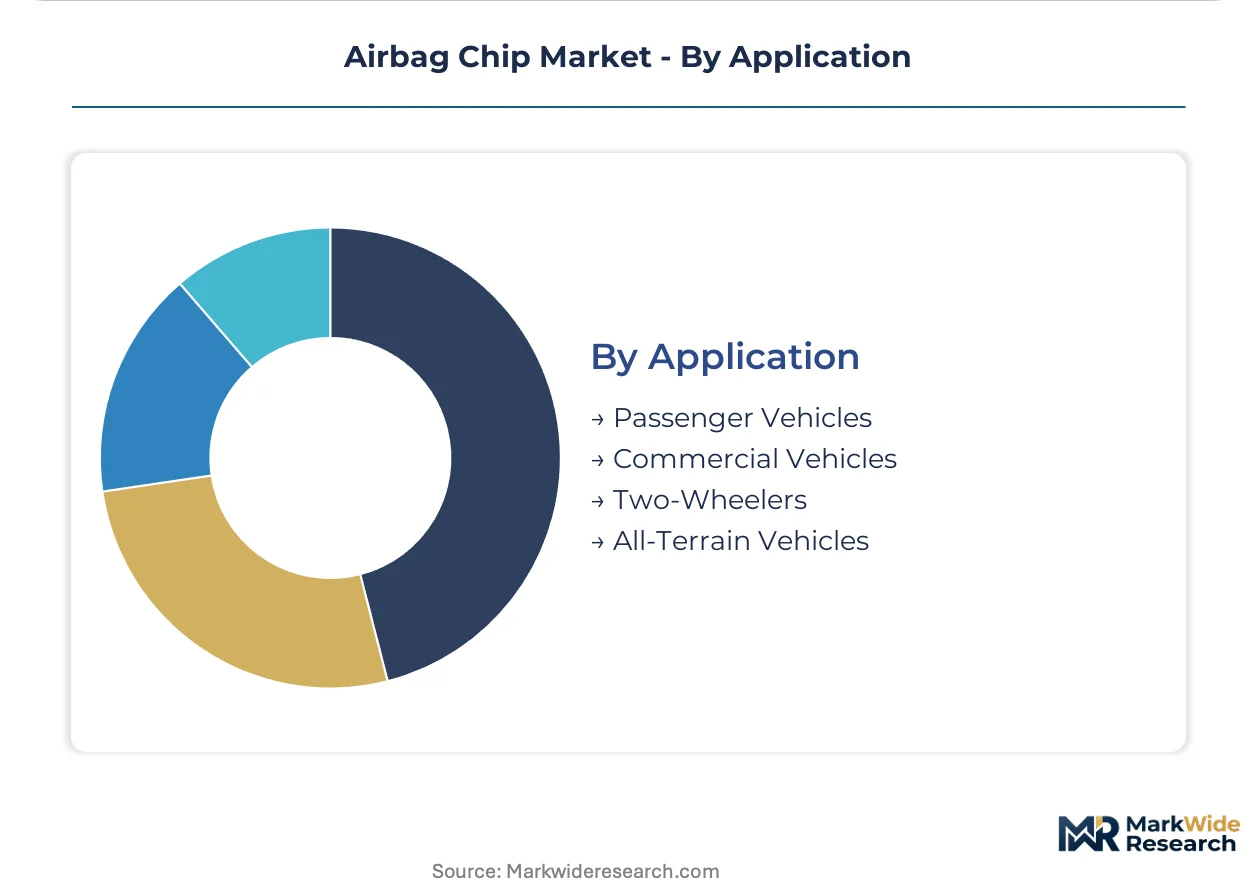
- Passenger Vehicles:Multi-channel configurations with ten or more deployment zones including far-side protection and center airbags. Chinese OEMs are standardizing knee-bag and curtain deployments across all trim levels as domestic safety regulations tighten.
- Commercial Vehicles:Heavy-duty trucks and buses require reinforced mounting structures and higher inflator output for occupant mass ranges up to 150kg. Fleet operators in the United States specify these systems for driver protection in cab-over-engine configurations.
- Two-Wheelers:Motorcycle airbag vests and jacket-integrated systems.
- All-Terrain Vehicles:Side-by-side and quad applications with rollover detection.
Unit volume leadership belongs to Passenger Vehicles. Regulatory momentum is building fastest in Commercial Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundry capacity in Taiwan and South Korea anchors semiconductor supply for airbag chip fabrication, while vehicle assembly concentration in China, Germany, and the United States shapes demand geography. Regulatory divergence across NHTSA, UN ECE, and Bharat NCAP frameworks is fragmenting certification requirements. Tier-1 suppliers are responding with regionalized sourcing offices and qualified alternative foundry relationships.
United States
Detroit-area pickup truck and SUV platforms consume the highest airbag chip volumes per vehicle, with NHTSA Federal Motor Vehicle Safety Standard 208 mandating multi-point sensor calibration for front-impact protection. Long-term supply agreements between Tier-1 suppliers and domestic vehicle assemblers now span three-to-five-year die capacity reservations directly with foundry partners. Michigan-based engineering clusters concentrate mixed-signal verification expertise for high-voltage pyrotechnic drive circuit design.
Germany
Luxury automakers in Stuttgart and Munich are standardizing knee-bag and center-curtain deployments as baseline equipment, with UN ECE R94 protocols requiring enhanced side-impact sensor thresholds. The KBA enforces type-approval compliance for imported semiconductor components used in safety-critical applications. Bavaria hosts captive foundry partnerships securing MEMS sensor die capacity for integrated airbag module production.
China
Domestic OEMs are expanding multi-channel airbag configurations across all passenger vehicle trim levels as vehicle safety regulations tighten, with the MIIT implementing GB standards for occupant protection systems. Shanghai and Yangtze River Delta manufacturing hubs concentrate foundry capacity for automotive-grade CMOS and BCD process fabrication. Local Tier-1 suppliers are qualifying domestic semiconductor sources to reduce import dependency for safety-critical chips.
India
Bharat NCAP adoption and proposed airbag minimums for all passenger vehicle categories are creating greenfield demand for cost-optimized analog architectures, with the Ministry of Road Transport and Highways accelerating mandate phase-in timelines. Maharashtra and Tamil Nadu vehicle assembly corridors are attracting Tier-1 supplier investments in localized module production. The PLI scheme for automotive components is incentivizing domestic chip packaging and testing capabilities.
Japan
Keiretsu-affiliated suppliers maintain integrated development relationships with domestic automakers for zonal safety architectures, with METI coordinating standards alignment for vehicle-to-infrastructure safety communication. Nagoya and Tokyo engineering clusters specialize in ARM Cortex-M based digital architectures for multi-axis sensor fusion. Domestic foundry capacity concentrates on high-reliability processes for negative-forty to one-hundred-fifty-degree Celsius operation.
Airbag Chip Market Competitive Landscape
Global majors compete with regional champions across MEMS fabrication and microcontroller integration, with captive foundry relationships distinguishing integrated system suppliers from fabless competitors. The vendor base separates into three tiers: semiconductor houses with automotive-grade process leadership, Tier-1 module integrators with direct OEM relationships, and specialized MEMS foundries with high-g accelerometer expertise. Dominant competitive moves include long-term die capacity reservations with foundry partners and FPGA-to-ASIC transition services that compress OEM validation cycles.
Within the integrated module supplier tier, Robert Bosch, Autoliv, and Infineon Technologies occupy positions defined by their proximity to foundry capacity and OEM specification authority. Bosch exemplifies the captive fabrication archetype through MEMS sensor die production for complete airbag systems. Autoliv represents the North American volume aggregation model with supply agreements anchored to Detroit-area platform commitments. Infineon Technologies sits within the silicon-germanium process leadership segment, supplying high-g-force accelerometer chips to Tier-1 module manufacturers across multiple geographies.
| Leading Market Players |
|---|
| Robert Bosch |
| Autoliv |
| Continental AG |
| NXP Semiconductors |
| Infineon Technologies |
| Denso Corporation |
| ST Microelectronics |
| ZF Friedrichshafen AG |
| Joyson Safety Systems |
| Others |
Pricing and Supply Chain Analysis
Mixed-signal verification engineers concentrated in Munich, Detroit, and Tokyo command premium compensation that propagates through three-tier pricing spreads separating AEC-Q100 Grade 0 certified modules from commercial-grade alternatives. Labor-cost differentials between these engineering clusters and emerging design centers in India widen the premium-economy gap for airbag chip procurement.
Pricing Analysis
Warranty and field-failure liability coverage bundle into long-term supply agreements for Tier-1 suppliers, while spot-market transactions carry unbundled service obligations. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 Grade 0 certified devices from industrial-grade and commercial-tier alternatives. Price differentiation hinges on MEMS sensor integration density and foundry process geometry. Pricing pressure stems from OEM consolidation of multi-channel airbag configurations into single-sourced module contracts. Aftermarket repair channels exhibit highest price sensitivity; luxury OEM direct sourcing shows lowest.
Supply Chain Analysis
Automotive-grade MEMS foundry talent pools in Taiwan and South Korea constrain capacity expansion timelines for 300mm wafer production. Silicon wafers, high-purity propellant chemicals, and automotive-grade ceramic packaging substrates anchor bill-of-materials costs. Single-source vulnerability concentrates in Taiwan foundry clusters serving Bosch and STMicroelectronics captive production. Distribution runs through Tier-1 module integrators with direct OEM qualification relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The airbag chip market sits in a technology-transition phase where digital sensor fusion architectures displace legacy analog front-end dominance. ARM Cortex-M based processing cores with dedicated DSP blocks are capturing share from continuous voltage signal conditioning circuits.
For Market Incumbents: Lock in foundry capacity reservations through five-year die supply agreements before 300mm automotive MEMS capacity tightens further. Deepen backward integration into MEMS sensor fabrication to offset fabless competitor pricing pressure. Prioritize AEC-Q100 Grade 0 qualification pipeline investments as NHTSA side-pole crash requirements recalibrate detection thresholds.
For New Entrants and Emerging Players: Capture Bharat NCAP mandate phase-in demand with cost-optimized analog architectures for India's price-sensitive passenger vehicle market. Target commercial vehicle retrofit segments where legacy electrical architectures resist digital module upgrades. Pursue FPGA-to-ASIC transition service partnerships with domestic OEMs seeking compressed validation cycles.
For Investors and Strategic Acquirers: Re-rating potential sits with MEMS foundry specialists possessing high-g accelerometer expertise given silicon-germanium process migration catalysts. Five-to-ten year viability favors suppliers with captive fabrication and direct OEM specification authority. Monitor NHTSA Federal Motor Vehicle Safety Standard 214 final rulemaking as inflection indicator for lateral-impact sensor demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Foundry Capacity Reservation | Secures MEMS sensor die supply for integrated module production against Taiwan concentration risk. |
| Silicon-Germanium Process Migration | Enables Bosch and Infineon to consolidate accelerometer and digital signal paths on single die. |
| FPGA-to-ASIC Transition Services | Compresses OEM validation cycles for zonal safety architectures before volume production commitments. |
| Bharat NCAP Market Entry | Positions suppliers for India's greenfield airbag mandate phase-in across cost-optimized segments. |
| AEC-Q100 Grade 0 Certification Investment | Qualifies devices for negative-forty to one-hundred-fifty-degree Celsius operation under tightened UN ECE R94 protocols. |
Research Methodology
Document review covered NHTSA Federal Motor Vehicle Safety Standard filings, UN ECE R94 regulatory texts, AEC-Q100 stress-test protocols, and vehicle production databases, complemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, MEMS foundry operations managers, and automotive semiconductor sales executives. Secondary sources included SEC 10-K filings, customs trade records, and IHS Markit registration data. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Segment-level projections across analog, digital, hybrid, and ASIC architectures incorporated vehicle class, airbag channel count per platform, and regional regulatory cluster dimensions. CAGRs derived from regression analysis of historical penetration rates against mandate implementation timelines. Model inputs included foundry capacity utilization rates, AEC-Q100 qualification pipeline durations, and OEM platform lifecycle commitments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to 300mm wafer capacity allocation shifts and NHTSA rulemaking finalization. Projections reflect assumptions regarding UN ECE R94 harmonization progress and MEMS sensor integration adoption curves. Material deviation in foundry capex cycles or side-pole crash test protocol implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Edge Artificial Intelligence Chips Market
Chipset and Processors
Global Digital Light Processing Chipset Market
Chipset and Processors
AI Chipsets Market
Chipset and Processors
Auto Chip Market
Chipset and Processors
PC Processor Market
Chipset and Processors
Global Multimedia Chipsets Market
Chipset and Processors
Self-Learning Neuromorphic Chip Market
Chipset and Processors
Smartwatch Chips Market
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
Global Battery Management IC Market
Chipset and Processors
China Automotive Microcontroller Market
Chipset and Processors
Global Microcontroller (MCU) Market
Chipset and Processors
Global ASIC Miner Market
Chipset and Processors
Edge AI Chipset Market
Chipset and Processors
Chiplet Technology Market