
 Japan Data Center Processor Market | 2026-2036
Japan Data Center Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Data Center Processor Market Insights
Specialized semiconductor engineering talent is rotating toward AI accelerator design, tightening supply for legacy CPU architecture teams. NVIDIA Corporation leverages its CUDA software ecosystem to dominate AI training deployments across Japanese hyperscale facilities. Fujitsu Ltd. sustains domestic relevance through its Arm-based A64FX architecture, purpose-built for high-performance computing workloads at RIKEN and national laboratories. Advanced Micro Devices competes aggressively on core density and price-performance metrics in the x86 server segment.
Data center processors are integrated circuits engineered to execute computational workloads within centralized server environments, typically fabricated on advanced nodes with TDP ratings spanning 150W to 400W for high-performance units. These devices manage virtualization layers, distributed storage protocols, and parallel matrix operations essential to modern cloud infrastructure. GPU accelerators are capturing the fastest expansion trajectory as generative AI training clusters multiply across Japanese facilities. CPU architectures still anchor the installed base for general-purpose virtualization and transactional database workloads. FPGA deployments concentrate in low-latency financial services and telecommunications edge nodes where programmable logic outperforms fixed-function silicon.
METI efficiency mandates and JIS standards for data center power usage effectiveness are reshaping procurement criteria toward thermal design power optimization and liquid cooling compatibility. The Personal Information Protection Commission enforces data localization requirements that sustain domestic processor demand rather than offshore cloud substitution. Stakeholders must monitor how export control alignments between METI and allied semiconductor regimes affect supply security for leading-edge fabrication.
Market Dynamics
METI's green data center directives are compressing procurement timelines toward liquid-cooled, high-TDP silicon as domestic hyperscalers race to meet 2030 efficiency targets.
Growth Catalysts
- AI Training Cluster Expansion:Domestic cloud operators are procuring GPU accelerators at scale to serve generative model development, pulling silicon demand upward.
- METI Efficiency Mandates:Regulatory pressure on power usage effectiveness is forcing facility operators to prioritize processors with superior performance-per-watt metrics.
- Domestic Data Localization:The Personal Information Protection Commission's strict data sovereignty rules prevent offshore cloud substitution and sustain local processor deployment.
Market Restraints
- Leading-Edge Fabrication Concentration:Taiwan and South Korea dominate advanced node production, exposing Japanese buyers to geopolitical supply disruption.
- Specialized Talent Scarcity:Semiconductor engineering expertise is migrating toward AI accelerator design, leaving legacy CPU architecture teams understaffed.
- Advanced Packaging Cost Inflation:CoWoS and HBM integration requirements are driving unit economics toward hyperscaler-only affordability tiers.
Strategic Opportunities
- Fukuoka Edge Expansion:Submarine cable landings and lower land costs are positioning the Kyushu region as an alternative to Tokyo-Osaka concentration.
- Arm Architecture Penetration:Power-efficient designs are gaining traction in high-performance computing workloads where x86 dominance is weakening.
- Domestic Advanced Packaging Investment:METI subsidies for local substrate and interposer capacity are creating captive supply opportunities for domestic processor integrators.
Industry Challenges
- Legacy System Integration Friction:Mainframe-era transactional databases resist migration to modern virtualized environments, complicating processor refresh cycles.
- Export Control Alignment Complexity:METI coordination with allied semiconductor regimes on equipment licensing creates procurement uncertainty for leading-edge nodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Data Center Processor Market |
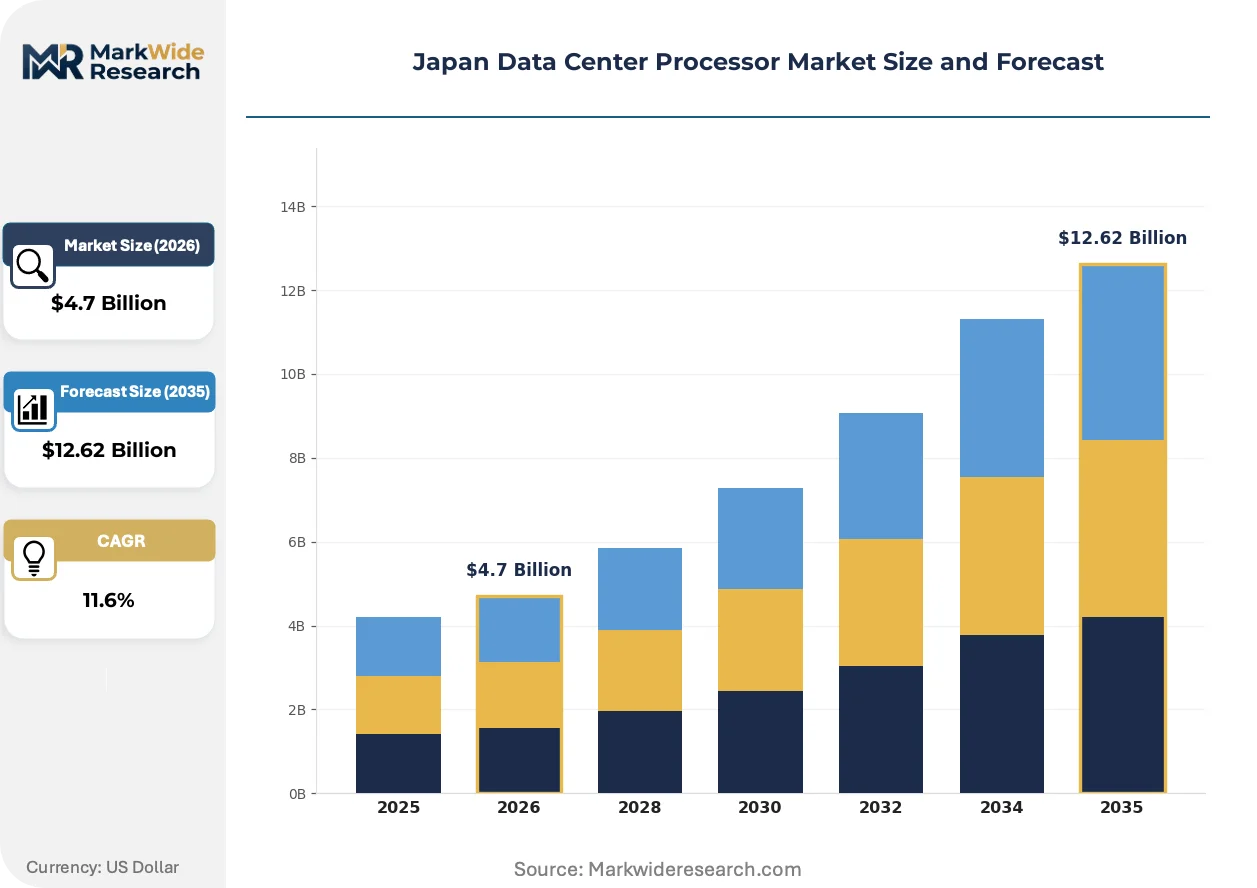
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.62 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CPU, GPU, FPGA, ASIC Application: Cloud Computing, Big Data Analytics, AI Processing, Virtualization End User: IT Services, Telecommunication, E-Commerce, Gaming Deployment Model: On-Premises, Hybrid Cloud, Private Cloud, Public Cloud |
| Companies Covered | Intel Corporation, Advanced Micro Devices, NVIDIA Corporation, Ampere Computing, ARM Holdings, Fujitsu Ltd., IBM Corporation, Qualcomm, Amazon Web Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Data Center Processor Market Trends and Innovations
Silicon architecture specialization is fragmenting procurement portfolios as workload-specific accelerators outperform general-purpose designs. Japanese facilities are at the forefront of this compute disaggregation.
GPU-based AI accelerators are supplanting CPU-centric training clusters in domestic hyperscale deployments. RIKEN and national laboratory procurement is shifting toward massive parallel matrix operation engines. This architectural pivot is compressing demand for legacy x86 sockets in high-performance computing segments.
METI's green data center standards are mandating liquid cooling compatibility and thermal design power optimization across new facility certifications. Processor vendors must now qualify products against JIS power usage effectiveness benchmarks before hyperscaler consideration. Domestic operators are responding by specifying immersion-ready socket designs in procurement tenders.
Hyperscale buyers are consolidating supplier relationships around vertically integrated silicon vendors who control both chip design and software ecosystems. Traditional value-added resellers and distributor intermediaries are losing share to direct manufacturer contracts. Tokyo-based cloud operators are pioneering this procurement rationalization, with Osaka facilities following rapidly.
Japan Data Center Processor Market Segmentation
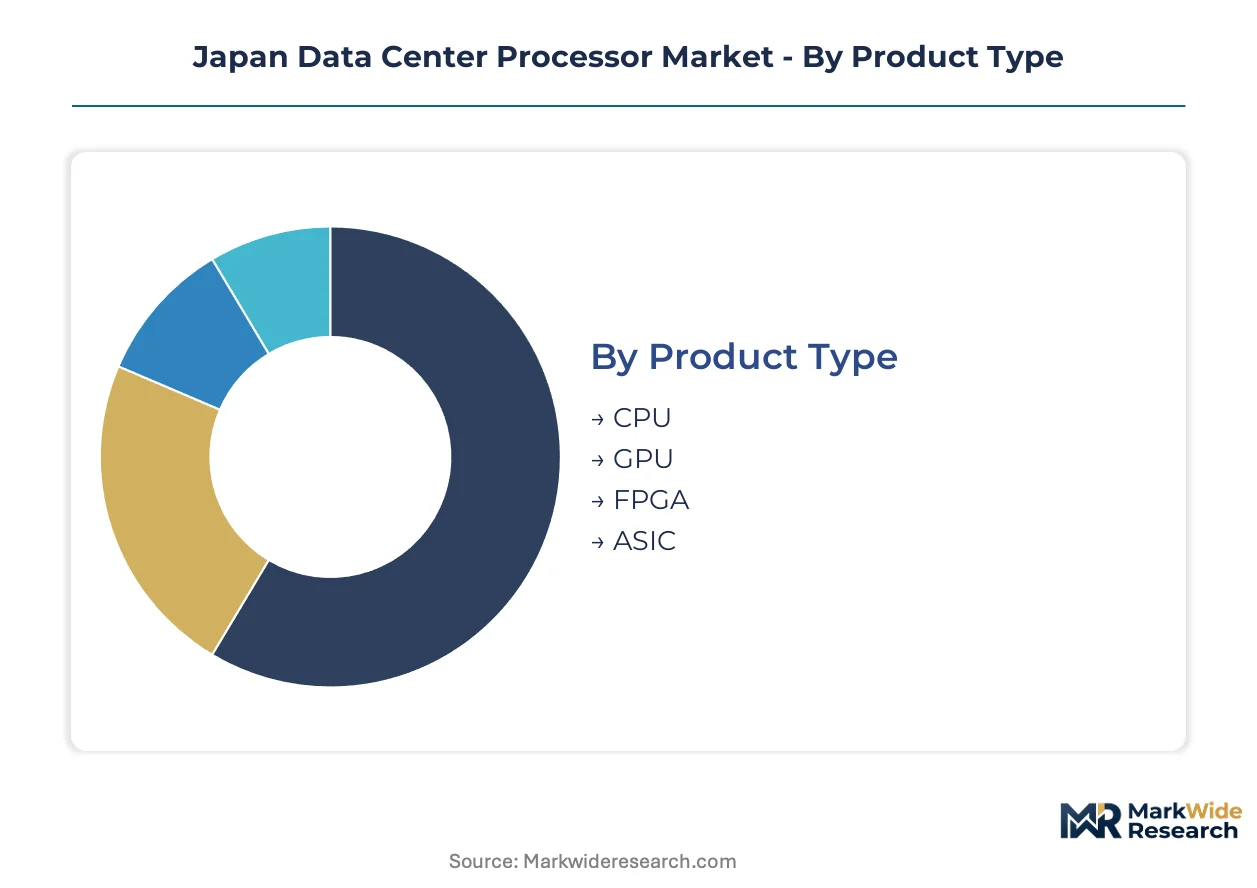
Processor procurement patterns in Japanese data centers diverge sharply across workload types, with hyperscale cloud operators pursuing GPU-heavy configurations while enterprise virtualization maintains CPU dominance. Channel strategies vary by segment: direct manufacturer contracts prevail for high-volume accelerator purchases, whereas system integrators intermediate legacy CPU deployments.
Product Type:
GPU accelerators flow almost exclusively through direct procurement channels to hyperscale operators, while CPUs and FPGAs distribute through tier-one system integrators serving enterprise and telecommunications verticals.
- GPU:Parallel matrix operation engines fabricated on advanced nodes with HBM integration, commanding 300W to 700W thermal envelopes. Tokyo-based hyperscalers are absorbing the bulk of domestic allocation for generative AI training clusters, constrained by CoWoS packaging bottlenecks at TSMC.
- CPU:General-purpose x86 and Arm-based sockets anchoring virtualization layers and transactional databases. Osaka enterprise facilities prioritize these for legacy workload consolidation, though procurement volumes are compressing as AI accelerators capture capital expenditure share.
- FPGA:Programmable logic devices from Xilinx and Intel concentrating in Fukuoka financial services edge nodes where nanosecond latency arbitrage justifies premium silicon.
- ASIC:Custom matrix multiplication engines from domestic designers targeting RIKEN supercomputing procurement with government subsidy backing.
By volume, CPU leads. By growth pace, GPU is climbing the fastest.
Application:
Cost tier stratification separates cloud computing infrastructure (premium accelerator configurations) from virtualization workloads (standard x86 sockets), with big data analytics occupying a mid-tier hybrid position.
- Cloud Computing:Hyperscale virtualization and container orchestration at scale. Tokyo and Osaka facilities dominate procurement, with METI efficiency mandates forcing liquid-cooled rack specifications.
- AI Processing:Generative model training and inference clusters. Domestic cloud operators are procuring GPU-heavy configurations exclusively, with RIKEN and national laboratories driving frontier demand.
- Big Data Analytics:Distributed storage protocol execution and batch processing. Financial services in Fukuoka and manufacturing in Nagoya sustain mid-tier CPU and FPGA demand.
- Virtualization:Legacy enterprise server consolidation and database hosting. Procurement is concentrating through Fujitsu and NEC system integrator channels for on-premises Tokyo enterprise accounts.
Cloud computing captures the largest procurement volume. AI processing shows the steepest expansion trajectory.
End User:
Customer type determines socket specification: IT services demand density-optimized configurations, while telecommunications prioritizes edge-hardened thermal profiles.
- IT Services:Domestic cloud operators and managed hosting providers. These buyers consolidate procurement around NVIDIA and AMD direct contracts, bypassing traditional distribution.
- Telecommunication:NTT and KDDI edge facilities. Low-latency requirements in Tokyo and Osaka metro rings sustain FPGA and custom ASIC demand.
- E-Commerce:Rakuten and domestic platform operators. Transactional database workloads favor high-core-count x86 configurations with memory-optimized topologies.
- Gaming:Cloud gaming infrastructure operators. GPU allocation for render streaming competes with AI training for silicon supply.
IT services lead by procurement value. Gaming infrastructure is gaining share fastest as cloud streaming multiplies.
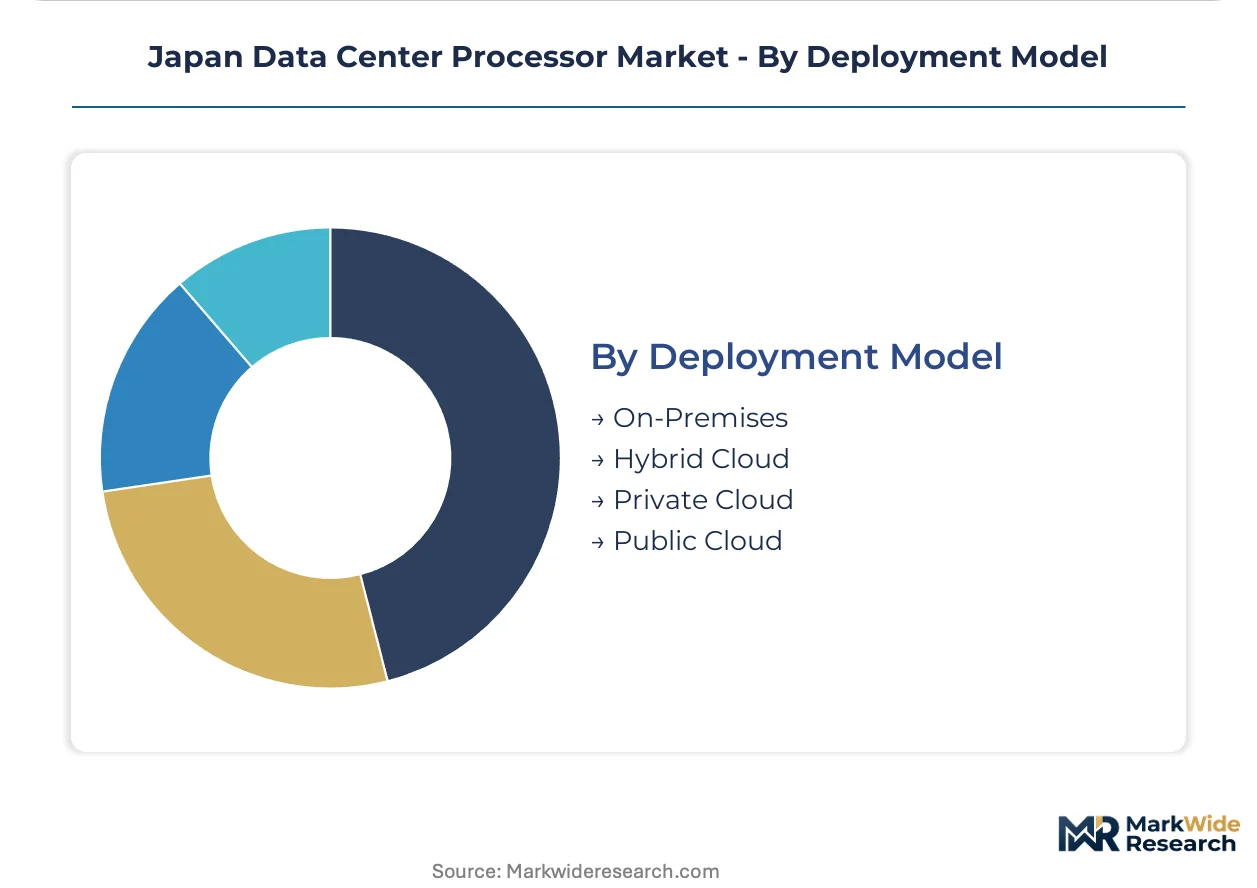
Deployment Model:
Maturity gradient separates established on-premises infrastructure from emerging hybrid configurations, with public cloud representing the most standardized procurement profile.
- Public Cloud:Multi-tenant hyperscale facilities operated by domestic and international providers. Processor procurement here is the most consolidated, with direct NVIDIA and AMD contracts dominating.
- Hybrid Cloud:Workload portability between on-premises and off-premises resources. Enterprise buyers in Osaka manufacturing and Tokyo financial services are specifying Arm-based servers for power efficiency.
- Private Cloud:Single-tenant dedicated infrastructure. Fujitsu and NEC system integrators intermediate processor sales to conservative enterprise accounts resisting public cloud migration.
- On-Premises:Legacy enterprise data centers. Mainframe-era transactional databases in Tokyo banking complicate processor refresh cycles and sustain outdated socket generations.
Public cloud leads by accelerator deployment. Hybrid cloud is expanding most quickly as METI efficiency mandates force facility consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI anchors processor procurement patterns across Japan's domestic data center landscape, with efficiency mandates and localization requirements shaping facility investment geography. Sub-regional capacity distribution reflects submarine cable infrastructure, land cost differentials, and proximity to hyperscale customer clusters.
Kanto/Tokyo
Tokyo's hyperscale concentration absorbs the bulk of GPU accelerator procurement for generative AI training clusters. METI's green data center directives compress facility certification timelines toward liquid-cooled rack specifications. The Tokyo-Osaka corridor sustains legacy enterprise virtualization demand through Fujitsu and NEC system integrator channels.
Kansai/Osaka
Osaka enterprise facilities prioritize high-core-count x86 configurations for transactional database consolidation and legacy workload hosting. The Personal Information Protection Commission's data sovereignty rules prevent offshore cloud substitution and sustain local processor deployment. Manufacturing sector concentration in surrounding prefectures drives mid-tier CPU and FPGA procurement through tier-one system integrators.
Kyushu
Fukuoka's submarine cable landings and lower land costs position the region as an alternative to Tokyo-Osaka concentration. Financial services edge nodes in the city deploy programmable logic devices for nanosecond latency arbitrage. METI subsidies for local substrate capacity are creating captive supply opportunities for domestic processor integrators targeting RIKEN procurement.
Chubu/Nagoya
Nagoya's manufacturing base sustains distributed storage protocol execution and batch processing workloads across mid-tier CPU configurations. Automotive sector data localization requirements align with METI efficiency mandates to drive facility consolidation toward hybrid cloud architectures. Regional operators are specifying Arm-based servers for power efficiency in new procurement tenders.
Japan Data Center Processor Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Japan's data center processor market. NVIDIA Corporation and Intel Corporation anchor the upper tier through direct hyperscale contracts, while Fujitsu Ltd. and Ampere Computing occupy specialist positions in high-performance computing and cloud-native workloads respectively. Competitive moves concentrate on software ecosystem lock-in and thermal design power optimization for liquid-cooled deployments.
Within the integrated tier, NVIDIA Corporation exemplifies the CUDA-anchored accelerator archetype dominating AI training procurement, while Intel Corporation represents the legacy x86 virtualization incumbent defending socket share against core-density challengers. Fujitsu Ltd. occupies a distinct position as the domestic Arm-based architecture provider serving national laboratory and government-backed supercomputing procurement.
| Leading Market Players |
|---|
| Intel Corporation |
| Advanced Micro Devices |
| NVIDIA Corporation |
| Ampere Computing |
| ARM Holdings |
| Fujitsu Ltd. |
| IBM Corporation |
| Qualcomm |
| Amazon Web Services |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts lock Japanese hyperscalers into CoWoS allocation at TSMC, anchoring price visibility for GPU accelerators while exposing buyers to fixed-cost obligations regardless of demand fluctuations. METI efficiency mandates compound procurement rigidity by mandating liquid-cooled socket specifications that narrow vendor qualification pools.
Pricing Analysis
Tokyo-Osaka procurement premiums run 15-20% above Fukuoka edge deployments due to land cost differentials and submarine cable proximity. Three-tier pricing structure across premium accelerator, standard x86, and economy legacy sockets reflects performance-per-watt certification tiers under JIS standards. Cost compression in high-TDP GPU segments is intensifying because CoWoS packaging bottlenecks constrain supply elasticity. Enterprise virtualization buyers exhibit highest price sensitivity, whereas RIKEN and national laboratories absorb premium silicon with minimal negotiation leverage.
Supply Chain Analysis
Container availability constraints on the Taiwan-Japan trade lane inflate inbound logistics costs for advanced node wafers, compressing margin buffers for domestic system integrators. Taiwan, South Korea, and the United States concentrate leading-edge fabrication, with advanced substrates drawing from Japanese chemical suppliers and HBM memory resting on South Korean foundry output. Single-source vulnerability at TSMC for CoWoS packaging creates procurement uncertainty under export control alignment complexity. Distribution runs through direct manufacturer contracts for hyperscale GPU procurement, while tier-one system integrators intermediate legacy CPU channels to enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based AI inference services threaten on-premises processor deployment as domestic operators evaluate subscription models against capital-intensive silicon procurement. Incumbents must articulate total-cost-of-ownership advantages to defend socket share.
For Market Incumbents: Secure captive CoWoS allocation through multi-year foundry partnerships before substrate capacity tightens further. Deepen backward integration into advanced packaging by qualifying domestic interposer suppliers under METI subsidy programs. Arm-based architecture teams require retention investment as talent migrates toward accelerator design.
For New Entrants and Emerging Players: Edge-hardened FPGA configurations for Fukuoka financial services nodes represent an under-served latency tier where programmable logic outperforms GPU flexibility. Target hybrid cloud procurement in Nagoya manufacturing clusters where Arm-based power efficiency specifications are displacing x86 incumbents. Partner with Fujitsu system integrators to bypass direct-hyperscale channel consolidation.
For Investors and Strategic Acquirers: Domestic advanced packaging specialists with JIS-certified substrate capacity offer acquisition exposure to METI reshoring incentives. Long-term viability hinges on silicon architecture diversification beyond x86 dominance. Monitor RIKEN procurement award patterns as inflection indicator for government-backed supercomputing demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Certification | JIS-compliant thermal designs unlock hyperscale procurement eligibility under METI mandates. |
| CoWoS Capacity Reservation | Foundry partnerships at TSMC secure packaging allocation for GPU accelerator deployment. |
| Arm Architecture Migration | Power-efficient sockets penetrate HPC workloads where x86 dominance weakens. |
| Domestic Substrate Investment | METI subsidies for local interposer capacity reduce Taiwan supply concentration risk. |
| Direct Hyperscale Contracting | Bypassing system integrators captures margin from Tokyo cloud operator consolidation. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with data center procurement officers, semiconductor supply chain managers, and METI policy specialists, combined with secondary validation against hyperscaler capex disclosures, foundry utilization reports, and JIS certification databases. Bottom-up triangulation across facility-level processor deployment estimates and top-down reconciliation with national import trade data anchored volume figures. Primary fieldwork concentrated on Tokyo hyperscale operators, Osaka enterprise facilities, and Fukuoka edge deployments.
Across the analysis window, the forecasting framework modeled processor demand through segmentation dimensions spanning product type, application workload, end-user vertical, and deployment model maturity. CAGRs derived from installer-level procurement pattern analysis and foundry capacity expansion timelines. Industry-specific inputs included CoWoS packaging bottleneck severity and METI green data center certification adoption curves.
Material uncertainties — geopolitical export control alignment, foundry yield volatility, and talent migration acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding subsidy continuity and hyperscaler capital commitment stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
United States Wi-Fi Chipset Market
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Auto Chip Market
Chipset and Processors
Automotive Image Signal Processor Market
Chipset and Processors
Automotive Chip Market
Chipset and Processors
Data Processing Neuromorphic Chip Market
Chipset and Processors
Global Graphic Processors Market
Chipset and Processors
Quantum Processing Units (QPU) Market
Chipset and Processors
Latin America Neuromorphic Chip Market
Chipset and Processors
X86 Architecture CPU Market
Chipset and Processors
Japan Microprocessor (MPU) Market
Chipset and Processors
Micro Server IC Market
Chipset and Processors
Protein Chip Market
Chipset and Processors
NB-IoT Chipset Market
Chipset and Processors
Combo Chip Market