
 Wearable Processor Market | 2026-2036
Wearable Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Processor Market Analytics
Silicon design talent scarcity in advanced node development is reorganizing competitive hierarchies among wearable processor vendors. Qualcomm sustains technology leadership through its Snapdragon Wear platform portfolio spanning LTE and 5G modem integration. Ambiq Micro specializes in sub-threshold power architectures that extend battery life for multi-day wearable devices. Samsung Electronics leverages captive semiconductor fabrication to control supply allocation for its Galaxy Watch chipsets.
A wearable processor is a system-on-chip computing unit engineered to execute sensor fusion, wireless communication, and machine learning inference within strict thermal envelopes below one watt. These devices integrate ARM or RISC-V CPU cores with dedicated neural processing units and Bluetooth Low Energy radios to enable real-time health telemetry and contextual awareness. Smartwatches command the largest product type volume as OEMs prioritize always-on display controllers and SpO2 signal processing blocks. Fitness trackers represent the fastest-growing application segment among medical professionals seeking continuous arrhythmia monitoring with prescription-grade algorithm validation. GPS-enabled health monitors carry premium positioning within the technology matrix due to dual-frequency GNSS receiver complexity and associated RF front-end certification requirements.
FDA premarket notification pathways for wrist-worn electrocardiogram devices directly shape processor validation requirements and software lockdown protocols in the United States. The EUs MDR and GDPR frameworks impose clinical evidence and data residency standards that filter chipset vendors capable of supporting European wearable rollouts. Stakeholders must monitor how NMPA cybersecurity rules for connected medical devices in China will reshape firmware signing and secure boot implementation across Asia-Pacific supply chains.
Market Dynamics
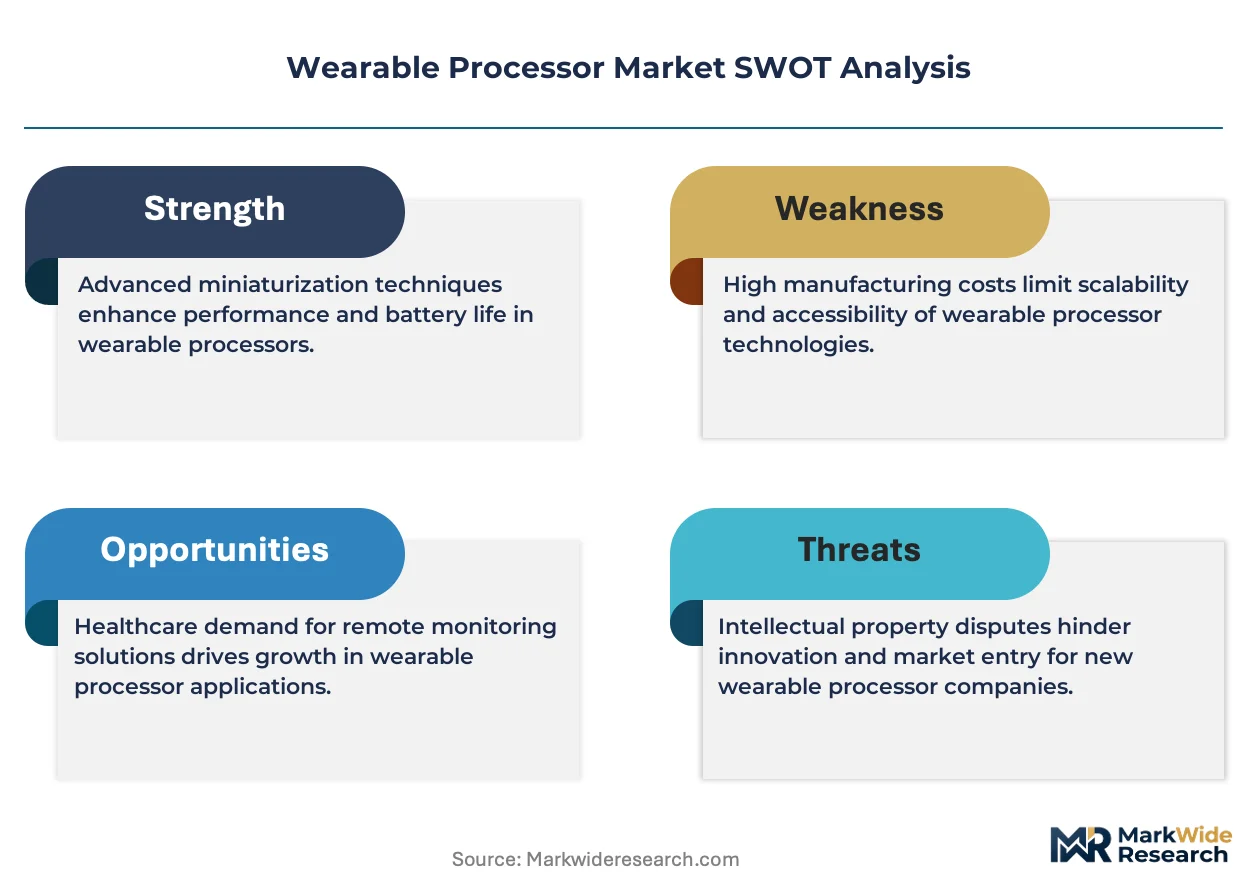
Ultra-low-power SoC design is concentrating procurement leverage among fabless vendors capable of securing advanced node capacity at TSMC and Samsung Foundry, compressing margins for second-tier suppliers locked at mature nodes.
Growth Catalysts
- FDA 510(k) Streamlining:Accelerated premarket notification pathways for wrist-worn ECG devices are validating multi-lead signal processing architectures and expanding addressable hardware requirements for US-bound wearables.
- Bluetooth-Integrated Die Shrinks:Die-level integration of BLE 5.3 radios with application processors is eliminating discrete RF component costs and enabling single-chip designs for fitness tracker OEMs.
- China Consumer Electronics Peak Seasons:Domestic fabless designers are pre-booking foundry capacity ahead of Q3-Q4 manufacturing ramps, securing wafer starts before global allocation tightening.
Market Restraints
- Advanced Node Cost Escalation:3nm and 4nm tape-out costs at leading foundries are excluding mid-tier wearable vendors from sub-5nm process migration, locking innovation within capital-rich incumbents.
- Taiwan Strait Concentration Risk:Over 80% of leading-edge wearable SoC fabrication resides within a single geopolitical corridor, exposing supply continuity to cross-strait tension scenarios.
- SpO2 Algorithm Patent Thickets:Dense intellectual property layering around photoplethysmography signal processing is forcing licensing negotiations that extend product development timelines by 8-14 months.
Strategic Opportunities
- India PLI Scheme for Wearables:Production-linked incentive structures for electronic manufacturing are attracting chipset packaging and testing investments that could shift regional supply gravity toward South Asia.
- Continuous Glucose Monitoring Convergence:Non-invasive optical glucose sensing is creating processor requirements for multi-spectral LED drivers and specialized ADC arrays that exceed current fitness tracker capabilities.
- EU MDR Data Residency Mandates:Clinical evidence storage requirements are opening firmware localization services and EU-based secure enclave implementations as premium service tiers.
Industry Challenges
- Sub-Threshold Design Talent Scarcity:Engineers proficient in near-threshold voltage circuit optimization remain concentrated within fewer than five specialized design houses, constraining power-performance scaling roadmaps.
- Dual-Frequency GNSS Certification Complexity:L1/L5 band receiver validation for FDA-cleared health monitors requires RF front-end redesigns that conflict with existing smartwatch form factor constraints.
- Secure Boot Implementation Fragmentation:NMPA cybersecurity rules for connected medical devices in China are diverging from EU MDR and FDA software lockdown protocols, forcing region-specific firmware branches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Processor Market |
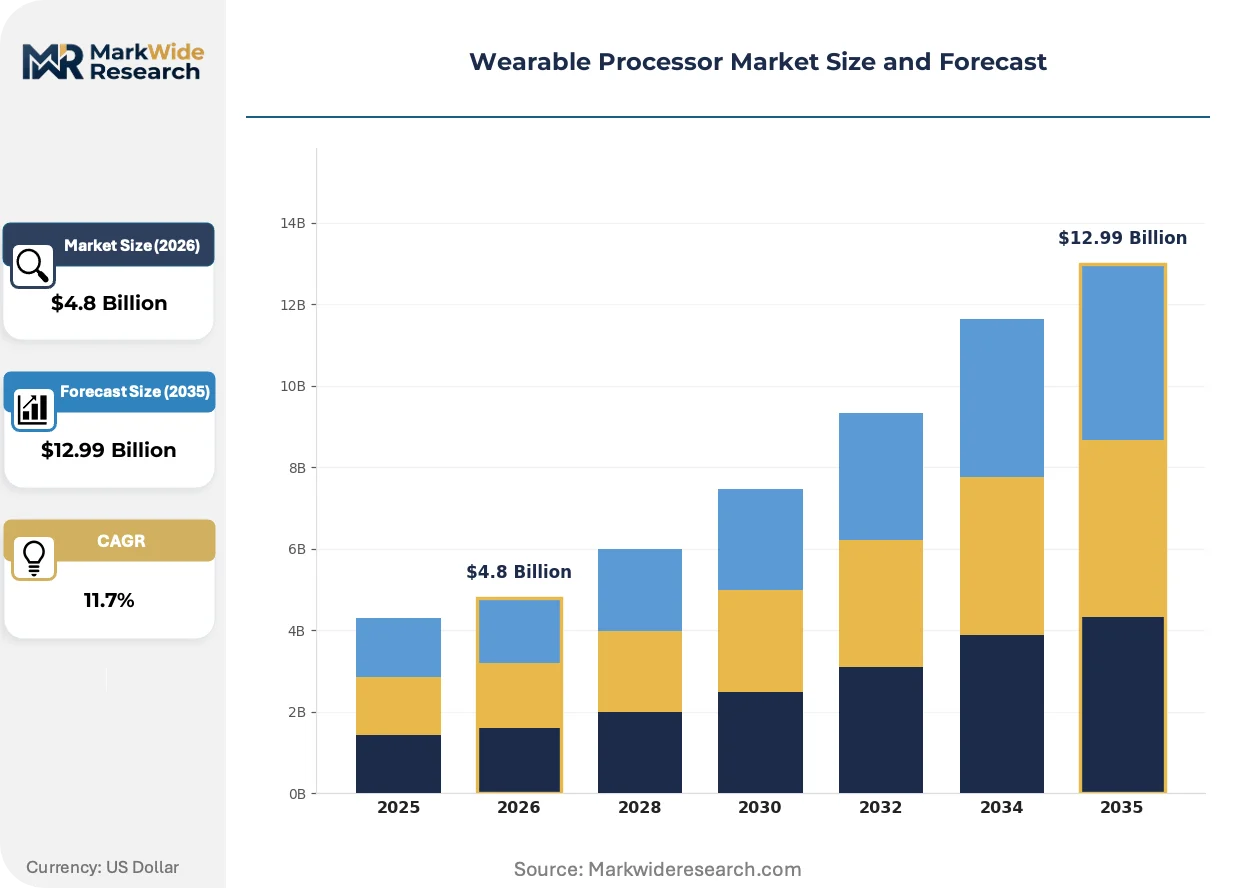
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Smart Glasses, Health Monitors Technology: Bluetooth, Wi-Fi, NFC, GPS Application: Healthcare, Sports, Navigation, Entertainment End User: Consumers, Athletes, Medical Professionals, Enterprises |
| Companies Covered | Samsung Electronics, MediaTek, Ambiq Micro, NXP Semiconductors, ARM Holdings, Qualcomm, Intel, STMicroelectronics, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Processor Market Evolving Landscape
Silicon architecture is decomposing monolithic health sensor integration into modular chiplets, enabling faster validation cycles and foundry process mixing that was previously uneconomical at wearable volume scales.
Sub-threshold power architectures are decomposing the traditional voltage-frequency tradeoff that constrained always-on health monitoring. Medical-grade wearable OEMs are adopting Ambiq-style near-threshold designs for multi-day ECG recording. This decomposition is collapsing the battery capacity premium that previously separated consumer fitness bands from prescription monitoring devices.
EU MDR clinical evidence requirements are mandating prospective validation studies for algorithm-driven health notifications. Wearable processor vendors must now embed deterministic execution environments that prevent post-certification firmware modifications. Smartwatch manufacturers targeting European reimbursement pathways are selecting chipsets with hardware-backed secure boot chains and immutable audit logging.
Hospital procurement departments are consolidating vendor relationships around prescription-grade wearable platforms that integrate directly with electronic health record systems. This concentration is displacing direct-to-consumer channels for arrhythmia monitoring devices in Germany and France. Cardiology departments at Charité Berlin and AP-HP Paris have established preferred supplier lists that prioritize FDA-cleared and CE-marked processors with validated signal processing pipelines.
Wearable Processor Market Segmentation
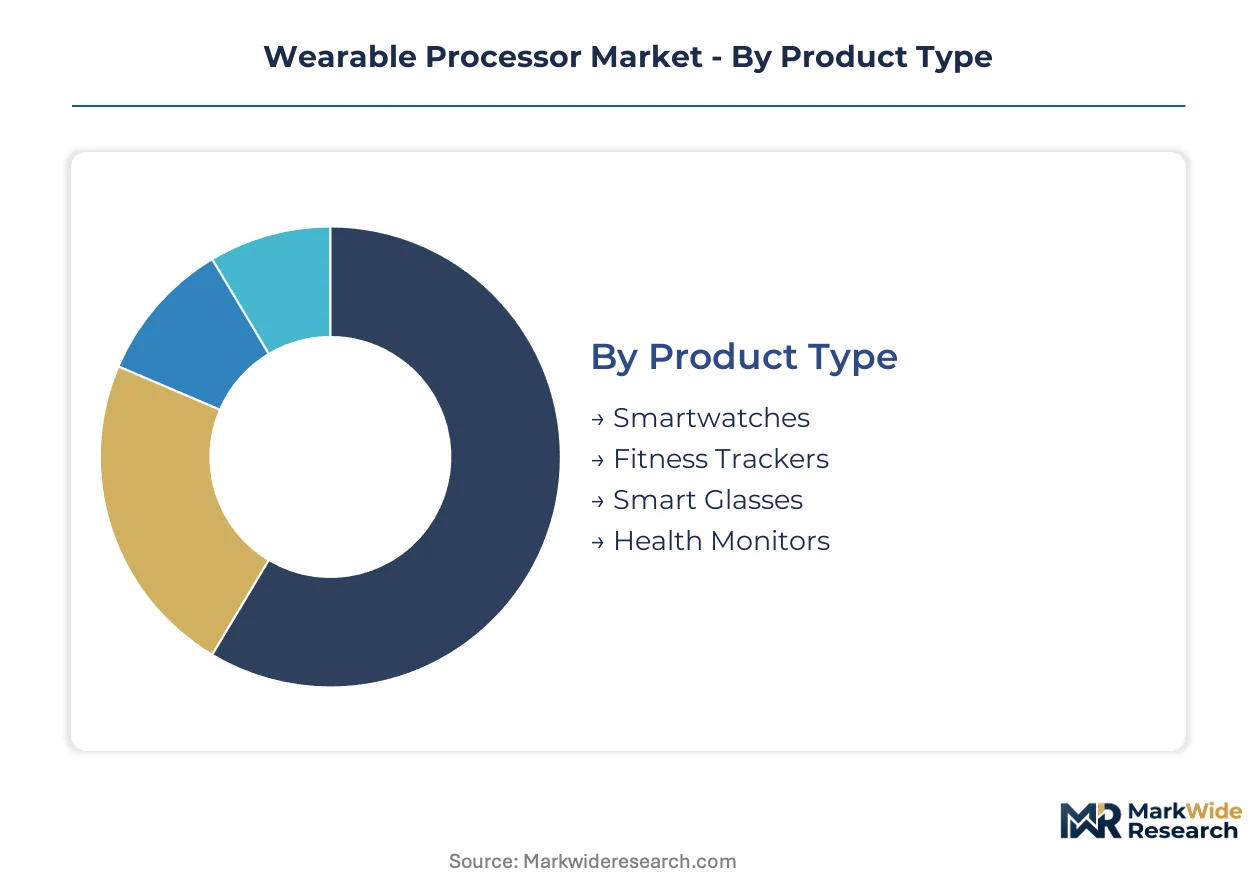
Wearable processor procurement patterns diverge sharply across device categories, with health certification requirements and power envelopes creating distinct silicon specification tiers. OEMs optimize chipset selection against battery life targets, wireless integration needs, and regulatory validation pathways that vary by end-use environment.
Product Type:
Fitness trackers face the most acute substitution pressure from smartwatches as display technology and health sensor convergence collapses the historical price-performance gap between categories.
- Smartwatches:These devices integrate always-on display controllers with multi-lead ECG signal processing blocks and SpO2 photoplethysmography engines. Demand concentrates among OEMs pursuing FDA 510(k) clearance for wrist-based arrhythmia detection in the United States, where validated algorithm pipelines command premium silicon pricing.
- Fitness Trackers:Stripped-down sensor fusion architectures prioritize step-counting accelerometers and basic heart rate monitoring within sub-100 milliwatt thermal envelopes. Medical professionals in Germany and France are adopting prescription-grade variants with continuous monitoring capabilities, displacing direct-to-consumer channels.
- Smart Glasses:Optical waveguide drivers and micro-LED controllers dominate silicon area alongside lightweight AR co-processors.
- Health Monitors:Specialized devices for remote patient monitoring integrate multi-spectral LED arrays and clinical-grade ADC precision.
Smartwatches anchor the volume base while health monitors gain share at the steepest rate.
Technology:
Cost tier stratification separates discrete RF component stacks from single-chip integration, with premium devices absorbing modem complexity that economy designs eliminate entirely.
- Bluetooth:BLE 5.3 radio integration at the die level is eliminating discrete component costs for fitness tracker OEMs. China-based fabless designers are pre-booking foundry capacity for Bluetooth-integrated chipsets ahead of Q3-Q4 manufacturing ramps.
- GPS:Dual-frequency L1/L5 band receivers require RF front-end redesigns that conflict with smartwatch form factor constraints. FDA-cleared health monitors targeting European reimbursement pathways demand this positioning precision for outdoor activity validation.
- Wi-Fi:Higher throughput enables standalone music streaming and cloud-synced health data upload without smartphone tethering.
- NFC:Contactless payment authentication and medical device pairing protocols drive secure element integration.
Bluetooth dominates unit shipments while GPS carries the steepest technology premium.
Application:
Customer type fragmentation creates divergent firmware requirements, with healthcare mandates forcing deterministic execution environments that entertainment applications relax.
- Healthcare:EU MDR clinical evidence requirements mandate prospective validation studies for algorithm-driven notifications. Processors must embed hardware-backed secure boot chains and immutable audit logging to prevent post-certification firmware modifications.
- Sports:Real-time biomechanical analysis demands sensor fusion rates exceeding 100 Hz with sub-10 millisecond latency guarantees.
- Navigation:Outdoor positioning reliability depends on multi-constellation GNSS receiver integration.
- Entertainment:Audio codec performance and haptic feedback precision prioritize user experience over clinical validation.
Healthcare anchors the value pool while sports applications expand most quickly.
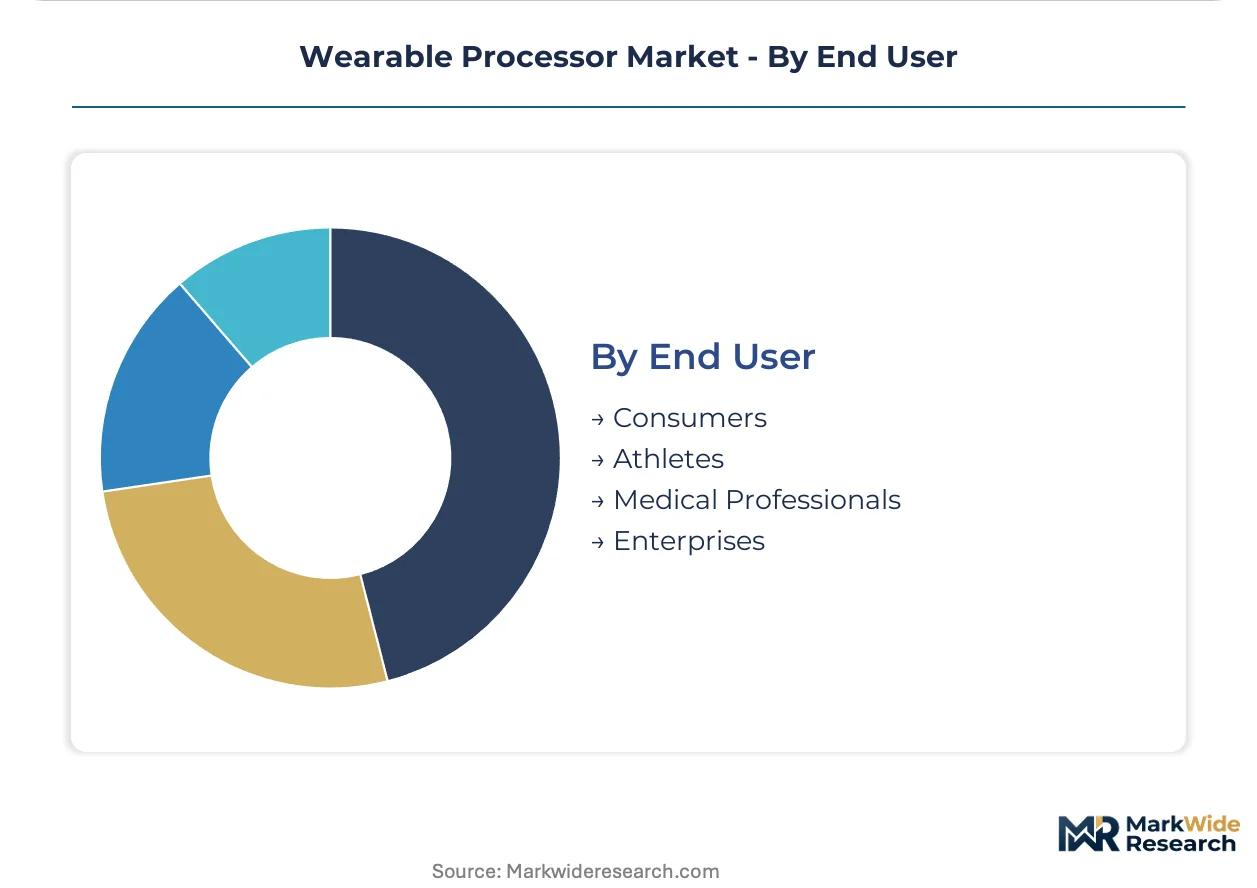
End User:
Volume concentration among consumer channels is fragmenting as enterprise wellness programs and hospital procurement consolidate around prescription-grade platforms.
- Medical Professionals:Cardiology departments at Charité Berlin and AP-HP Paris maintain preferred supplier lists prioritizing FDA-cleared and CE-marked processors. Hospital procurement is consolidating vendor relationships around platforms integrating directly with electronic health record systems.
- Consumers:Mass-market demand prioritizes multi-day battery life and always-on display aesthetics over clinical validation.
- Athletes:Training load optimization requires validated VO2 max estimation and recovery metrics.
- Enterprises:Workforce safety monitoring drives ruggedized designs with extended temperature operating ranges.
Consumers anchor the volume base while medical professionals drive the steepest value expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wearable processor procurement patterns diverge sharply by geography. The United States prioritizes FDA-cleared health monitoring architectures, while China concentrates on high-volume Bluetooth-integrated chipsets for consumer electronics. European demand centers on GDPR-compliant secure boot implementations for clinical reimbursement pathways.
United States
Smartwatch OEMs are expanding procurement of ultra-low-power SoCs as FDA 510(k) clearance pathways for wrist-based ECG devices streamline approval timelines. The FDA premarket notification framework validates multi-lead signal processing architectures and mandates software lockdown protocols. Austin and San Diego host design centers where fabless vendors optimize neural processing units for real-time health telemetry.
China
Domestic fabless designers are securing foundry capacity for Bluetooth-integrated wearable chipsets ahead of Q3-Q4 consumer electronics peak seasons. NMPA cybersecurity rules for connected medical devices are reshaping firmware signing and secure boot implementation requirements. Shenzhen and Shanghai anchor the ecosystem where tape-out activity concentrates for BLE 5.3 radio integration.
Germany
Hospital procurement departments are consolidating vendor relationships around prescription-grade wearable platforms that integrate directly with electronic health record systems. The EU MDR framework imposes clinical evidence and data residency standards that filter chipset vendors capable of supporting European rollouts. Berlin's Charité hospital maintains preferred supplier lists prioritizing CE-marked processors with validated signal processing pipelines.
South Korea
Captive semiconductor fabrication controls supply allocation for Galaxy Watch chipsets as OEMs prioritize always-on display controllers and SpO2 signal processing blocks. MFDS medical device regulations align with FDA validation requirements for wrist-worn arrhythmia detection. Seoul's Pangyo Techno Valley clusters design houses specializing in sub-threshold power architectures for multi-day battery life.
India
Production-linked incentive structures for electronic manufacturing are attracting chipset packaging and testing investments that could shift regional supply gravity toward South Asia. The PLI scheme for wearables targets domestic value addition in assembly and test operations. Karnataka and Tamil Nadu are emerging as preferred locations for back-end semiconductor facilities serving wearable OEMs.
Wearable Processor Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that concentrates on sub-threshold power optimization and secure boot implementations. Foundry access at TSMC and Samsung Foundry separates capital-rich incumbents from mid-tier vendors locked at mature nodes. Strategic archetypes include integrated platform providers, ultra-low-power specialists, and captive silicon designers. Competitive moves center on advanced node tape-outs and die-level Bluetooth radio integration.
Within the integrated platform tier, Qualcomm and Samsung Electronics occupy positions spanning LTE and 5G modem integration. Ambiq Micro exemplifies the ultra-low-power specialist archetype through near-threshold voltage circuit optimization. MediaTek represents the scale-driven fabless model securing foundry capacity ahead of manufacturing ramps. These three anchors illustrate how technology leadership, power architecture specialization, and supply security define competitive positioning.
| Leading Market Players |
|---|
| Samsung Electronics |
| MediaTek |
| Ambiq Micro |
| NXP Semiconductors |
| ARM Holdings |
| Qualcomm |
| Intel |
| STMicroelectronics |
| Apple |
| Others |
Value Network & Pricing Analysis
Wafer-level economies at TSMC's N4 and N3 nodes concentrate procurement leverage among capital-rich fabless vendors, compressing margins for mid-tier suppliers locked at 28nm and above while establishing hard price floors for FDA-validated health monitoring chipsets. This scale dynamic simultaneously shapes supply allocation hierarchies and pricing stratification across certification tiers.
Pricing Analysis
Long-term foundry offtake contracts dominate procurement for advanced-node wearable SoCs, insulating Qualcomm and MediaTek from spot-market volatility while locking second-tier vendors into quarterly spot pricing at mature nodes. Price differentiation separates FDA 510(k)-cleared processors with validated signal processing pipelines from consumer-grade fitness tracker chipsets lacking clinical certification. Pricing pressure intensifies in the Bluetooth-integrated tier as Chinese fabless designers pre-book capacity ahead of peak seasons, compressing margins for late movers. Medical professionals and hospital procurement departments exhibit lowest price sensitivity, prioritizing CE-marked validation and EHR integration over unit cost.
Supply Chain Analysis
Taiwan Strait fabrication chokepoints expose over four-fifths of leading-edge wearable SoC production to geopolitical disruption scenarios, with TSMC's Hsinchu and Taichung facilities anchoring global capacity for sub-5nm health monitoring processors. Silicon supply draws from Arizona and Kumamoto expansion projects, though these remain minority shares through the mid-decade. Germanium and gallium substrate dependencies feed from China and Russia, creating tariff exposure under evolving export control frameworks. Distribution runs through Shenzhen and Shanghai assembly hubs for consumer electronics, with dedicated logistics lanes serving FDA-regulated medical device channels in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wearable processor market sits in cyclical recovery as FDA 510(k) clearance pathway streamlining for wrist-worn ECG devices restarts health certification investment cycles that stalled during pandemic-era regulatory backlogs.
For Market Incumbents: Secure advanced node capacity reservations at TSMC and Samsung Foundry through multi-year offtake structures that lock out emerging competitors from sub-5nm migration. Defend against Ambiq-style sub-threshold specialists by acquiring near-threshold voltage design talent concentrated in Seoul's Pangyo Techno Valley and Austin design clusters. Channel control through direct hospital procurement relationships at Charité Berlin and AP-HP Paris insulates premium pricing from consumer electronics margin erosion. For New Entrants and Emerging Players: Lead with prescription-grade fitness tracker architectures targeting Germany and France where EU MDR reimbursement pathways displace direct-to-consumer channels. The continuous glucose monitoring convergence segment offers penetrable white space as non-invasive optical sensing creates processor requirements exceeding current capabilities. A go-to-market angle through EU-based secure enclave firmware localization services captures MDR data residency mandates as a service-tier differentiator. For Investors and Strategic Acquirers: Specialized sub-threshold design houses with near-threshold voltage circuit optimization capabilities represent priority acquisition targets as power-performance scaling roadmaps constrain wearable battery life extension. Long-term viability over the next decade hinges on FDA clearance velocity and China foundry allocation security rather than consumer electronics volume scale. Watch NMPA cybersecurity rule implementation timelines as the inflection signal for Asia-Pacific firmware architecture standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Node Tape-Out | TSMC N3E reservations at Samsung Foundry secure health monitoring SoC capacity ahead of Q3 ramps. |
| Die-Level Bluetooth Integration | BLE 5.3 radio consolidation eliminates discrete RF costs for fitness tracker OEMs in Shenzhen. |
| EU Secure Enclave Localization | GDPR-compliant firmware implementations capture MDR clinical evidence storage premium tiers. |
| Sub-Threshold Design Acquisition | Near-threshold voltage talent concentration in Austin and Pangyo extends multi-day battery architectures. |
| Hospital Procurement Integration | EHR system connectivity at Charité Berlin and AP-HP Paris locks prescription-grade platform relationships. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with semiconductor design executives, foundry account managers, FDA regulatory consultants, and hospital biomedical engineering directors; and secondary validation against SEC 10-K filings, TSMC and Samsung Foundry capacity disclosures, FDA 510(k) clearance databases, and EU MDR notified body certification records. Bottom-up triangulation across fabless vendor shipment estimates and top-down reconciliation against foundry wafer start data anchored volume and value outputs.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, technology integration level, application certification tier, and end-user procurement channel. CAGRs were derived from segment-level growth rate reconciliation against macro wearable device shipment forecasts and semiconductor content-per-unit assumptions. Key inputs included FDA clearance velocity assumptions, China foundry allocation tightening scenarios, and EU MDR reimbursement pathway adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) streamlining, stable Taiwan Strait logistics, or continued EU MDR enforcement would require recalibration. Practitioners should keep alternative scenarios live as NMPA cybersecurity rule divergence and advanced node cost escalation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Superconducting Quantum Chip Market
Chipset and Processors
Hybrid Chip Market
Chipset and Processors
Automotive Gateway Chips Market
Chipset and Processors
Brazil Data Center Processor Market
Chipset and Processors
8-Bit MCU Market
Chipset and Processors
Europe Neuromorphic Chip Market
Chipset and Processors
Japan Data Center Processor Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
Global Digital Light Processing Chipset Market
Chipset and Processors
Multi-Mode Chipset Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
Microserver Market
Chipset and Processors
Cloud AI Chipsets Market
Chipset and Processors
Wi-Fi Chipset Market
Chipset and Processors
Global Wireless Chipsets Market
Chipset and Processors
Data Processing Neuromorphic Chip Market