
 Germany Data Center Processor Market | 2026-2036
Germany Data Center Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Data Center Processor Market Insights
The EU AI Act is decoupling compliance costs from traditional hardware procurement cycles, forcing processor vendors to redesign certification pathways before deployment. Intel Corporation sustains manufacturing scale through its European foundry partnerships, while NVIDIA Corporation dominates AI training workloads with specialized accelerator architectures. Advanced Micro Devices Inc. competes on x86 server density, offering alternative socket compatibility for enterprise refresh cycles.
A data center processor is a compute-optimized integrated circuit fabricated on advanced process nodes, typically featuring billions of transistors, multi-core architectures, and thermal design power ratings exceeding 200 watts for high-performance variants, engineered to execute parallel workloads across virtualization, analytics, and artificial intelligence inference. CPUs retain the largest installed base among processor types, though GPUs capture expanding margin pools as generative AI training scales. Liquid cooling adoption accelerates fastest among cooling technologies, driven by rack densities that air systems cannot dissipate, while blade form factors lead hyperscale deployments due to spatial efficiency.
KBA efficiency standards and the EU Green Deal framework shape mandatory power-usage metrics, compelling operators to prioritize processors with verified performance-per-watt benchmarks. BSI certification requirements for electromagnetic compatibility add compliance layers to import and integration timelines. Stakeholders must weigh sovereign silicon initiatives against established supply chains as Berlin evaluates domestic fabrication subsidies.
Market Dynamics
The EU AI Act is decoupling compliance costs from traditional hardware procurement cycles, forcing processor vendors to redesign certification pathways before deployment can proceed. This regulatory compression is reshaping how silicon enters German data centers.
Growth Catalysts
- EU AI Act certification mandates:Operators must procure AI-optimized silicon meeting algorithmic transparency standards, creating pull for certified processors before deployment deadlines.
- Hyperscale cloud expansion:Frankfurt's Rhine-Main cluster and Berlin-Brandenburg corridor concentrate demand from cloud providers scaling generative AI training infrastructure.
- Liquid cooling integration:Rack densities exceeding air-cooling thresholds accelerate adoption of processors designed for direct liquid cooling architectures.
Market Restraints
- TSMC foundry concentration:Advanced node fabrication depends on single-source Taiwan supply, exposing German operators to geopolitical disruption risk.
- BSI electromagnetic compatibility certification:Extended testing timelines for imported processors delay integration by 8-14 weeks versus domestic EU alternatives.
- High-purity silicon substrate costs:Wafer input prices fluctuate with polysilicon energy intensity, compressing margin on sub-7nm processor production.
Strategic Opportunities
- Domestic foundry subsidies:Berlin's sovereign silicon initiative offers capital grants for local advanced packaging facilities, reducing import dependency.
- Edge AI inference deployment:Manufacturing and automotive verticals in Bavaria and Baden-Württemberg demand low-latency processors for factory-floor analytics.
- EU Green Deal efficiency premiums:KBA power-usage benchmarks reward processors with verified performance-per-watt metrics, creating pricing differentiation for compliant silicon.
Industry Challenges
- Legacy x86 socket compatibility:Enterprise refresh cycles stall when new AI accelerators lack backward integration with existing server motherboards.
- BSI-KBA dual certification timelines:Parallel electromagnetic and efficiency testing creates bottlenecks that extend procurement-to-deployment intervals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Data Center Processor Market |
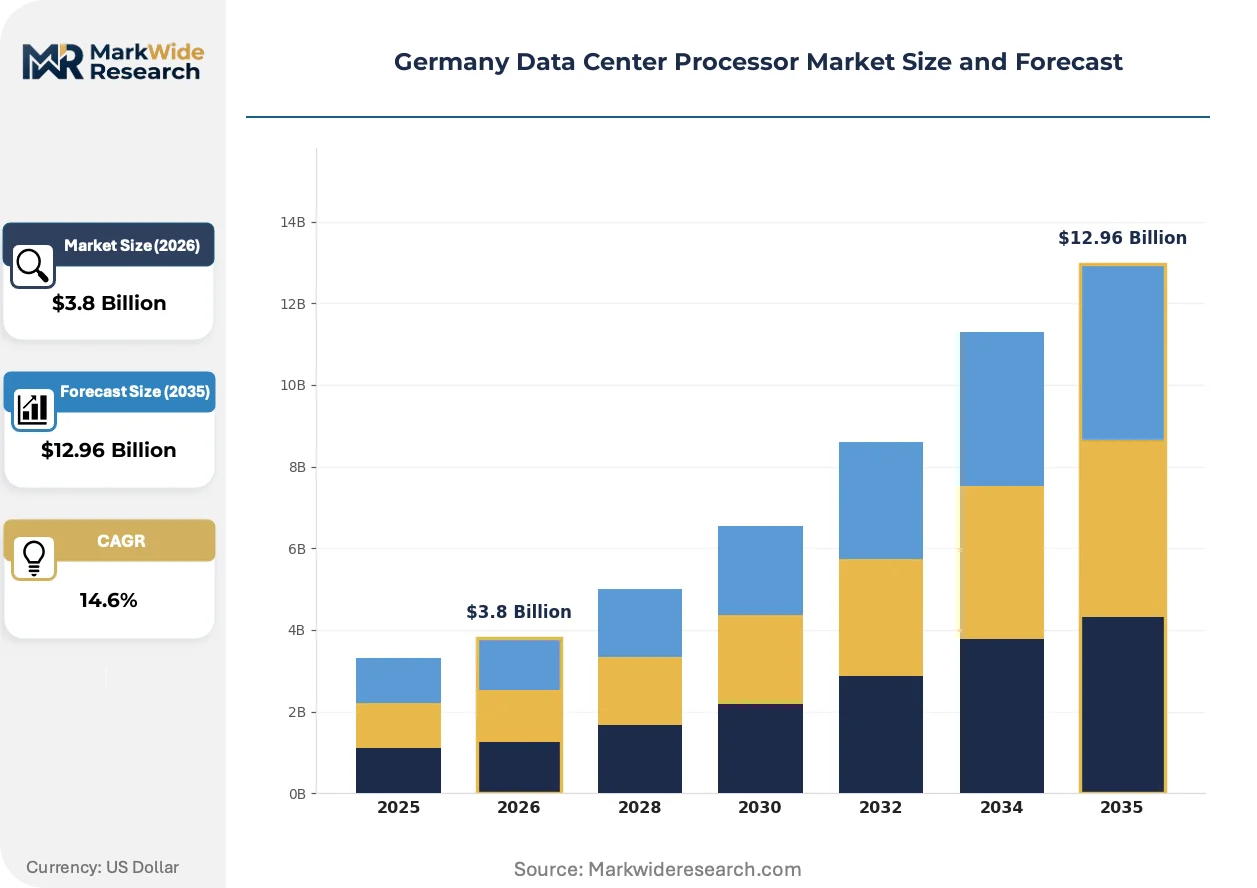
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Processor Type: CPUs, GPUs, FPGAs, ASICs Form Factor: Blade, Rackmount, Modular, Tower Cooling Technology: Air Cooling, Liquid Cooling, Immersion Cooling, Hybrid Cooling End User Sector: IT Services, Telecommunications, Cloud Providers, Enterprises |
| Companies Covered | Arm Limited, Broadcom Inc., Intel Corporation, IBM Corporation, Qualcomm Technologies, Inc., Advanced Micro Devices Inc., Marvell Technology, Inc., Graphcore, NVIDIA Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Data Center Processor Market Trends and Innovations
Advanced packaging architectures and regulatory compliance frameworks are converging to redefine processor qualification timelines. German operators now prioritize silicon that satisfies both performance benchmarks and emerging AI governance standards.
Chiplet-based modular processors are expanding into high-performance compute deployments. Hyperscale operators in Frankfurt deploy these disaggregated dies to customize core-to-memory ratios for specific AI training workloads. This packaging approach is expanding into mainstream enterprise servers as socket compatibility standardizes.
KBA efficiency standards under the EU Green Deal framework now mandate granular power-usage effectiveness reporting for processors above 200W thermal design power. Operators must document per-workload energy consumption, compelling vendors to embed telemetry circuits. Frankfurt's certified data centers face the strictest enforcement, with quarterly audits verifying claimed performance-per-watt benchmarks.
Cloud provider procurement now bundles silicon with liquid cooling infrastructure as single-vendor packages. Traditional server OEMs lose direct relationships as hyperscalers specify bare processors and cooling systems separately. This unbundling concentrates most visibly in Berlin-Brandenburg, where Microsoft and Google operate self-designed facilities with captive integration teams.
Germany Data Center Processor Market Segmentation
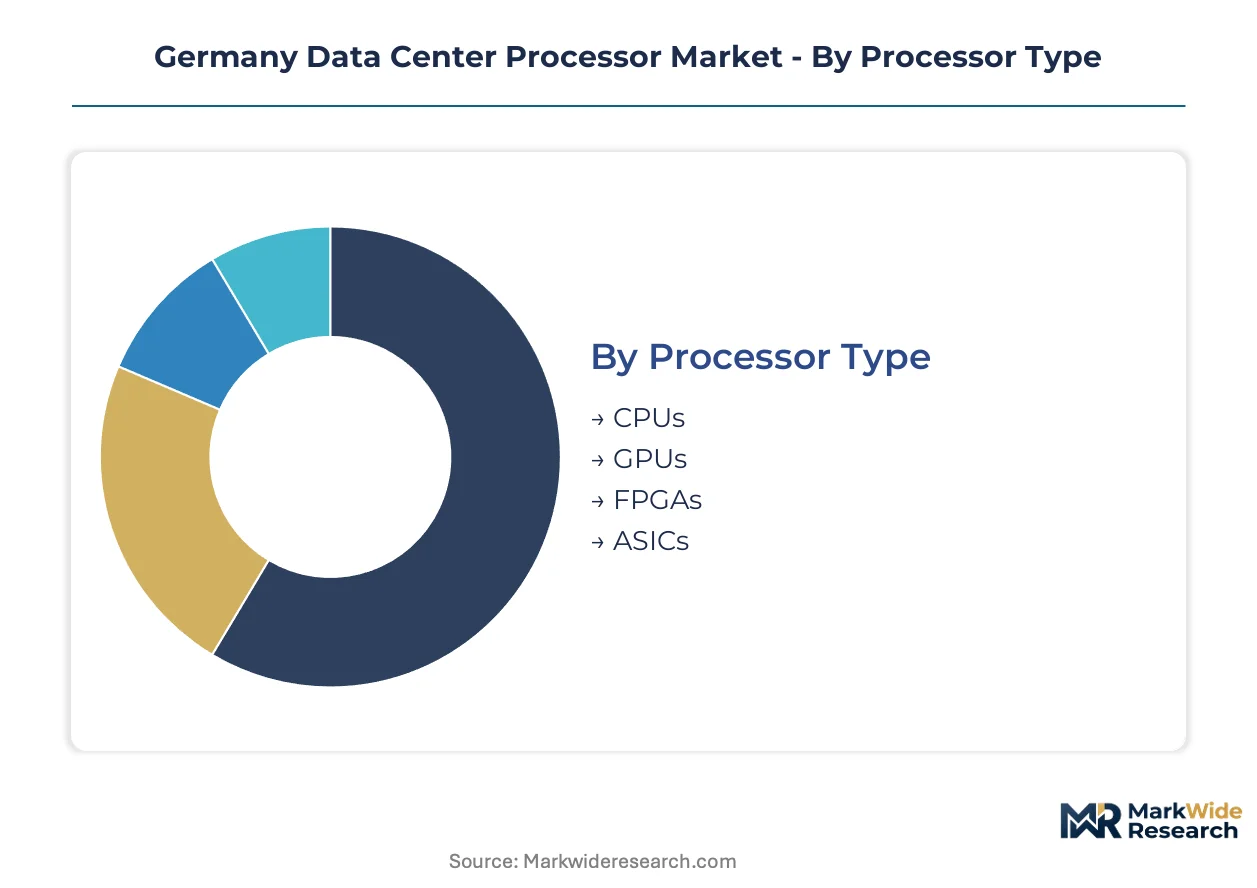
Processor selection in German data centers now hinges on workload-specific optimization rather than generic compute capacity. Buyers evaluate silicon through the lens of EU AI Act compliance timelines and KBA efficiency mandates, forcing segmentation to align with certification pathways rather than raw performance metrics alone.
Processor Type:
Hyperscale procurement teams prioritize architectural fit against training versus inference workloads, with algorithmic transparency requirements under EU AI Act reshaping vendor shortlists.
- CPUs:Multi-core x86 and ARM architectures retain the largest installed base across Frankfurt's Rhine-Main cluster. Enterprise refresh cycles in Berlin-Brandenburg favor socket-compatible upgrades that preserve existing motherboard investments while meeting BSI electromagnetic compatibility windows.
- GPUs:Massively parallel tensor architectures dominate generative AI training deployments. Cloud providers in the Rhine-Main corridor scale GPU clusters for large language model development, driving demand for processors with verified performance-per-watt telemetry under KBA audit protocols.
- FPGAs:Reprogrammable logic arrays serve low-latency inference in Bavarian automotive manufacturing facilities.
- ASICs:Application-specific designs capture hyperscale inference at scale for fixed-workload deployments.
CPUs lead on scale; GPUs lead on momentum.
Form Factor:
Spatial constraints in urban data centers and cooling architecture compatibility drive form factor selection, with rack density limits compressing deployment options.
- Blade:Ultra-dense server nodes integrate compute, storage, and networking in single chassis units. Microsoft and Google facilities in Berlin-Brandenburg deploy blade configurations to maximize floor space per square meter while accommodating direct liquid cooling manifolds.
- Rackmount:Standard 19-inch units balance expandability with serviceability for enterprise colocation tenants. Frankfurt's certified data centers favor rackmount servers for mixed-workload environments requiring frequent hardware swaps under tight BSI-KBA dual certification schedules.
- Modular:Disaggregated compute resources enable core-to-memory ratio customization for specific AI training pipelines.
- Tower:Standalone units persist in edge and small-business deployments across Baden-Württemberg manufacturing zones.
Blade configurations dominate hyperscale absorption; modular designs are climbing the fastest among new deployments.
Cooling Technology:
Thermal design power thresholds above 200W force explicit cooling architecture commitments before processor procurement proceeds.
- Liquid Cooling:Direct-to-chip and cold plate systems dissipate heat from high-density GPU clusters. Frankfurt's certified facilities mandate liquid cooling for racks exceeding 30kW, with quarterly KBA audits verifying claimed efficiency metrics against actual telemetry.
- Air Cooling:Conventional forced-air systems retain cost advantages for sub-200W processors. Smaller colocation operators in secondary German cities delay liquid cooling capital expenditure until EU Green Deal enforcement tightens.
- Immersion Cooling:Dielectric fluid submersion eliminates fan power draw for extreme density deployments.
- Hybrid Cooling:Mixed architectures transition legacy air-cooled infrastructure toward liquid-ready configurations.
Air cooling retains the broadest footprint; liquid cooling is gaining share fastest as rack densities climb.
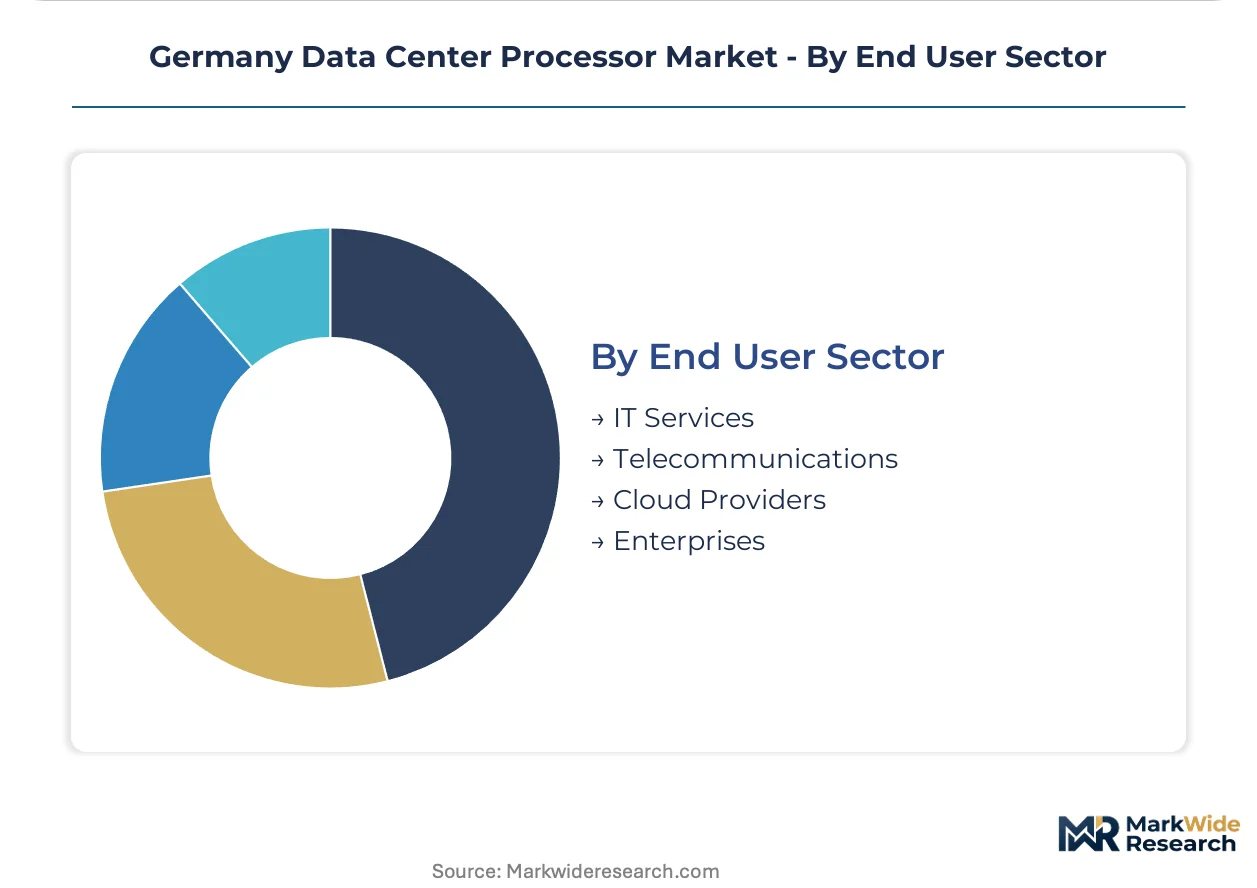
End User Sector:
Procurement scale and compliance urgency vary sharply across buyer types, with cloud providers setting technology adoption pacing.
- Cloud Providers:Hyperscale operators in Frankfurt and Berlin-Brandenburg specify bare processors and cooling systems separately, bypassing traditional server OEMs. Self-designed facilities with captive integration teams compress deployment timelines despite BSI certification requirements.
- Enterprises:Manufacturing and automotive verticals in Bavaria and Baden-Württemberg demand low-latency edge inference processors for factory-floor analytics. Sovereign data requirements under EU AI Act push these buyers toward certified silicon with algorithmic transparency documentation.
- IT Services:Managed hosting providers balance multi-tenant workload diversity against standardization pressures.
- Telecommunications:Network operators prioritize latency-sensitive processors for 5G core infrastructure and edge computing nodes.
Cloud providers lead on procurement volume; enterprises are expanding most quickly as edge AI deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep semiconductor engineering talent pools in Bavaria and Baden-Württemberg anchor Germany's processor design capabilities. Frankfurt's Rhine-Main cluster concentrates hyperscale facility operations. Berlin's sovereign silicon initiative channels federal subsidies toward domestic advanced packaging capacity.
Bavaria
Automotive manufacturing and industrial automation drive edge AI processor demand across Munich and Ingolstadt. The EU AI Act mandates algorithmic transparency documentation for factory-floor inference deployments. BMW and Siemens facilities in the Munich metropolitan area scale low-latency compute for real-time quality control systems.
North Rhine-Westphalia
Legacy industrial infrastructure and chemical sector digitization create hybrid cloud processor procurement. KBA efficiency standards under the EU Green Deal enforce granular power-usage reporting for deployments above 200W thermal design power. Cologne's media and telecom corridor concentrates GPU clusters for content rendering and 5G core infrastructure.
Baden-Württemberg
Precision engineering and automotive R&D centers in Stuttgart demand specialized inference accelerators. BSI electromagnetic compatibility certification extends testing timelines for imported processors by 8-14 weeks versus domestic alternatives. Bosch and Porsche engineering campuses pilot chiplet-based modular architectures for autonomous driving development pipelines.
Hesse
Frankfurt's Rhine-Main cluster absorbs the highest hyperscale processor volumes in continental Europe. Liquid cooling mandates for racks exceeding 30kW reshape procurement specifications toward thermally optimized silicon. Deutsche Börse and Commerzbank data centers drive financial services demand for latency-sensitive FPGA deployments.
Berlin-Brandenburg
Sovereign cloud initiatives and public sector digitization prioritize EU-certified processors with supply chain traceability. Berlin's domestic foundry subsidies attract advanced packaging investments to reduce Taiwan dependency. Microsoft and Google self-designed facilities in the capital region specify bare processors and cooling systems separately, bypassing traditional server OEM channels.
Germany Data Center Processor Market Competitive Landscape
The competitive structure tilts toward specialized accelerator vendors over general-purpose compute incumbents. Intel Corporation and Advanced Micro Devices Inc. occupy the x86 server density tier, while NVIDIA Corporation dominates AI training workloads with tensor-optimized architectures. Three archetypes define positioning: hyperscale-integrated designers, fabless accelerator specialists, and European foundry partners. Capacity expansion through TSMC allocation agreements and strategic partnerships for domestic packaging capacity represent the dominant competitive moves.
Within the fabless accelerator tier, NVIDIA Corporation and Graphcore exemplify divergent specialization strategies, with the former anchoring large-scale training deployments and the latter occupying a position in sparse compute inference. Intel Corporation and Advanced Micro Devices Inc. sit within the x86 socket-compatible refresh cycle archetype, serving enterprise data centers prioritizing motherboard preservation. Among UK-based IP licensors, Arm Limited represents the architectural licensing model that enables custom silicon development across the EU sovereign compute initiative.
| Leading Market Players |
|---|
| Arm Limited |
| Broadcom Inc. |
| Intel Corporation |
| IBM Corporation |
| Qualcomm Technologies, Inc. |
| Advanced Micro Devices Inc. |
| Marvell Technology, Inc. |
| Graphcore |
| NVIDIA Corporation |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed foundry initiatives in Berlin channel state capital into domestic advanced packaging capacity, compressing import premiums for EU-certified processors while hyperscale cloud operators unbundle server procurement from traditional OEM markups. This ownership pattern tightens pricing discipline across Frankfurt's Rhine-Main cluster as operators weigh Taiwan-sourced silicon against emerging European alternatives.
Pricing Analysis
The bundled-versus-unbundled service split separates hyperscale procurement from enterprise refresh cycles. Cloud providers in Berlin-Brandenburg specify bare processors and cooling infrastructure separately, eliminating OEM margin layers, while colocation tenants in Frankfurt accept rackmount bundles with embedded service premiums. Price differentiation rests on KBA efficiency certification tiers and BSI electromagnetic compatibility windows. Cost compression in air-cooled tiers intensifies as liquid cooling mandates spread. Enterprise buyers with legacy x86 sockets exhibit highest price sensitivity; hyperscale operators with captive integration teams show lowest.
Supply Chain Analysis
Certification and qualification gating through BSI-KBA dual timelines extends procurement-to-deployment intervals by 8-14 weeks for non-EU sourced processors. Geographic concentration centers on Taiwan for advanced node fabrication, South Korea for memory integration, and the Netherlands for EUV lithography equipment. Raw material dependencies include high-purity silicon wafers, cobalt interconnect metals, and neon process gases. Single-source vulnerability at TSMC's leading-edge foundries exposes German operators to geopolitical disruption. Distribution runs through direct allocation agreements with cloud provider procurement teams, bypassing traditional server OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's data center processor market functions as a geographic-arbitrage play between Taiwan-dependent advanced node costs and Berlin's subsidized domestic packaging capacity, with the EU AI Act's compliance windows creating timing premiums for EU-certified silicon.
For Market Incumbents: Cement socket compatibility leadership through backward integration into European advanced packaging facilities, preserving enterprise refresh cycle capture against ARM-based challengers. Prioritize KBA telemetry circuit embedding to defend margin position under quarterly audit protocols. Threat: Chiplet-based modular architectures from fabless entrants disaggregate traditional monolithic processor value capture. For New Entrants and Emerging Players: Enter via edge AI inference deployments in Bavarian automotive manufacturing corridors, where latency requirements and sovereign data mandates outstrip incumbent GPU cost structures. Target FPGA-based low-latency accelerators for factory-floor quality control systems. Go-to-market angle: Algorithmic transparency documentation bundled with processor supply to satisfy EU AI Act deployment deadlines. For Investors and Strategic Acquirers: Valuations sit cheapest among European advanced packaging specialists with BSI pre-certification pathways and existing TSMC allocation agreements. Long-term viability hinges on sovereign silicon initiative durability and hyperscale cloud capex cycles. Acquisition target archetype: Domestic packaging facilities with KBA-verified efficiency telemetry capabilities. Signal to watch: Berlin foundry subsidy allocation volumes as inflection indicator for EU supply chain momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Advanced Packaging Investment | Berlin subsidies reduce Taiwan dependency for KBA-certified processor integration. |
| Liquid Cooling Infrastructure Bundling | Hyperscale operators in Frankfurt specify cooling-processor packages bypassing OEM channels. |
| EU AI Act Certification Pre-Qualification | BSI-KBA dual testing completion before procurement accelerates deployment timelines. |
| Chiplet-Based Modular Architecture Development | Disaggregated dies enable core-to-memory customization for specific AI training workloads. |
| Edge AI Inference Processor Localization | Bavarian automotive facilities demand low-latency silicon with algorithmic transparency documentation. |
Research Methodology
Coverage spans Germany's federal states with primary inputs from each, combining structured interviews with data center procurement officers, cloud provider infrastructure planners, semiconductor distributor channel managers, and regulatory compliance specialists at BSI and KBA with secondary validation. Sources include SEC filings from listed processor vendors, hyperscaler capex disclosure reports, EU AI Act implementation guidance documents, and KBA efficiency audit protocols. Bottom-up triangulation across installation volumes in Frankfurt's Rhine-Main cluster and Berlin-Brandenburg corridor converges with top-down semiconductor trade flow analysis.
Rate-of-change decomposition separates volume expansion from price trajectory shifts across the analysis window. Segmentation dimensions modeled include processor architecture type, form factor density tier, cooling technology requirement, and end-user sector procurement scale. CAGRs derive from installed base replacement cycles, hyperscale cloud expansion commitments, and EU regulatory compliance deadline clustering. Industry-specific inputs capture TSMC allocation agreement volumes and Berlin sovereign silicon subsidy disbursement schedules.
Inputs from hyperscaler infrastructure planners and BSI certification officials were available through the study window; gaps in TSMC foundry capacity allocation transparency introduce uncertainty bands around advanced node supply assumptions. Deviation in EU AI Act enforcement timelines or Taiwan Strait logistics conditions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Advanced Audio Processor Market
Chipset and Processors
Processor for Smartphones Market
Chipset and Processors
China Data Center Processor Market
Chipset and Processors
Spain Data Center Processor Market
Chipset and Processors
Singapore Data Center Processor Market
Chipset and Processors
Multi-Mode Chipset Market
Chipset and Processors
China Automotive Microcontroller Market
Chipset and Processors
Chiplet Technology Market
Chipset and Processors
Tablet Application Processor Market
Chipset and Processors
South Korea Data Center Processor Market
Chipset and Processors
Nano Chip Market
Chipset and Processors
Wireless Charging Ics Market
Chipset and Processors
IP Core Chip Market
Chipset and Processors
DNA Sequencing Chip Market
Chipset and Processors
Microserver Market
Chipset and Processors
Envelope Tracking Chips Market