
 Natural Rubber Market | 2026-2036
Natural Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Rubber Market Intelligence
Capital-intensity divergence between plantation-backed processors and merchant traders is collapsing as integrated producers lock in feedstock security. JSR Corporation leverages its polymer science expertise to develop high-performance natural rubber compounds for premium tire segments. The Goodyear Tire and Rubber Company sustains massive offtake agreements with Southeast Asian cooperatives, anchoring volume through long-term contracts. Kumho Petrochemical Company Ltd. competes by specializing in modified natural rubber grades for electric vehicle tire applications.
Natural rubber is a cis-1,4-polyisoprene biopolymer harvested from Hevea brasiliensis trees, typically containing 90-95% rubber hydrocarbon with the remainder comprising proteins, lipids, and carbohydrates that influence vulcanization behavior and aging resistance. Its primary industrial purpose centers on dynamic load-bearing applications requiring high elasticity, abrasion resistance, and heat dissipation, with tire manufacturing consuming the dominant share of global production. Standard rubber occupies the mature volume core of the market, while reclaimed rubber is gaining structural traction as circular economy mandates intensify across automotive supply chains. The tire application segment leads absolute demand, though adhesives represent a concentrated margin pool where specialized grades command formulation premiums.
EUDR traceability requirements and REACH substance restrictions are reshaping import compliance costs for European-bound natural rubber shipments, forcing upstream documentation investments. Thailand's Rubber Authority and Indonesia's Ministry of Agriculture are implementing national sustainability certification schemes aligned with ISO 17065 to maintain market access. Stakeholders must monitor how smallholder digital traceability platforms and deforestation-linked finance exclusions reshape sourcing geography before committing to long-term plantation investments.
Market Dynamics
EUDR traceability mandates are compressing procurement timelines and forcing upstream documentation investments across Southeast Asian supply chains, fundamentally altering how tire manufacturers qualify their natural rubber suppliers.
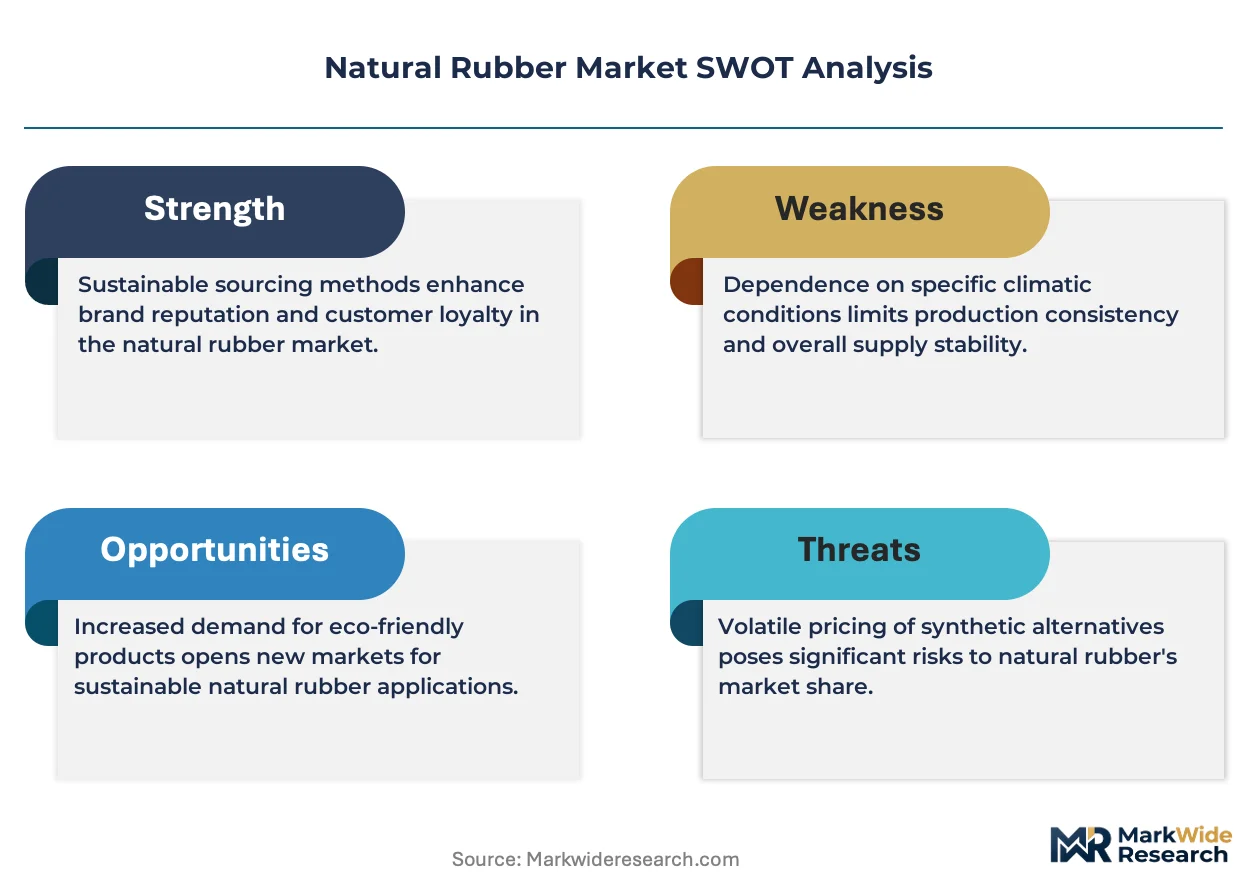
Growth Catalysts
- EU Deforestation Regulation (EUDR) compliance:Mandatory geolocation and chain-of-custody documentation for European-bound shipments is accelerating investment in digital traceability platforms across Thai and Indonesian processing hubs.
- Electric vehicle tire specifications:Higher load-bearing requirements and reduced rolling resistance targets in EV platforms are pulling demand toward technically specified natural rubber grades with enhanced dynamic properties.
- ISO 17065-aligned national schemes:Thailand's Rubber Authority and Indonesia's Ministry of Agriculture are harmonizing domestic sustainability certifications to preserve market access for smallholder-dependent supply bases.
Market Restraints
- Smallholder supply concentration:Approximately 85 percent of global natural rubber originates from farms under 5 hectares, creating feedstock security vulnerabilities and quality inconsistency for processors.
- Synthetic rubber substitution in commodity grades:Styrene-butadiene rubber (SBR) and polybutadiene rubber (PBR) are capturing volume in standard tire components where dynamic performance requirements permit polymer blending.
- Climate-induced yield volatility:Monsoon pattern disruption and pest pressure in the South China Sea region are amplifying production uncertainty without corresponding price elasticity in farmer replanting decisions.
Strategic Opportunities
- Blockchain-enabled smallholder aggregation:Distributed ledger systems for farm-level traceability are opening compliance pathways for previously excluded cooperative networks seeking direct processor relationships.
- Reclaimed rubber specification advancement:Devulcanization technology improvements are expanding reclaimed rubber applicability from industrial matting into passenger tire tread compounds under circular economy procurement mandates.
- Indian processing capacity expansion:The country's PLI scheme for rubber product manufacturing is attracting downstream tire investment that could reshape regional trade flows from Southeast Asian export dependence.
Industry Challenges
- Tapper labor availability:Rural wage competition from manufacturing and service sectors is thinning the skilled workforce required for latex collection, compressing harvest windows during peak season.
- EUDR compliance system integration:Smallholder cooperatives face 18-24 month implementation timelines for satellite mapping and management information systems before December 2025 enforcement deadlines.
- Carbon accounting methodology disputes:Divergent lifecycle assessment standards for biogenic carbon in rubber cultivation are creating certification friction between ISO, GHG Protocol, and EU Taxonomy frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Rubber Market |
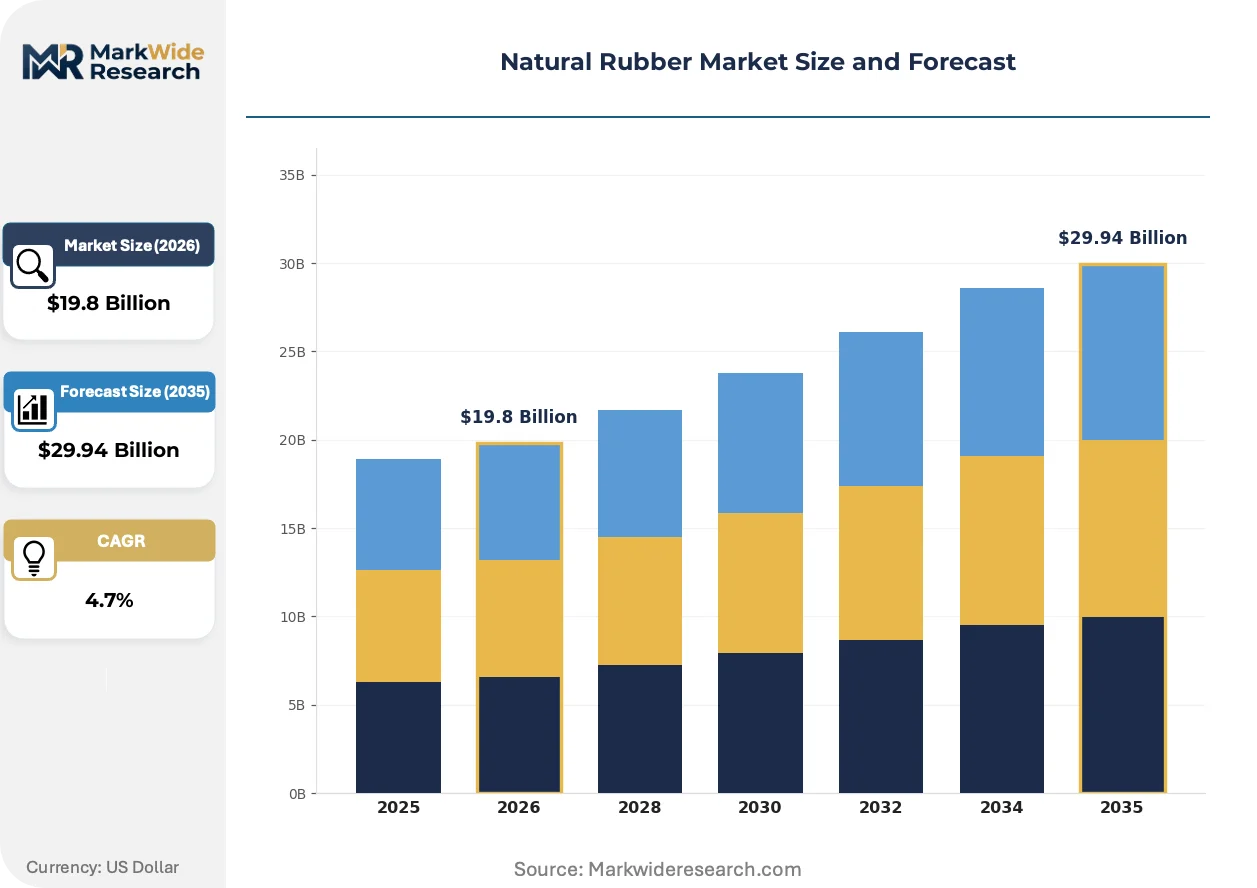
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $29.94 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Rubber, Synthetic Blend, Reclaimed Rubber, Liquid Rubber Application: Tires, Footwear, Adhesives, Coatings End User: Automotive, Consumer Goods, Industrial, Construction Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | The Dow Chemical Company, JSR Corporation, Sinopec, Kumho Petrochemical Company Ltd., Asahi Kasei Corporation, The Goodyear Tire and Rubber Company, DuPont, Denka Company Ltd., Exxon Mobil Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Rubber Market Strategic Shifts & Innovations
Digital traceability infrastructure and advanced compound engineering are converging to redefine value capture in natural rubber supply chains, separating compliant, specification-capable suppliers from commodity traders.
Epoxidized natural rubber (ENR) is displacing conventional grades in high-performance tire treads through superior wet grip and reduced rolling resistance. Bridgestone and Michelin are qualifying ENR50 and ENR25 specifications for premium passenger segments. This displacement is compressing margins for standard technically specified rubber processors lacking polymer modification capabilities.
REACH substance restrictions on polycyclic aromatic hydrocarbons (PAHs) in extender oils and vulcanization residues are forcing compound reformulation across European tire manufacturing. ECHA's 2023 update to Annex XVII entry 50 is accelerating substitution toward low-PAH process oils. Asian exporters to EU markets are absorbing testing and certification costs or ceding volume to European compounders with in-house compliance infrastructure.
Long-term offtake contracting is displacing spot market procurement for tire manufacturers with net-zero commitments. Direct farmgate partnerships with Thai and Indonesian cooperatives are replacing merchant trader intermediation for volume security. This pattern is most visible among German and Japanese OEM tire divisions with 2030 scope 3 reduction targets.
Natural Rubber Market Segmentation
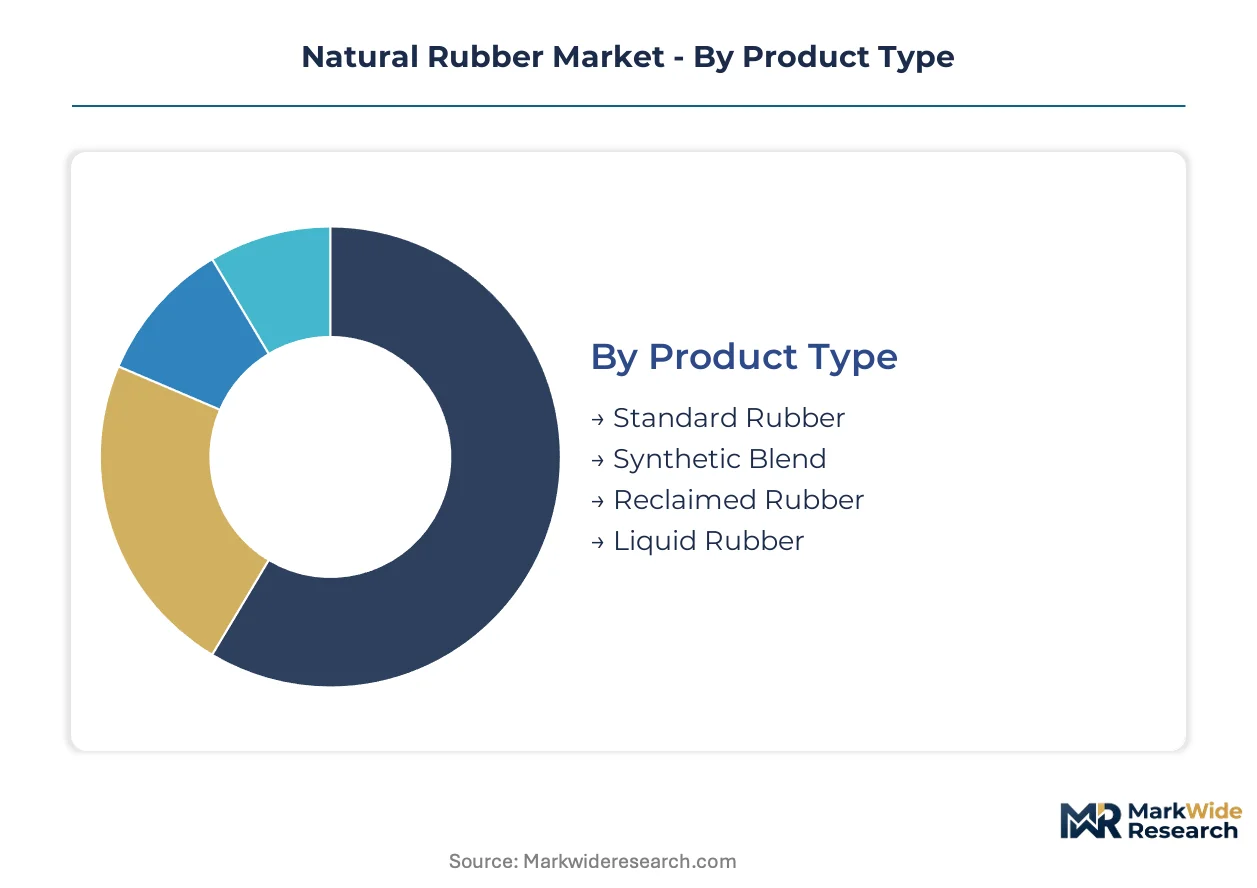
Natural rubber segmentation reveals how regulatory pressure and performance specifications fragment value capture across the supply chain. Tire manufacturers now qualify suppliers through EUDR compliance tiers rather than commodity grades alone.
Product Type:
REACH substance restrictions and EUDR traceability mandates are bifurcating procurement between certified sustainable grades and undocumented commodity rubber.
- Standard Rubber:Technically specified natural rubber grades (TSR10, TSR20) constitute the volume core, with 90-95% cis-1,4-polyisoprene content driving vulcanization consistency. Demand concentrates in Thai and Indonesian processing hubs where smallholder consolidation is accelerating under ISO 17065-aligned national schemes.
- Synthetic Blend:Styrene-butadiene and polybutadiene hybrids are displacing conventional natural rubber in standard tire components where dynamic performance requirements permit polymer substitution. European tire manufacturers are qualifying these blends under REACH-compliant process oil specifications to reduce scope 3 exposure.
- Reclaimed Rubber:Devulcanized grades are expanding from industrial matting into passenger tire treads under circular economy procurement mandates from German and Japanese OEMs.
- Liquid Rubber:Low-molecular-weight grades serve specialized adhesive and sealant formulations where solvent-free processing is required.
Established volume favors Standard Rubber; emerging adoption favors Reclaimed Rubber.
Application:
Load-bearing specifications and rolling resistance targets are concentrating procurement in technically demanding segments while commodity applications face synthetic substitution.
- Tires:Dynamic load-bearing requirements and heat dissipation needs make natural rubber irreplaceable in heavy truck and aircraft tire carcasses. EV platform specifications are pulling demand toward epoxidized natural rubber grades with enhanced wet grip and reduced rolling resistance.
- Adhesives:Solvent-based and hot-melt formulations command formulation premiums where specialized grades enable bond strength in automotive and construction assembly.
- Footwear:Crepe and smoked sheet grades serve premium sole applications requiring abrasion resistance and flexibility.
- Coatings:Chlorinated and cyclized rubber derivatives provide chemical resistance in marine and industrial protective applications.
Volume concentration sits with Tires; margin expansion sits with Adhesives.
End User:
Automotive procurement patterns are restructuring supplier relationships through direct farmgate partnerships and long-term offtake contracting.
- Automotive:Tire manufacturers with net-zero commitments are locking in feedstock security through Southeast Asian cooperative agreements, bypassing merchant traders. EUDR compliance timelines are compressing supplier qualification windows.
- Consumer Goods:Footwear and household product manufacturers prioritize crepe and pale crepe grades for aesthetic and tactile properties.
- Industrial:Conveyor belting, vibration isolation, and matting applications absorb lower-specification grades with less stringent traceability requirements.
- Construction:Waterproofing membranes and expansion joint seals demand chlorinated rubber grades with weathering resistance.
Procurement leverage concentrates in Automotive; specification tolerance permits Industrial.
Distribution Channel:
Digital traceability infrastructure is enabling processor-direct relationships that displace traditional trader intermediation.
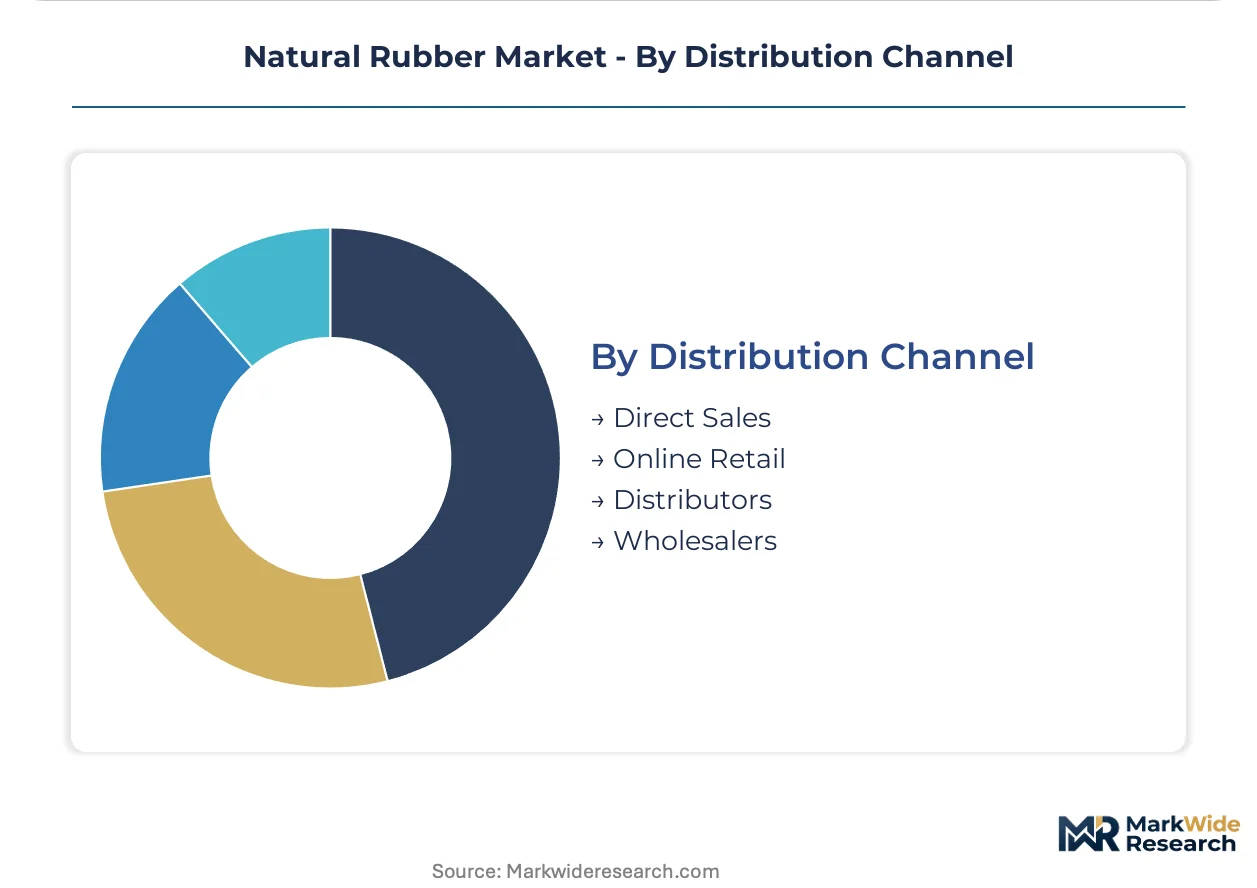
- Direct Sales:Integrated tire manufacturers are contracting directly with Thai Rubber Authority-certified cooperatives for volume security and EUDR-compliant documentation.
- Distributors:Regional processors maintain relationships with compounders requiring smaller lot sizes and technical support.
- Wholesalers:Commodity grades flow through Singapore and Rotterdam trading hubs for spot market procurement.
- Online Retail:Specialty liquid and reclaimed rubber grades are penetrating small-scale adhesive and coating formulators through B2B platforms.
Contract security favors Direct Sales; spot flexibility favors Wholesalers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in natural rubber are tightening as EUDR compliance costs reshape trade flows. Thailand and Indonesia remain net exporters while major tire-producing economies deepen direct procurement ties with Southeast Asian cooperatives.
Thailand
Thai Rubber Authority-certified cooperatives are digitizing farm-level traceability ahead of December 2025 EUDR deadlines. The national ISO 17065-aligned sustainability scheme is absorbing documentation costs for smallholders. Processing clusters in Songkhla and Surat Thani provinces are consolidating merchant trader functions into cooperative-direct sales channels.
Indonesia
Indonesia's Ministry of Agriculture is harmonizing domestic certification with EU market access requirements. Smallholder farms in North Sumatra and West Kalimantan face 18-24 month satellite mapping implementation timelines. Jakarta-based processors are locking in long-term offtake contracts with German and Japanese tire manufacturers.
China
China's tire manufacturers are qualifying Thai and Indonesian suppliers through EUDR-compliant documentation tiers. MIIT standards for tire labeling are pulling domestic procurement toward technically specified grades. Processing capacity in Hainan province is expanding devulcanization capabilities for reclaimed rubber integration.
India
India's PLI scheme for rubber product manufacturing is attracting downstream tire investment that could reduce Southeast Asian import dependence. Kerala and Tamil Nadu smallholder networks are piloting blockchain-enabled aggregation platforms. Domestic processors in Kochi are qualifying for direct supply relationships with automotive OEMs.
Germany
German tire manufacturers with 2030 scope 3 reduction targets are contracting directly with Southeast Asian cooperatives. ECHA's REACH Annex XVII updates on PAH restrictions are forcing compound reformulation costs onto Asian exporters. Continental and Michelin operations in Hanover and Frankfurt are absorbing testing infrastructure investments.
Natural Rubber Market Key Industry Players
Concentration sits with integrated tire manufacturers and polymer science specialists rather than commodity traders. The supplier base fragments across plantation-backed processors, merchant intermediaries, and compound engineering firms. Three archetypes dominate: Southeast Asian cooperative aggregators with EUDR-compliant documentation, Japanese and Korean polymer modification specialists, and integrated tire OEMs with captive sourcing. Competitive moves center on direct farmgate partnerships displacing spot procurement and devulcanization technology licensing for reclaimed rubber specification advancement.
Within the polymer science tier, JSR Corporation and Kumho Petrochemical Company Ltd. exemplify specification-driven positioning. JSR Corporation leverages rubber hydrocarbon expertise for high-performance compound development. Kumho Petrochemical Company Ltd. anchors modified natural rubber grades for electric vehicle tire applications. The Goodyear Tire and Rubber Company represents the integrated OEM archetype, sustaining Southeast Asian cooperative relationships through long-term volume contracts. Asahi Kasei Corporation and Denka Company Ltd. occupy positions in specialty rubber derivative segments.
| Leading Market Players |
|---|
| The Dow Chemical Company |
| JSR Corporation |
| Sinopec |
| Kumho Petrochemical Company Ltd. |
| Asahi Kasei Corporation |
| The Goodyear Tire and Rubber Company |
| DuPont |
| Denka Company Ltd. |
| Exxon Mobil Corporation |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracting locks in both feedstock security and price visibility for tire manufacturers with net-zero commitments, anchoring volume through direct Thai and Indonesian cooperative agreements while compressing spot market liquidity.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure, with EUDR-compliant certified grades commanding premiums over undocumented commodity rubber. Price differentiation rests on certification tier and volume scale, with ISO 17065-aligned documentation driving tier separation. Cost compression in standard technically specified rubber grades is intensifying because synthetic blend substitution erodes natural rubber's volume core. Smallholder-dependent cooperatives exhibit highest price sensitivity due to margin pressure from traceability infrastructure investments, while integrated tire OEMs with captive sourcing demonstrate lowest sensitivity.
Supply Chain Analysis
Inventory cycles in Southeast Asian processing hubs run 6-8 weeks longer than historical norms as EUDR documentation requirements extend qualification timelines. Geographic supply concentrates in Thailand, Indonesia, and Vietnam, with raw material dependencies on latex harvest labor, satellite mapping infrastructure, and devulcanization reagents. Single-source vulnerability from smallholder farm concentration creates feedstock security risks. Distribution runs through processor-direct channels displacing Singapore and Rotterdam merchant traders for EUDR-compliant volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as automotive tire production rebounds from inventory destocking and EUDR compliance deadlines concentrate procurement activity.
For Market Incumbents: Secure EUDR-compliant smallholder cooperative partnerships ahead of enforcement deadlines to lock in feedstock access. Deepen backward integration into Thai and Indonesian processing capacity to control documentation costs. Defend against synthetic rubber substitution by advancing epoxidized natural rubber specifications for EV tire platforms.
For New Entrants and Emerging Players: Blockchain-enabled traceability services represent a service-layer gap where incumbents under-serve smallholder cooperatives facing 18-24 month implementation timelines. Target Indian processing capacity expansion under PLI scheme incentives as the most penetrable geography. Pursue devulcanization technology licensing agreements with German and Japanese OEMs seeking circular economy procurement pathways.
For Investors and Strategic Acquirers: Capital is best deployed toward plantation-backed processors with polymer modification capabilities and existing EUDR documentation infrastructure. Long-term viability over a 5-10 year window favors suppliers with technical specification advancement expertise rather than commodity traders. Monitor smallholder digital traceability platform adoption rates as the key inflection signal for cooperative-direct channel displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Processing Capacity | Thai and Indonesian cooperative partnerships secure EUDR-compliant feedstock access for tire manufacturers. |
| Devulcanization Technology Licensing | Reclaimed rubber specification advancement opens circular economy procurement pathways with German OEMs. |
| Blockchain Traceability Platform Deployment | Satellite mapping infrastructure enables smallholder cooperatives to meet December 2025 EUDR deadlines. |
| Epoxidized Natural Rubber Capacity Expansion | ENR50 and ENR25 grades capture premium EV tire specifications from Bridgestone and Michelin. |
| Direct Farmgate Partnership Structuring | Long-term offtake contracts displace merchant trader intermediation for volume security. |
Research Approach
A standing panel of tire manufacturer procurement directors, Thai Rubber Authority certification officers, Indonesian Ministry of Agriculture officials, polymer compound engineers, and merchant trading house executives provided ongoing calibration across primary interviews. Secondary validation drew from customs and trade data, ISO 17065 certification registries, SEC filings from listed tire OEMs, and ECHA REACH substance restriction updates. Bottom-up volume modeling from smallholder farm clusters and top-down demand estimation from automotive production forecasts were triangulated for consistency.
Outputs were validated against external benchmarks including regional export statistics and tire manufacturer raw material disclosure filings across the analysis window. Segmentation dimensions modeled encompass product grade tier, application load-bearing specification, end-user industry vertical, and regional processing hub concentration. CAGRs were derived from regression analysis of historical production volumes against automotive tire shipment patterns and EUDR implementation timeline assumptions.
Underlying assumptions cover EUDR enforcement adherence, smallholder cooperative digitization completion, and synthetic rubber substitution elasticity, with deviation risk concentrated in climate-induced yield volatility and tapper labor availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Foam Materials Market
Rubber
Rubber Splicing Tape Market
Rubber
Tire Chemicals Market
Rubber
Specialty Nitrile Butadiene Rubber (NBR) Market
Rubber
Pre-Dispersed Rubber Chemicals Market
Rubber
Corrosion Protection Rubber Linings and Coatings Market
Rubber
Rubber Carbon Black Market
Rubber
Silicone Rubber Market
Rubber
Carboxylated Nitrile Rubber Market
Rubber
Global Liquid Synthetic Rubber Market
Rubber
Liquid Silicone Rubber Market
Rubber
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Rubber
Polybutadiene Market
Rubber
Recycled Elastomers Market
Rubber
Global Medical Rubber Stopper Market
Rubber
Chloro-Sulfonated Polyethylene Market