
 Global Medical Rubber Stopper Market | 2026-2036
Global Medical Rubber Stopper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Rubber Stopper Market Foresight
ISO 8871-3 qualification for elastomeric closures is reorganizing supplier tiers, as only manufacturers with validated washing and siliconization lines retain access to multinational pharmaceutical contracts. Dätwyler Holding Inc. leverages its Swiss manufacturing base to dominate high-purity chlorobutyl grades for biologics. West Pharmaceutical Services, Inc. sustains North American vaccine vial supply through integrated coating technologies. Samsung Medical Rubber Co., Ltd. anchors Asian production with automated vision-inspection systems that reduce particle contamination.
Medical rubber stoppers are elastomeric seals manufactured from halobutyl or silicone compounds, designed to maintain container integrity while permitting needle penetration for parenteral drug delivery; they must meet particle count, self-sealability, and extractables thresholds defined by pharmacopeial standards. Bromobutyl rubber stoppers lead volume due to their low gas permeability and inertness with protein-based formulations, while silicone variants capture premium positioning for lyophilized and high-viscosity injectables where needle glide force matters. Vaccine vials and injectable drugs together concentrate the largest application demand, with diagnostic kits representing a faster-growing segment as point-of-care testing expands.
FDA container closure guidance, EU MDR Annex I general safety requirements, and ISO 8871 series standards collectively govern extractables profiles, biocompatibility testing, and post-market surveillance obligations for elastomeric closures. These frameworks force manufacturers to maintain dedicated regulatory affairs teams and region-specific dossiers, raising fixed costs that favor scaled producers. Stakeholders must monitor how USP <381> elastomeric closures revisions and the EU F-Gas Regulation's indirect effects on halobutyl feedstock costs reshape total cost of ownership calculations for stopper procurement.
Market Dynamics
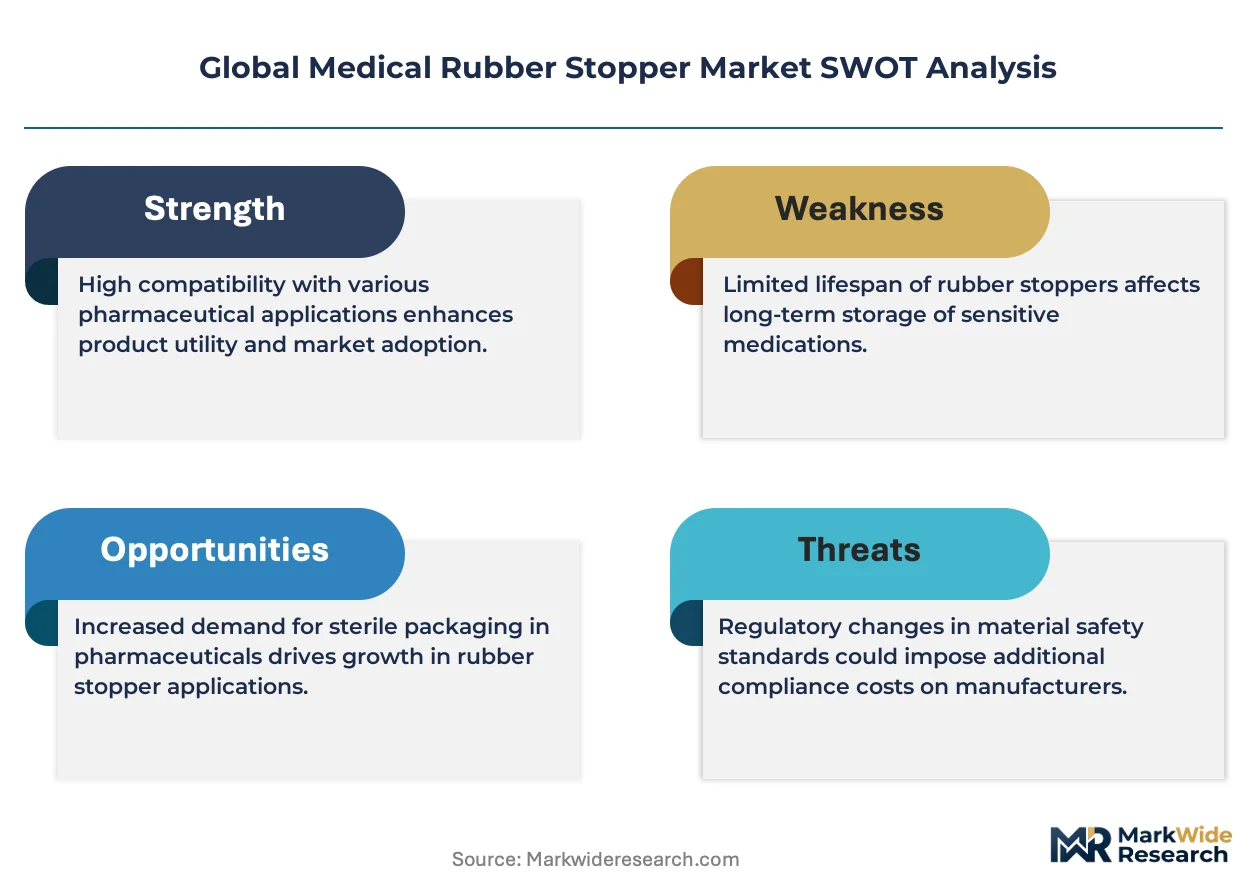
ISO 8871-3 qualification requirements are reorganizing supplier tiers, washing out smaller manufacturers lacking validated siliconization lines while concentrating contract awards among scaled producers with dedicated regulatory affairs infrastructure.
Growth Catalysts
- EU MDR Annex I enforcement:Tightened general safety requirements for container closure systems are forcing drug manufacturers to upgrade elastomer specifications, directly expanding demand for pharmacopeia-grade stoppers.
- Biologics manufacturing expansion:Protein-based injectable therapies require halobutyl formulations with ultra-low extractables profiles, pulling premium stopper volumes into sterile packaging supply chains.
- Point-of-care diagnostic proliferation:Rapid testing kits utilizing pre-filled syringes and vial configurations are creating incremental demand outside traditional hospital pharmacy channels.
Market Restraints
- Halobutyl feedstock volatility:Chlorine and bromine derivative costs fluctuate with EU F-Gas Regulation compliance burdens, compressing margins for non-integrated compounders.
- Supplier concentration in East Asia:Automated vision-inspection capacity clusters in China and South Korea, creating single-source risk for Western pharmaceutical fill-finish operations.
- Silicone alternative limitations:High gas permeability in silicone stoppers restricts their deployment in oxygen-sensitive biologics, capping premium segment expansion.
Strategic Opportunities
- Indian parenteral manufacturing:CDSCO's streamlined medical device regulations and PLI scheme incentives are attracting sterile injectable investments requiring qualified closure supply.
- Cell and gene therapy packaging:Cryogenic storage requirements for CAR-T therapies favor specialized elastomer formulations with validated low-temperature performance.
- Direct-to-pharma distribution platforms:Digital procurement channels are disintermediating traditional medical product distributors, enabling stopper manufacturers to capture margin through direct technical service relationships.
Industry Challenges
- Extractables testing capacity:USP <381> revision compliance requires advanced chromatography and mass spectrometry capabilities that strain mid-tier quality laboratories.
- Siliconization process validation:FDA container closure guidance demands documented particle control during elastomer coating, extending qualification timelines for new production lines.
- Cross-functional regulatory expertise:Dossier preparation spanning ISO 8871, pharmacopeial standards, and regional medical device frameworks requires rare combined chemistry and regulatory affairs skill sets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Rubber Stopper Market |
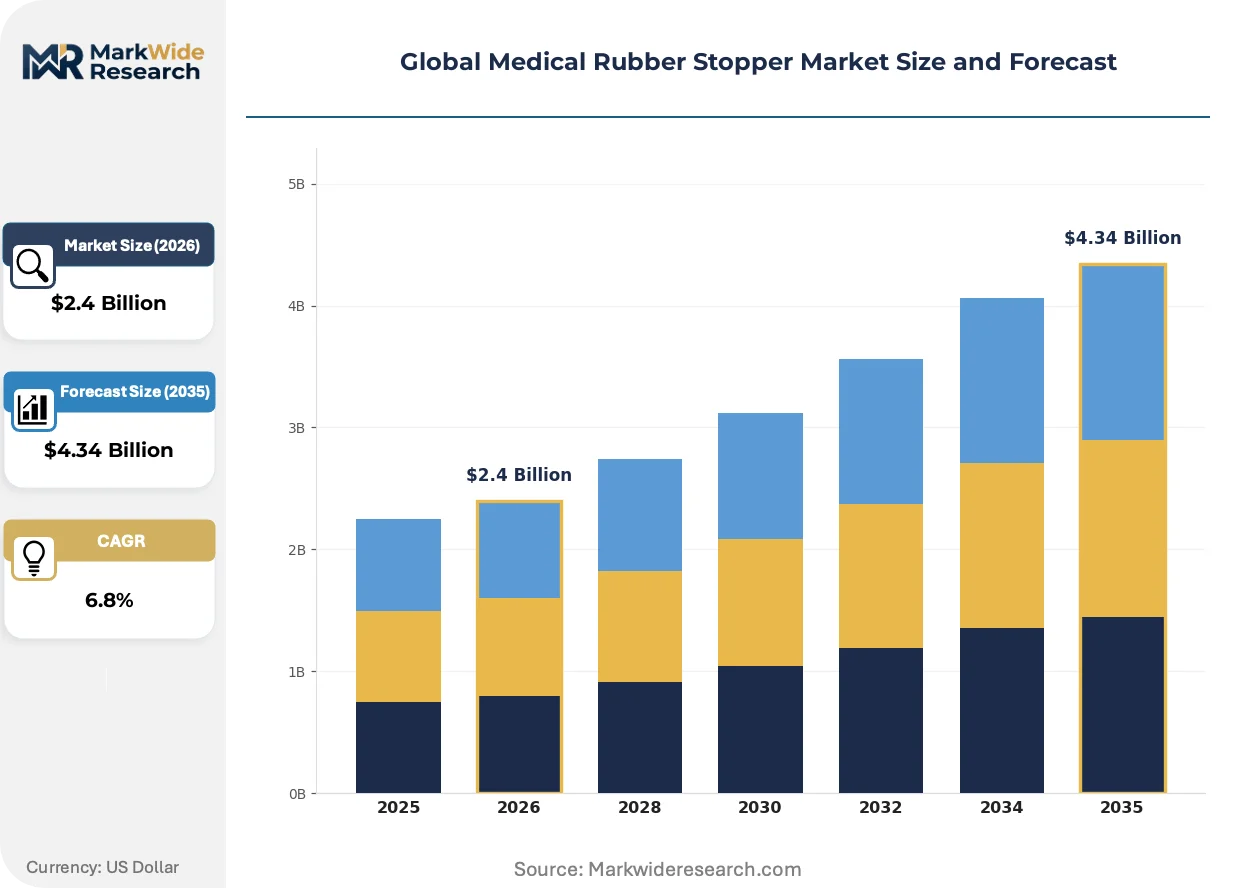
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Rubber Stopper, Butyl Rubber Stopper, Silicone Rubber Stopper, Chlorobutyl Rubber Stopper, Bromobutyl Rubber Stopper Application: Vaccine Vials, Injectable Drugs, Blood Collection Tubes, Diagnostic Kits, Pharmaceutical Bottles End User: Pharmaceutical Manufacturers, Biotechnology Firms, Diagnostic Laboratories, Contract Research Organizations, Healthcare Facilities Packaging Type: Blister Packs, Bulk Packaging, Sterile Packaging, Pouch Packaging, Tray Packaging |
| Companies Covered | West Pharmaceutical Services, Inc., Dätwyler Holding Inc., AptarGroup, Inc., Schott AG, Samsung Medical Rubber Co., Ltd., Hualan NPM, Hubei Huaqiang High-Tech Co., Ltd., Jiangsu Best New Medical Material Co., Ltd., Gerresheimer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Rubber Stopper Market Shifts & Advancements
Functional coating technologies and automated inspection systems are compressing defect rates while regulatory data integrity requirements are reshaping how manufacturers document batch release. These forces are converging to redefine competitive differentiation beyond base elastomer formulation.
Plasma-enhanced coating deposition is miniaturizing. This vacuum-based surface modification technology applies nanometer-scale barrier layers to halobutyl substrates, reducing drug-container interaction without thick silicone coatings. Vaccine manufacturers in Germany and the United States are piloting these systems for mRNA lipid nanoparticle formulations. The technology is miniaturizing equipment footprints from cleanroom-scale to isolator-integrated modules, enabling distributed qualification labs closer to pharmaceutical fill-finish sites.
REACH Annex XVII restrictions on persistent organic pollutants are tightening impurity thresholds for rubber processing aids. ECHA's updated guidance on short-chain chlorinated paraffins is forcing compounders to reformulate vulcanization accelerators and plasticizers across European supply chains. Bromobutyl grades destined for EU pharmaceutical markets now require extended supply chain documentation, with raw material certificates of analysis extending three tiers upstream to petrochemical feedstock.
Consolidated buying desks at multinational biopharmaceutical firms are compressing supplier qualification cycles. Procurement functions in Basel, Boston, and Shanghai now coordinate global stopper tenders through centralized technical committees, replacing regional purchasing autonomy. This pattern concentrates contract awards among manufacturers with multi-site ISO 8871-3 certifications and harmonized quality management systems, disadvantaging single-facility specialists even when technically qualified.
Global Medical Rubber Stopper Market Segmentation
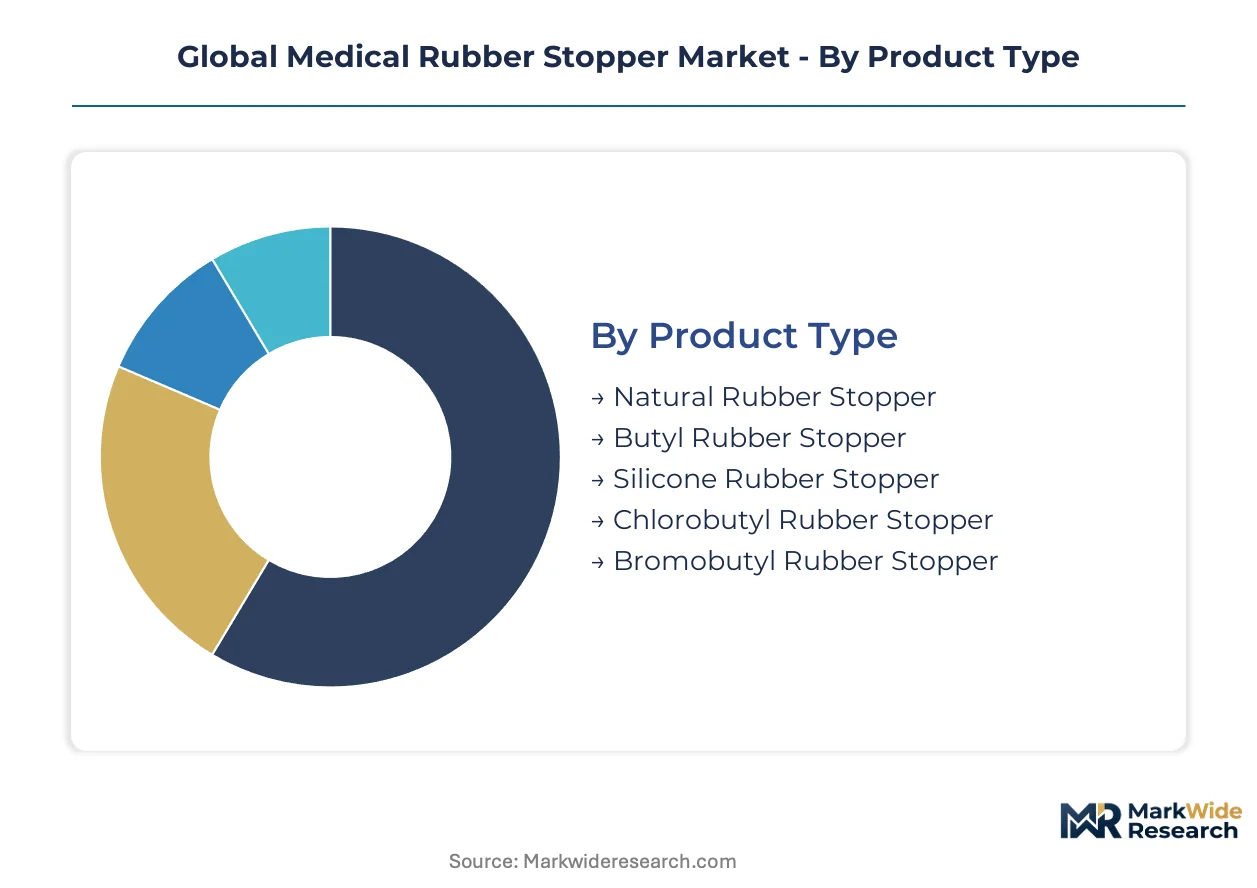
Medical rubber stopper procurement decisions hinge on extractables profiles, sterilization compatibility, and regulatory qualification status. Segmentation reveals how material chemistry, end-use sterility requirements, and packaging format collectively determine supplier selection criteria and contract value concentration.
Product Type:
Domestic production of natural and butyl grades dominates supply in India and China, while chlorobutyl and bromobutyl variants move through export-led channels serving European and North American biopharmaceutical fill-finish operations.
- Bromobutyl Rubber Stopper:Halogenated isobutylene-isoprene copolymer delivers ultra-low gas permeability and inertness with protein-based formulations. Demand concentrates in German and US vaccine manufacturing hubs where FDA container closure guidance mandates validated extractables profiles for parenteral applications.
- Chlorobutyl Rubber Stopper:Chlorinated variant offers superior moisture barrier properties and reduced sulfur content for sensitive biologics. Swiss and German sterile packaging specialists specify this grade for monoclonal antibody vials, pulling premium volumes through qualified supply chains.
- Silicone Rubber Stopper:Elastomeric seals optimized for lyophilized products requiring low needle penetration force; limited by oxygen permeability constraints in oxygen-sensitive formulations.
- Butyl Rubber Stopper:Standard halobutyl base compound serving generic injectable markets with balanced cost-performance profiles; volume production centers on East Asian compounders.
- Natural Rubber Stopper:Legacy formulation declining in pharmaceutical applications due to higher protein and allergen extractables; residual demand persists in certain diagnostic and veterinary segments.
Bromobutyl commands the established base. The steepest expansion runs through chlorobutyl as EU MDR Annex I enforcement tightens elastomer specifications for biologics.
Application:
Cost tier stratification separates high-value sterile injectable applications from commodity diagnostic formats, with vaccine vials and biologics commanding qualification-intensive supply relationships.
- Vaccine Vials:Multi-dose and single-dose glass vial configurations requiring validated self-sealability after multiple needle penetrations. US and German mRNA vaccine manufacturers specify plasma-coated halobutyl grades to minimize lipid nanoparticle interaction.
- Injectable Drugs:Parenteral therapy containers spanning insulin, oncology, and anticoagulant formulations. Chinese and Indian sterile fill-finish expansion is pulling volume demand for ISO 8871-3 qualified closures through regional supply chains.
- Diagnostic Kits:Point-of-care and laboratory testing configurations utilizing pre-filled syringes and sample vials. CDSCO's streamlined device regulations in India are accelerating local production of kit-compatible stopper formats.
- Blood Collection Tubes:Vacuum-sealed evacuated tube systems requiring precise elastomer compression set and gas barrier properties; specifications governed by CLSI standards.
- Pharmaceutical Bottles:Oral and topical liquid containers with less stringent extractables requirements; price-sensitive segment served by standard butyl compounds.
Injectable drugs anchor volume demand. Diagnostic kits are climbing the fastest as decentralized testing infrastructure expands across Asia-Pacific and Latin American markets.
End User:
Customer type determines procurement complexity, with multinational pharmaceutical manufacturers imposing harmonized global specifications while regional healthcare facilities accept distributor-tier products.
- Pharmaceutical Manufacturers:Integrated fill-finish operations at firms like those in Basel, Boston, and Shanghai requiring multi-site qualified supply with harmonized quality management systems and dedicated regulatory affairs support.
- Biotechnology Firms:Cell and gene therapy developers specifying cryogenic-validated elastomer formulations for CAR-T preservation; smaller batch sizes with premium pricing tolerance.
- Diagnostic Laboratories:High-throughput clinical testing operations consuming standardized blood collection and sample tube closures; procurement through consolidated medical product distributors.
- Contract Research Organizations:Clinical trial material packaging requiring flexible batch sizes and rapid qualification timelines; price-sensitive with limited long-term contract commitments.
- Healthcare Facilities:Hospital pharmacies and clinics sourcing through group purchasing organizations; generic product acceptance with emphasis on immediate availability.
Pharmaceutical manufacturers dominate contract value. Biotechnology firms are gaining share fastest as cell therapy pipelines mature toward commercial manufacturing.
Packaging Type:
Supply concentration clusters on sterile packaging formats where automated vision-inspection and siliconization capabilities create qualification barriers, while bulk and pouch formats accommodate smaller compounders.
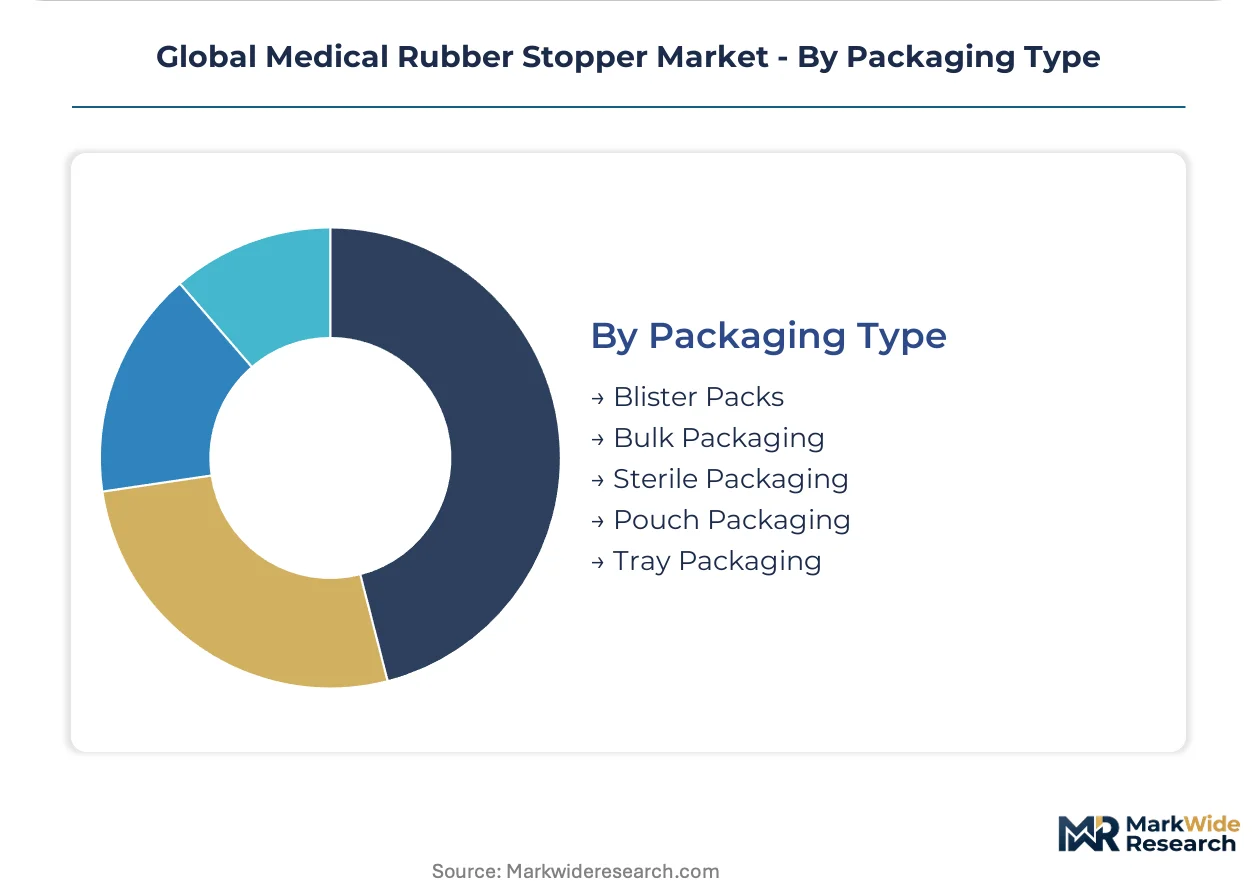
- Sterile Packaging:Pre-sterilized, individually wrapped closures delivered directly to isolator-equipped fill-finish lines. South Korean and Chinese manufacturers with automated particle inspection systems supply Western vaccine producers under long-term agreements.
- Bulk Packaging:Unwashed, uncoated elastomer components shipped in polyethylene liners for downstream processing. Indian compounders serving domestic parenteral manufacturers leverage this format to avoid capital-intensive finishing investments.
- Blister Packs:Medical-grade PET or PVC tray configurations for single-unit dispensing; common in diagnostic kit assembly.
- Pouch Packaging:Tyvek or foil laminate pouches providing moisture and particulate protection for non-sterile applications.
- Tray Packaging:Rigid container systems for automated stopper feeding equipment in high-speed pharmaceutical production lines.
Sterile packaging captures the premium tier. Bulk formats are expanding most quickly in cost-sensitive emerging manufacturing regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational pharmaceutical procurement offices in Basel, Boston, and Shanghai coordinate global stopper tenders through centralized technical committees. This pattern concentrates contract awards among manufacturers with multi-site ISO 8871-3 certifications. Regional production clusters align with parenteral drug manufacturing hubs and regulatory enforcement intensity.
United States
FDA container closure guidance mandates validated extractables profiles for parenteral applications. mRNA vaccine manufacturers in Massachusetts and North Carolina specify plasma-coated halobutyl grades to minimize lipid nanoparticle interaction. The Boston-Cambridge biotech corridor anchors premium stopper demand for cell and gene therapy packaging.
Germany
EU MDR Annex I enforcement tightens elastomer specifications for biologics manufacturing. ECHA's REACH Annex XVII restrictions on persistent organic pollutants force compounders to reformulate vulcanization accelerators. The Rhine-Main pharmaceutical cluster around Frankfurt drives chlorobutyl demand for monoclonal antibody vials.
China
CDSCO-aligned regulatory harmonization accelerates sterile injectable investments requiring qualified closure supply. NMPA's updated pharmaceutical packaging standards elevate extractables testing protocols. The Yangtze River Delta concentration of fill-finish operations pulls volume demand through regional supply chains.
Switzerland
Swissmedic's stringent biocompatibility requirements favor high-purity chlorobutyl grades for biologics. The country's pharmaceutical headquarters economy generates specification-setting power for global stopper procurement. Basel-based multinational firms impose harmonized quality management systems across their supplier networks.
India
CDSCO's streamlined medical device regulations and PLI scheme incentives attract sterile injectable investments. Domestic production of natural and butyl grades dominates supply for regional parenteral manufacturers. The Hyderabad-Bengaluru pharmaceutical corridor expands ISO 8871-3 qualified capacity for export markets.
Global Medical Rubber Stopper Market Competitive Landscape
Player mix skews toward integrated pharmaceutical packaging specialists with validated washing and siliconization lines. The supplier base concentrates among scaled producers maintaining dedicated regulatory affairs infrastructure and multi-site quality certifications. Two strategic archetypes dominate: Swiss-German precision compounders serving premium biologics segments and East Asian manufacturers leveraging automated vision-inspection systems. Competitive moves center on plasma-enhanced coating technology licensing and direct-to-pharma distribution platform development.
Within the integrated packaging tier, West Pharmaceutical Services, Inc. and Dätwyler Holding Inc. exemplify the regulatory-heavy archetype with Swiss and North American manufacturing bases. Samsung Medical Rubber Co., Ltd. anchors the automated production vector among Korean specialists. These three occupy positions that reflect the market's bifurcation between premium biologics qualification and high-volume sterile packaging efficiency.
| Leading Market Players |
|---|
| West Pharmaceutical Services, Inc. |
| Dätwyler Holding Inc. |
| AptarGroup, Inc. |
| Schott AG |
| Samsung Medical Rubber Co., Ltd. |
| Hualan NPM |
| Hubei Huaqiang High-Tech Co., Ltd. |
| Jiangsu Best New Medical Material Co., Ltd. |
| Gerresheimer AG |
| Others |
Supply & Pricing Matrix
Validated siliconization line capacity in Switzerland and South Korea sets minimum efficient scale thresholds that filter out sub-scale compounders and establish price floors for pharmacopeia-grade supply. This concentration of qualified finishing infrastructure concentrates pricing power among ISO 8871-3 certified manufacturers while forcing regional buyers to absorb logistics premiums for cross-continental delivery.
Pricing Analysis
Cost-plus contracts with chlorine and bromine derivative indexation dominate long-term pharmaceutical supply agreements. Pricing stratifies across premium chlorobutyl for biologics, standard bromobutyl for vaccines, and economy butyl for generic injectables. Cost compression in the economy tier is intensifying because Indian compounders are expanding unwashed bulk output. Contract research organizations exhibit the highest price sensitivity; Swiss biologics manufacturers the least.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German and US vaccine manufacturers, while strategic stockpiling characterizes Chinese fill-finish operations buffering against halobutyl feedstock volatility. Supply concentrates in Switzerland, South Korea, and China. Bromine and chlorine derivatives, silicone oils, and halobutyl rubber feed the manufacturing base. Single-source vulnerability runs through automated vision-inspection equipment concentrated in East Asia. Distribution runs through direct technical service relationships with multinational pharmaceutical procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as cell and gene therapy packaging demands splinter the incumbent biologics-centric supply model, creating niches for cryogenic-validated specialists outside traditional vaccine and monoclonal antibody supply chains.
For Market Incumbents: Compound regulatory affairs capabilities through dedicated dossier teams spanning ISO 8871, USP, and EU MDR frameworks to defend against emerging Asian compounders with automated inspection cost advantages. Prioritize backward integration into halobutyl rubber compounding to buffer margin pressure from EU F-Gas Regulation feedstock cost volatility.
For New Entrants and Emerging Players: Technical service gaps in rapid qualification timelines for clinical trial materials present immediate white-space opportunity. Target Indian parenteral manufacturing expansion under CDSCO's streamlined device regulations. Pursue direct-to-pharma distribution platforms disintermediating traditional medical product distributors.
For Investors and Strategic Acquirers: Regional compounders with ISO 8871-3 certification gaps but established customer relationships in emerging fill-finish markets represent the most actionable acquisition archetype. Long-term viability hinges on regulatory qualification moat durability against automated production technology diffusion. Watch for plasma-enhanced coating technology licensing deals as inflection signal for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Plasma-Enhanced Coating Licensing | mRNA vaccine manufacturers in Germany and the United States pilot nanometer-scale barrier layers to minimize lipid nanoparticle interaction. |
| Automated Vision-Inspection Scale-Up | South Korean and Chinese manufacturers reduce particle contamination rates to meet FDA container closure guidance for sterile packaging. |
| Direct-to-Pharma Distribution Platform | Stopper manufacturers capture margin through technical service relationships bypassing traditional medical product distributors. |
| Cryogenic Formulation Validation | Cell and gene therapy developers specify elastomer performance for CAR-T preservation at ultra-low temperatures. |
| REACH Annex XVII Compliance Reformulation | European compounders replace short-chain chlorinated paraffins in vulcanization accelerators to maintain EU market access. |
Research Methodology
Operator-level perspectives from regulatory affairs directors, pharmaceutical procurement managers, sterile fill-finish engineers, and elastomer compounder technical leads anchored the qualitative base. Primary interviews combined with secondary validation from FDA container closure guidance documents, EMA MDR implementation guidance, ISO 8871 series standards, and customs trade data for halobutyl rubber derivatives. Bottom-up demand modeling and top-down supply capacity assessment provided triangulation.
Sensitivity analysis tested forecast robustness across feedstock cost volatility scenarios and regulatory enforcement intensity variations. Segmentation dimensions modeled include material chemistry grade, packaging sterility requirement, end-use therapeutic category, and regional regulatory cluster. CAGRs derived from compound growth mechanics applied to base-year volume estimates. Industry-specific inputs incorporated biologics pipeline maturation rates and point-of-care diagnostic kit proliferation trends.
Underlying assumptions cover stable EU MDR enforcement timelines and halobutyl feedstock supply continuity, with deviation risk concentrated in REACH Annex XVII restriction expansion and F-Gas Regulation cost pass-through magnitude. Forecasts reflect these conditions holding across the analysis window. Revision becomes warranted when CDSCO regulatory harmonization pace or plasma-coating technology adoption rates cross material thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Performance Elastomers Market
Rubber
Polyisoprene Rubber Market
Rubber
Styrene Butadiene Rubber (E-SBR and S-SBR) Market
Rubber
Silica for S-SBR Market
Rubber
Flexible Rubber Sheets Market
Rubber
Liquid Silicone Rubber Market
Rubber
Polybutadiene Rubber (PBR) Market
Rubber
Global Thermoplastic Vulcanizate (TPV) Market
Rubber
Rubber Foam Materials Market
Rubber
Cellular Rubber Market
Rubber
Rubber Compound Market
Rubber
Isobutylene Market
Rubber
Chloroprene Rubber Modified Asphalt Emulsion Market
Rubber
EMEA and Asia Pacific Electrical Insulating Rubber Gloves Market
Rubber
EPDM Market
Rubber
Tire Chemicals Market