
 Global Liquid Synthetic Rubber Market | 2026-2036
Global Liquid Synthetic Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liquid Synthetic Rubber Market Foresight
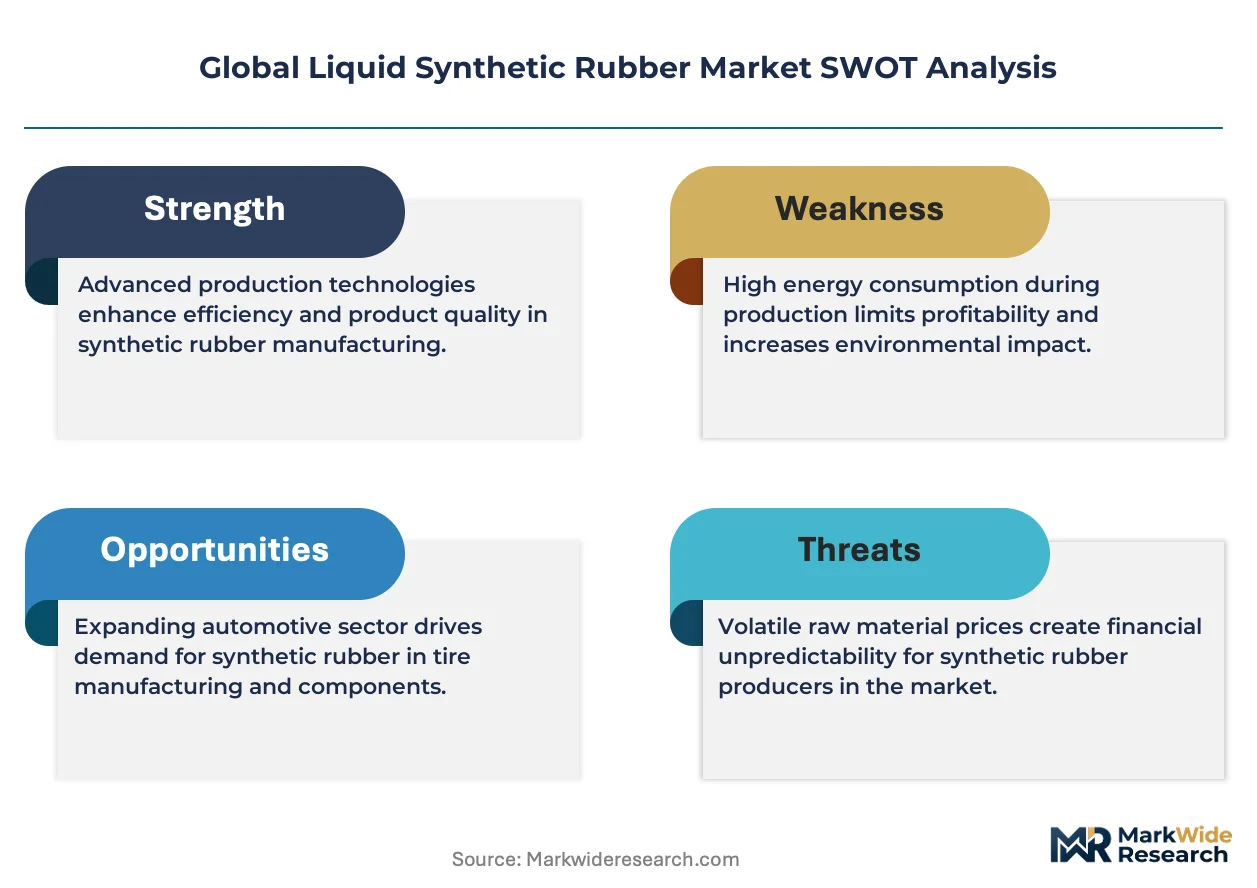
Conventional solid synthetic rubber is shifting toward liquid analogs in adhesive and sealant formulations, driven by processing efficiency gains and solvent-reduction mandates. Evonik Industries AG leverages its specialty additives portfolio to anchor premium positions in reactive liquid rubber for epoxy toughening. Synthomer plc sustains European supply leadership through integrated emulsion polymerization assets. Kuraray Co., Ltd. differentiates via specialized liquid isoprene technologies serving precision automotive applications.
Liquid synthetic rubber denotes low-molecular-weight elastomeric polymers with viscosities typically below 100,000 mPa·s at room temperature, manufactured through controlled anionic or free-radical polymerization to enable pourable processing without mechanical mastication. These materials function primarily as reactive modifiers, primary binders, and soft-segment precursors in formulations demanding elasticity combined with liquid-state processability. Styrene-butadiene liquid rubber dominates volume flows across adhesive and sealant applications where hot-melt and UV-curable systems require tack-optimized flow characteristics. Nitrile liquid rubber commands margin concentration in oil-resistant gasket and fuel-hose compounding for automotive and aerospace end users. Polyisoprene grades represent the fastest-expanding category, propelled by medical-grade sealant demand and precision molding applications in electronics.
REACH registration requirements and EPA New Chemicals Program oversight govern monomer feedstock approvals and downstream formulation compliance, elevating testing burdens for new liquid rubber chemistries. ECHA substance evaluation protocols and evolving F-Gas Regulation frameworks indirectly shape demand by restricting competing fluorinated sealant technologies. ISO 1629 nomenclature standards and ASTM D1418 classification systems provide the technical vocabulary enabling cross-border specification and procurement. Stakeholders must monitor regulatory divergence between European hazard-based approaches and US risk-assessment methodologies when positioning liquid synthetic rubber platforms across multinational supply contracts.
Market Dynamics
Automotive electrification and REACH-mandated solvent reduction are compressing formulation windows, forcing liquid synthetic rubber suppliers to engineer reactive grades that cure faster at lower temperatures while maintaining oil resistance.
Growth Catalysts
- EPA New Chemicals Program:Accelerated monomer approvals for low-VOC liquid rubber systems are unlocking reformulation projects across US adhesive manufacturers.
- EV battery pack sealing:Thermal management demands in electric vehicles are pulling pourable liquid rubber into gap-filling and vibration-dampening applications previously served by solid elastomers.
- China's tire sector:Domestic producers are scaling solution-polymerized liquid rubber procurement to replace imported solid grades in tread compound modifications.
Market Restraints
- Butadiene feedstock volatility:Styrene-butadiene liquid rubber margins compress when naphtha-derived butadiene spot prices spike, squeezing formulators without backward integration into cracker operations.
- German supply concentration:European liquid isoprene capacity clusters around Ludwigshafen and Marl, creating single-source exposure for medical-grade sealant makers.
- Cure kinetics limitation:Room-temperature vulcanization speeds lag behind hot-melt polyurethane alternatives, restricting liquid rubber penetration in high-speed assembly lines.
Strategic Opportunities
- India's adhesive sector:Construction chemical formulators in Mumbai and Ahmedabad are underserved by reactive liquid rubber distributors, presenting white-space entry for technical service-focused suppliers.
- UV-LED curing convergence:Photoinitiator advances combined with liquid rubber oligomer design are enabling instant-cure sealant systems for electronics assembly.
- EU F-Gas Regulation:Restrictions on fluorinated sealants are redirecting aerospace gasket specifications toward hydrogenated nitrile liquid rubber grades.
Industry Challenges
- Anionic polymerization expertise:The specialized skill set for living polymerization control is scarce outside legacy synthetic rubber hubs, constraining new entrant process scale-up.
- ISO 1629 compliance timelines:Multi-year substance evaluation protocols delay novel liquid rubber nomenclature recognition, freezing specification updates in cross-border supply contracts.
- Legacy mixing equipment retrofit:Adhesive plants designed for solid rubber mastication require tank farm and metering system overhauls to handle liquid feedstocks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liquid Synthetic Rubber Market |
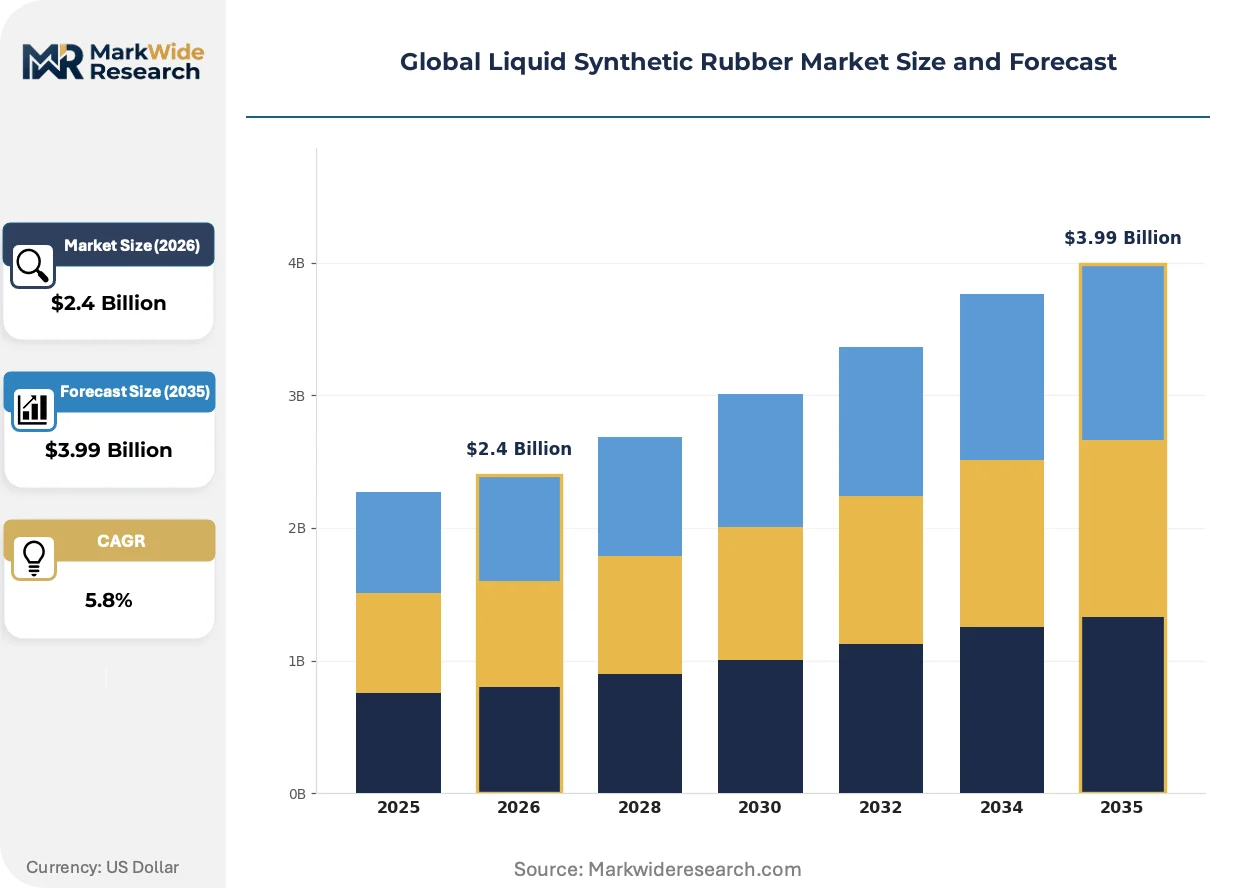
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Styrene-Butadiene, Nitrile, Polyisoprene, Ethylene-Propylene, Neoprene Application: Adhesives, Sealants, Coatings, Automotive Parts, Textile Finishing Manufacturing Stage: Polymerization, Emulsification, Crosslinking, Compounding, Formulation End User Industry: Construction, Electronics, Consumer Goods, Packaging, Aerospace |
| Companies Covered | Evonik Industries AG, Synthomer plc, Kuraray Co., Ltd., ENEOS Corporation, Asahi Kasei Corporation, NIPPON SODA CO., LTD., H.B. Fuller Company, Kumho Petrochemical, China National Petroleum Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liquid Synthetic Rubber Market Shifts & Advancements
Formulation chemistry is pivoting toward reactive liquid rubber architectures that eliminate mechanical mixing stages while satisfying multi-jurisdictional VOC limits.
Telechelic liquid rubber with defined end-group functionality is overtaking conventional non-reactive grades in structural adhesive formulations. Automotive tier-one suppliers in Stuttgart and Detroit are specifying hydroxyl-terminated polybutadiene for crash-durable bonding applications. This shift is compressing demand for solvent-borne solid rubber solutions that require extended drying cycles.
REACH authorization requirements for 1,3-butadiene are tightening monomer handling protocols across European polymerization facilities. Downstream formulators face elevated compliance documentation burdens when sourcing styrene-butadiene liquid rubber for consumer-facing adhesive products. German and French sealant manufacturers are responding by qualifying alternative feedstock streams from Middle Eastern butadiene producers.
Specification-driven procurement is consolidating buyer power among multinational automotive OEMs and medical device assemblers. Distributors serving mid-tier adhesive compounders in Southeast Asia are losing share to direct mill relationships with liquid rubber producers. This channel compression is most visible in Thailand and Vietnam, where domestic construction chemical growth outpaces technical service capacity at traditional trading houses.
Global Liquid Synthetic Rubber Market Segmentation
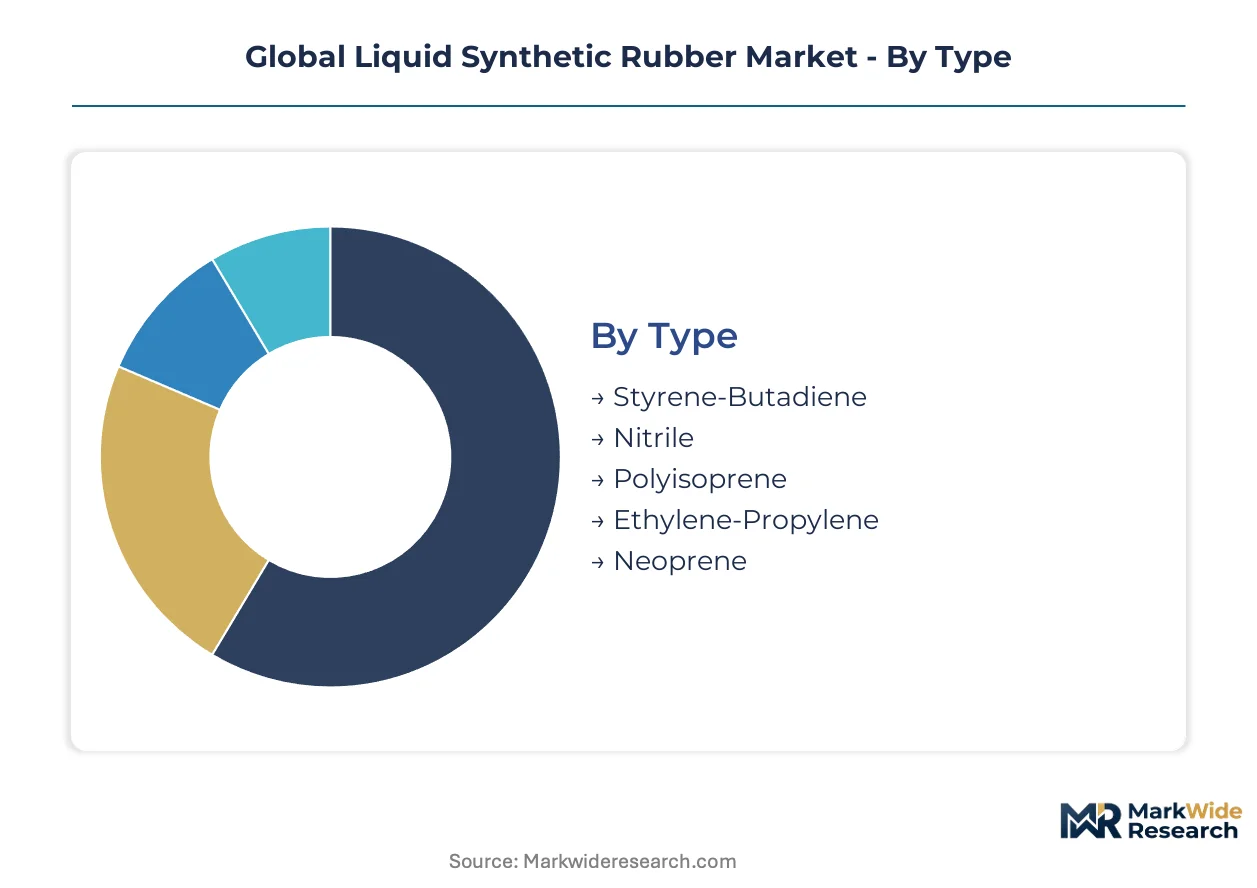
Liquid synthetic rubber segmentation reveals how molecular architecture and processing stage determine value capture across adhesive, automotive, and industrial end uses. Supplier portfolios concentrate around high-margin reactive grades while commodity flows serve volume construction applications.
Type:
Polymer chemistry dictates supply concentration, with butadiene-based capacity clustering around integrated petrochemical complexes and specialty grades requiring captive anionic polymerization expertise.
- Styrene-Butadiene:Random copolymer structure with 15-25% styrene content delivers optimized tack and flow characteristics for hot-melt adhesive systems. Procurement concentrates among German and Chinese sealant formulators seeking REACH-compliant, low-VOC alternatives to solvent-borne solid rubber.
- Nitrile:Acrylonitrile-butadiene copolymer with 18-50% acrylonitrile content provides oil and fuel resistance for under-the-hood gaskets and hose liners. Aerospace specification writers in Toulouse and Hamburg are qualifying hydrogenated grades to replace fluorinated sealants under EU F-Gas Regulation restrictions.
- Polyisoprene:Synthetic equivalent of natural rubber latex with controlled molecular weight distribution serves medical-grade sealant and precision electronics molding applications.
- Ethylene-Propylene:Saturated backbone copolymer delivers ozone and weathering resistance for outdoor construction sealants and roofing membranes.
- Neoprene:Chloroprene-based polymer offers flame resistance and chemical stability for industrial conveyor belt repair compounds and marine sealants.
Styrene-Butadiene absorbs the bulk of installed capacity; Polyisoprene is expanding most quickly.
Application:
End-use formulation requirements separate commodity volume markets from specification-driven premium positions where technical service and certification documentation command margin premiums.
- Adhesives:Reactive liquid rubber modifiers enable solvent-free structural bonding with crash-durable elasticity for automotive assembly. Tier-one suppliers in Stuttgart specify hydroxyl-terminated polybutadiene grades that cure at lower temperatures to protect adjacent electronics.
- Sealants:Pourable consistency eliminates mechanical mixing stages while accommodating movement joints in construction and transportation applications. Chinese high-speed rail projects are pulling specialized polysulfide-liquid rubber hybrid formulations for expansion joint durability.
- Coatings:Low-viscosity liquid rubber serves as flexible binder in corrosion-resistant pipeline and tank linings requiring film-forming elasticity.
- Automotive Parts:Vibration-dampening mounts and bushings utilize liquid rubber castable into complex geometries without compression molding equipment.
- Textile Finishing:Soft-hand coatings and non-slip treatments employ low-molecular-weight liquid rubber emulsions for fabric surface modification.
Adhesives command the deepest supplier-formulator technical partnerships; Sealants deliver the steepest expansion trajectory as construction chemical demand accelerates in Southeast Asia.
Manufacturing Stage:
Process step segmentation tracks where value addition occurs and where backward integration into monomer supply or forward integration into formulated products reshapes competitive economics.
- Polymerization:Controlled anionic or free-radical processes establish molecular weight and end-group functionality that determine downstream reactivity. Living polymerization expertise concentrates in Ludwigshafen, Marl, and select Japanese coastal industrial zones.
- Emulsification:Aqueous dispersion of liquid rubber enables waterborne adhesive formulations meeting EPA and ECHA VOC limits without solvent handling infrastructure.
- Crosslinking:Peroxide, sulfur, or moisture-cure systems transform liquid feedstocks into elastomeric networks; cure kinetics remain the primary constraint against high-speed assembly line adoption.
- Compounding:Addition of fillers, plasticizers, and stabilizers tailors viscosity and performance for specific application machinery and cure conditions.
- Formulation:Final blending with resins, pigments, and additives produces application-ready adhesive, sealant, or coating products.
Polymerization captures the highest fixed-asset barriers; Formulation is gaining share fastest as mid-tier compounders outsource captive rubber processing.
End User Industry:
Customer industry segmentation exposes diverging procurement patterns between specification-driven sectors with extended qualification timelines and price-sensitive volume buyers.
- Construction:Joint sealants, waterproofing membranes, and flooring adhesives consume bulk liquid rubber volumes. Indian formulators in Mumbai and Ahmedabad remain underserved by reactive grade distributors with local technical service presence.
- Electronics:Precision potting, encapsulation, and flexible circuit protection demand ultra-low ionic content and batch-to-batch consistency. Japanese semiconductor packaging houses specify telechelic grades with defined hydroxyl functionality for moisture-cure reliability.
- Consumer Goods:Footwear adhesives and DIY sealant cartridges represent high-volume, price-elastic demand sensitive to raw material cost fluctuations.
- Packaging:Flexible laminate adhesives for food contact applications require FDA and EFSA compliance documentation for migration testing.
- Aerospace:Fuel tank sealants and firewall gaskets specify hydrogenated nitrile grades with extended service temperature ranges and fire-resistant certifications.
Construction absorbs the majority of volume flows; Electronics is climbing the fastest as miniaturization and thermal management demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai Free-Trade Zone incentives have concentrated liquid synthetic rubber distribution hubs serving Asia-Pacific adhesive formulators. European REACH compliance costs and US EPA New Chemicals Program timelines are redrawing procurement geography.
China
Tire manufacturers in Shandong and Jiangsu provinces are scaling solution-polymerized liquid rubber procurement to modify tread compounds. MEE enforcement of GB standards on VOC emissions is accelerating waterborne adhesive adoption. Qingdao chemical parks host expanding emulsion polymerization capacity for construction sealant feedstocks.
Germany
Automotive tier-one suppliers in Stuttgart specify hydroxyl-terminated grades for crash-durable bonding applications. ECHA substance evaluation protocols under REACH tighten monomer handling documentation for consumer-facing products. Ludwigshafen and Marl industrial clusters retain concentrated liquid isoprene capacity for medical-grade sealant makers.
United States
EV battery pack assemblers in Michigan and Ohio are pulling pourable liquid rubber into thermal gap-filling applications. EPA New Chemicals Program accelerated approvals are unlocking reformulation projects across Midwest adhesive manufacturers. Detroit-area automotive R&D centers qualify reactive grades for lower-temperature cure cycles protecting adjacent electronics.
Japan
Semiconductor packaging houses in Kanto specify telechelic grades with defined hydroxyl functionality for moisture-cure reliability. METI guidance on chemical substance management shapes importer compliance documentation. Osaka-based electronics assemblers drive precision molding demand for ultra-low ionic content polyisoprene.
India
Construction chemical formulators in Mumbai and Ahmedabad remain underserved by reactive liquid rubber distributors with local technical service. BIS certification requirements for imported polymer feedstocks extend qualification timelines. Domestic adhesive compounders seek direct mill relationships bypassing traditional trading house channels.
Global Liquid Synthetic Rubber Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with specification-driven automotive and medical applications favoring technical service depth while construction volume flows to price-optimized suppliers. The vendor base clusters around three archetypes: integrated petrochemical majors with backward monomer control, specialty polymer houses with captive anionic polymerization expertise, and regional distributors with formulation technical support. Competitive moves center on direct mill relationships displacing traditional trading channels, and capacity expansion into underserved Indian and Southeast Asian markets.
Among European specialty polymer houses, Evonik Industries AG and Synthomer plc exemplify the premium-tier positioning anchored by reactive grade portfolios. Kuraray Co., Ltd. represents the Japanese specialist archetype with concentrated expertise in liquid isoprene technologies. These three occupy positions where specification documentation and qualification support command margin premiums over commodity volume plays.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Synthomer plc |
| Kuraray Co., Ltd. |
| ENEOS Corporation |
| Asahi Kasei Corporation |
| NIPPON SODA CO., LTD. |
| H.B. Fuller Company |
| Kumho Petrochemical |
| China National Petroleum Corporation |
| Others |
Supply & Pricing Matrix
REACH-mandated VOC reduction gates qualified supply access and premium-tier pricing power, forcing formulators to pay structural premiums for certified low-emission liquid rubber grades while spot buyers face exclusion from specification-driven automotive and medical procurement channels.
Pricing Analysis
Lead-time compression commands measurable premiums in liquid synthetic rubber procurement, with automotive tier-one suppliers paying above-base rates for hydroxyl-terminated polybutadiene delivered within contracted windows while spot purchasers of standard styrene-butadiene grades capture discounts from inventory liquidation events. Three-tier pricing structure across reactive specialty, standard industrial, and commodity construction grades differentiates by certification burden and technical service depth. Cost compression in commodity styrene-butadiene is intensifying because naphtha-derived butadiene spot volatility squeezes non-integrated formulators. Construction adhesive compounders in emerging markets exhibit the highest price elasticity, while medical-grade sealant makers accept substantial premiums for batch-to-batch consistency documentation.
Supply Chain Analysis
Freight cost differentials between bulk liquid tanker and packaged container shipments reshape procurement geography for adhesive formulators lacking dedicated unloading infrastructure. Supply concentrates in Germany, China, and Japan, with Ludwigshafen and Marl hosting captive liquid isoprene capacity, Shandong and Jiangsu provinces expanding solution-polymerized output, and Kanto industrial zones serving precision electronics demand. Feedstock chains draw from Middle Eastern butadiene, Southeast Asian natural rubber processing byproducts, and regional naphtha cracker operations. Single-source exposure around German medical-grade isoprene creates vulnerability for FDA-compliant sealant makers. Distribution runs through direct mill relationships displacing traditional trading houses in Thailand and Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control into butadiene feedstock or forward capture of formulated adhesive demand determines margin sustainability.
For Market Incumbents: Anchor specification-driven positions by expanding anionic polymerization capacity in Ludwigshafen and Marl to capture medical-grade sealant demand, while qualifying alternative Middle Eastern butadiene streams to dilute ECHA handling cost exposure. Deepen captive emulsification assets to serve waterborne adhesive growth in China under MEE-enforced GB standards.
For New Entrants and Emerging Players: Enter via technical service partnerships with Mumbai and Ahmedabad construction chemical formulators currently underserved by reactive liquid rubber distributors. Target India's adhesive sector through direct mill relationships bypassing traditional trading channels, leveraging BIS certification timelines as competitive moats against established suppliers.
For Investors and Strategic Acquirers: Accelerated EPA New Chemicals Program monomer approvals for low-VOC systems is the leading indicator that US adhesive reformulation demand is inflecting toward specialty reactive grades. Prioritize acquisition candidates with living polymerization expertise and established automotive tier-one supplier qualifications, monitoring ECHA substance evaluation protocol expansions as regulatory risk signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butadiene Feedstock | Captive naphtha cracker access insulates margin compression from spot price volatility. |
| Capacity Expansion in Qingdao Chemical Parks | MEE enforcement of GB standards pulls waterborne emulsion polymerization demand. |
| Long-term Supply Agreement with EV Battery Assemblers | Thermal gap-filling specifications in Michigan and Ohio secure volume offtake. |
| Joint Venture for Indian Technical Service Infrastructure | Mumbai and Ahmedabad formulators require localized reactive grade support. |
| Green Manufacturing Transition to Bio-based Monomers | EU Green Deal compliance positioning opens premium construction sealant channels. |
Research Methodology
Multi-period observation of monomer approval timelines, REACH registration status, and automotive qualification cycles anchored the trend analysis, supplemented by interviews with liquid rubber plant managers, adhesive procurement leads at Tier 1 suppliers, construction chemical formulators, and distribution channel partners. Secondary validation drew from ECHA substance evaluation databases, EPA New Chemicals Program filings, SEC 10-K disclosures by listed polymer producers, and customs trade data tracking styrene-butadiene and polyisoprene cross-border flows. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic elasticity assumptions.
Input-output matrices mapped polymerization stage economics through formulation value capture across adhesive, sealant, and automotive end uses, with segmentation dimensions spanning grade tier, end-use industry, cure chemistry, and regional production hub. CAGRs were derived from elasticity-adjusted volume projections across the analysis window, incorporating butadiene feedstock cost trajectories and regulatory-driven formulation substitution rates as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH authorization expansions or sustained naphtha price dislocations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Butyl Reclaimed Rubber Market
Rubber
Global Rubber Market
Rubber
Rubber Chemicals Market
Rubber
Silicone Rubber Market
Rubber
Pre-Dispersed Rubber Chemicals Market
Rubber
Silica for S-SBR Market
Rubber
Rubber Ropes Market
Rubber
Conductive Silicone Rubber Market
Rubber
EPDM Market
Rubber
Specialty Nitrile Butadiene Rubber (NBR) Market
Rubber
Solution Styrene Butadiene Rubber (S-SBR) Market
Rubber
EMEA and Asia Pacific Electrical Insulating Rubber Gloves Market
Rubber
Oil Saver Rubber Market
Rubber
Tire Chemicals Market
Rubber
Tire Recycling Downstream Products Market
Rubber
Rubber Foam Materials Market