
 Industrial Rubber Market | 2026-2036
Industrial Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Rubber Market Intelligence
Demand from specialty buyers seeking high-performance formulations for niche industrial machinery is bifurcating a procurement landscape once dominated by large-volume automotive OEMs. ContiTech Deutschland GmbH specializes in engineered products for specific industrial challenges like vibration dampening. ARLANXEO leads in the development and supply of advanced synthetic elastomers such as EPDM. Meanwhile, Bridgestone Industrial leverages its manufacturing scale to compete in high-volume segments like conveyor belts and heavy-duty hoses.
Industrial rubber refers to a broad category of natural and synthetic elastomers engineered for durability in demanding applications. These materials undergo processes like vulcanization to achieve high tensile strength and resistance to abrasion, chemicals, and extreme temperatures. Synthetic rubber types, including EPDM and Nitrile Rubber, hold a dominant position due to their specific performance characteristics. While conveyor belts and hoses represent mature, high-volume applications, the seals and gaskets segment offers higher margins for custom solutions.
Environmental and safety regulations shape material composition and market access. The EU's REACH framework restricts specific chemical agents, while the US EPA enforces standards on emissions from rubber processing facilities. In Asia, China's MEE also imposes strict environmental protection laws on manufacturers. Navigating these diverse international standards while meeting demands for performance and cost-efficiency remains the central strategic challenge.
Market Dynamics
The central tension shaping the industrial rubber market is the conflict between stringent environmental regulations, such as the EU's REACH framework, and unyielding demand from heavy industries for materials offering extreme durability and performance under harsh conditions.
Growth Catalysts
- Infrastructure Development:Persistent expansion of construction and manufacturing activities, particularly in industrializing economies like India and Brazil, sustains baseline volume demand for essential components like hoses, belts, and anti-vibration mountings.
- High-Performance Synthetics:The adoption of advanced synthetic elastomers, including EPDM and specialty nitrile rubbers, is accelerating in automotive and aerospace applications to meet higher standards for thermal resistance and chemical stability.
- Workplace Safety Mandates:Regulations enforced by bodies like the US Occupational Safety and Health Administration (OSHA) drive the use of high-grade rubber in safety equipment, electrical matting, and vibration-dampening machine pads, creating a floor for quality-driven demand.
Market Restraints
- Feedstock Price Volatility:The market is exposed to price fluctuations of key raw materials, with natural rubber prices subject to agricultural variables and synthetic rubber costs linked directly to volatile crude oil and petrochemical markets.
- Regulatory Compliance Burden:The EU's REACH regulation restricts numerous chemicals used as plasticizers and accelerators, forcing costly reformulation and extensive testing for companies seeking access to the European market.
- Threat from Thermoplastic Elastomers:In applications not requiring extreme heat or chemical resistance, TPEs present a significant substitution threat due to their easier, faster processing cycles and recyclability, eroding share in lower-performance segments.
Strategic Opportunities
- Renewable Energy Components:The build-out of wind and solar energy infrastructure creates new applications for specialized rubber seals, gaskets, and dampeners designed to withstand long-term outdoor exposure and mechanical stress in turbines and panel systems.
- Smart Rubber Integration:Embedding sensors into rubber components like conveyor belts and engine mounts enables predictive maintenance capabilities, offering a value-added service for industrial end-users seeking to minimize downtime.
- Bio-Based Formulations:Developing and commercializing industrial-grade rubber from renewable feedstocks, such as guayule or bio-derived isoprene, presents a major opportunity to mitigate petrochemical dependency and meet corporate sustainability goals.
Industry Challenges
- Divergent Global Standards:Manufacturers face significant complexity in creating products that simultaneously comply with the differing environmental and chemical safety rules set by the US EPA, the EU's ECHA, and China's MEE.
- Capital-Intensive Processing:The high cost of essential manufacturing equipment, including large-scale mixers and vulcanization presses, creates a substantial barrier to entry and limits the agility of existing producers to scale capacity quickly.
- Formulation Expertise Scarcity:A persistent shortage of polymer chemists and material scientists capable of developing novel compounds that balance performance, cost, and regulatory compliance constrains innovation across the industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Rubber Market |
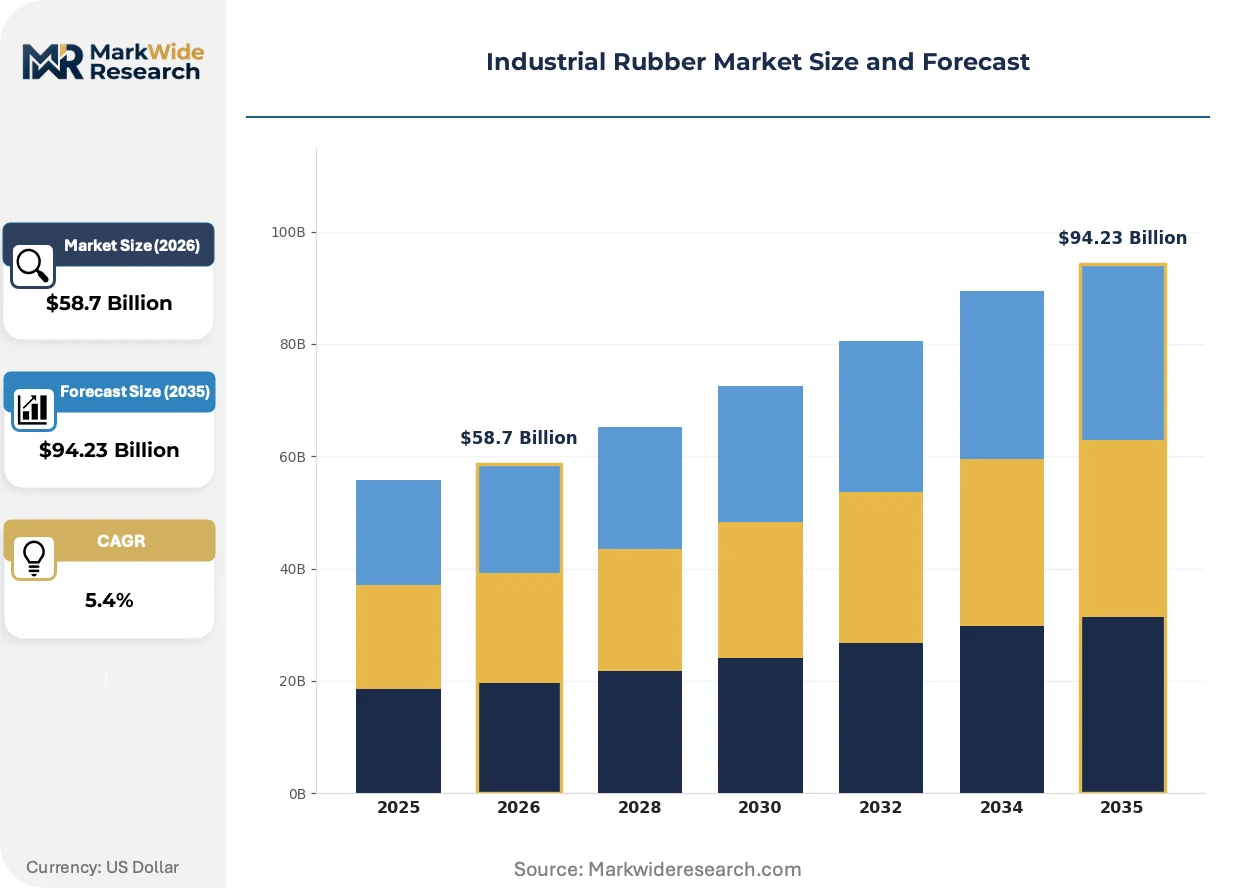
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $94.23 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Rubber, Natural Rubber, Butyl Rubber, Nitrile Rubber, Neoprene, EPDM Application: Seals & Gaskets, Conveyor Belts, Hoses & Tubing, Vibration Dampening, Protective Coatings, Industrial Gloves End User Industry: Construction, Mining, Chemical Processing, Electrical Equipment, Packaging, Consumer Goods Manufacturing Process: Extrusion, Molding, Calendering, Vulcanization, Coating, Lamination |
| Companies Covered | Exxon Mobil Corporation, Dynasol Group, Bridgestone Industrial, THE YOKOHAMA RUBBER CO., LTD., Sumitomo Rubber Industries, Ltd., The Goodyear Tire & Rubber Company, ContiTech Deutschland GmbH, SIBUR International GmbH, ARLANXEO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Rubber Market Strategic Shifts & Innovations
Material science advancements are being accelerated by dual pressures from sustainability mandates and the operational demands of extreme industrial environments. This is pushing innovation beyond simple durability toward materials with active, responsive, and traceable properties across their lifecycle.
Self-healing elastomers represent a significant evolution in material science. These materials incorporate reversible chemical bonds or embedded microcapsules that allow the rubber to repair minor cuts and abrasions, extending its operational lifespan. Adoption is gaining traction in high-wear applications like mining conveyor belts and seals for heavy machinery. This technology is displacing traditional replace-on-failure maintenance models with a more resilient, lower-lifetime-cost alternative.
The EU's Corporate Sustainability Reporting Directive (CSRD) is a pivotal policy shift impacting supply chain transparency. It compels companies to provide audited disclosures on the environmental footprint of their products, including rubber processing emissions and raw material sourcing. Manufacturers supplying the automotive and machinery sectors are most affected, now investing heavily in traceability systems to meet the rigorous reporting requirements for market access.
A notable behavioral shift is occurring as sophisticated end-users move from buying standard components to co-developing custom formulations directly with specialist suppliers. This trend bypasses traditional distribution channels for high-specification applications, fostering direct collaboration for specific performance needs. This custom procurement model is most prominent in the North American aerospace and European medical device sectors, where material properties must meet exacting certification standards.
Industrial Rubber Market Segmentation
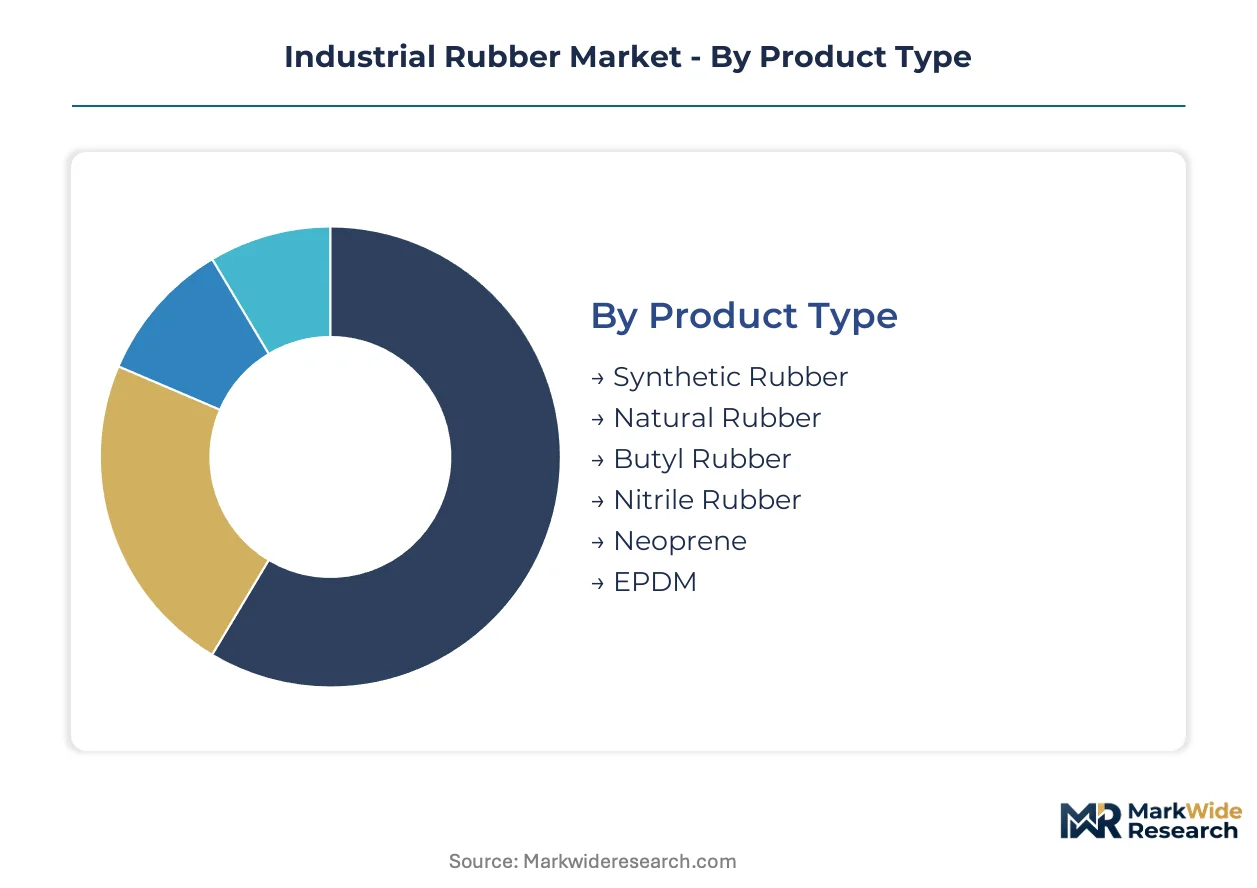
The industrial rubber market's segmentation reveals diverse material demands and application-specific performance requirements across various end-use sectors. Understanding these distinct segments is critical for identifying specific growth pockets and navigating the complex interplay of material science and industrial application.
Product Type:
Margin pools in industrial rubber product types often concentrate in advanced synthetic formulations offering specialized performance characteristics.
- EPDM:Known for excellent resistance to weathering, ozone, and extreme temperatures, EPDM finds extensive use in automotive seals and roofing membranes, driven by longevity requirements.
- Nitrile Rubber:Renowned for its oil and fuel resistance, Nitrile Rubber is critical in hydraulic hoses and seals for machinery, with demand concentrating in manufacturing hubs like China due to industrial output.
- Synthetic Rubber:This broad category encompasses various man-made elastomers engineered for specific industrial applications requiring enhanced durability.
- Natural Rubber:Derived from latex, natural rubber provides high elasticity and tear strength for applications like vibration isolators and heavy-duty tires.
- Butyl Rubber:Butyl rubber offers exceptional impermeability to gases and good vibration dampening, crucial for pharmaceutical stoppers and automotive components.
- Neoprene:Known for its resistance to oil, chemicals, and heat, Neoprene is used in protective gear and industrial hoses.
Natural Rubber holds installed capacity. EPDM is rotating up the share rankings.
Application:
The application landscape reveals varying functional requirements, from static sealing to dynamic material transport in harsh industrial settings.
- Seals & Gaskets:Engineered to prevent leakage and ingress, seals and gaskets require precise material formulation for chemical resistance and temperature stability in industrial machinery across Europe.
- Conveyor Belts:Designed for material handling, conveyor belts demand high abrasion resistance and tensile strength, with significant volume deployed in mining operations in Brazil.
- Hoses & Tubing:These components transport fluids and gases under pressure, requiring flexibility and chemical compatibility in diverse industrial processes.
- Vibration Dampening:Rubber components absorb mechanical shocks and vibrations, extending equipment lifespan and improving operational stability in manufacturing facilities.
- Protective Coatings:Applied to surfaces, these coatings offer chemical resistance and abrasion protection in harsh industrial environments like chemical processing plants.
- Industrial Gloves:These personal protective equipment items safeguard workers from chemical exposure and physical hazards in manufacturing and laboratory settings.
The highest volume demand currently stems from conveyor belts. Seals and gaskets are exhibiting the steepest expansion trajectory.
End User Industry:
End-user industries vary significantly in their performance demands, directly influencing material specifications and procurement volumes for industrial rubber products.
- Construction:This sector requires durable rubber components for heavy machinery, sealing, and vibration isolation in infrastructure projects, particularly in industrializing economies like India.
- Mining:Demanding extreme abrasion and impact resistance, the mining industry utilizes rubber for conveyor belts and heavy-duty hoses in operations across regions like South America.
- Chemical Processing:This industry relies on chemical-resistant rubber for seals, gaskets, and protective linings in corrosive environments, requiring specialized elastomer formulations.
- Electrical Equipment:Rubber provides insulation and vibration dampening for various electrical components and wiring, ensuring safety and performance.
- Packaging:Rubber is used in seals, rollers, and cushioning for automated packaging machinery, ensuring efficient and reliable operation.
- Consumer Goods:This sector incorporates rubber for seals, grips, and various functional components in everyday products, prioritizing durability and tactile properties.
Volume demand from the construction sector remains substantial. The chemical processing industry is gaining share fastest due to specialized material needs.
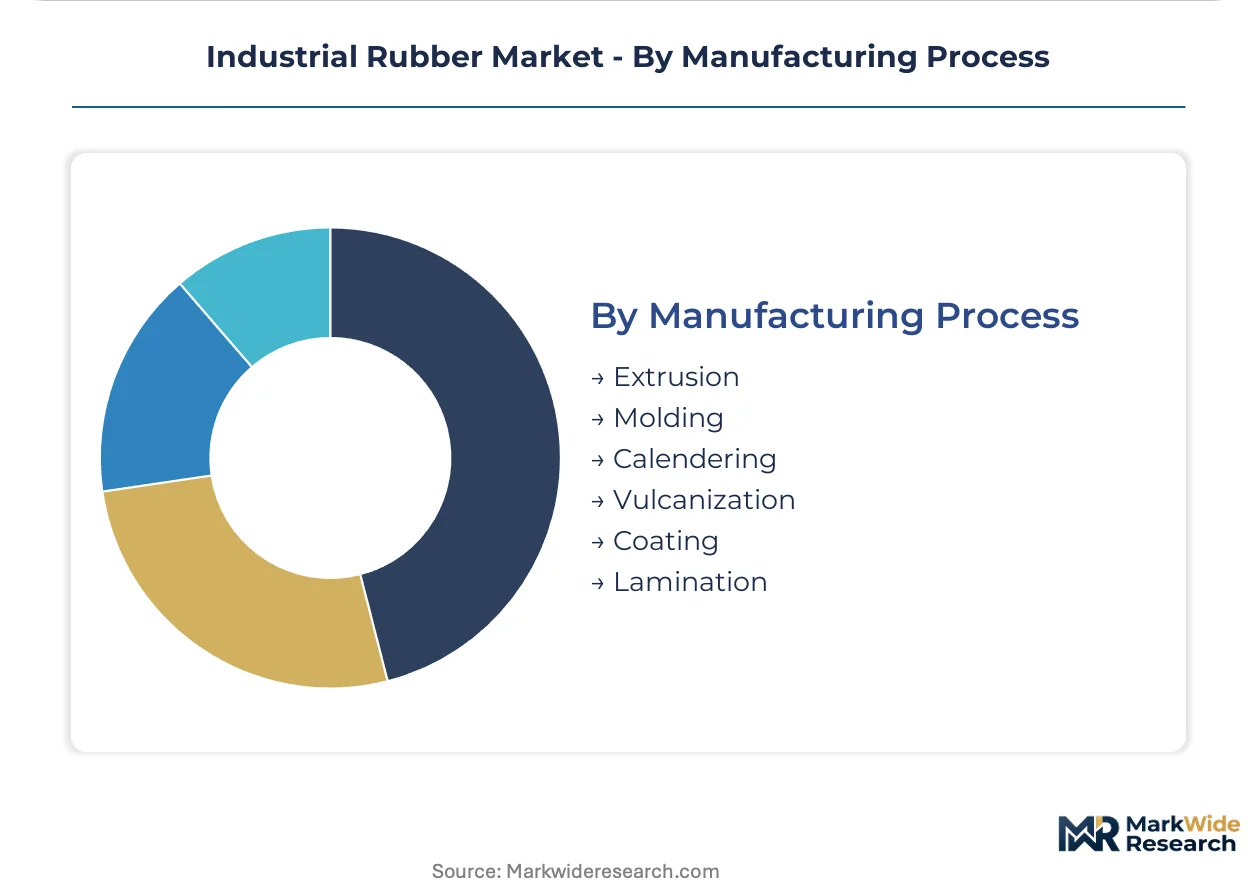
Manufacturing Process:
Production methodologies range from high-volume continuous processes to intricate shaping techniques for specialized components, influencing cost and product complexity.
- Vulcanization:This chemical process enhances rubber's elasticity and durability by cross-linking polymer chains, critical for achieving high tensile strength in products like industrial tires.
- Molding:Shaping rubber compounds under heat and pressure, molding produces complex geometries for seals, gaskets, and vibration dampeners, with precision required for aerospace components in North America.
- Extrusion:This continuous process forms rubber into profiles like hoses and tubing by forcing it through a die, enabling high-volume production.
- Calendering:Rubber sheets are produced through calendering, a process involving rollers for consistent thickness, used in conveyor belt manufacturing.
- Coating:Applying a rubber layer to a substrate, coating provides protection and enhances material properties for various industrial textiles and components.
- Lamination:Bonding multiple layers of rubber or rubber with other materials creates composites for specialized applications like reinforced membranes or dampening mats.
Extrusion processes dominate high-volume output. Molding techniques are climbing the fastest in value due to custom solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The extensive Trans-Eurasian rail network underwrites China's and India's roles as central demand hubs for industrial rubber, facilitating material transport. Global industrial rubber demand is shaped by diverse regional manufacturing and regulatory landscapes. Each geography presents unique growth dynamics and compliance challenges for manufacturers.
China
Infrastructure development and a robust manufacturing base sustain demand for conveyor belts and industrial hoses. China's MEE imposes strict environmental protection laws on rubber processing facilities, driving investment in cleaner technologies. Industrial clusters in the Yangtze River Delta continue to expand output, requiring substantial volumes of durable rubber components for machinery.
India
Persistent expansion of construction and automotive manufacturing activities drives baseline demand for seals, gaskets, and anti-vibration mountings. India's BIS standards for industrial components ensure quality and performance in critical applications. The Gujarat industrial corridor sees significant investment in new factories, consuming high volumes of industrial rubber for equipment and infrastructure.
Germany
High-performance applications in automotive and precision machinery sectors require specialized rubber formulations like EPDM. The EU's REACH framework restricts numerous chemical agents, forcing costly reformulation for market access. Manufacturing hubs in Bavaria and North Rhine-Westphalia focus on engineered products for specific industrial challenges, including vibration dampening.
United States
Demand from aerospace and heavy machinery sectors requires advanced synthetic elastomers for thermal resistance and chemical stability. The US EPA enforces standards on emissions from rubber processing facilities, influencing material composition. Industrial centers in the Great Lakes region remain strong consumers of rubber for automotive and industrial equipment production.
Brazil
Mining operations and ongoing infrastructure projects drive significant volume demand for heavy-duty hoses and conveyor belts. Brazil's national environmental regulations guide material sourcing and processing for industrial rubber products. The state of Minas Gerais, a major mining region, consistently requires robust rubber components for material handling and equipment maintenance.
Industrial Rubber Market Key Industry Players
Concentration sits with large, diversified chemical companies and specialized rubber product manufacturers. The market structure is tiered, with global conglomerates competing alongside regional specialists. Strategic archetypes include integrated elastomer producers, engineered product specialists, and high-volume component manufacturers. Competitive moves often involve strategic partnerships for new material development and targeted geographic expansion to industrializing economies.
Specialists in engineered products, such as ContiTech Deutschland GmbH, exemplify the focus on high-performance solutions for specific industrial challenges like vibration dampening. ARLANXEO, a synthetic elastomer producer, occupies a position at the forefront of advanced material development, particularly with products like EPDM. Bridgestone Industrial anchors the high-volume segment, leveraging its manufacturing scale for products like conveyor belts and heavy-duty hoses.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Dynasol Group |
| Bridgestone Industrial |
| THE YOKOHAMA RUBBER CO., LTD. |
| Sumitomo Rubber Industries, Ltd. |
| The Goodyear Tire & Rubber Company |
| ContiTech Deutschland GmbH |
| SIBUR International GmbH |
| ARLANXEO |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for industrial rubber components lock in supply access and provide price visibility for large-volume buyers. This market's pricing dynamics are intrinsically linked to the global supply chain for raw materials and manufacturing capabilities.
Pricing Analysis
Volume-based discount structures dominate the industrial rubber market, rewarding large-scale procurement for standard components. Price differentiation stems from the customization level required for seals and gaskets, alongside certification levels for aerospace applications. Pricing pressure stems from feedstock price volatility, particularly for crude oil affecting synthetic rubber costs. The construction sector exhibits high price sensitivity for commodity-grade rubber products, while aerospace and medical device sectors prioritize performance over cost.
Supply Chain Analysis
Port congestion and container availability impact the inbound logistics costs for industrial rubber manufacturers globally. Geographic supply concentrates in China and India for finished products, with natural rubber sourcing heavily from Southeast Asia. The market draws from key raw materials including natural rubber latex, crude oil derivatives for synthetic elastomers, and carbon black. Commodity price volatility, especially for crude oil and natural rubber, represents a significant structural risk. Distribution runs primarily through direct sales to large original equipment manufacturers (OEMs) and specialized distributors for niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial rubber market is a high-growth disruption, driven by the emergence of self-healing elastomers and stringent sustainability mandates like the EU's CSRD.
For Market Incumbents: Shield core market share by deepening vertical integration into specialty additives for high-performance formulations. Expand manufacturing capacity in industrializing economies like India to counter thermoplastic elastomer (TPE) substitution threats. Invest in R&D for bio-based formulations to meet evolving regulatory standards. Secure long-term contracts with key automotive OEMs.
For New Entrants and Emerging Players: Anchor in specialized niches like smart rubber integration for predictive maintenance applications. Target the underpenetrated renewable energy sector with custom seals and gaskets for wind turbines. Leverage direct co-development models with aerospace and medical device manufacturers for high-specification solutions. Offer localized production capabilities in regions with high regulatory barriers.
For Investors and Strategic Acquirers: Capital is best deployed toward engineered product specialists with strong intellectual property in advanced synthetic elastomers. Seek out companies commercializing bio-based rubber formulations for long-term sustainability alignment. The successful adoption of embedded sensor technology in industrial components is a key signal to watch. Focus on firms demonstrating robust compliance with EU REACH and CSRD mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture | Combines material science expertise with application-specific engineering for novel solutions. |
| Green Manufacturing Transition | Reduces environmental footprint and ensures compliance with China's MEE regulations. |
| Capacity Expansion | Meets persistent demand from construction and automotive sectors in India. |
| Product Launch | Introduces self-healing elastomers for high-wear mining conveyor belts. |
| Strategic Partnership | Develops smart rubber components with sensor technology for predictive maintenance. |
Research Approach
Initial hypotheses were tested against primary input from polymer chemists, procurement leads at automotive OEMs, plant managers, and regulatory affairs specialists. This primary data was validated through extensive secondary research, including industry association reports, customs trade data, company 10-K filings, and EU ECHA publications. A rigorous bottom-up and top-down triangulation process ensured data accuracy and consistency.
Variance decomposition was applied to isolate the impact of key drivers on market growth across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user industry, manufacturing process, and regional regulatory environment. Compound annual growth rates were derived from historical trends and future projections, incorporating inputs like crude oil prices and global construction spending.
Material uncertainties — including major geopolitical disruptions or unforeseen rapid material science breakthroughs — sit outside the modeled envelope of this study. Forecasts reflect assumptions documented at the time of analysis. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Ethylene Propylene Rubber Cable Market
Rubber
Global Rubber Market
Rubber
Synthetic Polyisoprene Rubber Market
Rubber
Snap on Rubber Stopper Market
Rubber
Rubber Color Masterbatch Market
Rubber
Rubber Wear Liners Market
Rubber
Rubber Molding Market
Rubber
Cellular Rubber Market
Rubber
Tire Reinforcement Materials Market
Rubber
Rubber Foam Market
Rubber
Global Elastomers Market
Rubber
Abrasion-Resistant Rubber Pipe Market
Rubber
US Nitrile Gloves Market
Rubber
Reclaimed Rubber Market
Rubber
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Rubber
Styrene Butadiene Rubber (E-SBR and S-SBR) Market