
 Vulcanization Accelerators Market | 2026-2036
Vulcanization Accelerators Market Size, Share, and Industry Trends Forecast 2026-2036
Vulcanization Accelerators Market Outlook
Specialized rubber chemist labor pools across Northeast Asia and Western Europe is bifurcating the competitive landscape, with incumbent hubs struggling to replenish retiring formulation expertise while emerging producers scale technical training programs. Lanxess leverages its captive precursor supply chain to sustain margin stability across sulfenamide accelerator lines. Sumitomo Chemical anchors high-specification output for Japanese tire OEMs through integrated R&D facilities in Chiba and Osaka. China Sunsine Chemical Holdings Ltd. dominates bulk thiazole and thiuram production from its Shandong manufacturing base, competing primarily on throughput scale and backward integration into aniline feedstocks.
Vulcanization accelerators are sulfur-donor or sulfur-activating compounds, typically organosulfur chemicals such as 2-mercaptobenzothiazole (MBT) derivatives or sulfenamides, that reduce cure time and lower vulcanization temperature in rubber compounding by facilitating cross-link formation between polymer chains. Primary accelerators, particularly sulfenamide variants, command the largest volume share due to their delayed-action characteristics essential for tire manufacturing, while secondary accelerators such as thiurams and dithiocarbamates concentrate in industrial rubber goods where ultra-fast cure profiles reduce cycle times in molded seals and hoses. Processing accelerators remain a narrower margin pool despite growing specification complexity from footwear and adhesives formulators seeking reduced scorch risk in high-shear mixing environments.
REACH registration requirements enforced by ECHA mandate comprehensive toxicological dossiers for thiazole and guanidine accelerator categories, elevating compliance costs for European compounders while creating technical barriers for non-registered imports. EPA New Chemicals Program oversight under TSCA Section 5 constrains introduction of novel accelerator chemistries in United States tire and industrial rubber applications, reinforcing reliance on established molecular structures with existing PMN exemptions. Stakeholders must monitor evolving classification thresholds for nitrosamine-generating accelerators under both frameworks, as regulatory pressure on secondary amine precursors threatens reformulation requirements across multiple end-use segments without clear replacement pathways at equivalent cost-performance ratios.
Market Dynamics
Electric vehicle tire specifications are rewriting accelerator performance requirements, as higher torque loads and extended range imperatives force compounders toward delayed-action sulfenamides with superior scorch safety and cross-link density control.
Growth Catalysts
- REACH Phase-in Substances:ECHA registration deadlines for thiazole derivatives are consolidating supply among compliant European compounders, locking out unregistered imports and securing premium pricing for dossier-holding producers.
- Automotive lightweighting:Tire OEMs are specifying higher-performance rubber to offset battery weight, accelerating procurement of primary sulfenamide accelerators with enhanced reversion resistance.
- Shandong manufacturing cluster:Concentrated aniline and MBT precursor capacity across this Chinese province is compressing regional feedstock costs and enabling aggressive export pricing.
Market Restraints
- Aniline price volatility:Feedstock cost swings for this benzene derivative directly compress accelerator margins, particularly for thiazole producers lacking backward integration into petrochemical precursors.
- Nitrosamine regulatory pressure:Secondary amine-based accelerators face classification uncertainty under evolving EPA and ECHA frameworks, threatening reformulation costs without equivalent-performance replacements.
- Specialized chemist scarcity:Retiring formulation expertise across Western Europe and Northeast Asia is constraining R&D throughput for novel accelerator development.
Strategic Opportunities
- Indian tire manufacturing expansion:Domestic production capacity additions by Apollo Tyres and MRF are creating localized accelerator demand currently served by imports from China and South Korea.
- Bio-based accelerator platforms:Renewable feedstock-derived thiazole alternatives align with EU Green Deal procurement mandates and automotive OEM sustainability scorecards.
- Digital compounding integration:AI-driven formulation optimization is compressing trial-batch cycles and enabling just-in-time accelerator procurement from integrated suppliers.
Industry Challenges
- Toxicological dossier compilation:REACH-compliant toxicology studies for novel accelerator chemistries demand 18-24 month timelines and seven-figure investments, freezing innovation pipelines for mid-scale compounders.
- Legacy mixing equipment retrofit:High-shear internal mixers at aging tire plants require scorch-resistant accelerator packages that conflict with cost-minimization procurement mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vulcanization Accelerators Market |
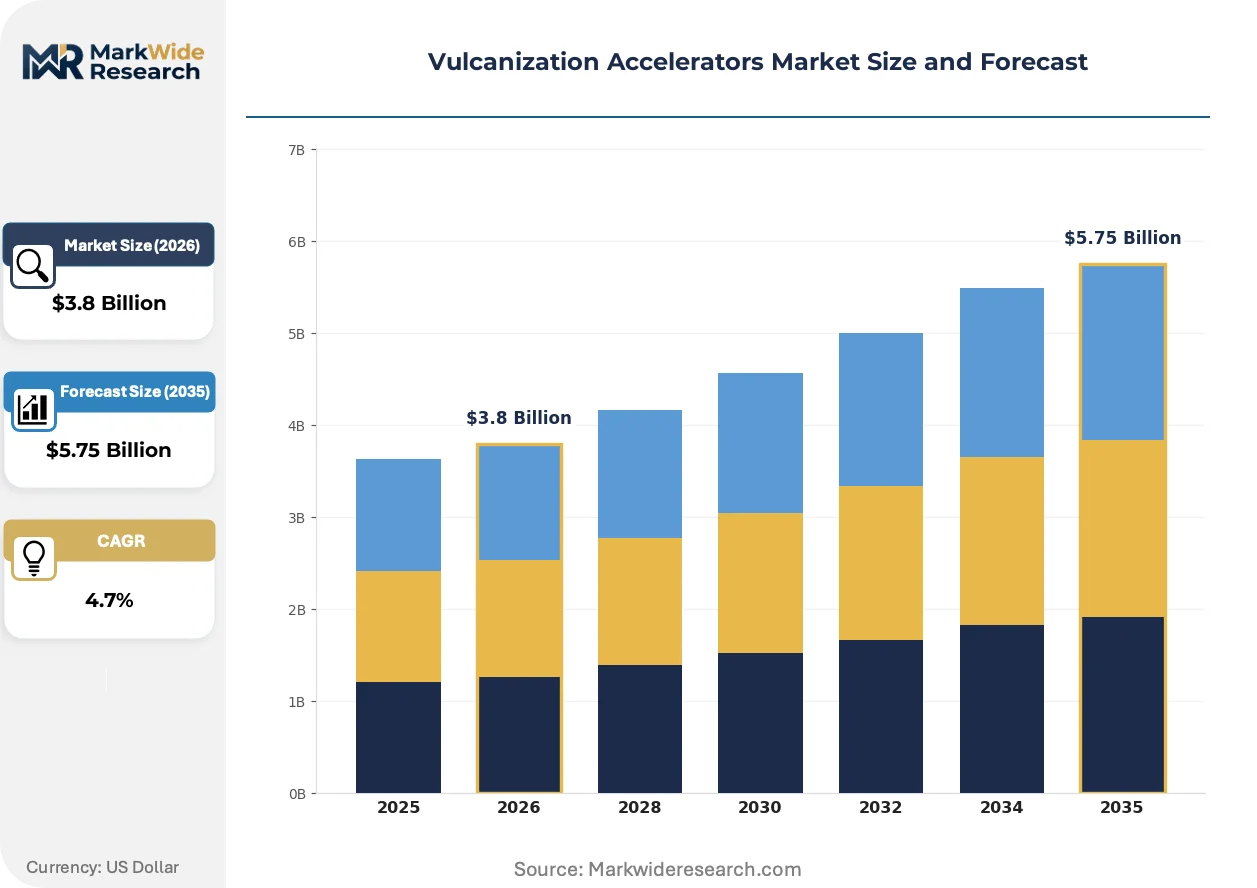
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Accelerators, Secondary Accelerators, Processing Accelerators, Vulcanizing Agents End User: Automotive, Footwear, Industrial Rubber Goods, Adhesives Application: Sealants, Coatings, Tires, Hoses Form: Granules, Powder, Liquid, Tablets |
| Companies Covered | KUMHO PETROCHEMICAL, Shandong Yanggu Huatai Chemical, Lanxess, Sumitomo Chemical, Puyang Willing Chemicals, Eastman Chemical Company, China Sunsine Chemical Holdings Ltd., Sunsine, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vulcanization Accelerators Market Strategic Shifts
Accelerator technology is bifurcating between commodity thiazole scale and specialty sulfenamide performance, with digital formulation tools compressing development cycles and regulatory pressure forcing molecular innovation.
Pre-dispersed accelerator masterbatches are miniaturizing dosing variability in high-volume tire production. Compounders at Bridgestone and Michelin facilities are adopting polymer-bound MBT and CBS variants to eliminate dust exposure and improve dispersion uniformity. This shift is miniaturizing batch-to-batch cure variation, enabling statistical process control that reduces scrap rates in continuous vulcanization lines.
EPA New Chemicals Program oversight under TSCA Section 5 is constraining novel molecular introductions in United States rubber applications. The agency's expanded scrutiny of nitrosamine precursor pathways is reinforcing reliance on grandfathered sulfenamide structures with existing PMN exemptions. Tire formulators in Ohio and South Carolina are responding by accelerating qualification of European-registered alternatives ahead of potential domestic restriction.
Specification-driven procurement is consolidating accelerator buying among integrated suppliers with captive toxicology data. Tier-one tire manufacturers are unbundling compound development from raw material sourcing, contracting directly with Lanxess and Sumitomo Chemical for customized sulfenamide blends rather than distributor intermediaries. This concentration is most visible in Japanese and German automotive supply chains, where OEM sustainability audits favor single-source accountability over cost-optimized multi-vendor arrangements.
Vulcanization Accelerators Market Segmentation
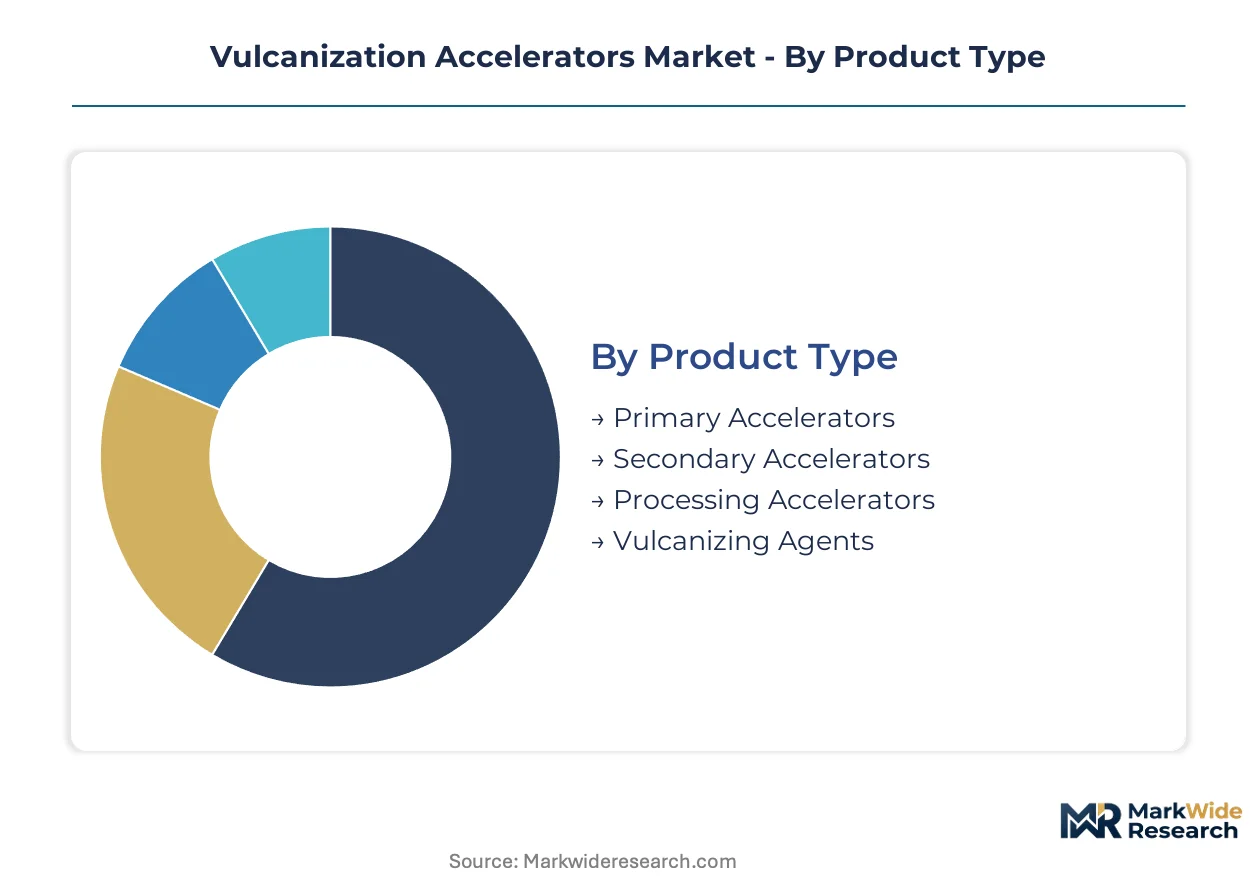
Accelerator procurement channels bifurcate sharply between bulk thiazole spot markets and contracted sulfenamide supply agreements. Tire manufacturers consolidate primary accelerator purchases through direct supplier relationships, while industrial rubber compounders source secondary grades via distributor networks.
Product Type:
Primary accelerators move through long-term supply contracts with integrated petrochemical suppliers, while secondary and processing grades trade through regional chemical distributors.
- Primary Accelerators:Sulfenamide variants such as CBS and TBBS deliver delayed-action cure profiles essential for tire manufacturing. Bridgestone and Michelin facilities in Japan and Germany specify these grades for high-torque electric vehicle tire compounds where scorch safety determines batch yield.
- Secondary Accelerators:Thiurams and dithiocarbamates enable ultra-fast cure cycles in molded industrial seals. Demand concentrates at Korean and Chinese hose manufacturers serving construction equipment OEMs where cycle time reduction drives procurement decisions.
- Processing Accelerators:Scorch retarders and pre-dispersed masterbatches reduce mixing risk in high-shear environments. Footwear compounders in Vietnam and Indonesia specify these for multi-component sole formulations.
- Vulcanizing Agents:Sulfur donors and peroxide curatives complete cross-link networks in specialty rubber grades. Aerospace sealant formulators in France and Germany source these through qualified supplier programs.
Primary accelerators dominate installed base. Processing accelerators are where expansion concentrates.
End User:
Cost tier stratification separates automotive procurement at premium specification levels from price-sensitive footwear and adhesive segments.
- Automotive:Tire OEMs command the largest volume pull, with delayed-action sulfenamides specified for electric vehicle platforms requiring higher cross-link density. German and Japanese automotive supply chains enforce REACH-compliant sourcing with full toxicological dossiers.
- Industrial Rubber Goods:Hose and belt manufacturers in the United States and China drive secondary accelerator consumption. EPA oversight of nitrosamine precursors is forcing qualification of alternative cure systems at Ohio and South Carolina mixing plants.
- Footwear:Sole compounders prioritize processing safety over cure speed. Vietnamese and Indonesian manufacturers specify pre-dispersed masterbatches to eliminate dust exposure in labor-intensive finishing operations.
- Adhesives:Pressure-sensitive and structural adhesive formulators require ultra-low scorch risk. European tape manufacturers align procurement with EU Green Deal bio-based content mandates.
Automotive commands premium pricing tiers. Industrial rubber goods represent the steepest expansion trajectory.
Application:
Volume concentration in tire production contrasts with specification complexity across sealing and coating applications.
- Tires:Passenger and commercial vehicle tire curing consumes the majority of primary sulfenamide output. Electric vehicle specifications at Korean and German OEMs are rewriting accelerator performance thresholds for torque resistance.
- Hoses:Hydraulic and pneumatic hose manufacturing favors fast-cure thiuram systems. Chinese construction equipment suppliers in Shandong province compress cycle times through automated vulcanization lines.
- Sealants:Automotive and aerospace gasket applications demand peroxide-curable fluoroelastomer grades. French and German compounders qualify sulfur-donor alternatives under ECHA scrutiny of traditional accelerator chemistries.
- Coatings:Rubber-to-metal bonding primers and protective finishes require specialized cure packages. Japanese automotive coating suppliers specify low-nitrosamine accelerator blends ahead of potential METI restrictions.
Tires anchor volume demand. Sealants concentrate specification innovation.
Form:
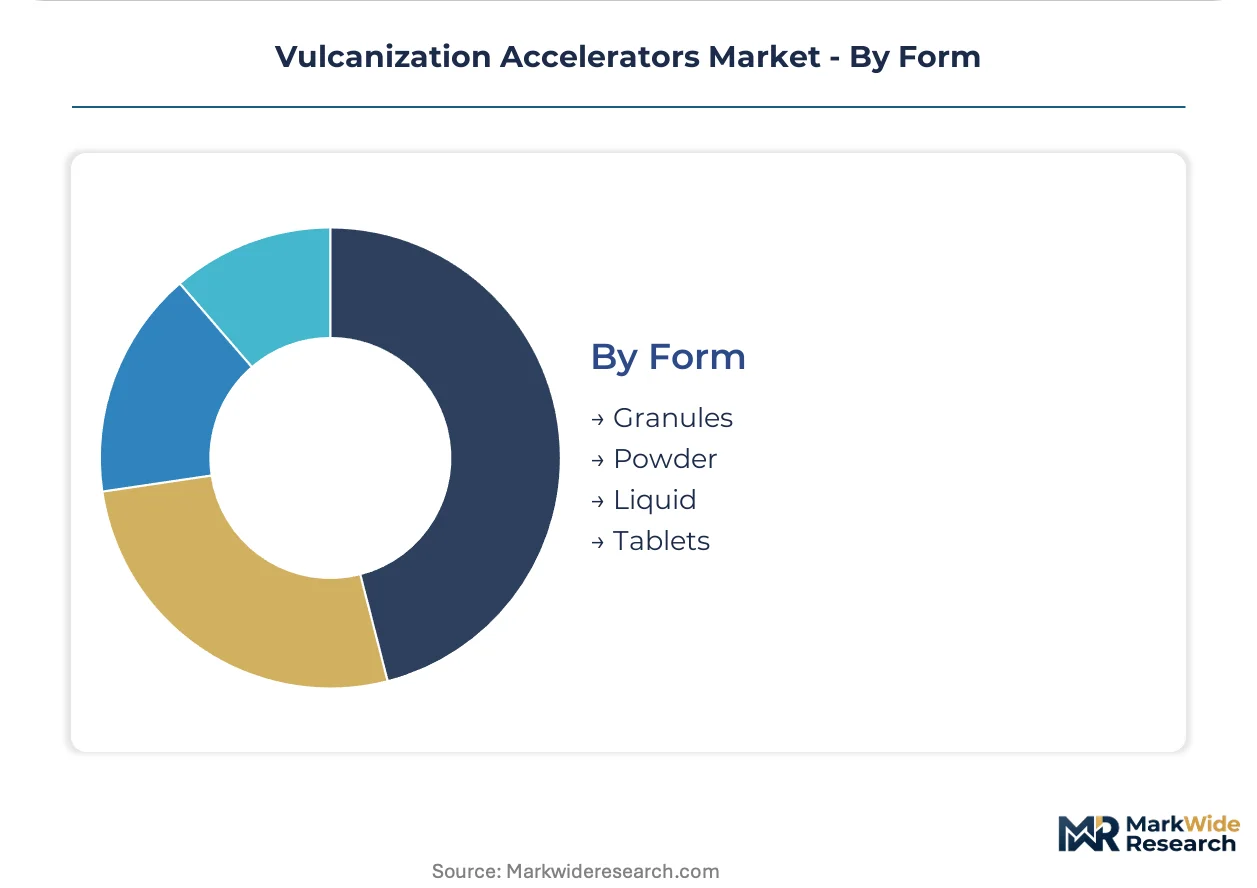
Supply chain maturity separates established powder and granule formats from emerging liquid and tablet delivery systems.
- Granules:Dust-free handling characteristics dominate high-volume tire plant specifications. Polymer-bound granules at Bridgestone and Michelin facilities eliminate weighing variability in continuous mixing operations.
- Powder:Lowest-cost format retains share at price-sensitive industrial rubber compounders. Chinese and Indian hose manufacturers specify powder grades where automated dosing systems reduce handling exposure.
- Liquid:Pumpable accelerator dispersions enable closed-system dosing at adhesive and coating lines. European tape manufacturers adopt liquid TBBS for solvent-free compounding aligned with REACH environmental targets.
- Tablets:Pre-weighed unit doses simplify batch consistency at small-scale footwear operations. Indonesian sole manufacturers specify tablet formats to reduce skilled labor requirements in mixing rooms.
Granules dominate installed base. Liquid forms are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH enforcement anchors European procurement compliance, while EPA oversight shapes United States formulation constraints. Chinese manufacturing clusters dominate bulk thiazole output. Japanese and Korean tire OEMs drive specification innovation for electric vehicle platforms.
China
Shandong province concentrates aniline and MBT precursor capacity, enabling aggressive export pricing from integrated producers. The Ministry of Ecology and Environment enforces dual carbon goals that tighten emissions standards at chemical manufacturing facilities. Qingdao and Yantai host rubber processing clusters where domestic tire manufacturers source accelerators under long-term supply contracts.
Germany
Automotive tire OEMs in Baden-Württemberg and Lower Saxony specify REACH-compliant sulfenamides with full toxicological dossiers. ECHA registration deadlines for thiazole derivatives consolidate supply among compliant compounders, locking out unregistered imports. Lanxess operates integrated production facilities leveraging captive precursor supply chains to sustain margin stability.
United States
Ohio and South Carolina mixing plants face EPA New Chemicals Program oversight under TSCA Section 5, constraining novel accelerator introductions. Tire formulators accelerate qualification of European-registered alternatives ahead of potential domestic restriction on nitrosamine-generating chemistries. Akron retains legacy rubber compounding expertise despite retiring formulation labor pools.
Japan
Sumitomo Chemical anchors high-specification output for domestic tire OEMs through integrated R&D facilities in Chiba and Osaka. METI scrutiny of nitrosamine precursors threatens reformulation requirements without clear replacement pathways. Yokohama and Kobe manufacturing bases serve Toyota and Honda electric vehicle tire specifications demanding superior scorch safety.
India
Apollo Tyres and MRF expand domestic production capacity, creating localized accelerator demand currently served by imports from China and South Korea. The Bureau of Indian Standards enforces quality specifications for rubber chemicals used in automotive applications. Gujarat and Tamil Nadu host emerging tire manufacturing clusters where procurement patterns favor cost-optimized distributor networks.
Vulcanization Accelerators Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the vulcanization accelerators market. European and Japanese petrochemical conglomerates control premium sulfenamide supply through captive precursor integration. Chinese manufacturers dominate bulk thiazole and thiuram output via concentrated feedstock access in Shandong province. Competitive moves center on backward integration into aniline feedstocks and toxicology dossier compilation for REACH compliance.
Among the integrated leaders, Lanxess and Sumitomo Chemical exemplify the European-Japanese tier that anchors premium supply contracts with automotive OEMs. China Sunsine Chemical Holdings Ltd. occupies a position representing the scale-driven Chinese manufacturers competing on throughput and feedstock integration. These three entities collectively illustrate the geographic bifurcation between specification-driven Western procurement and volume-optimized Asian production.
| Leading Market Players |
|---|
| KUMHO PETROCHEMICAL |
| Shandong Yanggu Huatai Chemical |
| Lanxess |
| Sumitomo Chemical |
| Puyang Willing Chemicals |
| Eastman Chemical Company |
| China Sunsine Chemical Holdings Ltd. |
| Sunsine |
| Arkema |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty-day inventory cycles at European tire compounders signal supply-chain rigidity that amplifies pricing power for REACH-registered sulfenamide producers while squeezing spot-market thiazole margins. This lead-time band concentrates procurement leverage among dossier-holding suppliers who can guarantee compliance continuity.
Pricing Analysis
Price spreads between Shandong-origin bulk thiazole and German-manufactured sulfenamides exceed three-to-one multiples, reflecting certification-grade differentiation rather than molecule cost alone. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant specialty grades from commodity spot volumes and pre-dispersed masterbatch formats. Cost compression in economy-tier thiazole is intensifying because Shandong producers leverage captive aniline integration to undercut non-integrated rivals. Industrial rubber goods compounders exhibit highest price sensitivity, while Japanese tire OEMs absorb premium sulfenamide pricing to secure scorch-safety specifications.
Supply Chain Analysis
Strategic stockpiling of MBT precursors dominates procurement behavior at risk-averse European compounders, contrasting with just-in-time aniline sourcing at Shandong manufacturing clusters. Supply concentrates in China, Germany, and Japan, with aniline, benzothiazole intermediates, and polymer-binding agents forming critical input dependencies. Single-source vulnerability around Shandong aniline capacity creates systemic exposure to MEE emissions enforcement actions. Distribution runs through integrated petrochemical suppliers for automotive tier-one contracts, while regional chemical distributors serve fragmented industrial rubber goods segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for formulation optimization are expanding faster than accelerator molecule sales, creating recurring-revenue attachments that offset commodity pricing cycles. This service layer rewards suppliers with captive R&D facilities and qualified laboratory networks.
For Market Incumbents: Compound toxicology dossier advantages into exclusive supply agreements with German and Japanese automotive OEMs ahead of ECHA thiazole registration deadlines. Deepen backward integration into aniline feedstocks to defend margin stability against Shandong cost compression. Lock in long-term offtake contracts with Indian tire manufacturers expanding domestic capacity.
For New Entrants and Emerging Players: Lead with bio-based thiazole alternatives targeting EU Green Deal procurement mandates at French and German adhesive formulators. White-space concentrates in Indian domestic tire manufacturing, currently import-dependent from China and South Korea. Establish qualification partnerships with Apollo Tyres and MRF before incumbent suppliers consolidate distributor relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical conglomerates divesting non-core rubber chemical divisions amid portfolio rationalization. Five-to-ten-year viability hinges on REACH dossier completeness rather than production scale alone. Watch for ECHA classification decisions on nitrosamine-generating accelerators as inflection signal forcing industry-wide reformulation investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aniline | Lanxess and Sumitomo Chemical sustain margin stability through captive precursor supply chains. |
| REACH Dossier Compilation | ECHA registration deadlines consolidate supply among compliant European compounders with locked-out imports. |
| Pre-dispersed Masterbatch Expansion | Bridgestone and Michelin adoption eliminates dust exposure while reducing batch-to-batch cure variation. |
| Bio-based Accelerator Development | EU Green Deal mandates and automotive OEM sustainability scorecards drive renewable feedstock qualification. |
| Indian Manufacturing Partnership | Apollo Tyres and MRF capacity additions create localized demand currently served by Chinese imports. |
Study Parameters
The analysis maps primary sulfenamide, secondary thiuram, and processing accelerator categories, each validated through procurement directors at tire OEMs, technical R&D leads at rubber compounders, and distribution channel partners across Northeast Asia and Western Europe. Primary interviews with plant managers at Shandong manufacturing facilities and regulatory affairs specialists at ECHA-registered suppliers combined with secondary validation from customs trade data, ACC and Cefic industry reports, and SEC 10-K chemical segment disclosures. Bottom-up volume builds from end-use consumption patterns triangulated against top-down petrochemical feedstock flow analysis.
Consistency checks against external benchmarks validated projection outputs across the analysis window, with segmentation modeling incorporating accelerator type, end-use industry tier, and regional regulatory cluster dimensions. CAGRs derived from historical elasticity analysis applied to electric vehicle tire specification shifts and Indian manufacturing capacity trajectories. Industry-specific inputs included aniline price volatility indices and ECHA registration timeline assumptions.
Underlying assumptions cover sustained REACH enforcement stringency and stable aniline feedstock availability, with deviation risk concentrated in nitrosamine regulatory reclassification and Shandong emissions policy tightening. Revision becomes warranted when ECHA substance evaluation timelines accelerate or Indian import substitution rates exceed modeled thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Specialty Resins Market
Specialty Chemicals
Stearyl Alcohol Market
Specialty Chemicals
Fluorotelomers Market
Specialty Chemicals
Global Release Agents Market
Specialty Chemicals
Polyether Modified Silicone Market
Specialty Chemicals
Ubiquinone Market
Specialty Chemicals
Specialty Biocides Market
Specialty Chemicals
Hyaluronic Acid Products Market
Specialty Chemicals
Preparative Chromatography Market
Specialty Chemicals
Carnauba Wax Market
Specialty Chemicals
Global Prepacked Chromatography Columns Market
Specialty Chemicals
Bio-Based Aromatics Market
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
Global Photoacid Generators Market
Specialty Chemicals
Silicone Oil Market
Specialty Chemicals
Nucleotides Market