
 Rubber Splicing Tape Market | 2026-2036
Rubber Splicing Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Splicing Tape Market Analytics
Aftermarket service revenue for cable jointing and field repair is rewriting margin expectations across the value chain. 3M Company leverages its Scotch brand equity and captive resin formulation technology to sustain premium positioning in electrical-grade tapes. Henkel AG & Co. KGaA anchors European demand through localized compounding facilities and direct utility relationships. Nitto Denko Corporation dominates Asian supply with integrated backing-film production and just-in-time delivery to Japanese OEMs.
Rubber splicing tape is a self-fusing, elastomeric adhesive tape manufactured from ethylene-propylene rubber or silicone compounds, typically 0.5 to 2.0 mm thick, designed to create moisture-sealed, electrically insulated splices on low- through medium-voltage cables. The material vulcanizes under tension and heat exposure to form a homogeneous, void-free barrier resistant to ozone, UV, and chemical ingress. Electrical-grade tapes command the largest revenue pool given utility procurement scale and specification rigor, while silicone-based technology captures the fastest expansion due to thermal stability demands in EV charging infrastructure and renewable interconnection projects. Waterproof variants retain stable volumes in marine and underground applications where submersion resistance is non-negotiable.
REACH registration requirements and RoHS substance restrictions in Europe compel reformulation of halogenated plasticizers and heavy-metal stabilizers, elevating compliance costs for non-EU exporters. The US EPA and OSHA jointly govern workplace chemical exposure limits and volatile organic compound emissions during tape manufacturing and application, shaping plant location decisions and product chemistry. China's SAMR enforces GB standards for electrical insulation materials that foreign suppliers must certify through designated testing laboratories. Stakeholders must monitor divergence between regional chemical approval frameworks and pre-position formulation platforms that can toggle between regulatory jurisdictions without full product redevelopment.
Market Dynamics
REACH compliance deadlines and GB standard revisions are forcing simultaneous reformulation across ethylene-propylene and silicone compound portfolios, compressing product development cycles while elevating certification costs for cross-border suppliers.
Growth Catalysts
- EV charging infrastructure buildout:Thermal stability specifications for 150°C+ operating environments are pulling silicone-based splicing tape into utility-scale interconnection projects.
- Indonesia's state-grid modernization:PLN's medium-voltage expansion program is generating concentrated procurement volume for moisture-sealed jointing systems in Java and Sumatra corridors.
- RoHS substance restrictions:European halogenated plasticizer bans are accelerating migration to non-heavy-metal stabilizer chemistries, creating first-mover advantages for compliant formulators.
Market Restraints
- EPDM resin supply concentration:Backward integration by Asian petrochemical majors is limiting third-party access to high-purity ethylene-propylene feedstock.
- Substitution by cold-shrink technology:Pre-expanded silicone sleeves are displacing labor-intensive tape wrapping in utility maintenance protocols.
- REACH registration cost burden:Full substance dossier requirements for imported rubber compounds are pricing out smaller non-EU compounders.
Strategic Opportunities
- Vietnam manufacturing corridor penetration:Samsung and Foxconn cable harness facilities in Bac Ninh and Hai Phong are creating captive demand for just-in-time tape supply.
- Marine offshore wind interconnection:Submersible-rated waterproof variants are opening specification windows in North Sea and Baltic cable landing projects.
- GB standard harmonization:China's SAMR alignment with IEC 60454 is reducing dual-certification overhead for qualified foreign suppliers.
Industry Challenges
- Certified cable jointer shortage:Utility-scale field installation requires trained technicians capable of tension-wrapping to manufacturer torque specifications.
- Dual-track inventory management:Suppliers must maintain separate formulation stocks for REACH-compliant and legacy-chemistry markets without commingling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Splicing Tape Market |
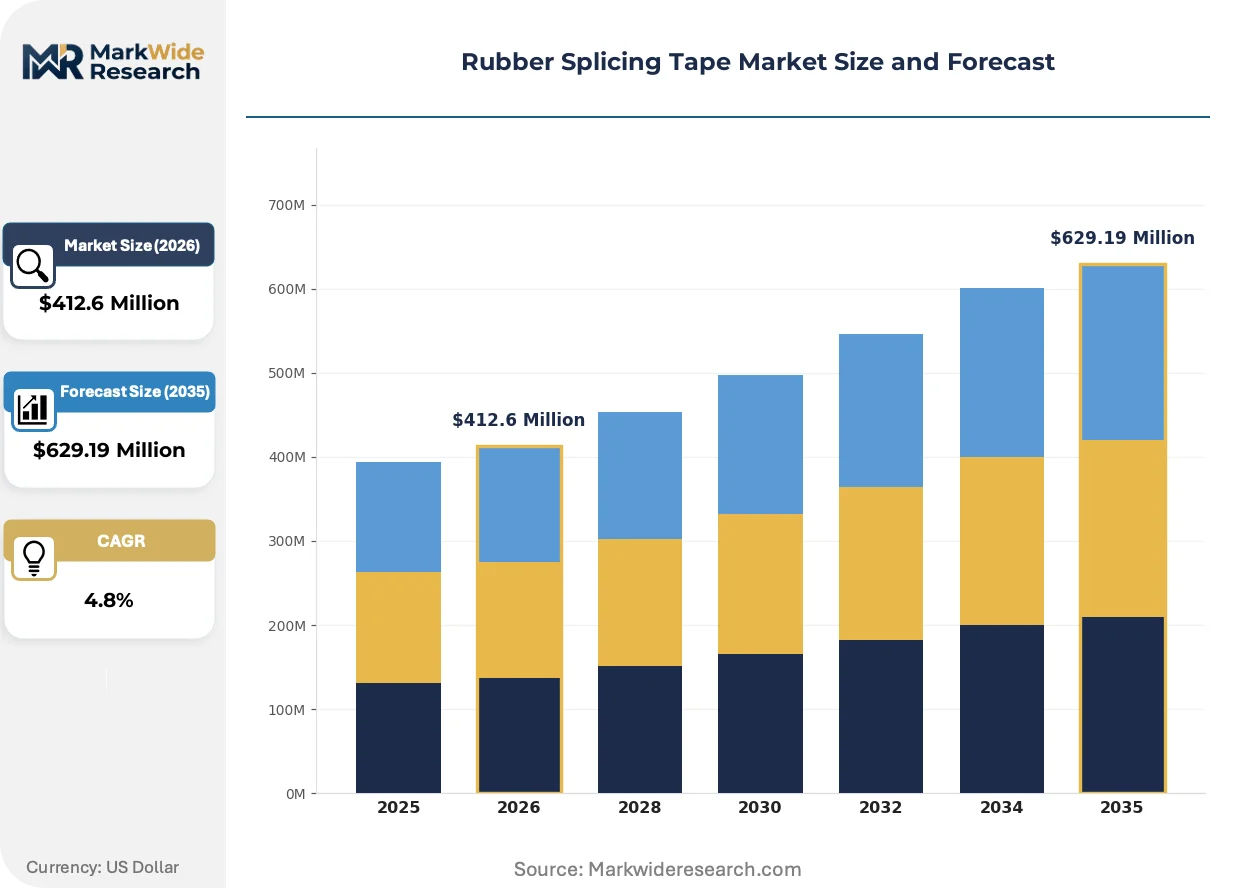
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrical, Insulation, Waterproof, High-Temperature Application: Construction, Automotive, Electronics, Marine End User: Manufacturers, Contractors, Distributors, DIY Enthusiasts Technology: Polymeric, Silicone-Based, Natural Rubber, Synthetic |
| Companies Covered | 3M Company, tesa SE, Nitto Denko Corporation, Avery Dennison Corporation, Intertape Polymer Group, Scapa Group plc, Shurtape Technologies, LLC, Saint-Gobain Performance Plastics, Henkel AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Splicing Tape Market Evolving Landscape
Formulation chemistry and application methodology are converging around automation-readiness and regulatory pre-certification, compressing the traditional specification-to-procurement timeline for electrical-grade materials.
Self-fusing silicone compounds with embedded temperature-indicating pigments are digitizing quality assurance protocols. Japanese OEMs and German tier-one harness suppliers are adopting these smart-tape variants for traceability in EV battery pack assemblies. The technology is digitizing field inspection workflows by enabling non-contact thermal history verification without disassembly.
ECHA's 2023 update to REACH candidate list restrictions on medium-chain chlorinated paraffins is forcing reformulation of legacy plasticizer systems. Compounders serving European electrical utilities must now validate alternative phthalate-free flexibilizers through accelerated aging testing. Silicone-based product lines are capturing preference share as they bypass the restriction entirely.
Integrated supply contracts are bundling splicing tape with jointing kits and installation supervision. Vietnamese and Indonesian utilities are consolidating vendor panels to single-source agreements that shift inventory risk to suppliers. Aftermarket service revenue is displacing pure product margin as the primary profitability lever in medium-voltage segments.
Rubber Splicing Tape Market Segmentation
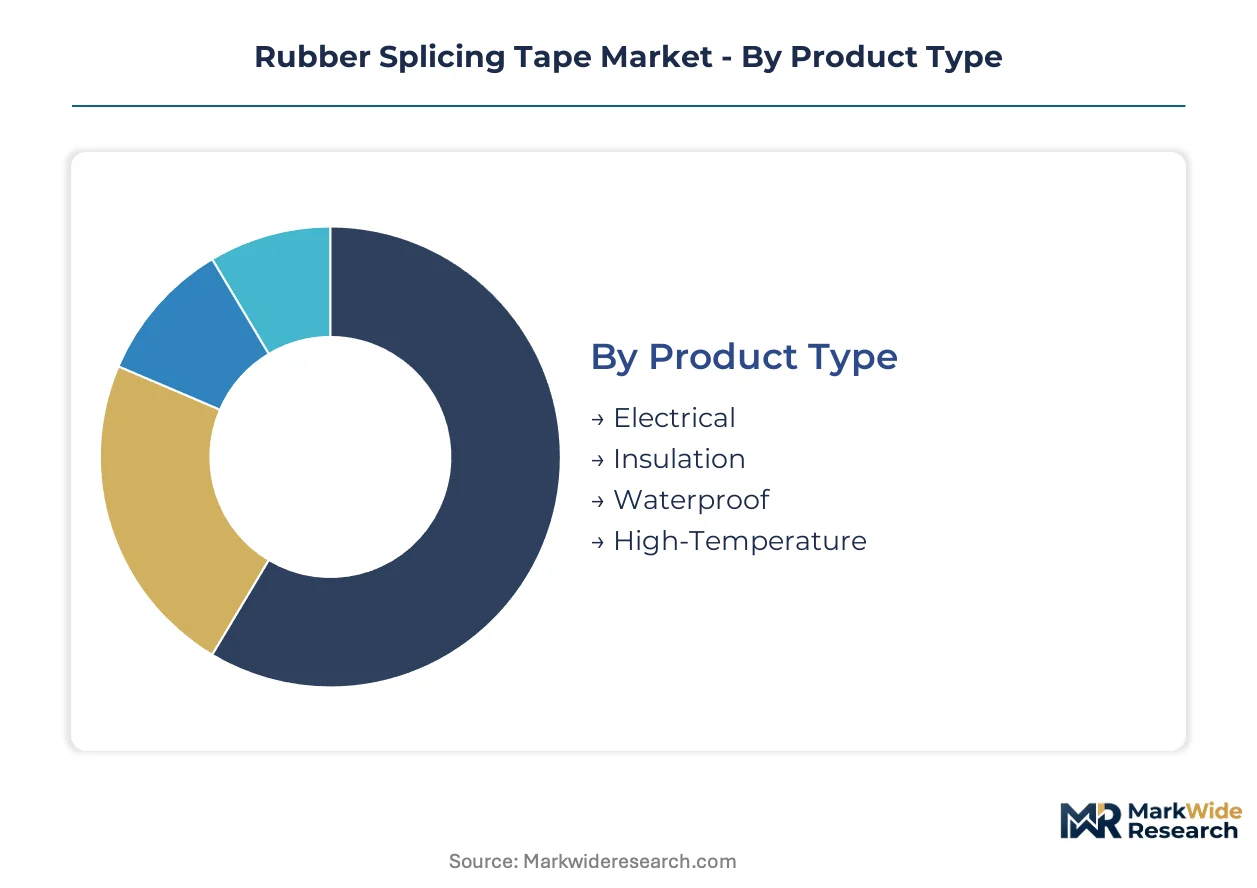
Segmentation in rubber splicing tape markets tracks how formulation chemistry, installation environment, and procurement authority fragment demand across incompatible specification regimes. Each dimension carries distinct margin profiles and certification burdens that shape supplier portfolio decisions.
Product Type:
Cost tier stratification separates specification-grade electrical products from general-purpose alternatives, with thermal performance and regulatory compliance driving price multiples.
- Electrical:Ethylene-propylene and silicone compounds formulated to IEC 60454 and GB standards dominate utility procurement. PLN's medium-voltage expansion in Java and Sumatra corridors concentrates volume for moisture-sealed jointing systems with full REACH dossier compliance.
- High-Temperature:Silicone-based formulations rated for 150°C+ operating environments serve EV charging infrastructure and renewable interconnection projects. Thermal stability specifications from German tier-one harness suppliers are accelerating preference share for this chemistry.
- Waterproof:Submersible-rated variants with ozone and UV resistance retain stable volumes in marine offshore wind applications.
- Insulation:General-purpose dielectric barriers for low-voltage residential and commercial installations.
Electrical holds installed capacity. High-Temperature is rotating up the share rankings.
Application:
End-use environment dictates moisture ingress specifications, chemical exposure profiles, and the labor intensity of approved installation methods.
- Automotive:EV battery pack assemblies and charging cable harnesses demand temperature-indicating pigment technologies for traceable quality assurance. Japanese OEMs specify these smart-tape variants under integrated supply contracts bundling tape with jointing kits.
- Marine:North Sea and Baltic cable landing projects specify submersible-rated waterproof variants with accelerated aging validation.
- Construction:Medium-voltage infrastructure buildouts across Southeast Asian manufacturing corridors drive moisture-sealed jointing procurement.
- Electronics:Miniaturized cable harness assemblies for consumer devices and industrial controls.
Automotive commands specification intensity. Marine is climbing the fastest on offshore wind capital deployment.
End User:
Customer type determines whether procurement flows through centralized utility panels, fragmented contractor networks, or retail channels with divergent technical support expectations.
- Contractors:Certified cable jointers capable of tension-wrapping to manufacturer torque specifications represent a bottleneck for utility-scale field installation. Vietnamese and Indonesian utilities are consolidating vendor panels to single-source agreements that shift inventory risk.
- Manufacturers:Samsung and Foxconn cable harness facilities in Bac Ninh and Hai Phong create captive demand for just-in-time tape supply with embedded traceability features.
- Distributors:Channel intermediaries serving fragmented maintenance and repair demand across industrial estates.
- DIY Enthusiasts:Consumer retail segments for residential electrical repair with minimal specification rigor.
Contractors concentrate project value. Manufacturers are gaining share fastest on integrated supply contract expansion.
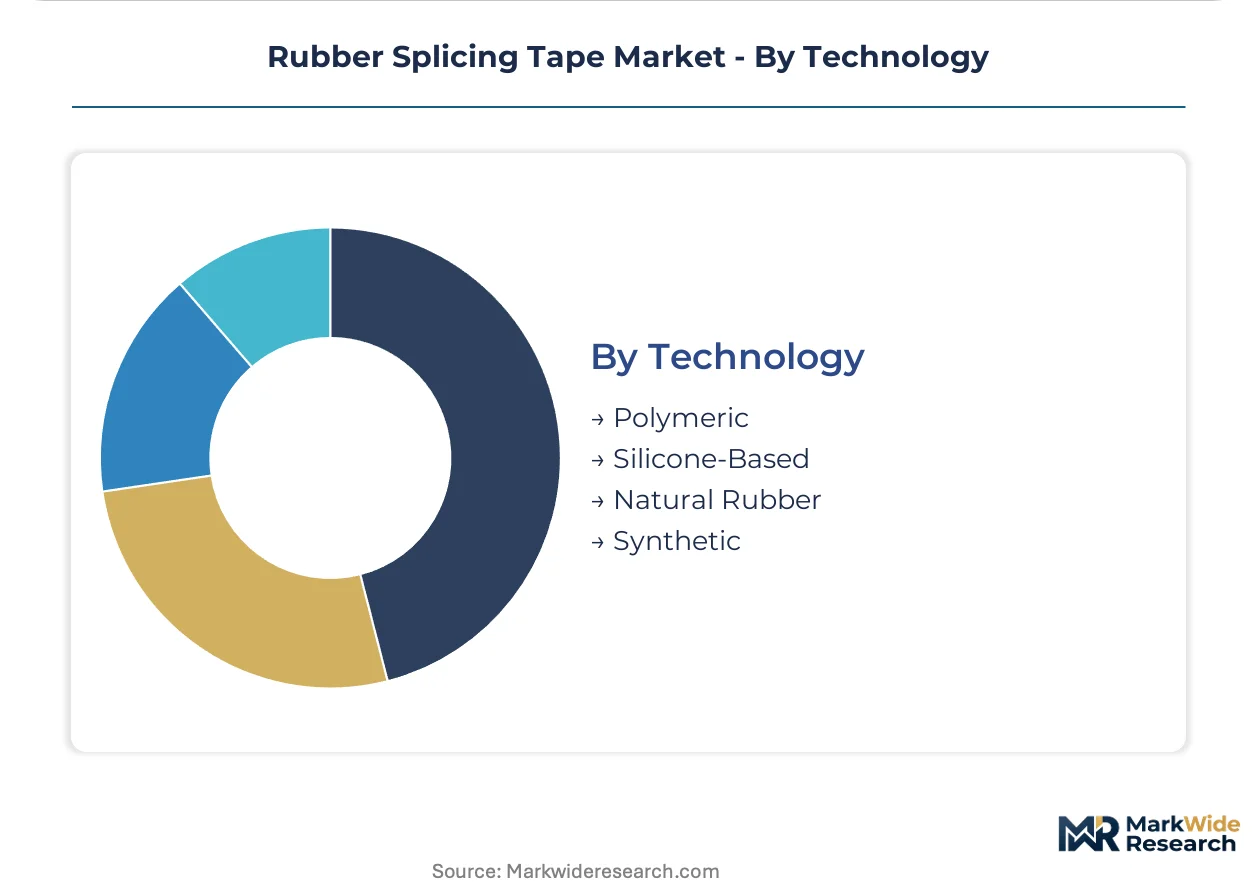
Technology:
Feedstock chemistry determines regulatory pathway efficiency, with silicone compounds bypassing REACH candidate list restrictions on chlorinated paraffins that ensnare legacy EPDM formulations.
- Silicone-Based:Self-fusing compounds with embedded temperature-indicating pigments digitize field inspection workflows. ECHA's 2023 update to REACH candidate list restrictions accelerates migration from halogenated plasticizer systems.
- Polymeric:Ethylene-propylene compounds with non-heavy-metal stabilizer chemistries serve cost-optimized utility specifications.
- Synthetic:Engineered elastomer blends for specialized chemical resistance profiles.
- Natural Rubber:Legacy formulations with limited thermal stability for ambient-temperature applications.
Silicone-Based leads specification preference. Polymeric retains volume scale on installed base maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian utilities demonstrate the lowest price elasticity as PLN's state-grid modernization mandates specification-grade procurement, while Vietnamese manufacturing corridors exhibit higher sensitivity where Foxconn and Samsung cable harness facilities drive volume-based negotiations.
Indonesia
PLN's medium-voltage expansion across Java and Sumatra corridors generates concentrated procurement for moisture-sealed jointing systems. The country's national electrical regulator enforces SNI certification parallel to IEC standards for imported insulation materials. Surabaya and Jakarta manufacturing zones anchor cable landing infrastructure serving offshore wind interconnection projects.
Vietnam
Samsung and Foxconn cable harness facilities in Bac Ninh and Hai Phong create captive demand for just-in-time tape supply with embedded traceability features. Vietnam's Ministry of Science and Technology administers QCVN standards that increasingly reference GB harmonization for electrical insulation imports. The northern manufacturing corridor concentrates specification-intensive automotive harness production.
China
SAMR's GB standard enforcement through designated testing laboratories shapes foreign supplier certification pathways. The country's dual carbon goals accelerate silicone-based tape preference in renewable interconnection and EV charging infrastructure. Yangtze River Delta industrial clusters integrate splicing tape procurement within bundled jointing kit contracts.
Germany
ECHA's 2023 REACH candidate list update on medium-chain chlorinated paraffins forces reformulation of legacy plasticizer systems across EPDM compound portfolios. German tier-one harness suppliers specify temperature-indicating pigment technologies for EV battery pack traceability. Bavaria and Baden-Württemberg automotive clusters drive specification intensity for thermal stability-rated materials.
United States
EPA and OSHA joint governance of workplace chemical exposure limits shapes plant location decisions and product chemistry for domestic compounders. The Inflation Reduction Act's clean energy tax credits accelerate utility-scale solar and offshore wind interconnection projects. Texas and California energy corridors concentrate procurement for submersible-rated waterproof variants in coastal cable landing applications.
Rubber Splicing Tape Market Competitive Landscape
Multinational chemical conglomerates and specialized adhesive tape manufacturers split the market between specification-grade electrical products and cost-optimized industrial variants. Three archetypes dominate: integrated resin compounders with captive formulation technology, regional converters leveraging localized compounding facilities, and automotive-tier suppliers bundling tape within harness assembly contracts. Competitive dynamics center on backward integration into EPDM feedstock and strategic partnerships with utility procurement panels.
Within the multinational tier, 3M Company and Henkel AG exemplify archetypes built on brand equity and direct utility relationships respectively. Nitto Denko Corporation anchors Asian supply positioning through integrated backing-film production capabilities. These three entities occupy positions that reflect divergent geographic anchoring and customer access models rather than interchangeable competitive postures.
| Leading Market Players |
|---|
| 3M Company |
| tesa SE |
| Nitto Denko Corporation |
| Avery Dennison Corporation |
| Intertape Polymer Group |
| Scapa Group plc |
| Shurtape Technologies, LLC |
| Saint-Gobain Performance Plastics |
| Henkel AG & Co. KGaA |
| Others |
Value Network & Pricing Analysis
EPDM resin concentration among Asian petrochemical majors in South Korea and Japan funnels pricing power toward integrated compounders while squeezing margin pools for third-party formulators dependent on spot feedstock markets.
Pricing Analysis
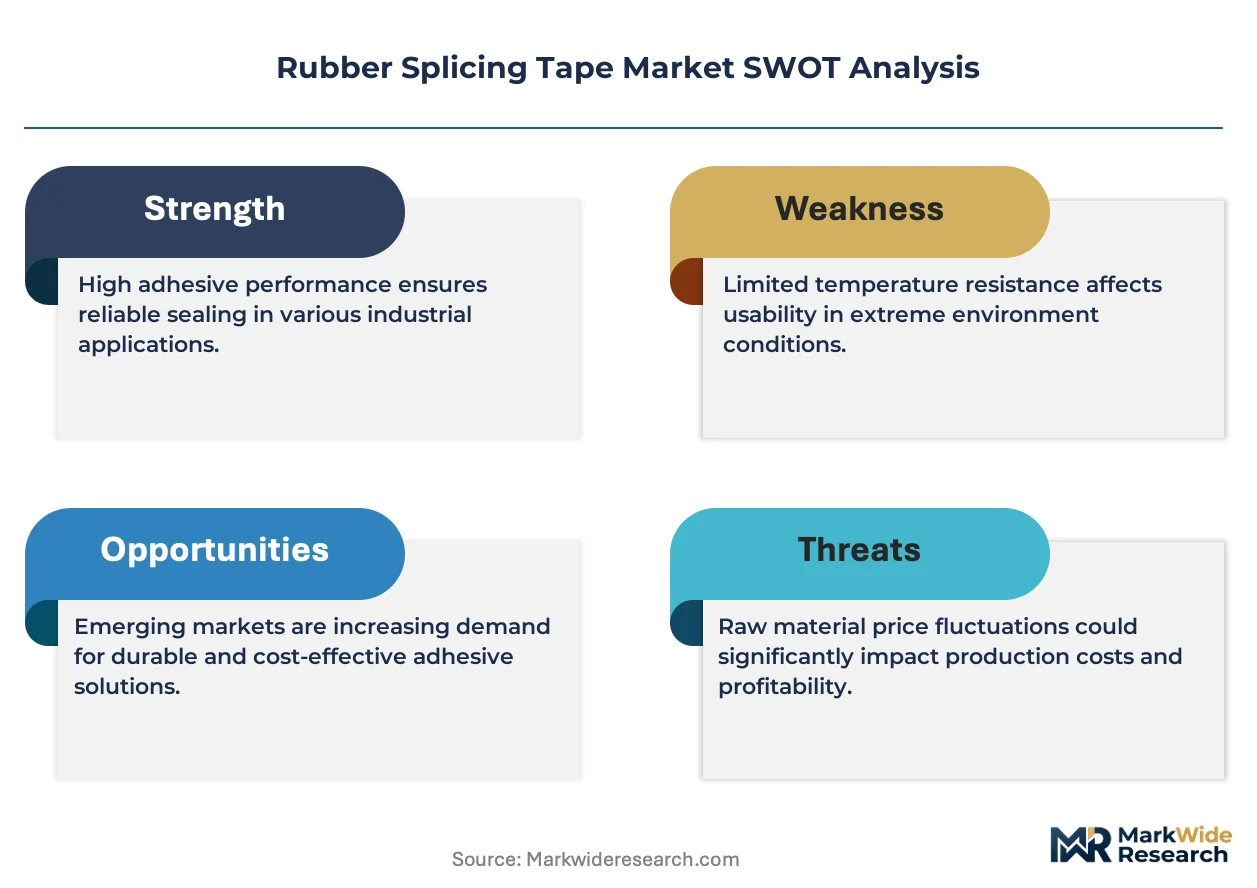
Aftermarket service revenue from cable jointing supervision and field repair drives lifetime value beyond unit tape sales. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade electrical products with full REACH dossiers from general-purpose alternatives. Cost compression in economy tiers intensifies because Vietnamese manufacturing corridors negotiate volume-based contracts. Contractors exhibit highest price sensitivity where procurement panels consolidate to single-source agreements, while Indonesian utilities demonstrate lowest sensitivity under PLN's mandated specification-grade procurement.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for cross-border compounders. Manufacturing concentrates in China, Japan, and Germany where integrated resin production and backing-film fabrication anchor output. Raw material dependencies rest on ethylene-propylene feedstock, silicone precursors, and halogen-free plasticizer alternatives. Single-source vulnerability persists for high-purity EPDM grades controlled by backward-integrated petrochemical majors. Distribution runs through direct utility relationships in Indonesia, just-in-time supply contracts in Vietnam, and bundled jointing kit channels in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rubber splicing tape sits in early-cycle expansion as EV charging infrastructure and offshore wind interconnection projects accelerate specification-grade demand beyond traditional utility replacement cycles.
For Market Incumbents: Harden formulation platforms against REACH candidate list volatility by pre-positioning phthalate-free flexibilizer alternatives through accelerated aging validation. Deepen backward integration into silicone precursor supply to bypass EPDM feedstock concentration risk. Lock in multi-year single-source agreements with Indonesian and Vietnamese utilities before procurement panels consolidate further.
For New Entrants and Emerging Players: Establish a beachhead in marine offshore wind applications where submersible-rated waterproof variants face limited incumbent specialization and specification windows remain open. Target North Sea and Baltic cable landing projects with accelerated ozone resistance certification. Lead with bundled installation supervision to differentiate from pure product suppliers.
For Investors and Strategic Acquirers: Capital is best deployed toward compounders with captive silicone formulation technology and existing GB standard certification through SAMR-designated laboratories. Long-term viability hinges on regulatory pathway efficiency across REACH, RoHS, and evolving GB harmonization. Watch for inflection when cold-shrink substitution rates plateau in medium-voltage utility maintenance protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Precursors | Circumvents EPDM feedstock concentration and REACH plasticizer restrictions entirely. |
| GB Standard Harmonization Investment | Reduces dual-certification overhead for SAMR-designated laboratory qualification. |
| Integrated Supply Contract Expansion | Bundles tape with jointing kits and supervision to shift inventory risk downstream. |
| Temperature-Indicating Pigment Development | Digitizes quality assurance for Japanese OEM EV battery pack traceability requirements. |
| Marine Offshore Wind Certification | Opens specification windows in North Sea and Baltic cable landing projects. |
Research Methodology
Cross-validation between primary interviews with cable jointer technicians, utility procurement officers, and compounder R&D directors and secondary sources including IEC certification databases, SAMR GB standard filings, and customs trade data anchors the qualitative findings. Bottom-up triangulation against top-down market sizing validates segment-level assumptions.
Calibration relies on modeling formulation chemistry splits, end-use application intensity, and regional regulatory cluster penetration across the projection horizon. Segmentation dimensions include product grade tier, installation environment, procurement authority type, and technology chemistry. CAGRs derive from elasticity-adjusted volume projections against utility capital expenditure cycles and automotive harness production schedules.
Sensitivities concentrate around REACH substance restriction timelines, cold-shrink substitution rates in utility maintenance protocols, and EPDM feedstock availability disruptions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Extruder Market
Rubber
Rubber Bulb Seals Market
Rubber
Rubber Gloves Market
Rubber
Liquid Silicone Rubber Market
Rubber
Solution Styrene Butadiene Rubber (S-SBR) Market
Rubber
Snap on Rubber Stopper Market
Rubber
Global Rubber Processing Chemicals Market
Rubber
Rubber Flooring Market
Rubber
Industrial Rubber Market
Rubber
Chloroprene Rubber Tape Market
Rubber
Rubber Choppers Market
Rubber
Industrial Rubber Products Market
Rubber
Rubber Chemicals Market
Rubber
Europe Rubber Derived Unrefined Pyrolysis Oil Market
Rubber
Synthetic Rubber Market
Rubber
Rubber Foam Materials Market