
 Tire Chemicals Market | 2026-2036
Tire Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Tire Chemicals Market Analysis
Asset-light toll manufacturing and third-party compounding arrangements is rewriting capital requirements for mid-tier chemical suppliers entering the tire value chain. BASF SE leverages its integrated antioxidant and filler portfolios across multiple tire maker supply agreements. Cabot Corporation anchors its position through captive carbon black capacity tied to major rubber processing hubs. Evonik Industries AG specializes in silica-silane coupling systems that enable reduced fuel consumption in passenger tire designs.
Tire chemicals comprise functional additives, reinforcing fillers, processing aids, and protective agents blended into rubber compounds to achieve specified tensile strength, abrasion resistance, and thermal stability targets. Antidegradants such as paraphenylenediamines protect against ozone cracking and flex fatigue in dynamic tire applications. The passenger car tire segment leads volume consumption due to global vehicle parc expansion, while eco-friendly grades are capturing margin pools as OEMs enforce sustainability scorecards across supply tiers. High-performance silica grades are displacing conventional carbon black in premium segments where wet grip and rolling resistance specifications tighten.
The EPA regulates particulate emissions from carbon black production under the Clean Air Act, while OSHA enforces permissible exposure limits for rubber process dust in mixing and milling operations. REACH restricts polycyclic aromatic hydrocarbon content in extender oils, compelling reformulation across European tire chemical supply chains. Stakeholders must monitor evolving chemical hazard classifications under ECHA's SVHC candidate list and calibrate product development pipelines accordingly.
Market Dynamics
REACH restrictions on polycyclic aromatic hydrocarbons in extender oils are forcing compounders across European tire supply chains to reformulate rubber recipes and qualify alternative plasticizers at accelerated timelines.
Growth Catalysts
- Electric vehicle OEM specifications:Battery-powered passenger car platforms mandate low-rolling-resistance tread compounds. Silica-silane coupling systems capture expanded specification sheets.
- REACH regulatory deadlines:European aromatic oil phase-outs accelerate migration to bio-based plasticizers and treated distillate aromatic extracts.
- China tire export capacity:Domestic manufacturers in Shandong and Jiangsu provinces scale compounding facilities to serve replacement demand across Southeast Asia and Middle East markets.
Market Restraints
- Carbon black feedstock volatility:High-sulfur fuel oil and coal tar pitch prices swing with refinery output decisions, compressing margin predictability for furnace black producers.
- Antioxidant supply concentration:Paraphenylenediamine manufacturing clusters in eastern China create single-source vulnerability for Western tire compounders.
- Silica surface chemistry limitations:Precipitated silica dispersion challenges in natural rubber compounds restrict full carbon black substitution in truck tire applications.
Strategic Opportunities
- India tire manufacturing expansion:PLI scheme incentives for domestic rubber processing capacity create localized chemical demand outside historical import dependence.
- Retread chemical formulations:Premium precure tread compounds require specialized bonding agents and vulcanization accelerators distinct from new tire recipes.
- Mass balance certification:ISCC PLUS tracking enables fossil-derived carbon black to claim circular feedstock status, unlocking OEM sustainability scorecard compliance.
Industry Challenges
- Rubber process safety expertise:OSHA permissible exposure limits for respirable crystalline silica require upgraded ventilation engineering at mixing mills.
- Multi-standard certification timelines:Simultaneous ECHA SVHC screening, EPA TSCA premanufacture review, and China GB standard alignment extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire Chemicals Market |
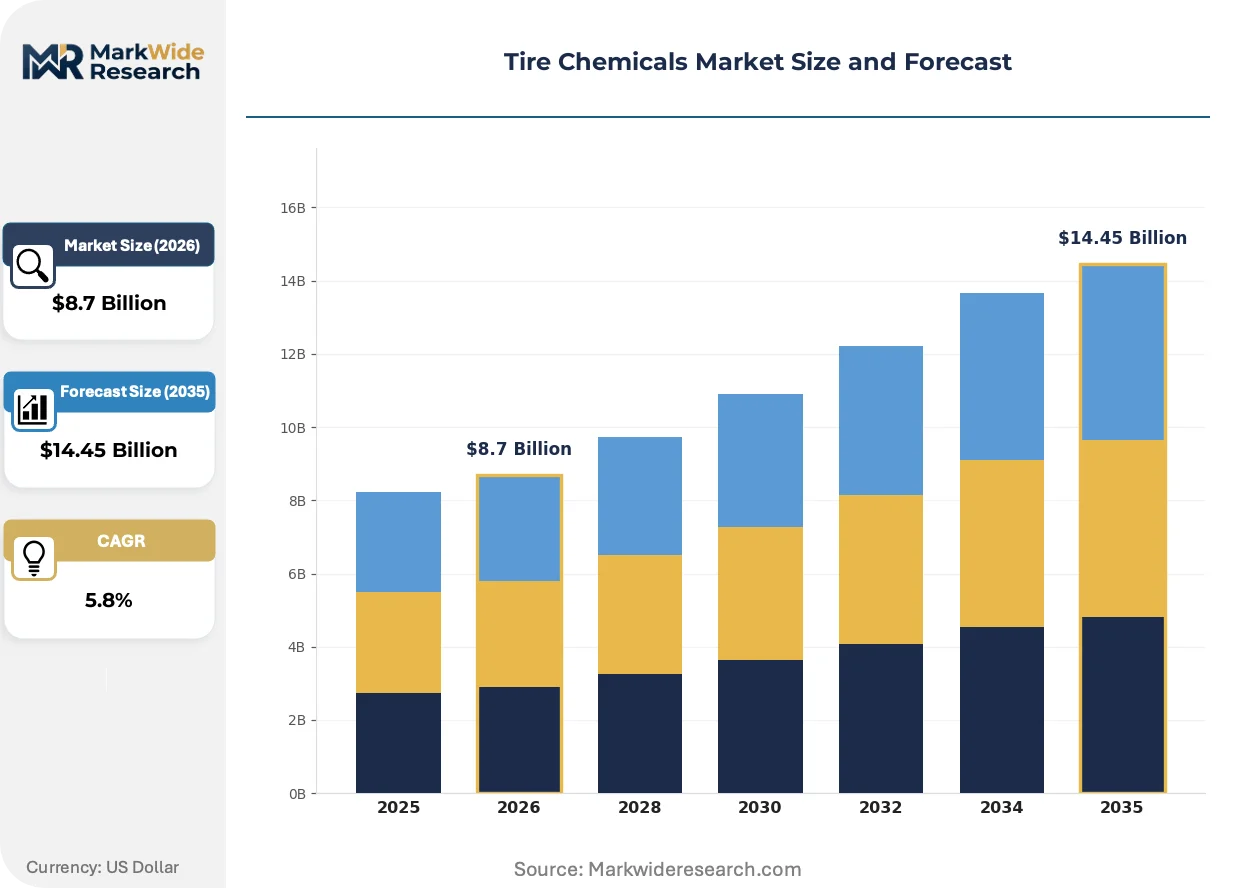
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antidegradants, Fillers, Reinforcing Agents, Processing Oils Application: Passenger Car Tires, Truck Tires, Two-Wheeler Tires, Specialty Tires End User: OEMs, Aftermarket Providers, Tire Manufacturers, Distributors Grade: High-Performance, Standard, Eco-Friendly, Specialty |
| Companies Covered | BASF SE, Cabot Corporation, Evonik Industries AG, Lanxess, Birla Carbon, ExxonMobil Corporation, Orion Engineered Carbons, Eastman Chemicals, Sinopec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire Chemicals Market Emerging Trajectories
Functional filler technologies and regulatory chemistry mandates are converging to redefine compound performance benchmarks and supplier qualification protocols across passenger and commercial tire segments.
High-dispersion silica grades engineered through in-situ silane modification are hybridizing conventional carbon black reinforcement in premium passenger tire treads. European OEM platforms specify these compounds for wet grip and rolling resistance targets. The technology is compressing specification windows for commodity carbon black grades in original equipment contracts.
EPA enforcement of Clean Air Act New Source Review requirements tightens particulate emission limits at carbon black production facilities. Furnace black manufacturers face capital decisions on baghouse upgrades or facility consolidation. Texas and Louisiana production sites encounter heightened state environmental agency scrutiny relative to imported material alternatives.
Long-term chemical supply agreements are displacing spot market purchasing among tier-one tire manufacturers. Compounders in Germany and Japan consolidate supplier panels to three-to-five approved partners per chemical category. This concentration is most visible in antioxidant and antiozonant procurement for high-volume passenger tire platforms.
Tire Chemicals Market Segmentation
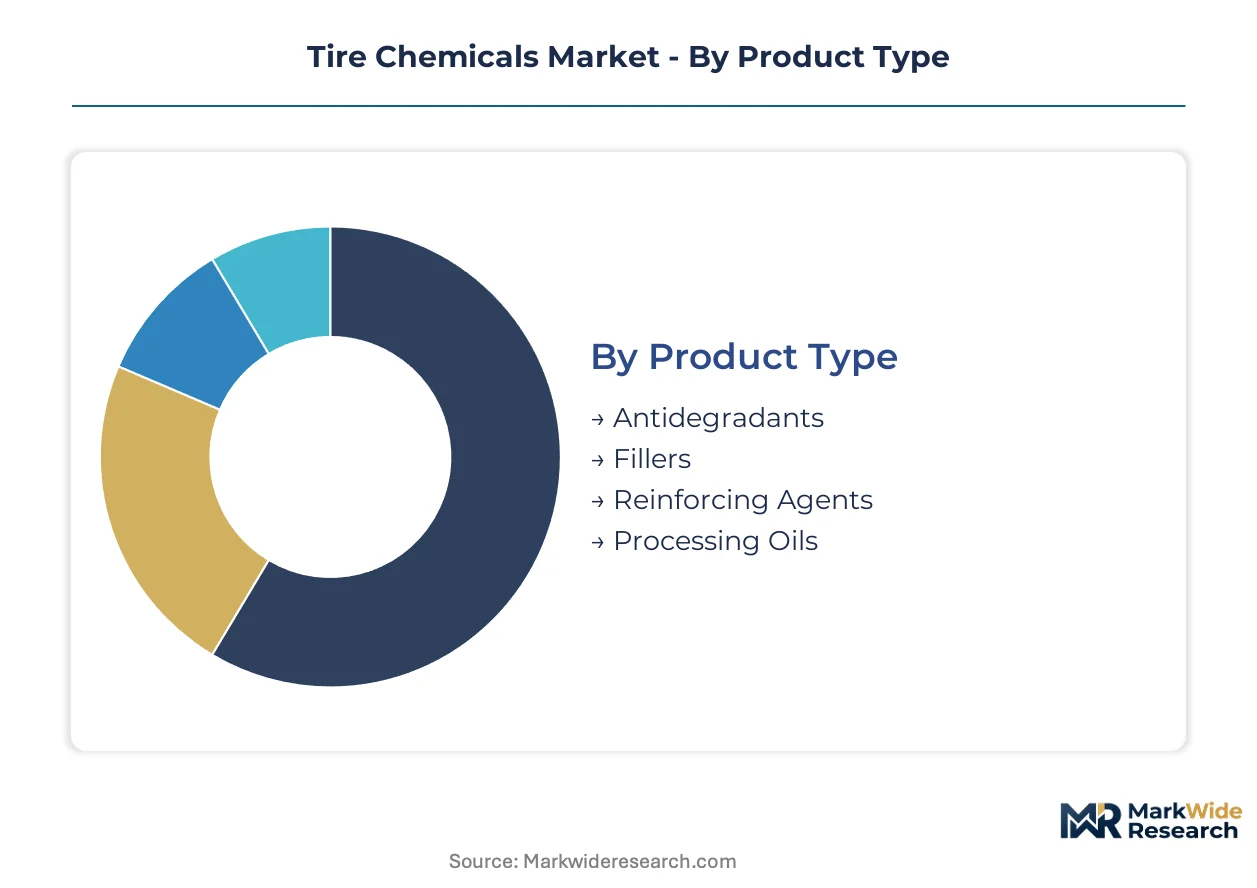
Tire chemical formulations vary sharply by vehicle platform and performance tier, with compounding recipes optimized for distinct stress profiles, rolling resistance targets, and regulatory exposure. Segmentation clarity enables suppliers to align R&D pipelines with OEM specification sheets and regional compliance calendars.
Product Type:
Mature antidegradant chemistries dominate procurement volumes, while emerging filler technologies capture specification upgrades in electric vehicle platforms.
- Antidegradants:Paraphenylenediamine derivatives and phenolic stabilizers protect rubber matrices against ozone attack and thermal oxidation during dynamic flex cycles. Demand concentrates in truck tire applications across North American long-haul fleets, where retread cycles extend compound exposure windows and antioxidant loadings run higher than passenger specifications.
- Fillers:Precipitated silica and carbon black particles modify tensile strength, abrasion resistance, and hysteresis characteristics in tread and sidewall compounds. European OEM platforms specify high-dispersion silica grades for wet grip ratings, with REACH aromatic oil restrictions accelerating silane coupling system adoption in German and French tire plants.
- Reinforcing Agents:Resorcinol-formaldehyde resins and cobalt adhesion promoters bond rubber to steel cord and textile reinforcements in belt and carcass plies.
- Processing Oils:Treated distillate aromatic extracts and bio-based plasticizers reduce compound viscosity during mixing and extrusion operations.
Antidegradants retain volume leadership; fillers hold the steepest expansion curve.
Application:
Cost tier stratification separates premium original equipment contracts from replacement market formulations, with specification density varying across vehicle classes.
- Passenger Car Tires:Low-rolling-resistance tread compounds incorporate high-silane silica loadings and functionalized solution SBR to meet EPA fuel economy credits and EU tire labeling requirements. Chinese EV OEMs specify these grades for battery range optimization, with domestic compounders in Jiangsu province scaling precipitation silica capacity to serve BYD and NIO supply agreements.
- Truck Tires:Natural rubber-dominant compounds resist abrasion and heat buildup under heavy axle loads and sustained highway speeds. Retread formulations for American commercial fleets require specialized bonding agents and vulcanization kinetics distinct from new tire recipes, creating discrete chemical demand pools.
- Two-Wheeler Tires:High-grip tread compounds for Southeast Asian motorcycle markets emphasize silica-carbon black hybrids at lower loadings than passenger specifications.
- Specialty Tires:Off-the-road mining and agricultural tires demand cut-resistant sidewall compounds with elevated carbon black and antidegradant concentrations.
Passenger car tires command the largest revenue base; specialty tires generate the highest margin per kilogram of chemical input.
End User:
Customer type determines contract structure, with OEMs enforcing sustainability scorecards and aftermarket channels prioritizing formulation flexibility.
- OEMs:Original equipment manufacturers specify chemical grades through approved supplier lists with multi-year volume commitments and ISCC PLUS mass balance certification requirements. German and Japanese automakers audit compounders for carbon intensity disclosures across antioxidant and filler supply tiers.
- Aftermarket Providers:Independent tire retailers and service chains procure chemical formulations through distributors, with pricing sensitivity higher than OEM channels and specification latitude enabling cost-optimized recipes.
- Tire Manufacturers:Integrated compounders at Bridgestone, Michelin, and Goodyear facilities blend chemicals in captive mixing operations with proprietary additive packages.
- Distributors:Regional chemical traders stock antioxidant and processing aid inventories for smaller compounders without direct supplier relationships.
Tire manufacturers absorb the highest chemical volumes; OEMs drive the fastest specification upgrades.
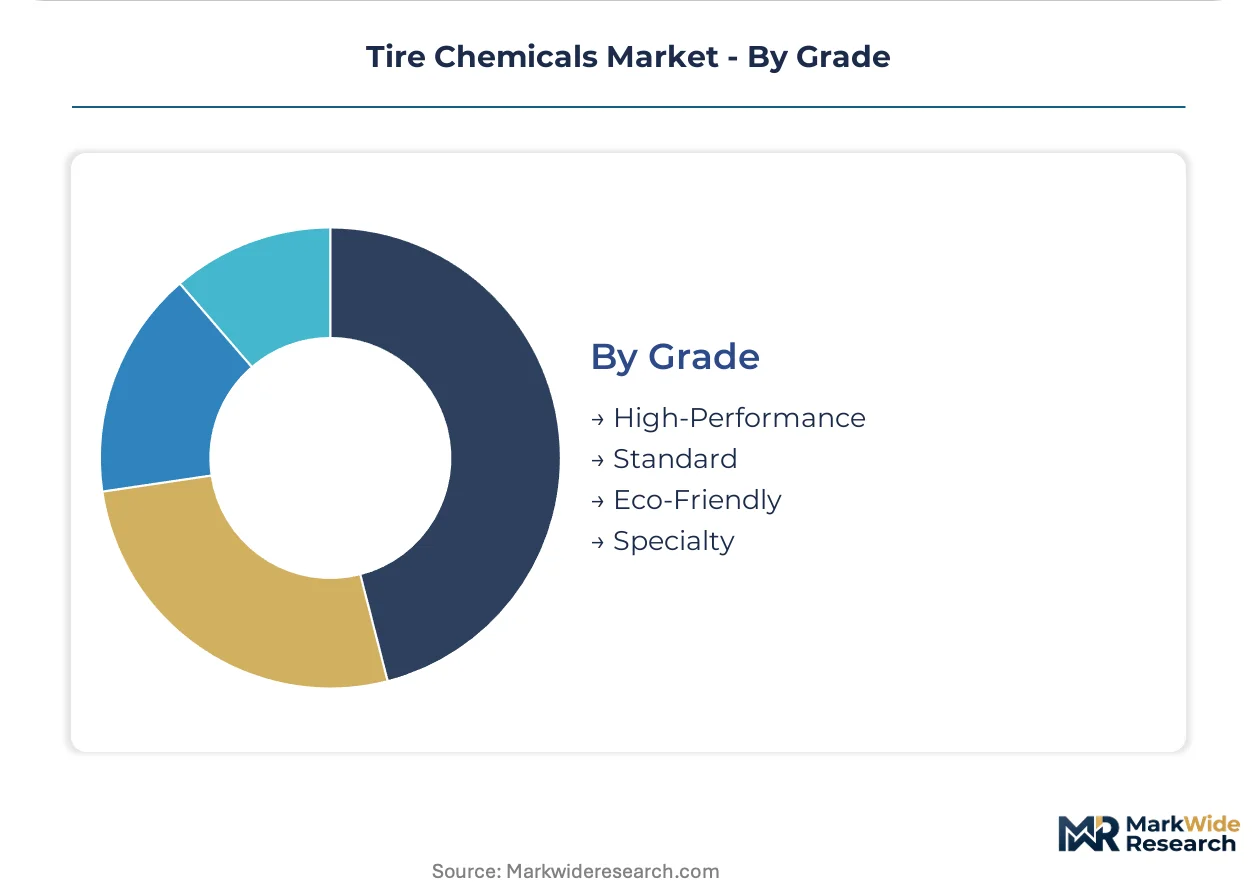
Grade:
Margin concentration aligns with performance tier, with premium grades capturing disproportionate value despite smaller unit volumes.
- High-Performance:Ultra-low-hysteresis silica grades and functionalized polymers enable A-grade wet grip and rolling resistance ratings on EU tire labels. Japanese luxury vehicle platforms specify these compounds for original equipment fitment.
- Standard:Conventional carbon black and commodity antioxidant packages serve replacement market tires with baseline regulatory compliance.
- Eco-Friendly:Bio-based plasticizers, recycled carbon black, and mass balance certified precipitated silica meet OEM sustainability scorecards and emerging green procurement mandates.
- Specialty:Aerospace tire compounds with extreme temperature stability and racing tire formulations with bespoke grip characteristics command formulation premiums.
Standard grades retain volume leadership; eco-friendly grades climb the fastest on regulatory pull.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands premium multiples over spot-indexed transactions in Shandong province. This asymmetry reflects specification density gaps between EU OEM sustainability scorecards and export-oriented replacement formulations. Chemical suppliers calibrate regional strategies against these divergent margin architectures.
United States
EPA Clean Air Act enforcement tightens particulate limits at carbon black furnaces in Texas and Louisiana. OSHA permissible exposure rules for rubber process dust force ventilation upgrades at mixing mills serving Detroit-area automotive clusters. Domestic tire makers in the Southeast states expand compounding capacity to reduce import dependence on Asian antioxidant shipments.
Germany
ECHA REACH aromatic oil restrictions accelerate bio-based plasticizer adoption across Continental and Michelin production sites. The KBA enforces rolling resistance verification for tire type approvals, pulling high-silica compound specifications into OEM contracts. Rhineland chemical parks integrate mass balance certification infrastructure to supply ISCC PLUS validated materials.
China
Domestic tire manufacturers in Shandong and Jiangsu provinces scale precipitated silica precipitation capacity to serve BYD and NIO supply agreements. MEE enforcement of dual carbon goals pressures coal-tar-based carbon black producers toward natural gas feedstock switching. Export-oriented compounders face GB standard alignment requirements for Middle East and Southeast Asian replacement markets.
India
PLI scheme incentives for domestic rubber processing capacity localize antioxidant and filler demand previously met through imports. BIS certification timelines extend product registration cycles for European and East Asian chemical suppliers. Tamil Nadu and Gujarat tire manufacturing corridors attract toll compounding investments to serve aftermarket distribution networks.
Japan
METI carbon neutrality roadmaps push Bridgestone and Yokohama Rubber toward low-hysteresis silica formulations for domestic EV platforms. JIS standards for tire labeling enforce wet grip and fuel efficiency thresholds that cascade into chemical specification sheets. Chubu region chemical producers specialize in silane coupling agent modifications for premium passenger tire exports.
Tire Chemicals Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in discrete additive categories. The tire chemicals sector exhibits consolidated leadership in carbon black and silica manufacturing alongside fragmented specialty antioxidant supply. Three archetypes dominate: integrated petrochemical conglomerates with captive carbon black capacity, specialty chemical houses focused on silane-silane coupling systems, and regional compounders leveraging toll manufacturing arrangements. Capacity expansion and mass balance certification acquisition represent the dominant competitive moves as OEM sustainability scorecards harden.
Among Germany-based chemical conglomerates, BASF SE and Evonik Industries AG occupy positions reflecting divergent strategic emphases. BASF SE anchors the integrated platform tier through combined antioxidant and filler portfolios. Evonik Industries AG exemplifies the specialty coupling agent archetype. Cabot Corporation represents North American carbon black manufacturing concentration. These three entities illustrate how geographic origin and corporate structure map onto distinct competitive positioning within tire chemical supply hierarchies.
| Leading Market Players |
|---|
| BASF SE |
| Cabot Corporation |
| Evonik Industries AG |
| Lanxess |
| Birla Carbon |
| ExxonMobil Corporation |
| Orion Engineered Carbons |
| Eastman Chemicals |
| Sinopec Corporation |
| Others |
Supply Flow & Price Mechanics
Shandong province's precipitated silica capacity expansion is compressing spot pricing for commodity grades while European REACH-compliant formulations sustain premium multiples. This geographic asymmetry rewards suppliers with mass balance certification infrastructure against those tethered to aromatic oil formulations facing regulatory phase-out.
Pricing Analysis
Configured-to-order silica-silane systems command spreads of 40-60 percent above standard carbon black quotations due to OEM specification density. Pricing stratifies across ISCC PLUS certified, high-performance, and commodity standard tiers. Cost compression in furnace black runs through feedstock volatility in high-sulfur fuel oil markets. Aftermarket distributors exhibit highest price sensitivity; German OEM direct contracts show lowest.
Supply Chain Analysis
Coal tar pitch and high-sulfur fuel oil feedstocks draw from refinery byproduct streams concentrated in China, the United States, and India. Precipitated silica production rests on sodium silicate and sulfuric acid inputs. Single-source vulnerability clusters in eastern Chinese paraphenylenediamine manufacturing. Distribution runs through long-term chemical supply agreements displacing spot purchasing at tier-one tire manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle platform mandates for low-rolling-resistance compounds are disrupting procurement patterns faster than incumbent capacity can pivot. REACH aromatic oil restrictions compound this inflection by disqualifying legacy formulations from European OEM contracts.
For Market Incumbents: Pre-empt substitution threats by accelerating ISCC PLUS certification acquisition across carbon black and silica portfolios. Lock in backward integration into bio-based plasticizer feedstocks before alternative suppliers capture reformulation cycles. Defensive capacity consolidation in Rhineland chemical parks protects margin position against Asian import competition.
For New Entrants and Emerging Players: Pursue toll compounding arrangements with Shandong and Jiangsu tire manufacturers seeking to bypass import dependence on Western antioxidant shipments. India's PLI-scheme rubber processing corridors offer the most penetrable geography. A technical service partnership model with domestic compounders accelerates qualification timelines versus direct supplier approval routes.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because sustainability scorecard compliance creates tiered access to OEM contract pools. Target specialty silane coupling agent producers with existing automotive qualification. Watch for ECHA SVHC candidate list expansions as the signal for accelerated reformulation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Mass Balance Certification Acquisition | ISCC PLUS validation unlocks OEM sustainability scorecard compliance for fossil-derived carbon black. |
| Backward Integration into Bio-Plasticizers | Captive supply of treated distillate aromatic extracts hedges REACH aromatic oil phase-out exposure. |
| Silica Precipitation Capacity Expansion | Jiangsu province greenfield sites capture BYD and NIO low-rolling-resistance specification demand. |
| Long-term Supply Agreement Consolidation | German and Japanese tire makers compress supplier panels to three approved partners per chemical category. |
| Toll Manufacturing Partnership | Asset-light arrangements reduce capital requirements for mid-tier entrants serving export-oriented compounders. |
Methodological Framework
Initial hypotheses were tested against primary input from tire compounder procurement leads, rubber processing plant managers, OEM sustainability officers, and chemical distribution channel partners and refined through secondary validation against customs trade data, SEC 10-K filings, Cefic industry reports, and ECHA regulatory databases. Bottom-up volume modeling triangulated with top-down market sizing across antioxidant, filler, and processing aid categories.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled included grade tier, end-use vehicle platform, regional production hub, and sustainability certification status. CAGRs derived from trend extrapolation of historical volume trajectories adjusted for regulatory inflection points. Silica displacement rates in passenger tire treads and carbon black feedstock cost curves served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, refinery output decisions, or battery electric vehicle penetration would shift the trajectory. Forecasts reflect documented assumptions regarding REACH implementation timelines and Chinese dual carbon enforcement intensity. Cross-checking against IHS Markit vehicle production databases and EIA refinery utilization benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Gum Rosin Market
Rubber
Cellular Rubber Market
Rubber
EMEA and Asia Pacific Electrical Insulating Rubber Gloves Market
Rubber
Global Rubber Additives Market
Rubber
Liquid Silicone Rubber Market
Rubber
Tire Reinforcement Materials Market
Rubber
Butyl Rubber Market
Rubber
Rubber Seal Plugs Market
Rubber
Rubber Bulbs Market
Rubber
Rubber Roller Cleaner Market
Rubber
Global Medical Rubber Stopper Market
Rubber
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Rubber
Global Liquid Synthetic Rubber Market
Rubber
Corrosion Protection Rubber Linings and Coatings Market
Rubber
Global Rubber Processing Chemicals Market
Rubber
Global Thermoplastic Vulcanizate (TPV) Market