
 Polybutadiene Elastomers Market | 2026-2036
Polybutadiene Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Polybutadiene Elastomers Market Intelligence
Custom formulation support services for specific end-use applications is rebalancing the traditional volume-based sales model toward value-added partnerships. ARLANXEO leverages its extensive portfolio of high-performance grades to serve the global automotive tire sector. LANXESS sustains its market position through significant R&D investment in synthetic rubber technologies, while Kumho Petrochemical specializes in solution-polymerized products for demanding industrial applications.
Polybutadiene elastomers are synthetic rubbers derived from the polymerization of 1,3-butadiene. Characterized by high resistance to abrasion and low heat buildup, these materials are crucial for applications requiring durability and resilience. The automotive industry, particularly for tire manufacturing, constitutes the largest end-use segment by a significant margin. High-performance and solution-polymerized grades represent the fastest-growing categories, displacing older emulsion-polymerized variants in specialized applications.
European Union's REACH regulations and tire labeling standards govern chemical safety and performance claims, impacting material formulation. In the United States, EPA rules on volatile organic compounds (VOCs) and fuel economy influence polymer selection for both tire and non-tire applications. Future investment decisions for producers will hinge on balancing the production of commodity grades against the higher-margin, but more capital-intensive, specialty high-performance elastomers.
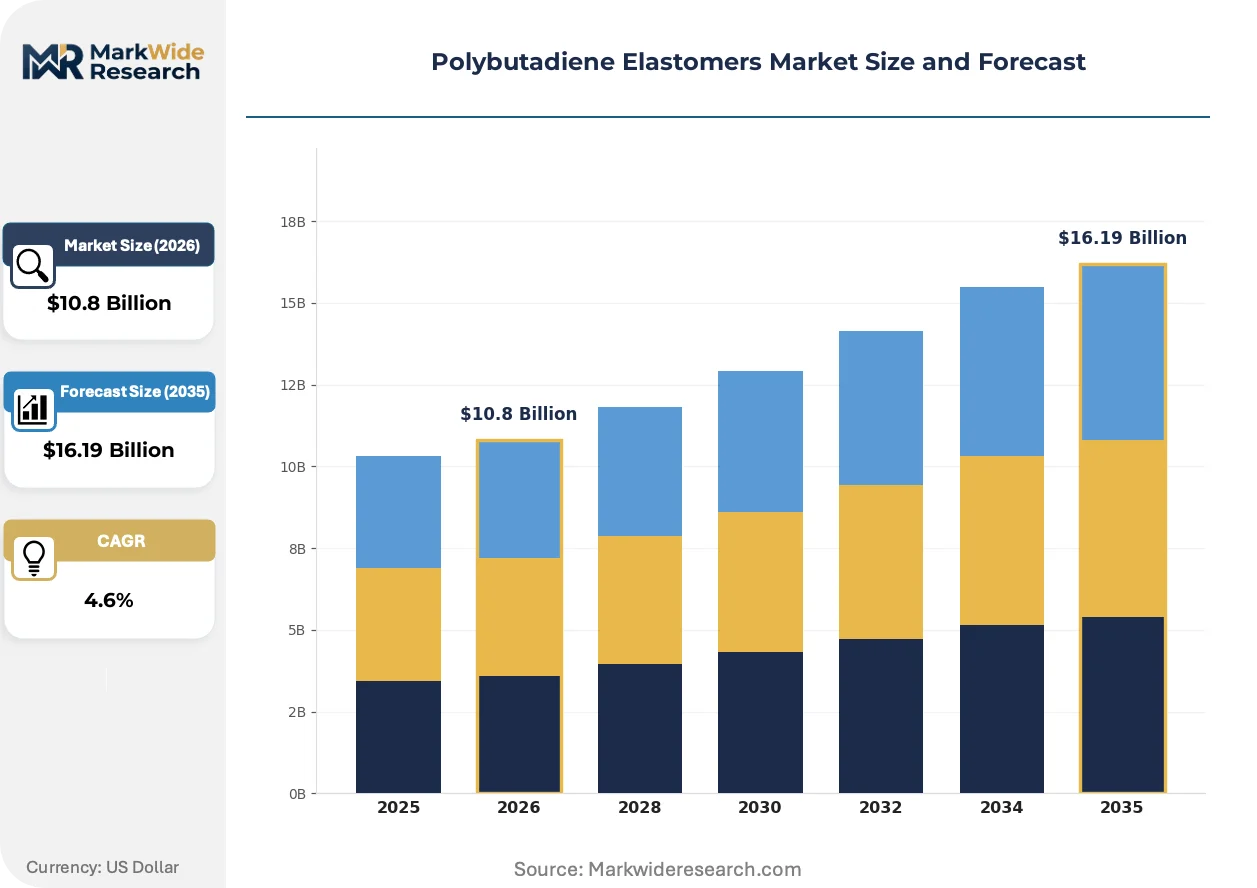
Market Dynamics
The polybutadiene elastomers market is defined by the structural tension between high-volume, commodity-grade production for standard tires and the capital-intensive development of high-performance grades. This divergence is driven by global automotive regulations mandating improved fuel efficiency and safety, forcing a value-over-volume re-evaluation.
Growth Catalysts
- Tire Labeling Regulations:European Union tire labeling standards, which mandate ratings for fuel efficiency, wet grip, and noise, directly compel the use of advanced polybutadiene grades to meet higher performance tiers.
- Automotive Sector Expansion:China's continued dominance in automotive production and its expanding industrial goods sector create a concentrated and sustained demand base for all grades of polybutadiene elastomers.
- Solution Polymerization Technology:The adoption of solution-polymerized polybutadiene (S-PBR) enables precise control over polymer properties, meeting demand for specialized materials in high-performance tires and demanding industrial applications.
Market Restraints
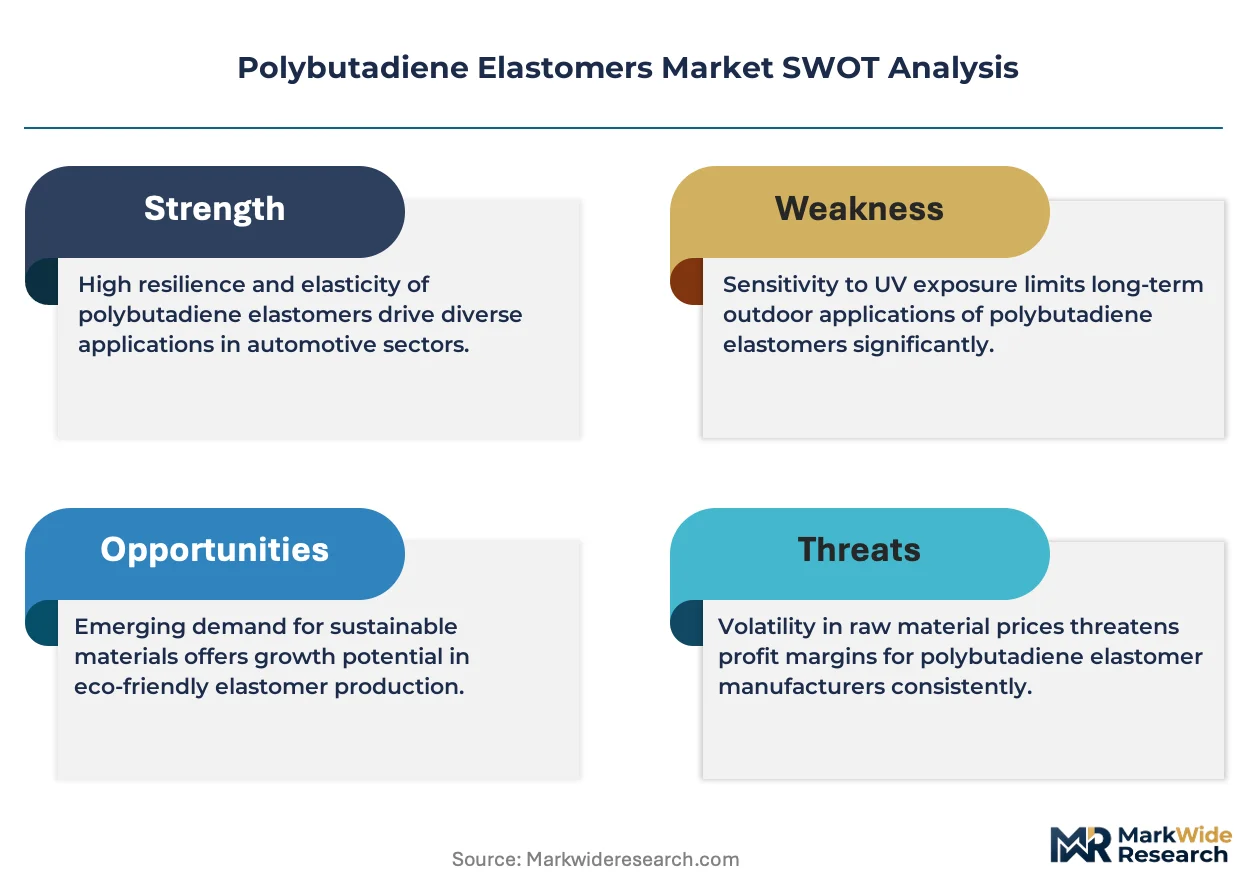
- Feedstock Price Volatility:As a derivative of crude oil, the price of 1,3-butadiene feedstock is volatile and subject to geopolitical factors and refinery operating rates, creating cost instability for elastomer producers.
- Regulatory Compliance Burden:The European Union's REACH framework imposes significant testing and registration costs on chemical manufacturers, potentially slowing the introduction of novel polymer formulations to the market.
- Substitution from Other Synthetics:In certain tire components and non-tire applications, polybutadiene faces competition from other synthetic rubbers like styrene-butadiene rubber (SBR), which can offer a different balance of properties.
Strategic Opportunities
- Polymer Modification Applications:Growing use of polybutadiene as an impact modifier for plastics such as high-impact polystyrene (HIPS) and acrylonitrile butadiene styrene (ABS) opens a significant non-tire growth avenue.
- Emerging Automotive Hubs:Automotive manufacturing growth in Southeast Asian countries provides an opportunity for producers to establish supply chains and partnerships in markets with rising elastomer consumption.
- Advanced Material Composites:The development of functionalized polybutadiene for use in electric vehicle tires and advanced composites presents a high-value opportunity, targeting enhanced durability and energy efficiency.
Industry Challenges
- High Capital Investment:The construction of new polymerization facilities, particularly for advanced solution-polymerized grades, requires substantial capital expenditure, creating a high barrier to entry and capacity expansion.
- Logistical Complexity:Managing the global supply chain for a bulk chemical product involves navigating fluctuating shipping costs, port congestion, and geopolitical risks that can disrupt material flow to key manufacturing regions.
- Process Standardization:A lack of global standardization for testing methods related to tire performance metrics like abrasion resistance can create friction between elastomer suppliers and their automotive customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polybutadiene Elastomers Market |
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $16.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Performance, Solution-Polymerized, Emulsion-Polymerized, Styrene-Butadiene End Use Industry: Automotive, Footwear, Consumer Goods, Industrial Goods Form: Solid, Liquid, Powder, Granule Application: Tires, Sealants, Adhesives, Coatings |
| Companies Covered | LANXESS, JSR Corporation, ARLANXEO, LG Chem, Synthos, Kumho Petrochemical, SABIC, China Petroleum & Chemical Corporation, Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polybutadiene Elastomers Market Strategic Shifts & Innovations
The market's evolution is marked by a clear pivot from commodity supply to application-specific performance, driven by technological advancements in polymerization and stringent environmental mandates. This shift prioritizes material characteristics that directly contribute to end-product efficiency and durability.
Solution-polymerized polybutadiene (S-PBR) provides superior control over polymer microstructure, enabling the creation of materials with tailored performance traits. High-performance tire producers and manufacturers of technical rubber goods are steadily adopting these advanced grades. As a result, S-PBR is overtaking older emulsion-polymerized variants in applications where low rolling resistance and high wear resistance are critical design requirements.
In the United States, the Environmental Protection Agency's (EPA) fuel economy standards are a powerful force shaping material development. These regulations directly link vehicle efficiency to tire performance, creating a strong incentive for innovation in rubber chemistry. The high-performance and electric vehicle tire segments are most impacted, accelerating the adoption of specialty polybutadiene elastomers that reduce energy loss.
A notable behavioral change involves end-users seeking collaborative, custom formulation services over simple transactional purchases. This move from volume-based procurement to value-added partnerships disrupts the traditional sales model, favoring suppliers who can provide deep technical support. This trend is most pronounced within the specialty industrial goods and advanced automotive components sectors across North America and Europe.
Polybutadiene Elastomers Market Segmentation
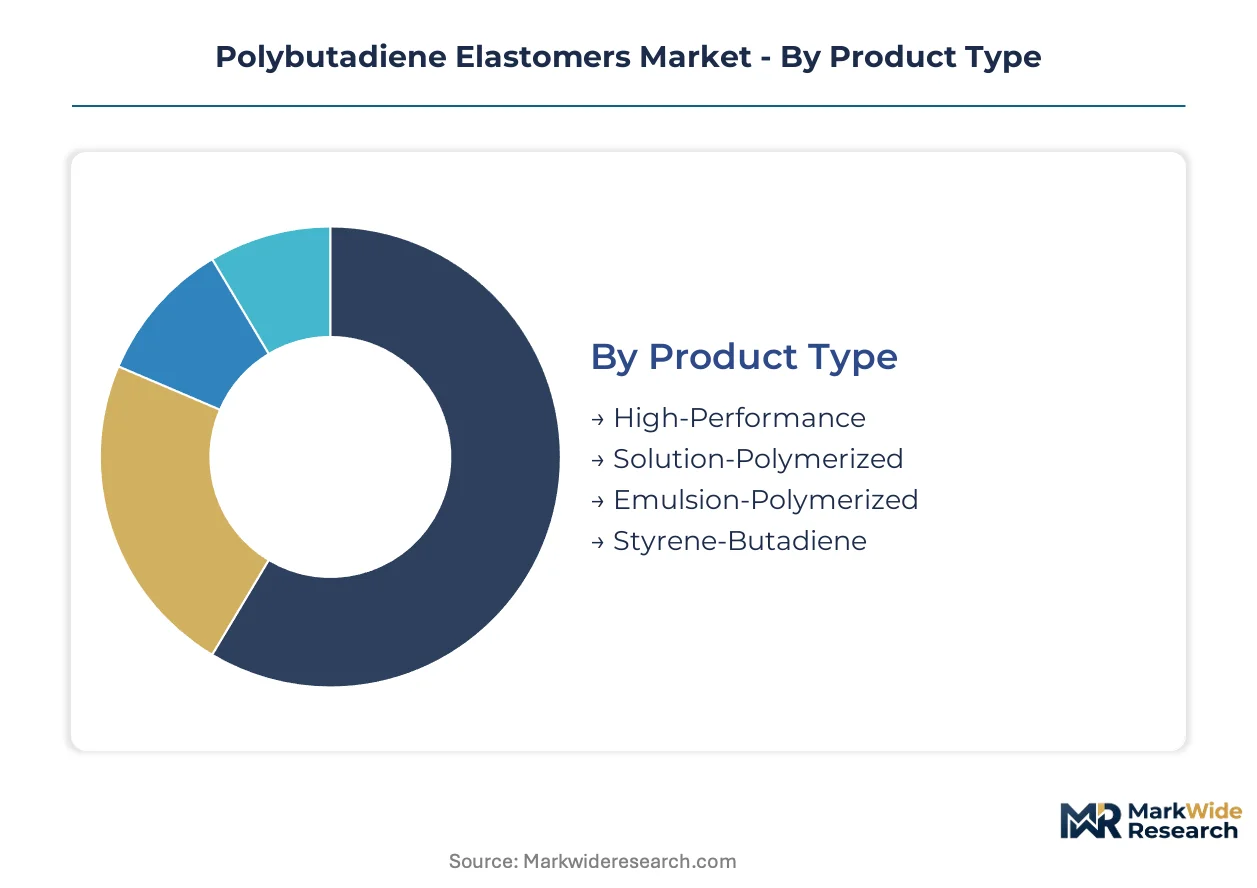
The polybutadiene elastomers market is meticulously segmented to reflect the diverse product characteristics, broad industrial applications, and varying physical forms of these critical materials. Understanding these segments provides a granular view of demand drivers and competitive dynamics across the value chain.
Product Type:
Specific product types within polybutadiene elastomers face varying regulatory scrutiny, with advanced grades often requiring extensive validation to meet performance and safety standards like the European Union's REACH framework.
- High-Performance:These grades offer enhanced properties such as superior abrasion resistance, reduced rolling resistance, and improved wet grip, crucial for meeting stringent automotive tire labeling standards in Europe. Demand for high-performance elastomers is concentrating in advanced tire manufacturing hubs like Germany and Japan.
- Solution-Polymerized:S-PBR provides precise control over polymer microstructure, enabling tailored properties for specialized applications in electric vehicle tires and demanding industrial parts. The United States EPA fuel economy standards strongly incentivize the adoption of these materials for vehicle efficiency.
- Emulsion-Polymerized:These are commodity grades produced via emulsion polymerization, offering cost-effectiveness for standard tire components and general rubber goods. China's expansive automotive and industrial sectors maintain a consistent demand base for these conventional variants.
- Styrene-Butadiene:As a co-polymer, styrene-butadiene rubber (SBR) often competes with polybutadiene in tire treads and other rubber applications, providing a different balance of properties.
Leading the category by volume: Emulsion-Polymerized. Solution-Polymerized represents the fastest-growing category.
End Use Industry:
The diverse end-use industries for polybutadiene elastomers dictate distinct material specifications and performance requirements.
- Automotive:This sector constitutes the largest consumer of polybutadiene elastomers, primarily for tire manufacturing, where durability and low heat buildup are paramount. China's dominant position in global automotive production drives substantial and sustained demand.
- Industrial Goods:Polybutadiene finds extensive use in conveyor belts, hoses, and seals, where its resilience and abrasion resistance are highly valued. Kumho Petrochemical specializes in solution-polymerized products for these demanding industrial applications.
- Footwear:Polybutadiene elastomers contribute to the durability and flexibility of shoe soles, particularly in athletic and work footwear.
- Consumer Goods:Various consumer products, including sporting equipment and household items, utilize polybutadiene for its elastic properties and wear resistance.
Automotive production consumes the largest volume, while industrial goods applications demonstrate significant expansion.
Form:
Different physical forms of polybutadiene elastomers enable distinct processing methods and cater to varied manufacturing scales.
- Solid:This form, typically bales or sheets, is the most common for bulk processing in tire plants and large-scale rubber goods manufacturing. Solid polybutadiene elastomers offer ease of handling and blending in traditional rubber compounding operations.
- Liquid:Liquid polybutadiene (L-PBR) acts as a reactive plasticizer or binder, enhancing processability and final product properties in specialized formulations. These are often utilized in coatings and adhesives for enhanced flexibility and impact resistance.
- Powder:Powdered polybutadiene is frequently used as an impact modifier for plastics like high-impact polystyrene (HIPS) and acrylonitrile butadiene styrene (ABS).
- Granule:Granular forms facilitate automated feeding systems and consistent dosing in continuous compounding processes.
Solid forms dominate established markets, with liquid variants gaining traction in specialized formulations.
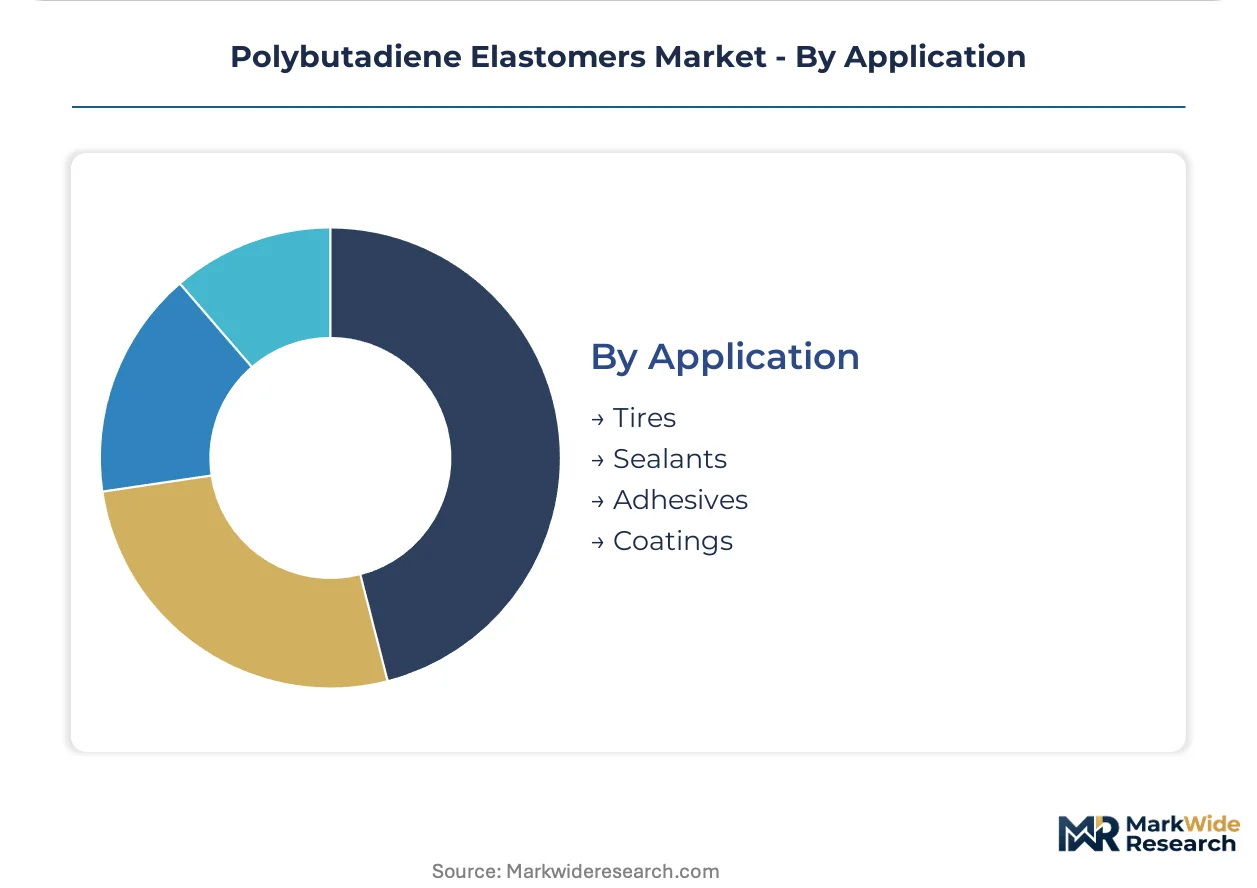
Application:
Polybutadiene elastomers find critical utility across a range of applications, each demanding specific material properties for optimal performance.
- Tires:Polybutadiene's high resistance to abrasion and low heat buildup makes it indispensable for tire treads, sidewalls, and inner liners, contributing to tire longevity and fuel efficiency. European Union tire labeling standards directly compel the use of advanced polybutadiene grades in this segment.
- Adhesives:Polybutadiene is incorporated into adhesive formulations to impart flexibility, impact strength, and improved bonding characteristics for various substrates. This application represents a significant non-tire growth avenue for the material.
- Sealants:Its elastic recovery and chemical resistance make polybutadiene suitable for various sealing applications in construction and automotive sectors.
- Coatings:Polybutadiene-based coatings offer protective properties, including abrasion resistance and flexibility, for industrial and specialty applications.
Tire manufacturing remains the dominant application, while adhesive formulations are seeing considerable innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polybutadiene elastomers production and consumption patterns vary significantly across regions. China dominates both manufacturing and demand, while Europe and the United States focus on high-performance grades. This regional specialization shapes supply chains and investment decisions for producers.
China
China's expansive automotive production and industrial goods manufacturing drive substantial demand for polybutadiene elastomers. The country's national GB standards influence material specifications for various rubber products. Major industrial clusters in the Yangtze River Delta and Pearl River Delta areas concentrate significant elastomer consumption for both tire and non-tire applications.
Germany
Germany's advanced tire manufacturing sector demands high-performance polybutadiene grades for premium automotive applications. European Union tire labeling standards compel German manufacturers to use materials that improve fuel efficiency and wet grip. The Rhine-Ruhr region, with its strong chemical and automotive industries, serves as a hub for both production and consumption of specialty elastomers.
United States
The United States automotive market, particularly for electric vehicles, creates strong demand for solution-polymerized polybutadiene. The Environmental Protection Agency's (EPA) fuel economy standards incentivize the adoption of advanced materials for vehicle efficiency. Major automotive manufacturing centers in the Midwest, such as Detroit, drive significant procurement of specialized rubber components.
Japan
Japan's sophisticated automotive industry and focus on advanced materials technology generate consistent demand for high-performance polybutadiene elastomers. Japanese Industrial Standards (JIS) guide material quality and performance in various applications. The Kanto region, including Tokyo, hosts significant research and development activities alongside manufacturing facilities for advanced rubber products.
South Korea
South Korea's robust automotive sector and chemical industry contribute to substantial polybutadiene elastomer consumption. The country's national quality standards ensure performance and safety for tire and industrial applications. Manufacturing hubs in the Gyeonggi province and Ulsan concentrate production and processing of synthetic rubbers for both domestic and export markets.
Polybutadiene Elastomers Market Key Industry Players
Capital-heavy producers compete with asset-light designers, creating a structural tension between commodity volume and specialty value. The polybutadiene elastomers market exhibits a tiered structure, with large integrated chemical companies alongside specialized elastomer manufacturers. Key strategic archetypes include global chemical giants leveraging scale and niche players focusing on advanced material formulations. Companies pursue competitive advantage through significant R&D investment in synthetic rubber technologies and targeted capacity expansion for high-performance grades.
Specialists in high-performance elastomers include ARLANXEO, which leverages its extensive portfolio to serve the global automotive tire sector. LANXESS sustains its market position through significant R&D investment in synthetic rubber technologies. Kumho Petrochemical exemplifies a focused strategy, specializing in solution-polymerized products for demanding industrial applications across various end-use segments.
| Leading Market Players |
|---|
| LANXESS |
| JSR Corporation |
| ARLANXEO |
| LG Chem |
| Synthos |
| Kumho Petrochemical |
| SABIC |
| China Petroleum & Chemical Corporation |
| Asahi Kasei Corporation |
| Others |
Cost & Logistics Intelligence
Stricter global tire labeling regulations for fuel efficiency and wet grip are compelling downstream manufacturers to demand specialized polybutadiene elastomers, which in turn forces suppliers to invest in advanced production capabilities and higher-value pricing models.
Pricing Analysis
Margin tightening in commodity-grade emulsion-polymerized polybutadiene reflects intense competition and volatile 1,3-butadiene feedstock costs. The dominant pricing model remains contract-based long-term offtake agreements for bulk volumes, supplemented by commodity spot pricing for immediate needs. Price differentiation stems from quality grade, adherence to certifications like EU REACH, and the level of custom formulation support. Buyers of standard emulsion-polymerized grades exhibit higher price sensitivity, while manufacturers requiring high-performance or solution-polymerized elastomers prioritize consistent quality and technical service.
Supply Chain Analysis
Mandated dual-sourcing requirements for critical automotive and industrial applications are diversifying procurement strategies for polybutadiene elastomers. Geographic supply concentration for 1,3-butadiene feedstock centers in China, South Korea, and Japan, which also serve as major production hubs for the elastomers themselves. The supply chain draws heavily from crude oil derivatives, making it highly susceptible to geopolitical factors and refinery operating rates. A significant structural risk is feedstock price volatility, impacting producer margins. Distribution runs through direct sales channels to large-scale tire and industrial manufacturers, complemented by regional distributors for smaller-volume specialty buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polybutadiene elastomers market is engaged in a vertical-integration race, driven by producers seeking to control feedstock supply and customize polymer properties for high-value applications.
For Market Incumbents: Deploy strategic R&D investment to functionalize polybutadiene for electric vehicle tires and advanced composites. This move defends against substitution from other synthetic rubbers like SBR and addresses emerging performance demands. Incumbents should also pursue targeted capacity expansion for solution-polymerized grades in regions like the United States, aligning with EPA fuel economy standards. Diversifying into polymer modification applications for plastics offers a defensive play against margin pressure in commodity segments.
For New Entrants and Emerging Players: Enter via specialized niches focusing on custom formulation services for demanding industrial applications. The most penetrable segment for new players is high-performance elastomers for non-tire applications, where technical expertise commands a premium. A viable go-to-market angle involves offering advanced material composites with enhanced durability and energy efficiency, leveraging partnerships with smaller, agile manufacturers in emerging automotive hubs in Southeast Asia.
For Investors and Strategic Acquirers: The window for entry favors patient capital seeking long-term value creation in specialty chemical assets. Acquisition targets should be niche players with proprietary solution polymerization technologies or strong intellectual property in functionalized polybutadiene. A specific signal to watch is the acceleration of automotive OEM collaborations with elastomer suppliers for next-generation EV tire development, indicating a shift towards performance-driven material innovation.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Solution Polymerization R&D | Develops advanced materials with tailored properties for high-performance tire and industrial applications, meeting stringent regulatory demands. |
| Expand High-Performance Grade Capacity | Addresses the growing demand for specialized elastomers in automotive and industrial sectors, particularly in China and the United States. |
| Formulate Custom Application Solutions | Shifts the business model from volume-based sales to value-added partnerships, enhancing customer loyalty and market differentiation. |
| Secure 1,3-Butadiene Feedstock Agreements | Mitigates price volatility risks and ensures stable supply for polybutadiene production, safeguarding operational continuity. |
| Target Emerging Automotive Hubs | Establishes supply chains in high-growth markets like Southeast Asia, capturing rising elastomer consumption for automotive manufacturing. |
Research Approach
Industry reports from chemical associations, customs and trade data, and SEC 10-K filings from publicly traded chemical companies formed the secondary backbone of this analysis. This was rigorously combined with primary interviews conducted with plant managers, procurement leads at downstream OEMs, and technical R&D directors across the polybutadiene elastomers value chain. The approach utilized both bottom-up market sizing and top-down validation to ensure data accuracy.
Historical trendline analysis provided the foundation for projecting market trajectories across the analysis window. The forecast framework modeled segmentation dimensions including product type, end-use industry, form, application, and regional production hubs. Compound Annual Growth Rates were derived from an assessment of demand drivers and market restraints, integrating key inputs such as projected automotive production volumes and 1,3-butadiene supply forecasts.
Revisions become necessary when significant shifts in crude oil prices, global automotive production, or environmental regulations materialize. Forecasts reflect assumptions regarding technological adoption rates and geopolitical stability. Deviation in feedstock availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Conveyor Belt Market
Rubber
Isobutylene Market
Rubber
Tire Reinforcement Materials Market
Rubber
Global Styrene Butadiene Styrene Market
Rubber
Rubber Coatings Market
Rubber
Industrial Rubber Market
Rubber
Synthetic Rubber Market
Rubber
Europe Silicone Rubber Market
Rubber
Rubber Tapes Market
Rubber
Co-Extruded Rubber Profiles Market
Rubber
Rubber Bulb Seals Market
Rubber
Rubber Valve Stem Market
Rubber
Fluorosilicone (FVMQ) Rubber Market
Rubber
Rubber Color Masterbatch Market
Rubber
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Rubber
Global Hydraulic Rubber Hose Market