
 Rubber Repair Adhesives Market | 2026-2036
Rubber Repair Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Repair Adhesives Market Outlook
Capital-intensity divergence between integrated resin producers and formulation specialists is rotating competitive advantage toward backward-integrated suppliers with captive polymer supply. Dow Inc. leverages its ethylene propylene diene monomer chain to control input costs for high-performance repair grades. Henkel AG & Co. KGaA sustains global distribution density across automotive OEM service networks. Sika AG anchors its position through construction-focused rubber bonding systems with established specification approvals.
Rubber repair adhesives comprise elastomeric bonding systems formulated with polyurethane, epoxy, silicone, or contact adhesive chemistries, typically achieving shear strengths of 2-8 MPa and operating temperature ranges from -40°C to 150°C depending on base polymer; these formulations restore structural integrity to damaged conveyor belts, tires, gaskets, and molded rubber components in industrial maintenance cycles. Contact adhesives dominate volume consumption in footwear and packaging repair due to fast tack development and room-temperature curing. Polyurethane types capture expanding share in automotive underhood applications where thermal cycling resistance and flexibility under dynamic load prove critical. Silicone segments command premium positioning in electronics and high-temperature industrial seals where outgassing specifications and dielectric stability determine specification.
EPA regulates volatile organic compound emissions from adhesive formulations under 40 CFR Part 59, while REACH restricts hazardous substance content in imported chemical products bound for European industrial end users. OSHA workplace exposure limits for isocyanates in polyurethane systems shape formulation choices and personal protective equipment requirements at repair shop level. Stakeholders must monitor evolving bio-based content mandates and per- and polyfluoroalkyl substance restrictions as these frameworks redefine permissible chemistries and qualifying raw material sourcing.
Market Dynamics
REACH compliance deadlines and EPA volatile organic compound limits are compressing solvent-based formulation viability while polyurethane systems capture automotive underhood applications through superior thermal cycling resistance.
Growth Catalysts
- Tire Retreading Demand:Automotive repair shops in Germany are expanding adhesive procurement for commercial vehicle tire remanufacturing, driven by fleet cost optimization mandates and circular economy frameworks.
- REACH Phase-Down Schedules:European hazardous substance restrictions are accelerating reformulation investments toward waterborne and hot-melt systems that eliminate toluene and xylene content.
- Conveyor Belt Maintenance Cycles:Mining operations in Australia and Chile are extending heavy-duty belt service life through structural bonding rather than capital replacement.
Market Restraints
- Isocyanate Price Volatility:Methylene diphenyl diisocyanate feedstock costs fluctuate with crude oil derivatives, compressing margin stability for polyurethane adhesive specialists lacking backward-integrated supply.
- German Supply Concentration:Industrial rubber processing clusters around Cologne and Leverkusen create geographic dependency risk for specialized adhesive procurement networks.
- Curing Time Limitations:Contact adhesives require extended open times and pressure fixation that conflict with high-throughput automotive assembly line speeds.
Strategic Opportunities
- Bio-Based Content Mandates:EU Green Deal procurement guidelines are creating specification preference for adhesives incorporating renewable polyol feedstocks derived from castor or soybean oil.
- Electronics Sealing Applications:Silicone rubber repair systems with low-outgassing properties are penetrating aerospace and semiconductor equipment maintenance protocols.
- Direct-to-Maintenance Procurement:Original equipment manufacturers are establishing certified adhesive specification programs that bypass traditional distributor channels for mining and port logistics operators.
Industry Challenges
- Formulation Chemistry Expertise Gap:Compounders with hybrid polyurethane-epoxy knowledge are scarce, delaying product development cycles for multi-substrate bonding solutions.
- Certification Timeline Compression:OEM qualification protocols for underhood automotive applications require 18-24 month validation periods that conflict with rapid regulatory reformulation demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Repair Adhesives Market |
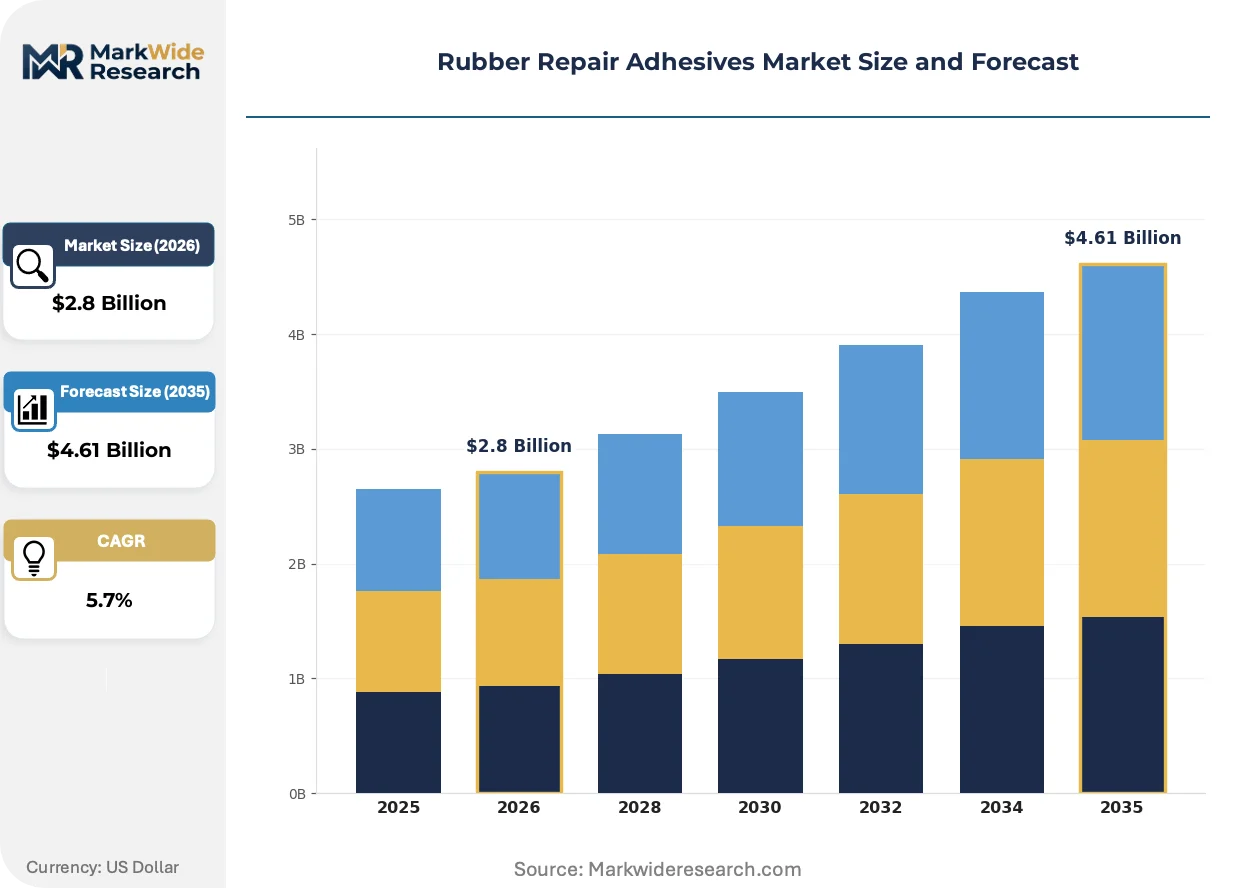
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Automotive, Footwear, Packaging, Electronics Type: Contact Adhesives, Polyurethane, Epoxy, Silicone End User: Manufacturers, DIY Users, Repair Shops, Industrial Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Arkema Group, RPM Adhesives, Henkel AG & Co. KGaA, Dow Inc., H.B. Fuller Company, 3M Company, Huntsman Corporation, Wacker Chemie AG, Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Repair Adhesives Market Strategic Shifts
Reformulation toward low-VOC chemistries is intersecting with automation-ready application systems to reshape how industrial maintenance operations source and deploy rubber bonding solutions.
Two-component polyurethane systems with adjustable pot life and rapid green strength development are decomposing the historical dominance of solvent-based contact cements in conveyor belt splicing. Mining maintenance contractors in Western Australia are adopting meter-mix dispensing equipment that eliminates manual mixing variability. This technology shift is decomposing the market position of traditional brush-applied neoprene formulations that require extended solvent flash-off periods.
EPA enforcement of 40 CFR Part 59 Subpart M is tightening permissible reactive organic gas emissions from adhesive application operations at tire retreading facilities. The regulation is forcing capital investment in enclosed application booths and thermal oxidizers at US-based repair shops. Small and mid-size retreaders in the Ohio and Texas manufacturing corridors are consolidating volumes to justify compliance infrastructure.
Maintenance procurement teams are consolidating adhesive specifications across multiple rubber substrate categories to reduce supplier qualification overhead. Fleet operators with mixed equipment portfolios are replacing grade-specific formulations with universal polyurethane systems rated for -40°C to 150°C operation. This behavioral shift is most pronounced among North American Class 8 trucking fleets operating cross-border routes between Michigan and Ontario.
Rubber Repair Adhesives Market Segmentation
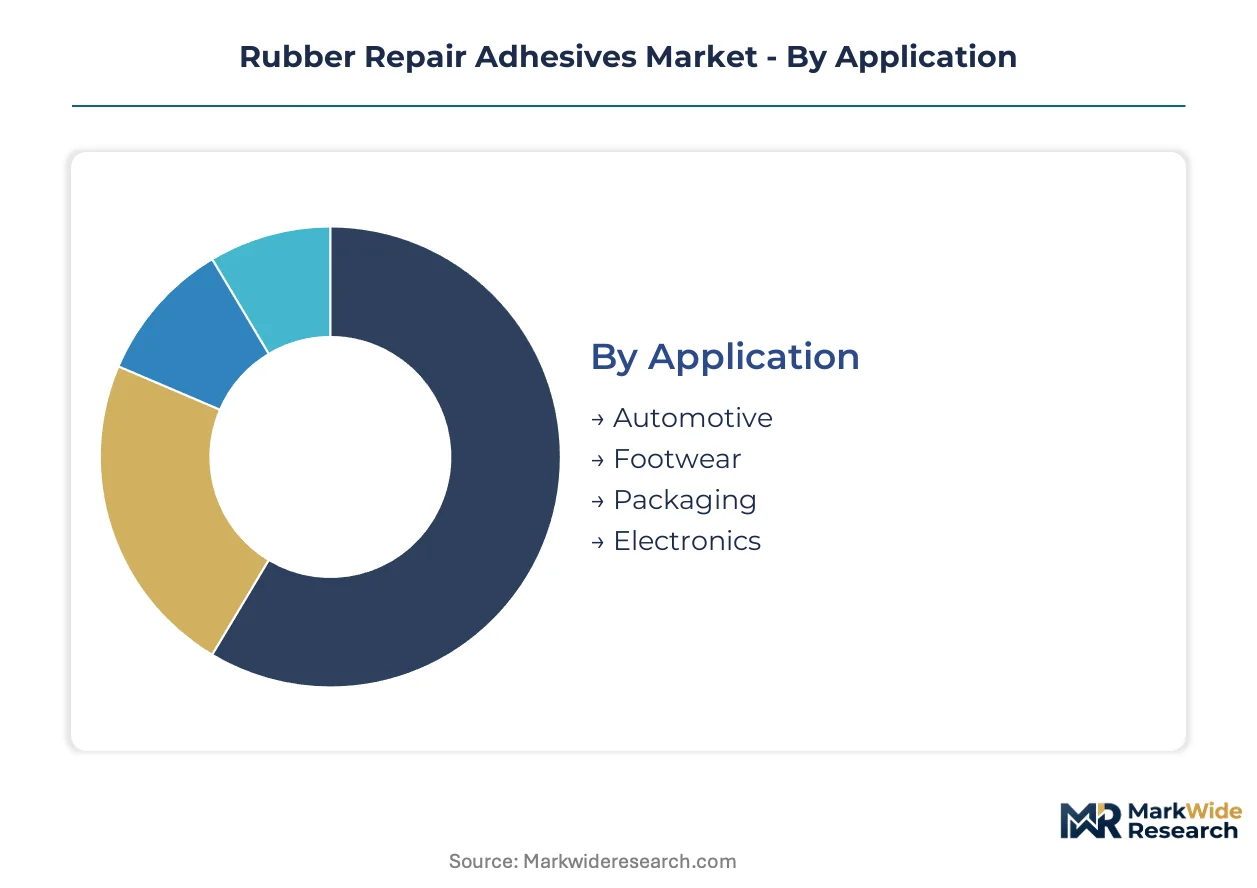
Rubber repair adhesives serve divergent performance requirements across tire retreading, conveyor belt splicing, and electronics sealing. Segmentation reveals how formulation chemistry and procurement channel choices map to specific operational constraints and regulatory exposure.
Application:
Automotive procurement flows through certified distributor networks serving OEM service programs, while industrial maintenance contracts bypass traditional channels through direct specification agreements.
- Automotive:Underhood applications demand polyurethane systems with thermal cycling resistance from -40°C to 150°C. Fleet operators in Michigan and Ontario are consolidating specifications across mixed equipment portfolios to reduce supplier qualification overhead.
- Footwear:Contact adhesives dominate volume consumption due to fast tack development and room-temperature curing. Brazilian and Vietnamese manufacturing clusters drive procurement through wholesale chemical distributors serving cut-make-trim operations.
- Packaging:High-speed converting lines favor hot-melt formulations with instant green strength.
- Electronics:Low-outgassing silicone systems command premium positioning in aerospace and semiconductor equipment maintenance protocols.
By volume, Footwear leads. By growth pace, Automotive is climbing the fastest.
Type:
Cost tiering separates commodity contact cements from engineered polyurethane and silicone grades with specification-backed pricing premiums.
- Contact Adhesives:Neoprene and polychloroprene formulations achieve rapid bond development through solvent activation. Extended open times and pressure fixation requirements conflict with high-throughput assembly line speeds in tire retreading facilities.
- Polyurethane:Two-component systems with adjustable pot life are displacing solvent-based formulations in mining belt splicing across Western Australia. Methylene diphenyl diisocyanate feedstock volatility compresses margins for non-integrated formulators.
- Epoxy:Rigid structural bonding suits metal-rubber hybrid substrates in heavy machinery repair.
- Silicone:Dielectric stability and outgassing compliance determine specification in aerospace sealing applications.
Contact Adhesives retain volume leadership. Polyurethane represents the steepest expansion trajectory.
End User:
Customer type dictates formulation sophistication and compliance documentation requirements.
- Manufacturers:Integrated rubber processors in Leverkusen and Cologne clusters specify adhesives with REACH-compliant documentation and batch traceability for tire retreading operations.
- DIY Users:Small-format retail packaging emphasizes ease-of-application and minimal surface preparation requirements.
- Repair Shops:Automotive service networks in Ohio and Texas manufacturing corridors consolidate volumes to justify EPA 40 CFR Part 59 compliance infrastructure including enclosed application booths.
- Industrial:Mining contractors in Chile and Australia adopt meter-mix dispensing equipment to eliminate manual mixing variability in conveyor belt maintenance.
Industrial users generate highest per-account revenue. Repair Shops are gaining share fastest through fleet consolidation.
Distribution Channel:
Supply concentration in specialized chemical distribution creates geographic dependency risk for just-in-time procurement.
- Online:E-commerce penetration accelerates in DIY and small repair shop segments where technical documentation and safety data sheet accessibility reduce purchase friction.
- Retail:Hardware and automotive parts chains stock commodity contact adhesive grades with immediate availability requirements.
- Direct Sales:OEM-certified adhesive specification programs bypass traditional distributor channels for mining and port logistics operators seeking volume pricing and technical service integration.
- Wholesalers:Regional chemical distributors maintain inventory positions for polyurethane and epoxy systems serving industrial maintenance contractors.
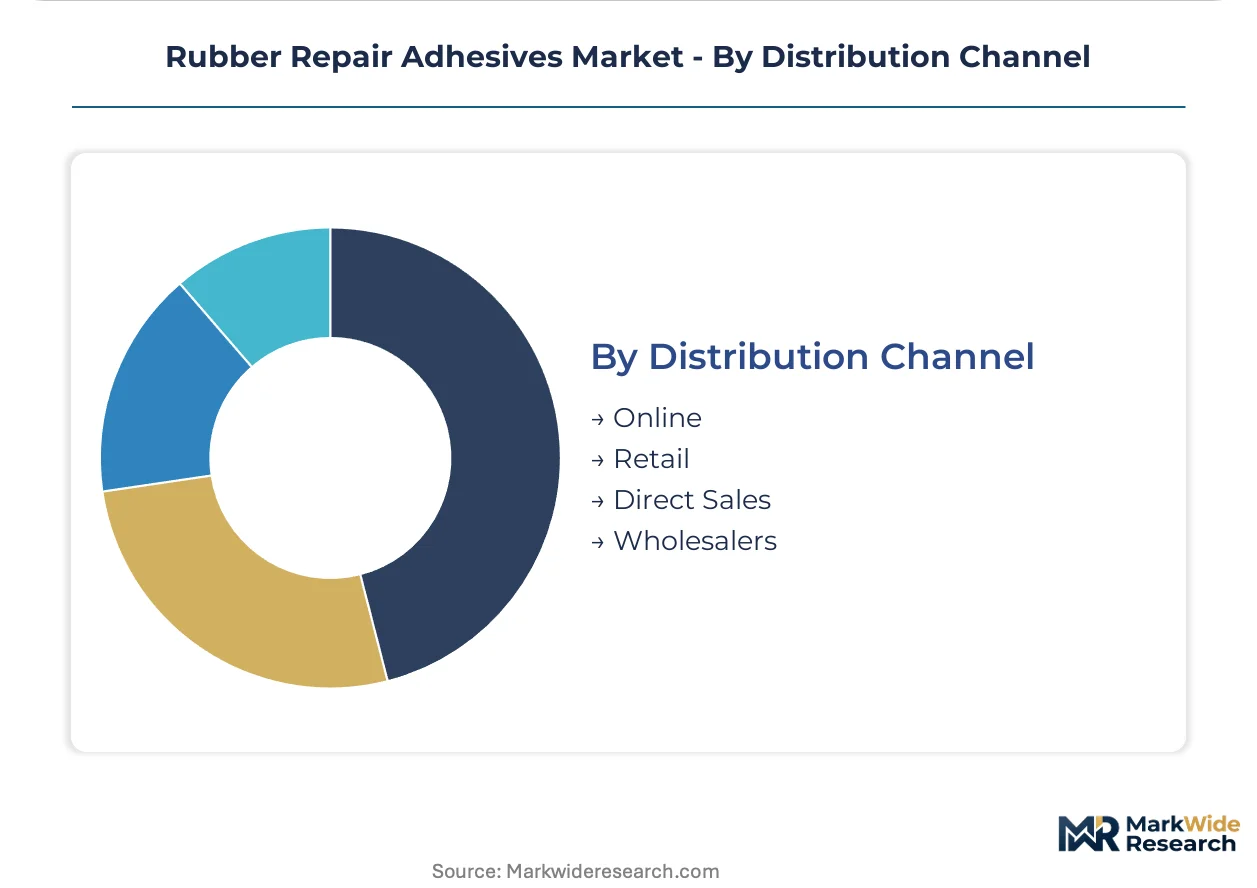
Wholesalers dominate volume throughput. Direct Sales channels are expanding most quickly through OEM specification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in rubber repair adhesives varies sharply by end-use intensity. Mining contractors in Australia treat structural bonding as capital-avoidance and accept premium polyurethane grades. DIY retail buyers in the United States prioritize shelf price over performance specifications.
United States
Class 8 trucking fleets operating Michigan-Ontario corridors consolidate adhesive specifications across mixed equipment portfolios to reduce supplier qualification overhead. EPA enforcement of 40 CFR Part 59 Subpart M forces capital investment in enclosed application booths and thermal oxidizers at tire retreading facilities. Ohio and Texas manufacturing corridors see small and mid-size retreaders consolidating volumes to justify compliance infrastructure.
Germany
Industrial rubber processing clusters around Cologne and Leverkusen drive specialized adhesive consumption for tire retreading and conveyor belt maintenance. REACH phase-down schedules for hazardous substances accelerate reformulation investments toward waterborne and hot-melt systems eliminating toluene and xylene content. Automotive OEM service networks in Baden-Württemberg specify adhesives with batch traceability and compliance documentation.
China
Dual carbon goals under MIIT guidance push domestic formulators toward bio-based polyol feedstocks derived from castor and soybean oil. Yangtze River Delta manufacturing hubs absorb meter-mix dispensing equipment for conveyor belt splicing previously dominated by solvent-based neoprene formulations. GB standards for volatile organic compound emissions tighten permissible limits at industrial maintenance facilities.
Australia
Mining operations in Western Australia extend heavy-duty belt service life through structural bonding rather than capital replacement, treating adhesives as operational expenditure optimization. National environmental regulators enforce workplace exposure frameworks shaping personal protective equipment requirements at remote maintenance sites. Perth-based contractors adopt automation-ready polyurethane systems with adjustable pot life and rapid green strength development.
Brazil
Footwear manufacturing clusters in São Paulo and Minas Gerais drive contact adhesive procurement through wholesale chemical distributors serving cut-make-trim operations. ANVISA oversight of chemical product registration shapes import documentation requirements for foreign adhesive suppliers. Domestic formulators face margin pressure from methylene diphenyl diisocyanate feedstock volatility tied to crude derivative pricing.
Rubber Repair Adhesives Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence rotating advantage toward backward-integrated suppliers controlling captive polymer supply. The market structure separates integrated resin producers from formulation specialists lacking upstream raw material security. Three archetypes dominate: diversified chemical conglomerates with adhesive divisions, pure-play adhesive specialists with specification expertise, and regional compounders serving price-sensitive industrial maintenance. Competitive moves concentrate on portfolio diversification into bio-based content and geographic expansion through OEM-certified specification programs.
Among diversified chemical conglomerates, Dow Inc. and Henkel AG & Co. KGaA exemplify contrasting strategic positions. Dow's ethylene propylene diene monomer chain integration represents the backward-integrated archetype controlling input costs for high-performance grades. Henkel occupies a position defined by global distribution density across automotive OEM service networks. Sika AG anchors the construction-focused specialist tier with established specification approvals in rubber bonding systems.
| Leading Market Players |
|---|
| Arkema Group |
| RPM Adhesives |
| Henkel AG & Co. KGaA |
| Dow Inc. |
| H.B. Fuller Company |
| 3M Company |
| Huntsman Corporation |
| Wacker Chemie AG |
| Sika AG |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between mining contractors and polyurethane adhesive suppliers lock in supply access for conveyor belt maintenance while anchoring price visibility against methylene diphenyl diisocyanate volatility. These contracts insulate procurement teams in Western Australia from spot market swings while committing formulators to volume guarantees that shape production scheduling.
Pricing Analysis
After-sales service bundling with technical support drives lifetime value for industrial maintenance accounts. Three-tier pricing structure across specification-grade, standard industrial, and commodity contact adhesive levels separates OEM-certified formulations from generic neoprene cements. Cost compression in commodity tiers is intensifying because Brazilian footwear manufacturers prioritize shelf price over performance documentation. Mining contractors exhibit least price sensitivity, treating structural bonding as capital-avoidance expenditure.
Supply Chain Analysis
Strategic stockpiling of methylene diphenyl diisocyanate feedstock dominates inventory strategy among German formulators facing crude derivative volatility. Supply concentrates in Germany, China, and the United States, with industrial rubber processing clusters around Cologne and Leverkusen anchoring European procurement networks. Formulation draws from petroleum-derived polyols, isocyanate intermediates, and solvent carriers. Single-source vulnerability in MDI supply creates exposure for non-integrated specialists. Distribution runs through regional chemical wholesalers serving automotive service networks and mining maintenance contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks cyclical recovery patterns tied to commercial vehicle fleet replacement cycles. Class 8 trucking procurement accelerations signal adhesive demand inflections with 12-18 month lag structures.
For Market Incumbents: Secure backward integration into ethylene propylene diene monomer supply chains to defend margin position against feedstock volatility. Invest in REACH-compliant waterborne formulation capacity ahead of European hazardous substance phase-down deadlines. Consolidate specification approvals with OEM service networks to create switching costs for fleet operators. For New Entrants and Emerging Players: OEM certification fast-tracks for underhood automotive applications represent the most penetrable entry vector. Target electronics sealing segments where low-outgassing silicone specifications command premium positioning absent entrenched supplier relationships. Pursue direct-to-maintenance procurement channels bypassing traditional chemical distributors. For Investors and Strategic Acquirers: Capital is best deployed toward formulators with hybrid polyurethane-epoxy compounding expertise and established REACH documentation capabilities. Long-term viability rests on regulatory compliance infrastructure rather than commodity volume positioning. Watch methylene diphenyl diisocyanate price volatility as margin compression signal triggering consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive polymer supply secures margin stability against crude-linked feedstock volatility. |
| REACH Compliance Investment | Waterborne formulation capacity positions formulators ahead of European hazardous substance restrictions. |
| OEM Certification Programs | Specification approvals with automotive service networks create switching costs for fleet operators. |
| Meter-Mix Dispensing Deployment | Automation-ready application systems displace manual mixing in Western Australian mining operations. |
| Bio-Based Feedstock Transition | Castor and soybean oil polyol sourcing aligns with EU Green Deal procurement preferences. |
Study Parameters
The analysis maps polyurethane, silicone, epoxy, and contact adhesive sub-sectors, each validated through plant managers at tire retreading facilities, procurement leads at mining contractors, distribution channel partners, and technical R&D directors at formulation houses. Primary interview findings cross-reference customs and trade data, chemical industry association reports, SEC 10-K filings from diversified conglomerates, and EPA enforcement records. Bottom-up volume estimates triangulate against top-down market sizing.
Consistency checks against external benchmarks validate projection outputs across the modeling period. The analytical framework segments by chemistry type, end-use industry, compliance tier, and regional production hub. CAGRs derive from trend extrapolation of fleet replacement cycles, mining capital expenditure patterns, and regulatory compliance investment trajectories. Forecast inputs incorporate methylene diphenyl diisocyanate price elasticity and OEM specification adoption curves.
Decision-makers should treat outputs as directional under stable crude derivative pricing and unchanged REACH phase-down schedules; material deviation would warrant model refresh. Revision becomes warranted when MDI feedstock volatility crosses thresholds that compress formulator margins below sustainable levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Ocular Adhesives and Sealants Market
Adhesives & Sealants
South Africa Sealants Market
Adhesives & Sealants
UV Glue Market
Adhesives & Sealants
Urea Formaldehyde Concrete Market
Adhesives & Sealants
Mirror Adhesive Market
Adhesives & Sealants
Waterproof Tapes Market
Adhesives & Sealants
Timber Laminating Adhesives Market
Adhesives & Sealants
Thailand Adhesives Market
Adhesives & Sealants
Low VOC Adhesive Market
Adhesives & Sealants
Asia-Pacific Automotive Adhesives and Sealants Market
Adhesives & Sealants
Mexico Adhesives Market
Adhesives & Sealants
Global Epoxy Adhesive Market
Adhesives & Sealants
Asia-Pacific Flock Adhesives Market
Adhesives & Sealants
Specialty Adhesives Market
Adhesives & Sealants
Foam Adhesive Market
Adhesives & Sealants
Lignin for Adhesives Market