
 Carboxylated Nitrile Rubber Market | 2026-2036
Carboxylated Nitrile Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Carboxylated Nitrile Rubber Market Outlook
Specialized polymer compounding expertise is collapsing across mature manufacturing economies, constraining capacity expansion for high-performance elastomer grades. ZEON Corporation leverages captive acrylonitrile supply chains to sustain margin stability in specialty grades. LANXESS AG anchors European demand through backward integration into precursor chemicals. Kumho Petrochemical dominates Asian supply with integrated petrochemical feedstock access.
Carboxylated nitrile rubber denotes a modified nitrile-butadiene elastomer containing pendant carboxylic acid groups typically at 3-10% by weight, manufactured through emulsion polymerization with methacrylic or acrylic acid comonomers to achieve superior tensile strength and abrasion resistance for dynamic sealing applications. High-performance grades command premium positioning due to their critical role in aerospace hydraulic systems where failure tolerance approaches zero. Oil-resistant grades occupy mature volume pools in industrial hose production where specification standardization limits margin expansion. Automotive seals represent the fastest-growing application segment as thermal management system complexity rises in electrified powertrains.
EPA regulates volatile organic compound emissions from rubber compounding operations under Clean Air Act Title V permitting, while REACH restricts phthalate plasticizer use in European automotive supply chains. The EU Green Deal carbon border adjustments will reshape cost structures for imported compounded materials. FDA food-contact regulations govern nitrile use in processing equipment seals for North American dairy and meat operations. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border automotive supply chains.
Market Dynamics
Automotive electrification is forcing thermal management system redesigns that demand higher-performance sealing materials capable of withstanding aggressive coolants and wider temperature cycling ranges than conventional nitrile formulations permit.
Growth Catalysts
- EPA Clean Air Act Title V:Stricter volatile organic compound emission controls on rubber compounding operations are accelerating capital investment in advanced emission capture systems, favoring larger compounders with compliance infrastructure.
- Aerospace hydraulic systems:Zero-failure-tolerance specifications in commercial aviation maintenance programs are sustaining premium-grade demand despite cyclical airframe production rates.
- German automotive supplier ecosystem:Dense clustering of specialized compounders around Stuttgart and Wolfsburg creates knowledge spillovers that accelerate formulation development cycles for next-generation grades.
Market Restraints
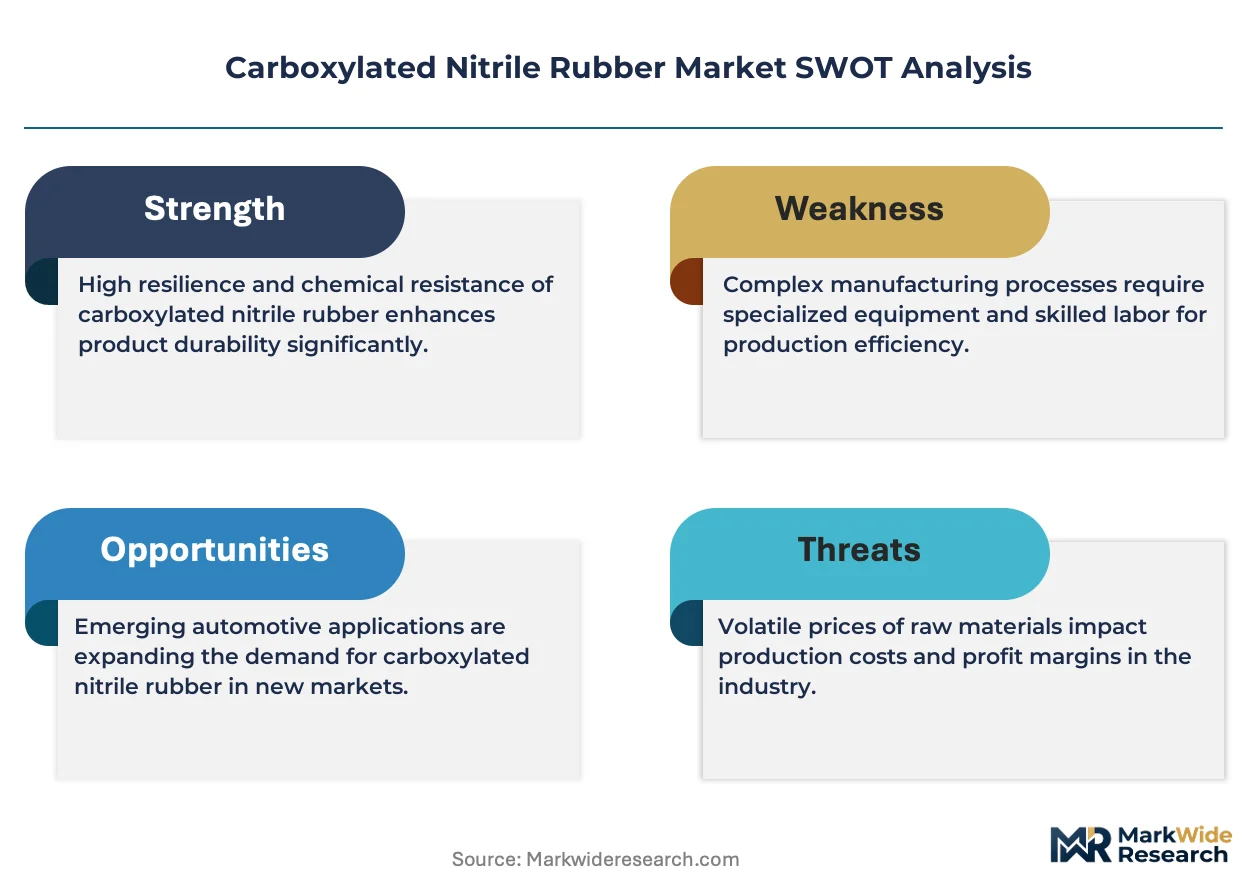
- Acrylonitrile feedstock volatility:Crude oil price sensitivity in butadiene and acrylonitrile supply chains compresses margin predictability for non-integrated compounders lacking captive petrochemical access.
- Specialized polymer compounding expertise collapse:Retirement-driven skill attrition across mature manufacturing economies constrains capacity expansion for high-performance elastomer grades requiring precise carboxylation control.
- REACH phthalate restrictions:ECHA limitations on plasticizer chemistries in European automotive supply chains force reformulation investments that delay new product qualification timelines.
Strategic Opportunities
- India automotive manufacturing:PLI scheme incentives for electric vehicle component localization create first-mover positioning for compounders establishing technical partnerships with domestic gasket and seal producers.
- EU Green Deal carbon border adjustments:Import cost restructuring for compounded materials rewards European-based production with verified low-carbon process credentials.
- Fluoroelastomer convergence:Hybrid formulation development combining carboxylated nitrile cost structures with partial fluoropolymer performance is opening mid-tier aerospace and chemical processing applications previously closed to nitrile chemistry.
Industry Challenges
- Emulsion polymerization process control:Precise carboxylic acid group distribution at 3-10% weight loading demands specialized reactor engineering expertise that has concentrated among a shrinking pool of veteran technologists.
- Cross-border automotive supply chain compliance:Divergent EPA, REACH, and emerging carbon border documentation requirements create stranded inventory risk for compounders serving multinational OEMs with unified platform strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carboxylated Nitrile Rubber Market |
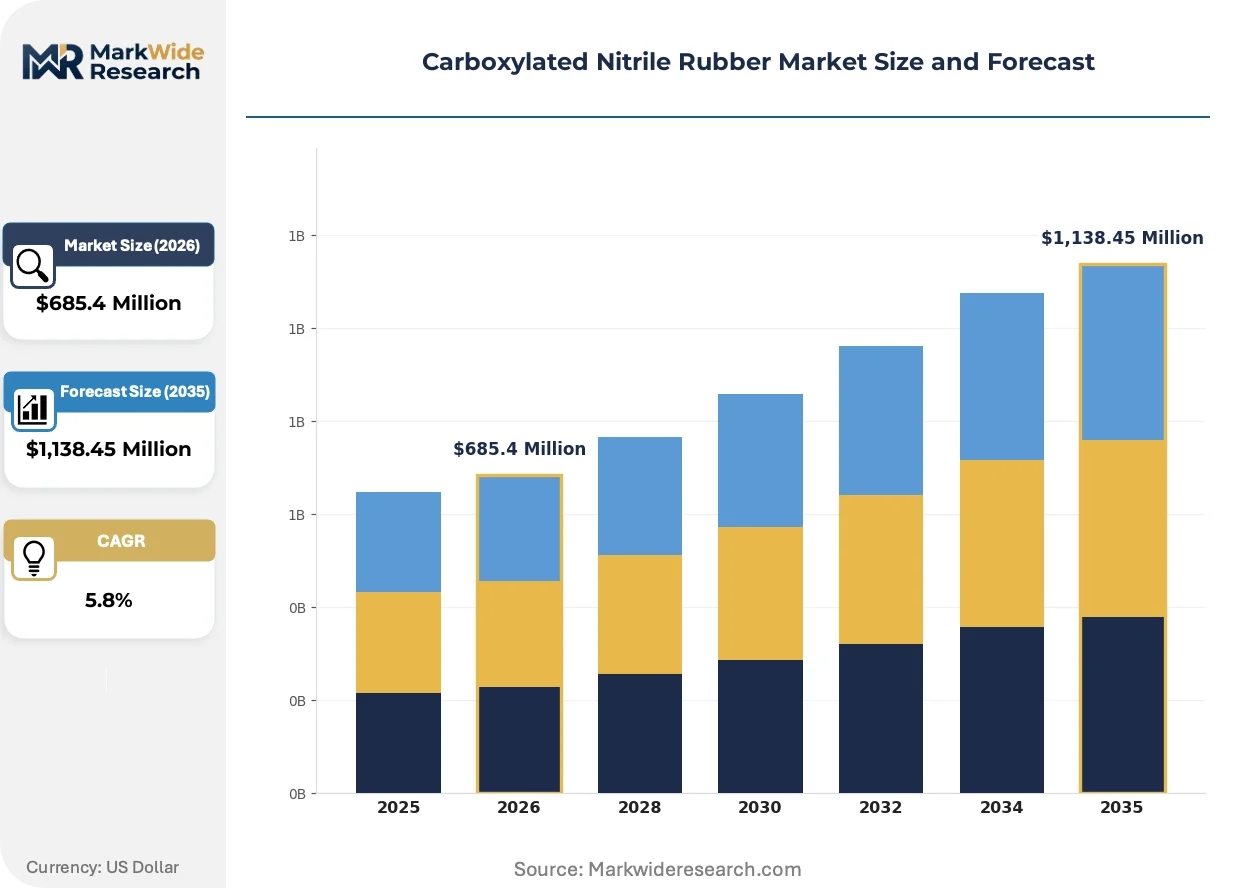
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Grade, High-Performance Grade, Low-Temperature Grade, Oil-Resistant Grade Application: Automotive Seals, Hose Production, Grommets, O-Rings End User: Automotive Industry, Industrial Equipment, Electronics Manufacturers, Aerospace Sector Form: Sheets, Blends, Coatings, Compounds |
| Companies Covered | ZEON Corporation, LANXESS AG, ARLANXEO, JSR Corporation, Kumho Petrochemical, Synthomer, OMNOVA Solutions Inc., LG Chem, Emerald Performance Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carboxylated Nitrile Rubber Market Strategic Shifts
Formulation science is advancing through convergent pressures from electrification thermal loads, regulatory chemical restrictions, and aerospace reliability mandates that collectively exceed the performance envelope of standard nitrile-butadiene elastomers.
Peroxide-curable carboxylated nitrile grades with enhanced metal adhesion properties are decomposing the traditional distinction between molded seals and bonded metal-composite assemblies in electric vehicle battery pack thermal management systems. Tier-1 suppliers in Germany and Japan are qualifying these materials for coolant circuit interfaces where vibration resistance and chemical compatibility must coexist. The technology is decomposing established procurement patterns that historically separated elastomer and metal-stamping supply chains.
REACH restrictions on phthalate plasticizers and the EU Green Deal carbon border adjustment mechanism are restructuring compounder cost structures and qualification priorities across European automotive supply chains. ECHA regulatory updates are forcing substitution toward bio-based plasticizer alternatives that maintain low-temperature flexibility without compromising heat aging performance. German and French automotive seal producers are responding with accelerated internal testing programs to secure OEM approvals ahead of 2026 implementation timelines.
Specification-driven procurement consolidation among electric vehicle platform architects is compressing supplier qualification cycles and concentrating volume with compounders holding simultaneous EPA Title V permits, REACH compliance certifications, and IATF 16949 automotive quality credentials. Tier-1 seal manufacturers are unbundling after-sales technical service from material supply contracts, creating discrete revenue streams for formulation troubleshooting and failure analysis. This pattern is most visible in California and Michigan where domestic EV production scale-up has concentrated platform engineering decisions.
Carboxylated Nitrile Rubber Market Segmentation
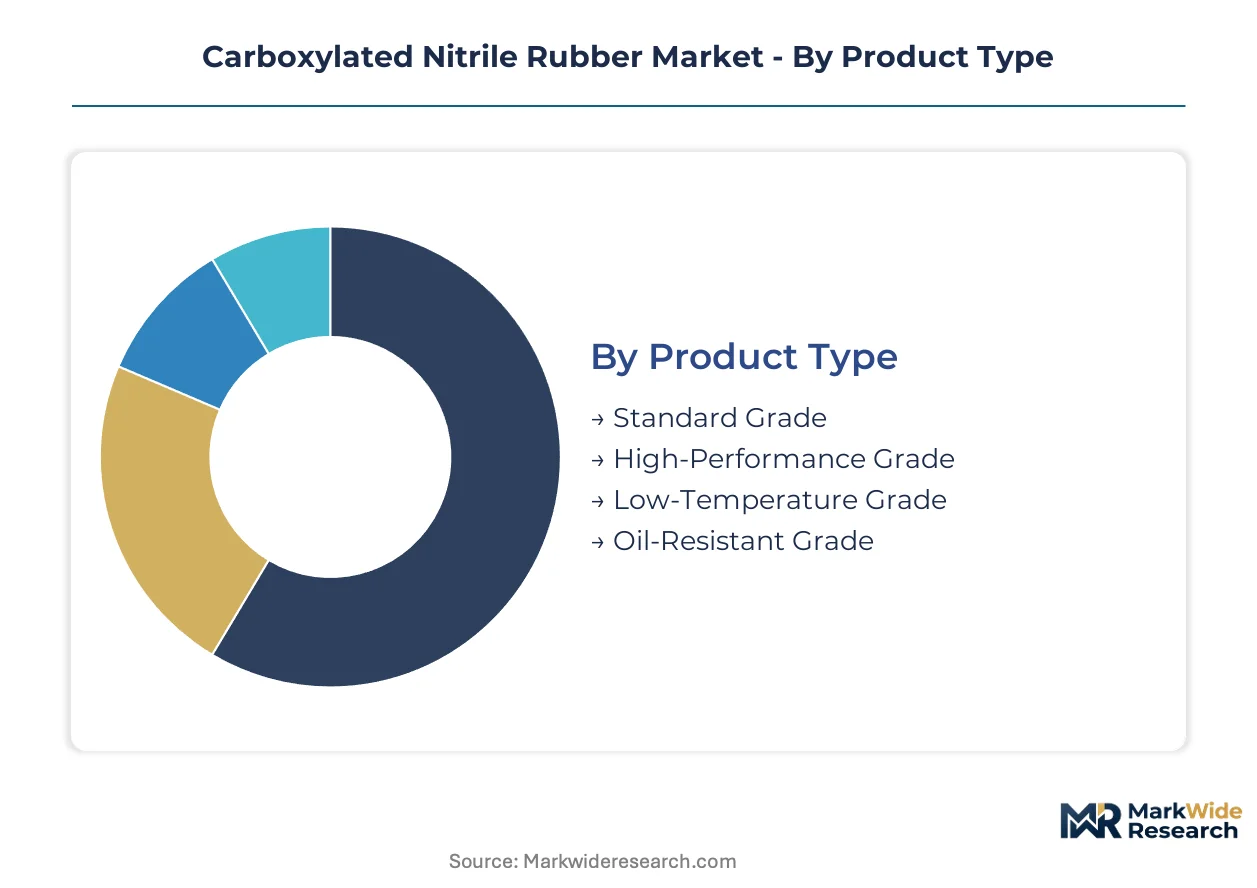
Segmentation in carboxylated nitrile rubber markets reflects divergent regulatory thresholds across end-use applications. EPA Title V permitting, REACH chemical restrictions, and aerospace zero-failure specifications each create distinct material qualification pathways that reshape procurement patterns.
Product Type:
REACH phthalate restrictions and EPA emission controls split the product landscape into compliance-tiered categories with divergent capital requirements.
- High-Performance Grade:Formulations with precise carboxylic acid distribution at 6-10% weight loading achieve tensile strength exceeding 25 MPa for aerospace hydraulic systems. Demand concentrates in Germany and Japan where commercial aviation maintenance programs enforce zero-failure-tolerance specifications.
- Standard Grade:Baseline carboxylation at 3-5% weight loading serves industrial applications with moderate mechanical stress requirements. Volume concentrates in Chinese and Indian automotive seal production where cost sensitivity dominates procurement decisions.
- Low-Temperature Grade:Specialized plasticizer packages maintain elasticity below -40°C for Arctic oilfield equipment.
- Oil-Resistant Grade:Enhanced acrylonitrile content resists hydrocarbon swelling in refinery hose applications.
Standard Grade handles the majority of throughput; High-Performance Grade is expanding most quickly on share as electrification thermal management demands intensify.
Application:
Automotive platform electrification is restructuring volume distribution across legacy industrial applications.
- Automotive Seals:Battery pack coolant circuit interfaces and thermal management gaskets in electric powertrains require peroxide-curable grades with metal adhesion properties. German Tier-1 suppliers around Stuttgart are qualifying these materials ahead of domestic EV production scale-up.
- O-Rings:Precision-molded seals for aerospace hydraulic actuators command premium positioning due to lot traceability and statistical process control requirements. Japanese and French aviation suppliers sustain demand despite cyclical airframe build rates.
- Hose Production:Industrial fluid transfer applications with mature specification standards limit margin expansion opportunities.
- Grommets:Vibration isolation components in industrial machinery represent stable replacement-driven demand pools.
Automotive Seals carries the volume lead; O-Rings posts the steepest expansion trajectory as aerospace reliability mandates tighten.
End User:
Customer concentration patterns follow geographic clustering of specialized compounding expertise and captive feedstock access.
- Automotive Industry:Platform architects in Michigan and California are consolidating supplier qualification cycles around compounders holding simultaneous EPA Title V permits and IATF 16949 credentials.
- Aerospace Sector:Maintenance repair organizations in France and Germany specify lot-controlled grades with full chemical traceability.
- Industrial Equipment:Durable goods manufacturers in India source cost-optimized grades under PLI scheme localization incentives.
- Electronics Manufacturers:Cleanroom-compatible formulations serve semiconductor fabrication equipment sealing requirements.
Automotive Industry dominates absolute consumption; Aerospace Sector commands the highest unit margins.
Form:
Supply chain configuration determines competitive positioning across material delivery formats.
- Compounds:Pre-formulated uncured stocks with curated curative packages accelerate processing for high-mix automotive seal producers. German compounders leverage backward integration into precursor chemicals to defend margin stability.
- Sheets:Calendered goods for die-cutting operations serve high-volume gasket manufacturers with standardized thickness requirements.
- Blends:Custom polymer alloys with EPDM or fluorocarbon components address hybrid performance specifications.
- Coatings:Dispersion-based surface treatments protect substrates in chemical processing environments.
Compounds represents the largest throughput format; Blends is climbing the fastest as hybrid formulation development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Clean Air Act Title V permitting anchors United States demand, while REACH compliance requirements and EU Green Deal carbon border adjustments reshape European procurement patterns. Electrification thermal management needs concentrate material qualification cycles in Germany, Japan, and the United States.
United States
Domestic EV production scale-up in Michigan and California drives thermal management seal demand. EPA Title V permitting requirements favor compounders with advanced emission capture infrastructure. Detroit-area Tier-1 suppliers consolidate procurement around IATF 16949-credentialed compounders.
Germany
Stuttgart and Wolfsburg automotive clusters accelerate next-generation grade development through knowledge spillovers. REACH phthalate restrictions force reformulation investments ahead of 2026 implementation. Dense supplier ecosystems around major OEMs sustain specialized compounding expertise concentration.
Japan
Commercial aviation maintenance programs sustain premium-grade consumption for zero-failure-tolerance specifications. METI industrial standards govern material traceability for aerospace hydraulic applications. Osaka and Nagoya manufacturing belts host precision-molded seal producers serving domestic aviation suppliers.
China
Industrial hose production absorbs standard-grade volumes with cost-sensitive procurement patterns. MIIT automotive standards govern domestic EV thermal management material specifications. Yangtze River Delta petrochemical integration supports acrylonitrile feedstock access for regional compounders.
India
PLI scheme incentives for EV component localization attract technical partnerships from foreign compounders. BIS quality standards govern automotive seal material approvals for domestic manufacturing. Tamil Nadu and Maharashtra automotive corridors concentrate gasket and seal production capacity.
Carboxylated Nitrile Rubber Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with feedstock access and regulatory compliance infrastructure determining tier placement. Japanese and German chemical conglomerates leverage captive petrochemical supply chains to defend margin stability. Strategic archetypes include backward-integrated petrochemical majors, automotive-focused compounders with IATF credentials, and aerospace-certified precision specialists. Competitive moves concentrate on emission control infrastructure investment and hybrid formulation development bridging nitrile and fluoropolymer performance.
Within the integrated petrochemical tier, ZEON Corporation and Kumho Petrochemical exemplify feedstock-anchored positioning through acrylonitrile supply chain control. LANXESS AG occupies a position representing European backward integration into precursor chemicals, anchoring regional demand through compliance-ready production systems. These three entities represent distinct geographic anchors for specialty grade supply.
| Leading Market Players |
|---|
| ZEON Corporation |
| LANXESS AG |
| ARLANXEO |
| JSR Corporation |
| Kumho Petrochemical |
| Synthomer |
| OMNOVA Solutions Inc. |
| LG Chem |
| Emerald Performance Materials |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between German Tier-1 automotive suppliers and acrylonitrile-integrated compounders lock in supply access and price visibility across electrification-driven thermal management seal demand. These contracts insulate qualified compounders from butadiene spot volatility while binding buyers to IATF 16949-certified production lines.
Pricing Analysis
Contract-based long-term offtake structures dominate procurement between Stuttgart-area automotive clusters and backward-integrated chemical producers. Price differentiation hinges on carboxylation precision grade and REACH phthalate compliance certification tier. Margins are tightening due to ECHA plasticizer substitution mandates forcing reformulation investments. Chinese industrial hose manufacturers exhibit highest price sensitivity; German aerospace hydraulic seal buyers show least.
Supply Chain Analysis
Japan and Germany anchor high-performance grade production through METI-governed aerospace traceability systems and REACH-compliant compounding infrastructure. Raw material flows draw from captive acrylonitrile supply chains and specialized peroxide curative networks. Single-source vulnerability concentrates around veteran emulsion polymerization technologists nearing retirement. Distribution runs through Tier-1 seal manufacturers holding simultaneous EPA Title V permits and automotive platform engineering credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle platform standardization is creating winner-take-most dynamics where compounders holding interoperability across EPA, REACH, and IATF credential stacks capture disproportionate volume. The shift devalues pure material suppliers lacking technical service bundling.
For Market Incumbents: Fortify backward integration into precursor chemicals to defend margin stability against acrylonitrile feedstock volatility. Prioritize emission capture infrastructure investment ahead of EPA Title V enforcement intensification. Consolidate formulation expertise through technical apprenticeship programs addressing retirement-driven skill attrition. For New Entrants and Emerging Players: Lead with technical partnership structures targeting India's PLI-scheme EV component localization incentives. The Tamil Nadu and Maharashtra automotive corridors offer penetrable white space for compounders offering REACH-compliant grade qualification support. Position around after-sales troubleshooting services unbundled from material supply contracts. For Investors and Strategic Acquirers: Capital is best deployed toward compounders with verified low-carbon process credentials positioning for EU Green Deal carbon border adjustment advantages. Five-to-ten-year viability favors entities combining captive petrochemical access with aerospace certification maintenance. Watch for inflection signals in peroxide-curable metal adhesion grade qualification timelines at German Tier-1 suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive acrylonitrile supply chains defend margin stability against crude-linked feedstock volatility. |
| Emission Control Infrastructure | EPA Title V permitting creates defensive moats favoring capital-rich compounders with capture systems. |
| Hybrid Formulation Development | Fluoroelastomer convergence opens mid-tier aerospace applications previously closed to nitrile chemistry. |
| Technical Partnership Structuring | India PLI scheme localization creates first-mover positioning with domestic gasket and seal producers. |
| Low-Carbon Process Certification | Verified credentials reward European-based production under EU Green Deal carbon border adjustments. |
Study Parameters
The analysis maps high-performance grade, standard grade, low-temperature grade, and oil-resistant grade segments, each validated through technical R&D directors at compounders, procurement leads at Tier-1 automotive seal manufacturers, plant managers at acrylonitrile production facilities, and distribution channel partners serving industrial hose producers. Primary interview findings triangulate against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated chemical producers, and EPA Title V permit databases. Bottom-up volume modeling from application-level consumption patterns reconciles with top-down petrochemical feedstock demand estimates.
Consistency checks validate volume and value outputs against external benchmarks including regional automotive production databases and aerospace maintenance program expenditure patterns. The analytical framework segments by carboxylation precision tier, end-use industry, and regional regulatory compliance cluster across the projection horizon. CAGRs derive from fitted growth curves incorporating electrification thermal management content per vehicle trajectories and REACH plasticizer substitution implementation timelines.
Forecasts assume regulatory continuity in EPA Title V permitting, REACH phthalate restrictions, and EU Green Deal carbon border adjustment mechanisms; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in EV platform thermal management system redesigns and ECHA regulatory update implementations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Global Automotive Elastomers Market
Rubber
Metallurgical Rubber Roller Market
Rubber
Isobutylene Market
Rubber
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Rubber
Global Rubber Coated Fabrics Market
Rubber
Styrene Butadiene Rubber (E-SBR and S-SBR) Market
Rubber
Global Rubber Vulcanization Market
Rubber
Polybutadiene Rubber (PBR) Market
Rubber
Silica for S-SBR Market
Rubber
Rubber Bulbs Market
Rubber
Liquid Polybutadiene Market
Rubber
Chloroprene Rubber Modified Asphalt Emulsion Market
Rubber
Pre-Dispersed Rubber Chemicals Market
Rubber
Butyl Reclaimed Rubber Market
Rubber
Recycled Elastomers Market
Rubber
Liquid Silicone Rubber Market