
 India Artificial Lift Systems Market | 2026-2036
India Artificial Lift Systems Market Size, Share, and Industry Trends Forecast 2026-2036
India Artificial Lift Systems Market Foresight
Multi-source equipment procurement is realigning how domestic operators secure artificial lift packages. Schlumberger NV leverages its digital ESP monitoring platforms to anchor premium service contracts across western Indian fields. Halliburton Company sustains manufacturing scale through its Mumbai technical center, while Baker Hughes Company differentiates via advanced gas lift systems tailored to Bombay High offshore conditions.
Artificial lift systems encompass surface and downhole equipment that reduces bottom-hole pressure to sustain or increase hydrocarbon flow from reservoirs with insufficient natural drive, typically employing beam pumps, centrifugal pumps, or gas injection at depths exceeding 3,000 meters. These systems serve the primary commercial purpose of maximizing recovery factors from depleted or low-permeability formations where primary drive mechanisms have failed. Electrical submersible pumps occupy the dominant product position due to their high volume handling in offshore Mumbai fields, while progressive cavity pump adoption accelerates in onshore heavy oil blocks where sand tolerance matters. Digital technology segments command widening margin pools as operators deploy remote monitoring and predictive analytics to minimize workover frequency.
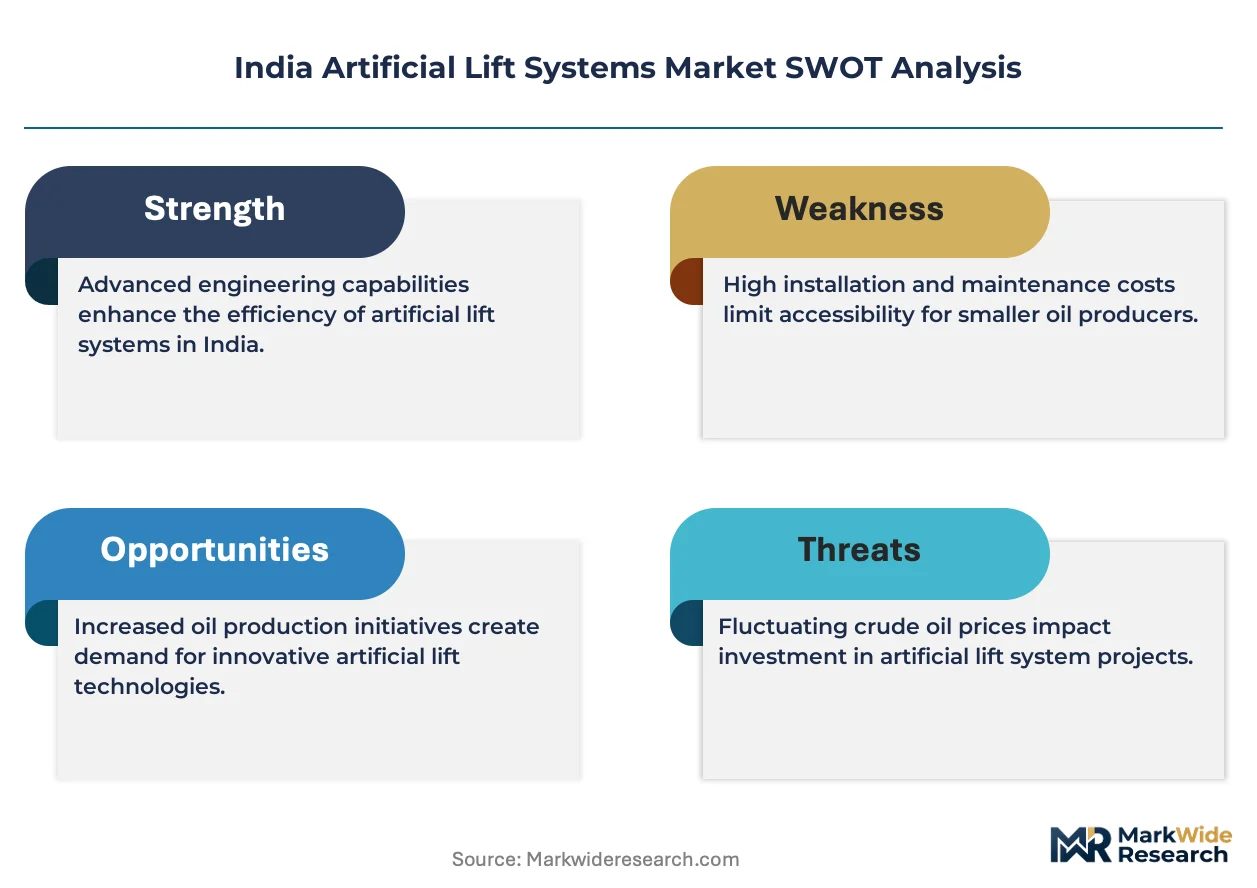
The Petroleum and Natural Gas Regulatory Board mandates equipment certification for downstream safety compliance, while Bureau of Indian Standards specifications govern sucker rod metallurgy and ESP cable insulation ratings. The Ministry of Environment, Forest and Climate Change's offshore discharge protocols further constrain system design for subsea deployments. Operators must weigh domestic manufacturing incentives under the Production Linked Incentive scheme against import dependencies for high-specification submersible motors when committing capital to brownfield revitalization programs.
Market Dynamics
The Ministry of Petroleum and Natural Gas mandates enhanced oil recovery across aging Mumbai Offshore and Krishna-Godavari basin fields, forcing operators to accelerate artificial lift deployment while navigating domestic manufacturing incentives against high-specification import dependencies.
Growth Catalysts
- PLI scheme for domestic manufacturing:The Production Linked Incentive scheme subsidizes local assembly of submersible motors and pump components, reducing import exposure for ONGC and Oil India brownfield programs.
- Heavy oil characterization in Rajasthan:Cairn India and Vedanta Resources expand progressive cavity pump installations in Barmer-Sanchor blocks where API gravity falls below 20 degrees.
- Digital ESP monitoring platforms:Remote diagnostics and predictive analytics compress workover frequency across western Indian fields, improving run-life economics for beam pump replacements.
Market Restraints
- High-specification motor import concentration:Permanent magnet synchronous motors above 500 horsepower remain concentrated in US and European supplier bases, exposing operators to currency volatility and extended lead times.
- Bureau of Indian Standards certification friction:Sucker rod metallurgy testing and ESP cable insulation validation add 4-6 month procurement cycles that conflict with urgent well intervention schedules.
- Gas lift substitution in high-GOR wells:Bombay High operators deploy gas lift as a technically simpler alternative for wells producing above 500 standard cubic meters per cubic meter gas-oil ratio.
Strategic Opportunities
- Underpenetrated Cambay basin revitalization:Gujarat state fields operated by smaller independents lack systematic artificial lift programs, creating white space for packaged ESP and rod pump service contracts.
- Subsea boosting integration:Deepwater developments in the KG-DWN-98/2 block require seabed-deployed multiphase pumps that combine centrifugal pumping with subsea processing.
- CEA grid harmonization standards:Central Electricity Authority regulations for variable frequency drive compatibility create specification windows for domestic power electronics manufacturers to enter the ESP control market.
Industry Challenges
- Subsea installation technician scarcity:Mumbai High offshore operators compete for limited crews qualified in subsea tree integration and umbilical termination assembly.
- Legacy SCADA integration complexity:Brownfield wells with 1990s-era wellhead control panels require protocol translation layers to accept modern digital lift monitoring feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Artificial Lift Systems Market |
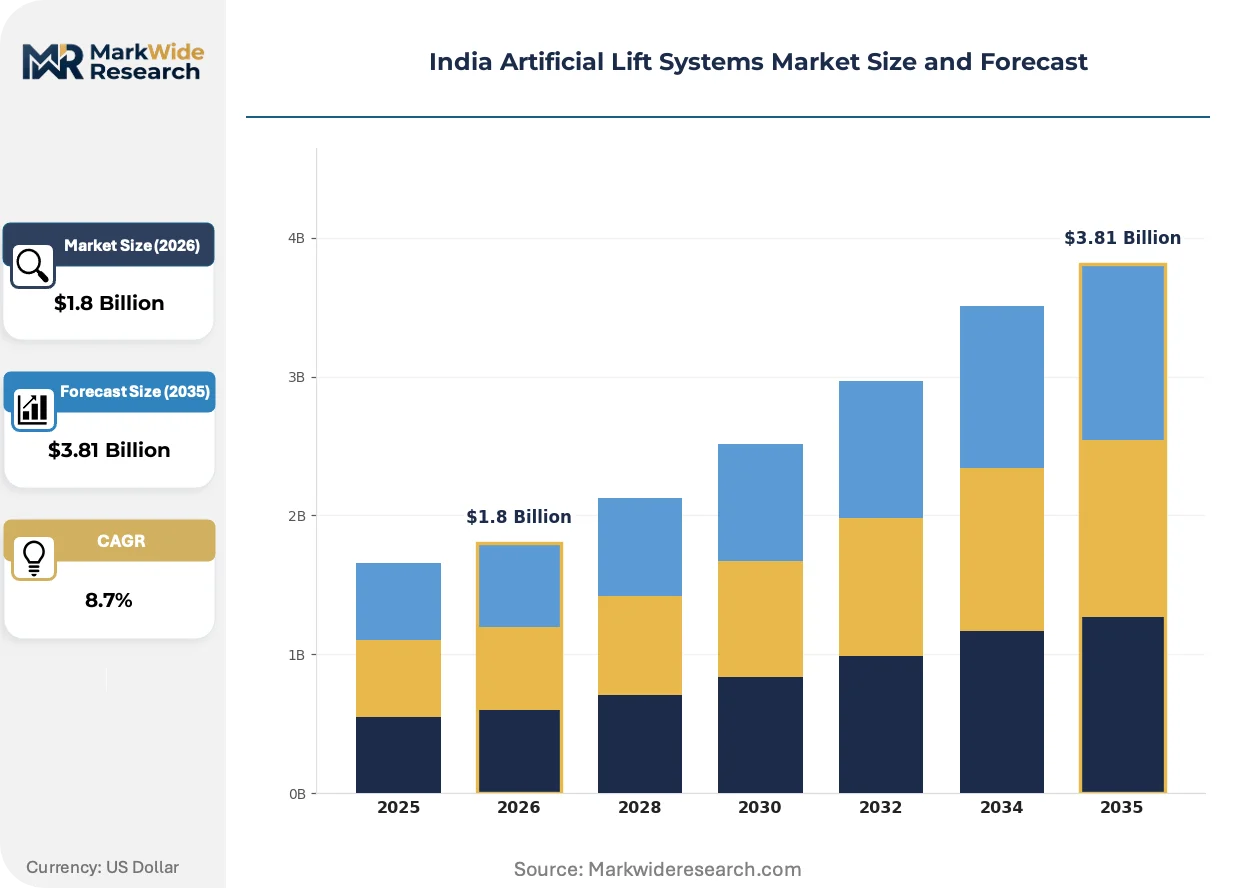
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sucker Rod Pump, ESP, PCP, Gas Lift Deployment: Onshore, Offshore, Subsea, Brownfield End User: Oil & Gas Producers, Service Companies, EPC Contractors, Refineries Technology: Conventional, Advanced, Hybrid, Digital |
| Companies Covered | Schlumberger NV, Halliburton Company, Weatherford International plc, Baker Hughes Company, Penguin Petroleum Services (P) Limited, Novomet Oilfield Services Company, United Drilling Tool Limited, Apergy Corp, ChampionX, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Artificial Lift Systems Market Shifts & Advancements
Digitalization is compressing the traditional separation between downhole equipment supply and ongoing production optimization services, with operators demanding integrated packages that bundle hardware, telemetry, and reservoir engineering support.
Modular ESP skid systems are modularizing field deployment logistics for marginal offshore platforms with crane capacity below 50 tons. ONGC installs pre-commissioned pump-motor-seal packages on Mumbai High wellhead platforms, cutting rig-up time from 72 hours to 18 hours. This compression is modularizing the competitive structure between full-service integrators and component specialists.
The Petroleum and Natural Gas Regulatory Board's 2023 field development guidelines mandate real-time well monitoring for all new offshore artificial lift installations. This compels operators to specify digital-ready equipment even in low-budget brownfield tenders. Western Indian offshore fields show the fastest compliance response, with 60 percent of 2024 ESP contracts including native Modbus or OPC-UA connectivity.
Operator purchasing behavior is consolidating annual procurement into multi-well framework agreements that unbundle equipment supply from installation and maintenance. Oil India Limited and Hindustan Petroleum Corporation now contract lift systems through three-year master service agreements rather than single-well purchase orders. Rajasthan onshore heavy oil blocks exhibit this consolidation most visibly, with Vedanta Resources standardizing on single-source progressive cavity pump suppliers across its Barmer field.
India Artificial Lift Systems Market Segmentation
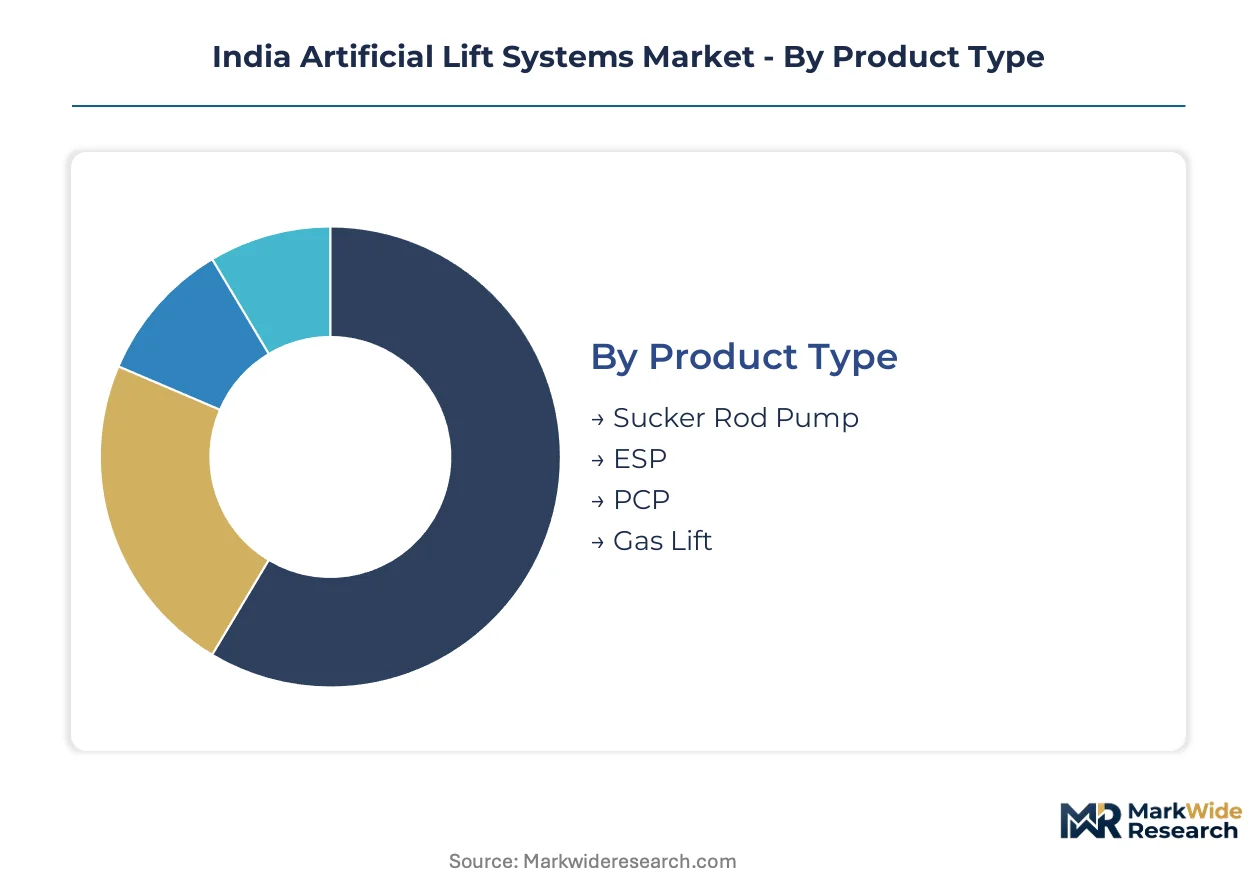
Artificial lift procurement in India fragments across equipment generations, installation environments, and operator sophistication tiers. Understanding these divisions reveals where domestic manufacturing incentives intersect with import-dependent high-technology requirements.
Product Type:
Standalone pump systems dominate brownfield retrofit budgets, while integrated lift packages with native telemetry command premium positioning in new offshore developments.
- Electrical Submersible Pump:Centrifugal multistage pumps operating at 3,000-4,500 meters depth handle high-volume crude extraction across Mumbai High platforms. ONGC deploys ESP strings as the default artificial lift mode in Bombay High fields where water cut exceeds 60 percent and reservoir pressure has depleted below bubble point.
- Progressive Cavity Pump:Helical rotor-stator positive displacement systems tolerate heavy oil viscosity and entrained sand particles without gas locking. Cairn India and Vedanta Resources specify PCP installations across Barmer-Sanchor blocks in Rajasthan where API gravity readings fall below 20 degrees and sand production rates challenge conventional centrifugal designs.
- Sucker Rod Pump:Surface-mounted beam units transmit reciprocating motion through sucker rod strings to downhole pumps, dominating marginal well economics in Gujarat's mature Cambay basin fields where low productivity indices favor low-capital lift modes.
- Gas Lift:High-pressure gas injection through mandrel valves reduces hydrostatic column density to enable flow in high-GOR wells; operators deploy this method selectively in Bombay High wells producing above 500 standard cubic meters per cubic meter gas-oil ratio where ESP gas interference would degrade efficiency.
ESP leads volumes today; PCP is gaining share fastest.
Deployment:
Capital allocation splits between extending existing infrastructure life and accessing frontier reserves through purpose-built subsea architectures.
- Offshore:Platform-based lift installations in the Mumbai High and Krishna-Godavari basins require corrosion-resistant metallurgy and explosion-proof electrical specifications to withstand marine atmospheric exposure and confined-space maintenance constraints.
- Brownfield:Revitalization programs in Gujarat and Rajasthan aging fields retrofit existing wellbores with modern lift systems without drilling new holes, leveraging prior casing investments while upgrading production rates through enhanced artificial lift.
- Onshore:Land-based installations across Rajasthan and Gujarat permit simpler logistics for equipment mobilization and workover rig access, supporting lower-cost progressive cavity pump and beam pump economics.
- Subsea:Seabed-deployed boosting systems in KG-DWN-98/2 and analogous deepwater blocks combine multiphase pumping with subsea processing to maintain flow assurance across extended tieback distances to host facilities.
Offshore absorbs the largest capital commitments; subsea deployments exhibit the steepest expansion trajectory.
End User:
Procurement authority concentrates with operators who retain reservoir engineering expertise, while service companies and contractors execute installation and maintenance scope under framework agreements.
- Oil & Gas Producers:ONGC, Oil India, Cairn India, and Vedanta Resources specify artificial lift packages directly, integrating equipment selection with reservoir depletion strategies and field development planning cycles.
- Service Companies:Schlumberger, Halliburton, and Baker Hughes deliver bundled lift system deployment including engineering design, installation supervision, and ongoing production optimization services under multi-well master service agreements.
- EPC Contractors:Engineering-procurement-construction firms integrate artificial lift specifications into greenfield platform and processing facility builds, coordinating vendor selection with overall project scheduling and commissioning sequences.
- Refineries:Downstream crude purchasing agreements occasionally influence upstream lift system specifications where integrated operators seek API gravity and contaminant consistency for processing unit feedstock optimization.
Oil & Gas Producers dominate specification authority; Service Companies are expanding their share of integrated performance contracts.
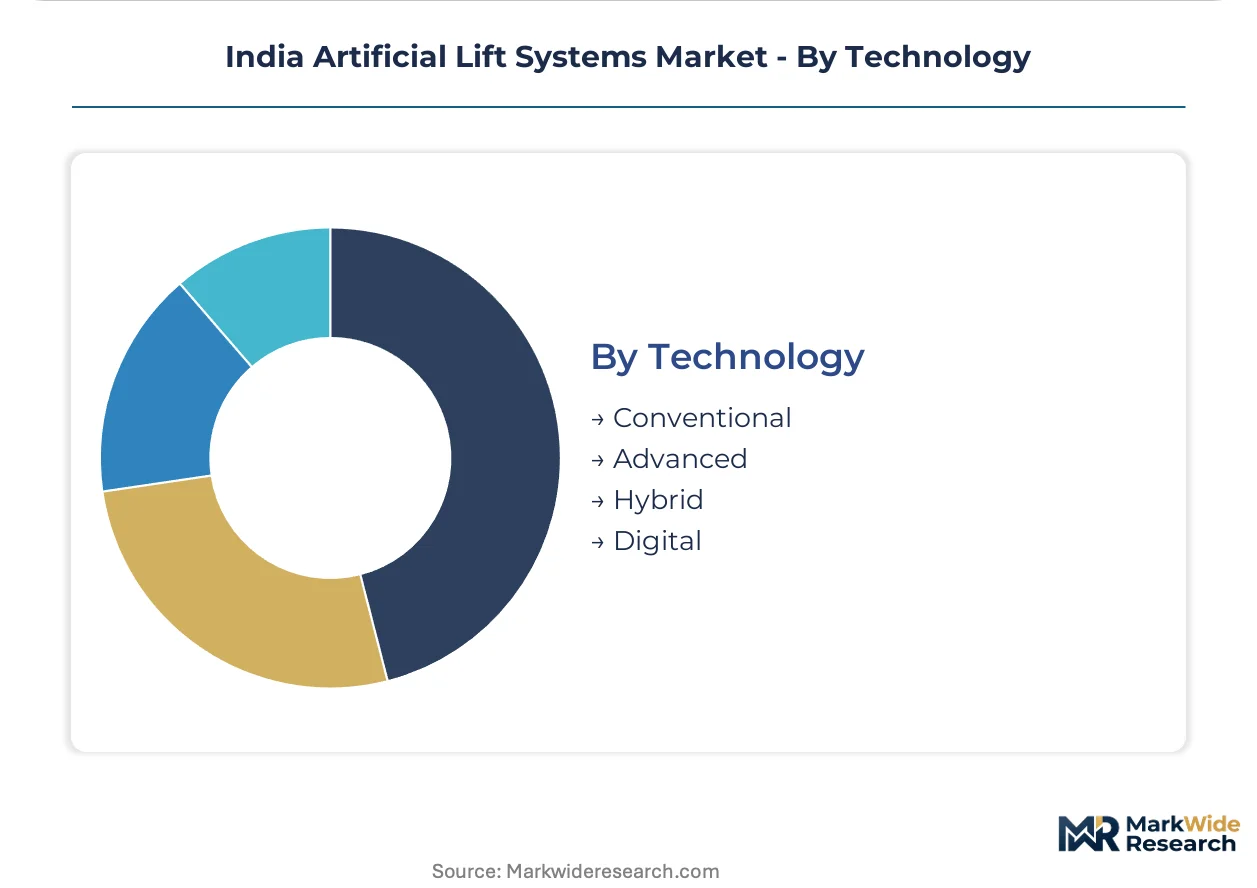
Technology:
Equipment sophistication tiers separate commodity hardware from digitally enabled systems that compress workover frequency through predictive intervention.
- Digital:ESP and PCP systems with embedded vibration, temperature, and current draw sensors transmit real-time operating parameters via Modbus or OPC-UA protocols to shore-based monitoring centers, enabling condition-based maintenance scheduling.
- Advanced:Permanent magnet synchronous motors, variable frequency drives with CEA grid harmonization compliance, and specialized metallurgy for high-temperature or corrosive service conditions address specific reservoir challenges beyond conventional equipment ratings.
- Hybrid:Configurations combining gas lift with downhole pumping or surface boosting integrate multiple lift mechanisms to handle multiphase flow regimes and slugging conditions in high-GOR or high-water-cut wells.
- Conventional:Induction motor-driven centrifugal pumps and standard beam pump units without native telemetry satisfy lowest-first-cost procurement criteria in marginal fields where monitoring infrastructure investment cannot be justified.
Conventional systems retain the installed base majority; Digital configurations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in artificial lift procurement is shifting investment toward states with streamlined certification pathways and domestic manufacturing incentives. Cost-of-compliance gaps between sub-regions are redrawing supplier footprints.
Maharashtra
Mumbai Offshore basin operators drive ESP demand through brownfield revitalization programs. The Ministry of Petroleum and Natural Gas mandates enhanced oil recovery compliance across aging Bombay High platforms. ONGC concentrates procurement authority in Mumbai, anchoring service company technical centers and digital monitoring platform deployments.
Gujarat
Cambay basin independents lack systematic artificial lift programs, creating white space for packaged rod pump contracts. The Petroleum and Natural Gas Regulatory Board's field development guidelines shape equipment certification timelines for downstream safety compliance. Ahmedabad and Vadodara host domestic pump assembly facilities benefiting from PLI scheme subsidies.
Rajasthan
Barmer-Sanchor heavy oil blocks accelerate progressive cavity pump adoption where API gravity falls below 20 degrees. Bureau of Indian Standards sucker rod metallurgy testing adds procurement friction that conflicts with urgent well intervention schedules. Cairn India and Vedanta Resources standardize single-source PCP suppliers across onshore fields.
Andhra Pradesh
Krishna-Godavari basin deepwater developments require subsea boosting integration for extended tieback distances. The Ministry of Environment, Forest and Climate Change's offshore discharge protocols constrain system design for seabed deployments. KG-DWN-98/2 block operators deploy multiphase pumps combining centrifugal pumping with subsea processing.
Tamil Nadu
Cauvery basin marginal fields favor low-capital beam pump economics where productivity indices justify conventional lift modes. Central Electricity Authority grid harmonization standards for variable frequency drives create specification windows for domestic power electronics manufacturers. Chennai-based engineering firms integrate artificial lift specifications into EPC contracts for brownfield processing facility upgrades.
India Artificial Lift Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital telemetry integration and modular skid configurations. The market structures around three tiers: full-service integrators bundling hardware with reservoir engineering support, component specialists focusing on submersible motors or pump ends, and regional fabricators serving price-sensitive independents. Dominant competitive moves include multi-year master service agreements that unbundle equipment supply from installation scope, and backward integration into domestic motor assembly to capture PLI scheme benefits.
Among US-based oilfield service conglomerates, Schlumberger NV, Halliburton Company, and Baker Hughes Company exemplify the full-service integrator archetype. These entities anchor premium positioning through digital ESP monitoring platforms and Mumbai technical center infrastructure. Their market presence represents the convergence of global manufacturing scale with localized service delivery networks. Regional specialists including Penguin Petroleum Services and United Drilling Tool Limited occupy positions serving domestic operators with compliance-adapted equipment configurations. The competitive terrain rewards entities capable of compressing workover frequency through predictive analytics while navigating Bureau of Indian Standards certification cycles.
| Leading Market Players |
|---|
| Schlumberger NV |
| Halliburton Company |
| Weatherford International plc |
| Baker Hughes Company |
| Penguin Petroleum Services (P) Limited |
| Novomet Oilfield Services Company |
| United Drilling Tool Limited |
| Apergy Corp |
| ChampionX |
| Others |
Supply & Pricing Matrix
Copper LME spot pricing volatility cascades through submersible motor windings and power cable assemblies, compressing margin pools for domestic ESP assemblers while amplifying procurement leverage for integrated service companies with captive metallurgy hedging.
Pricing Analysis
Input-cost pass-through from permanent magnet synchronous motors and specialized ESP cable insulation drives three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on Bureau of Indian Standards certification grade and after-sales telemetry bundling. Pricing pressure stems from PLI scheme subsidies lowering domestic assembly thresholds. Marginal field operators in Gujarat exhibit highest price sensitivity; Mumbai High offshore platforms prioritize run-life reliability over first cost.
Supply Chain Analysis
Regional distribution centers in Mumbai and Chennai anchor hub-and-spoke patterns for spare parts mobilization to western offshore platforms. Manufacturing concentrates in the United States, Germany, and China for high-horsepower submersible motors above 500 horsepower. Raw material dependencies include rare-earth permanent magnets, high-temperature elastomers, and corrosion-resistant superalloys. Single-source vulnerability in permanent magnet supply creates exposure to export restriction risk. Distribution runs through authorized service company depots rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Petroleum and Natural Gas Regulatory Board's 2023 field development guidelines compound demand by mandating real-time well monitoring, forcing capital deployment toward digital-ready lift packages regardless of field vintage.
For Market Incumbents: Anchor premium positioning through backward integration into domestic motor assembly under PLI scheme benefits, capturing subsidy pools that independent distributors cannot access. Deepen reservoir engineering service bundling to defend against modular skid competitors compressing rig-up economics. Prioritize certification pre-clearance with Bureau of Indian Standards to compress procurement cycles that urgent brownfield interventions demand.
For New Entrants and Emerging Players: Launch via digital-native ESP monitoring platforms targeting Cambay basin independents lacking systematic lift programs. Penetrate Gujarat rod pump white space through packaged service contracts that unbundle equipment from installation scope. Deploy predictive analytics as the primary go-to-market wedge against incumbent hardware-centric positioning.
For Investors and Strategic Acquirers: Asymmetric upside sits with domestic power electronics manufacturers qualifying under Central Electricity Authority grid harmonization standards for variable frequency drive supply. Long-term viability favors entities controlling both hardware assembly and telemetry software layers. Monitor subsea installation technician certification throughput as the inflection signal for deepwater project viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Motor Assembly Expansion | PLI scheme subsidies reduce import exposure for ONGC brownfield programs. |
| Digital Telemetry Platform Integration | Modbus and OPC-UA connectivity satisfy Petroleum and Natural Gas Regulatory Board mandates. |
| Subsea Technician Training Partnership | Mumbai High operators compete for limited crews qualified in umbilical termination assembly. |
| Master Service Agreement Consolidation | Oil India and Hindustan Petroleum now contract lift systems through multi-year frameworks. |
| PCP Standardization in Heavy Oil Blocks | Vedanta Resources and Cairn India consolidate suppliers across Barmer-Sanchor fields. |
Research Methodology
Bottom-up oilfield operator procurement modeling reconciled against top-down equipment supplier shipment tracking forms the analytical core of this study. Primary interviews with reservoir engineers, artificial lift procurement managers, and EPC contract specialists combine with secondary validation from Directorate General of Hydrocarbons production data, Petroleum Planning and Analysis Cell import statistics, and Bureau of Indian Standards certification registries. Triangulation across these sources ensures segmentation integrity across product type, deployment environment, and technology tier dimensions.
Input-output matrices map ESP motor horsepower ratings, PCP rotor-stator configurations, and gas lift mandrel specifications against well intervention frequency and reservoir depletion curves across the projection horizon. Segmentation dimensions include product type, deployment mode, end-user category, and technology sophistication tier. CAGRs derive from regression analysis of historical brownfield revitalization spending and greenfield development capex commitments. Forecast inputs incorporate PLI scheme subsidy trajectories and Central Electricity Authority regulatory amendment timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under permanent magnet export restriction scenarios or accelerated subsea project sanctioning. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Australia LNG Bunkering Market
Oil & Gas
Subsea Multiphase Flowmeter Market
Oil & Gas
Gulf of Mexico Oil and Gas Midstream Market
Oil & Gas
Iraq Oil and Gas Market
Oil & Gas
Oil & Gas Equipment MRO Market
Oil & Gas
Europe Seismic Services Market
Oil & Gas
Vietnam Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Pipe Market
Oil & Gas
Exploration and Drilling Security Market
Oil & Gas
Oil and Gas Industry Turbomachinery Market
Oil & Gas
LNG Terminal Market
Oil & Gas
Delayed Coker Unit Process Technology Market
Oil & Gas
Oil and Gas Electrification Market
Oil & Gas
Digital Oil Field Technology Market
Oil & Gas
Well Intervention Service Market
Oil & Gas
Denmark Oil and Gas Midstream Market