
 Sand Control Screens Market | 2026-2036
Sand Control Screens Market Size, Share, and Industry Trends Forecast 2026-2036
Sand Control Screens Market Analytics
The split between premium alloy screens and commodity-grade wire-wrapped products is shifting procurement patterns across upstream supply chains. Baker Hughes leverages its integrated manufacturing footprint to sustain margin capture on high-nickel alloy systems. Halliburton anchors its position through R&D intensity in expandable screen architectures. National Oilwell Varco competes on channel control, dominating offshore rig outfitting workflows where sand control integrates with broader completion packages.
Sand control screens are downhole filtration devices engineered from corrosion-resistant alloys, typically 316L stainless steel or Inconel, with slot openings precision-cut to exclude formation sand while permitting hydrocarbon flow. These systems prevent sand production that erodes tubulars, chokes surface equipment, and degrades well productivity over time. Premium metallurgy segments command the deepest margin pools as operators push into high-pressure, high-temperature reservoirs where standard materials fail. Wire-wrapped technology leads installed base volumes, though composite and expandable variants represent the fastest-growing category as slim-hole and multilateral completions proliferate. Onshore applications remain the volume anchor, while offshore and enhanced oil recovery segments concentrate value growth.
API Specification 19SS governs screen design validation and testing protocols, while NORSOK M-001 and M-503 standards dictate material selection and manufacturing quality for North Sea deployments. The US Bureau of Safety and Environmental Enforcement enforces well integrity requirements that cascade into sand control specification stringency, particularly for deepwater permits in the Gulf of Mexico. Stakeholders must monitor how tightening methane emissions frameworks and carbon intensity benchmarks reshape operator preferences between gravel pack and standalone screen completion strategies.
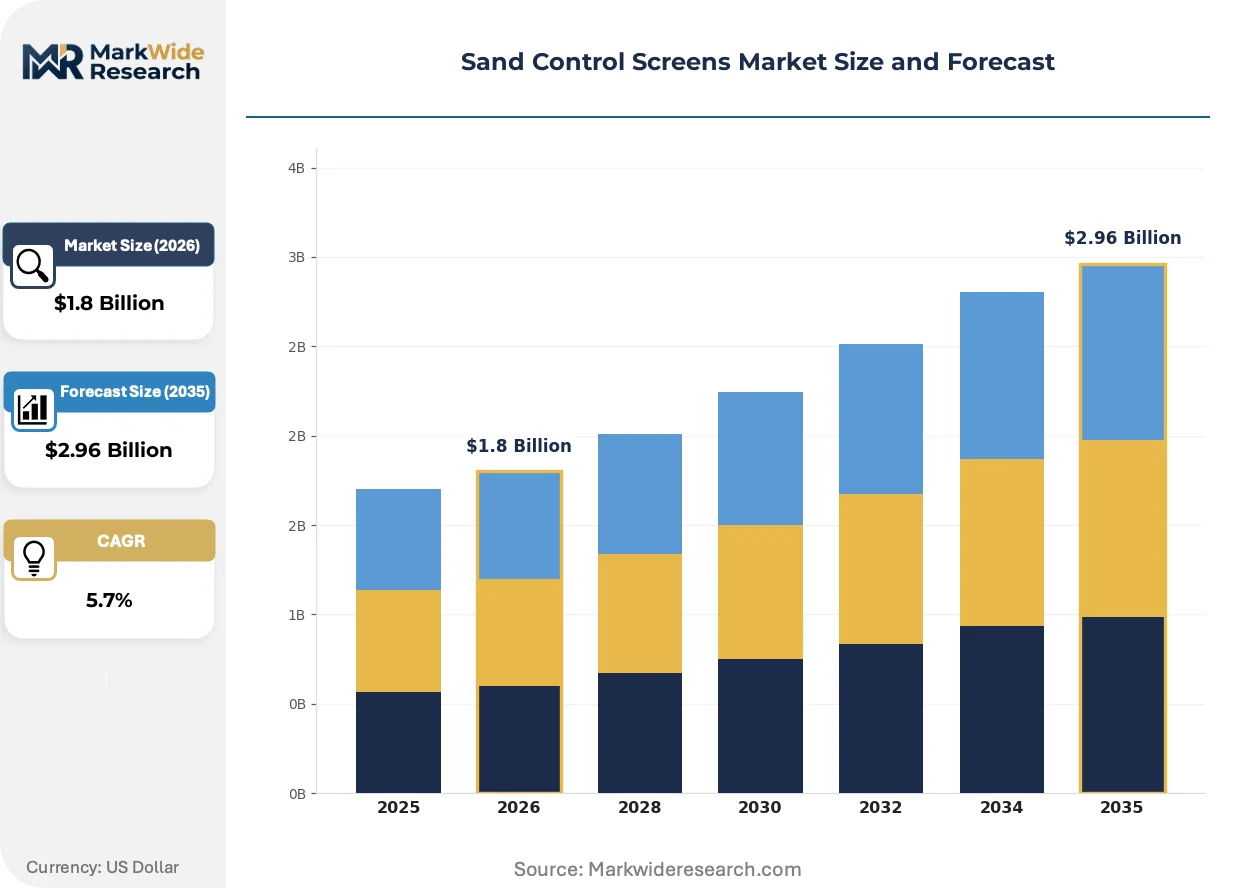
Market Dynamics
Expandable screen architectures are compressing the traditional gravel-pack market as operators pursue slim-hole completions that reduce rig time and tubular inventory. API Specification 19SS validation protocols and NORSOK M-001 material standards are tightening qualification barriers, forcing suppliers to absorb higher testing overhead or exit premium segments.
Growth Catalysts
- Deepwater Gulf of Mexico activity:High-pressure, high-temperature reservoirs below 15,000 feet demand Inconel-based screen systems that withstand corrosive formation fluids. BSEE well integrity enforcement cascades into mandatory premium metallurgy specifications.
- REACH substance restrictions:European operators face phased limitations on chromium plating processes, accelerating adoption of laser-cut slot geometries that eliminate surface coating requirements.
- Multilateral well architectures:Expandable screen technologies enable junction isolation without gravel pack placement, reducing completion complexity in Brazil's pre-salt carbonate formations.
Market Restraints
- Nickel price volatility:Inconel 625 and 718 alloys constitute 40-60% of raw material cost for premium screens. LME nickel contract swings compress fabricator margins and destabilize long-term supply agreements.
- Supply concentration in seamless pipe:Premium alloy tubular feedstock concentrates among a limited set of European and Japanese mills, creating bottleneck risk for screen manufacturers without backward integration.
- Gravel pack substitution economics:Mature onshore fields in West Texas continue deploying low-cost gravel pack completions, limiting standalone screen penetration in price-sensitive basins.
Strategic Opportunities
- Pre-salt Brazil expansion:Petrobras development plans through 2030 target 45+ deepwater wells annually, creating dedicated demand for expandable sand control systems in ultra-deepwater carbonate reservoirs.
- CCUS well repurposing:Carbon capture and storage projects require sand control in depleted oil and gas formations converted to injection service, opening retrofit screen demand in the US Permian and Gulf Coast.
- Digital inventory platforms:Operator consortiums are piloting vendor-managed inventory systems that shift screen procurement from project-based tendering to consumption-based replenishment.
Industry Challenges
- HPHT qualification timelines:API 19SS validation testing for 350°F+ service requires 18-24 month certification cycles, delaying revenue recognition for new alloy formulations.
- Slot geometry precision:Tolerance control below 0.001 inch demands specialized wire EDM and laser cutting capabilities that concentrate among a limited supplier base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sand Control Screens Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screens, Gravel Packs, Inflow Control Devices, Expandable Screens Technology: Wire Wrapped, Composite, Premium, Solid Application: Offshore, Onshore, Well Completion, Enhanced Oil Recovery End User: Oil & Gas Companies, Service Providers, Drilling Contractors, Research Institutions |
| Companies Covered | Schlumberger Limited, Baker Hughes, Halliburton Company, National Oilwell Varco, Weatherford International, Superior Energy Services, Tendeka, Welltec, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sand Control Screens Market Evolving Landscape
Composite material formulations and additive manufacturing methods are disrupting traditional wire-wrapped construction, enabling conformable screen geometries that adapt to irregular borehole profiles without gravel pack annulus.
Expandable sand control screen technology is unifying the functions of mechanical support, sand filtration, and annular isolation into single-trip deployment systems. Major Gulf of Mexico operators now specify expandable architectures for 70% of deepwater completions, compressing rig time from 14 days to 4 days versus conventional gravel pack alternatives. This unification is compressing the addressable market for standalone wire-wrapped products in premium offshore segments.
EU F-Gas Regulation phase-down mandates are accelerating elimination of perfluorinated compounds in screen manufacturing surface treatments. Fabricators serving North Sea deployments must reformulate passivation and cleaning chemistries by 2030, raising process validation costs but creating competitive separation for early compliant suppliers. The restriction most affects composite screen manufacturers relying on fluoropolymer coatings for erosion resistance.
Operator procurement functions are consolidating sand control purchasing into integrated completion package tenders, disintermediating standalone screen distributors. Majors in the US Gulf Coast now mandate single-source accountability for lower completion hardware, forcing screen suppliers to integrate with packer and liner system providers. This consolidation is most visible among independent operators in the Eagle Ford who previously sourced screens through regional oilfield distributors.
Sand Control Screens Market Segmentation
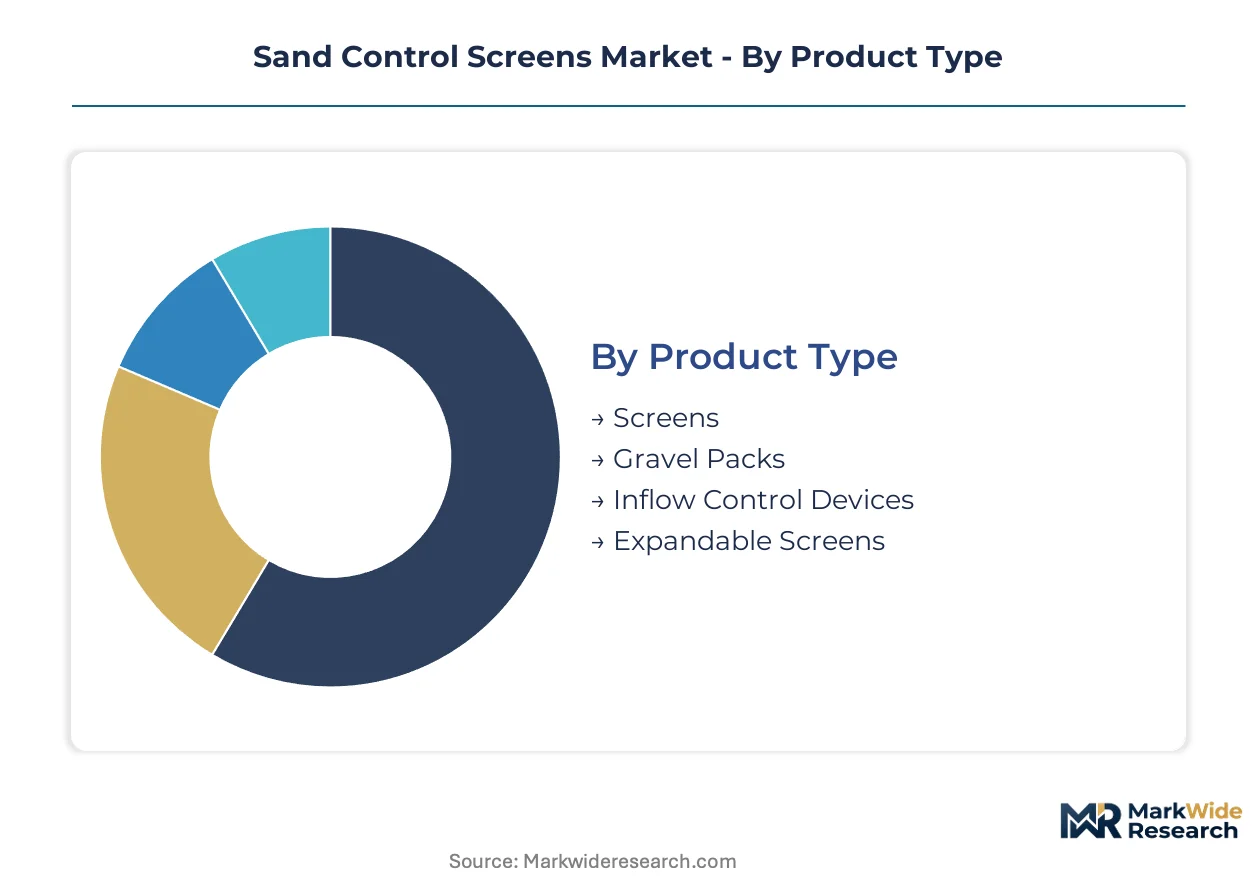
Sand control screen procurement splits sharply between volume-driven wire-wrapped commodity products and premium metallurgy systems commanding outsized margins in deepwater applications. Understanding these segment boundaries clarifies where suppliers can defend pricing power versus where cost compression dominates.
Product Type:
Volume concentrates in gravel pack completions, while value migrates toward expandable and integrated screen architectures that reduce rig time.
- Screens:Standalone filtration devices manufactured from 316L stainless steel or Inconel with precision-cut slot geometries. Demand clusters in the US Gulf Coast where BSEE well integrity mandates specify premium metallurgy for deepwater permits.
- Gravel Packs:Conventional annular filtration systems combining wire-wrapped screens with proppant placement. Operators in West Texas mature fields continue deploying these completions for their established cost economics in low-pressure reservoirs.
- Inflow Control Devices:ICDs integrate autonomous flow regulation with sand exclusion functions.
- Expandable Screens:Conformable architectures that expand to borehole diameter without gravel pack placement.
Today's leader: Gravel Packs. Tomorrow's challenger: Expandable Screens.
Technology:
Cost tier stratification separates precision-manufactured premium systems from commodity wire-wrapped products with divergent margin profiles.
- Wire Wrapped:Continuous wire helically wound around longitudinal rods to form precise filtration slots. This technology anchors installed base volumes across Oklahoma'sSTACK play and other mature onshore basins where operators prioritize unit economics over metallurgical sophistication.
- Premium:High-nickel alloy systems engineered for HPHT service above 350°F and 15,000 psi. Gulf of Mexico pre-salt exploration and BSEE deepwater enforcement create dedicated demand for Inconel 625 and 718 formulations with 18-24 month API 19SS qualification cycles.
- Composite:Polymer-matrix constructions eliminating metallic corrosion risks.
- Solid:Laser-perforated base pipe without wire wrapping.
Wire Wrapped dominates volume. Premium captures value. Composite architectures are climbing the fastest as REACH substance restrictions accelerate coating elimination.
Application:
Geography and reservoir characteristics dictate technology selection more than operator size or drilling program scale.
- Offshore:Deepwater completions below 15,000 feet requiring Inconel-based systems. Brazil's pre-salt carbonate formations and US Gulf of Mexico high-pressure reservoirs specify expandable architectures for 70% of new completions, compressing rig time from 14 days to 4 days versus gravel pack alternatives.
- Onshore:Mature field redevelopment and unconventional shale development. The Permian Basin and Eagle Ford sustain wire-wrapped volume demand, though CCUS well repurposing is creating retrofit screen opportunities in depleted formations.
- Well Completion:New well construction across reservoir types.
- Enhanced Oil Recovery:Thermal and chemical flood applications with specialized metallurgy requirements.
Offshore commands pricing power. Onshore anchors volume. Enhanced Oil Recovery offers the steepest expansion trajectory as thermal EOR projects proliferate in California and the Middle East.
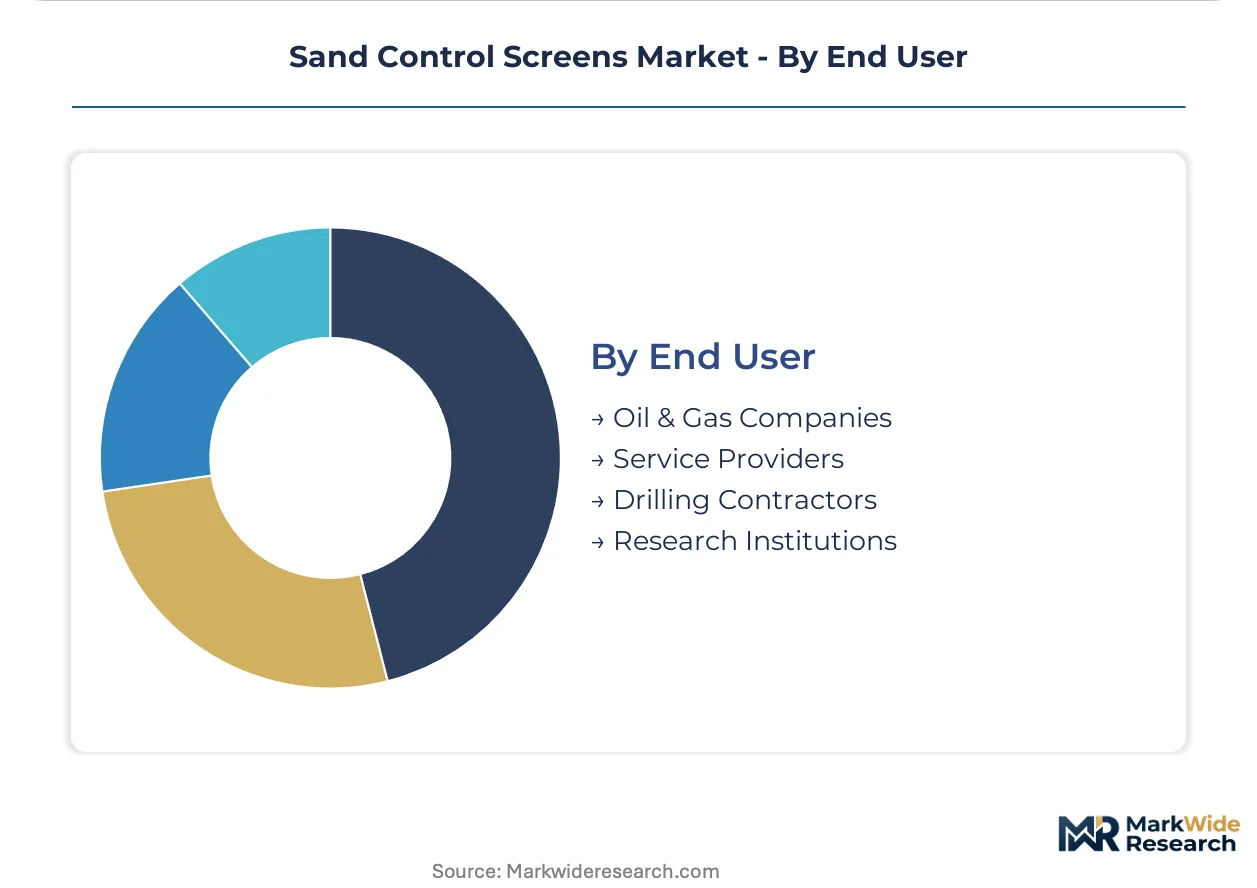
End User:
Procurement consolidation is reshaping vendor relationships as integrated completion packages displace standalone screen purchasing.
- Oil & Gas Companies:Majors and independents specifying sand control as part of lower completion tenders. US Gulf Coast operators now mandate single-source accountability for completion hardware, forcing screen suppliers to integrate with packer and liner system providers.
- Service Providers:Schlumberger, Halliburton, and Baker Hughes operating as integrated completion contractors. These firms leverage manufacturing footprints to capture margin on high-nickel alloy systems while outsourcing commodity wire-wrapped production.
- Drilling Contractors:Rig operators outfitting offshore units with completion packages.
- Research Institutions:Universities and national laboratories developing next-generation filtration materials.
Oil & Gas Companies control specification. Service Providers control fulfillment. Drilling Contractors represent the fastest-growing procurement channel as offshore rig outfitting workflows consolidate sand control into broader completion packages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deepwater drilling economics diverge sharply between the US Gulf Coast and Brazil's pre-salt basins, with each geography imposing distinct metallurgical and regulatory burdens on screen suppliers.
United States
The US Bureau of Safety and Environmental Enforcement mandates premium Inconel formulations for deepwater permits below 15,000 feet in the Gulf of Mexico. Baker Hughes and Halliburton maintain manufacturing footprints in Houston to capture margin on high-nickel alloy systems serving HPHT reservoirs. The Permian Basin anchors wire-wrapped volume demand for mature onshore redevelopment.
Brazil
Petrobras development plans target 45+ deepwater wells annually through 2030 in pre-salt carbonate formations. ANP regulatory frameworks require expandable screen architectures for junction isolation without gravel pack placement. The Santos Basin concentrates demand for conformable systems that reduce rig time from 14 days to 4 days versus conventional completions.
Norway
NORSOK M-001 and M-503 standards dictate material selection and manufacturing quality for North Sea deployments. EU F-Gas Regulation phase-down mandates accelerate elimination of perfluorinated compounds in surface treatments by 2030. Stavanger-based fabricators reformulate passivation chemistries to maintain access to Barents Sea exploration licenses.
United Kingdom
The North Sea Transition Authority enforces well integrity requirements that cascade into sand control specification stringency for aging platform infrastructure. REACH substance restrictions on chromium plating processes drive adoption of laser-cut slot geometries. Aberdeen clusters specialize in retrofit screen demand for enhanced oil recovery projects in depleted formations.
Saudi Arabia
Aramco unconventional gas programs in the Jafurah Basin create demand for standalone screen completions in tight sandstone reservoirs. The Ministry of Energy's localization mandates push suppliers toward in-country manufacturing partnerships. Dhahran industrial zones concentrate service provider operations for integrated completion packages across the Eastern Province.
Sand Control Screens Market Competitive Landscape
Top-tier vendors anchor the premium metallurgy segment, while mid-scale fabricators compete on wire-wrapped commodity volumes. The supplier base stratifies across integrated oilfield service conglomerates, independent screen specialists, and regional manufacturing operations. Strategic archetypes include backward-integrated alloy processors, technology licensors for expandable architectures, and channel-dominant rig outfitters. Competitive moves concentrate on API 19SS qualification acceleration and vendor-managed inventory partnerships with operator consortiums.
Within the integrated service tier, Schlumberger Limited, Baker Hughes, and Halliburton Company exemplify archetypes of manufacturing scale, R&D intensity, and completion package integration respectively. These entities occupy positions where captive alloy supply chains intersect with global offshore rig outfitting workflows. Independent specialists such as Tendeka and Welltec represent technology-focused alternatives in expandable screen architectures. The competitive dynamic situates conglomerates against nimble specialists in a market where procurement consolidation favors single-source accountability for lower completion hardware.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Baker Hughes |
| Halliburton Company |
| National Oilwell Varco |
| Weatherford International |
| Superior Energy Services |
| Tendeka |
| Welltec |
| 3M Company |
| Others |
Value Network & Pricing Analysis
LME nickel contract volatility cascades through sand control screen supply chains, compressing fabricator margins on Inconel 625 and 718 formulations while forcing tiered pricing separation between premium alloy systems and commodity wire-wrapped alternatives. Buyers in the US Gulf Coast absorb metallurgy premiums mandated by BSEE well integrity enforcement, whereas West Texas operators retain leverage on standard-grade procurement.
Pricing Analysis
Capacity additions in Japan and Germany are reshaping price floors for seamless pipe feedstock, yet premium screen manufacturers maintain pricing power through captive alloy processing and API 19SS certification barriers. Three-tier pricing structure across premium, standard, and economy levels separates Inconel-based HPHT systems from 316L stainless architectures and basic wire-wrapped commodities. Price differentiation hinges on qualification timeline length and after-sales technical support bundling. Cost compression in standard-grade segments is intensifying because regional distributors are consolidating purchasing into integrated completion tenders. Independent operators in the Eagle Ford exhibit highest price sensitivity, while deepwater majors in Brazil and the Gulf of Mexico demonstrate lowest sensitivity due to failure-cost risk.
Supply Chain Analysis
Regional distribution centers in Houston, Stavanger, and Singapore anchor hub-and-spoke patterns that position finished screens within 72-hour reach of active offshore rig fleets. Geographic supply concentration centers on Japanese and European seamless pipe mills for premium alloy tubulars, Chinese wire-wrapped component fabricators for commodity volumes, and US Gulf Coast machining clusters for precision slot cutting. Raw material dependencies draw from LME-traded nickel, chromium alloying elements, and specialized wire EDM consumables. Single-source vulnerability in seamless pipe feedstock creates bottleneck exposure for non-integrated screen manufacturers. Distribution runs through oilfield service provider warehouses and operator consortium vendor-managed inventory platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sand control screens constitute a late-cycle quality story as deepwater operators substitute expandable architectures for gravel packs, elevating specification stringency on metallurgy, slot precision, and qualification documentation.
For Market Incumbents: Extend API 19SS certification coverage into composite material formulations before EU F-Gas restrictions eliminate fluoropolymer coating alternatives. Consolidate channel position through vendor-managed inventory partnerships with Petrobras and US Gulf Coast operator consortiums. Nickel price volatility and REACH substance phase-downs threaten margin stability for suppliers without backward integration into alloy processing. For New Entrants and Emerging Players: Capture retrofit screen demand in CCUS well repurposing projects across the US Permian and Gulf Coast, where depleted formation conversions require sand control without established supplier relationships. Target expandable screen technology licensing agreements with mid-size service providers lacking R&D scale. The most penetrable entry vector lies in digital inventory platforms that shift procurement from project-based tendering to consumption-based replenishment. For Investors and Strategic Acquirers: Asymmetric upside sits with independent specialists holding expandable screen patents and pre-salt Brazil operational track records. Five-to-ten year viability favors fabricators with demonstrated HPHT qualification completion and in-country manufacturing partnerships in Saudi Arabia's Jafurah Basin. Watch Petrobras annual well completion targets as the primary inflection indicator for premium expandable system demand.| Strategic Initiative | Industry Significance |
|---|---|
| API 19SS Certification Acceleration | Shortens revenue recognition cycles for new Inconel formulations entering HPHT service. |
| Backward Integration into Alloy Processing | Insulates margin capture from LME nickel volatility and seamless pipe supply bottlenecks. |
| Vendor-Managed Inventory Partnerships | Locks channel position with US Gulf Coast operators consolidating lower completion procurement. |
| Composite Material Formulation Investment | Positions early compliance with EU F-Gas Regulation surface treatment restrictions. |
| In-Country Manufacturing Localization | Satisfies Saudi Aramco and Ministry of Energy mandates for Jafurah Basin unconventional gas development. |
Research Methodology
Direct dialogue with completion engineers at supermajors, sand control procurement leads at national oil companies, API certification auditors, and wire EDM equipment specialists grounded qualitative findings in operational reality. Secondary validation drew from BSEE well integrity enforcement records, NORSOK M-001 and M-503 technical specifications, ANP regulatory filings for Brazil pre-salt developments, and SEC 10-K disclosures from integrated oilfield service providers. Bottom-up well completion counts across the US Gulf Coast, Brazil, and Norway were triangulated against top-down market size estimates.
Segment-level projections across product type, technology tier, application geography, and end-user channel were generated through the analysis window using a structured analytical framework. CAGRs were derived from regression analysis of historical completion activity correlated with Brent crude price trajectories and deepwater rig day-rate movements. Industry-specific forecast inputs incorporated Petrobras development plan commitments, US Bureau of Safety and Environmental Enforcement permit issuance trends, and EU F-Gas Regulation implementation timelines.
Geopolitical disruption to nickel supply corridors, abrupt shifts in ANP or BSEE regulatory stringency, and faster-than-anticipated gravel pack substitution by expandable architectures are the dominant revision risks to the forecast framework. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Proppant Market
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
Romania Oil and Gas Market
Oil & Gas
Europe Seismic Services Market
Oil & Gas
Casing Centralizer Market
Oil & Gas
United States Artificial Lift Systems Market
Oil & Gas
Mobile Servicing Rig Market
Oil & Gas
Latin America Artificial Lift System Market
Oil & Gas
Azerbaijan Oil and Gas Downstream Market
Oil & Gas
South and Central America Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Oil and Gas Well Conductor Installation Services Market
Oil & Gas
Oil & Gas Static and Rotating Equipment Market
Oil & Gas
Russian Federation Oil and Gas Market
Oil & Gas
North America Seismic Services Market
Oil & Gas
Middle East and North Africa Oilfield Services Market
Oil & Gas
Canada Oil and Gas Pipeline Services Market