
 Europe Oilfield Equipment Rental Services Market | 2026-2036
Europe Oilfield Equipment Rental Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Oilfield Equipment Rental Services Market Foresight
Buyer concentration among European supermajors and national oil companies is restructuring procurement dynamics across the rental services landscape. Baker Hughes Co leverages its integrated technology portfolio to anchor long-term maintenance contracts in the Norwegian sector. Schlumberger NV competes through digital drilling solutions bundled with equipment packages. Weatherford International plc specializes in well construction rental tools, sustaining market presence through regional service hubs.
Europe Oilfield Equipment Rental Services encompass the short-term provision of drilling rigs, well control systems, pressure pumps, and measurement tools to upstream oil and gas operators, typically governed by day-rate or meterage-based contract structures with technical specifications tied to well depth, pressure ratings, and environmental operating envelopes. Onshore Services dominate current rental volumes across mature basins in Romania and the United Kingdom, while Offshore Services capture premium rate structures in deeper North Sea waters. Drilling Rigs represent the most capital-intensive equipment category, with margin pools concentrating in Project-based Rentals where operators seek flexibility amid exploration uncertainty.
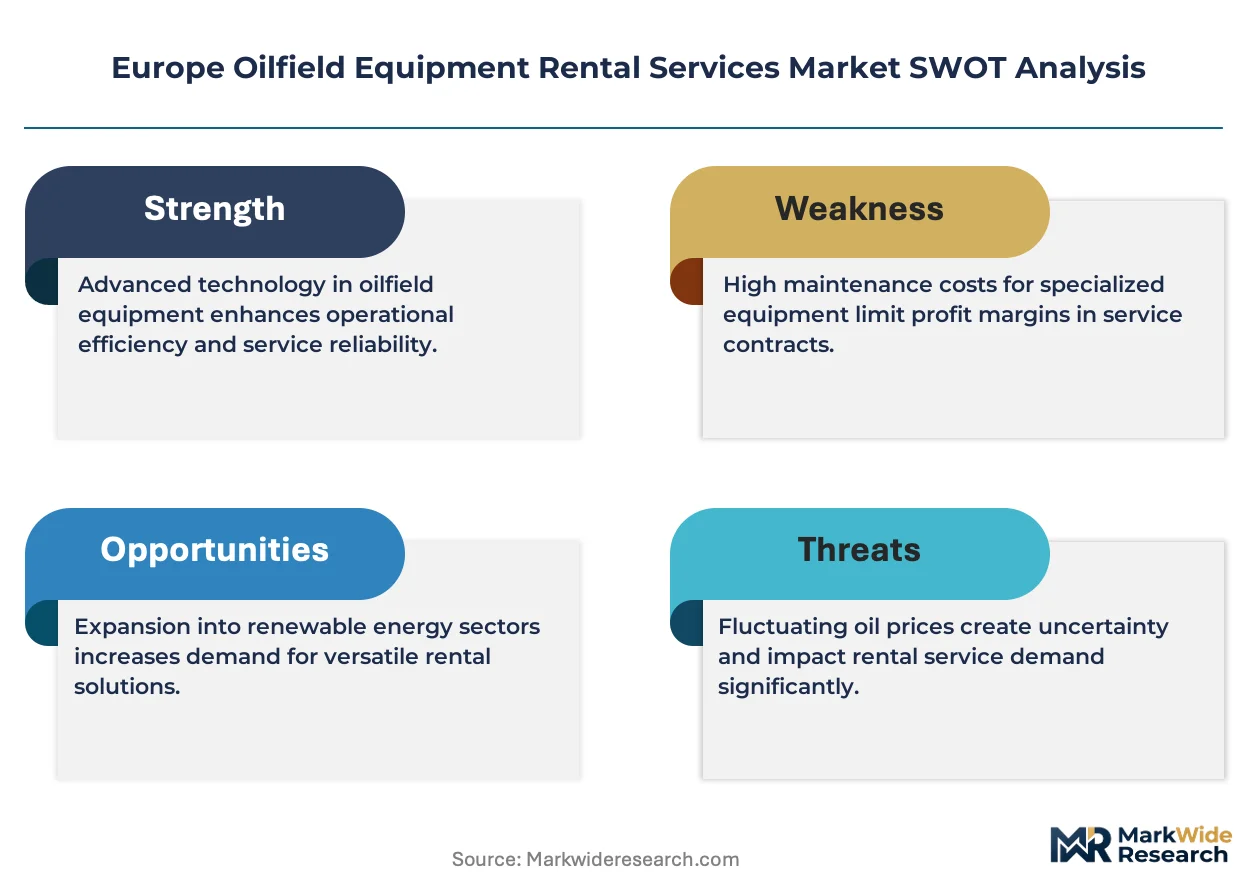
The EU Green Deal and F-Gas Regulation impose escalating emissions standards on offshore drilling equipment, compelling rental providers to upgrade fleets with lower-carbon power systems and enhanced blowout preventer configurations. REACH and CE marking requirements govern chemical handling and pressure equipment safety across EU member state operations. Stakeholders must monitor regulatory divergence between EU climate mandates and individual national oil company production targets when calibrating fleet investment and contract pricing strategies.
Market Dynamics
Capital discipline among North Sea operators is compressing equipment ownership cycles, with rental models displacing outright purchase across pressure pumping and well control categories as exploration budgets tighten and F-Gas compliance costs escalate.
Growth Catalysts
- EU Green Deal stringency:The F-Gas Regulation mandates phasedown of hydrofluorocarbon emissions from offshore drilling power systems, compelling operators to lease compliant blowout preventer packages rather than retrofit owned assets.
- Norwegian continental shelf activity:Equinor-led field developments in the Barents Sea and mature North Sea blocks sustain demand for flexible-term pressure pumping rentals amid reservoir complexity.
- Digital twin integration:Real-time equipment monitoring via IoT sensors is reducing downtime penalties in day-rate contracts, improving rental economics for high-specification drilling tools.
Market Restraints
- Steel and alloy input volatility:Chromium-molybdenum steel price swings compress margin predictability for drill pipe and casing rental inventories held on long-term balance sheets.
- Specialized fabricator concentration:Premium pressure control equipment manufacturing clusters in Houston and Aberdeen create geographic supply vulnerability for European rental fleets.
- REACH chemical handling friction:The ECHA authorization process for drilling fluid additives extends deployment timelines for rental packages requiring cross-border EU mobilization.
Strategic Opportunities
- Romanian onshore underpenetration:Mature Carpathian basin operators lack modern rental infrastructure, creating first-mover potential for automated drilling rig lessors establishing regional hubs.
- CSRD disclosure mandates:The EU Corporate Sustainability Reporting Directive requires Scope 3 emissions transparency, advantaging rental providers with certified low-carbon equipment chains over owned-asset competitors.
- Electrification-meets-subsea convergence:Battery-hybrid power modules paired with subsea wellhead systems open new rental categories in Norway's electrification-focused field developments.
Industry Challenges
- BOP recertification bottlenecks:Lloyd's Register and DNV well control equipment inspection queues extend 40-60 days, stranding rental assets during peak demand windows.
- Legacy SCADA integration friction:Older drilling rigs require protocol bridging to connect with modern rental telemetry packages, complicating mixed-fleet deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Oilfield Equipment Rental Services Market |
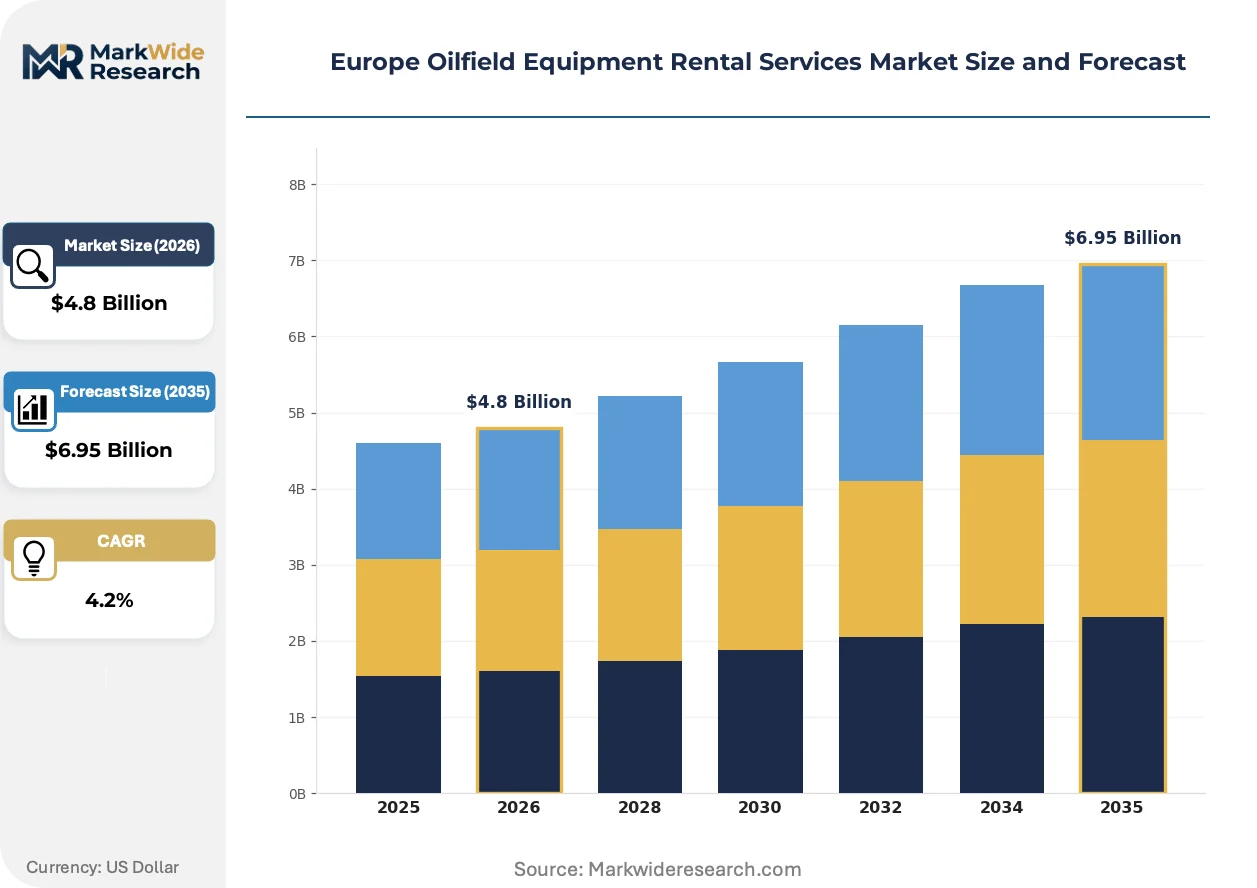
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Onshore Services, Offshore Services, Equipment Leasing, Maintenance Services Equipment Type: Drilling Rigs, Well Control Equipment, Pressure Pumps, Measurement Tools End User: Exploration Companies, Production Companies, Service Providers, Contractors Contract Duration: Short-term Contracts, Long-term Contracts, Project-based Rentals, Hourly Rentals |
| Companies Covered | Baker Hughes Co, Seadrill Ord Shs, TechnipFMC PLC, Noble Corporation PLC, Valaris Ltd, Weatherford International plc, Transocean LTD, Halliburton Company, Schlumberger NV, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Oilfield Equipment Rental Services Market Shifts & Advancements
Equipment intelligence and emissions accountability are converging to redefine rental value propositions, with data-enabled performance guarantees displacing traditional day-rate structures and regulatory compliance becoming a bundled service layer.
Condition-based monitoring systems using vibration analysis and thermal imaging are automating predictive maintenance scheduling for high-value blowout preventer stacks. North Sea drilling contractors are adopting these packages fastest, with 18-month payback thresholds now standard in Norwegian sector tenders. This automation is compressing unplanned downtime penalties and shifting rental pricing toward guaranteed-availability models.
The F-Gas Regulation's 2030 phase-down targets are forcing rapid fleet turnover in offshore power modules, with rental providers absorbing stranded asset risk from older diesel-hydraulic systems. Equipment lessors with capital reserves for dual-fuel and battery-hybrid acquisitions are capturing premium rate structures in UK and Dutch North Sea blocks. Subsea well intervention units face the steepest compliance cost escalation under these rules.
Performance-based contracting is displacing pure day-rate structures across Norwegian and UK continental shelf operations, with operators tying 30-40% of rental fees to footage drilled or non-productive time reduction. This shift concentrates procurement authority with drilling superintendents rather than traditional supply chain functions. The model is most advanced in Equinor's supplier framework agreements, where digital performance dashboards determine contract renewals.
Europe Oilfield Equipment Rental Services Market Segmentation
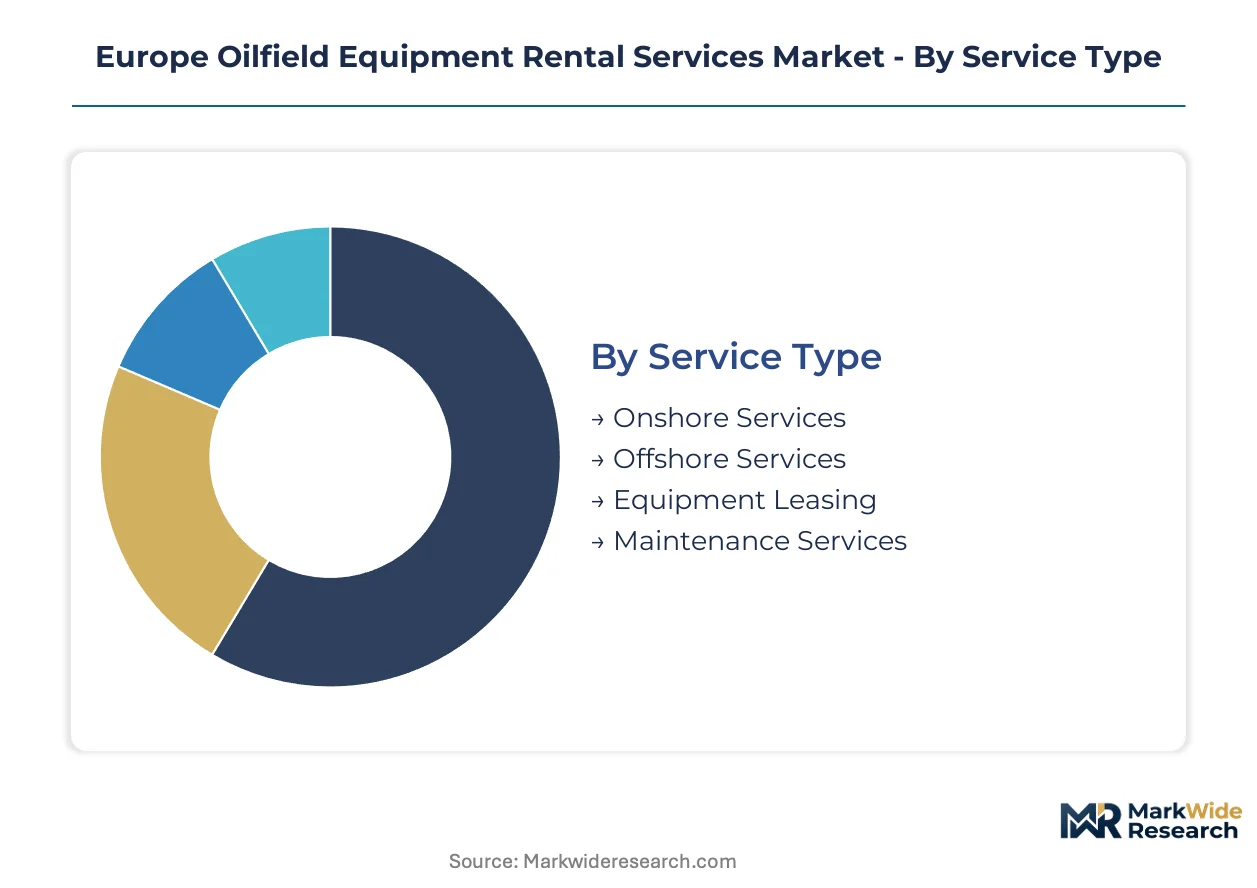
Equipment rental services in the European oilfield sector fragment across service delivery models, asset categories, customer procurement patterns, and contract structures. Each dimension carries distinct margin profiles and capital requirements that shape competitive positioning.
Service Type:
Capital intensity varies sharply across service delivery models, with offshore mobilization demanding vessel fleets and subsea infrastructure that dwarf onshore logistics requirements.
- Onshore Services:Rental packages for mature Romanian and UK land basins emphasize automated drilling rigs and pressure pumping units deployable via standard heavy-haul logistics. Operators in the Carpathian basin favor flexible-term contracts amid exploration uncertainty, while North Sea onshore terminals require rapid-response maintenance fleets.
- Offshore Services:Subsea well control equipment and intervention vessels command premium day-rates tied to weather windows and regulatory inspection cycles. Norwegian continental shelf projects absorb the bulk of North Sea offshore rental commitments, with Equinor-led developments specifying dual-fuel power modules under F-Gas compliance mandates.
- Equipment Leasing:Extended-term asset provision with bundled insurance and recertification services targets capital-constrained mid-tier operators.
- Maintenance Services:Predictive maintenance contracts leveraging IoT telemetry reduce unplanned downtime penalties in day-rate structures.
Onshore Services absorbs the bulk of installed capacity; Offshore Services is expanding most quickly.
Equipment Type:
Margin pools concentrate in categories where technical specification, regulatory compliance, and recertification complexity create barriers to fleet replication.
- Drilling Rigs:The most capital-intensive category, with jack-up and semi-submersible units requiring Lloyd's Register or DNV certification cycles that extend 40-60 days. Norwegian sector tenders now specify battery-hybrid power configurations, accelerating fleet turnover among lessors with capital reserves for dual-fuel acquisitions.
- Well Control Equipment:Blowout preventer stacks face the steepest F-Gas Regulation compliance cost escalation, with rental providers absorbing stranded asset risk from older diesel-hydraulic systems. Real-time condition monitoring via vibration analysis and thermal imaging is compressing downtime penalties across UK and Dutch North Sea blocks.
- Pressure Pumps:Specialized packages for high-pressure, high-temperature reservoirs dominate Equinor's Barents Sea and mature North Sea block developments.
- Measurement Tools:Directional drilling and logging-while-drilling sensors bundled with digital twin integration command performance-based contract structures.
Drilling Rigs locks up the majority of balance sheet deployment; Well Control Equipment is climbing the fastest on regulatory replacement cycles.
End User:
Procurement authority patterns diverge between exploration-focused risk-takers and production-optimized incumbents with established supplier frameworks.
- Exploration Companies:Flexible rental terms predominate as operators defer capital purchases amid reservoir uncertainty, particularly in UK and Norwegian frontier blocks where Equinor-led consortiums specify meterage-based pricing.
- Production Companies:Long-term maintenance contracts anchor revenue for rental providers with regional service hub infrastructure.
- Service Providers:Subcontracted rental procurement concentrates in integrated drilling contractors bundling equipment with operational crews.
- Contractors:Specialized well intervention and workover firms seek short-term pressure control packages for campaign-based deployment.
Exploration Companies drive spot-market volatility; Production Companies provide the steadiest contract renewal visibility.
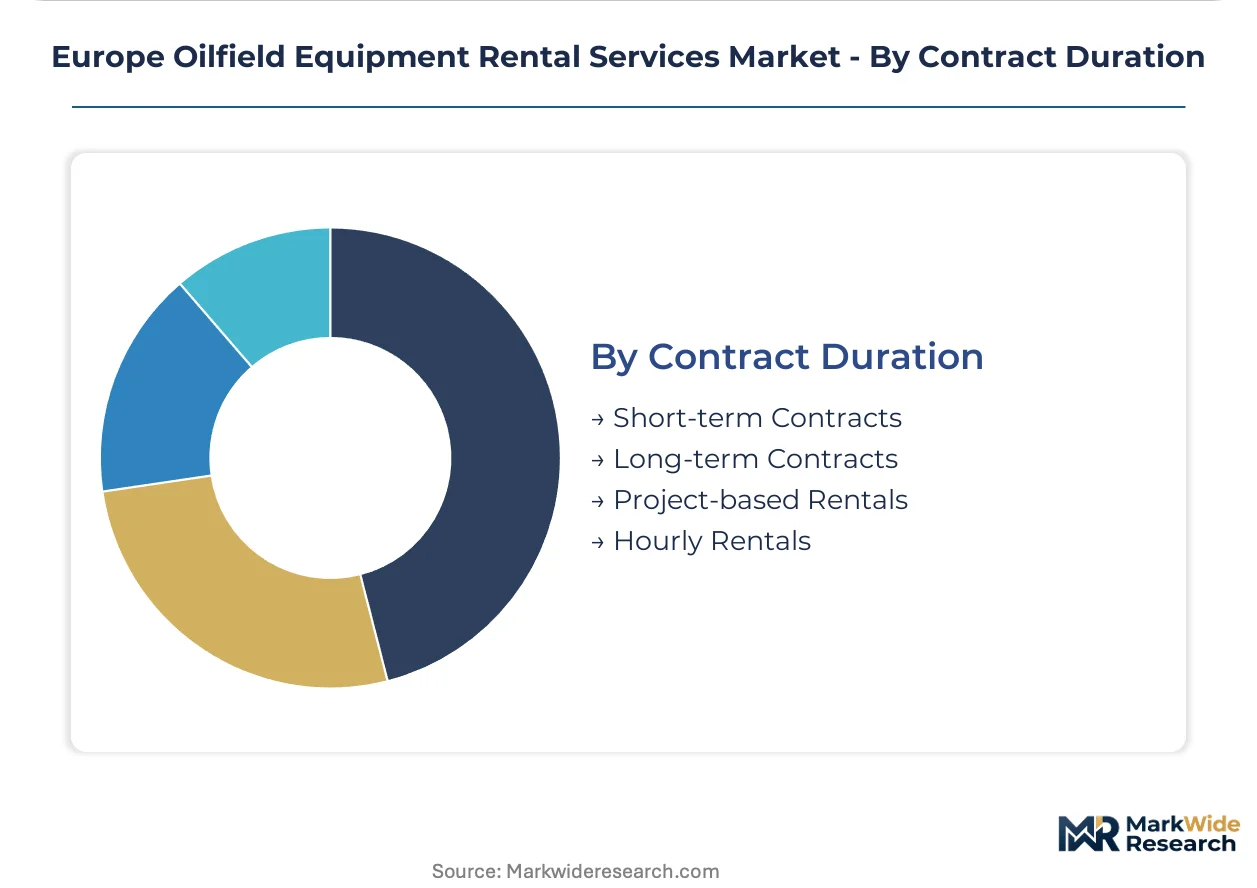
Contract Duration:
Pricing structures and working capital requirements shift dramatically across commitment horizons, with performance guarantees displacing pure day-rate mechanisms in longer-term arrangements.
- Short-term Contracts:Spot-market rentals for unplanned workovers and exploration spudding carry weather-window risk and mobilization cost uncertainty.
- Long-term Contracts:Multi-year framework agreements with Norwegian national oil companies embed digital performance dashboards determining renewal eligibility.
- Project-based Rentals:Field development-specific packages with guaranteed-availability clauses concentrate procurement authority with drilling superintendents rather than traditional supply chain functions.
- Hourly Rentals:Supplementary equipment provision for maintenance windows and regulatory inspection support.
Project-based Rentals capture the deepest operational integration; Long-term Contracts are gaining share fastest as operators seek CSRD-aligned Scope 3 transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equinor-led developments on Norway's continental shelf concentrate regional rental demand, while UK and Dutch North Sea operators defer capital purchases amid exploration budget constraints. F-Gas Regulation compliance costs and CSRD disclosure mandates are reshaping fleet procurement patterns across European offshore basins.
Norway
Barents Sea field developments and mature North Sea block workovers sustain demand for flexible-term pressure pumping packages. The Norwegian Petroleum Directorate enforces strict blowout preventer certification cycles through DNV standards. Stavanger anchors the regional service hub infrastructure, with rental providers clustering around Equinor's supplier framework agreements.
United Kingdom
Capital discipline among North Sea operators compresses equipment ownership cycles, favoring rental models for subsea well control systems. The UK North Sea Transition Authority aligns decommissioning timelines with emissions reduction mandates. Aberdeen concentrates specialized maintenance capabilities and Lloyd's Register inspection queues for premium pressure control equipment.
Netherlands
Offshore electrification initiatives in Dutch North Sea blocks drive demand for battery-hybrid power module rentals. The Netherlands Enterprise Agency coordinates offshore wind-oilfield convergence projects with dual-use infrastructure requirements. Rotterdam serves as the primary logistics node for cross-border equipment mobilization into German and Danish sectors.
Germany
Onshore shale exploration restrictions limit rental volumes, though North Sea service support functions concentrate in Hamburg and Bremen port clusters. The Federal Maritime and Hydrographic Agency enforces strict environmental operating envelopes for offshore equipment transit. Lower Saxony hosts specialized fabricator relationships for pressure pump component sourcing.
Europe Oilfield Equipment Rental Services Market Competitive Landscape
US-based integrated service companies anchor the premium technology tier; European and offshore drilling specialists hold position in asset-heavy categories. Market structure tilts toward consolidation among full-service providers with digital integration capabilities, while specialized lessors compete on regional responsiveness. Two strategic archetypes dominate: integrated technology portfolios bundling equipment with maintenance contracts, and pure-play rental fleets optimized for rapid mobilization. Competitive moves concentrate on dual-fuel fleet acquisitions and predictive maintenance service layering.
Within the integrated technology tier, Baker Hughes Co and Schlumberger NV exemplify providers combining digital drilling solutions with long-term equipment provision. Weatherford International plc occupies a position among specialized well construction rental tool providers sustaining presence through regional service hubs. These three companies represent contrasting approaches to the regulatory compliance and performance-based contracting shifts reshaping Norwegian and UK continental shelf procurement.
| Leading Market Players |
|---|
| Baker Hughes Co |
| Seadrill Ord Shs |
| TechnipFMC PLC |
| Noble Corporation PLC |
| Valaris Ltd |
| Weatherford International plc |
| Transocean LTD |
| Halliburton Company |
| Schlumberger NV |
| Others |
Supply & Pricing Matrix
Chromium-molybdenum steel price volatility cascades through European oilfield equipment rental tiers, compressing margins on drill pipe inventories while amplifying rate premiums for F-Gas-compliant blowout preventer packages in Norwegian and UK North Sea tenders.
Pricing Analysis
Volume concentrates in onshore automated drilling rigs across Romanian and UK land basins, while margin pools shift toward offshore well control equipment where F-Gas Regulation compliance costs stratify rate structures. Premium-mid-economy pricing differentiation separates battery-hybrid power modules from legacy diesel-hydraulic systems, with certification grade through DNV and Lloyd's Register acting as the primary price lever. Cost compression in standard-tier pressure pumping rentals is intensifying because exploration companies defer capital purchases amid reservoir uncertainty. Production companies with Equinor framework agreements exhibit the lowest price sensitivity, while spot-market exploration contractors in UK frontier blocks face the highest.
Supply Chain Analysis
Norwegian local-content mandates through the Petroleum Activities Act reshape sourcing patterns, requiring rental providers to maintain Stavanger-based service hubs and domestic fabrication relationships for pressure control equipment. Manufacturing clusters in the United States, Scotland, and Norway dominate premium blowout preventer and subsea wellhead production. Raw material dependencies rest on chromium-molybdenum steel alloys, high-pressure seals, and specialized electronics for IoT-enabled condition monitoring. Single-source vulnerability concentrates in Aberdeen and Houston for DNV-certified fabricators. Distribution runs through Rotterdam port clusters for cross-border EU mobilization into Dutch, German, and Danish sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-hybrid power modules are displacing diesel-hydraulic systems across North Sea rental fleets, creating a technology-transition window where capital allocation separates consolidators from stranded-asset holders.
For Market Incumbents: Deepen predictive maintenance service layering through IoT telemetry integration to anchor Equinor framework renewals and defend against digital-native entrants. Prioritize backward integration into dual-fuel power module acquisitions in Norwegian sectors to absorb stranded asset risk from F-Gas Regulation phase-down timelines. Fortify regional hub infrastructure around Stavanger and Aberdeen to compress mobilization costs for project-based rental contracts. For New Entrants and Emerging Players: The premium-economy price-point gap in Romanian onshore automated drilling rigs creates first-mover potential for flexible-term lessors establishing Carpathian basin hubs. Target underpenetrated mature basin operators lacking modern rental infrastructure. Pursue meterage-based contract structures with exploration companies in UK frontier blocks to bypass incumbent maintenance contract lock-in. For Investors and Strategic Acquirers: Distressed-cycle entries favor asset-heavy rental fleets with DNV-certified blowout preventer inventories in Norwegian waters during BOP recertification bottlenecks. Long-term viability hinges on electrification-ready equipment chains aligned with CSRD Scope 3 disclosure mandates. Watch Lloyd's Register inspection queue lengths as the inflection signal for rental asset utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Fleet Acquisition | Battery-hybrid power modules capture premium rates under F-Gas Regulation mandates in Norwegian blocks. |
| Predictive Maintenance Service Layering | IoT-enabled condition monitoring reduces unplanned downtime penalties in Equinor framework agreements. |
| Regional Hub Consolidation | Stavanger and Aberdeen service clusters compress mobilization costs for UK and Dutch North Sea campaigns. |
| CSRD-Aligned Equipment Certification | Low-carbon equipment chains advantage rental providers over owned-asset competitors in EU disclosures. |
| Subsea Electrification Convergence | Battery-hybrid modules paired with wellhead systems open rental categories in Norway's electrification-focused developments. |
Research Methodology
Document review covered EU regulatory filings including F-Gas Regulation amendments and CSRD disclosure frameworks, complemented by interviews with drilling superintendents, procurement leads at North Sea operators, rental fleet managers, DNV certification engineers, and ECHA regulatory specialists. Secondary validation drew from Lloyd's Register inspection data, Norwegian Petroleum Directorate activity reports, UK North Sea Transition Authority decommissioning timelines, and EU customs trade statistics for oilfield equipment imports. Bottom-up equipment inventory analysis triangulated against top-down contract value estimates from operator framework disclosures.
Segment-level projections across onshore and offshore service types, drilling rig and well control equipment categories, and exploration versus production end users fed into analytical framework calculations over the projection horizon. CAGRs were derived from equipment replacement cycle modeling tied to F-Gas Regulation phase-down targets and Norwegian continental shelf development timelines. Forecast inputs incorporated chromium-molybdenum steel price indices, DNV inspection queue durations, and Equinor supplier framework renewal patterns.
Inputs from Norwegian Petroleum Directorate and UK North Sea Transition Authority databases were available through the study window; gaps in real-time contract pricing transparency introduce uncertainty bands around rental rate forecasts. Forecasts reflect assumptions regarding regulatory compliance timelines and exploration budget commitments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Oil and Gas Electric Submersible Pump Market
Oil & Gas
Romania Oil and Gas Market
Oil & Gas
LAMEA Oilfield Auxiliary Rental Equipment Market
Oil & Gas
United Arab Emirates Oil and Gas Downstream Market
Oil & Gas
Canada Oil and Gas Market
Oil & Gas
Japan LNG Bunkering Market
Oil & Gas
Mud Mixers Market
Oil & Gas
Digital Oilfield Market
Oil & Gas
Middle-East and Africa Pigging Services Market
Oil & Gas
Kazakhstan Oil and Gas Market
Oil & Gas
Modular Gas Processing Plants Market
Oil & Gas
Oil and Gas Corrosion Protection Market
Oil & Gas
Global Deep-Well Disposal Services Market
Oil & Gas
Thailand Oil and Gas Upstream Market
Oil & Gas
Asia-Pacific Oil Country Tubular Goods Market
Oil & Gas
Romania Oil and Gas Upstream Market