
 United States Onshore Drilling Fluid Market | 2026-2036
United States Onshore Drilling Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
United States Onshore Drilling Fluid Market Analytics
Synthetic base fluids is expanding its share of the United States onshore drilling fluid market as operators seek thermal stability above 400°F in deep horizontal laterals. Baker Hughes Company leverages its integrated chemical supply chain to deliver customized synthetic packages across the Permian and Bakken. Schlumberger Limited anchors its position through real-time downhole fluid monitoring tied to automated mud weight adjustments. Halliburton Energy Services, Inc. competes on manufacturing scale, operating regional blending plants that reduce logistics costs for independent operators in the Mid-Continent.
United States onshore drilling fluids are engineered liquid and slurry systems composed of base fluids, weighting agents, viscosifiers, and chemical additives designed to maintain hydrostatic pressure, transport cuttings, and stabilize wellbore walls during rotary drilling operations; water-based systems typically operate at densities of 8.5–19.0 ppg and dominate shallow to intermediate vertical drilling, while oil-based and synthetic variants tolerate higher temperatures and reactive shale formations. Water-based fluids occupy the largest volume share but face margin compression from environmental compliance costs, whereas synthetic fluids command premium pricing in extended-reach laterals exceeding 15,000 feet. The viscosity control technology segment leads R&D investment as operators push drilling efficiency metrics, and filtration-focused additive packages represent the fastest-growing technology category due to tighter shale reservoir compatibility requirements.
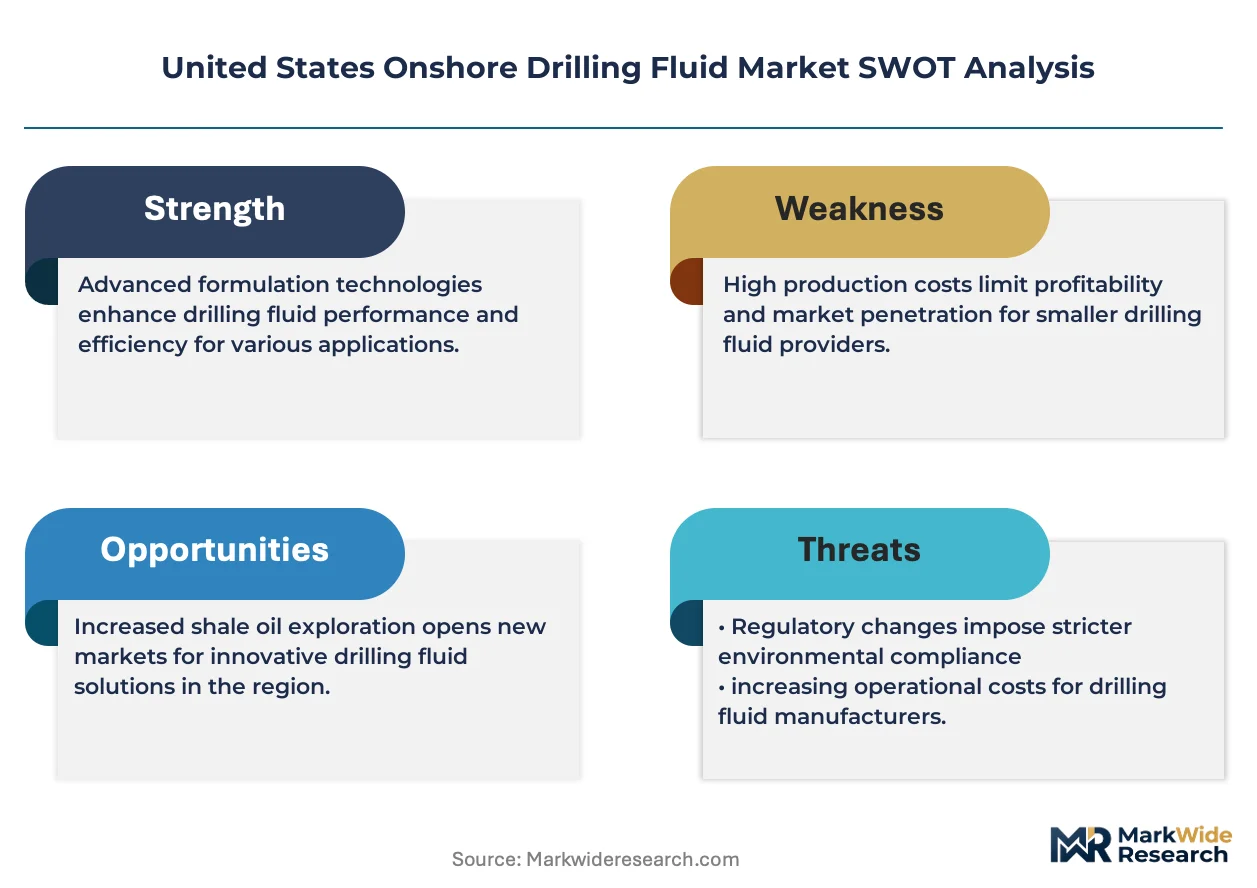
The EPA enforces drilling waste discharge limits under the Clean Water Act and Underground Injection Control program, compelling operators toward closed-loop systems and synthetic alternatives with lower toxicity profiles. OSHA mandates govern worker exposure to hydrocarbon vapors during mud mixing operations, shaping facility design and automation adoption at onshore rig sites. State regulators in Texas and New Mexico layer additional pit closure and groundwater protection rules that vary across county lines. Stakeholders must monitor the trajectory of federal methane rules and state-level produced water reuse policies, as both will determine whether water-based or synthetic fluid platforms deliver lower total compliance cost over the next development cycle.
Market Dynamics
Horizontal well complexity in the Permian Basin and Bakken formation is forcing rapid product reformulation cycles as operators push lateral lengths beyond 15,000 feet and bottom-hole temperatures exceed 400°F. This thermal and mechanical stress profile favors synthetic base fluid systems that maintain viscosity stability under extreme downhole conditions.
Growth Catalysts
- EPA Underground Injection Control program:The updated Class II well standards are accelerating closed-loop drilling waste adoption, which consumes higher volumes of advanced synthetic formulations that meet lower toxicity discharge thresholds.
- Extended-reach laterals:Permian Basin operators are deploying multi-mile horizontals that require synthetic fluids with superior lubricity and thermal stability compared to conventional water-based alternatives.
- Texas Railroad Commission pit closure rules:Stricter groundwater protection mandates in West Texas counties are eliminating surface impoundment options and driving demand for zero-discharge fluid systems.
Market Restraints
- Base fluid cost volatility:Synthetic ester and olefin feedstock prices track crude oil and natural gas liquids, compressing margins when commodity benchmarks spike above operator budget forecasts.
- Supply concentration in Gulf Coast:Specialty chemical additive manufacturing clusters heavily around Houston and Corpus Christi, creating hurricane-related disruption exposure for national distribution networks.
- Water-based substitution ceiling:Shallow vertical drilling in the Mid-Continent continues utilizing lower-cost water-based systems, limiting synthetic fluid penetration in price-sensitive independent operator segments.
Strategic Opportunities
- New Mexico Delaware Basin expansion:Lea and Eddy County drilling permits are outpacing Texas permit growth, creating greenfield demand for regional blending capacity and localized technical service presence.
- Produced water reuse integration:Texas Commission on Environmental Quality rulemaking is enabling treated flowback incorporation into water-based mud formulations, opening hybrid fluid development pathways.
- Real-time downhole monitoring convergence:Automated density adjustment systems are converging with synthetic fluid chemistry to enable continuous optimization without surface circulation stops.
Industry Challenges
- Formulation chemist talent scarcity:The specialized expertise required for high-pressure high-temperature synthetic design is concentrated among retiring veterans, constraining R&D velocity for mid-tier suppliers.
- OSHA hydrocarbon vapor compliance:Automated mud mixing system retrofits demand capital deployment that independent operators defer, creating workforce exposure liability and inspection penalty risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Onshore Drilling Fluid Market |
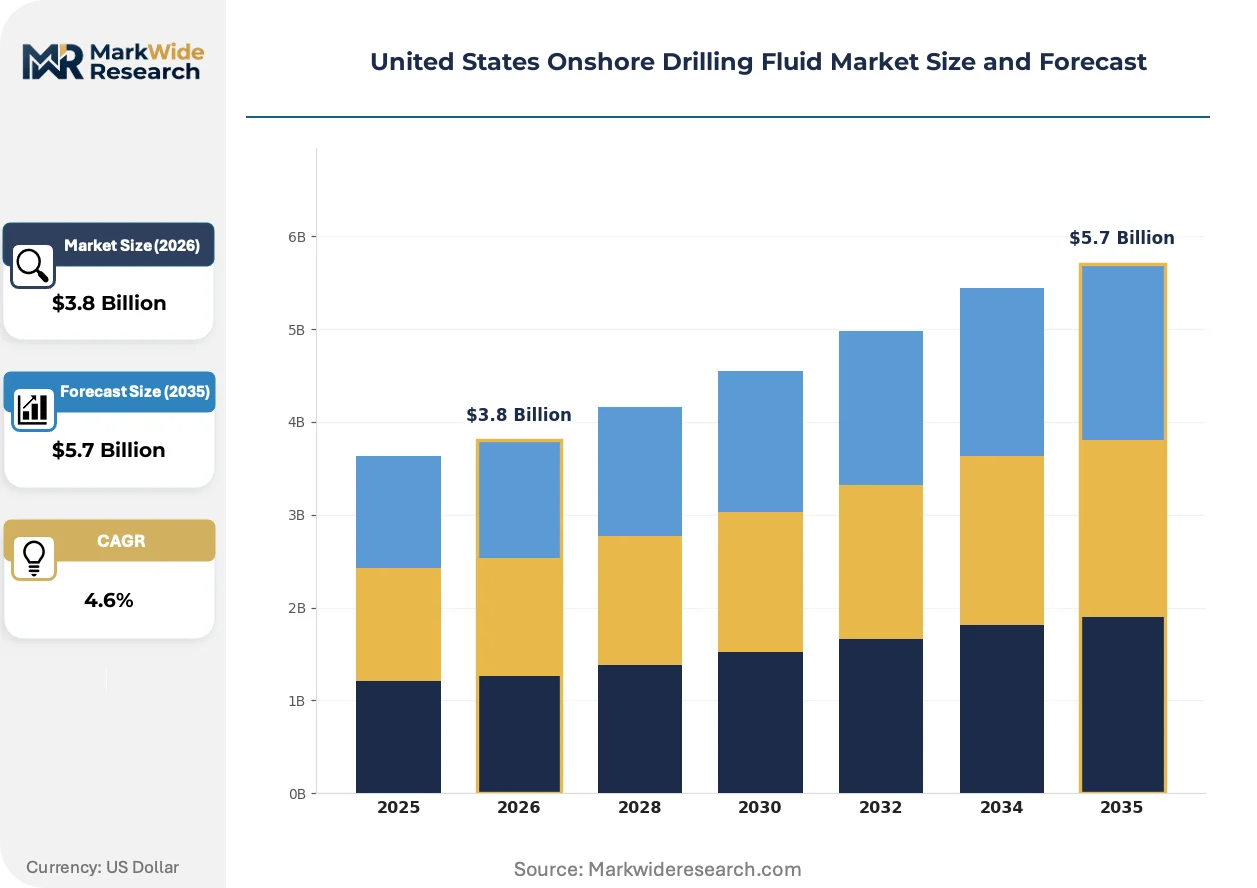
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Oil-Based, Synthetic, Compressible Application: Exploration, Production, Workover, Well Abandonment End User: Independent Operators, National Oil Companies, Service Providers, Equipment Manufacturers Technology: Viscosity Control, Density Adjusters, Corrosion Inhibitors, Filtration |
| Companies Covered | Horizon Mud Company Inc., AES Drilling Fluids, Medserv PLC, Baker Hughes Company, Schlumberger Limited, Halliburton Energy Services, Inc., Newpark Resources Inc., Weatherford International plc, CES Energy Solutions Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Onshore Drilling Fluid Market Evolving Landscape
Synthetic base fluid chemistry is undergoing rapid evolution as thermal stability requirements outpace legacy formulation capabilities. Three interconnected developments are restructuring competitive positioning across the value chain.
Nanoparticle-enhanced weighting agents are converging with synthetic carrier fluids to deliver density maintenance above 18 ppg without barite sag in high-angle laterals. Bakken operators are piloting these systems in 20,000-foot measured-depth wells where conventional barite settles and causes stuck pipe. The structural consequence is compressing the performance gap between oil-based and synthetic systems while avoiding EPA toxicity classification issues.
OSHA's updated permissible exposure limits for diesel particulate matter are forcing rig-site ventilation upgrades and mud mixing automation across Texas and New Mexico operations. The industrial consequence is capital flight from manual mixing infrastructure toward enclosed skidded systems. Smaller independent operators in the Anadarko Basin are most affected, responding through contract drilling arrangements that transfer compliance burden to service companies.
Operator procurement is consolidating fluid supply under integrated service contracts that bundle chemicals, engineering, and waste management. The discrete product purchase model is yielding to performance-based agreements where payment ties to rate of penetration and non-productive time reduction. This shift is most visible among Permian Basin supermajors, which now specify synthetic fluid packages through single-source five-year frameworks rather than spot market purchasing.
United States Onshore Drilling Fluid Market Segmentation
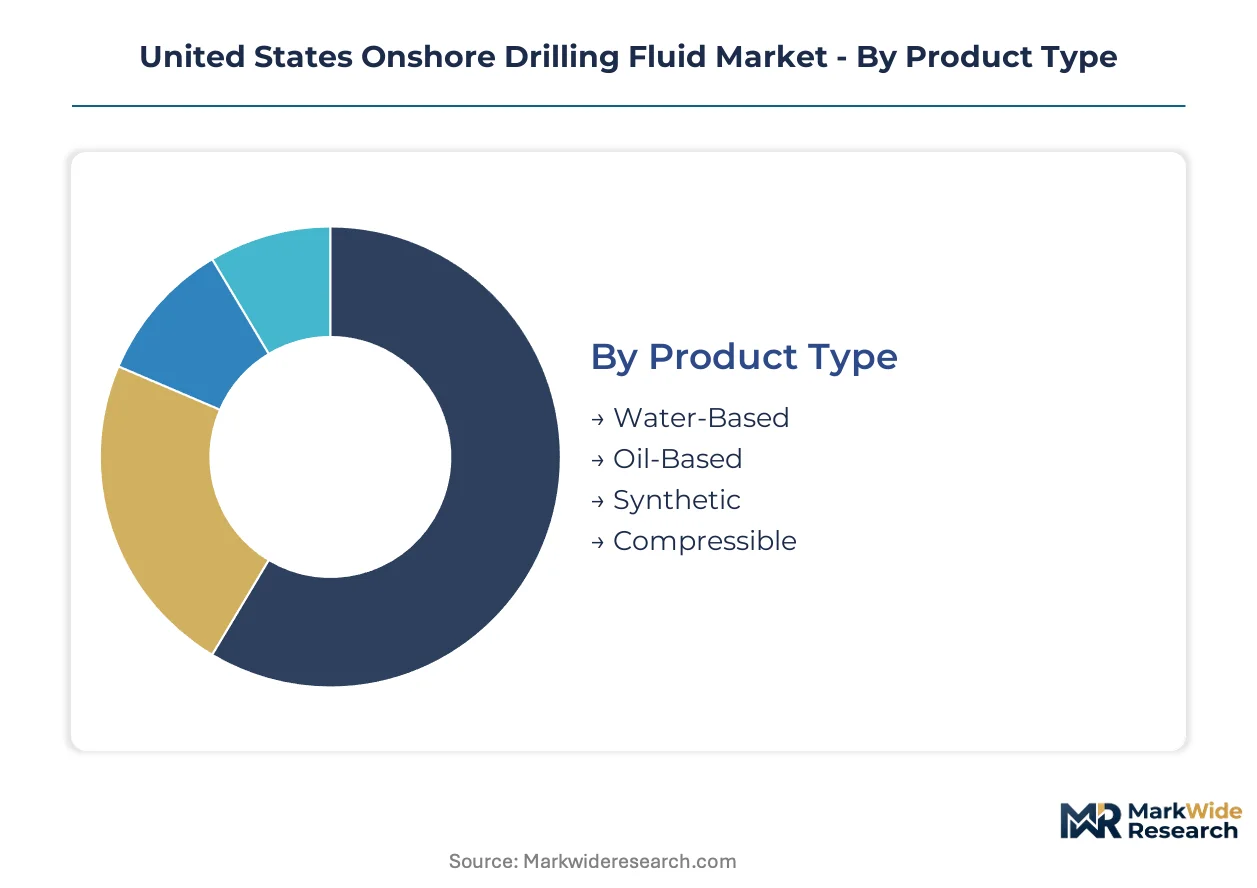
Drilling fluid selection in the United States onshore market hinges on well architecture complexity and regulatory exposure. Operators balance thermal performance against disposal economics across four distinct product platforms, while application stage and end-user scale dictate procurement patterns and service intensity.
Product Type:
Standalone fluid systems dominate high-complexity horizontal drilling, while embedded additive packages serve routine vertical workovers. Integration depth varies sharply across base chemistry families.
- Water-Based:Formulations blend fresh or brine water with bentonite clay, lignosulfonates, and cellulose polymers to achieve densities up to 19.0 ppg. Independent operators in the Mid-Continent deploy these systems for shallow vertical drilling where thermal stress remains below 250°F and disposal costs favor aqueous waste streams.
- Synthetic:Ester and olefin-based carriers deliver thermal stability above 400°F with lower EPA toxicity classification than diesel-based alternatives. Permian Basin laterals exceeding 15,000 feet require these fluids to maintain viscosity integrity under extreme bottom-hole conditions.
- Oil-Based:Diesel or mineral oil carriers provide superior shale inhibition through continuous phase chemistry. EPA discharge restrictions and OSHA vapor exposure limits constrain deployment to remote sites with closed-loop waste handling.
- Compressible:Nitrogen or air-based systems reduce hydrostatic head in underbalanced drilling applications. Wyoming coalbed methane operators utilize these fluids to minimize formation damage in low-pressure reservoirs.
Water-Based leads volumes today; Synthetic is gaining share fastest.
Application:
Cost tier stratification separates capital-intensive exploration from routine maintenance work. Higher-margin stages command premium fluid chemistry and dedicated engineering support.
- Exploration:Wildcat drilling in frontier basins demands high-performance synthetic systems with real-time density monitoring. Delaware Basin operators allocate disproportionate fluid budgets to exploratory horizontals where formation uncertainty elevates non-productive time risk.
- Production:Infill drilling on proven acreage utilizes standardized water-based formulations with regional barite sourcing. Bakken development programs achieve scale economies through repeatable fluid specifications across multi-well pads.
- Workover:Well intervention operations require lightweight, low-solids fluids compatible with existing completion hardware. Texas Railroad Commission well integrity rules shape brine selection for plugging and abandonment preparation.
- Well Abandonment:Permanent plug-and-abandon procedures use cement slurries and weighted kill fluids to isolate productive zones. EPA Underground Injection Control Class II standards mandate specific density and chemical compatibility thresholds.
Production commands the largest expenditure base; Exploration delivers the steepest per-well fluid intensity.
End User:
Customer scale determines procurement sophistication, from spot market purchasing to integrated performance contracts. Volume concentration varies across operator ownership structures.
- Independent Operators:Privately held E&P companies in the Permian and Anadarko basins prioritize cost containment through regional blending plant relationships. These buyers exhibit price sensitivity that limits synthetic fluid penetration outside high-temperature laterals.
- National Oil Companies:State-affiliated producers maintain captive supply chains with multi-year framework agreements. Their procurement specifications increasingly embed emissions and toxicity criteria alongside technical performance metrics.
- Service Providers:Contract drilling companies bundle fluid supply with rig operations, transferring formulation risk from operators. This segment consolidates purchasing power through master service agreements covering hundreds of annual wells.
- Equipment Manufacturers:Downhole tool suppliers specify compatible fluid chemistries to protect directional drilling and logging-while-drilling assets. Their technical input influences operator fluid selection for extended-reach applications.
Independent Operators consume the greatest aggregate volume; Service Providers are consolidating procurement authority fastest.
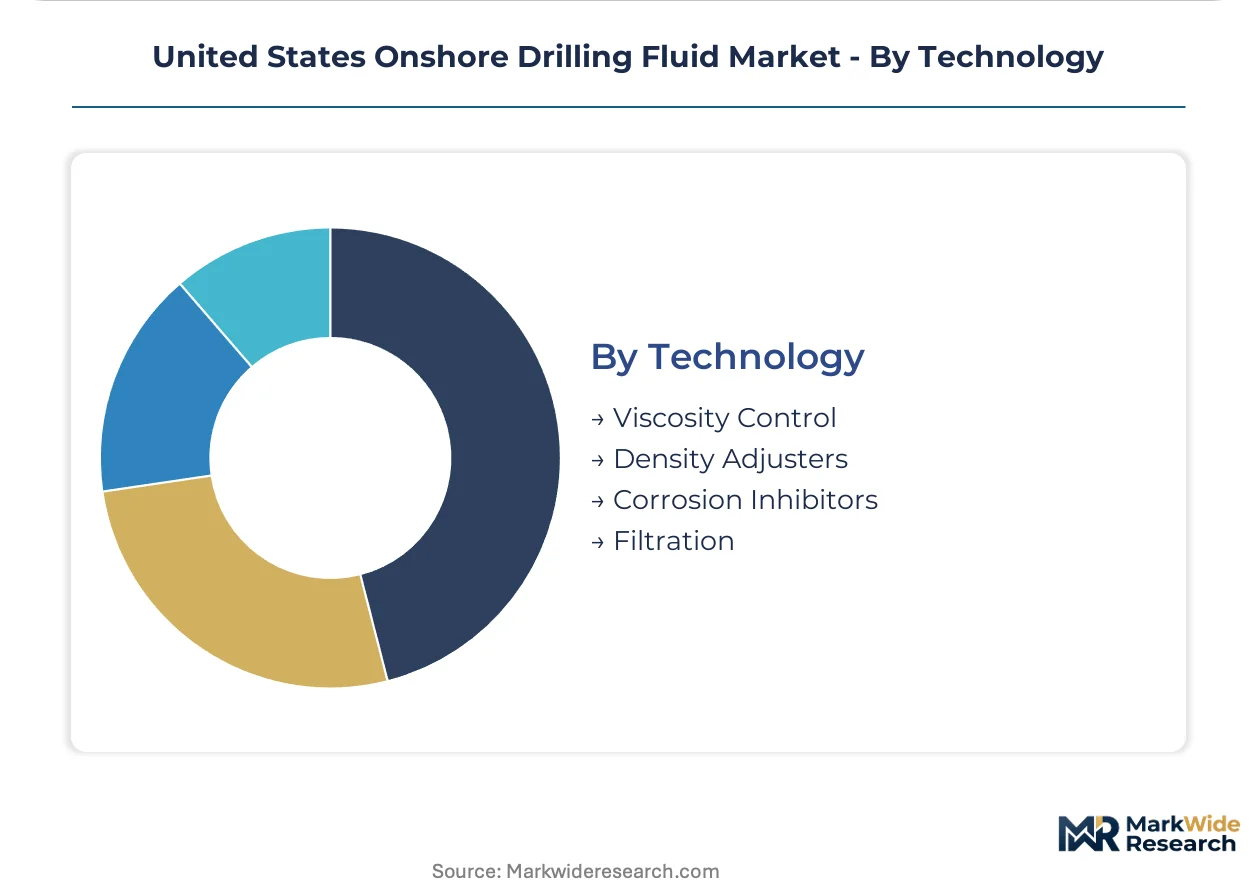
Technology:
Supply concentration in Gulf Coast chemical manufacturing clusters shapes additive availability and pricing. Technology maturity spans decades-old commodity chemistry to emerging nanomaterial platforms.
- Viscosity Control:Xanthan gum and cellulose derivatives maintain rheological properties across temperature and shear variations. Bakken high-angle laterals demand these additives to prevent barite sag and equivalent circulating density spikes.
- Filtration:Bridging agents and fluid-loss polymers minimize formation damage by sealing permeable zones. Tight shale reservoir compatibility requirements are accelerating R&D investment in nanoparticle-enhanced filtration packages.
- Density Adjusters:Barite, hematite, and calcium carbonate weighting agents achieve target mud weights from 8.5 to 22.0 ppg. Hurricane disruption risk at Houston-area processing facilities creates periodic supply constraints for high-specific-gravity formulations.
- Corrosion Inhibitors:Amine and phosphate ester compounds protect drill string and casing from acid gas attack. Sour gas fields in East Texas and Oklahoma require continuous inhibitor treatment to meet NACE metallurgical standards.
Viscosity Control anchors current technology spending; Filtration exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin spanning West Texas and southeastern New Mexico anchors United States onshore drilling fluid consumption, with Delaware Basin sub-basins driving synthetic formulation demand as lateral lengths extend past 15,000 feet.
West Texas
Reeves, Loving, and Midland counties host the most intensive horizontal drilling activity in the nation. Texas Railroad Commission pit closure rules have eliminated surface impoundment options across 12 West Texas counties since 2023. Regional blending plants in Odessa and Midland supply synthetic fluid packages to operators drilling multi-mile laterals where bottom-hole temperatures exceed 400°F.
Southeastern New Mexico
Lea and Eddy counties are outpacing Texas permit growth for Delaware Basin development. New Mexico Oil Conservation Division groundwater protection mandates require closed-loop systems on all new drilling permits issued after January 2024. Hobbs and Carlsbad serve as logistics hubs where service companies pre-position synthetic base fluid inventories to reduce trucking distances to remote pad sites.
North Dakota Bakken
Williams, McKenzie, and Dunn counties sustain demand for high-temperature synthetic systems in 20,000-foot measured-depth wells. North Dakota Industrial Commission flare capture requirements indirectly favor drilling efficiency investments that reduce non-productive time. Williston Basin service yards concentrate blending capacity near Watford City to support extended-reach laterals where barite sag prevention drives additive selection.
Oklahoma Mid-Continent
Anadarko Basin and STACK play operators in Canadian, Kingfisher, and Blaine counties maintain price-sensitive procurement patterns favoring water-based systems for shallow vertical drilling. Oklahoma Corporation Commission induced seismicity protocols have shifted some activity to deeper formations where synthetic fluids gain relevance. Oklahoma City hosts regional distribution centers supplying independent operators with cost-optimized formulations.
Rocky Mountain Region
Wyoming's Powder River Basin and Colorado's Denver-Julesburg Basin utilize compressible fluids for coalbed methane and underbalanced drilling applications. Wyoming Oil and Gas Conservation Commission well integrity rules shape brine selection for plugging and abandonment preparation. Casper and Denver serve as secondary logistics nodes with limited synthetic blending capacity compared to Permian infrastructure.
United States Onshore Drilling Fluid Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and logistics reach, creating a tiered structure where integrated service providers hold premium positions and independent blenders compete on price. Baker Hughes Company, Schlumberger Limited, and Halliburton Energy Services, Inc. anchor the top tier through captive chemical manufacturing and real-time monitoring integration. Mid-tier regional suppliers concentrate around Houston and Corpus Christi chemical clusters. Competitive moves center on automated mud mixing system deployment and multi-year performance-based contracting.
Within the integrated service provider tier, Baker Hughes Company and Schlumberger Limited exemplify the convergence of synthetic fluid chemistry with downhole telemetry. Halliburton Energy Services, Inc. occupies a position emphasizing manufacturing scale and regional blending density. Among independent specialists, Newpark Resources Inc. and CES Energy Solutions Corp. represent the North American-focused archetype competing through logistics proximity and operator relationship depth. Weatherford International plc sits within the international diversified tier where drilling fluids form one element of broader well construction portfolios.
| Leading Market Players |
|---|
| Horizon Mud Company Inc. |
| AES Drilling Fluids |
| Medserv PLC |
| Baker Hughes Company |
| Schlumberger Limited |
| Halliburton Energy Services, Inc. |
| Newpark Resources Inc. |
| Weatherford International plc |
| CES Energy Solutions Corp. |
| Others |
Value Network & Pricing Analysis
Operator consolidation around multi-year performance contracts is compressing spot-market premiums and forcing suppliers to absorb feedstock volatility through inventory pre-positioning. This procurement shift elevates contract manufacturing scale as the decisive cost-control mechanism.
Pricing Analysis
Synthetic ester and olefin feedstock costs pass through directly to fluid pricing, with Gulf Coast chemical indices serving as the reference benchmark. Three-tier pricing structure across premium synthetic, standard water-based, and economy brine systems differentiates by thermal performance ceiling and EPA toxicity classification. Cost compression in water-based tiers is intensifying because independent operators in the Mid-Continent prioritize disposal economics over downhole performance. Price sensitivity concentrates among independent operators drilling shallow vertical wells, while Permian Basin supermajors exhibit inelastic demand for high-temperature synthetic formulations.
Supply Chain Analysis
Domestic-content preferences embedded in Texas Railroad Commission procurement guidelines and New Mexico Oil Conservation Division contractor qualification standards are redirecting additive sourcing toward US-based chemical manufacturing. Supply draws from Texas, Louisiana, and Oklahoma petrochemical corridors, with specialty ester production concentrated around Houston and Corpus Christi. Raw material dependencies center on natural gas liquids for olefin feedstocks, barite ore from Nevada and China, and xanthan gum fermentation capacity. Single-source vulnerability exists for high-purity barite processing after hurricane disruptions. Distribution runs through regional blending plants in Odessa, Midland, and Hobbs serving pad-specific just-in-time delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Underground Injection Control Class II well standards and state-level pit closure mandates continuously elevate formulation complexity and compliance costs.
For Market Incumbents: Extend synthetic fluid chemistry leadership through captive manufacturing of ester base stocks in Texas Gulf Coast facilities, reducing exposure to feedstock price spikes. Consolidate regional blending capacity in Lea and Eddy counties to capture Delaware Basin permit growth. Defend against mid-tier price competition by embedding real-time downhole monitoring into multi-year service contracts. For New Entrants and Emerging Players: The pricing gap between premium synthetic systems and economy water-based alternatives in the Anadarko Basin creates entry space for hybrid formulations combining produced water reuse with moderate thermal stability. Target Oklahoma independent operators through contract drilling bundling arrangements that transfer compliance burden from capital-constrained buyers. Establish logistics presence in Oklahoma City distribution corridors. For Investors and Strategic Acquirers: Asymmetric upside sits with regional blending specialists possessing EPA-compliant waste handling infrastructure and established Texas Railroad Commission relationships. Long-term viability hinges on positioning for continued regulatory tightening around toxicity classification and methane containment. Acquisition candidates should demonstrate captive supply agreements with Gulf Coast chemical producers. Watch Texas Commission on Environmental Quality rulemaking on produced water reuse as the signal for hybrid fluid platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ester Feedstock Production | Captive olefin supply insulates margin compression from natural gas liquids price volatility. |
| Regional Blending Capacity Expansion | Lea County facility placement reduces trucking costs for Delaware Basin operators. |
| Closed-Loop Waste Handling Infrastructure | EPA Class II compliance enables synthetic fluid premium capture in West Texas counties. |
| Real-Time Downhole Monitoring Integration | Automated density adjustment ties payment to rate of penetration performance metrics. |
| Produced Water Reuse Formulation Development | Texas Commission on Environmental Quality rulemaking opens hybrid fluid pathways. |
Research Methodology
Multiple input streams — drilling contractor procurement directors, EPA regulatory affairs specialists, petrochemical supply planners, and independent operator engineering managers — were reconciled against secondary validation from EIA drilling statistics, Texas Railroad Commission permit databases, and SEC 10-K filings from integrated service providers. Bottom-up volume estimates from county-level rig counts and top-down spending analysis from operator capital budgets were triangulated to establish market sizing.
Historical rig efficiency trends were cross-referenced against expert panel input on lateral length extension and thermal stability requirements across the projection horizon. Segmentation modeling incorporated base fluid chemistry, well architecture complexity, end-user scale, and additive technology maturity. CAGRs were derived from operator spending intention surveys and service company capacity expansion announcements, with particular weighting applied to Permian Basin permit trajectories and synthetic fluid penetration assumptions in extended-reach laterals.
Caveats apply where EPA methane rule finalization or state-level produced water reuse policy shifts could materially shift the outlook between water-based and synthetic fluid platforms. Forecasts reflect documented assumptions regarding lateral length extension, thermal stability requirements, and regulatory enforcement intensity. A small set of named triggers — Texas Railroad Commission pit closure expansion, New Mexico groundwater protection rule amendments, and OSHA vapor exposure limit updates — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Thailand Oil and Gas Market
Oil & Gas
Oil and Gas Corrosion Protection Market
Oil & Gas
3D Printing in Oil and Gas Market
Oil & Gas
Malaysia Oil and Gas Midstream Market
Oil & Gas
Downhole Tools Market
Oil & Gas
Sucker Rod Market
Oil & Gas
Crude Oil Assay Testing Services Market
Oil & Gas
Oil and Gas Accumulators Market
Oil & Gas
Vacuum Gas Oil Market
Oil & Gas
Seismic Survey Equipment Market
Oil & Gas
South America Oil and Gas Storage Tank Market
Oil & Gas
Flexible Pipes for Oil and Gas Market
Oil & Gas
Well Stimulation Vessels Market
Oil & Gas
Algeria Oil and Gas Downstream Market
Oil & Gas
Coiled Tubing Services Market
Oil & Gas
North America Fracking Chemicals Market