
 Mexico Oil and Gas Downstream Market | 2026-2036
Mexico Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Oil and Gas Downstream Market Foresight
Industrial feedstock purchasers is rotating share toward transportation fleet operators as Mexico's freight corridors expand diesel consumption. Petróleos Mexicanos anchors national refining capacity through its six-plant network while Braskem Idesa leverages ethane feedstock access for polyethylene production. Shell México competes on retail network density along federal highway corridors, and IEnova controls critical storage terminal infrastructure at Lazaro Cardenas and Topolobampo.
Mexico oil and gas downstream operations encompass crude oil refining, petroleum product manufacturing, and petrochemical processing through catalytic cracking, hydrocracking, and coker units operating at 200,000+ barrels per day capacity per major facility. These operations yield transportation fuels, lubricants, asphalt, and chemical precursors for plastics and synthetic materials. Gasoline and diesel product types dominate volume throughput due to Mexico's vehicle fleet dependency, while jet fuel exhibits faster structural growth tied to airport hub expansion at Cancun and Mexico City. The transportation application segment leads absolute consumption, though industrial demand for petrochemical derivatives captures superior margin pools through captive ethane supply contracts.
CRE, Mexico's energy regulator, enforces fuel quality specifications and open-access storage mandates that reshape terminal investment patterns. ASEA, the environmental regulator for the hydrocarbon sector, imposes emissions standards and spill-response protocols that elevate operational compliance costs for coastal refineries. SENER's downstream planning directives determine import-export licensing frameworks that constrain private participant market entry timing. Stakeholders must monitor Pemex's coking capacity additions and CRE's third-party terminal access rulings to anticipate product flow reallocations between domestic refining and import dependence.
Market Dynamics
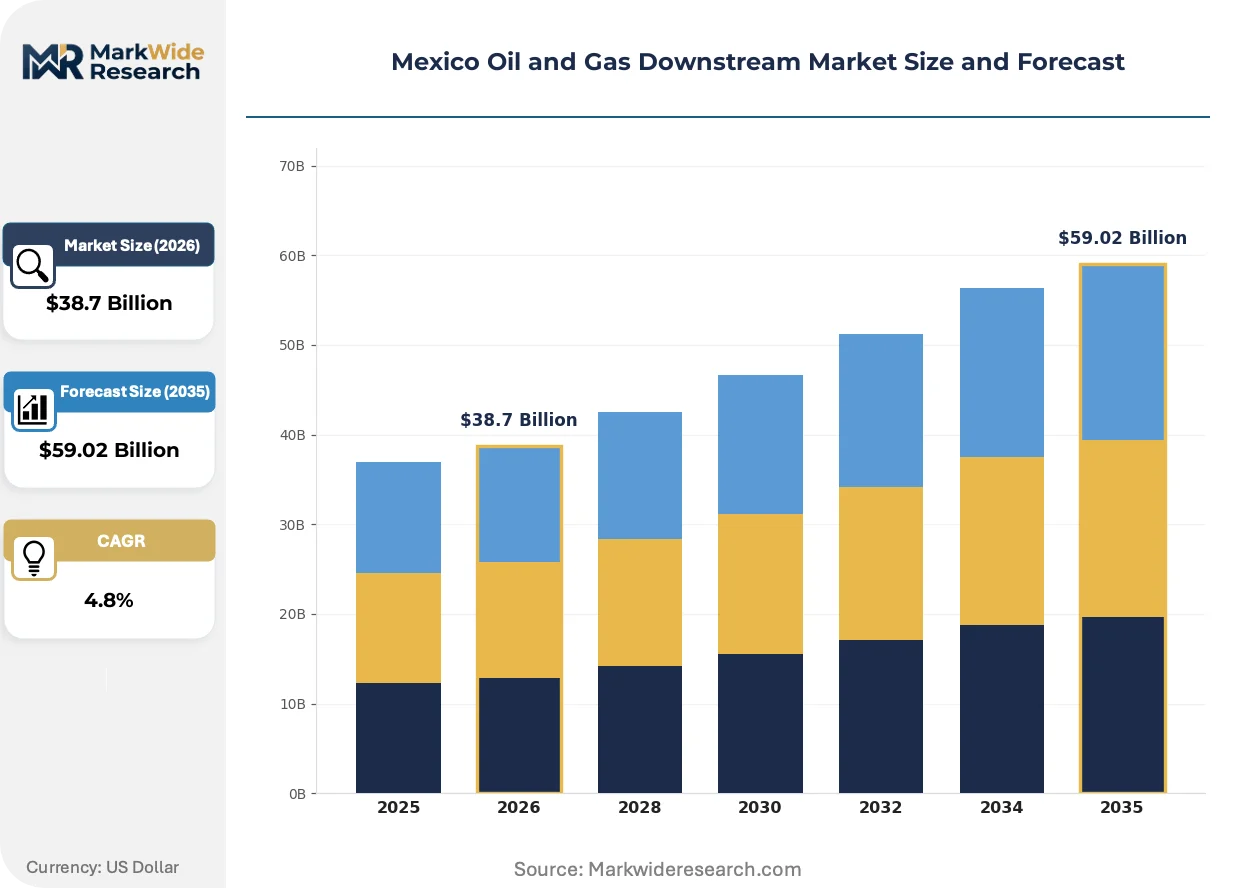
Pemex's refining modernization program under SENER directives is concentrating domestic capacity expansion around coker unit additions, reducing Mexico's structural dependence on US Gulf Coast gasoline imports while reshaping product flow patterns across the national pipeline network.
Growth Catalysts
- CRE Open-Access Mandates:The energy regulator's terminal access rulings force incumbent storage operators to grant third-party entry, expanding private participation in product distribution corridors.
- Freight Corridor Dieselization:Transportation fleet operators along federal highway networks are absorbing higher distillate volumes as cargo tonnage shifts from rail to long-haul trucking.
- Cancun Airport Hub Expansion:Jet fuel offtake is accelerating at this tourism gateway, requiring dedicated pipeline capacity from Pajaritos terminal infrastructure.
Market Restraints
- Maya Crude Price Volatility:Input cost swings for heavy sour feedstocks compress refining margins unpredictably, exposing Pemex's six-plant network to cash flow instability.
- US Gulf Coast Import Dependence:Structural supply concentration in Texas and Louisiana refineries creates vulnerability to hurricane disruptions and cross-border pipeline constraints.
- ASEA Emissions Compliance:The environmental regulator's spill-response protocol requirements elevate coastal refinery operating costs through mandated containment infrastructure.
Strategic Opportunities
- Coatzacoalcos Petrochemical Integration:Veracruz's refining corridor offers captive ethane access for polyethylene producers seeking backward integration into feedstock supply.
- Lazaro Cardenas Storage Development:IEnova-controlled terminal infrastructure at this Pacific port enables import arbitrage for West Coast product markets underserved by domestic refining.
- Industrial Cogeneration Expansion:Refinery off-gas utilization for captive power generation aligns with SENER efficiency directives while reducing grid electricity purchases.
Industry Challenges
- Coker Unit Commissioning Delays:Pemex's capacity additions face construction timeline slippage, deferring the domestic production ramp-up needed to displace import volumes.
- Specialized Maintenance Labor Scarcity:Hydrocracker and catalytic reformer technicians with heavy crude processing experience command premium wages, constraining operational flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Oil and Gas Downstream Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Kerosene, Jet Fuel Application: Transportation, Industrial, Residential, Agricultural Distribution Channel: Retail, Wholesale, Direct Sales, E-commerce End User: Consumers, Businesses, Government, Organizations |
| Companies Covered | Valero Energy México, Iconn, Petróleos Mexicanos, Monterra Energy, Oxxo Gas, Braskem Idesa, Shell México, BP México, IEnova, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Oil and Gas Downstream Market Shifts & Advancements
Digital instrumentation and advanced process control systems are penetrating Mexico's downstream facilities, enabling real-time optimization of conversion unit yields while reducing unplanned downtime across aging infrastructure.
Residue upgrading technology is decomposing the traditional light-heavy crude price arbitrage that historically favored simple refining configurations. Pemex's Tula and Salamanca complexes are retrofitting delayed coker units to process vacuum residue into higher-value transportation fuels. This capability compression is enabling domestic facilities to compete with US Gulf Coast imports on medium-sour crude slates.
ASEA's environmental discharge permits now mandate continuous emissions monitoring systems for sulfur dioxide and nitrogen oxide releases. Coastal refineries at Minatitlan and Salina Cruz face accelerated compliance timelines, forcing capital allocation toward scrubber installations. The industrial consequence concentrates on coker and fluid catalytic cracking units, where operators are retrofitting wet gas scrubbers to avoid production curtailments.
Fleet operators in Mexico's freight corridors are consolidating fuel purchasing through direct terminal offtake agreements, bypassing traditional retail network intermediaries. Large trucking cooperatives now contract directly with storage terminal operators at Puebla and Guadalajara hubs for diesel volumes. This channel disintermediation is most visible along the Mexico City-Queretaro-Leon industrial corridor, where transport demand concentrates.
Mexico Oil and Gas Downstream Market Segmentation
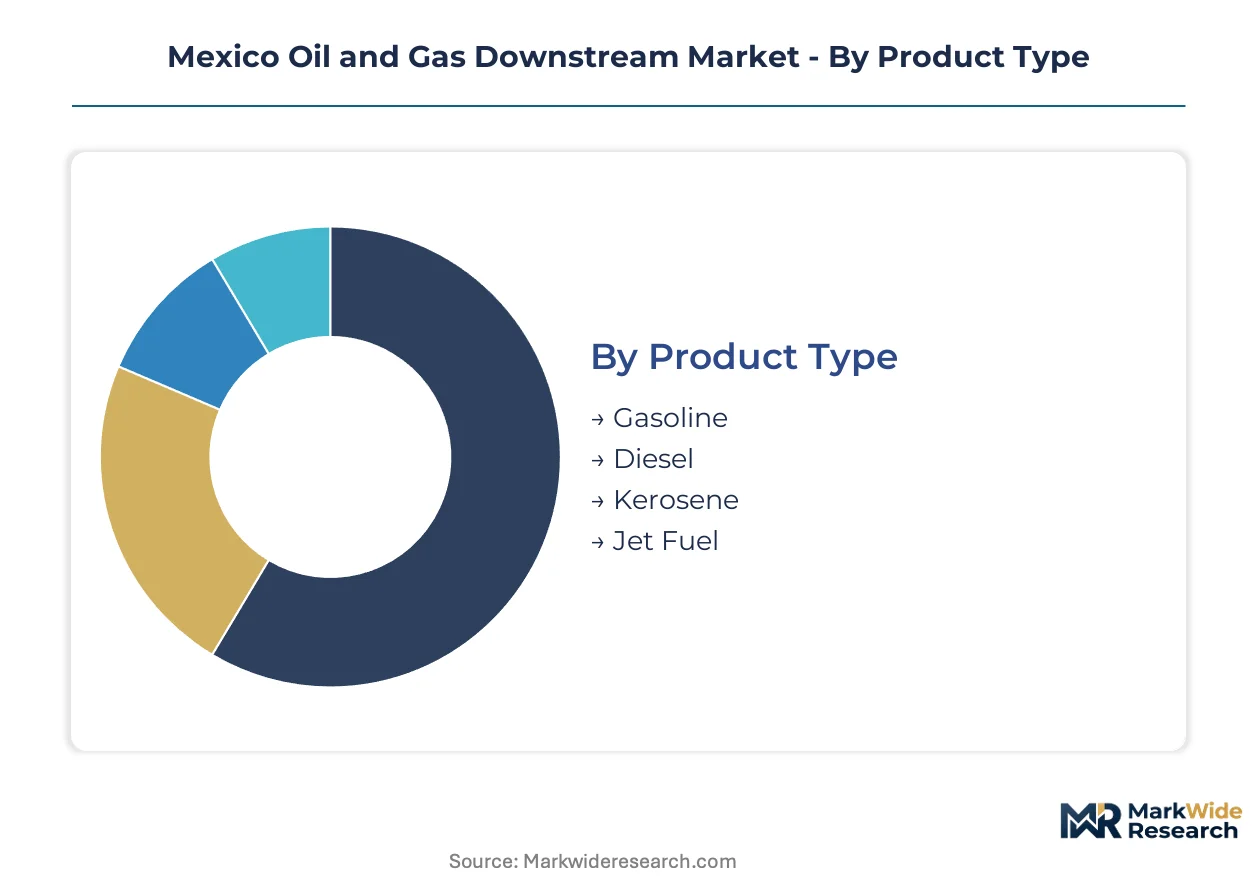
Downstream segmentation in Mexico reveals how product flows split between domestic consumption corridors and export-adjacent logistics. Category boundaries determine where Pemex retains pricing power versus where private terminal operators capture margin.
Product Type:
Domestic demand concentrates on light distillates for vehicle fleets, while heavier fractions serve industrial buyers in Veracruz's petrochemical corridor.
- Gasoline:Reformulated and premium grades dominate Pemex's six-plant output, with octane specifications tightening under CRE quality mandates. Private importers from US Gulf Coast terminals supply volume shortfalls in Mexico City and Guadalajara metropolitan zones, exposing the segment to cross-border pipeline constraints.
- Diesel:Ultra-low sulfur formulations absorb the bulk of freight corridor expansion along federal highways connecting industrial hubs. Tula and Salamanca refineries prioritize diesel yield from coker retrofits, displacing historical import dependence for long-haul fleet operators.
- Kerosene:Illuminating and heating grades serve rural residential markets with declining per-capita consumption as LPG substitutes penetrate.
- Jet Fuel:Jet A-1 specifications for commercial aviation concentrate demand at Cancun and Mexico City airport hubs, requiring dedicated pipeline capacity from coastal terminals.
Gasoline holds the largest share; momentum sits with diesel as freight dieselization accelerates.
Application:
Cost-tier differentiation separates high-volume transportation buyers from premium-margin industrial accounts seeking petrochemical derivatives.
- Transportation:Fleet operators consume gasoline and diesel through direct terminal offtake agreements, bypassing retail intermediaries. Federal highway corridor expansion concentrates volume in the Mexico City-Queretaro-Leon triangle, where trucking cooperatives negotiate bulk pricing.
- Industrial:Petrochemical feedstock buyers in Coatzacoalcos process heavier crude slates into polyethylene and synthetic materials. Captive ethane supply contracts from Pemex infrastructure anchor margin capture for integrated producers.
- Residential:LPG and kerosene serve cooking and heating needs with seasonal demand spikes in highland states.
- Agricultural:Diesel powers irrigation pumps and harvesting equipment across Sinaloa and Veracruz growing regions with weather-dependent consumption patterns.
Transportation commands absolute volume; industrial applications capture superior margins through backward integration into feedstock supply.
Distribution Channel:
Customer-type stratification determines whether buyers access product through branded retail networks or unbranded wholesale terminals.
- Retail:Shell México and franchise operators maintain network density along federal highways, competing on convenience and payment infrastructure for consumer gasoline purchases.
- Wholesale:Storage terminal operators at Puebla and Guadalajara hubs supply independent distributors with diesel volumes for fleet and agricultural accounts.
- Direct Sales:Large industrial consumers contract refinery-direct for petrochemical feedstocks, locking in ethane supply terms with Pemex.
- E-commerce:Fleet fuel cards and digital procurement platforms penetrate urban logistics segments with real-time pricing transparency.
Retail retains the widest reach; direct sales are climbing fastest as industrial buyers consolidate purchasing power.
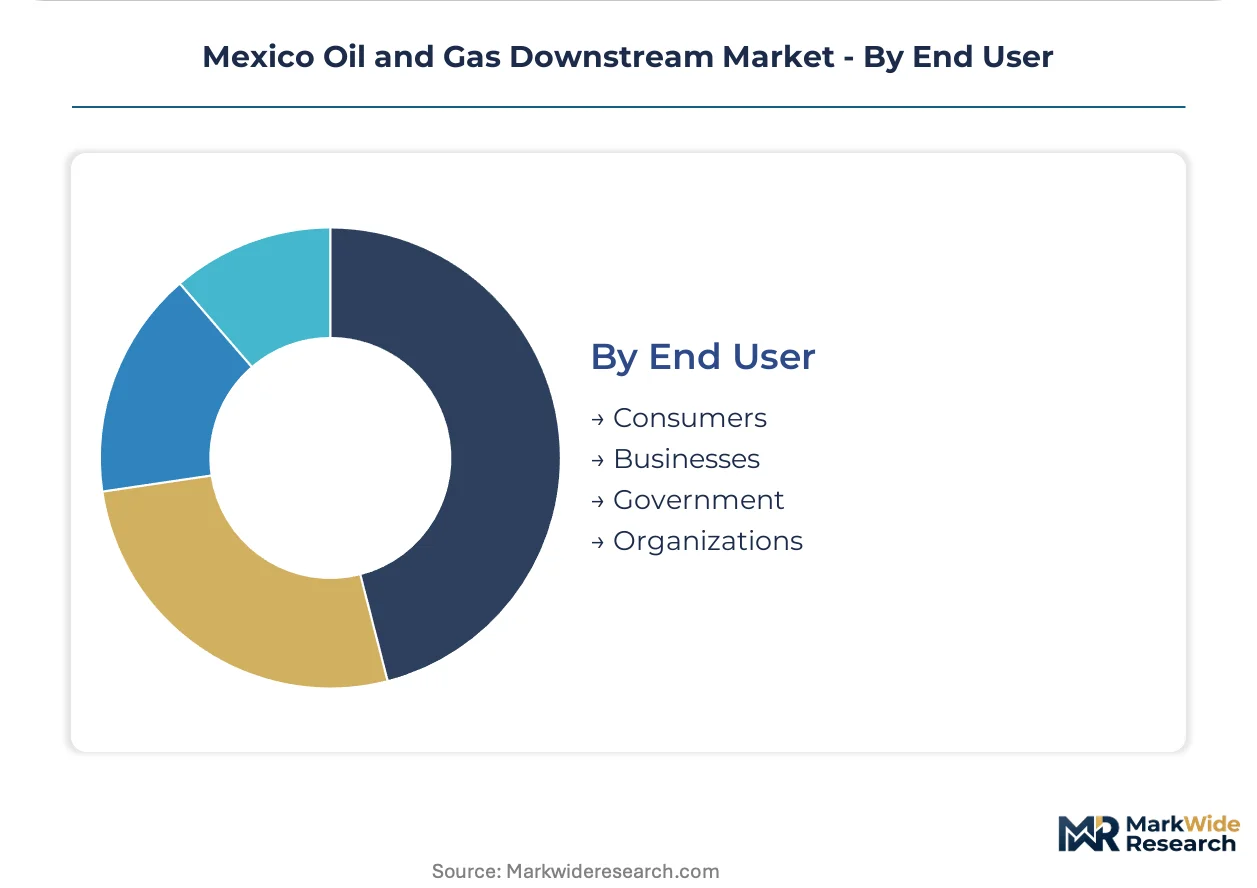
End User:
Maturity gradients separate price-sensitive consumer segments from institutional buyers with long-term contracting capacity.
- Consumers:Individual vehicle owners purchase gasoline through retail networks with high price elasticity and brand switching behavior.
- Businesses:Fleet operators and manufacturing facilities negotiate term contracts with storage terminal operators, prioritizing supply security over spot price minimization.
- Government:Federal and state procurement for public vehicle fleets and emergency reserves flows through centralized purchasing with quality specification enforcement.
- Organizations:Agricultural cooperatives and trucking associations pool demand for wholesale diesel access, achieving volume discounts unavailable to fragmented individual buyers.
Businesses represent the deepest revenue pool; organizations are expanding share fastest through cooperative purchasing structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic refining capacity clusters along Mexico's Gulf Coast corridor, with SENER infrastructure directives channeling investment toward Veracruz and Tabasco states. Pipeline networks radiate from this concentration to serve interior demand centers, while Pacific port terminals enable import arbitrage for West Coast markets.
Mexico City Metro
Fleet dieselization along the Mexico City-Queretaro-Leon freight triangle absorbs higher distillate volumes as cargo shifts from rail to trucking. CRE fuel quality mandates tighten gasoline specifications for the capital's vehicle concentration. Terminal infrastructure at Puebla and Tula anchors product distribution to this demand basin.
Veracruz
Coatzacoalcos refining corridor processes heavier crude slates into petrochemical derivatives for polyethylene producers. ASEA emissions protocols elevate operating costs for coastal facilities through mandated scrubber installations. Braskem Idesa leverages captive ethane access at this integrated complex.
Nuevo León
Industrial manufacturing in Monterrey metro drives petrochemical feedstock consumption for plastics and synthetic materials. SENER efficiency directives promote refinery off-gas cogeneration to reduce grid electricity purchases. Shell México maintains retail network density along federal highways connecting to this manufacturing hub.
Jalisco
Guadalajara's logistics sector consolidates diesel purchasing through direct terminal offtake agreements with storage operators. CRE open-access mandates expand third-party participation in product distribution. IEnova-controlled infrastructure enables wholesale supply to trucking cooperatives serving Pacific corridor freight.
Northern Border States
Cross-border pipeline connections concentrate gasoline import dependence in Chihuahua and Tamaulipas corridors. US Gulf Coast supply disruptions expose these markets to hurricane-related constraints. Monterra Energy and Valero Energy México compete on terminal access for private distribution networks.
Mexico Oil and Gas Downstream Market Competitive Landscape
Concentration sits with state-affiliated refiners and integrated petrochemical producers. Pemex's six-plant network anchors national capacity, while private terminal operators fragment distribution channels. Two archetypes dominate: vertically integrated energy conglomerates controlling upstream-through-retail value chains, and specialized storage-logistics platforms monetizing CRE-mandated open-access infrastructure. Competitive moves center on coker unit capacity additions and direct terminal offtake contracting with fleet operators.
Among state-affiliated and multinational energy groups, Petróleos Mexicanos represents the national refiner archetype with integrated pipeline and terminal control. Shell México and BP México exemplify international majors competing on retail network density and branded fuel quality. IEnova occupies a position as infrastructure-focused operator monetizing Pacific and Gulf Coast storage terminals under open-access frameworks.
| Leading Market Players |
|---|
| Valero Energy México |
| Iconn |
| Petróleos Mexicanos |
| Monterra Energy |
| Oxxo Gas |
| Braskem Idesa |
| Shell México |
| BP México |
| IEnova |
| Others |
Supply & Pricing Matrix
Coker unit scale economies at Pemex's six-plant network compress per-barrel processing costs while anchoring domestic price floors against US Gulf Coast import competition. SENER's refining directives concentrate capacity additions around heavy crude upgrading, concentrating supply-side pricing power in Veracruz's Coatzacoalcos corridor.
Pricing Analysis
Volume-discount tiering structures separate direct terminal offtake agreements for fleet operators from retail pump prices for consumer gasoline purchases. Three-tier pricing structure across premium, standard, and economy levels reflects octane specifications under CRE quality mandates and sulfur content differentiation in diesel grades. Cost compression in standard-tier gasoline is intensifying because Pemex's coker retrofits displace import volumes, narrowing arbitrage windows. Fleet operators exhibit lowest price sensitivity due to term-contract supply security priorities, while individual consumers demonstrate highest elasticity with brand-switching behavior at retail networks.
Supply Chain Analysis
Inventory lead times for Maya crude feedstock stretch from coastal extraction through pipeline delivery to Tula and Salamanca refineries, tethering throughput planning to tank farm capacity at Pajaritos terminal infrastructure. Supply concentration centers on Mexico's Gulf Coast corridor, with secondary dependence on US Gulf Coast gasoline and diesel imports through cross-border pipelines. Heavy sour crude slates, specialized hydrocracker catalysts, and ethane feedstock for polyethylene production anchor raw material dependencies. Single-source vulnerability runs through Pemex's integrated pipeline network controlling product flows to interior demand basins. Distribution runs through a hybrid structure combining state-controlled refining, IEnova-operated open-access terminals, and Shell México's retail network density along federal highway corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes Mexico's downstream sector as coker unit commissioning and CRE open-access mandates accelerate private participation in storage and distribution infrastructure.
For Market Incumbents: Consolidate terminal access advantages at Lazaro Cardenas and Topolobampo through capacity additions ahead of third-party entry rulings. Deepen backward integration into ethane supply contracts with Pemex infrastructure to defend margin capture against Braskem Idesa's captive feedstock position. ASEA emissions compliance timelines threaten production curtailments for coastal refineries lacking scrubber installations. For New Entrants and Emerging Players: Lead with direct terminal offtake contracting for diesel volumes along the Mexico City-Queretaro-Leon freight corridor, bypassing established retail intermediaries. Target trucking cooperatives and agricultural purchasing pools in Jalisco and Nuevo León as underpenetrated wholesale accounts. Pursue CRE-mandated open-access storage participation at Puebla and Guadalajara hubs as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among storage-terminal operators with long-term lease structures under open-access frameworks, outperforming volatile refining margin exposure. Infrastructure-focused platforms controlling Pacific and Gulf Coast import capacity offer superior cash-flow stability across the analysis window. Monitor Pemex coker unit commissioning schedules as the critical inflection signal for domestic production ramp-up displacing import dependence.| Strategic Initiative | Industry Significance |
|---|---|
| Coker Unit Capacity Expansion | Pemex's heavy crude upgrading capability reduces structural dependence on US Gulf Coast gasoline imports. |
| Open-Access Terminal Development | CRE mandates force incumbent storage operators to grant third-party entry, fragmenting distribution control. |
| Direct Fleet Contracting | Trucking cooperatives bypass retail networks through terminal offtake agreements along freight corridors. |
| Petrochemical Backward Integration | Braskem Idesa leverages captive ethane access at Coatzacoalcos for polyethylene margin capture. |
| Emissions Compliance Infrastructure | ASEA-mandated scrubber installations at Minatitlan and Salina Cruz refineries prevent production curtailments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across refining, terminal operations, and fleet logistics functions. Primary interviews captured perspectives from Pemex refinery managers, CRE regulatory affairs specialists, IEnova terminal operators, Shell México retail network directors, and Braskem Idesa procurement leads. Secondary validation drew from SENER infrastructure planning documents, ASEA emissions permit filings, CRE open-access rulings, customs import data, and SEC filings from listed energy infrastructure operators. Bottom-up volume modeling triangulated against top-down market sizing across product type and application segments.
Across the analysis window, forecasts incorporated capacity utilization rates at Pemex's six-plant network, coker unit commissioning timelines, and freight corridor dieselization patterns. Segmentation dimensions spanned product type, application, distribution channel, and end user, with regional production hub differentiation between Gulf Coast refining and Pacific port import terminals. CAGRs derived from trend extrapolation of historical throughput data adjusted for SENER policy directives and CRE regulatory implementation schedules.
Forecasts assume regulatory continuity in SENER downstream planning and CRE open-access enforcement; material policy shifts around import licensing or terminal access would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oilfield Drilling Elevator Market
Oil & Gas
Iraq Oil and Gas Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
Sucker Rod Market
Oil & Gas
Tight Gas Market
Oil & Gas
Italy Oil and Gas Upstream Market
Oil & Gas
Middle East and Africa Coiled Tubing Market
Oil & Gas
Drilling and Completion Fluids Market
Oil & Gas
Egypt Oil and Gas Market
Oil & Gas
Europe Intelligent Pigging Market
Oil & Gas
Middle-East Oil and Gas Line Pipe Market
Oil & Gas
Delayed Coker Unit Market
Oil & Gas
Intelligent Well Completion Market
Oil & Gas
United States Oil and Gas Separation Market
Oil & Gas
United Kingdom LNG Market
Oil & Gas
East Africa Oil and Gas Market