
 Oil Field Drill Bits Market | 2026-2036
Oil Field Drill Bits Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Field Drill Bits Market Analytics
Premium matrix-body PDC bit specifications is rotating through the replacement cycle for steel-body alternatives in high-impact drilling zones. SLB leverages integrated drilling systems to bundle bit selection with downhole telemetry, sustaining pricing power across North American shale plays. Baker Hughes Company anchors its position through materials science investments in thermally stable polycrystalline diamond cutters. Halliburton Company differentiates via real-time bit wear analytics that reduce trip frequency in extended-reach laterals.
Oil field drill bits are cutting tools engineered with tungsten carbide inserts or synthetic diamond compacts bonded to steel or matrix bodies, typically ranging from three to twelve inches in diameter, designed to pulverize or shear rock formations during hydrocarbon extraction. Their primary purpose is to maintain rate of penetration while minimizing non-productive time in environments exceeding 150°C and 20,000 psi. PDC bits command the largest share of new capital deployment due to superior efficiency in homogeneous shale, while diamond bits retain niche dominance in hard abrasive formations where cutter longevity determines economics. Onshore applications absorb the majority of unit volume, though offshore bits carry substantially higher per-unit value given complex directional requirements and corrosive environments.
API Specification 7-1 governs dimensional and performance standards for rotary drill bits in US operations, while NORSOK D-001 imposes supplementary fatigue-testing protocols for North Sea deployments. EPA methane emissions rules indirectly shape bit demand by pressuring operators to reduce drilling days and associated venting per wellbore. BSEE well-control regulations for offshore US waters mandate redundant barrier systems that influence cutter layout and hydraulics design. Stakeholders must weigh capital allocation between next-generation cutter materials and digital twin predictive models as the primary path to differentiation.
Market Dynamics
Directional drilling intensity in unconventional reservoirs is compressing bit replacement cycles and forcing cutter design trade-offs between thermal stability and impact resistance. Operators now specify bits for specific lithology windows rather than basin-generalized applications, fragmenting procurement patterns across North American shale plays.
Growth Catalysts
- EPA methane emissions rules:Compressed drilling timelines reduce venting per wellbore, accelerating premium PDC bit deployment to maintain rate of penetration in the Permian Basin and Gulf of Mexico.
- Extended-reach laterals:Laterals exceeding 15,000 feet in the Delaware Basin demand real-time bit wear monitoring to eliminate unplanned trips, expanding telemetry-integrated bit systems.
- Thermally stable polycrystalline diamond:Next-generation cutter materials withstand formation temperatures above 175°C, unlocking deeper targets in the Anadarko and Williston basins.
Market Restraints
- Tungsten carbide supply concentration:Powder metallurgy feedstock for matrix-body bits depends on Chinese tungsten concentrate processing, exposing margins to export quota volatility.
- API Specification 7-1 fatigue-testing:Compliance timelines extend 18-24 months for new bit designs, freezing small manufacturers out of premium offshore qualification.
- Steel-body bit substitution:Matrix-body PDC platforms retain 40% cost premium over steel alternatives, limiting penetration in price-sensitive onshore drilling contracts.
Strategic Opportunities
- Digital twin predictive models:Physics-based cutter wear simulation integrated with SLB's drilling systems enables bit selection optimization before spud, creating service-revenue capture.
- BSEE well-control redundancy:Dual-barrier mandates for offshore US waters drive specialized cutter layouts and hydraulics engineering for ultra-deepwater contractors.
- Geothermal drilling crossover:Hard-rock geothermal projects in Nevada and Utah require diamond bit durability adapted from oilfield designs, opening non-hydrocarbon revenue streams.
Industry Challenges
- ISO 9001 material traceability:Certification audits now demand cutter origin documentation through three supply tiers, complicating procurement for mid-tier bit assemblers.
- Downhole telemetry integration:Legacy rig fleets lack MWD/LWD compatibility with smart bit systems, forcing capital-intensive retrofit decisions or exclusion from integrated drilling tenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Field Drill Bits Market |
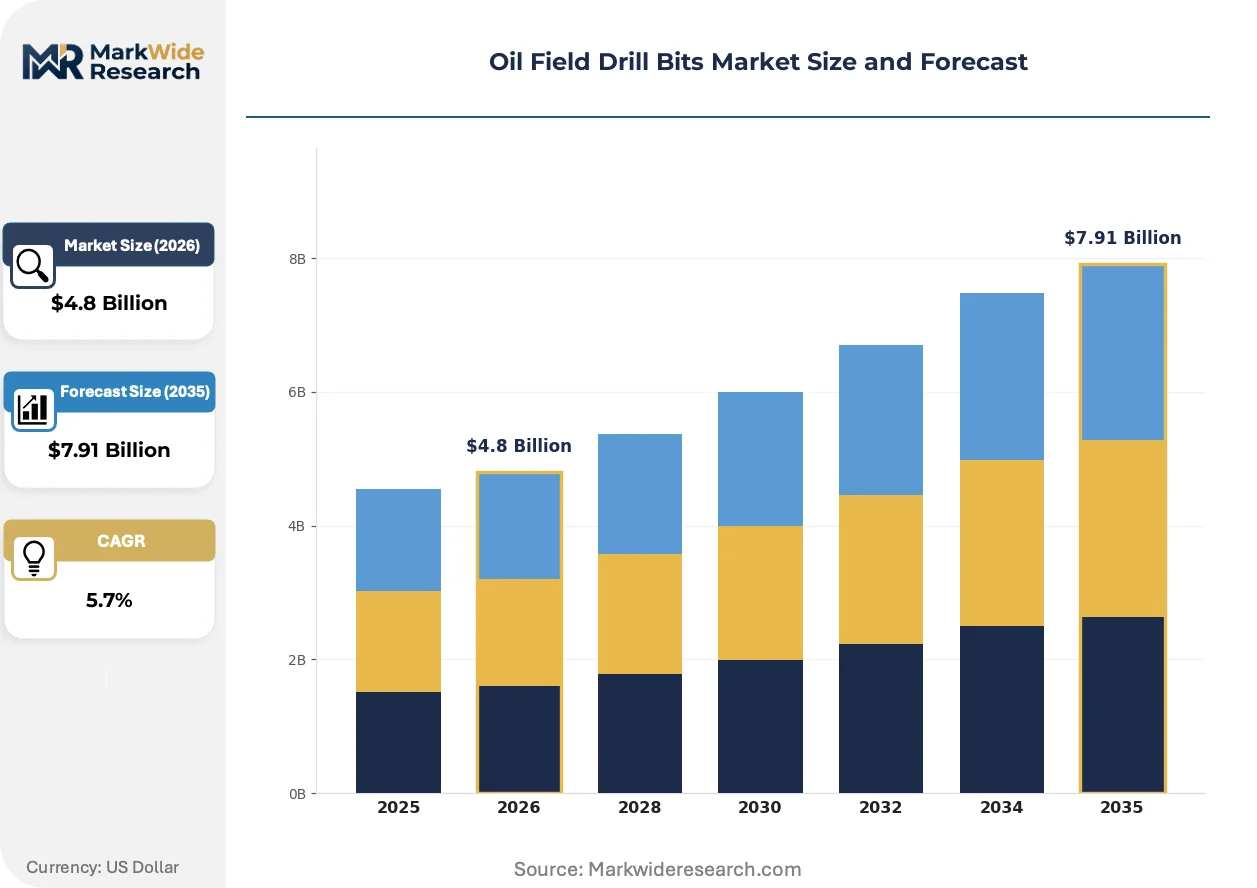
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tri-Cone Bits, PDC Bits, Drag Bits, Diamond Bits Application: Onshore, Offshore, Mining, Geothermal End User: Oil & Gas Companies, Service Providers, Drilling Contractors, Government Entities Material: Steel, Carbide, Diamond, Composite |
| Companies Covered | SLB, Baker Hughes Company, Halliburton Company, NOV, Varel International, Ulterra Drilling Technologies, Atlas Copco, Sandvik AB, Torquato Drilling Accessories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Field Drill Bits Market Evolving Landscape
Bit engineering is pivoting from mechanical durability to data-enabled performance optimization, with cutter materials and real-time analytics converging to reshape competitive differentiation. Three developments are compressing traditional design cycles and rewiring supplier-operator relationships.
Hybrid diamond-carbide cutter architectures are fragmenting the historical PDC-versus-diamond bit dichotomy. Operators in the Midland Basin now specify gradient-density cutter layouts that shear soft interbeds yet withstand chert stringers. Baker Hughes and Halliburton field teams report 30% faster field trials for these transitional designs versus conventional qualification paths.
BSEE offshore barrier regulations are mandating redundant cutter activation systems for subsea BOP compatibility. This forces bit manufacturers to engineer hydraulic bypass channels that maintain cutting action during primary circulation failure. Gulf of Mexico contractors now pre-qualify bits against simulated well-control scenarios, extending procurement lead times but reducing stack insurance premiums.
Operator purchasing departments are unbundling bit supply from directional drilling services, reversing decade-long bundled contracting norms. Large independents in the Eagle Ford now source bits through separate RFPs from RSS providers, compressing supplier margins but expanding specialty bit vendor access. This disintermediation is most advanced among Permian operators with captive directional drilling capabilities.
Oil Field Drill Bits Market Segmentation
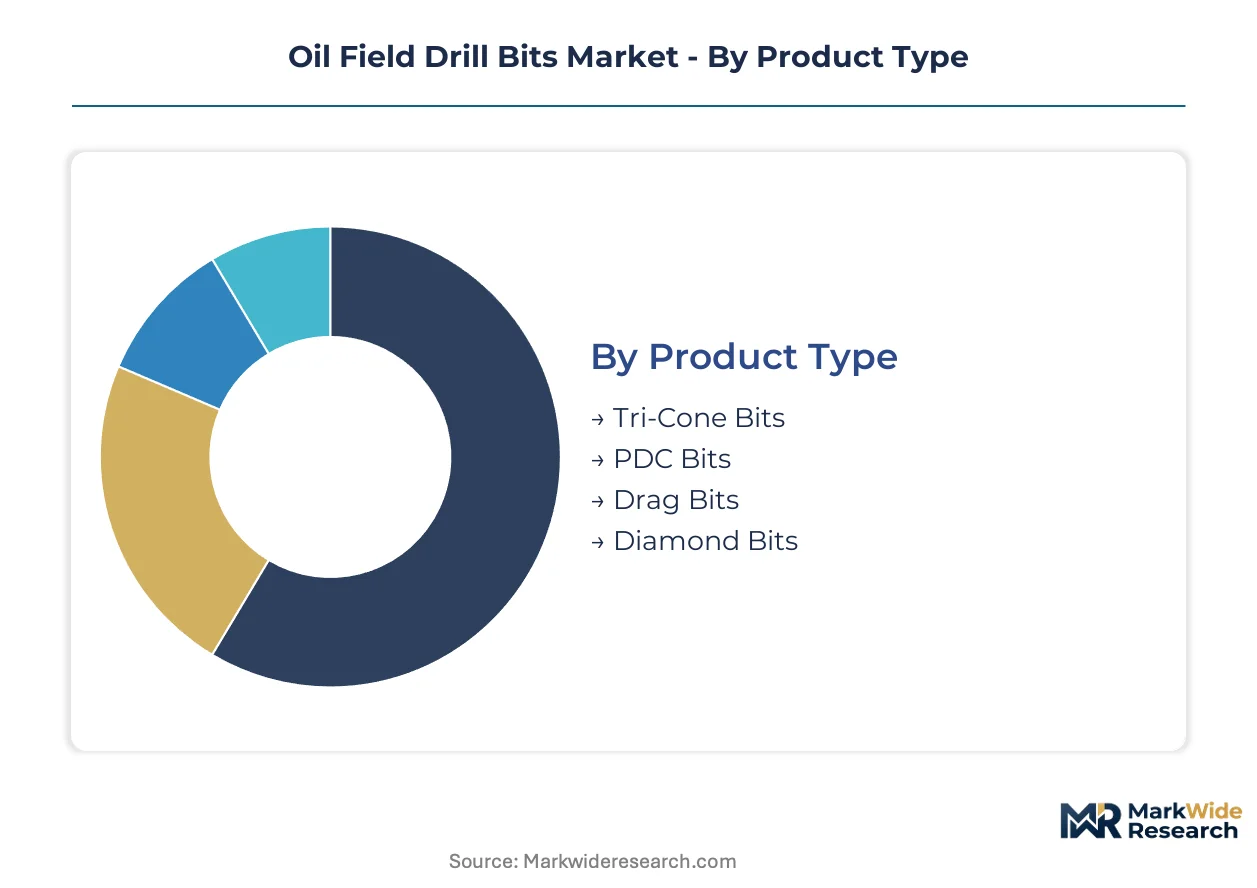
Drill bit procurement patterns fragment across four distinct taxonomies. Product type determines cutter technology and thermal limits. Application scope dictates barrier-system requirements and telemetry integration. End-user structure separates bundled service contracts from direct equipment purchases. Material composition anchors supply chain exposure and certification complexity.
Product Type:
PDC bits and diamond variants command premium margin pools due to materials intensity and qualification barriers. Tri-cone and drag bit segments compete on replacement volume and fleet standardization.
- PDC Bits:Polycrystalline diamond compact cutters bonded to steel or matrix bodies deliver shearing action in homogeneous shale. Demand concentrates in the Permian Basin and Delaware Basin where laterals exceed 15,000 feet and thermal stability above 175°C unlocks deeper targets. API Specification 7-1 fatigue-testing extends qualification timelines, freezing marginal competitors out of premium offshore deployment.
- Diamond Bits:Natural or synthetic diamond-impregnated matrices grind through abrasive formations where cutter longevity determines economics. Mining applications in Nevada hard-rock geothermal and Gulf of Mexico deepwater pre-salt zones absorb high-unit-value production. Thermally stable polycrystalline formulations withstand formation temperatures that degrade conventional PDC cutters.
- Tri-Cone Bits:Tungsten carbide insert or milled tooth configurations rotate through roller bearings to crush rock via compressive fracture. Shallow vertical wells in legacy onshore fields sustain replacement demand.
- Drag Bits:Fixed-blade steel designs with hardened cutting edges penetrate soft, unconsolidated formations at low cost. Water well and environmental drilling contractors specify these for non-hydrocarbon applications.
PDC bits hold installed capacity. Diamond bits are rotating up the share rankings.
Application:
Offshore deployments generate value concentration through complex directional requirements and redundant barrier mandates. Onshore volume dominates unit throughput.
- Onshore:Unconventional shale development in the Permian, Bakken, and Marcellus formations drives bit consumption through extended-reach laterals and pad drilling intensity. EPA methane emissions rules compress drilling timelines, accelerating premium PDC deployment to minimize venting per wellbore.
- Offshore:Subsea BOP compatibility and BSEE well-control redundancy requirements mandate specialized cutter layouts and hydraulic bypass channels. Gulf of Mexico contractors pre-qualify bits against simulated well-control scenarios, extending procurement lead times but reducing stack insurance premiums.
- Mining:Hard-rock extraction in copper and iron ore operations adapts oilfield diamond bit durability for non-hydrocarbon mineral recovery.
- Geothermal:Hard-rock projects in Nevada and Utah require diamond bit longevity adapted from oilfield designs, opening non-hydrocarbon revenue streams for established manufacturers.
Onshore absorbs volume throughput. Offshore is climbing the fastest in value per unit.
End User:
Service providers and drilling contractors concentrate procurement leverage through fleet scale and integrated drilling system bundling.
- Service Providers:SLB, Baker Hughes, and Halliburton field organizations specify bits within integrated drilling systems that bundle selection with downhole telemetry and real-time wear analytics. These entities sustain pricing power through physics-based cutter wear simulation and digital twin predictive models.
- Drilling Contractors:Nabors, Helmerich & Payne, and Patterson-UTI operate rig fleets that unbundle bit supply from directional services, sourcing through separate RFPs to compress supplier margins.
- Oil & Gas Companies:Large independents in the Eagle Ford and Permian with captive directional drilling capabilities drive disintermediation trends.
- Government Entities:State-owned operators in producing regions mandate ISO 9001 material traceability through three supply tiers, complicating procurement for mid-tier assemblers.
Service providers hold procurement leverage. Drilling contractors are gaining share fastest in unbundled sourcing.
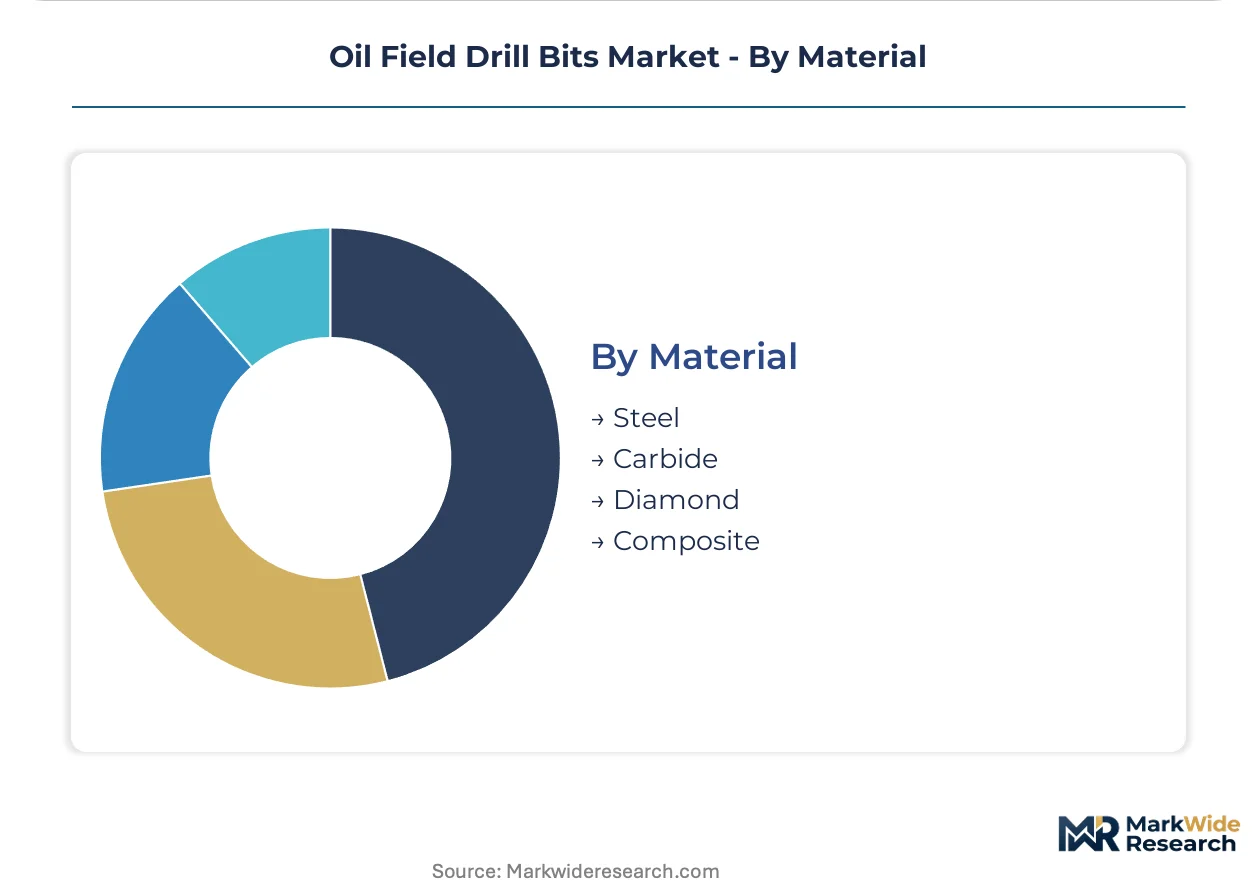
Material:
Matrix-body carbide and diamond materials capture value through thermal performance and supply concentration.
- Carbide:Tungsten carbide powder metallurgy for matrix-body bits depends on Chinese concentrate processing, exposing margins to export quota volatility. Carbide inserts in tri-cone configurations balance impact resistance and cost in heterogeneous formations.
- Diamond:Synthetic polycrystalline and thermally stable variants withstand temperatures exceeding 175°C in deep Anadarko and Williston basin targets. Cutter origin documentation requirements complicate three-tier supply chain audits.
- Steel:Forged alloy bodies for PDC platforms carry 40% cost discount versus matrix alternatives, limiting penetration in price-sensitive onshore contracts.
- Composite:Hybrid diamond-carbide architectures fragment historical product dichotomies, with gradient-density layouts specified for Midland Basin interbeds and chert stringers.
Carbide holds installed capacity. Diamond is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for oil field drill bits track closely with hydrocarbon production geography, with the United States maintaining a structural surplus in high-performance PDC designs while importing specialized diamond matrices for geothermal crossover applications.
United States
Permian Basin operators drive premium PDC bit consumption through extended-reach laterals exceeding 15,000 feet. EPA methane emissions rules compress drilling timelines, accelerating replacement cycles. Midland-Odessa anchors manufacturing clusters where SLB and Halliburton field teams co-locate with directional drilling contractors.
China
Tungsten carbide concentrate processing dominates powder metallurgy feedstock supply for matrix-body bits. MIIT industrial standards govern cutter material specifications for domestic oilfield service procurement. Sichuan basin shale pilots import thermally stable diamond designs for high-temperature formations.
Norway
North Sea ultra-deepwater projects demand redundant barrier-compatible bit systems under NORSOK D-001 fatigue-testing protocols. Equinor-operated Johan Sverdrup field specifies bits with hydraulic bypass channels for BOP compatibility. Stavanger clusters host specialized engineering for subsea well-control scenarios.
Saudi Arabia
Aramco unconventional gas pilots in Jafurah Basin adopt PDC platforms for tight carbonate formations. Saudi national procurement mandates ISO 9001 material traceability through three supply tiers. Dhahran-Riyadh corridor concentrates bit inventory management for rig fleet standardization.
Brazil
Pre-salt carbonate drilling in Santos Basin requires diamond-impregnated bit durability for abrasive formations. ANP local content rules shape supplier qualification for offshore tenders. Rio de Janeiro engineering clusters adapt oilfield designs for Libra field ultra-deepwater complexity.
Oil Field Drill Bits Market Competitive Landscape
Concentration sits with integrated oilfield service conglomerates that bundle bit selection with telemetry and real-time analytics. Three strategic archetypes define competitive positioning: full-service drilling systems providers, specialized bit engineering houses, and mining-to-oilfield crossover manufacturers. Dominant competitive moves include backward integration into cutter material supply and technology licensing agreements for thermally stable diamond formulations.
Within the integrated systems tier, SLB, Baker Hughes Company, and Halliburton Company occupy positions that exemplify bundled service models where bit procurement decisions tie to broader drilling performance contracts. These entities represent the premium vector where physics-based cutter wear simulation and digital twin predictive models create service-revenue capture distinct from standalone equipment sales.
| Leading Market Players |
|---|
| SLB |
| Baker Hughes Company |
| Halliburton Company |
| NOV |
| Varel International |
| Ulterra Drilling Technologies |
| Atlas Copco |
| Sandvik AB |
| Torquato Drilling Accessories |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Chinese tungsten carbide powder plants anchors cost floors for matrix-body PDC bits, concentrating supply leverage among integrated manufacturers while fragmenting price-setting power for steel-body assemblers. This scale asymmetry forces procurement officers to balance thermal performance premiums against feedstock volatility exposure.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for premium PDC bits, with price differentiation resting on API Q2 certification grade and volume scale commitments. Cost compression in steel-body alternatives intensifies as drilling contractors unbundle directional services, squeezing margins for non-integrated suppliers. Large independents in the Permian Basin exhibit highest price sensitivity, while Gulf of Mexico ultra-deepwater operators absorb premiums for redundant barrier compatibility.
Supply Chain Analysis
China and Vietnam anchor tungsten concentrate processing and powder metallurgy feedstock for matrix-body bits, with synthetic diamond cutter production clustering in the United States and Japan. Raw material dependencies center on tungsten carbide powders, thermally stable polycrystalline diamond blanks, and forged alloy steel bodies. Single-source vulnerability in Chinese export quotas exposes margin stability to geopolitical disruption. Distribution runs through integrated oilfield service conglomerates that bundle bit selection with telemetry systems and real-time analytics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drill bit demand sits in early-cycle expansion as EPA methane rules compress drilling timelines and force premium PDC deployment to minimize venting per wellbore. Penetration of thermally stable cutter materials in deeper unconventional targets extends replacement intensity across North American shale plays.
For Market Incumbents: Shield installed base relationships by deepening backward integration into synthetic diamond cutter supply and accelerating digital twin predictive model deployment before unbundling trends fragment service bundling. Steel-body substitution threats from price-sensitive onshore contractors demand proactive capacity repositioning toward matrix-body thermal performance leadership.
For New Entrants and Emerging Players: Anchor in geothermal drilling crossover applications in Nevada and Utah, where hard-rock durability requirements outpace established oilfield supplier adaptation. Hard-rock mineral extraction and directional mining projects offer penetrable white-space with lower certification barriers than offshore hydrocarbon qualification. Go-to-market leverage rests on cutter longevity guarantees backed by physics-based wear simulation rather than integrated service bundling.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telemetry-integrated bit system providers that capture service contracts beyond equipment sales. Long-term viability favors manufacturers with captive synthetic diamond supply and ISO 9001 certification infrastructure spanning three supply tiers. Watch for inflection in unbundled procurement RFP volume from Permian operators with captive directional drilling capabilities as signal of structural margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cutter Material Supply | Captive synthetic diamond production insulates margins from Chinese tungsten quota volatility and API Q2 audit delays. |
| Digital Twin Predictive Model Deployment | Physics-based wear simulation embedded in SLB drilling systems creates service-revenue capture distinct from equipment sales. |
| Geothermal Drilling Crossover Expansion | Hard-rock projects in Nevada and Utah adapt oilfield diamond bit durability for non-hydrocarbon mineral recovery revenue. |
| BSEE Redundant Barrier System Qualification | Hydraulic bypass channel engineering for subsea BOP compatibility commands premium pricing from Gulf of Mexico contractors. |
| Unbundled Procurement Channel Development | Separate RFP positioning for drilling contractors bypasses integrated service conglomerates and captures price-sensitive onshore volume. |
Research Methodology
Desk research of API specification documentation, BSEE regulatory filings, and SEC 10-K equipment disclosures preceded structured interviews with directional drilling contractors, bit procurement officers at large independents, and thermally stable diamond cutter R&D directors. Primary fieldwork with SLB and Halliburton field teams in Midland-Odessa and Bakken clusters validated secondary trade flow data from USITC and OPEC drilling activity reports. Bottom-up rig fleet deployment models triangulated against top-down hydrocarbon production forecasts.
Variance decomposition across product type, application scope, material composition, and end-user structure shaped analytical framework development over the projection horizon. Segmentation dimensions modeled include cutter technology platform, barrier system requirement tier, and telemetry integration complexity. CAGRs derived from rig count trajectories, lateral length expansion curves, and replacement cycle compression under EPA methane timelines. Forecast inputs incorporated thermally stable polycrystalline diamond adoption rates and unbundled procurement pattern shifts.
Underlying assumptions cover continued unconventional reservoir development intensity, API Specification 7-1 compliance stability, and Chinese tungsten export quota continuity, with deviation risk concentrated in regulatory acceleration of methane emissions rules and BSEE barrier mandate expansion. Recalibration cycles align with material shifts in rig fleet telemetry adoption and geothermal drilling crossover penetration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Singapore LNG Storage Tank Market
Oil & Gas
Oil and Gas Pipe Market
Oil & Gas
Global Fracking Chemicals Market
Oil & Gas
Latin America AI in Oil and Gas Market
Oil & Gas
Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Oil Hose Market
Oil & Gas
Electric Fracking Market
Oil & Gas
Distributed Fiber Optic Sensor in Oil & Gas Market
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
Wired Drill Pipe Sales Market
Oil & Gas
Oilfield Drilling Elevator Market
Oil & Gas
Chad Oil and Gas Upstream Market
Oil & Gas
Swellable Packers Market
Oil & Gas
Polycrystalline Diamond Compact (PDC) Drill Bit Market
Oil & Gas
Kazakhstan Oil and Gas Midstream Market
Oil & Gas
India Natural Gas Market