
 America SLI Battery Market | 2026-2036
America SLI Battery Market Size, Share, and Industry Trends Forecast 2026-2036
America SLI Battery Market Analysis
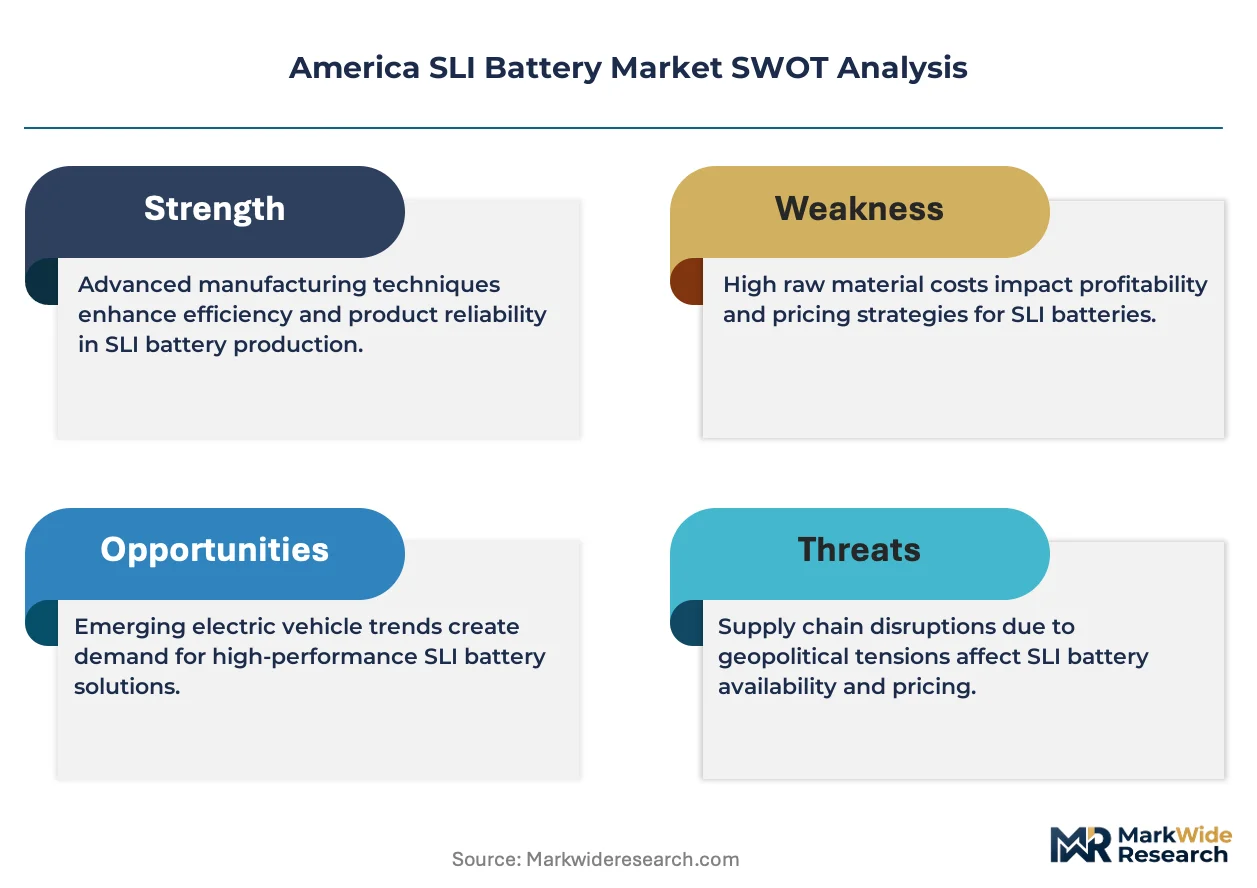
Enhanced flooded battery specifications is bifurcating the America SLI landscape as OEMs tighten cold-cranking amperage thresholds. Clarios leverages its North American manufacturing footprint to supply major automakers with advanced AGM formats. East Penn Manufacturing Company anchors the independent aftermarket through deep distributor relationships across the US and Canada. Interstate Batteries differentiates via private-label partnerships with national retail chains.
An SLI (Starting, Lighting, Ignition) battery is a rechargeable lead-acid or lithium-ion unit engineered to deliver short, high-current bursts for engine cranking while sustaining electrical accessory loads during idle periods. Flooded lead acid variants still dominate unit volume across the Americas, though AGM segments command premium pricing in start-stop vehicle applications. Commercial vehicles and marine applications represent the fastest-growing application pools, driven by heavier electrical loads and extended duty cycles. Aftermarket providers absorb the majority of replacement demand as OEM channels focus on new-vehicle fitment.
EPA emissions standards and NHTSA fuel-economy rules push automakers toward start-stop systems, which in turn mandate enhanced battery durability. The US Department of Transportation enforces battery safety labeling and recycling compliance through interstate commerce regulations. Stakeholders must weigh lithium-ion development costs against lead-acid recycling infrastructure maturity when allocating R&D budgets.
Market Dynamics
EPA emissions enforcement is compressing commercial vehicle replacement cycles while start-stop system mandates force battery chemistry upgrades across North American automotive platforms. This regulatory pressure is decomposing conventional flooded lead-acid demand into enhanced flooded and AGM segments.
Growth Catalysts
- Start-Stop Mandates:NHTSA fuel-economy rules require automakers to install engine stop-start systems, which demand enhanced battery durability and higher cold-cranking amperage specifications.
- Commercial Fleet Electrification:Heavy-duty truck operators in the US Midwest and Southeast corridor are accelerating battery replacement schedules to maintain EPA compliance under tightening enforcement protocols.
- Cold-Climate Performance Standards:AGM chemistry is capturing share in northern US states where subzero temperature reliability has become a non-negotiable procurement criterion for fleet managers.
Market Restraints
- Lead Price Volatility:Raw material input costs for lead-acid chemistries fluctuate with commodity markets, compressing margin stability for manufacturers dependent on flooded cell production.
- Recycling Infrastructure Concentration:Secondary lead smelting capacity clusters in specific US industrial corridors, creating geographic supply risk for battery producers seeking closed-loop material recovery.
- Lithium-Ion Substitution Threat:Declining lithium-ion pack costs for light-duty applications threaten SLI lead-acid dominance in premium passenger vehicle segments.
Strategic Opportunities
- Canadian Aftermarket Expansion:Independent distributor networks in Ontario and Quebec remain underpenetrated relative to US density, offering white-space growth for enhanced flooded product lines.
- Marine Application Convergence:Dual-purpose deep-cycle SLI hybrids are capturing demand from recreational boaters seeking single-battery solutions for starting and house loads.
- IRA Manufacturing Credits:Domestic content incentives under the Inflation Reduction Act are accelerating North American AGM production capacity investments.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Battery manufacturers face recruitment gaps for specialists in absorbent glass mat separator optimization and valve-regulated lead-acid design.
- Start-Stop System Integration Complexity:Battery management system calibration with vehicle ECUs requires extended validation cycles, delaying new product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | America SLI Battery Market |
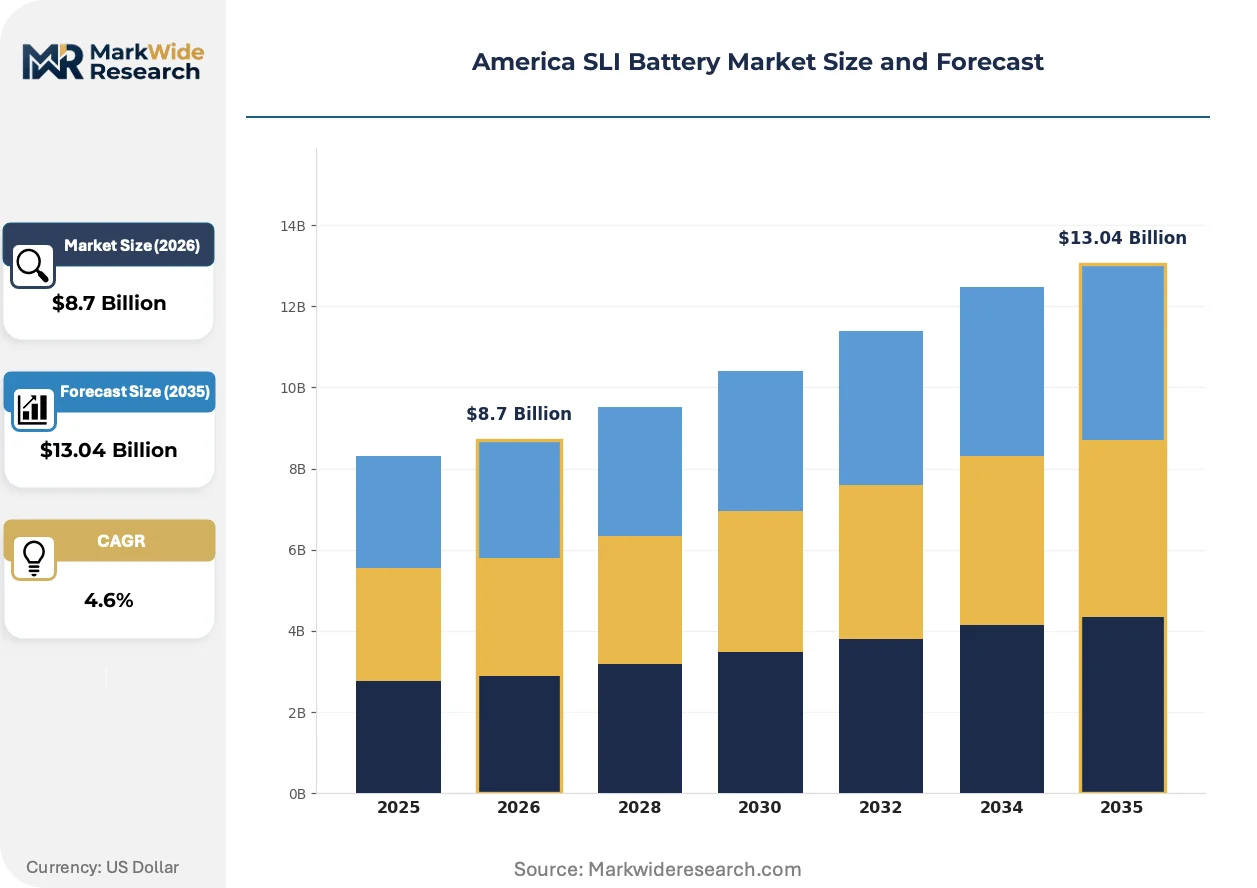
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Flooded Lead Acid, AGM, Gel, Lithium-Ion Application: Automobiles, Marine, Motorcycles, Commercial Vehicles Technology: Standard, Enhanced, Smart, Sustainable End User: OEMs, Aftermarket Providers, Rental Services, Retailers |
| Companies Covered | EnerSys, Crown Battery, Clarios, ACDelco, Interstate Batteries, East Penn Manufacturing Company, GS Yuasa International Ltd, FIAMM Energy Technology, Exide Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
America SLI Battery Market Emerging Trajectories
Active material formulations and separator architectures are undergoing rapid iteration as battery engineers respond to start-stop duty cycle demands. The competitive frontier has shifted toward thermal management and charge acceptance rate optimization.
Absorbent glass mat technology is decomposing the traditional flooded lead-acid architecture in start-stop vehicle applications. OEMs in the US and Canada are specifying AGM formats for over half of new light-truck platforms. This chemistry migration is compressing conventional battery foundry utilization rates while expanding premium pricing tiers.
EPA enforcement protocols for commercial vehicle emissions are tightening inspection and maintenance requirements across interstate commerce corridors. Fleet operators must now document battery electrical system performance as part of compliance audits. Heavy-duty segments in California and Texas are responding with predictive replacement scheduling and enhanced electrical load monitoring.
Fleet procurement departments are consolidating supplier relationships and demanding extended warranty terms tied to telematics-verified duty cycle data. National retail chains and independent distributors are losing share to direct manufacturer agreements with large commercial operators. This concentration is most visible in the US Southeast corridor where regional trucking fleets command volume leverage.
America SLI Battery Market Segmentation
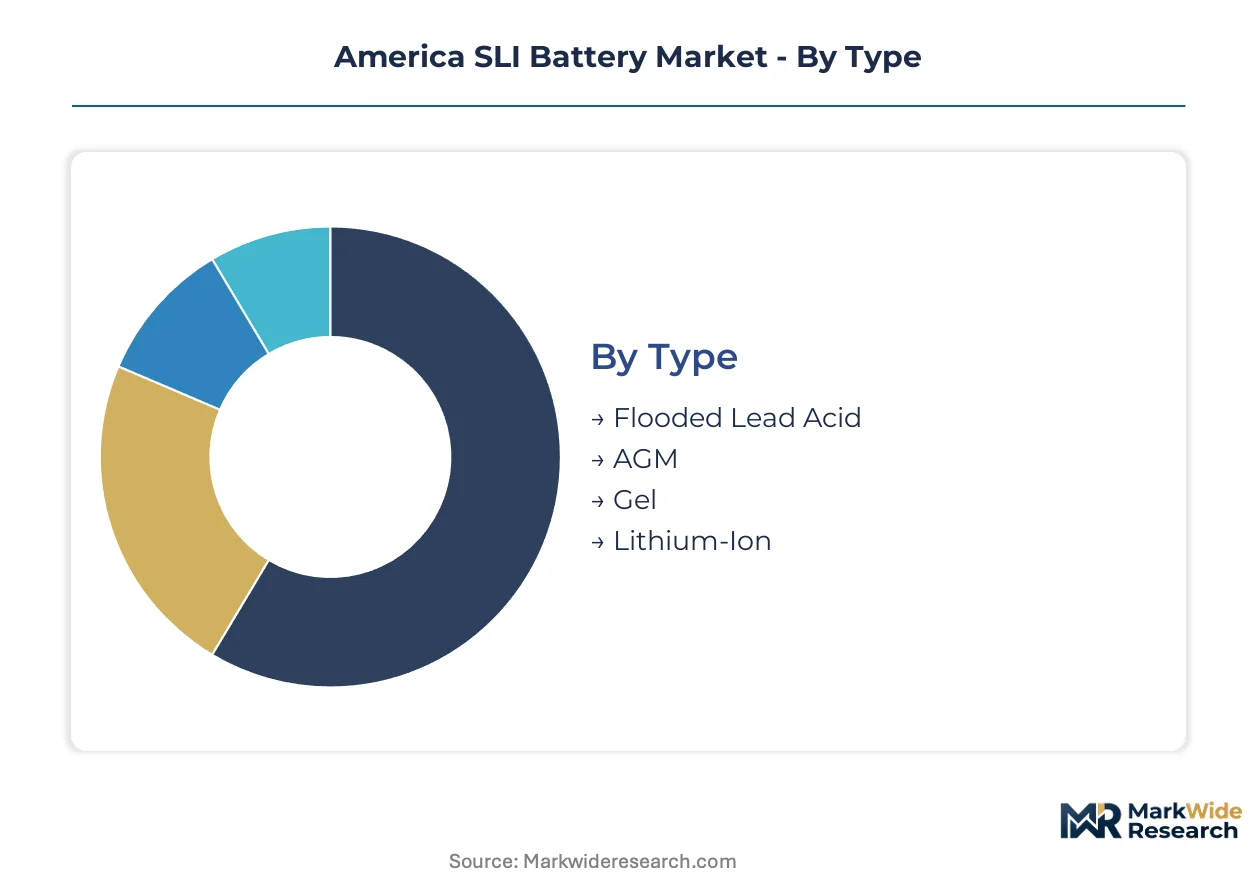
SLI battery segmentation reveals how regulatory pressure and duty-cycle demands fragment procurement patterns across vehicle platforms. Chemistry selection now hinges on EPA compliance mandates and cold-climate performance thresholds rather than upfront cost alone.
Type:
EPA emissions enforcement and NHTSA fuel-economy rules have created divergent compliance pathways that favor specific electrochemical architectures.
- Flooded Lead Acid:Conventional liquid-electrolyte construction with removable caps for maintenance access dominates replacement volume in legacy vehicle parc. Demand concentrates in the US Southeast corridor where light-truck aftermarket density remains highest and price-sensitive fleet operators prioritize unit economics over cycle life.
- AGM:Absorbent glass mat separators immobilize electrolyte to withstand deep-cycling and vibration stress demanded by start-stop systems. Cold-climate states from Minnesota to Maine specify AGM chemistry as a non-negotiable procurement criterion for commercial fleet compliance with idle-reduction mandates.
- Gel:Silica-thickened electrolyte formulation resists stratification in marine and deep-cycle applications. Recreational boaters in Florida and the Great Lakes region specify gel cells for dual-purpose starting and house-load service.
- Lithium-Ion:Lithium iron phosphate and lithium-manganese chemistries deliver weight reduction and charge acceptance advantages. Premium passenger EV platforms and performance motorcycles in California and Texas test lithium SLI substitution despite recycling infrastructure gaps.
Flooded lead acid handles the majority of throughput; lithium-ion is the fastest mover on share.
Application:
Vehicle electrification intensity and duty-cycle severity determine battery specification tiers across transportation modes.
- Automobiles:Light-duty passenger and truck platforms drive chemistry migration toward AGM for start-stop compatibility. OEM fitment in the US Midwest assembly corridor specifies enhanced flooded or AGM for over half of new platforms.
- Marine:Dual-purpose deep-cycle hybrids capture recreational boating demand in coastal Florida and Great Lakes markets. House-load requirements and trolling motor duty cycles favor gel and AGM formats over conventional flooded designs.
- Motorcycles:Compact form factors and vibration resistance prioritize AGM and lithium-ion for powersports OEMs. Aftermarket replacement in the US Southwest concentrates on conventional flooded for price-sensitive cruiser segments.
- Commercial Vehicles:Heavy-duty trucking fleets in the US Southeast and California corridor accelerate replacement schedules under tightening EPA enforcement. Predictive battery monitoring and telematics-verified warranty terms now dominate procurement negotiations.
Automobiles absorb the greatest unit volume; commercial vehicles exhibit the steepest specification upgrade trajectory.
Technology:
Battery management system sophistication and active material engineering separate procurement tiers across customer segments.
- Standard:Basic lead-acid construction without valve regulation or electronic monitoring serves price-driven replacement demand. Independent distributors in rural US markets stock standard flooded formats for legacy vehicle parc.
- Enhanced:Optimized active material formulations and improved separator architecture extend cycle life for start-stop duty. OEM specifications in Canada and the US mandate enhanced flooded or AGM for new light-truck platforms.
- Smart:Integrated battery management systems with state-of-charge telemetry enable predictive replacement and telematics integration. Fleet operators in Texas and California demand smart battery systems for compliance documentation.
- Sustainable:Closed-loop manufacturing and recycled lead content targets respond to IRA domestic content incentives. North American AGM production investments prioritize sustainable technology tiers for OEM qualification.
Enhanced technology carries the dominant specification share; smart systems are climbing the fastest on fleet procurement priority lists.
End User:
Channel structure and volume concentration determine pricing power and service-level requirements across the value chain.
- OEMs:Direct manufacturer agreements with automakers and commercial vehicle builders specify chemistry and warranty terms. US and Canadian light-truck assembly plants qualify AGM suppliers through extended validation cycles.
- Aftermarket Providers:Independent distributor networks and jobber channels absorb the majority of replacement demand. Deep relationships across the US and Canada anchor volume for enhanced flooded product lines.
- Rental Services:Fleet leasing operators standardize on predictive replacement schedules to minimize downtime penalties. Telematics-verified duty cycle data drives supplier consolidation in the US Southeast corridor.
- Retailers:National auto parts chains and mass merchants compete on private-label partnerships and installation service bundling. Price transparency and warranty terms differentiate retail channel positioning.
Aftermarket providers handle the majority of replacement throughput; rental services are gaining share fastest on fleet electrification timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in the America SLI battery market varies sharply across geographies. Fleet operators in the US Southeast corridor prioritize unit economics and volume procurement, while cold-climate buyers in northern states and Canadian provinces accept premium pricing for AGM durability.
United States
Light-truck assembly plants in Michigan, Ohio, and Tennessee drive OEM demand for enhanced flooded and AGM formats. EPA emissions enforcement under the Clean Air Act compels commercial fleets to document battery electrical system performance during compliance audits. The US Midwest and Southeast corridor concentrates aftermarket distribution density, with independent jobber networks absorbing the majority of replacement volume.
Canada
Subzero temperature reliability has become a non-negotiable procurement criterion for fleet managers across Ontario and Quebec. Transport Canada enforces battery safety labeling and recycling compliance through interprovincial commerce regulations. Independent distributor networks in Toronto and Montreal remain underpenetrated relative to US density, offering white-space growth for enhanced flooded product lines.
Mexico
Automotive assembly expansion in Nuevo León and the Bajío Region generates pull-through demand for SLI battery supply chains. Mexico's environmental regulator SEMARNAT enforces hazardous waste handling protocols for lead-acid battery recycling. Maquiladora operations near the US border concentrate inbound logistics for North American OEM qualification programs.
America SLI Battery Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the America SLI battery market. The vendor base clusters around three strategic tiers: integrated multinational suppliers with North American manufacturing footprints, independent domestic manufacturers anchored in distributor relationships, and private-label specialists serving retail chains. Capacity expansion and strategic partnerships represent the dominant competitive moves as players respond to IRA domestic content incentives.
Among integrated multinational suppliers, Clarios and GS Yuasa International Ltd occupy positions defined by OEM qualification scale and validation cycle depth. East Penn Manufacturing Company exemplifies the independent domestic manufacturer archetype, with distributor network density across the US and Canada anchoring aftermarket volume. Interstate Batteries represents the private-label specialist tier, with retail chain partnerships differentiating channel positioning.
| Leading Market Players |
|---|
| EnerSys |
| Crown Battery |
| Clarios |
| ACDelco |
| Interstate Batteries |
| East Penn Manufacturing Company |
| GS Yuasa International Ltd |
| FIAMM Energy Technology |
| Exide Technologies |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at North American AGM foundries shapes both supply concentration and price floors across the America SLI battery market. Scale advantages at Clarios and East Penn Manufacturing Company compress unit costs for enhanced flooded formats while elevating entry barriers for regional challengers seeking OEM qualification.
Pricing Analysis
NHTSA fuel-economy rules dictate the pricing tier structure across the America SLI battery market. Three-tier pricing structure across premium AGM, standard enhanced flooded, and economy conventional flooded levels separates procurement tiers. Price differentiation rests on cold-cranking amperage certification and start-stop system compatibility. Cost compression in economy flooded tiers is intensifying because fleet operators in the US Southeast corridor prioritize unit economics over cycle life. Commercial vehicle procurement departments exhibit the least price sensitivity due to telematics-verified warranty requirements.
Supply Chain Analysis
The United States and Canada anchor North American lead-acid battery manufacturing while Mexico concentrates maquiladora assembly operations for OEM qualification programs. Secondary lead smelting capacity draws from recycled battery feedstock and primary lead imports. Raw material dependencies center on lead bullion, sulfuric acid, and separator materials. Single-source vulnerability in secondary lead smelting clusters creates geographic supply risk during EPA enforcement audits. Distribution runs through independent jobber networks and direct manufacturer agreements with fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The America SLI battery market is entering a cyclical recovery phase driven by commercial fleet replacement acceleration under tightening EPA emissions enforcement. This regulatory-driven demand surge creates differentiated opportunities across incumbent defense, entrant positioning, and investment allocation.
For Market Incumbents: Consolidate distributor relationships in the Canadian aftermarket where independent networks remain underpenetrated relative to US density. Expand AGM production capacity to capture IRA domestic content incentives before qualification windows narrow. Lithium-ion substitution threats in premium passenger segments demand accelerated R&D in smart battery management systems to maintain technology differentiation. For New Entrants and Emerging Players: Telematics-integrated warranty services represent a service-layer gap where incumbents under-serve mid-size fleet operators. Target predictive battery monitoring solutions for regional trucking fleets in Texas and California corridors seeking compliance documentation. Partner with commercial vehicle telematics providers to bypass entrenched distributor relationships and establish direct fleet procurement channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AGM specialists with validated OEM qualification cycles over commodity flooded producers. Long-term viability hinges on recycling infrastructure control and separator material sourcing security. Watch for NHTSA rulemaking on heavy-duty start-stop mandates as the inflection signal for specification upgrade acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AGM Capacity Expansion | IRA domestic content credits accelerate North American foundry investments for OEM qualification. |
| Backward Integration into Lead Recycling | Closed-loop material recovery reduces EPA compliance risk and secures secondary lead supply. |
| Smart Battery Management System Development | Telematics integration enables predictive replacement scheduling valued by commercial fleet operators. |
| Canadian Aftermarket Distribution Partnership | Independent jobber networks in Ontario and Quebec offer white-space growth for enhanced flooded lines. |
| Marine Application Dual-Purpose Hybrid Launch | Great Lakes and Florida recreational boaters seek single-battery solutions for starting and house loads. |
Methodological Framework
A standing panel of OEM platform engineers, aftermarket distributor principals, fleet procurement managers, and EPA compliance officers provided ongoing calibration throughout the study. Primary interviews with Tier 1 supplier procurement teams and commercial vehicle maintenance directors were cross-validated against secondary sources including EPA enforcement databases, NHTSA fuel-economy rulemaking dockets, and vehicle production registration data. Bottom-up volume modeling triangulated with top-down value estimates across chemistry, application, and technology tiers.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled chemistry migration, application intensity, technology sophistication, and end-user channel structure. CAGRs were derived from segment-level growth trajectories weighted by base-year value shares. Industry-specific forecast inputs included start-stop system penetration curves and commercial fleet replacement cycle compression under EPA enforcement protocols.
Forecasts assume regulatory continuity in EPA emissions enforcement and NHTSA fuel-economy mandates; material policy shifts would require re-modeling. Specific risk factors that could revise projections include lithium-ion cost parity acceleration, lead price volatility spikes, and secondary smelting capacity constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
United Kingdom Rechargeable Battery Market
Batteries
Lithium Starters Market
Batteries
Forklift Battery Charger Market
Batteries
High Voltage Battery Market
Batteries
Battery Plate Market
Batteries
North America Lead-Acid Battery Separator for SLI Applications Market
Batteries
Marine Low-Voltage Battery Market
Batteries
Second-Life EV Battery Module Qualification Test Systems Market
Batteries
Global Coke Oven Batteries Market
Batteries
Lithium-Fluorinated Graphite Batteries Market
Batteries
Echelon Utilization of Power Battery Market
Batteries
Automotive AGM Battery Market
Batteries
Global Industrial Battery Market
Batteries
High Temperature NiMH Battery Market
Batteries
Elastic Battery Binders Market
Batteries
Solid Electrolyte Market