
 Nano Paints and Coatings Market | 2026-2036
Nano Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Nano Paints and Coatings Market Intelligence
A transition from multi-source procurement to single-source partnerships for specialized nanoparticle formulations is hardening. This shift favors suppliers with extensive R&D capabilities and proven material consistency. BASF leverages its vast chemical production scale to supply precursor materials for a range of nano coatings. In contrast, PPG Industries specializes in high-performance coatings for the aerospace and automotive sectors, while 3M differentiates through its advanced material science expertise.
Nano paints and coatings are liquid formulations incorporating particles typically smaller than 100 nanometers to achieve novel functionalities. These materials create surfaces with enhanced properties not possible with conventional coatings. Within product types, self-cleaning and antimicrobial coatings see widespread application in building facades and consumer electronics. Technology segments based on titanium dioxide and silica nanoparticles dominate volume due to their cost-effectiveness and established use in providing UV resistance and scratch resistance.
Regulatory frameworks, including the EU's REACH, the US EPA's oversight of novel chemical substances, and China's MEE standards, govern nanomaterial safety. These regulations mandate rigorous testing and disclosure, shaping product development cycles and market access. Consequently, navigating the evolving landscape of environmental health and safety rules for nanomaterials is a critical determinant of long-term commercial success for manufacturers.
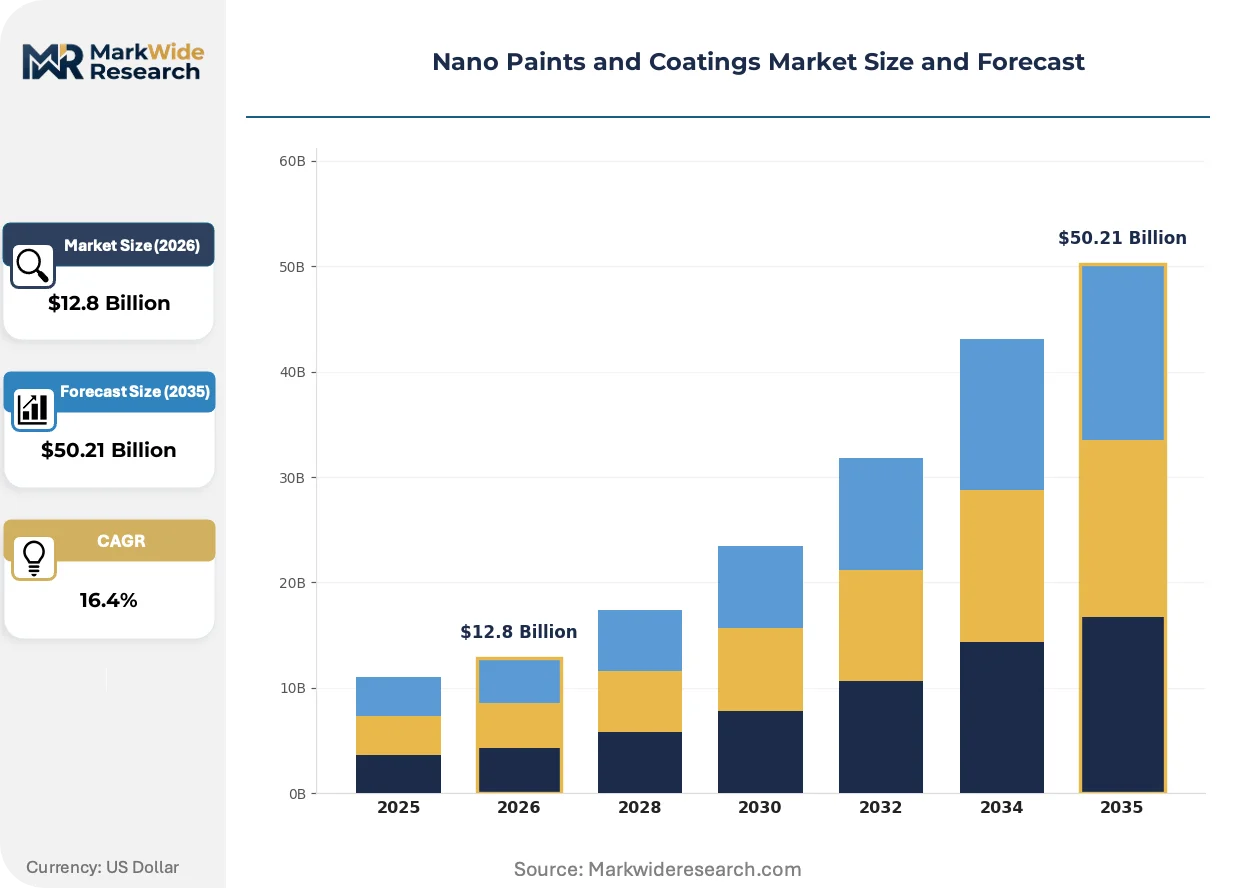
Market Dynamics
The central force shaping the market is the tension between demand for highly specialized nanoparticle formulations from single-source suppliers and the escalating complexity of navigating divergent global environmental, health, and safety regulations from bodies like ECHA and the EPA.
Growth Catalysts
- Aerospace Sector Demand:Requirements for lightweight, anti-corrosion, and thermally resistant coatings for aircraft components in manufacturing centers like the United States drive adoption of high-performance nano-coatings.
- Regulatory Incentives for Green Buildings:Policies under the EU Green Deal encourage the use of thermal insulating nano-paints on building facades to improve energy efficiency, creating a significant demand pull.
- Advanced Automotive Finishes:The automotive industry, particularly in technology-forward hubs like South Korea and Germany, seeks durable, self-healing, and aesthetically superior nano-paint finishes for premium vehicles.
Market Restraints
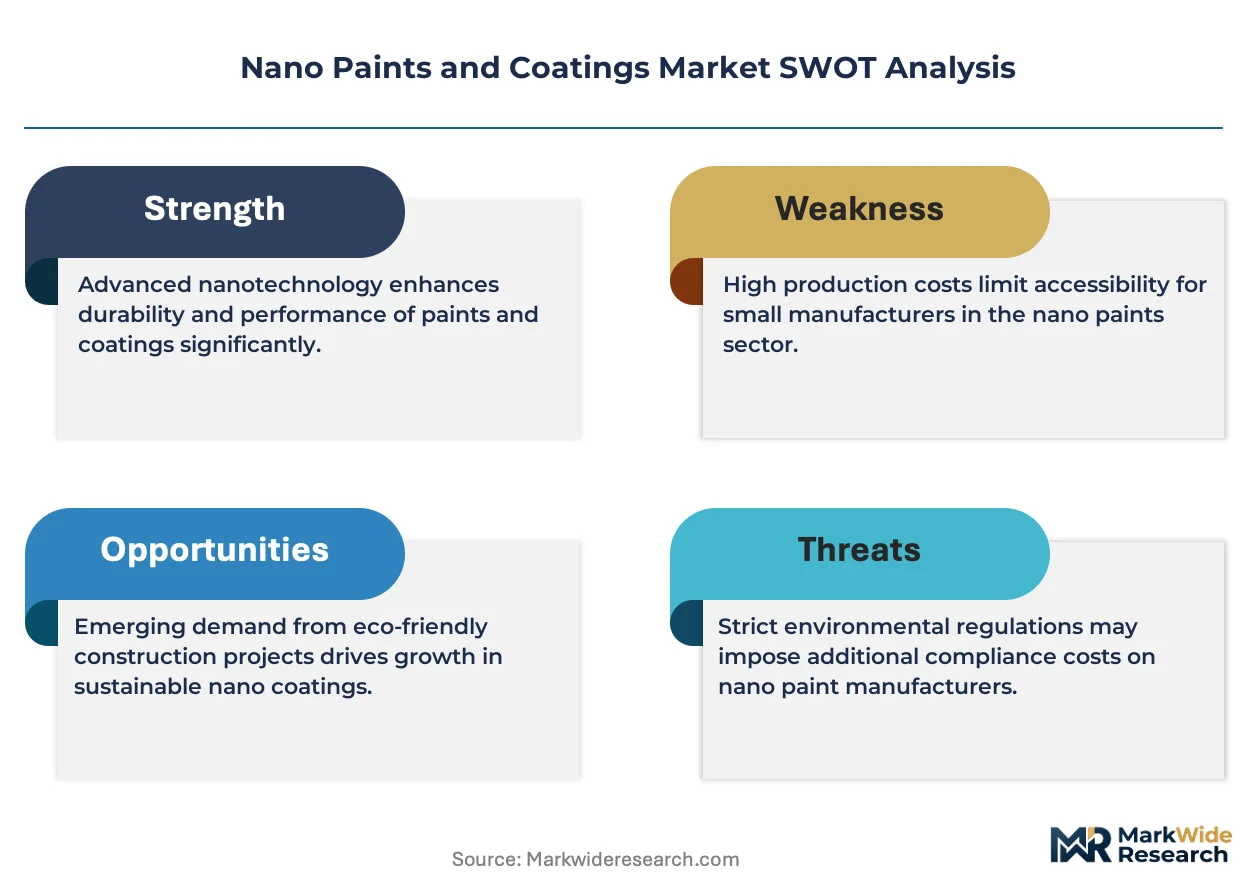
- High Production Costs:The elevated cost of synthesizing high-purity functional nanoparticles, such as carbon nanotubes and quantum dots, restricts their application to high-value, niche segments and limits broader market penetration.
- Stringent Regulatory Hurdles:Lengthy and expensive approval pathways under frameworks like the US EPA's oversight of new chemical substances create significant barriers to entry and slow the commercialization of novel nanomaterials.
- Technical Formulation Challenges:Preventing the agglomeration of nanoparticles within liquid coating formulations remains a persistent technical issue, impacting the stability, uniformity, and ultimate performance of the final product.
Strategic Opportunities
- Biomedical Applications:Developing biocompatible and antimicrobial nano-coatings for medical devices and implants represents a high-value opportunity, addressing needs for infection prevention and improved device integration within the human body.
- Smart Textiles Integration:The largely untapped market for functional textiles offers opportunities for integrating conductive, hydrophobic, or UV-blocking nano-coatings to create next-generation apparel and industrial fabrics.
- Energy Sector Enhancements:Applying anti-reflective and self-cleaning nano-coatings to solar panels can increase energy conversion efficiency and reduce maintenance costs, aligning with global renewable energy initiatives.
Industry Challenges
- Standardization Deficiencies:A lack of globally accepted ISO standards for characterizing and testing the properties and potential toxicity of nanomaterials complicates quality control, cross-border trade, and regulatory compliance.
- Specialized Talent Scarcity:The industry faces a shortage of material scientists, chemical engineers, and toxicologists with the specific interdisciplinary expertise required to develop and safely manage advanced nanomaterials.
- Intellectual Property Complexity:Navigating the dense and often overlapping patent landscape for nanoparticle synthesis and functionalization techniques presents a significant operational and legal challenge for new and existing manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano Paints and Coatings Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $50.21 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antimicrobial, Self-cleaning, UV Resistant, Scratch Resistant, Thermal Insulating, Anti-corrosion Technology: Silica Nanoparticles, Titanium Dioxide, Zinc Oxide, Carbon Nanotubes, Silver Nanoparticles, Nanoclays Application: Marine Vessels, Aerospace Components, Consumer Electronics, Building Facades, Renewable Energy Panels, Packaging Surfaces End User: OEM Manufacturers, Aftermarket Suppliers, Electronic Device Makers, Building Contractors, Energy Equipment Producers, Packaging Firms |
| Companies Covered | Artekya Teknoloji, Nanophase Technologies Corporation, PPG Industries, Inc., Aculon, Nanogate AG, BASF, Nanoshine Group Corp, 3M, Henkel AG and Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano Paints and Coatings Market Strategic Shifts & Innovations
Intensifying performance requirements from end-users are converging with a stricter global regulatory regime for chemical substances. This dynamic compels manufacturers to innovate beyond simple functional enhancements, focusing on lifecycle safety and material circularity for next-generation products.
Self-healing coatings incorporate microcapsules containing nanoparticle-based agents that are released upon impact to repair scratches and micro-cracks. The automotive and consumer electronics sectors are adopting these materials to enhance product durability and extend service life. This advanced functionality is absorbing development focus and investment previously directed toward purely passive protective coatings.
The EU's REACH regulation imposes stringent registration, evaluation, and authorization requirements for nanomaterials placed on the market. This mandate forces manufacturers to generate extensive safety and toxicology data prior to commercialization, which increases upfront R&D investment. Chemical producers in Germany and France are particularly affected, reorienting their innovation pipelines to prioritize compliance and transparency.
Consolidation of procurement for specialized coating formulations is becoming standard in high-tech industries. End-users in the aerospace and semiconductor sectors are moving away from multi-vendor sourcing, instead forming long-term partnerships with suppliers who can guarantee material consistency. This trend is most pronounced in North American and European supply chains where quality assurance and traceability are paramount.
Nano Paints and Coatings Market Segmentation
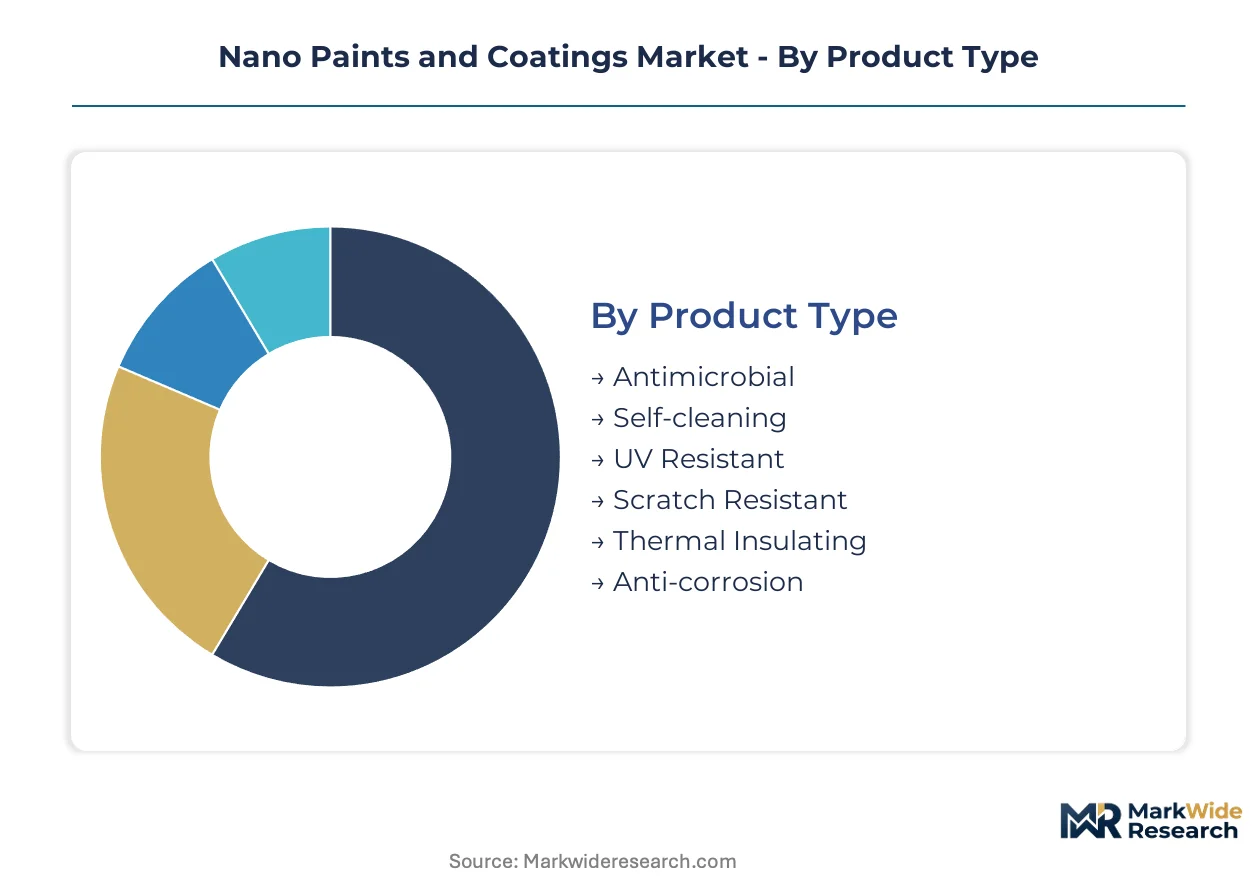
The Nano Paints and Coatings Market segments across diverse product types, underlying technologies, specific applications, and distinct end-user categories. This granular segmentation highlights the specialized functionalities and targeted demand within this advanced materials sector, reflecting the tailored solutions required for enhanced performance.
Product Type:
Nano paints and coatings offer distinct performance upgrades, driving replacement cycles in several industrial sectors.
- Self-cleaning:These coatings incorporate photocatalytic nanoparticles, often titanium dioxide, that react with UV light to break down organic pollutants on surfaces. Demand concentrates in building facades and solar panels, where reduced maintenance costs and sustained efficiency are critical for long-term asset value.
- Antimicrobial:Formulations containing silver or zinc oxide nanoparticles inhibit microbial growth on coated surfaces, preventing the spread of bacteria and fungi. Key demand areas include medical devices and consumer electronics, driven by stringent hygiene requirements and infection control protocols in Europe.
- UV Resistant:Nano-scale additives, such as titanium dioxide and zinc oxide, effectively block harmful ultraviolet radiation, protecting underlying materials from degradation. Outdoor structures and automotive exteriors benefit from these enhanced protective properties.
- Scratch Resistant:Coatings infused with hard nanoparticles like silica or alumina significantly improve surface durability and resistance to abrasion. This functionality is crucial for automotive clear coats and consumer electronic displays.
- Thermal Insulating:These coatings integrate aerogels or hollow glass microspheres at the nanoscale to reduce heat transfer through building envelopes. Energy efficiency mandates under the EU Green Deal drive adoption on building facades in Germany and France.
- Anti-corrosion:Nanoparticle-enhanced primers and topcoats provide superior barrier protection and active corrosion inhibition for metal substrates. Marine vessels and aerospace components require these robust protective layers to extend operational lifespan.
Self-cleaning coatings sit at the top of the volume ranking, with thermal insulating coatings climbing the fastest.
Technology:
The cost-effectiveness and established performance characteristics of various nanoparticle technologies influence their market penetration across different tiers.
- Silica Nanoparticles:These highly versatile particles provide excellent scratch resistance, hydrophobicity, and UV protection when incorporated into coating formulations. Their cost-effectiveness and widespread availability drive demand in automotive and consumer electronics applications across South Korea and Germany.
- Titanium Dioxide:Known for its photocatalytic and UV-blocking properties, titanium dioxide nanoparticles are fundamental to self-cleaning and UV-resistant coatings. Established use in building materials and paints ensures its significant market presence, particularly for large-scale architectural projects.
- Zinc Oxide:This technology offers broad-spectrum UV absorption and antimicrobial properties, making it valuable for sunscreens, personal care products, and some specialized coatings. Its non-toxic profile supports applications requiring direct human contact.
- Carbon Nanotubes:These advanced materials impart electrical conductivity, high strength, and lightweight properties to coatings for specialized applications. High production costs currently limit their use to niche, high-performance segments.
- Silver Nanoparticles:Recognized for potent antimicrobial efficacy, silver nanoparticles are integrated into medical device coatings and some consumer goods. Regulatory scrutiny and cost factors influence their deployment.
- Nanoclays:These layered silicates enhance barrier properties, flame retardancy, and mechanical strength in various polymer matrices. Packaging surfaces and fire-resistant materials utilize nanoclay technology for improved performance.
Supply concentration for titanium dioxide and silica nanoparticles drives their widespread availability in industrial applications.
Application:
The diverse functional requirements of various end-use applications dictate the specific nano coating formulations in demand.
- Aerospace Components:This sector requires lightweight, anti-corrosion, and thermally resistant coatings for critical aircraft parts, ensuring structural integrity and fuel efficiency. Manufacturing hubs in the United States and France are major consumers.
- Marine Vessels:Coatings for marine applications demand exceptional anti-corrosion, anti-fouling, and abrasion resistance to withstand harsh saltwater environments. Shipyards in South Korea and Japan frequently employ these advanced materials.
- Consumer Electronics:Nano coatings provide scratch resistance, antimicrobial properties, and enhanced aesthetics for smartphones, tablets, and other electronic devices. Manufacturers in China and South Korea integrate these functional finishes.
- Building Facades:Self-cleaning, thermal insulating, and UV-resistant nano paints contribute to energy efficiency and reduced maintenance for commercial and residential structures. European cities increasingly adopt these coatings for urban infrastructure.
- Renewable Energy Panels:Anti-reflective and self-cleaning nano-coatings enhance the efficiency and longevity of solar panels. Installations in Germany and China benefit from these performance-boosting treatments.
- Packaging Surfaces:Nanomaterials improve barrier properties against gases and moisture, extending shelf life and protecting contents for food and pharmaceutical packaging. Packaging firms globally seek these functional enhancements.
OEM manufacturers in the aerospace sector represent a significant customer base for specialized nano coatings.
End User:
Different end-user segments exhibit varying levels of maturity in adopting nano paints and coatings, impacting market penetration strategies.
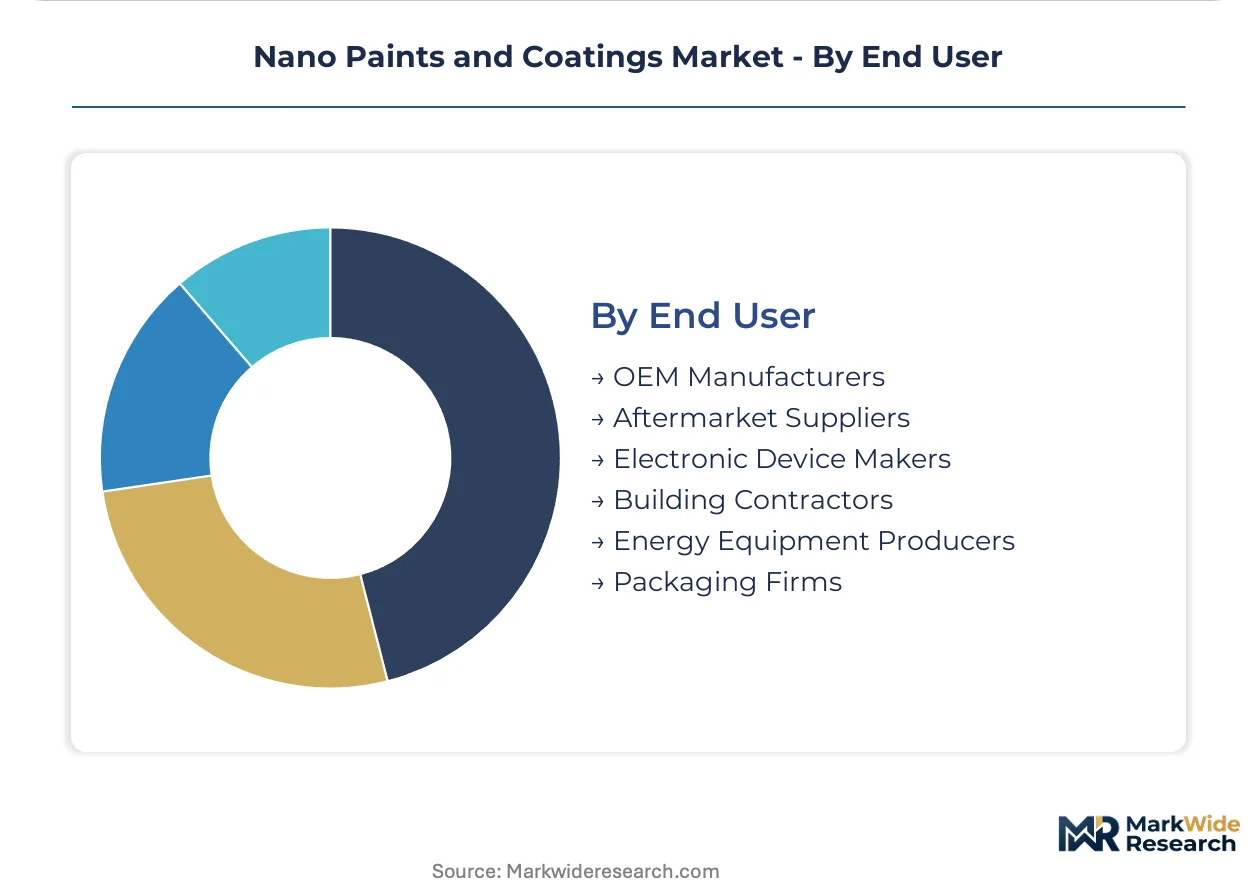
- OEM Manufacturers:Original Equipment Manufacturers in aerospace, automotive, and medical device industries demand highly specialized, consistent nano coating formulations for integration into their products. These long-term partnerships prioritize material consistency and performance validation.
- Aftermarket Suppliers:These entities provide nano coating solutions for repair, maintenance, and enhancement in sectors like automotive refinishing and building upkeep. Accessibility and ease of application are critical considerations for this segment.
- Electronic Device Makers:Companies producing consumer electronics integrate nano coatings to improve device durability, hygiene, and aesthetic appeal. Innovation cycles in this sector drive demand for novel surface functionalities.
- Building Contractors:Construction firms utilize thermal insulating and self-cleaning nano paints for new builds and renovation projects. Energy efficiency regulations and aesthetic considerations influence their procurement decisions.
- Energy Equipment Producers:Manufacturers of solar panels, wind turbines, and other energy infrastructure employ nano coatings to boost operational efficiency and extend asset lifespan. Performance metrics are paramount for these producers.
- Packaging Firms:Companies involved in producing packaging materials for food, pharmaceuticals, and other goods adopt nano-enhanced coatings for improved barrier properties and product protection. Regulatory compliance for direct food contact is a key factor.
The OEM sector typically commands higher-margin specialized formulations due to stringent performance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German advanced manufacturing hubs, alongside other key industrial centers, drive significant demand for nano paints and coatings across diverse high-value applications. The market's growth patterns reflect regional industrial strengths and regulatory landscapes. Localized innovation ecosystems and specific policy incentives further shape the adoption of these advanced material solutions.
Germany
Demand for thermal insulating nano-paints on building facades and advanced automotive finishes remains strong. The EU Green Deal actively encourages the use of energy-efficient building materials. Chemical producers in Bavaria and North Rhine-Westphalia are at the forefront of developing and supplying these specialized formulations.
South Korea
Advanced automotive finishes for premium vehicles and scratch-resistant coatings for consumer electronics are primary demand drivers. South Korea's national environmental standards for nanomaterials guide product development. Electronic device makers and automotive manufacturers in the Seoul Capital Area actively integrate these functional coatings.
United States
The aerospace sector's requirements for lightweight, anti-corrosion, and thermally resistant aircraft components fuel market expansion. The US EPA's rigorous oversight of new chemical substances mandates extensive testing. Aerospace manufacturing clusters in the Pacific Northwest and the Southeast demand high-performance nano-coatings.
China
Self-cleaning coatings for renewable energy panels and antimicrobial finishes for consumer electronics represent substantial market segments. China's MEE standards for nanomaterial safety influence manufacturing processes. Electronic device makers in the Pearl River Delta and solar panel manufacturers in Jiangsu province are key consumers.
France
Anti-corrosion coatings for critical aerospace components and thermal insulating paints for urban infrastructure projects generate robust demand. The EU's REACH regulation imposes stringent requirements for nanomaterials. Aerospace companies in Occitanie and chemical producers in Auvergne-Rhône-Alpes prioritize compliant and high-performance solutions.
Nano Paints and Coatings Market Key Industry Players
Global majors compete with regional champions across the nano paints and coatings market, creating a tiered competitive structure. The industry features large chemical conglomerates, specialized nano-coating providers, and advanced material science firms. Companies primarily engage in extensive R&D investment for specialized formulations and strategic partnerships to ensure consistent material supply.
Within the large chemical conglomerate archetype, BASF leverages its vast chemical production scale to supply precursor materials for a range of nano coatings. Specialized nano-coating providers like PPG Industries, Inc., focus on high-performance coatings for the aerospace and automotive sectors. Meanwhile, 3M exemplifies advanced material science firms, differentiating through its expertise in developing novel functional surfaces.
| Leading Market Players |
|---|
| Artekya Teknoloji |
| Nanophase Technologies Corporation |
| PPG Industries, Inc. |
| Aculon |
| Nanogate AG |
| BASF |
| Nanoshine Group Corp |
| 3M |
| Henkel AG and Co. KGaA |
Cost & Logistics Intelligence
High-purity functional nanoparticle synthesis costs directly influence the final pricing of specialized nano coatings, particularly for aerospace and biomedical applications, where performance guarantees command premium pricing. This upstream cost structure dictates downstream pricing tiers and supplier relationships.
Pricing Analysis
Input cost volatility for specialized nanoparticles directly impacts pricing stability across the nano paints and coatings market. The dominant pricing model is contract-based long-term offtake, especially for OEM manufacturers. Price differentiation stems from the certification level required for specific applications, such as aerospace standards, and the degree of customization for unique performance specifications. Pricing pressure stems from the elevated cost of synthesizing advanced nanomaterials like carbon nanotubes. OEM manufacturers are least price-sensitive due to stringent performance requirements, while aftermarket suppliers exhibit higher price sensitivity.
Supply Chain Analysis
Regional distribution centers for nano coating formulations facilitate localized supply to advanced manufacturing hubs. Geographic supply concentration for key raw materials centers in Germany, South Korea, and the United States. Raw material dependencies include titanium dioxide, silica, and specialized organic precursors for advanced functionalities. Single-source vulnerability for highly specialized nanoparticle formulations poses a structural supply chain risk. The dominant distribution model involves direct sales and technical support to OEM manufacturers, ensuring consistent material quality and integration assistance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nano paints and coatings market presents a margin-expansion opportunity, driven by the shift towards high-value, specialized formulations with enhanced performance characteristics.
For Market Incumbents: Lock in long-term supply agreements with aerospace and automotive OEMs to secure consistent demand for specialized formulations. This protects against margin pressure from generic coating alternatives. Invest in advanced R&D for next-generation self-healing and antimicrobial coatings. Leverage vertical integration into precursor material production as a strategic lever.
For New Entrants and Emerging Players: The EU Green Deal in Europe opens a window for new entrants to target the thermal insulating nano-paints segment. Focus on developing cost-effective, compliant solutions for building facades. A penetrable segment is smart textiles integration, offering conductive or hydrophobic coatings. A direct-to-market online channel for niche industrial applications provides a viable go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory hurdles for novel nanomaterials create barriers to entry for smaller players. This market offers long-term viability, particularly in high-performance industrial and biomedical applications. Target acquisition archetypes include specialized material science firms with proprietary nanoparticle synthesis techniques. The signal to watch is successful commercialization of advanced nanomaterials with clear regulatory approval.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding production capabilities for silica nanoparticles in South Korea supports growing automotive demand. |
| Backward Integration | Securing upstream control over titanium dioxide precursor supply enhances cost stability for self-cleaning coatings. |
| Joint Venture | Partnering with a European chemical producer facilitates market access for thermal insulating paints in Germany. |
| Technology Licensing | Licensing advanced self-healing coating technology accelerates product development for consumer electronics. |
| Green Manufacturing Transition | Adopting sustainable production processes for nanomaterials meets EU REACH compliance requirements. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build a comprehensive view of the nano paints and coatings market. This involved primary discussions with R&D directors, procurement leads at OEMs, chemical engineers, and regulatory affairs specialists. Secondary validation drew from industry association reports, patent filings, and environmental agency disclosures. A bottom-up approach was triangulated with top-down market sizing.
The forecast framework anchored the projection horizon to historical reference periods, ensuring continuity in market trend analysis. Segmentation dimensions modeled included product type, technology, application, end-user, and regional demand patterns. Compound annual growth rates were derived from a multi-factor regression analysis. Key forecast inputs included end-user industry production volumes and evolving regulatory compliance costs.
Revisions become necessary when significant shifts in nanomaterial regulation or raw material supply dynamics materialize. Forecasts reflect assumptions regarding technological adoption and economic stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Global Decorative Paints and Coatings Market
Paints & Coatings
Anti-Fungal and Anti-Bacterial Paints Market
Paints & Coatings
Water Color Market
Paints & Coatings
Paint Cans Market
Paints & Coatings
Aircraft Paint Market
Paints & Coatings
India Automotive OEM Coatings Market
Paints & Coatings
Bahrain Paints and Coatings Market
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
India Industrial Coatings Market
Paints & Coatings
Faux Paints and Coatings Market
Paints & Coatings
Polyolefin Resin Paints Market
Paints & Coatings
UAE Architectural Paints and Coatings Market
Paints & Coatings
Road Marking Paints and Coatings Market
Paints & Coatings
Faux Finish Coatings Market
Paints & Coatings
Mexico Paints and Coatings Market
Paints & Coatings
United Arab Emirates (UAE) Paints and Coatings Market