
 UAE Architectural Paints and Coatings Market | 2026-2036
UAE Architectural Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Architectural Paints and Coatings Market Analytics
Multi-source procurement for titanium dioxide and acrylic resins is repositioning how UAE-based manufacturers manage input cost volatility. Jotun leverages its coastal manufacturing presence in Dubai and Fujairah to sustain just-in-time delivery for mega-project contractors. National Paints Factories Co. Ltd. anchors its competitive stance through extensive distribution across the GCC, while Berger Paints Emirates Ltd. differentiates via specialized heat-reflective exterior coatings engineered for desert climates.
Architectural paints and coatings constitute liquid-applied protective and decorative films, typically formulated with binders such as acrylic or alkyd polymers, pigments, and solvents or water carriers, applied at dry-film thicknesses ranging from 25 to 100 microns to shield substrates from UV degradation, moisture ingress, and salt-laden air. Their primary commercial purpose centers on extending building envelope service life while enabling aesthetic customization in high-sunlight, high-humidity environments. Emulsion formulations now lead volume flows across residential applications, whereas solvent-based alkyd systems retain margin concentration in industrial and institutional maintenance cycles where durability specifications remain stringent. Water-based acrylic technologies are gaining fastest in commercial high-rises, driven by MOHAP indoor air quality mandates and contractor preference for shorter recoat intervals.
MOHAP enforces VOC emission ceilings aligned with Gulf Standardization Organization protocols, compelling reformulation across imported and locally manufactured product lines. Dubai Municipality's green building regulations and Abu Dhabi Quality and Conformity Council's product safety certifications further constrain market access for non-compliant suppliers. Stakeholders must monitor evolving emirate-level procurement rules that increasingly specify low-emitting materials for government-backed developments.
Market Dynamics
MOHAP's tightening VOC emission ceilings are compressing formulation timelines while megaproject contractors demand faster recoat cycles, creating a structural squeeze between compliance velocity and site productivity.
Growth Catalysts
- Water-based acrylic transition:MOHAP indoor air quality mandates are accelerating emulsion formulation adoption across commercial high-rise developments.
- Luxury hospitality pipeline:Dubai's premium facade coating specifications are expanding addressable premium volume for specialized exterior systems.
- Abu Dhabi megaproject concentration:Government-backed infrastructure clusters are generating sustained institutional demand for durable protective films.
Market Restraints
- Titanium dioxide cost volatility:Multi-source procurement requirements are squeezing margin stability for regional manufacturers dependent on Asian supply.
- Solvent-based alkyd displacement friction:Industrial maintenance cycles retain stringent durability specifications that water-based systems struggle to match.
- MOHAP certification timelines:Reformulation validation periods are extending product launch windows for imported and locally manufactured lines.
Strategic Opportunities
- Heat-reflective specialization:Desert climate engineering gaps are opening premium positioning for solar reflectance index-optimized exterior coatings.
- Fujairah coastal manufacturing leverage:Proximity to shipping corridors is enabling just-in-time delivery models for mega-project contractors.
- GCC distribution network expansion:Cross-border logistics integration is capturing spillover demand from Saudi megaproject pipelines.
Industry Challenges
- Formulation chemist scarcity:VOC-compliant binder expertise is concentrating among a limited pool of specialists, compressing R&D velocity.
- Recoat interval standardization:Divergent contractor specifications across emirates are fragmenting batch production efficiency.
- Salt-laden air testing protocols:Accelerated corrosion validation requirements are extending product qualification cycles for coastal applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Architectural Paints and Coatings Market |
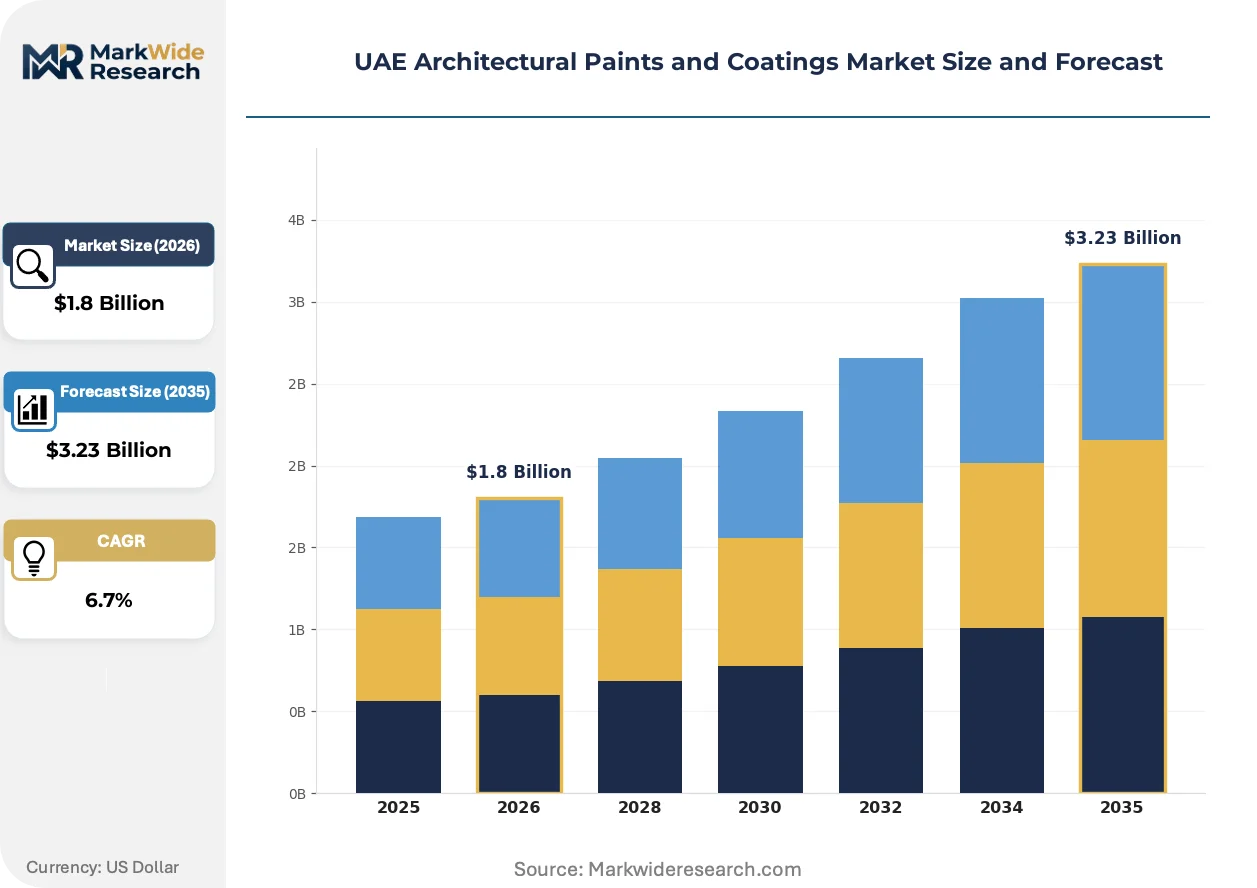
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion, Enamel, Primer, Stain Application: Residential, Commercial, Institutional, Industrial Finish Type: Matte, Gloss, Satin, Semi-Gloss Formulation: Acrylic, Alkyd, Water-Based, Solvent-Based |
| Companies Covered | Caparol Paints, Berger Paints Emirates Ltd., Jotun, PPG Industries Inc., Nippon Paint Holdings Co. Ltd., National Paints Factories Co. Ltd., Hempel A/S, Kansai Paint Middle East, AkzoNobel N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Architectural Paints and Coatings Market Evolving Landscape
Formulation chemistry, regulatory enforcement, and contractor procurement models are converging to reshape competitive positioning across emulsion and solvent-based product lines.
Nano-engineered self-cleaning coatings are rewriting facade maintenance economics for Dubai's luxury hospitality towers. Hotel operators are specifying hydrophilic photocatalytic surfaces at accelerated rates to reduce cleaning cycle frequency. The technology is compressing lifecycle service cost structures while enabling premium pricing for certified applicators.
MOHAP's alignment with Gulf Standardization Organization protocols is tightening market access for non-compliant imports. Dubai Municipality green building regulations and Abu Dhabi Quality and Conformity Council certifications are layering additional conformity requirements. Commercial high-rise segments are responding by consolidating supplier relationships around pre-qualified local manufacturers.
Direct contractor engagement is displacing traditional distributor-led specification for megaproject volumes. Large developers are establishing captive procurement frameworks that bypass wholesale channels. This pattern concentrates most visibly in Dubai's high-rise residential clusters where volume scale justifies dedicated supply agreements.
UAE Architectural Paints and Coatings Market Segmentation
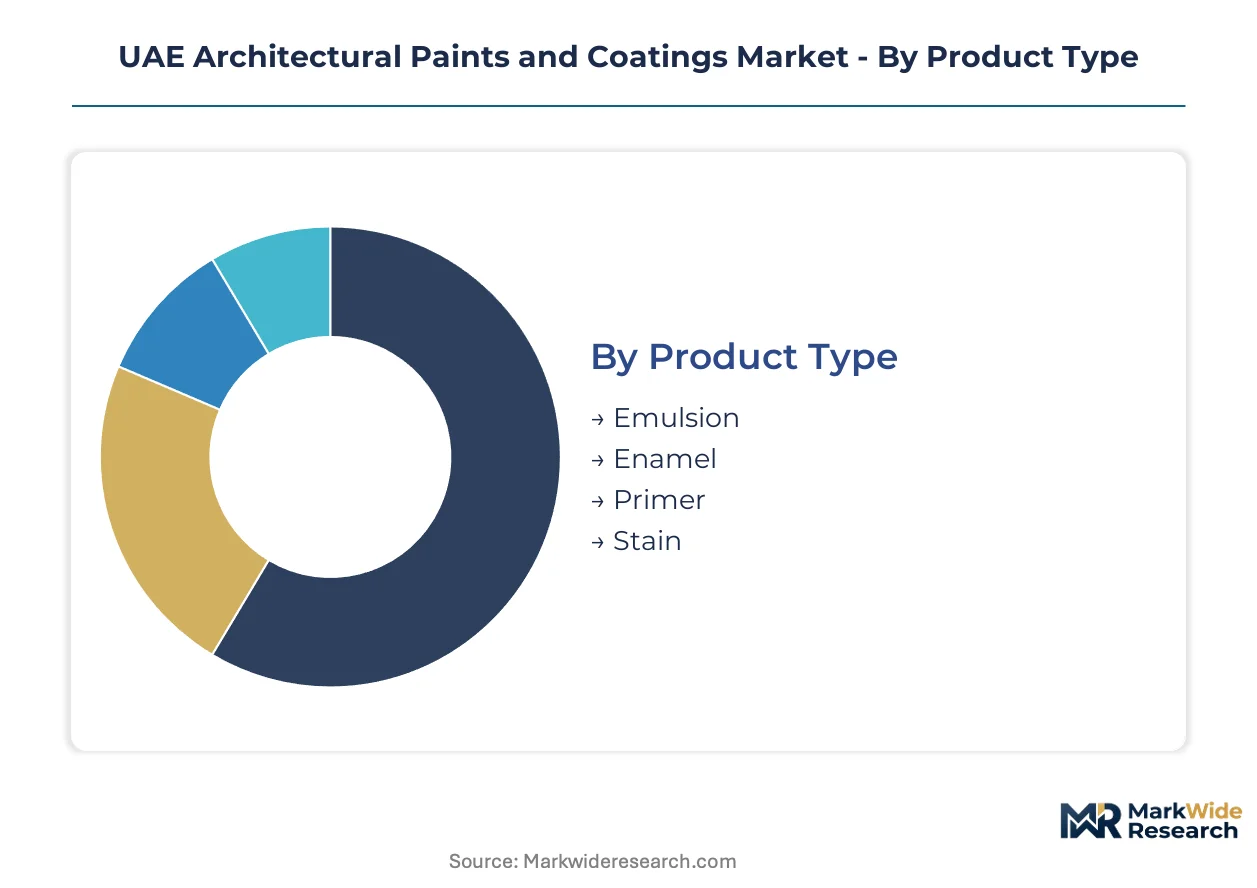
Segmentation in the UAE architectural paints and coatings market reveals distinct upgrade cycles across building typologies and regulatory compliance tiers. Each dimension exposes divergent specification pressures, from MOHAP-mandated formulation shifts to facade performance demands in Dubai's luxury hospitality pipeline.
Product Type:
Replacement cycles vary sharply across product categories, with interior emulsions refreshing every 5-7 years while exterior systems stretch toward 15-year intervals in the Gulf's harsh climate.
- Emulsion:Water-based acrylic and vinyl acetate copolymer dispersions dominate interior residential applications. Dubai's high-rise residential clusters are specifying low-VOC emulsions at accelerating rates as MOHAP indoor air quality mandates tighten compliance windows for contractors.
- Enamel:Hard, glossy alkyd or acrylic films provide abrasion-resistant finishes for trim, doors, and high-touch surfaces. Abu Dhabi's institutional megaprojects specify solvent-based enamel systems where durability requirements exceed water-based performance thresholds.
- Primer:Adhesion-promoting undercoats seal porous substrates and block tannin bleed. Demand concentrates in new construction phases across Dubai's luxury hospitality developments.
- Stain:Penetrating colorants protect wood and concrete while preserving natural texture. Niche applications persist in heritage restoration and premium villa segments.
Volume placements concentrate in Emulsion; the faster expansion belongs to Primer as megaproject completions accelerate substrate preparation phases.
Application:
Cost tier differentiation separates specification authority between owner-occupiers, developer-procurement desks, and government facilities managers.
- Residential:Single-family villas and apartment units drive emulsion volume through retail and contractor channels. Dubai's high-rise residential clusters are consolidating supplier relationships around pre-qualified local manufacturers with MOHAP certification.
- Commercial:Office towers, retail centers, and hospitality assets specify performance-grade exterior systems. Premium facade coatings for Dubai's luxury hospitality pipeline command specialized heat-reflective formulations.
- Institutional:Government buildings, healthcare facilities, and educational campuses enforce stringent VOC ceilings. Abu Dhabi's megaproject pipeline generates sustained demand for durable protective films with extended service life guarantees.
- Industrial:Warehousing and light manufacturing facilities prioritize chemical resistance and rapid recoat cycles. Solvent-based alkyd retention is strongest here where water-based durability gaps persist.
Commercial applications absorb the largest absolute volume; institutional procurement is climbing the fastest as government-backed infrastructure clusters expand.
Finish Type:
Surface sheen selection tracks maintenance economics and lighting conditions across interior and exterior exposure zones.
- Matte:Non-reflective films conceal surface imperfections in ceiling and wall applications. Residential interiors across Abu Dhabi and Dubai specify matte emulsions for aesthetic softness.
- Gloss:High-specularity finishes resist moisture and enable wipe-clean maintenance. Commercial kitchens, bathrooms, and trim details in hospitality assets specify gloss enamel systems.
- Satin:Intermediate sheen balances washability with subdued reflection. Living spaces in premium residential developments favor satin for versatility.
- Semi-Gloss:Moderate luster suits high-traffic corridors and institutional common areas. Dubai's commercial high-rises specify semi-gloss for durability without gloss glare.
Matte finishes dominate residential volume placements; semi-gloss specifications are gaining share fastest in commercial maintenance cycles.
Formulation:
Supply concentration among binder chemists and resin importers shapes competitive access across compliance tiers.
- Acrylic:Thermoplastic copolymers deliver UV resistance and color retention in exterior exposure. Water-based acrylic technologies are expanding most quickly in commercial high-rises under MOHAP mandates.
- Alkyd:Oil-modified polyester resins provide hardness and gloss in solvent-borne systems. Industrial maintenance cycles retain alkyd specifications where water-based alternatives fail durability tests.
- Water-Based:Emulsion systems using acrylic, vinyl, or hybrid binders meet tightening VOC limits. MOHAP alignment with Gulf Standardization Organization protocols is compressing formulation timelines for regional manufacturers.
- Solvent-Based:Hydrocarbon-carried alkyds and urethanes persist where rapid drying and chemical resistance outweigh emission concerns. Coastal manufacturing proximity in Fujairah sustains just-in-time delivery for solvent-based specialty contractors.
Water-based formulations capture the volume lead; acrylic binder systems are expanding most quickly as emulsion technology closes performance gaps with solvent alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Dubai's high-rise residential clusters and Abu Dhabi's megaproject pipeline, with spillover procurement extending into Sharjah's industrial zones and the Northern Emirates' construction corridors. MOHAP's VOC enforcement and emirate-level green building codes are reshaping supplier access across all sub-regions.
Dubai
Luxury hospitality developments and high-rise residential towers drive premium facade coating specifications. Dubai Municipality's green building regulations enforce low-emitting material mandates for commercial developments. The Downtown Dubai and Dubai Marina clusters are consolidating supplier relationships around pre-qualified local manufacturers with MOHAP certification.
Abu Dhabi
Government-backed infrastructure megaprojects generate sustained institutional demand for durable protective films. The Abu Dhabi Quality and Conformity Council layers additional product safety certification requirements beyond federal standards. The Al Reem Island and Saadiyat Island developments are specifying extended service life guarantees for exterior coating systems.
Sharjah
Industrial warehousing and light manufacturing facilities sustain solvent-based alkyd demand where durability specifications exceed water-based performance thresholds. The emirate's procurement frameworks increasingly reference MOHAP indoor air quality mandates for new construction phases. The Hamriyah Free Zone industrial cluster is attracting coating applicators serving cross-emirate maintenance contracts.
Northern Emirates
Fujairah's coastal manufacturing proximity enables just-in-time delivery models for mega-project contractors across the UAE. The emirate's shipping corridor access supports solvent-based specialty distribution to industrial maintenance segments. Ras Al Khaimah and Ajman construction corridors are absorbing spillover demand from Dubai and Abu Dhabi specification pipelines.
UAE Architectural Paints and Coatings Market Competitive Landscape
Capacity expansion dominates the current landscape as coastal manufacturing assets in Fujairah and Dubai scale to serve megaproject procurement timelines. The vendor base organizes around three tiers: global formulation houses with regional blending presence, GCC-anchored manufacturers with cross-border distribution networks, and specialized applicators serving premium facade segments. Two strategic archetypes predominate: coastal asset operators leveraging shipping corridor proximity, and certification-heavy players pre-qualified under emirate-level procurement frameworks. Competitive intensity centers on MOHAP compliance velocity and just-in-time delivery reliability rather than price alone.
Among the globally anchored formulation specialists, Jotun occupies a position exemplifying coastal manufacturing leverage, while Berger Paints Emirates Ltd. represents the heat-reflective specialization archetype engineered for desert climate applications. National Paints Factories Co. Ltd. anchors the GCC distribution network tier, illustrating how cross-border logistics integration captures spillover demand from Saudi megaproject pipelines. These three players sit within distinct competitive vectors—coastal proximity, climate-specific engineering, and regional distribution density—rather than competing head-to-head on identical specifications.
| Leading Market Players |
|---|
| Caparol Paints |
| Berger Paints Emirates Ltd. |
| Jotun |
| PPG Industries Inc. |
| Nippon Paint Holdings Co. Ltd. |
| National Paints Factories Co. Ltd. |
| Hempel A/S |
| Kansai Paint Middle East |
| AkzoNobel N.V. |
| Others |
Value Network & Pricing Analysis
MOHAP's VOC emission ceilings function as a gatekeeping mechanism that simultaneously constrains qualified supply pools and segments pricing tiers around certification status. Premium-grade water-based acrylic formulations command substantial markups over uncertified solvent-based alternatives, while bulk procurement contracts for megaproject developers compress margins at the volume end.
Pricing Analysis
Volume placements concentrate in economy-tier emulsion products where contractor procurement desks extract steep discounts for high-rise residential clusters, while margin concentration sits with specialized heat-reflective exterior systems specified for Dubai's luxury hospitality pipeline. Price differentiation separates MOHAP-certified formulations from non-compliant imports, with certification grade and after-sales technical support bundling driving tier separation. Pricing pressure stems from titanium dioxide cost volatility squeezing formulation economics, particularly for regional manufacturers dependent on Asian resin supply. Institutional buyers in Abu Dhabi's megaproject pipeline exhibit lowest price sensitivity due to extended service life guarantee requirements, whereas retail residential segments in Sharjah's industrial zones demonstrate acute sensitivity to per-liter costs.
Supply Chain Analysis
Single-source vulnerability sits with titanium dioxide feedstock concentrated among Chinese and Ukrainian suppliers, exposing UAE-based manufacturers to geopolitical disruption and currency fluctuation. Acrylic resin and vinyl acetate monomer dependencies draw from South Korean, Saudi, and Indian production hubs, with specialty additive packages sourcing from German and Swiss chemical houses. Regulatory restriction risk intensifies as MOHAP extends certification timelines and Dubai Municipality layers green building compliance requirements. Distribution runs through Fujairah's coastal manufacturing assets serving just-in-time megaproject delivery, supplemented by Jebel Ali port logistics for imported specialty formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE architectural paints and coatings market is accelerating into a vertical-integration race as players pursue captive control over resin supply to buffer titanium dioxide volatility and compress formulation costs.
For Market Incumbents: Anchor coastal manufacturing capacity in Fujairah to sustain just-in-time delivery advantages for Dubai and Abu Dhabi megaproject contractors. Deepen backward integration into acrylic resin production to offset Asian supply dependency, while accelerating MOHAP pre-qualification investments to defend specification share against emerging GCC-anchored competitors with cross-border distribution networks. For New Entrants and Emerging Players: The pricing gap between premium heat-reflective facade systems and economy-grade interior emulsions offers white-space capture opportunities in mid-tier commercial specifications. Target Sharjah's industrial maintenance segments where solvent-based alkyd displacement friction has slowed incumbent transition timelines. Pursue direct contractor engagement models that bypass traditional wholesale channels concentrated around Dubai's high-rise residential clusters. For Investors and Strategic Acquirers: MOHAP's alignment with Gulf Standardization Organization protocols is the leading indicator that certification-heavy players will consolidate specification authority across government-backed developments. Long-term viability favors acquisition targets with pre-qualified status under emirate-level procurement frameworks and coastal logistics infrastructure. Watch for accelerated consolidation signals when reformulation validation periods compress product launch windows for import-dependent suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Resin Production | Captive supply buffers UAE manufacturers against Asian titanium dioxide volatility and margin compression. |
| MOHAP Certification Pre-Qualification Investment | Pre-qualified status unlocks Dubai Municipality green building procurement and Abu Dhabi megaproject specifications. |
| Fujairah Coastal Capacity Expansion | Proximity to shipping corridors enables just-in-time delivery models for mega-project contractors across emirates. |
| Heat-Reflective Formulation R&D Specialization | Desert climate engineering gaps open premium positioning for solar reflectance index-optimized exterior coatings. |
| GCC Distribution Network Extension | Cross-border logistics integration captures spillover demand from Saudi megaproject pipelines and regional maintenance cycles. |
Research Methodology
Trade flow databases, MOHAP regulatory filings, and customs import records formed the secondary backbone of this analysis, supplemented by primary interviews with formulation chemists, megaproject procurement managers, and distribution channel partners across Dubai, Abu Dhabi, and Fujairah. Bottom-up and top-down triangulation validated volume estimates against emirate-level construction permit data and coating consumption benchmarks from comparable high-sunlight, high-humidity markets.
Bottom-up modeling aggregated product-level demand across emulsion, enamel, primer, and stain categories by application segment, while top-down analysis cross-checked aggregate market size against macro construction spending patterns and coating intensity ratios. Segmentation dimensions included formulation chemistry, finish type, building typology, and emirate-level regulatory compliance tier across the projection horizon. CAGRs were derived from regression analysis of historical construction completion rates and VOC mandate implementation timelines, with megaproject pipeline visibility and hospitality sector recovery curves serving as key forecast inputs.
Underlying measurement precision varies by segment; water-based acrylic volume flows carry tighter precision than solvent-based alkyd retention estimates where contractor specification fragmentation obscures data. Forecasts reflect assumptions around MOHAP enforcement consistency, titanium dioxide supply stability, and megaproject completion schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Insulating Paints and Coatings Market
Paints & Coatings
US Paints and Coatings Market
Paints & Coatings
North America Paints and Coatings Market
Paints & Coatings
South America Paints and Coatings Market
Paints & Coatings
Global Thinners and Paint Strippers Market
Paints & Coatings
GCC Paints and Coatings Market
Paints & Coatings
Global Exterior Architectural Coatings Market
Paints & Coatings
Europe Paints and Coatings Market
Paints & Coatings
Europe Paints and Coatings Additives Market
Paints & Coatings
Paints and Coatings Additives Market
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
Polyolefin Resin Paints Market
Paints & Coatings
Resins in Paints and Coatings Market
Paints & Coatings
Qatar Paints and Coatings Market
Paints & Coatings
Oman Paints and Coatings Market
Paints & Coatings
Global Aerosol Paints Market