
 Mexico Paints and Coatings Market | 2026-2036
Mexico Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Paints and Coatings Market Insights
Mexico is reconfiguring its paints and coatings supply base through expanded resin and additive production near Tamaulipas and Veracruz petrochemical hubs. PPG Industries leverages backward integration into automotive OEM coatings to sustain tier-one supplier status with assembly plants in Aguascalientes and San Luis Potosí. Sherwin-Williams anchors the architectural decorative segment through controlled distribution across twelve hundred retail points. Akzo Nobel differentiates via marine and protective coatings for PEMEX offshore platforms and Pacific port infrastructure.
Paints and coatings are liquid, powder, or high-solids formulations comprising binders, pigments, solvents, and additives that cure into adherent films providing corrosion resistance, aesthetic finish, or substrate protection. Water-based acrylic emulsions dominate interior architectural applications due to low VOC emissions and fast drying parameters. Epoxy and polyurethane formulations command premium positioning in industrial protective coatings for oil and gas infrastructure. Powder coatings represent the fastest-expanding formulation category as automotive and furniture manufacturers convert electrostatic lines to eliminate solvent handling and reduce hazardous waste streams.
SEMARNAT enforces NOM-086-ECOL on volatile organic compound limits, forcing reformulation of solvent-based alkyd products toward compliant water-borne and high-solids alternatives. PROFECO monitors labeling and performance claims under federal consumer protection standards, affecting import clearance and domestic brand positioning. COFEPRIS regulates antimicrobial additive claims in specialty coatings for healthcare facilities. Stakeholders must monitor upcoming NOM revisions and state-level environmental enforcement variations to align product portfolios with compliance trajectories and industrial customer procurement specifications.
Market Dynamics
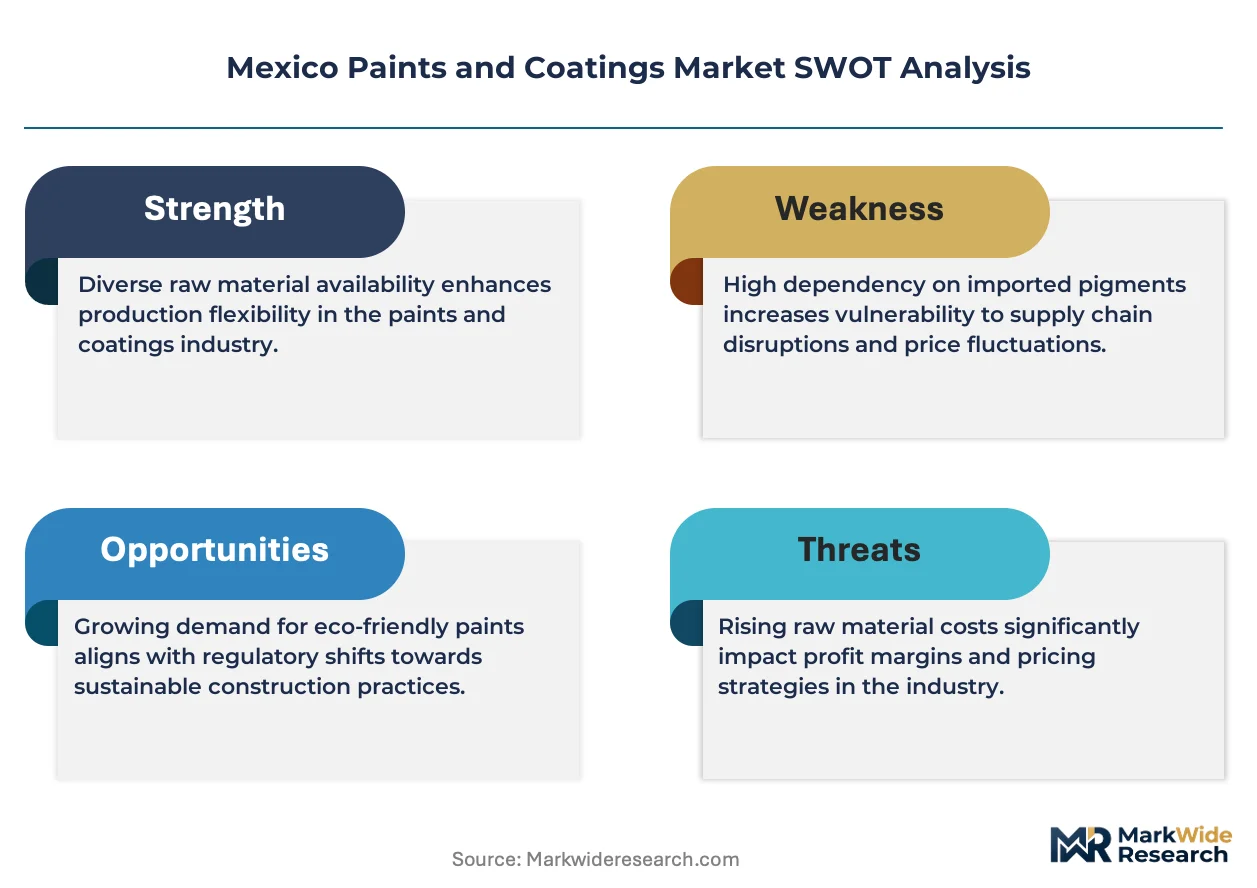
SEMARNAT's progressive tightening of NOM-086-ECOL VOC thresholds is forcing solvent-based alkyd producers toward water-borne and high-solids reformulations, compressing margins while opening premium positioning for compliant alternatives.
Growth Catalysts
- Automotive OEM expansion:Assembly plants in Aguascalientes and San Luis Potosí are scaling coating specifications for tier-one supplier qualification, pulling demand for electrocoat and basecoat systems.
- NOM-086-ECOL compliance deadlines:The regulation's phased VOC reduction mandates are accelerating capital deployment into compliant resin and additive production near Tamaulipas petrochemical infrastructure.
- Powder coating line conversions:Furniture and appliance manufacturers are eliminating solvent handling costs through electrostatic powder adoption, reducing hazardous waste disposal liabilities.
Market Restraints
- Titanium dioxide price volatility:Pigment input costs fluctuate with global ore supply disruptions, squeezing formulation margins for mid-tier decorative producers.
- Import dependency for specialty resins:Epoxy and polyurethane raw material concentration in US Gulf Coast and Asian supply nodes exposes Mexican blenders to freight and tariff friction.
- Technical limitation in high-performance marine:Domestic formulators lack certified NORSOK-compliant systems for deepwater PEMEX platform specifications, ceding share to imported protective coatings.
Strategic Opportunities
- Yucatán Peninsula infrastructure:Maya Train corridor maintenance depots and port modernization at Progreso are generating protective coating specifications for rail and marine assets.
- Antimicrobial healthcare coatings:COFEPRIS-regulated additive claims in hospital and clinic specifications are opening specialty formulation segments with premium pricing.
- Digital color-matching kiosks:Architectural decorative channels are deploying spectrophotometer-linked tinting systems in retail points, compressing custom order turnaround from days to hours.
Industry Challenges
- Formulation chemist scarcity:Mexican technical universities produce insufficient graduates trained in water-borne polymer science and UV-cure chemistry, constraining R&D pipeline velocity.
- COFEPRIS antimicrobial claim timelines:Regulatory review cycles for specialty coating registrations extend 14-18 months, delaying product launches and freezing working capital in pre-approval inventory.
- Legacy solvent line stranded assets:Smaller decorative producers face capex burdens to retrofit spray booths and curing ovens for compliant low-VOC operation, accelerating consolidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Paints and Coatings Market |
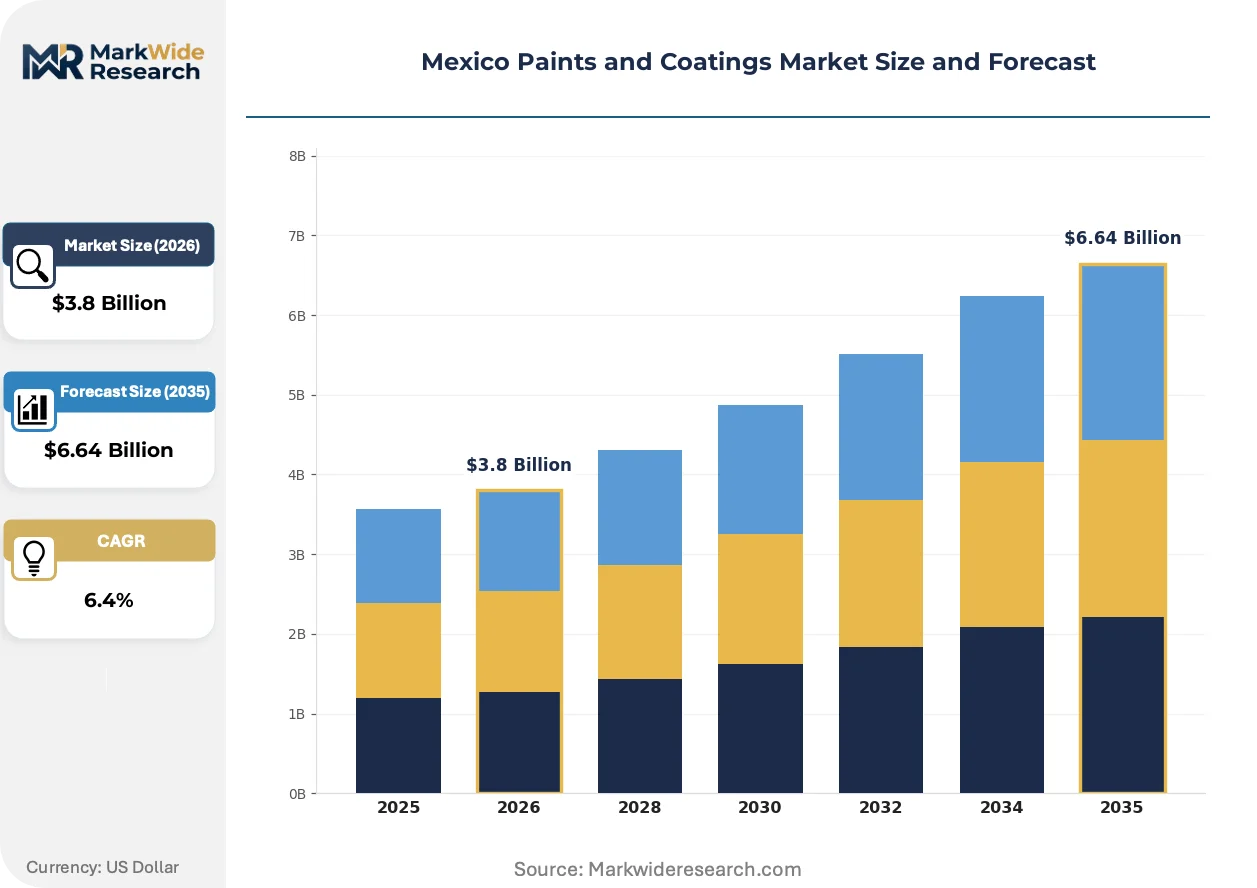
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Epoxy, Alkyd End User: Construction, Automotive, Furniture, Aerospace Formulation: Water-based, Solvent-based, Powder, High-solids Application: Decorative, Protective, Industrial, Specialty |
| Companies Covered | PPG Industries, Inc., The Sherwin-Williams Company, Akzo Nobel N.V., Axalta Coating Systems, Berel Mexico, BASF SE, Nippon Paint Holdings Co., Ltd., Pinturas Osel, S.A. DE C.V, WEG S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Paints and Coatings Market Trends and Innovations
Formulation science and compliance architecture are converging to reshape competitive positioning, with water-borne technologies, regulatory automation, and channel digitization emerging as the dominant vectors of change.
UV-curable coating chemistry is migrating from narrow wood-furniture applications into broader industrial metal finishing and automotive plastic component segments. Tier-two suppliers in Guanajuato are piloting LED-UV lines for dashboard and trim pieces, eliminating thermal curing energy costs while achieving sub-60-second cycle times. This technology compression is enabling just-in-sequence delivery to assembly plants that previously required 24-hour inventory buffers for conventional bake cycles.
NOM-086-ECOL's 2024-2027 implementation schedule is forcing alkyd and nitrocellulose decorative producers into accelerated reformulation programs. SEMARNAT enforcement inspections at Mexico City and Monterrey manufacturing facilities are triggering production stoppages for non-compliant solvent inventories. The architectural segment is responding fastest, with major distributors delisting high-VOC interior enamels ahead of statutory deadlines to preempt PROFECO consumer protection actions.
Specification-driven purchasing is consolidating decision authority among procurement teams at automotive OEMs and PEMEX contractors, displacing traditional distributor influence over product selection. Technical data sheet compliance with NORSOK, ISO 12944, and customer-specific lab test protocols now precedes price negotiation in contract awards. This shift is most visible in the Querétaro aeronautics cluster, where Bombardier and Airbus suppliers must pre-qualify coating systems through 18-month validation cycles before volume purchase authorization.
Mexico Paints and Coatings Market Segmentation
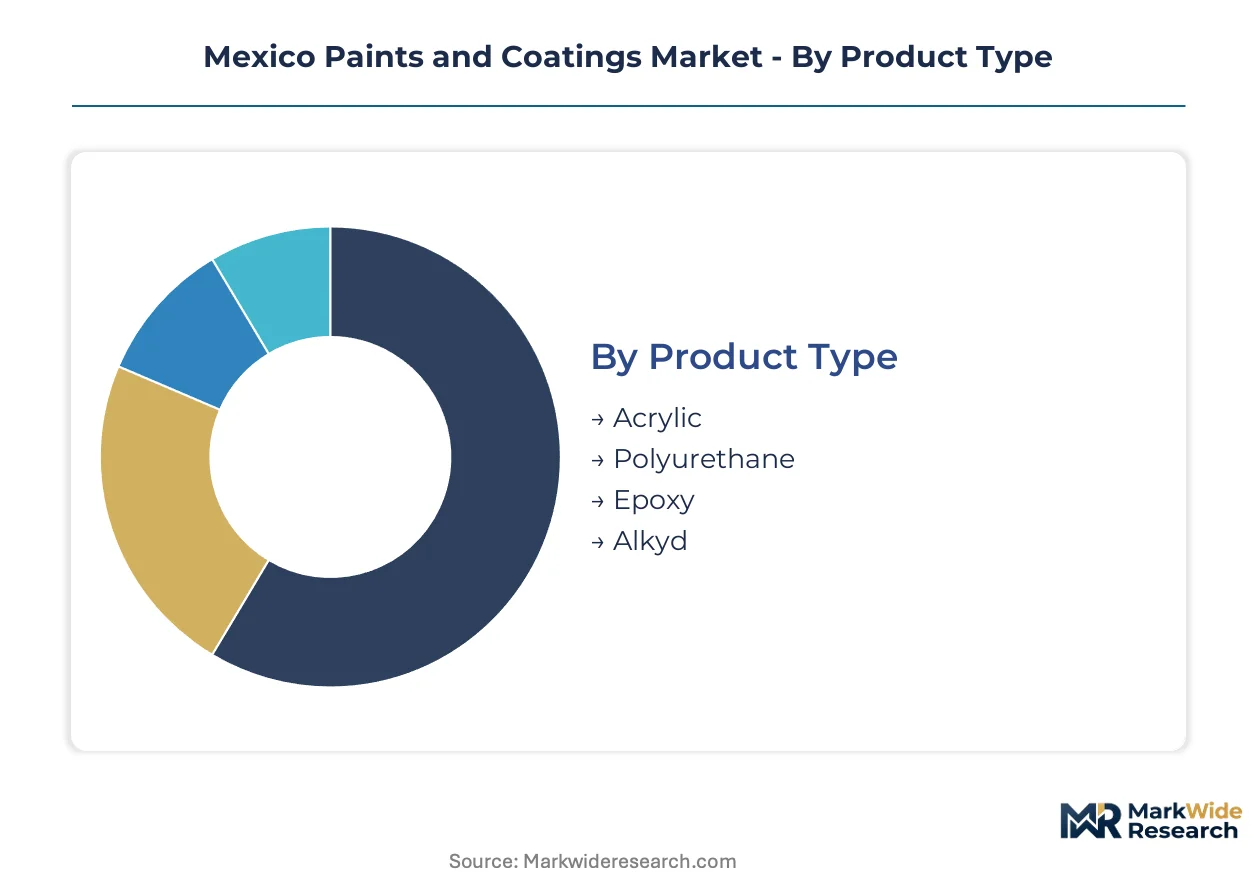
Segmentation in Mexico's paints and coatings market reveals how formulation chemistry, end-use specifications, and regulatory compliance intersect to determine procurement patterns. Each dimension carries distinct margin profiles and technical barriers that shape supplier positioning across industrial corridors.
Product Type:
Resin chemistry defines performance ceilings and environmental compliance trajectories across Mexican manufacturing.
- Acrylic:Water-borne acrylic emulsions dominate interior architectural applications through rapid drying and low VOC profiles. Demand concentrates in Mexico City metropolitan residential construction, where SEMARNAT enforcement of NOM-086-ECOL has accelerated displacement of alkyd alternatives.
- Polyurethane:Two-component polyurethane systems command premium positioning in industrial flooring and automotive refinish segments. Guanajuato automotive cluster plants specify aliphatic polyurethane topcoats for exterior durability, pulling imports of isocyanate curing agents from US Gulf Coast suppliers.
- Epoxy:High-build epoxy formulations serve PEMEX infrastructure and chemical processing facilities requiring chemical resistance.
- Alkyd:Solvent-borne alkyd resins face reformulation pressure as NOM-086-ECOL phases down permissible VOC content.
The dominant share belongs to Acrylic, while Polyurethane is closing the gap fastest.
End User:
Customer procurement authority varies sharply by vertical, with specification complexity determining supplier qualification barriers.
- Construction:Architectural decorative coatings flow through distributor networks to residential and commercial contractors, with color-matching services and bulk pricing driving loyalty.
- Automotive:OEM assembly plants in Aguascalientes and San Luis Potosí mandate electrocoat and basecoat systems qualified through 18-month validation cycles.
- Furniture:Guanajuato and Querétaro wood processing facilities are converting spray lines to UV-curable and powder coatings to eliminate solvent handling costs.
- Aerospace:Querétaro aeronautics cluster suppliers must certify coating systems to NORSOK and Airbus specification protocols before volume authorization.
Construction maintains volume leadership, though Automotive generates the steepest margin expansion.
Formulation:
Technology migration patterns reflect capital deployment responding to SEMARNAT compliance deadlines and hazardous waste liability reduction.
- Water-based:Acrylic and polyurethane dispersions lead interior architectural growth, with major distributors delisting high-VOC solvent alternatives ahead of statutory deadlines.
- Solvent-based:Alkyd and nitrocellulose formulations retreat to industrial maintenance applications where drying speed outweighs environmental compliance costs.
- Powder:Thermoset powder coatings represent the steepest expansion trajectory as appliance and furniture manufacturers eliminate solvent handling and reduce hazardous waste streams.
- High-solids:Reduced-solvent formulations bridge compliance and performance in marine and protective segments where water-borne chemistry lacks durability certification.
Water-based formulations hold installed base dominance, while Powder is gaining share fastest through line conversion investments.
Application:
Functional purpose determines specification intensity, with protective and specialty segments requiring certified performance data preceding price negotiation.
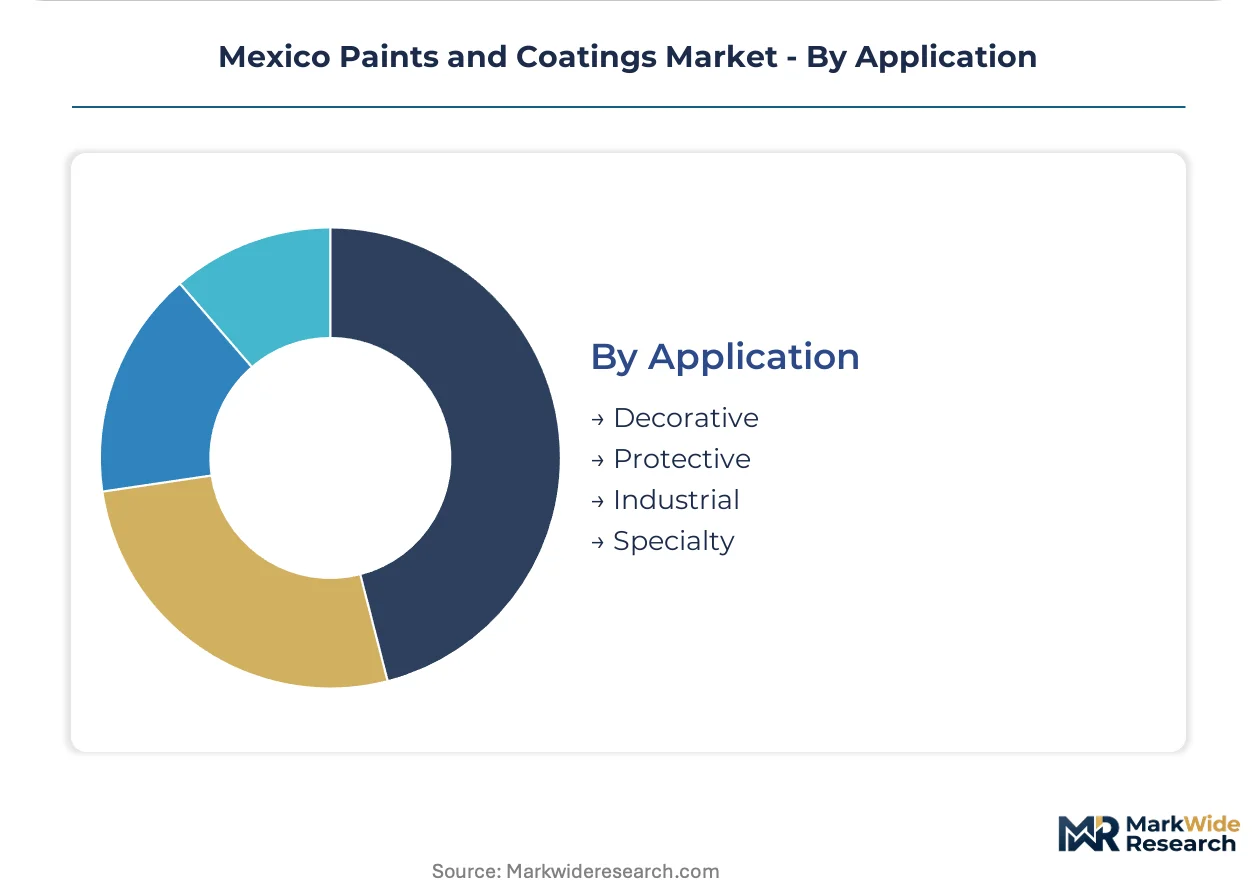
- Decorative:Interior and exterior architectural finishes distribute through twelve hundred retail points, with color-matching kiosks compressing custom order turnaround.
- Protective:PEMEX offshore platforms and Pacific port infrastructure specify epoxy and polyurethane systems compliant with ISO 12944 corrosion protection standards.
- Industrial:Manufacturing facility maintenance coatings balance chemical resistance with application window flexibility.
- Specialty:Antimicrobial healthcare coatings regulated by COFEPRIS command premium pricing in hospital and clinic specifications.
Decorative commands volume concentration, though Protective exhibits the most rapid specification upgrading.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Resin and additive production clusters near Tamaulipas and Veracruz petrochemical infrastructure anchor supply-side capacity. Mexican formulators source specialty isocyanates and epoxy precursors through Gulf Coast pipeline networks while SEMARNAT compliance deadlines reshape regional demand patterns.
Bajío Region
Automotive OEM coating demand concentrates in Aguascalientes and San Luis Potosí assembly corridors. NOM-086-ECOL enforcement accelerates water-borne basecoat adoption among tier-one suppliers. Guanajuato furniture manufacturers pilot UV-curable lines for dashboard and interior trim finishing.
Nuevo León
Industrial protective coatings serve Monterrey metropolitan manufacturing and chemical processing facilities. SEMARNAT state-level inspection protocols trigger production stoppages for non-compliant solvent inventories. Apodaca and Escobedo industrial parks host powder coating conversion projects for appliance exporters.
Querétaro
Aeronautics cluster suppliers endure 18-month NORSOK validation cycles before coating system authorization. COFEPRIS antimicrobial claim registrations face 14-18 month review timelines for healthcare facility specifications. El Marqués aerospace suppliers pre-qualify polyurethane topcoats through Airbus technical protocols.
Mexico City Metro
Architectural decorative volume flows through twelve hundred retail distribution points with spectrophotometer-linked tinting systems. PROFECO consumer protection monitoring affects import clearance for non-compliant labeling. Iztapalapa and Tlalnepantla manufacturing facilities face accelerated alkyd reformulation deadlines.
Yucatán Peninsula
Maya Train corridor maintenance depots generate protective coating specifications for rail infrastructure. Progreso port modernization projects specify ISO 12944-compliant epoxy systems for marine asset protection. Mérida construction activity pulls interior acrylic emulsion demand through distributor networks.
Mexico Paints and Coatings Market Competitive Landscape
Multinational coating formulators and domestic blenders split the market between specification-driven industrial segments and price-sensitive decorative channels. Three archetypes dominate: global integrated suppliers with captive resin production, regional distributors controlling architectural retail access, and specialty formulators serving certified protective applications. Competitive moves concentrate on backward integration into automotive OEM qualification programs and digital color-matching infrastructure deployment.
Within the multinational tier, PPG Industries, Sherwin-Williams, and Akzo Nobel exemplify integrated positioning. These entities occupy anchor positions across automotive OEM, architectural decorative, and marine protective segments. Domestic specialists including Berel Mexico and Pinturas Osel represent regional-scale fabrication capabilities. The competitive terrain rewards qualification timelines and compliance architecture over pure price positioning.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Akzo Nobel N.V. |
| Axalta Coating Systems |
| Berel Mexico |
| BASF SE |
| Nippon Paint Holdings Co., Ltd. |
| Pinturas Osel, S.A. DE C.V |
| WEG S.A. |
| Others |
Pricing and Supply Chain Analysis
Tamaulipas-Monterrey freight corridors impose diesel surcharge volatility that compresses margins for epoxy resin blenders while amplifying price spreads between Gulf Coast-imported specialty coatings and locally formulated water-borne alternatives. This logistics cost dynamic concentrates pricing power among petrochemical-integrated multinationals and forces mid-tier decorative producers toward aggressive distributor rebate programs.
Pricing Analysis
NOM-086-ECOL dictates the pricing tier structure across Mexican coatings procurement, separating NORSOK-certified protective systems for PEMEX infrastructure from standard architectural emulsions and economy-grade maintenance alkyds. Certification grade and volume scale drive price differentiation, with automotive OEM electrocoat contracts commanding premium positioning against price-sensitive residential repaint channels. Cost compression in solvent-borne decorative tiers is intensifying because SEMARNAT enforcement triggers reformulation capex burdens, while specification-driven aerospace buyers exhibit least price sensitivity due to 18-month qualification lock-ins.
Supply Chain Analysis
Extended payment terms from 90 to 120 days now dominate raw material procurement, with supply-chain finance facilities bridging working capital gaps for isocyanate and titanium dioxide imports. Geographic supply concentration centers on US Gulf Coast petrochemical complexes, Chinese epoxy resin manufacturers, and Korean specialty additive producers. Raw material dependencies include aromatic isocyanates, rutile titanium dioxide, and acrylic monomers. Single-source vulnerability persists for aliphatic polyurethane curing agents funneled through Houston-Tamaulipas pipeline networks. Distribution runs through twelve hundred retail tinting points for architectural segments and direct technical sales for automotive OEM qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's paints and coatings sector is recovering from cyclical trough conditions as automotive assembly capacity expansion and NOM-086-ECOL compliance deadlines restock demand pipelines. Capital deployment into compliant resin infrastructure signals durable recovery momentum.
For Market Incumbents: Harden qualification timelines at Querétaro aeronautics and Aguascalientes automotive clusters to preempt emerging Asian supplier encroachment. Anchor backward integration into Tamaulipas petrochemical corridors to secure captive isocyanate supply against US Gulf Coast tariff friction. Defensive consolidation through distressed mid-tier alkyd producer acquisition accelerates capacity rationalization ahead of SEMARNAT enforcement waves. For New Entrants and Emerging Players: Pursue antimicrobial healthcare coating registrations through COFEPRIS pathways, where 14-18 month review timelines deter incumbent reallocation of R&D resources. Target Yucatán Peninsula protective specifications for Maya Train maintenance depots and Progreso port modernization, segments where NORSOK certification requirements remain underpenetrated by domestic formulators. Deploy spectrophotometer-linked tinting kiosks as channel entry wedge against established distributor networks. For Investors and Strategic Acquirers: Specialty formulators with captive UV-curable chemistry expertise present acquisition targets given LED-UV line conversion momentum in Guanajuato furniture and automotive trim segments. Long-term viability hinges on water-borne polymer science capabilities and SEMARNAT compliance architecture rather than legacy solvent infrastructure. Monitor NOM-086-ECOL revision announcements as inflection signal for stranded asset risk concentration among decorative producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive acrylic emulsion supply secures margin protection against Gulf Coast feedstock volatility. |
| NORSOK Certification Investment | PEMEX deepwater platform specifications require certified systems that exclude uncertified competitors. |
| Powder Coating Line Conversion | Electrostatic thermoset adoption eliminates solvent handling costs for appliance exporters in Nuevo León. |
| Digital Color-Matching Deployment | Spectrophotometer-linked tinting kiosks compress custom order turnaround from days to hours. |
| COFEPRIS Antimicrobial Registration | Hospital and clinic specifications command premium pricing for validated additive claims. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEMARNAT enforcement records, PROFECO consumer protection filings, and customs import data for specialty resin categories. Primary interviews engaged formulation chemists at multinational coating producers, procurement directors at Aguascalientes automotive assembly plants, distribution channel managers controlling architectural retail networks, and technical specification officers at PEMEX infrastructure contractors. Secondary validation drew from COFEPRIS antimicrobial registration databases, NORSOK compliance certification lists, and SEC 10-K disclosures from listed coating manufacturers. Bottom-up volume estimates from end-use consumption patterns triangulate against top-down production capacity assessments across Tamaulipas and Veracruz petrochemical corridors.
Forecast inputs include resin chemistry migration rates, NOM-086-ECOL compliance phase-in schedules, automotive assembly plant coating specifications, and infrastructure project procurement pipelines. Segmentation dimensions span resin type, formulation technology, end-use vertical, and regional industrial corridor. CAGRs derive from regression analysis against historical consumption patterns adjusted for regulatory enforcement intensity. Industry-specific forecast inputs incorporate UV-curable line conversion rates in furniture manufacturing and powder coating adoption curves among appliance exporters.
Macroeconomic conditions sit as an overlay; deviation in peso-dollar exchange rates, automotive production schedules, or federal infrastructure appropriations would shift the trajectory. Forecasts reflect assumptions about SEMARNAT enforcement consistency and petrochemical feedstock pricing stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
Food Grade Epoxy Paint Market
Paints & Coatings
Decorative Paints Market
Paints & Coatings
Global Wood Coatings Market
Paints & Coatings
Middle East and Africa Floor Coatings Market
Paints & Coatings
Small Paint Pail Market
Paints & Coatings
Resins in Paints and Coatings Market
Paints & Coatings
Cement Paints Market
Paints & Coatings
Morocco Paints and Coatings Market
Paints & Coatings
Europe Paints and Coatings Market
Paints & Coatings
Global Decorative Paints and Coatings Market
Paints & Coatings
Aircraft Paint Market
Paints & Coatings
Global Antifouling Paints and Coatings Market
Paints & Coatings
Global Paints and Coatings Fillers Market
Paints & Coatings
South America Paints and Coatings Market
Paints & Coatings
India Automotive Paints and Coatings Market