
 Mexico Industrial Wood Coatings Market | 2026-2036
Mexico Industrial Wood Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Industrial Wood Coatings Market Foresight
High-performance polyurethane specifications are redrawing competitive boundaries in Mexican industrial wood finishing. AkzoNobel NV leverages its automotive-adjacent color-matching expertise to serve furniture OEMs demanding consistent batch-to-batch clarity. PPG Industries Inc anchors supply security through backward integration into resin intermediates, reducing exposure to imported acrylic acid volatility. Jotun differentiates via marine-grade UV stability technologies adapted for tropical hardwood export cabinetry.
Mexico industrial wood coatings comprise solvent-borne and water-borne film-forming systems engineered to protect timber substrates against moisture, abrasion, and photodegradation while delivering specified gloss levels and color retention; formulations typically incorporate acrylic or polyurethane resin binders at solids contents ranging from 25% to 45% depending on application method and regulatory limits. Acrylic water-borne systems lead volume in furniture applications where fast-dry schedules and low odor support just-in-line manufacturing, while polyurethane segments capture premium margin pools in flooring and musical instrument finishing where hardness and chemical resistance command price premiums. Stain and varnish categories occupy mature positions in artisanal and restoration contractor channels with limited formulation innovation.
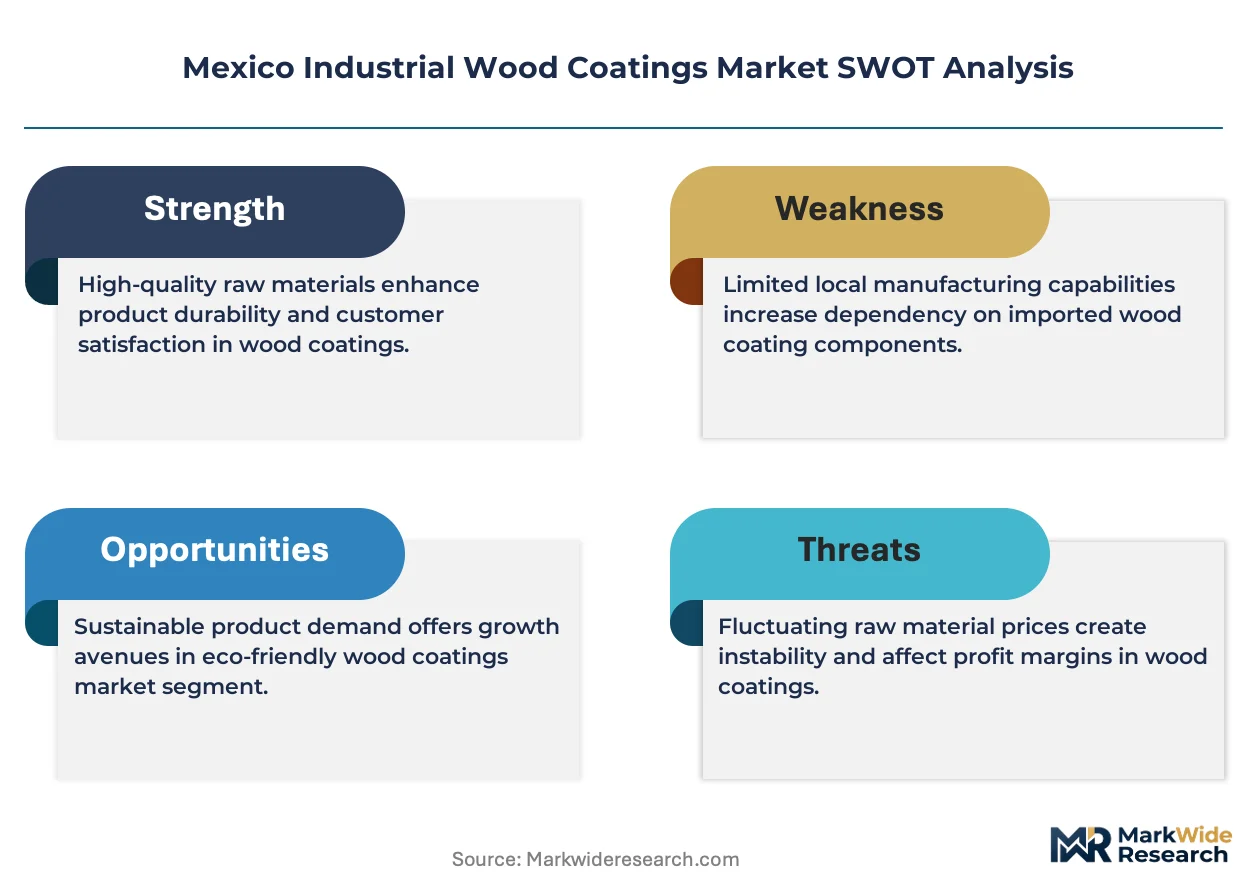
PROFEPA enforces NOM-085-SEMARNAT-2011 VOC emission standards that constrain solvent-borne formulation choices and accelerate water-borne substitution timelines. BIS-equivalent conformity assessment requirements for imported coating raw materials create compliance friction that favors domestic blending operations with established certification pathways. Stakeholders must monitor pending updates to Mexican official standards for hazardous substance labeling and evaluate captive water-borne conversion investments before regulatory phase-in deadlines compress available supplier qualification windows.
Market Dynamics
PROFEPA's tightening enforcement of NOM-085-SEMARNAT-2011 VOC limits is forcing solvent-borne coating users across Guanajuato and Querétaro into accelerated water-borne conversion timelines, compressing supplier qualification windows and reshaping procurement patterns among furniture OEMs.
Growth Catalysts
- Automotive-interior wood trim demand:Bajío-based suppliers to Volkswagen and Nissan assembly plants are expanding coating specifications for dashboard and door panel applications.
- NOM-085-SEMARNAT-2011 compliance deadlines:PROFEPA inspection intensity in Querétaro industrial parks is accelerating low-VOC polyurethane adoption among medium-scale furniture manufacturers.
- Polyurethane hardness specifications:Flooring and musical instrument finishers in Jalisco are specifying two-component water-borne systems for scratch resistance.
Market Restraints
- Imported acrylic acid volatility:PPG's backward integration into resin intermediates highlights systemic exposure to US Gulf Coast supply disruptions affecting domestic blenders without captive feedstock.
- BIS-equivalent conformity assessment friction:Imported coating raw materials face extended certification timelines at Mexican customs, favoring domestic blending operations with established PROFEPA pathways.
- Water-borne drying time limitations:High-humidity conditions in Veracruz port facilities extend cure schedules beyond just-in-line manufacturing tolerances for export cabinetry.
Strategic Opportunities
- Yucatán Peninsula export woodworking:Tropical hardwood processors near Mérida lack local coating distribution hubs, creating white space for regional service depots.
- UV-curable technology convergence:Marine-grade UV stability systems from Jotun's adapted portfolio are penetrating outdoor furniture segments previously served by conventional solvent-borne varnishes.
- PROFEPA environmental audit incentives:Voluntary clean production certifications unlock preferential treatment in government furniture procurement tenders.
Industry Challenges
- Formulation chemist scarcity:Water-borne polyurethane development requires specialized expertise in colloidal stability that outpaces technical training programs in Mexico City and Monterrey.
- Legacy spray booth retrofit costs:Conversion from solvent-borne to water-borne application requires humidity-controlled drying infrastructure investment that strains mid-cap furniture OEM balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Industrial Wood Coatings Market |
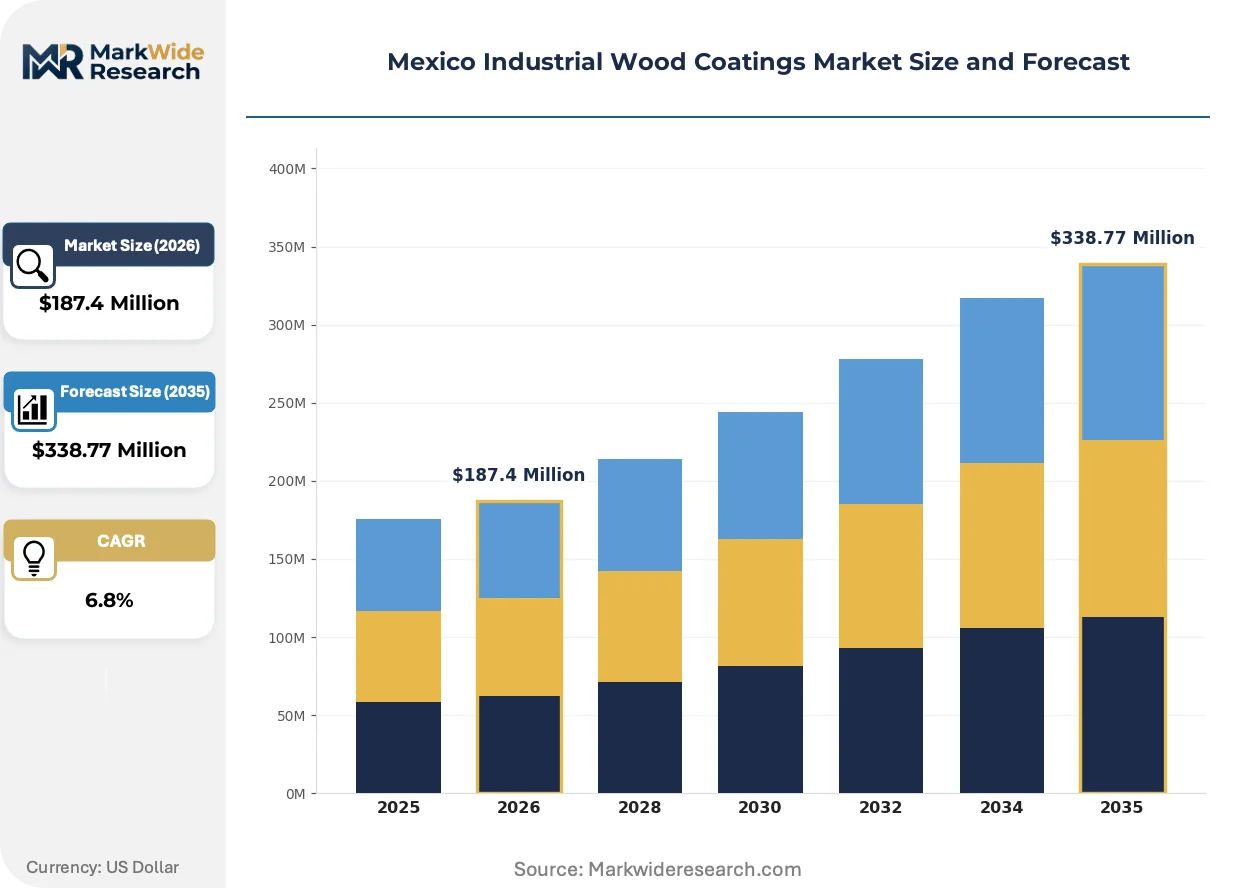
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Stain, Varnish Application: Furniture, Flooring, Cabinets, Musical Instruments End User: Manufacturers, Contractors, Retailers, OEMs Distribution Channel: Online, Retail Stores, Distributors, Wholesalers |
| Companies Covered | The Sherwin Williams, Jotun, RPM International Inc, BASF SE, Henkel AG & Co KGaA, AkzoNobel NV, PPG Industries Inc, Nippon Paint Holdings Co Ltd, Axalta Coatings Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Industrial Wood Coatings Market Shifts & Advancements
Formulation chemistry is pivoting toward hybrid resin systems that merge acrylic fast-dry characteristics with polyurethane durability, enabling furniture manufacturers to maintain throughput while meeting tightening VOC thresholds.
Hybrid acrylic-polyurethane water-borne systems are displacing conventional single-resin formulations in high-volume furniture finishing. Guanajuato cabinet OEMs are adopting these hybrids at accelerated pace to preserve line speeds during PROFEPA compliance transitions. The technology is displacing pure acrylic specifications in premium segments where hardness requirements previously forced solvent-borne retention.
PROFEPA's pending updates to hazardous substance labeling standards under NOM-018-STPS-2015 will mandate GHS-aligned pictogram systems on industrial coating containers. This regulatory shift forces reformulation documentation updates across distributed blending networks. Small-scale artisanal varnish suppliers in Michoacán face the steepest adaptation burden due to limited regulatory affairs staffing.
Specification authority is consolidating among Bajío automotive-tier wood trim suppliers who now dictate coating performance benchmarks to subordinate furniture finishers. Traditional distributor-led technical sales are yielding to direct OEM-formulator relationships. This pattern is most visible in Querétaro where Volkswagen interior suppliers have established approved vendor lists with locked formulation specifications.
Mexico Industrial Wood Coatings Market Segmentation
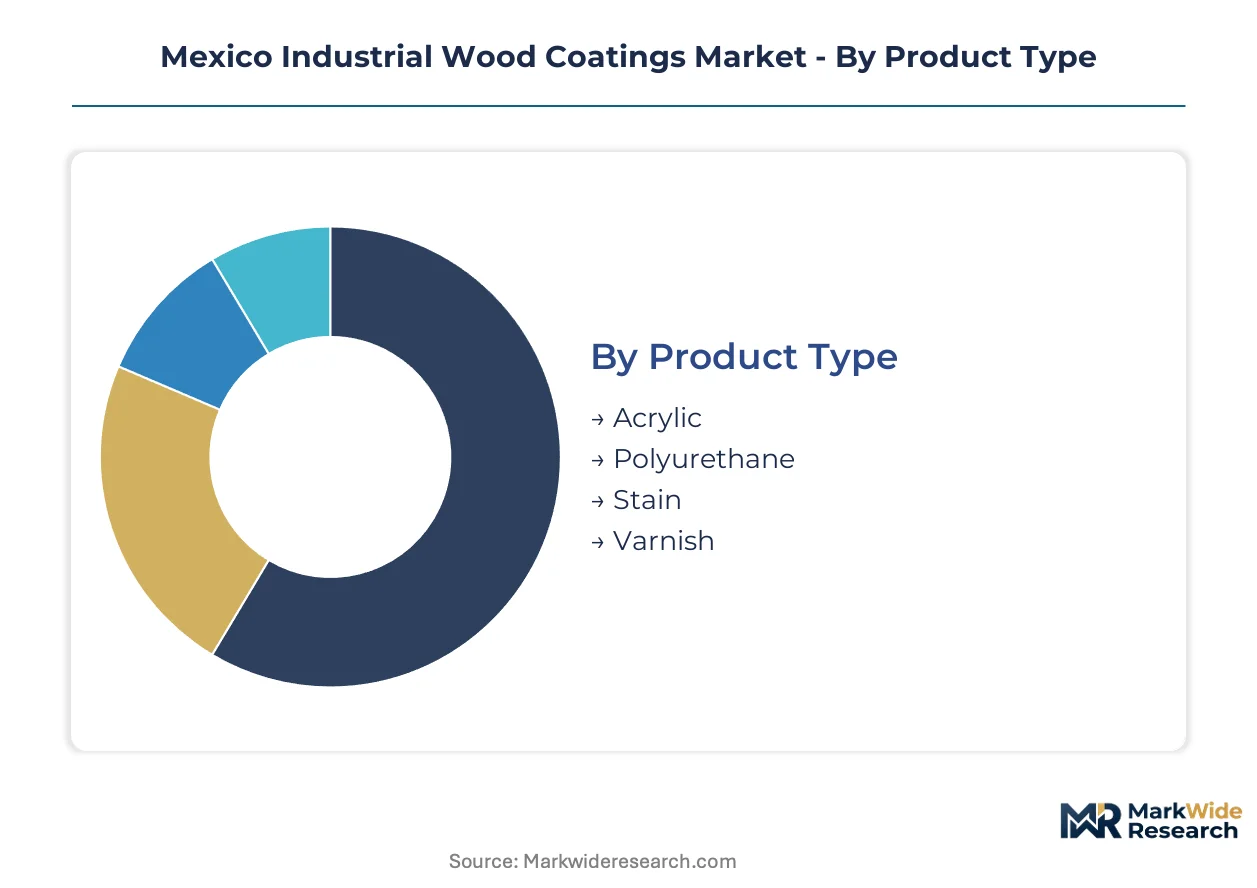
Mexico's industrial wood coatings market fragments across formulation chemistry, end-use specifications, and procurement channels that reflect the geographic concentration of furniture manufacturing in the Bajío corridor. Understanding these segment boundaries clarifies where PROFEPA compliance investments concentrate and which distribution pathways capture value from water-borne conversion timelines.
Product Type:
Channel-mix dynamics vary sharply by resin chemistry, with polyurethane systems flowing primarily through direct OEM-formulator relationships while acrylic and varnish categories retain distributor intermediaries.
- Acrylic:Water-borne acrylic dispersions dominate high-volume furniture finishing where fast-dry schedules support just-in-line manufacturing. Demand concentrates in Guanajuato cabinet clusters where medium-scale OEMs prioritize throughput over maximum hardness.
- Polyurethane:Two-component water-borne polyurethanes command premium positioning in flooring and musical instrument applications. Jalisco guitar manufacturers and hardwood flooring mills specify these systems for scratch resistance and chemical durability despite longer cure cycles.
- Stain:Penetrating colorants serve artisanal restoration contractors through retail contractor yards with limited formulation innovation.
- Varnish:Traditional solvent-borne varnishes persist in Michoacán small-scale woodworking despite PROFEPA phase-out pressures.
By volume, acrylic leads. By growth pace, polyurethane is expanding most quickly.
Application:
Cost-tier stratification separates specification-grade automotive-interior applications from commodity furniture finishing, with margin structures determining channel power.
- Furniture:Residential and commercial furniture OEMs across Querétaro and Guanajuato represent the volume anchor, with hybrid acrylic-polyurethane systems displacing pure acrylic specifications in premium segments.
- Flooring:Engineered wood and parquet manufacturers in Jalisco specify high-build polyurethane systems for abrasion resistance, with direct formulator relationships replacing distributor technical sales.
- Cabinets:Kitchen and bath cabinetry clusters near León drive water-borne conversion at accelerated pace to preserve export competitiveness under tightening VOC limits.
- Musical Instruments:Guitar and stringed instrument finishers in Paracho command specialized two-component systems where hardness and acoustic neutrality justify premium pricing.
Furniture captures the largest volume share. Flooring demonstrates the steepest expansion trajectory as hardwood exports gain share.
End User:
Customer-type concentration shapes service intensity, with manufacturers demanding embedded technical support while contractors prioritize availability and price transparency.
- Manufacturers:Integrated furniture and flooring producers in the Bajío corridor drive formulation co-development, locking suppliers into approved vendor lists with specification authority.
- Contractors:Installation and refinishing contractors purchase through distributor branches, with procurement patterns sensitive to humidity-adjusted cure schedules in Veracruz port facilities.
- Retailers:Big-box home improvement chains stock consumer-grade stains and varnishes with limited technical differentiation.
- OEMs:Automotive-tier wood trim suppliers to Volkswagen and Nissan assembly plants dictate performance benchmarks to subordinate finishers, consolidating specification authority.
Manufacturers dominate volume. OEMs are gaining share fastest as automotive-interior specifications proliferate.
Distribution Channel:
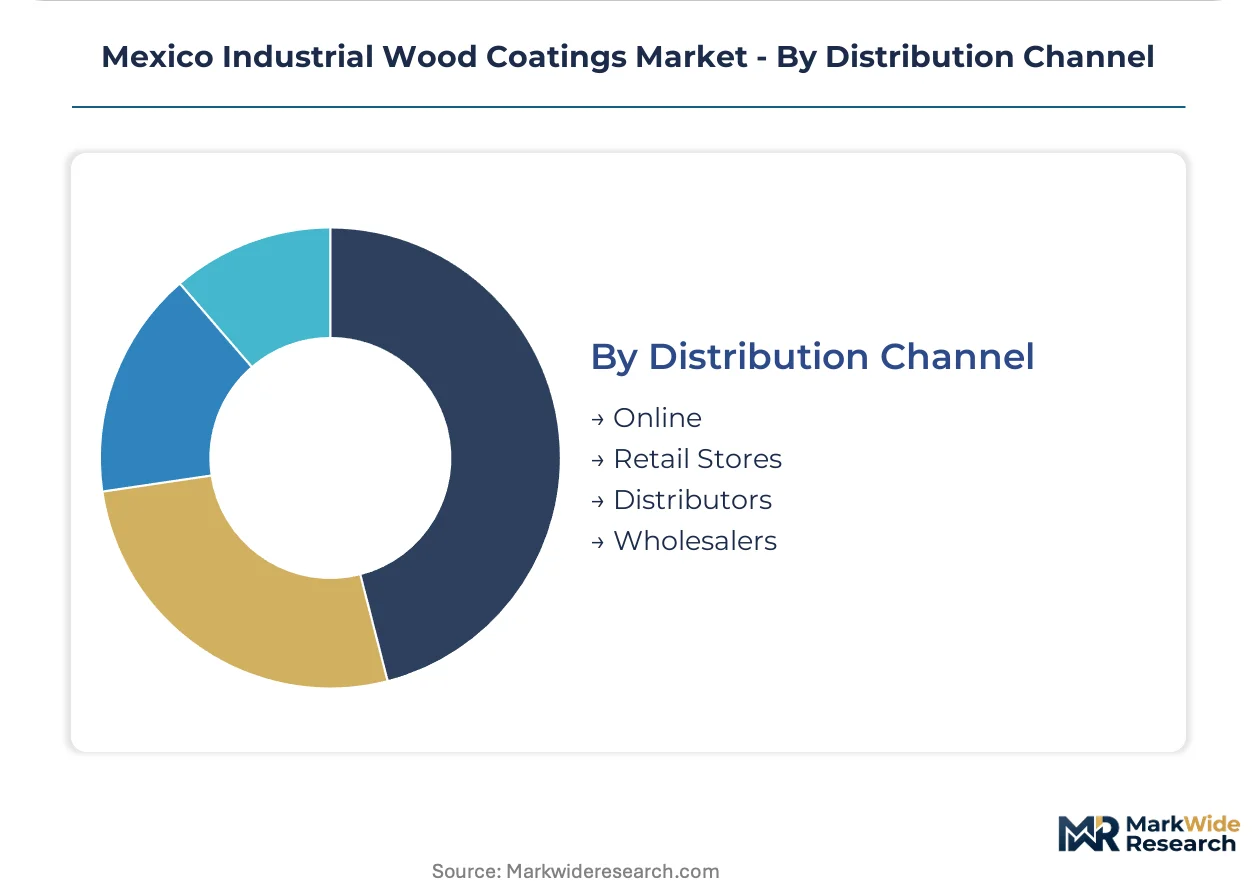
Supply concentration in Querétaro and Guanajuato distribution hubs determines reach efficiency, with digital channels penetrating smaller accounts underserved by branch networks.
- Online:E-commerce platforms capture stain and varnish demand from remote woodworking operations in Yucatán and southern regions lacking local distribution infrastructure.
- Retail Stores:Big-box and specialty coating retailers serve contractor walk-in demand with immediate availability of standard colors and finishes.
- Distributors:Technical distributors with PROFEPA certification pathways dominate water-borne polyurethane flows to medium-scale furniture OEMs, providing regulatory compliance documentation.
- Wholesalers:Volume wholesalers supply large furniture manufacturers with tank-wagon deliveries of base resins and formulated coatings under annual supply agreements.
Distributors lead by volume. Online channels are climbing the fastest as regional coverage gaps persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Mexican sub-regions. Bajío furniture OEMs absorb premium polyurethane costs for export compliance, while Veracruz port facilities resist water-borne conversion due to humidity-driven cure delays. Yucatán hardwood processors face acute distribution gaps that amplify landed coating costs.
Bajío Region
Guanajuato and Querétaro furniture clusters drive demand for low-VOC polyurethane systems as automotive-interior wood trim specifications proliferate. PROFEPA enforces NOM-085-SEMARNAT-2011 VOC limits with escalating inspection intensity across Querétaro industrial parks. Volkswagen and Nissan tier-one suppliers near Querétaro now dictate approved vendor lists with locked formulation specifications to subordinate finishers.
Jalisco
Hardwood flooring mills and Paracho musical instrument finishers specify two-component water-borne polyurethanes for scratch resistance and acoustic neutrality. The state's guitar manufacturers command specialized systems where hardness justifies premium pricing despite longer cure cycles. Guadalajara anchors coating distribution flows to regional flooring exporters serving US markets.
Nuevo León
Monterrey-based industrial furniture producers prioritize fast-dry acrylic dispersions for just-in-line manufacturing efficiency. The state's manufacturing base shows lower price elasticity than Bajío peers due to captive domestic market focus. Local distributors maintain PROFEPA-certified blending operations that reduce customs friction for imported raw materials.
Yucatán Peninsula
Tropical hardwood processors near Mérida lack local coating distribution hubs, creating white space for regional service depots. High humidity conditions extend water-borne cure schedules beyond export cabinetry tolerances, preserving solvent-borne retention despite regulatory pressure. E-commerce platforms increasingly capture stain and varnish demand from remote woodworking operations underserved by branch networks.
Veracruz
Port facility humidity levels disrupt water-borne coating performance for export-oriented cabinet manufacturers. Just-in-line manufacturing tolerances compress available cure windows, forcing retention of solvent-borne systems or investment in humidity-controlled drying infrastructure. PROFEPA enforcement intensity lags Bajío levels, slowing compliance investment timelines among mid-cap furniture OEMs.
Mexico Industrial Wood Coatings Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Mexico's industrial wood coatings sector. Multinational resin producers with captive intermediate supply anchor the premium polyurethane segment, while domestic blenders compete on price and regulatory compliance documentation. The market structure fragments across three strategic archetypes: global formulators with automotive-adjacent expertise, regional distributors with PROFEPA certification pathways, and captive blending operations integrated into large furniture OEMs. Dominant competitive moves include backward integration into resin intermediates and geographic expansion through regional service depot establishment.
Among global formulators, AkzoNobel NV, PPG Industries Inc, and Jotun occupy positions defined by distinct capability anchors. AkzoNobel represents the automotive-color-matching archetype, leveraging adjacent expertise to serve furniture OEMs demanding batch-to-batch consistency. PPG exemplifies the backward-integrated model, reducing exposure to imported acrylic acid volatility through captive resin intermediate supply. Jotun sits within the marine-grade adaptation archetype, applying UV stability technologies developed for harsh environments to tropical hardwood export applications. These three companies illustrate how multinational players differentiate through capability origins rather than convergent product strategies.
| Leading Market Players |
|---|
| The Sherwin Williams |
| Jotun |
| RPM International Inc |
| BASF SE |
| Henkel AG & Co KGaA |
| AkzoNobel NV |
| PPG Industries Inc |
| Nippon Paint Holdings Co Ltd |
| Axalta Coatings Systems |
| Others |
Supply & Pricing Matrix
Capacity utilization gaps among domestic resin blenders concentrate pricing power with backward-integrated multinationals while compressing margin floors for mid-scale furniture OEMs caught between PROFEPA compliance deadlines and imported acrylic acid volatility. Scale economies in captive intermediate production enable premium positioning for polyurethane systems serving automotive-interior specifications, whereas smaller blenders compete on regulatory documentation speed rather than formulation cost.
Pricing Analysis
NOM-085-SEMARNAT-2011 dictates the pricing tier structure across Mexico's industrial wood coatings sector, separating certified low-VOC polyurethane systems from commodity acrylic dispersions and legacy solvent-borne varnishes. Price differentiation hinges on PROFEPA compliance certification level and volume scale, with large furniture OEMs capturing standard-tier discounts through annual offtake commitments while artisanal finishers absorb premium markups for small-batch documentation. Cost compression in mid-tier acrylic segments is intensifying because hybrid resin R&D investments are concentrating among multinational formulators with captive technical resources. Export-oriented automotive-tier suppliers exhibit lowest price sensitivity, whereas Michoacán small-scale varnish producers face acute margin pressure from reformulation mandates.
Supply Chain Analysis
The United States and Germany anchor resin intermediate production for Mexico's industrial wood coatings sector, with US Gulf Coast acrylic acid and German isocyanate specialties feeding domestic blending operations in Querétaro and Guanajuato. Formulation chemistry draws from imported polyurethane prepolymers, water-borne acrylic dispersions, and specialty additives, with BIS-equivalent conformity assessment timelines creating inventory friction at Mexican customs. Single-source vulnerability concentrates in acrylic acid supply chains exposed to US petrochemical disruption. Distribution runs through PROFEPA-certified technical distributors for medium-scale OEMs, while tank-wagon direct delivery serves large furniture manufacturers under locked specification agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PROFEPA enforcement fragmentation across Mexican states creates geographic niches where regulatory timing arbitrage rewards agile formulators with localized compliance expertise.
For Market Incumbents: Fortify specification authority by embedding technical service teams within Bajío automotive-tier wood trim suppliers, converting approved vendor list status into multi-year formulation lock-ins. Deepen backward integration into water-borne polyurethane resin intermediates to reduce exposure to US Gulf Coast supply disruption threatening domestic blenders without captive feedstock. Prioritize humidity-controlled drying infrastructure partnerships with mid-cap furniture OEMs facing legacy spray booth retrofit cost barriers. For New Entrants and Emerging Players: Differentiate on regional service depot establishment in Yucatán Peninsula tropical hardwood processing clusters where Mérida-based exporters lack local coating distribution infrastructure. Target the musical instrument finishing segment in Paracho, Jalisco, where specialized two-component water-borne systems for acoustic neutrality command premium pricing with limited incumbent technical presence. Pursue e-commerce platform partnerships to capture stain and varnish demand from remote woodworking operations in southern regions underserved by branch networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic blenders with established PROFEPA certification pathways and captive water-borne conversion capabilities ahead of pending NOM-018-STPS-2015 labeling standard updates. Long-term viability hinges on acquisition targets with embedded regulatory affairs staffing capable of navigating hazardous substance documentation requirements without multinational overhead structures. Watch for inflection signals in Volkswagen and Nissan interior supplier consolidation patterns that would concentrate specification authority among fewer tier-one wood trim vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Intermediates | Captive acrylic acid supply insulates PPG-style operations from US Gulf Coast petrochemical disruption affecting domestic blenders. |
| Regional Service Depot Establishment | Yucatán Peninsula coating distribution gaps amplify landed costs for tropical hardwood exporters near Mérida. |
| Hybrid Acrylic-Polyurethane R&D Investment | Fast-dry durability combinations enable Guanajuato cabinet OEMs to preserve line speeds during PROFEPA compliance transitions. |
| PROFEPA Certification Pathway Expansion | Regulatory documentation speed separates technical distributors from price-competing commodity varnish suppliers. |
| Automotive-Tier Supplier Technical Embedding | Direct OEM-formulator relationships in Querétaro displace distributor-led specification authority for Volkswagen interior benchmarks. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with coating formulators, furniture OEM procurement leads, PROFEPA compliance officers, and Bajío automotive-tier wood trim suppliers; and secondary validation through Mexican customs trade records, SEMARNAT regulatory filings, SEC 10-K disclosures from multinational paint producers, and ACC regional chemical industry reports. Bottom-up triangulation across resin consumption estimates and top-down cross-checks against finished furniture export values anchored volume and value projections.
Across the analysis window, the forecasting framework modeled demand through segmentation dimensions spanning resin chemistry tier, end-use application, customer type concentration, and geographic production cluster. CAGRs derived from regression analysis of historical coating consumption against furniture manufacturing output indices, with specific inputs including PROFEPA inspection intensity trajectories and automotive-interior wood trim specification proliferation rates.
Material uncertainties — abrupt shifts in US-Mexico petrochemical trade flows, accelerated NOM-085-SEMARNAT-2011 phase-in schedules, or humidity-driven water-borne adoption failures in Veracruz — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and resin intermediate supply stability. Recalibration cycles align with material shifts in PROFEPA audit intensity and automotive OEM specification consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Batters and Coatings Market
Coatings
Fluid Bed and Coating System Market
Coatings
Coating Resins Market
Coatings
Carpet Back Coatings Market
Coatings
Vinyl Surface Coatings Market
Coatings
Anti-Friction Coatings Market
Coatings
High Temperature Coatings Market
Coatings
Non-Stick Coatings Market
Coatings
Global Anti Slip Coatings Market
Coatings
Dispersion Coating Market
Coatings
South Korea Protective Coatings Market
Coatings
South Korea Marine Coatings Market
Coatings
Germany Industrial Coatings Market
Coatings
Coated Casing Market
Coatings
Electrical Insulation Coatings Market
Coatings
US Protective Coatings Market