
 Global Decorative Paints and Coatings Market | 2026-2036
Global Decorative Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Decorative Paints and Coatings Market Intelligence
Online platforms for direct-to-consumer sales is tilting the traditional dominance of wholesale distributors in the decorative paints sector. AkzoNobel N.V. leverages its strong brand recognition to build direct relationships with homeowners and professional decorators. PPG Industries, Inc. sustains its market position through extensive retail partnerships and manufacturing scale, while The Sherwin-Williams Company operates a vast network of company-owned stores.
Decorative paints and coatings are formulations designed for aesthetic appeal and surface protection on architectural substrates. These products are characterized by specific pigment volume concentrations and binder systems, like water-based acrylics, which determine finish and durability. Emulsion paints command the largest share among product types, driven by their low odor and ease of application for interior walls. While interior applications remain the largest segment, demand for specialized furniture finishing and wood preservation coatings shows notable momentum.
Regulations governing Volatile Organic Compounds (VOCs) shape product development, with the US EPA and Europe's ECHA setting stringent limits on emissions. Concurrently, China's GB standards for indoor decorating materials influence formulation for market access. These rules drive innovation in water-based and low-solvent technologies. The key decision for manufacturers is how to balance investments in sustainable formulations against the cost pressures in highly competitive residential markets.
Market Dynamics
The central dynamic shaping the decorative paints market is the regulatory and consumer-driven pivot towards sustainable, low-emission formulations. This shift forces manufacturers to balance investments in water-based technologies against persistent cost pressures in the competitive residential construction sector.
Growth Catalysts
- Indian Construction Activity:A surge in new residential and commercial building projects across India provides a significant volume driver, particularly for emulsion paints and exterior coatings designed for tropical climates.
- EU Renovation Wave:The European Union's Renovation Wave strategy, aimed at improving building energy efficiency, stimulates demand for thermal insulating coatings and durable exterior paints as part of building upgrades.
- Hospitality Sector Refurbishment:The global hospitality industry's focus on facility upgrades and rebranding cycles creates consistent demand for premium interior paints that offer specific aesthetic finishes and high durability for common areas.
Market Restraints
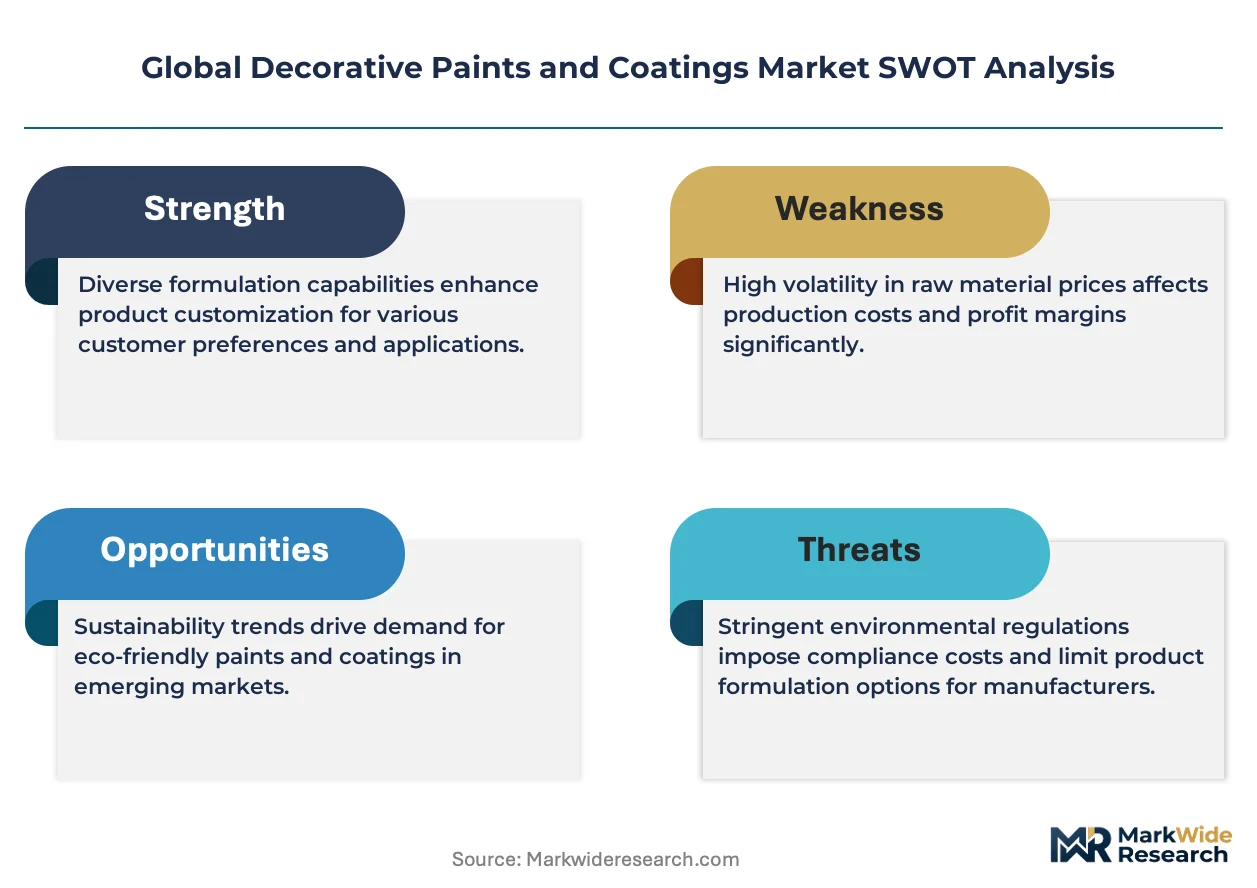
- Raw Material Volatility:Fluctuations in the price and availability of key inputs, such as titanium dioxide (TiO2) and petroleum-derived binders, create significant margin pressure and supply chain instability for paint manufacturers.
- Performance Trade-offs in Low-VOC Formulations:Achieving the same level of durability, adhesion, and washability in water-based and low-VOC paints compared to traditional solvent-based counterparts remains a technical hurdle for certain demanding applications.
- Substitution from Alternative Surfaces:The market faces competition from non-paint decorative solutions, including advanced textured wallpapers, architectural films, and pre-finished wall panels, which can offer faster installation in commercial projects.
Strategic Opportunities
- Functional and Smart Coatings:Integrating functionalities like air purification, anti-microbial properties, or thermal insulation into decorative paints opens new value-added segments in health-conscious residential and green building markets.
- Direct-to-Consumer (D2C) Channels:Establishing online platforms for direct sales allows brands to bypass traditional distribution layers, build direct relationships with end-users, and capture higher margins, especially in the DIY segment.
- Bio-Based Formulations:Developing paints and coatings using renewable, bio-based raw materials presents an opportunity to meet rising consumer demand for sustainable products and comply with circular economy principles.
Industry Challenges
- Global Regulatory Fragmentation:Manufacturers face the operational complexity of formulating products that comply with a patchwork of regional VOC standards, such as those from the US EPA, Europe's ECHA, and China's GB standards.
- Skilled Applicator Scarcity:A shortage of trained professional painters and applicators, particularly those skilled in applying specialized or high-performance coating systems, can constrain the growth of the premium and decorative effects segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Decorative Paints and Coatings Market |
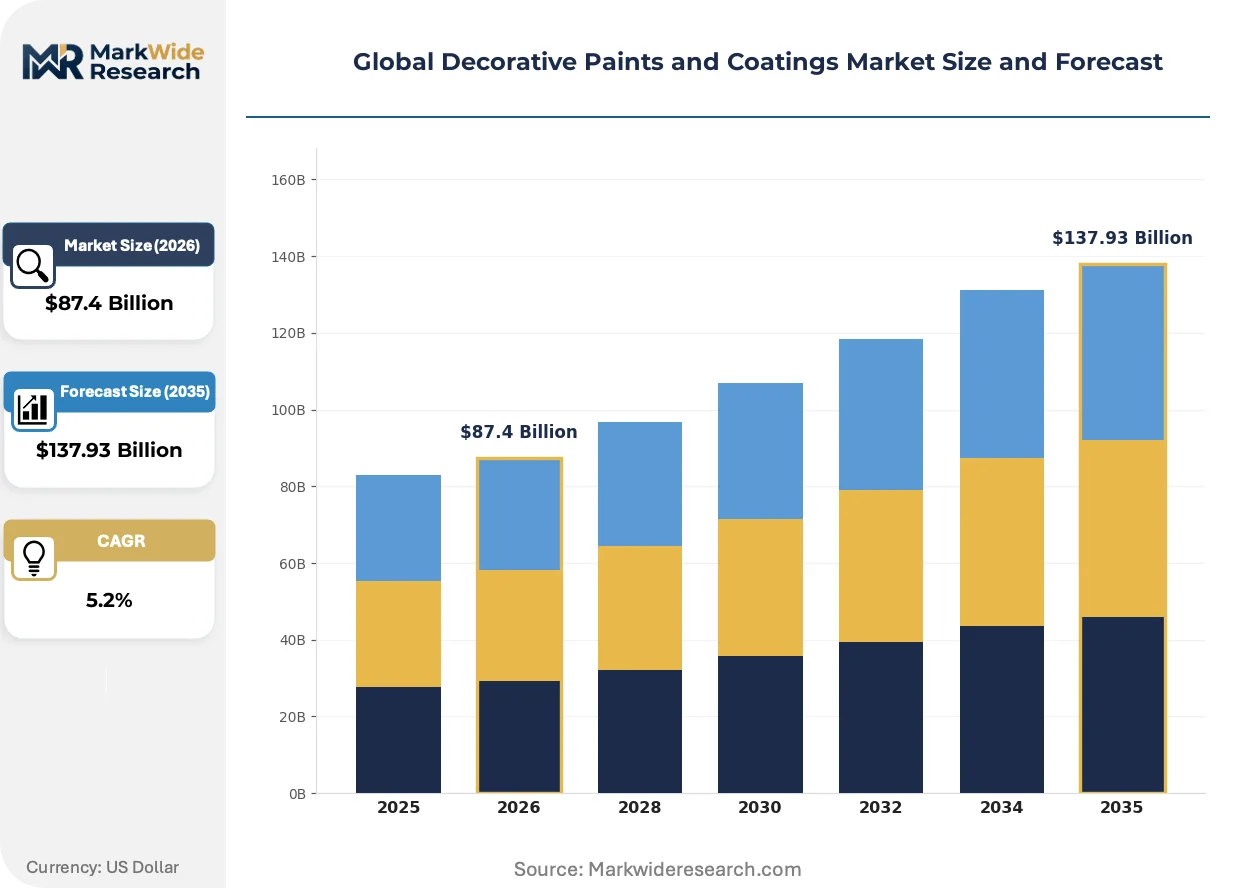
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $137.93 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion Paints, Enamel Paints, Powder Coatings, Varnishes, Primers Application: Interior Walls, Exterior Walls, Furniture Finishing, Metal Coating, Wood Preservation End User: Homeowners, Professional Decorators, Commercial Facilities, Hospitality Venues, Educational Institutions Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Wholesale Distributors, Paint Specialists |
| Companies Covered | The Sherwin-Williams Company, PPG Industries, Inc, AkzoNobel N.V., Nippon Paint Holdings Co., Ltd., Asian Paints Limited, BASF SE, Kansai Paint Co., Ltd., Jotun A/S, RPM International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Decorative Paints and Coatings Market Strategic Shifts & Innovations
Product development is increasingly focused on the convergence of aesthetics and performance, driven by stringent environmental regulations and evolving consumer expectations for healthier indoor environments. This is compelling a shift away from purely decorative products toward multi-functional coating solutions.
Functional additives are transforming the capabilities of standard paints. These materials, including photocatalytic compounds for air purification and phase-change materials for thermal regulation, are being integrated into interior emulsions. Adoption is accelerating among environmentally-conscious homeowners and developers of green-certified commercial buildings. This technology is hybridizing traditional aesthetic coatings with active performance characteristics, creating new product categories.
Mandates like China's GB standards for indoor decorating materials are setting a high bar for product safety and environmental impact. These regulations enforce strict limits on a wide range of hazardous substances beyond just VOCs, directly influencing formulation chemistry for market access. Global manufacturers targeting the vast Chinese residential market must now re-engineer their portfolios to meet these specific national requirements, often exceeding standards in their home markets.
A digital-first purchasing model is gaining significant traction, particularly for do-it-yourself (DIY) residential painting projects. This behavioral shift disrupts the traditional dominance of wholesale distributors and large home improvement retailers by enabling direct brand engagement. The trend is most advanced in North America and Europe, where mature e-commerce logistics support the growth of brand-led D2C platforms offering color visualization tools and curated palettes.
Global Decorative Paints and Coatings Market Segmentation
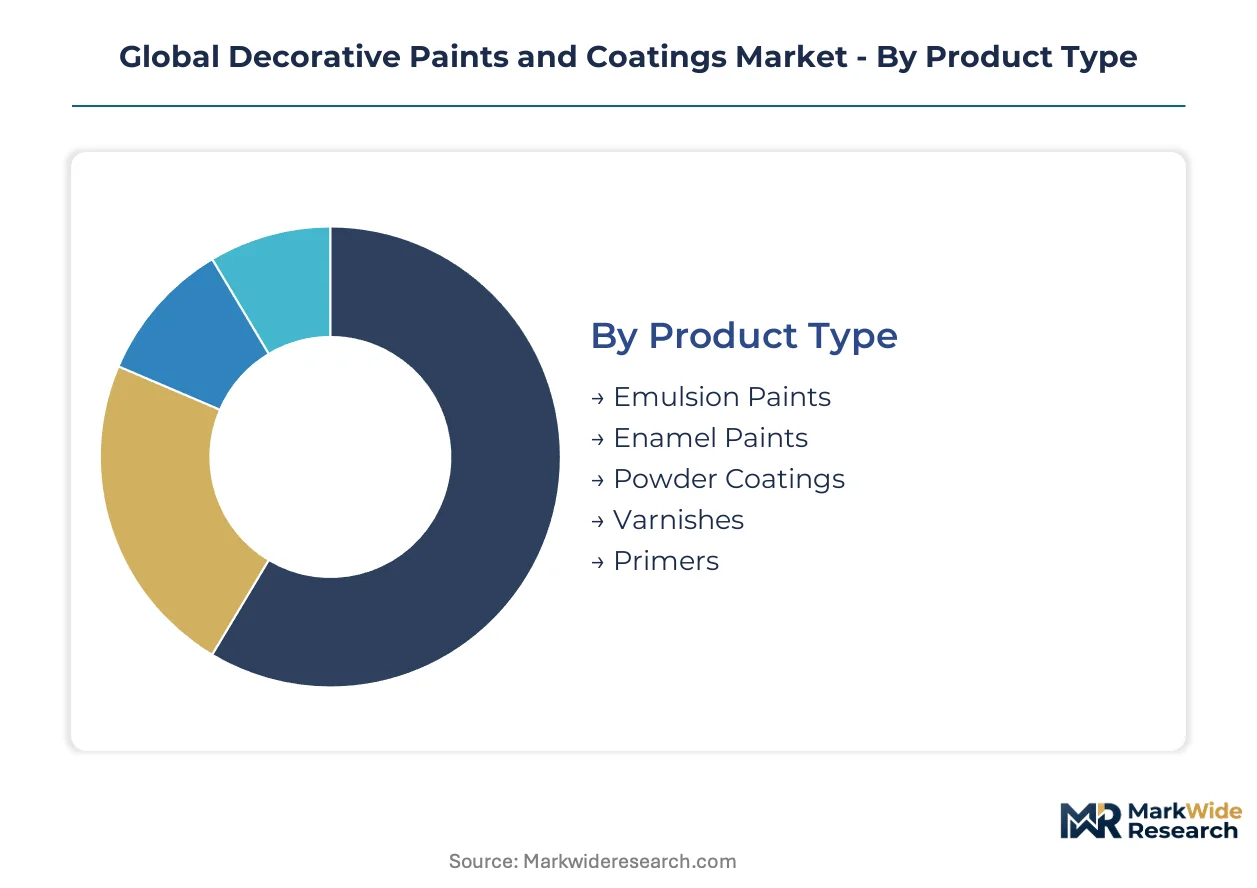
The segmentation of the global decorative paints and coatings market reveals distinct product characteristics, application requirements, end-user preferences, and distribution dynamics. Understanding these segments helps manufacturers tailor product portfolios and refine market entry strategies across diverse regional landscapes.
Product Type:
The after-sales-service intensity varies significantly across decorative paint product types, influencing technical support and customer engagement models.
- Emulsion Paints:These water-based formulations offer low odor and easy application, making them dominant for interior walls. Demand for emulsion paints concentrates in new residential construction projects across India, driven by rapid urbanization.
- Varnishes:Transparent or semi-transparent coatings provide durable protection and enhance the natural beauty of wood surfaces. The increasing focus on wood preservation coatings for furniture finishing demonstrates notable momentum in Europe.
- Enamel Paints:Known for their hard, glossy finish and durability, enamel paints are often oil-based and used for trim, doors, and metal surfaces. Their robust performance makes them suitable for high-traffic areas in commercial facilities.
- Powder Coatings:Applied as a free-flowing, dry powder, these coatings are cured under heat to form a hard finish, primarily for metal substrates. Environmental regulations in Europe favor their low-VOC profile for industrial decorative applications.
- Primers:These undercoats prepare surfaces for subsequent paint layers, improving adhesion and overall finish quality. Professional decorators rely on primers for consistent results across diverse architectural substrates.
Emulsion Paints holds the largest share; momentum sits with Varnishes.
Application:
Specific application needs dictate product formulation and performance requirements within the decorative paints market.
- Interior Walls:This segment accounts for the largest volume, demanding paints with low VOCs, aesthetic appeal, and ease of cleaning for residential and commercial spaces. Consumer preferences in North America increasingly favor healthier indoor environments.
- Furniture Finishing:Specialized coatings protect and beautify furniture, requiring formulations that offer durability, scratch resistance, and specific aesthetic effects. The hospitality sector refurbishment activities create consistent demand for premium furniture finishes.
- Exterior Walls:Products in this category must withstand harsh weather conditions, UV radiation, and biological growth, offering long-lasting protection and color retention. The EU Renovation Wave strategy stimulates demand for durable exterior paints.
- Wood Preservation:Coatings designed to protect wood from moisture, insects, and decay extend the lifespan of wooden structures and components. This application is critical for outdoor decking and historical building restoration.
- Metal Coating:Decorative coatings for metal surfaces provide corrosion resistance and aesthetic enhancement for architectural elements and fixtures. Industrial construction projects in China utilize these coatings for structural steel.
Interior Walls maintains the largest share; Furniture Finishing is expanding most quickly.
End User:
Customer type significantly influences purchasing patterns, product choices, and distribution channel preferences in the decorative paints market.
- Homeowners:This segment includes DIY enthusiasts and those hiring professional painters for residential projects, valuing ease of application, low odor, and specific aesthetic finishes. Direct-to-consumer channels increasingly target homeowners in the US.
- Hospitality Venues:Hotels, resorts, and restaurants require durable, aesthetically pleasing paints that can withstand high traffic and frequent cleaning. Global refurbishment cycles create consistent demand for premium interior paints.
- Professional Decorators:Experienced painters and contractors prioritize product performance, reliability, and technical support for diverse client projects. The scarcity of skilled applicators impacts the premium segments.
- Commercial Facilities:Offices, retail spaces, and public buildings demand paints that combine durability, fire resistance, and specific branding colors. Renovation activities in Europe drive demand for specialized coatings.
- Educational Institutions:Schools and universities require hard-wearing, low-VOC paints that contribute to healthy indoor air quality. These institutions often prioritize products with anti-microbial properties.
Homeowners represent the largest end-user segment; Hospitality Venues show the steepest expansion trajectory.
Distribution Channel:
The structure of distribution channels shapes market access and competitive dynamics for decorative paint manufacturers.
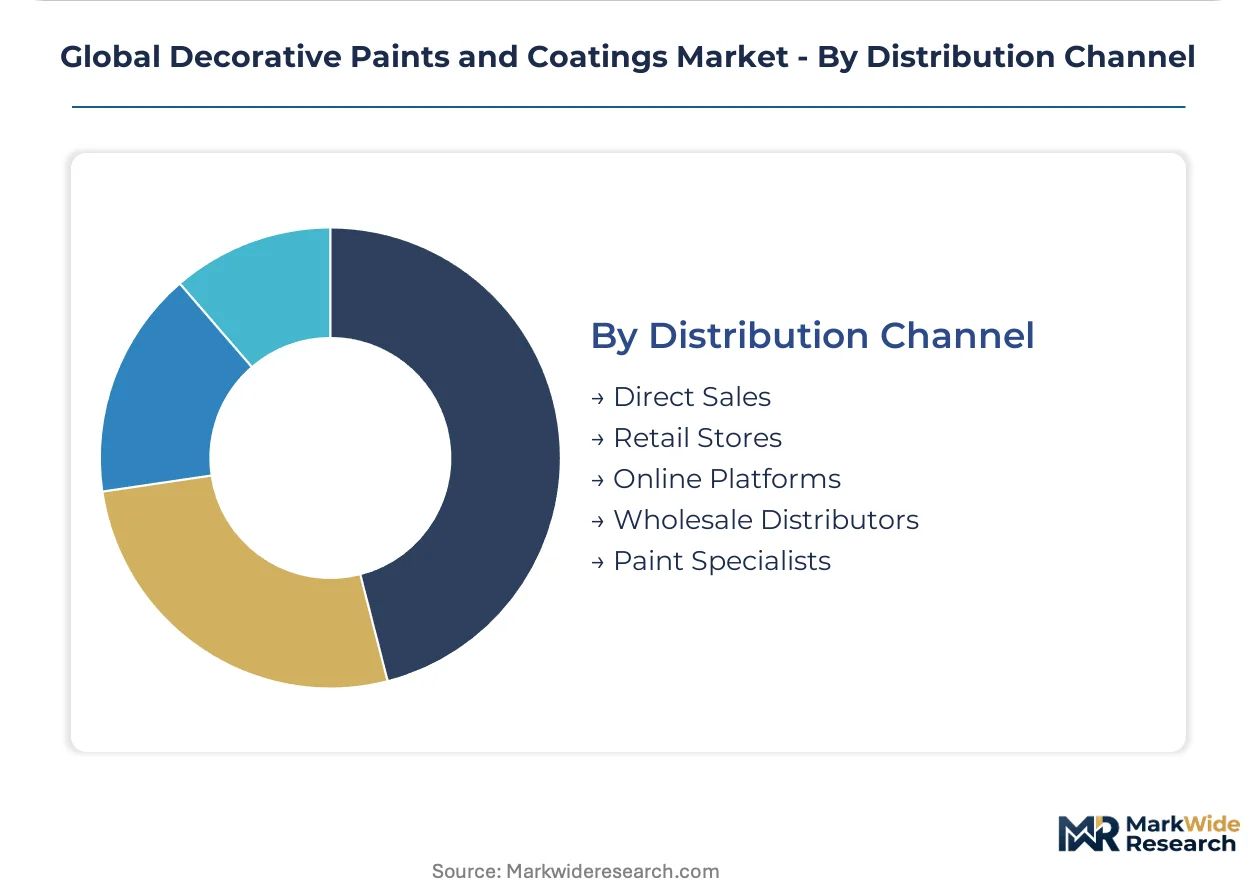
- Online Platforms:E-commerce channels facilitate direct-to-consumer sales, offering convenience, broader product selections, and digital visualization tools. This channel is gaining significant traction for DIY residential painting projects in North America.
- Wholesale Distributors:These traditional intermediaries supply large volumes of paint to retailers, contractors, and industrial clients, maintaining extensive logistical networks. Wholesale distributors historically dominated the decorative paints sector.
- Direct Sales:Manufacturers engage directly with end-users, often through company-owned stores or dedicated sales forces, offering specialized advice and services. The Sherwin-Williams Company operates a vast network of company-owned stores.
- Retail Stores:Large home improvement retailers and specialized paint shops provide accessibility for both DIY consumers and professional contractors. PPG Industries, Inc. sustains its market position through extensive retail partnerships.
- Paint Specialists:Independent paint stores offer niche products, expert advice, and color matching services to discerning customers and professionals. These specialists often cater to premium and decorative effects segments.
Wholesale Distributors retain a significant share; Online Platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power exhibits asymmetry across regions, with established markets like the United States seeing stable demand for premium formulations while emerging economies such as India drive volume with cost-sensitive products. This dynamic influences investment strategies for manufacturers globally. Regulatory frameworks further differentiate market access and product development.
India
A surge in new residential and commercial building projects across India provides a significant volume driver for decorative paints. The Indian government's PLI scheme for manufacturing supports local production capabilities for raw materials and finished goods. Construction activity in Mumbai and the Delhi-NCR region drives substantial demand for emulsion paints and exterior coatings.
China
Demand for decorative paints in China is shaped by stringent GB standards for indoor decorating materials, pushing innovation in low-VOC formulations. China's dual carbon goals also encourage the development of more sustainable and eco-friendly coating solutions. Industrial zones within the Yangtze River Delta continue to be a focal point for both production and consumption of decorative coatings.
United States
Consumer preferences in the United States increasingly favor healthier indoor environments, stimulating demand for low-VOC and functional paints. The US EPA sets stringent limits on Volatile Organic Compound emissions, influencing product development across the nation. Major metropolitan areas like New York and Los Angeles exhibit high demand for premium and specialized decorative finishes.
Germany
Germany benefits from the EU Renovation Wave strategy, which stimulates demand for thermal insulating coatings and durable exterior paints for building upgrades. The European Union's REACH regulation governs the chemical content of paints, ensuring product safety and environmental compliance. The Rhine-Ruhr region, with its dense industrial and residential areas, remains a strong market for decorative paint applications.
Brazil
Brazil's growing middle class and ongoing infrastructure projects contribute to consistent demand for decorative paints and coatings. Environmental regulations set by IBAMA encourage manufacturers to develop more sustainable and less hazardous product lines. The São Paulo metropolitan area, as a major economic hub, drives significant consumption in both residential and commercial sectors.
Global Decorative Paints and Coatings Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream providing essential raw materials. The decorative paints market exhibits a tiered structure, with global players dominating premium segments and regional firms serving local needs. Strategic archetypes include diversified chemical giants, specialized coatings manufacturers, and regional brand leaders. Portfolio diversification and geographic expansion remain dominant competitive moves across the industry.
Within the diversified chemical giants archetype, AkzoNobel N.V. and PPG Industries, Inc. exemplify global reach and broad product portfolios across decorative and industrial coatings. The Sherwin-Williams Company, a prominent US-based entity, anchors the market through its extensive network of company-owned stores and strong brand recognition in both professional and DIY segments. These entities leverage scale and established distribution channels to maintain market position.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries, Inc |
| AkzoNobel N.V. |
| Nippon Paint Holdings Co., Ltd. |
| Asian Paints Limited |
| BASF SE |
| Kansai Paint Co., Ltd. |
| Jotun A/S |
| RPM International, Inc. |
| Others |
Cost & Logistics Intelligence
Raw material volatility, particularly for titanium dioxide and petroleum-derived binders, determines both pricing tier spreads and the geographic shape of the decorative paints supply chain. Manufacturers must navigate these fluctuations while balancing cost-sensitive markets and premium product demands.
Pricing Analysis
The customization-premium spread influences pricing across the decorative paints market. Pricing stratifies across premium, standard, and economy levels, reflecting product quality, brand recognition, and customization for specific aesthetic effects. Price differentiation stems from enhanced durability, specialized finishes, and after-sales technical support. Pricing pressure intensifies within highly competitive residential markets due to the proliferation of standard offerings. Homeowners in the DIY segment exhibit high price sensitivity, while hospitality venues and professional decorators prioritize performance and specialized product features.
Supply Chain Analysis
Contract manufacturing capacity for decorative paints concentrates in industrial hubs across China, India, and Germany. The supply chain relies heavily on key inputs such as titanium dioxide and petroleum-derived binders, which are subject to global commodity markets. Raw material price volatility represents a significant structural risk for manufacturers globally. Downstream distribution runs through a hybrid model, combining traditional wholesale distributors, extensive retail partnerships, direct-to-consumer online platforms, and specialized paint stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The decorative paints market is an early-cycle expansion story, driven by the increasing penetration of low-VOC and functional coating technologies.
For Market Incumbents:Insulate core market share by deepening investments in bio-based and functional coating formulations. Enhance direct-to-consumer channels to counter the threat from alternative surface materials and traditional distribution erosion. Strengthen R&D efforts in air purification and thermal regulation technologies to meet evolving consumer health demands. Expand company-owned store networks to provide specialized technical support and maintain channel control against fragmented retail options.
For New Entrants and Emerging Players:Niche functional coatings for health-conscious residential markets in North America and Europe represent the most penetrable entry point. Target specialized furniture finishing and wood preservation segments with eco-friendly or bio-based solutions. A go-to-market angle focused on online platforms offering color visualization tools and curated palettes can bypass established distribution barriers. Emphasize sustainable product certifications to appeal to environmentally aware consumers and green building developers.
For Investors and Strategic Acquirers:The EU REACH regulation and China's GB standards reshape the acquisition landscape, favoring firms with robust low-VOC and sustainable formulation IP. Long-term viability over the next five to ten years hinges on companies that can balance innovation with cost-efficiency in a highly regulated environment. Acquisition targets should include specialized coatings manufacturers with patented functional additives or strong direct-to-consumer distribution capabilities. Increased M&A activity in bio-based technology providers signals an inflection point for sustainable material integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Formulation R&D | Meets rising consumer demand for sustainable products and complies with circular economy principles. |
| D2C Channel Expansion | Allows brands to build direct relationships with end-users and capture higher margins in the DIY segment. |
| Functional Coatings Integration | Opens new value-added segments in health-conscious residential and green building markets. |
| Global Regulatory Compliance | Ensures market access across diverse regions with fragmented VOC standards like US EPA and China GB. |
| Skilled Applicator Training | Addresses scarcity of trained professionals, supporting growth in premium and decorative effects segments. |
Research Approach
A standing panel of paint manufacturers' R&D directors, professional decorators, wholesale distributors, and architectural specifiers provided ongoing calibration for market insights. This involved combining primary interviews with industry stakeholders and rigorous secondary validation. Secondary data sources included industry association reports, government environmental agency publications from the US EPA and ECHA, company annual reports, and construction project databases. Bottom-up and top-down triangulation ensured data accuracy.
Scenario-bracketing framed the analytical framework across the analysis window, incorporating various growth trajectories. Segmentation dimensions modeled included product type, application, end-user, distribution channel, and regional regulatory compliance. Compound annual growth rates were derived from historical performance and projected market dynamics. Key industry-specific forecast inputs included new residential construction starts and commercial renovation project pipelines.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or raw material prices would shift the trajectory of the decorative paints market. Forecasts reflect assumptions documented through extensive primary and secondary research. Quarterly review of construction activity indicators and regulatory updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
Europe Paints and Coatings Additives Market
Paints & Coatings
Epoxy Paint Thinner Market
Paints & Coatings
Asia-Pacific Paint Thinner Market
Paints & Coatings
Europe Paints and Coatings Market
Paints & Coatings
Nigeria Paint and Protective Coatings Market
Paints & Coatings
Interior Architectural Coatings Market
Paints & Coatings
Polyolefin Resin Paints Market
Paints & Coatings
Radar Absorbing Paint Market
Paints & Coatings
Faux Finish Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Market
Paints & Coatings
Global Wood Coatings Market
Paints & Coatings
UAE Architectural Paints and Coatings Market
Paints & Coatings
Global Exterior Architectural Coatings Market
Paints & Coatings
Aircraft Paint Market
Paints & Coatings
Middle East and Africa Floor Coatings Market