
 Anti-Fungal and Anti-Bacterial Paints Market | 2026-2036
Anti-Fungal and Anti-Bacterial Paints Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Fungal and Anti-Bacterial Paints Market Outlook
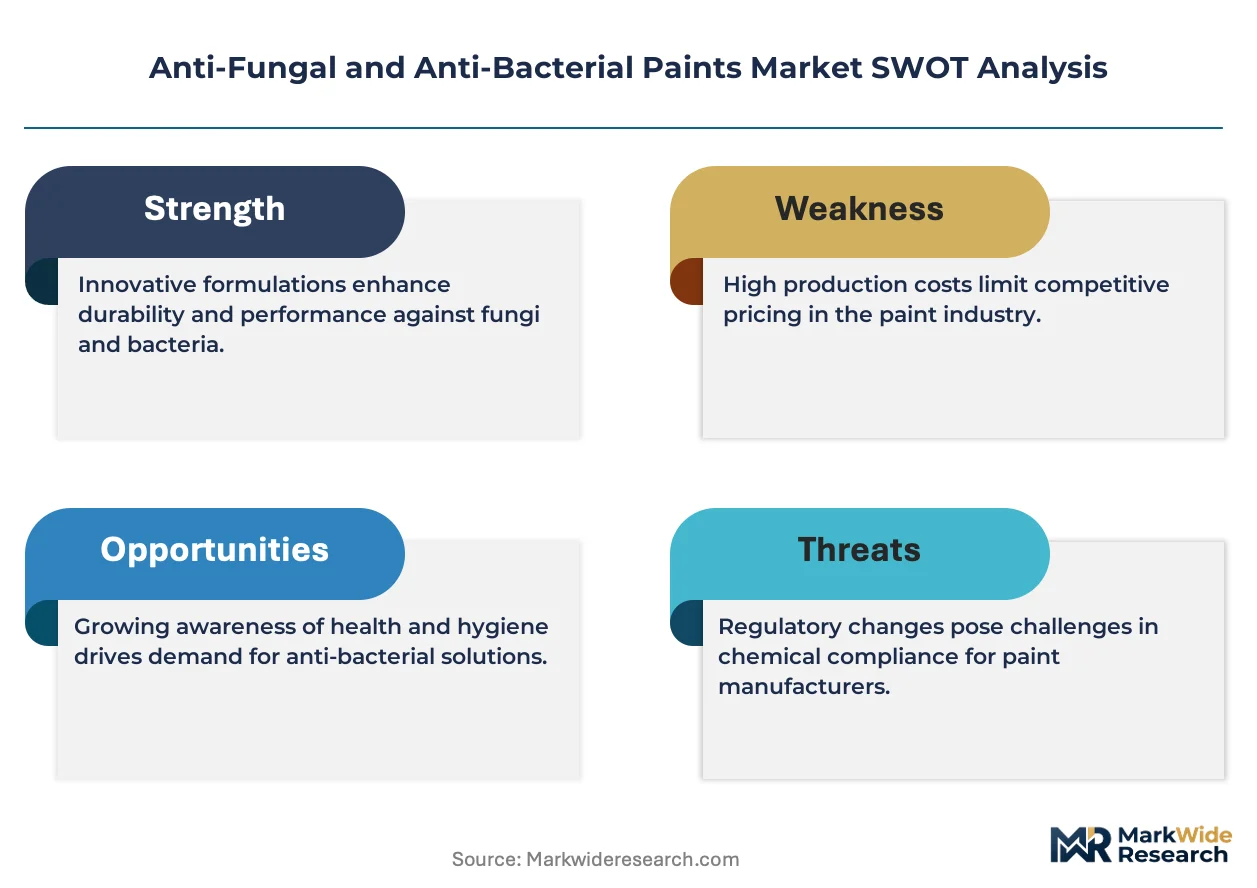
Buyer concentration among healthcare facility managers and large contracting consortiums is realigning procurement power toward volume-committed purchasers. PPG Industries leverages its architectural coatings distribution network to sustain institutional channel dominance. BASF SE anchors its position through specialty polymer additives that enhance biocidal durability. Nippon Paint Holdings competes aggressively in Asia-Pacific humidity-zone formulations where fungal resistance carries premium pricing power.
Anti-fungal and anti-bacterial paints are coating systems incorporating biocidal additives such as silver nanoparticles, quaternary ammonium compounds, or zinc pyrithione at loadings typically between 0.5% and 3% by weight, designed to inhibit microbial colonization on cured film surfaces in moisture-prone or hygiene-critical environments. Interior Paints command the largest revenue pool due to repetitive re-coating cycles in healthcare and residential settings, while Nano-Coatings represent the fastest-expanding technology segment as thin-film antimicrobial efficacy reduces material usage per treated area. Water-Based formulations dominate regulatory-permissive markets where VOC restrictions have matured, though Solvent-Based systems retain share in industrial applications requiring rapid cure and chemical resistance.
EPA regulates antimicrobial paint claims under FIFRA, requiring registration of products asserting public health benefits, while FDA oversight intersects where coatings contact medical device surfaces or food-zone applications. REACH in Europe constrains biocidal active substance approval through BPR harmonization, forcing reformulation cycles that favor established suppliers with regulatory affairs capacity. Stakeholders must monitor evolving biocidal product authorization timelines and humidity-zone performance certification standards to anticipate which formulation platforms will retain market access.
Market Dynamics
Healthcare facility managers now demand surface coatings with validated biocidal efficacy data, forcing manufacturers to restructure R&D budgets toward EPA-compliant efficacy testing and third-party certification rather than incremental color-matching innovation.
Growth Catalysts
- Hospital infection control mandates:United States healthcare procurement guidelines now specify antimicrobial surface performance standards for patient rooms and surgical suites, accelerating specification of certified coatings in new construction and renovation contracts.
- REACH BPR harmonization:Europe's Biocidal Products Regulation streamlines active substance approval across member states, reducing regulatory fragmentation and enabling pan-European formulation platforms for silver-ion and zinc-based systems.
- Tropical humidity exposure:India's coastal and monsoon-zone residential construction experiences accelerated fungal colonization on untreated surfaces, creating sustained replacement demand for moisture-resistant antimicrobial coatings in apartment complexes and commercial developments.
Market Restraints
- Silver nanoparticle cost volatility:Precious metal price swings and concentrated mining supply from Peru and Mexico compress margin stability for premium antimicrobial formulations.
- Biocidal authorization timelines:EPA FIFRA registration cycles extending 18-36 months delay product launch schedules and freeze formulation investments for emerging active substances.
- UV-C surface disinfection substitution:Healthcare facilities deploy room-scale ultraviolet sterilization systems that reduce perceived necessity of permanent antimicrobial coating properties on non-critical surfaces.
Strategic Opportunities
- Southeast Asia construction expansion:Vietnam and Indonesia's commercial real estate development in high-humidity zones lacks mature antimicrobial coating specification standards, creating first-mover positioning for humidity-optimized formulations.
- Food processing facility mandates:FDA Food Safety Modernization Act inspection protocols drive coating replacement cycles in meat processing and dairy operations where microbial biofilm control is compliance-critical.
- Photocatalytic-nano hybrid convergence:Titanium dioxide photocatalytic oxidation combined with silver-ion release creates dual-mode antimicrobial systems with extended efficacy duration in exterior architectural applications.
Industry Challenges
- Applied microbiology talent scarcity:Formulation chemists with biocidal efficacy testing expertise and EPA submission experience command premium compensation and extended recruitment timelines.
- Legacy coating system incompatibility:Antimicrobial topcoats require substrate-specific adhesion promoters and cure-condition matching, complicating retrofit application over existing alkyd or epoxy surfaces in renovation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Fungal and Anti-Bacterial Paints Market |
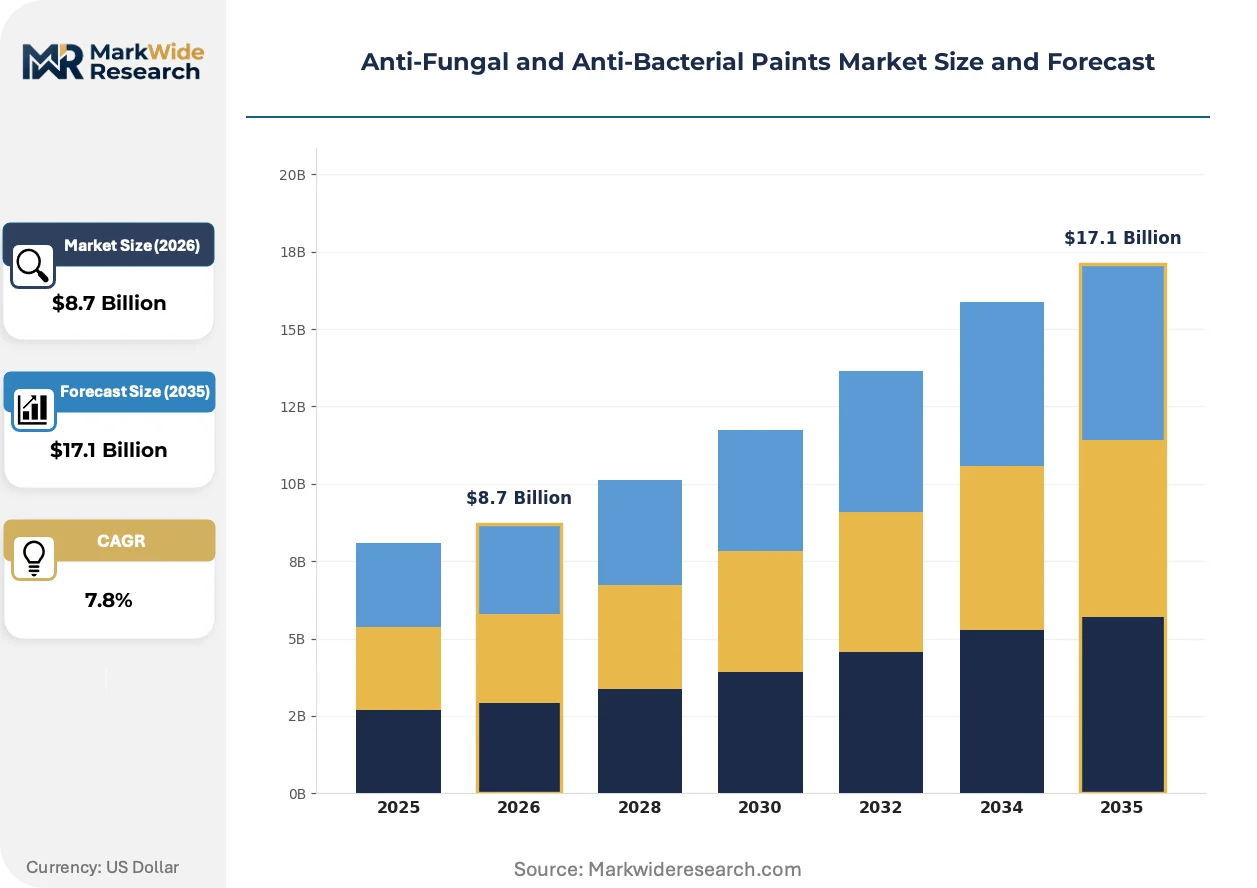
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Paints, Exterior Paints, Primers, Sealants Application: Residential, Commercial, Industrial, Healthcare Technology: Water-Based, Solvent-Based, Nano-Coatings, Hybrid Coatings End User: Architects, Contractors, DIY Consumers, Facility Managers |
| Companies Covered | AkzoNobel N.V., PPG Industries, Sherwin-Williams Company, BASF SE, Axalta Coating Systems, Nippon Paint Holdings, RPM International Inc., 3M Company, Hempel A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Fungal and Anti-Bacterial Paints Market Strategic Shifts
Formulation chemistry is pivoting toward durability-validated systems that maintain antimicrobial efficacy across multi-year service intervals rather than relying on initial biocidal loading claims.
Nano-encapsulated biocide delivery is electrifying coating performance architecture by enabling controlled-release kinetics that extend silver-ion or quaternary ammonium efficacy from months to years. Hospital facility engineering departments in Germany and Japan specify these systems for high-touch surface applications where frequent re-coating disrupts operational continuity. The technology is electrifying competitive positioning by compressing total-cost-of-ownership calculations and displacing conventional high-loading formulations that sacrifice film integrity for initial microbial kill rates.
EPA's 2024 updated guidance on public health claims for antimicrobial coatings tightens efficacy disclosure requirements and mandates standardized test method references on product labels. Manufacturers must re-register existing products or restrict marketing language to non-public health positioning, forcing portfolio segmentation between institutional-grade registered products and residential decorative coatings. Water-based interior formulations targeting United States healthcare construction face the steepest compliance recertification burden.
Facility managers increasingly bundle antimicrobial coating specification into multi-year facilities management contracts rather than discrete material procurement events. General contractors and specialty coating applicators in India's hospital construction sector consolidate specification influence by offering performance-guaranteed installation packages. This consolidation is most visible in Maharashtra and Karnataka state healthcare infrastructure programs where single-source responsibility for surface hygiene outcomes drives vendor selection criteria.
Anti-Fungal and Anti-Bacterial Paints Market Segmentation
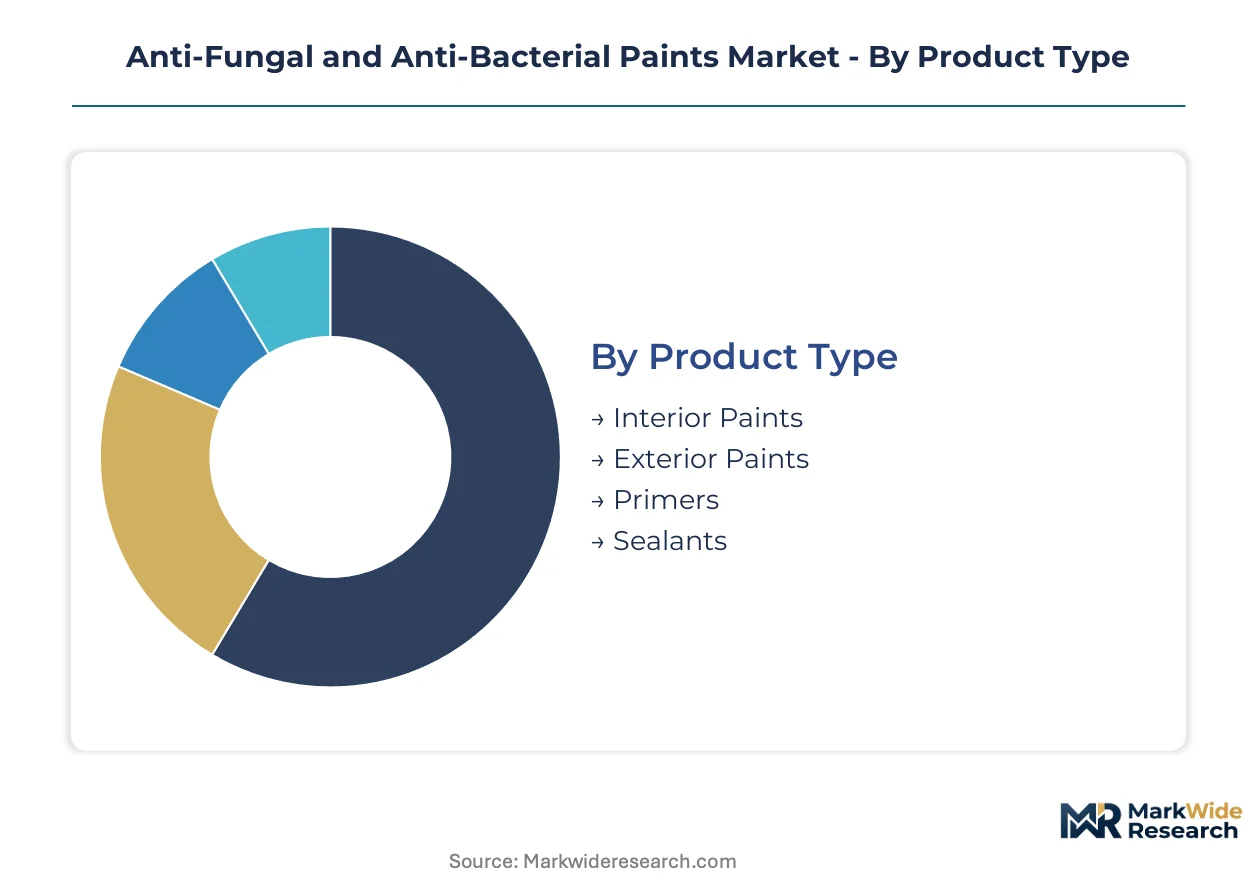
Anti-fungal and anti-bacterial paints serve divergent performance requirements across moisture-prone residential bathrooms, sterile surgical suites, and industrial food processing zones. Segmentation reveals how formulation chemistry, application protocol, and procurement authority reshape competitive positioning within each vertical.
Product Type:
Customization intensity spans from commodity architectural coatings to engineered multi-layer systems with validated biocidal durability certificates.
- Interior Paints:Water-based acrylic-urethane hybrids incorporating silver-ion or quaternary ammonium biocides at 0.5-2% loading dominate healthcare patient room specifications. Hospital renovation contracts in Maharashtra and Karnataka drive repetitive re-coating cycles where EPA-registered efficacy claims command specification priority.
- Exterior Paints:Alkyd and silicone-modified acrylic systems resist UV degradation and monsoon-driven fungal colonization on Indian coastal commercial facades. Titanium dioxide photocatalytic additives gain traction where extended service intervals reduce maintenance access costs.
- Primers:Substrate-specific adhesion promoters with embedded zinc pyrithione prevent osmotic blistering on concrete and gypsum board in high-humidity zones.
- Sealants:Elastomeric polyurethane and silicone formulations with quaternary ammonium surface modification protect expansion joints and facade penetrations from microbial biofilm accumulation.
Leading the category by volume: Interior Paints. Growing fastest: Exterior Paints with photocatalytic hybrid systems.
Application:
Project scale and regulatory scrutiny intensity separate institutional procurement from residential discretionary purchasing.
- Residential:Apartment complex developers in Vietnam and Indonesia specify humidity-optimized formulations for bathrooms and kitchens where mold-related tenant complaints drive replacement liability. DIY consumers in United States home improvement channels prioritize low-VOC water-based products with decorative finish compatibility.
- Commercial:Office and retail construction in Southeast Asian high-humidity zones lacks mature antimicrobial specification standards, creating first-mover positioning for performance-guaranteed installation packages.
- Industrial:Food processing and pharmaceutical manufacturing facilities require chemical-resistant solvent-based epoxy systems that withstand aggressive cleaning protocols.
- Healthcare:United States hospital infection control mandates specify antimicrobial surface performance standards for patient rooms and surgical suites, accelerating certified coating adoption in new construction and renovation contracts.
Healthcare commands premium pricing power. Residential delivers largest unit volumes across tropical humidity markets.
Technology:
Regulatory maturity and performance validation requirements segment formulation platforms by geographic market access.
- Water-Based:Acrylic and polyurethane dispersions dominate regulatory-permissive markets where VOC restrictions have matured, particularly United States healthcare construction facing EPA FIFRA compliance recertification burdens.
- Solvent-Based:Rapid-cure epoxy and polyurethane systems retain share in industrial applications requiring chemical resistance and substrate tolerance where ventilation permits higher VOC content.
- Nano-Coatings:Thin-film antimicrobial efficacy reduces material usage per treated area while nano-encapsulated biocide delivery extends silver-ion release kinetics from months to years in German and Japanese hospital high-touch surface specifications.
- Hybrid Coatings:Titanium dioxide photocatalytic oxidation combined with silver-ion release creates dual-mode systems with extended efficacy duration in exterior architectural applications.
Nano-Coatings expand most quickly on total-cost-of-ownership compression. Water-Based formulations retain largest installed base.
End User:
Technical specification authority and procurement contract structure determine channel access requirements.
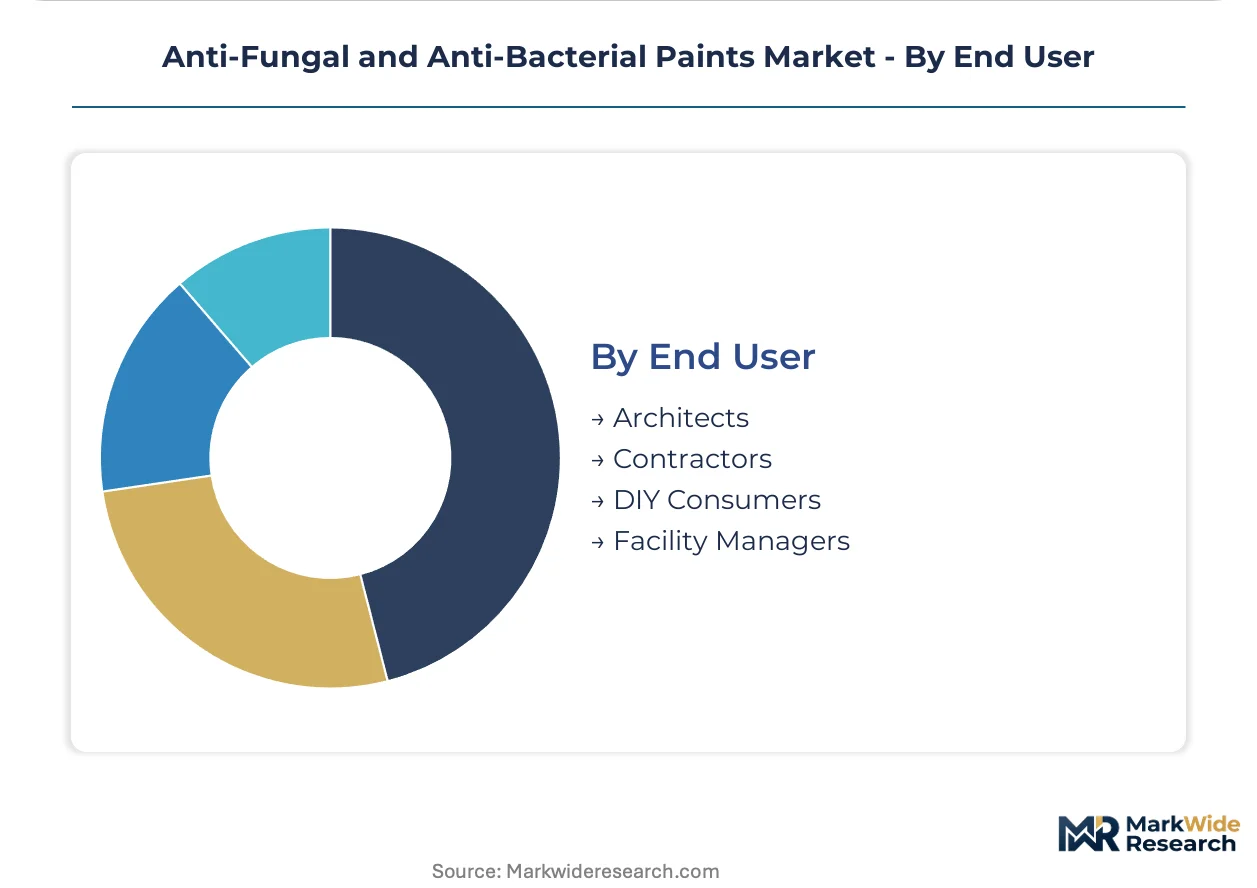
- Architects:Design-phase specification of EPA-registered products for United States healthcare and institutional projects demands third-party certification documentation and standardized test method references.
- Contractors:General contractors and specialty applicators in India's hospital construction sector consolidate influence through performance-guaranteed installation bundles covering surface preparation, application, and efficacy validation.
- DIY Consumers:Home improvement retail channels in United States and European markets favor ready-mixed water-based products with simplified application instructions and immediate availability.
- Facility Managers:Multi-year facilities management contracts increasingly bundle antimicrobial coating specification with guaranteed surface hygiene outcomes rather than discrete material procurement.
Facility Managers concentrate procurement power through outcome-based contracting. DIY Consumers provide highest volume fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare facility construction and tropical humidity exposure concentrate demand across distinct geographic clusters, with regulatory stringency and climate conditions reshaping procurement patterns in each market.
United States
Hospital infection control mandates from the Centers for Medicare & Medicaid Services now specify antimicrobial surface performance standards for patient rooms and surgical suites. EPA FIFRA registration requirements tighten efficacy disclosure for products asserting public health benefits. The Texas Medical Center in Houston and Boston's Longwood Medical Area anchor specification demand for EPA-registered coatings in renovation contracts.
Germany
REACH BPR harmonization streamlines active substance approval across EU member states, enabling pan-European formulation platforms. The country's national pharmaceutical regulator enforces stringent efficacy validation for coatings contacting medical device surfaces. The Rhine-Ruhr industrial corridor concentrates demand from pharmaceutical manufacturing facilities requiring chemical-resistant antimicrobial systems.
India
Tropical humidity accelerates mold-related coating degradation in residential and commercial structures across coastal and monsoon zones. BIS certification requirements for construction materials increasingly incorporate antimicrobial performance benchmarks. Maharashtra and Karnataka state healthcare infrastructure programs drive specification of humidity-optimized formulations through performance-guaranteed installation contracts.
Japan
Hospital facility engineering departments specify nano-encapsulated biocide delivery systems for high-touch surface applications where operational continuity limits re-coating frequency. METI industrial standards guide antimicrobial coating performance claims in healthcare and food processing sectors. The Kanto region around Tokyo concentrates demand from aging healthcare infrastructure requiring surface hygiene upgrades.
Vietnam
Commercial real estate development in high-humidity zones lacks mature antimicrobial coating specification standards, creating positioning opportunities for humidity-optimized formulations. The country's construction quality standards are evolving to address mold-related building envelope failures. Ho Chi Minh City and Hanoi metro areas anchor demand from apartment complex developers seeking tenant complaint reduction.
Anti-Fungal and Anti-Bacterial Paints Market Competitive Environment
North American producers anchor one tier; Asia-Pacific specialists hold differentiated positions in humidity-zone formulations. The vendor base spans consolidated multinational chemical conglomerates and regional coating formulators with regulatory affairs capacity. Three archetypes dominate: scale-driven architectural coating distributors, specialty polymer additive suppliers, and nano-technology licensing specialists. Competitive dynamics center on EPA registration acquisition speed and tropical climate performance certification.
Within the scale-driven tier, PPG Industries and Sherwin-Williams Company occupy positions tied to institutional channel access and healthcare construction specification networks. BASF SE exemplifies the specialty additive archetype through polymer chemistry capabilities that enhance biocidal durability. Nippon Paint Holdings anchors the Asia-Pacific humidity-zone specialization vector where fungal resistance commands premium positioning.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| PPG Industries |
| Sherwin-Williams Company |
| BASF SE |
| Axalta Coating Systems |
| Nippon Paint Holdings |
| RPM International Inc. |
| 3M Company |
| Hempel A/S |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialty coating formulators in the United States have consolidated regional applicator networks, tightening pricing discipline through captive distribution while compressing procurement leverage for independent contractors in India's Maharashtra healthcare construction corridor.
Pricing Analysis
Volume-driven residential coatings in Vietnam and Indonesia compete on thin margins against humidity-optimized formulations, while EPA-registered healthcare-grade systems in the United States command substantial premiums through third-party certification requirements. Price differentiation hinges on EPA FIFRA registration status and silver-ion biocide loading concentration. Pricing pressure intensifies in Southeast Asian commercial construction where specification standards remain immature and local formulators undercut imported systems. DIY consumers in United States home improvement channels exhibit highest price sensitivity; hospital facility managers in Germany and Japan prioritize total-cost-of-ownership over unit pricing.
Supply Chain Analysis
Returns and refurbishment flows remain minimal given coatings' irreversible cure chemistry, though remnant inventory from failed EPA registration attempts occasionally resurfaces in gray-market channels. Raw material sourcing concentrates in China for titanium dioxide photocatalytic additives, Peru and Mexico for silver nanoparticles, and Germany for specialty polymer dispersions. Single-source vulnerability in precious metal biocide supply creates margin instability when mining output fluctuates. Distribution runs through consolidated architectural coatings distributors in North America and performance-guaranteed installation contractors in India's hospital construction sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nano-encapsulated biocide delivery systems are displacing conventional high-loading formulations, compressing competitive timelines for manufacturers dependent on legacy release-kinetics chemistry.
For Market Incumbents: Extend EPA registration portfolios into nano-encapsulated platforms before efficacy validation requirements tighten further. Secure backward integration into silver-ion supply through offtake agreements with Peruvian and Mexican mining operations to buffer precious metal volatility. Channel control through performance-guaranteed installation bundles in India's state healthcare programs defends position against emerging humidity-zone specialists. For New Entrants and Emerging Players: Begin with commercial real estate developers in Vietnam and Indonesia where antimicrobial specification standards remain underdeveloped and first-mover positioning carries specification influence. Target food processing facility mandates under FDA Food Safety Modernization Act protocols where compliance-critical biofilm control creates replacement demand. Partner with regional applicator networks offering installation-efficacy guarantees rather than competing on material pricing alone. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap formulators with existing EPA FIFRA registrations and tropical climate performance certification in India's coastal states, where construction quality standard evolution will consolidate procurement toward validated suppliers. Long-term viability centers on regulatory affairs capacity and biocidal durability validation rather than commodity coating manufacturing. Monitor EPA guidance updates on public health claims as inflection signals for portfolio re-registration costs.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Registration Portfolio Expansion | Secures institutional channel access under tightening FIFRA efficacy disclosure requirements. |
| Silver-Ion Supply Integration | Reduces margin exposure to Peruvian and Mexican mining output fluctuations. |
| Nano-Encapsulation Licensing | Accelerates controlled-release kinetics development for German and Japanese hospital specifications. |
| Southeast Asian Applicator Partnerships | Establishes performance-guaranteed installation presence ahead of specification standard maturation. |
| Photocatalytic Hybrid R&D Investment | Creates dual-mode antimicrobial systems for exterior architectural applications in tropical zones. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with coating formulation chemists, EPA regulatory affairs consultants, hospital facility engineering directors, and specialty applicator contractors in India and Southeast Asia. Secondary validation drew from EPA FIFRA registration databases, REACH BPR authorization timelines, BIS construction material certifications, and import-export statistics for biocidal active substances. Bottom-up volume estimates by application segment triangulated against top-down market sizing from architectural coatings consumption trends.
Granularity-level modeling distinguished water-based versus solvent-based formulation platforms, interior versus exterior application protocols, and nano-coating versus conventional biocide delivery systems across the projection horizon. Segmentation dimensions included product type, application vertical, technology platform, and end-user procurement authority. CAGRs derived from regression analysis of historical coating consumption against healthcare construction expenditure and humidity-zone building stock growth. Forecast inputs incorporated EPA registration pipeline timelines and tropical climate performance certification adoption curves.
Underlying measurement precision varies by segment; healthcare-grade EPA-registered coatings carry tighter precision than emerging nano-coating volumes where standardization remains incomplete. Forecasts incorporate assumptions regarding regulatory authorization timelines and silver price trajectories that could shift materially. Practitioners should monitor EPA guidance updates on public health claims and REACH BPR active substance approval acceleration for early signals of competitive access restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Nordic Countries Architectural Coatings Market
Paints & Coatings
Fire Resistant Paints Market
Paints & Coatings
Floor Paints Market
Paints & Coatings
Mexico Paints and Coatings Market
Paints & Coatings
Decorative Paints Market
Paints & Coatings
Global Exterior Architectural Coatings Market
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
Water-Soluble Paints Market
Paints & Coatings
Food Grade Epoxy Paint Market
Paints & Coatings
Paint Defoamers Market
Paints & Coatings
Mosquito-Repellent Paints Market
Paints & Coatings
Iraq Paints and Coatings Market
Paints & Coatings
Automotive Coatings Market
Paints & Coatings
Saudi Arabia Paints and Coatings Market
Paints & Coatings
Faux Paints and Coatings Market
Paints & Coatings
Cellulose Paints Market