
 Water Color Market | 2026-2036
Water Color Market Size, Share, and Industry Trends Forecast 2026-2036
Water Color Market Analytics
Multi-source pigment procurement is hardening among European and North American manufacturers seeking supply resilience against raw material volatility. Winsor & Newton leverages its long-standing relationships with pigment mills to secure consistent quinacridone and phthalocyanine supplies. Daniel Smith differentiates through in-house mineral grinding operations that yield unique Primatek earth pigments unavailable from commodity suppliers. Schmincke sustains its competitive position by anchoring production in Germany with vertically integrated binder chemistry laboratories.
Water color comprises finely ground pigments suspended in a water-soluble gum arabic binder, typically formulated at pigment-to-binder ratios between 1:1 and 2:1 to achieve transparent, re-wettable color layers for paper-based artistic and illustration applications. Watercolor paints occupy the dominant revenue position due to their established use in academic curricula and professional ateliers, while watercolor pencils represent the fastest-expanding format as mixed-media artists seek portable, precise alternatives to traditional brush application. Acrylic watercolors sit at the premium margin frontier where reformulated polymer binders attract illustrators requiring waterproof finished surfaces.
EU REACH and the F-Gas Regulation constrain volatile solvent use in manufacturing facilities, pushing producers toward aqueous dispersion systems that align with existing water color chemistry. FDA oversight of cosmetic-grade pigments imported for artist material cross-use demands batch testing documentation that smaller distributors struggle to maintain. Stakeholders must monitor evolving classification thresholds under the EU Green Deal that could recategorize certain cadmium and cobalt pigments as substances of very high concern, forcing reformulation investments or portfolio exits.
Market Dynamics
Formulation chemistry is converging with environmental compliance as EU REACH substance classifications force pigment reformulation across legacy product lines. Manufacturers face simultaneous pressure to maintain lightfastness performance while eliminating cadmium and cobalt compounds.
Growth Catalysts
- Art School Procurement:German academic institutions are expanding lightfast pigment purchases for studio curricula. This institutional demand creates stable volume anchors for premium formulation tiers.
- Traditional Technique Preservation:Japan's nihonga painting academies sustain consumption of premium mineral pigments. Cultural heritage programs subsidize artisan-grade material acquisition.
- F-Gas Regulation Alignment:The EU F-Gas Regulation on fluorinated gases is accelerating aqueous dispersion adoption in manufacturing facilities. Existing water color chemistry infrastructure absorbs this transition cost-efficiently.
Market Restraints
- Raw Material Concentration:Quinacridone and phthalocyanine pigment synthesis concentrates in Chinese and Indian chemical clusters. Geopolitical friction threatens just-in-time supply reliability for European formulators.
- REACH Compliance Burden:ECHA substance evaluation timelines extend 18-36 months for novel pigment registrations. Smaller distributors lack capital reserves for prolonged regulatory dossier preparation.
- Acrylic Substitution:Reformulated polymer-bound water media attract illustrators requiring waterproof finished surfaces. These hybrid products capture premium margin segments from traditional gum arabic formulations.
Strategic Opportunities
- Indian Professional Segment:Mumbai and Delhi studio clusters show underpenetrated demand for artist-grade lightfast ranges. Domestic distributors lack technical service depth for professional pigment consultation.
- Cosmetic-Grade Cross-Use:FDA cosmetic pigment oversight creates batch documentation requirements that compliant manufacturers can leverage. Artist material distributors with existing cosmetic testing infrastructure capture dual-market positioning.
- Digital-Native Channel Expansion:Direct-to-artist subscription models bypass traditional art supply retail. Social media tutorial creators drive viral demand spikes for specific pigment formulations.
Industry Challenges
- Mineral Grinding Expertise Scarcity:Primatek-style earth pigment production requires geological sourcing and particle size control skills. Art chemistry programs produce fewer graduates with hands-on mineral processing experience.
- Green Deal Reclassification Risk:Pending EU Green Deal substance reviews may recategorize additional heavy metal pigments. Manufacturers face portfolio rationalization investments with uncertain timing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Color Market |
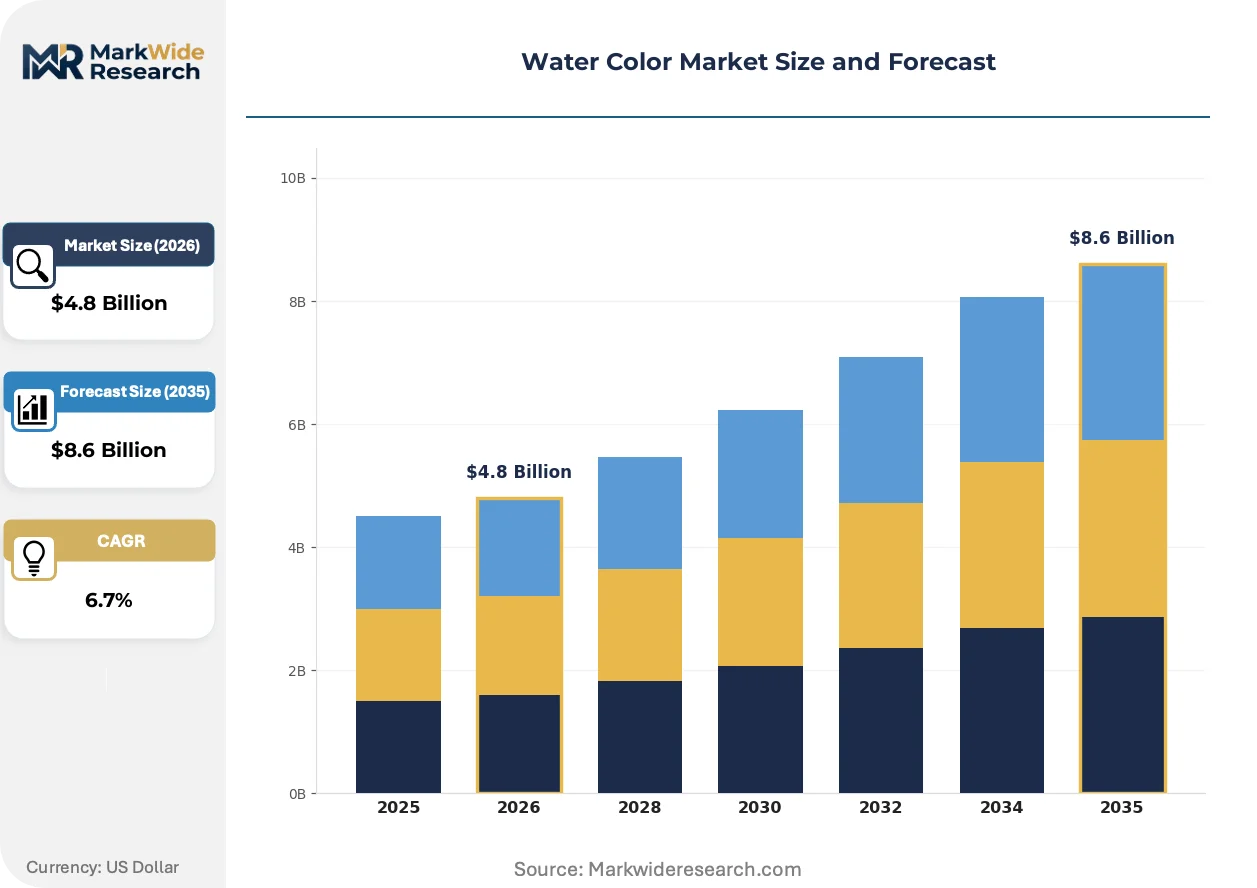
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Watercolor Pencils, Watercolor Paints, Watercolor Markers End User: Artists, Students, Hobbyists, Professionals Distribution Channel: Online Retail, Specialty Stores, Art Supply Stores, Wholesale Packaging Type: Tubes, Pans, Sets, Jars |
| Companies Covered | Sennelier, M. Graham, Winsor & Newton, Rembrandt, Old Holland, Daniel Smith, Holbein, Daler Rowney, Schmincke, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Color Market Evolving Landscape
Product architecture is fragmenting into specialized formats as mixed-media practitioners reject one-size-fits-all solutions. Technology convergence between traditional pigment chemistry and modern application methods is redrawing competitive boundaries.
Portable watercolor pencil systems are modularizing the creative workflow for plein air and travel artists. These formats combine dry pigment precision with water-activated wash capability. Urban sketching communities in Barcelona, Melbourne, and Seoul are adopting multi-format travel kits that integrate pencils with compact pan sets. The technology is modularizing supplier revenue models toward component-based rather than kit-based purchasing.
EU REACH authorization requirements for cadmium pigments are compressing formulation timelines across German and French manufacturing facilities. ECHA sunset date negotiations force portfolio decisions before toxicological data completion. Professional-grade lines face reformulation investments while student-grade alternatives absorb displaced volume.
Social media tutorial commerce is compressing product discovery cycles from seasonal to viral velocity. YouTube and Instagram demonstration content drives immediate pigment demand spikes for specific color indices. Korean and Brazilian online art communities demonstrate the strongest conversion from content engagement to direct purchase.
Water Color Market Segmentation
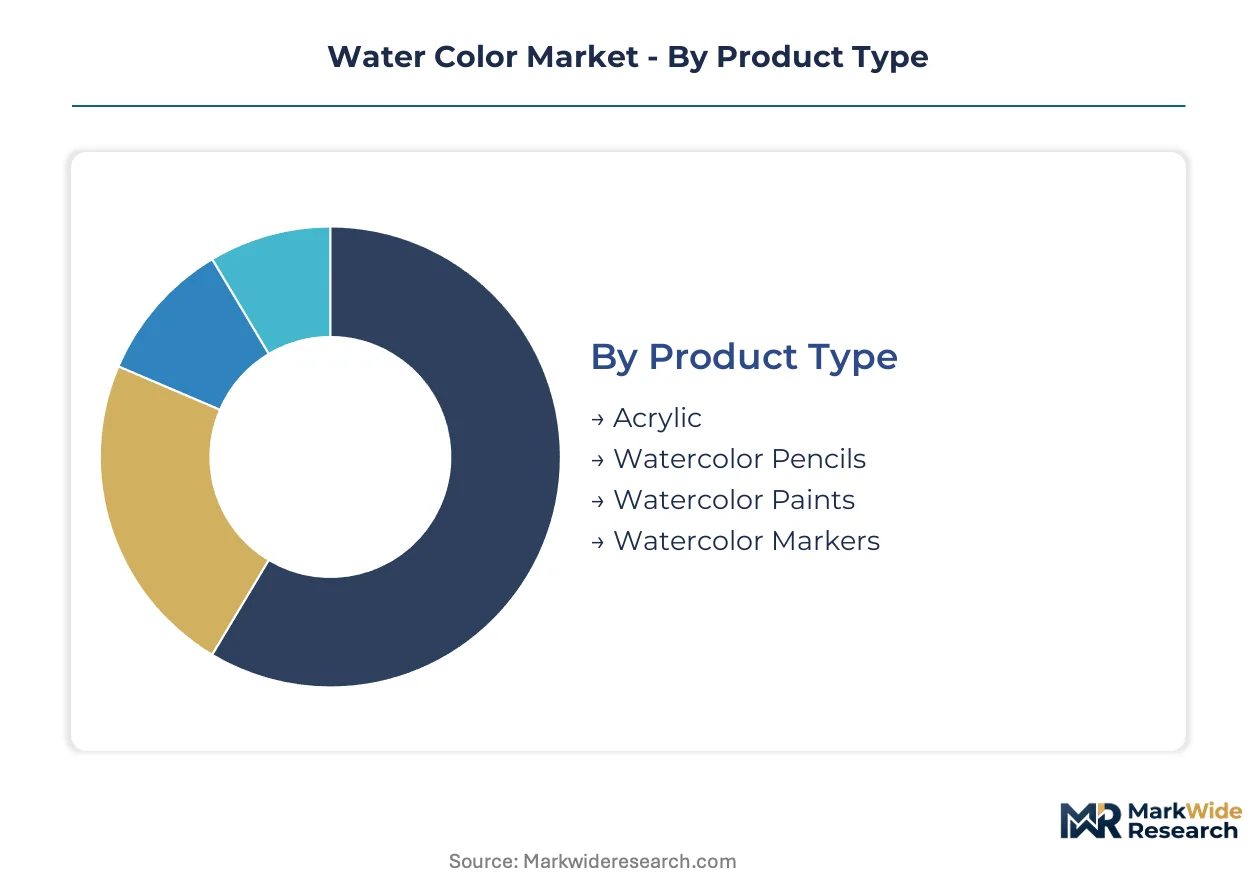
Water color segmentation reveals divergent supply chain configurations across format categories. Each dimension carries distinct procurement patterns, formulation requirements, and margin structures that reshape competitive positioning.
Product Type:
Pigment sourcing concentration determines cost structures and technical differentiation across water color formats.
- Watercolor Paints:Finely ground pigments suspended in gum arabic binder at 1:1 to 2:1 pigment-to-binder ratios enable transparent, re-wettable layers. German art schools and Japanese nihonga academies anchor institutional procurement of lightfast formulations.
- Watercolor Pencils:Dry pigment cores encased in wood or synthetic barrels activate with water application. Urban sketching communities in Barcelona, Melbourne, and Seoul drive portable format adoption through multi-format travel kit integration.
- Acrylic:Polymer-bound reformulations deliver waterproof finished surfaces for illustrators requiring durability.
- Watercolor Markers:Pre-activated liquid pigment in felt-tip applicators suit rapid illustration workflows.
Watercolor paints absorb the bulk of installed capacity; watercolor pencils are expanding most quickly.
End User:
Customer sophistication tiers segment pricing power and service intensity requirements.
- Artists:Professional practitioners demand lightfast ratings, single-pigment formulations, and batch consistency for archival work. EU REACH compliance documentation and toxicological data support premium positioning.
- Professionals:Commercial illustrators and designers prioritize waterproof acrylic alternatives and rapid application formats for client deliverables.
- Students:Academic curricula in German institutions drive volume procurement of student-grade lines with reduced cadmium content.
- Hobbyists:Recreational practitioners favor convenience formats and pre-mixed sets with lower technical service requirements.
Artists command the highest margin tier; professionals show the steepest format diversification.
Distribution Channel:
Channel selection reflects customer journey complexity and technical consultation needs.
- Art Supply Stores:Staff expertise in pigment properties and lightfast testing supports professional purchase decisions. Physical inspection of color charts and wet samples sustains format relevance.
- Online Retail:Direct-to-artist subscription models and social media tutorial commerce compress discovery-to-purchase cycles. Korean and Brazilian online art communities demonstrate strongest content-to-conversion velocity.
- Specialty Stores:Curated assortments target specific technique practitioners with premium positioning.
- Wholesale:Institutional procurement for art schools and studio clusters concentrates volume in contracted supply arrangements.
Art supply stores retain the professional core; online retail is climbing the fastest.
Packaging Type:
Container engineering intersects with portability requirements and studio storage constraints.
- Pans:Semi-moist cakes in plastic or metal trays suit plein air portability and travel kit modularity. Urban sketching adoption in Barcelona and Seoul drives compact format demand.
- Tubes:Paste consistency in collapsible metal enables large wash preparation and custom palette mixing. Studio-based professionals favor capacity and color control.
- Sets:Pre-curated color assortments reduce decision friction for entry-level practitioners and gift purchasers.
- Jars:Bulk liquid formats serve classroom and workshop environments with high-volume consumption patterns.
Tubes retain the professional studio standard; pans are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gum arabic harvesting in Sudan and pigment synthesis clusters in China and India anchor the raw material geography for water color manufacturing. These supply nodes connect to formulation centers in Germany, Japan, and the United States where binder chemistry expertise concentrates. Distribution networks radiate from these nodes to academic and professional end-users worldwide.
Germany
Art schools in Berlin and Leipzig are expanding procurement of lightfast pigment formulations for studio curricula. ECHA substance evaluation timelines under REACH extend 18-36 months for novel pigment registrations, compressing formulation investment windows. Manufacturing facilities in Hesse and Bavaria maintain vertically integrated binder chemistry laboratories serving European professional demand.
Japan
Nihonga painting academies in Kyoto and Tokyo sustain consumption of premium mineral pigments through cultural heritage preservation programs. METI subsidizes artisan-grade material acquisition for traditional technique transmission. Osaka-based distributors coordinate supply chains linking domestic mineral processors to academic institutions and professional ateliers.
United States
Commercial illustrators in New York and Los Angeles drive demand for waterproof acrylic watercolor alternatives. FDA oversight of cosmetic-grade pigments demands batch testing documentation that compliant manufacturers leverage for dual-market positioning. Seattle and Portland studio clusters anchor Pacific Northwest demand for portable plein air formats.
India
Mumbai and Delhi professional studio clusters show underpenetrated demand for artist-grade lightfast ranges. BIS standards for artist materials remain less stringent than EU REACH, creating quality tier fragmentation. Domestic distributors in Maharashtra lack technical service depth for professional pigment consultation, opening channels for specialized importers.
China
Quinacridone and phthalocyanine pigment synthesis concentrates in Jiangsu and Zhejiang chemical clusters. MEE environmental enforcement is tightening aqueous discharge standards for manufacturing facilities. Shenzhen and Guangzhou export hubs coordinate raw material flows to European and North American formulators despite geopolitical friction risks.
Water Color Market Competitive Landscape
Global majors compete with regional champions across pigment sourcing and binder chemistry capabilities. The vendor base spans vertically integrated European heritage houses, North American specialty grinders, and Asian manufacturing platforms. Three archetypes dominate: heritage European formulators with captive laboratory infrastructure, North American mineral grinding specialists, and Asian production platforms serving volume tiers. Consolidation pressure operates through M&A activity targeting pigment mill access and strategic partnerships for REACH compliance dossier sharing.
Within the heritage European tier, Winsor & Newton and Schmincke exemplify vertically integrated formulators with long-standing pigment mill relationships. Daniel Smith occupies a position among North American specialists distinguished by in-house mineral grinding operations. These three anchors represent divergent supply chain configurations: European laboratory integration, Asian raw material access, and American geological sourcing expertise.
| Leading Market Players |
|---|
| Sennelier |
| M. Graham |
| Winsor & Newton |
| Rembrandt |
| Old Holland |
| Daniel Smith |
| Holbein |
| Daler Rowney |
| Schmincke |
| Others |
Value Network & Pricing Analysis
Gum arabic harvest volatility in Sudan transmits directly through formulation costs to European and Japanese premium tiers, while pigment synthesis concentration in Chinese and Indian chemical clusters compresses margins for mid-market student-grade lines dependent on just-in-time phthalocyanine and quinacridone procurement.
Pricing Analysis
Lightfastness certification and REACH dossier documentation are bundled into professional-grade pricing, with unbundled student lines competing on raw pigment cost alone. Three-tier pricing structure across premium, standard, and economy levels separates archival single-pigment formulations from blended student alternatives. Cost compression in student tiers is intensifying because BIS-compliant Indian imports undercut REACH-certified European production. Hobbyists and academic bulk purchasers show highest price sensitivity; nihonga academies and German ateliers demonstrate lowest.
Supply Chain Analysis
Container freight rate fluctuations between Shanghai and Hamburg directly impact landed costs for European formulators sourcing from Jiangsu and Zhejiang pigment synthesis clusters. Formulation chemistry rests on gum arabic from Sudanese acacia belt harvesting, mineral pigments from domestic Japanese processors, and synthetic organics from Chinese chemical parks. Single-source vulnerability concentrates in quinacridone pigment synthesis where Indian alternatives lack capacity scale. Distribution runs through Osaka and Berlin distributor hubs serving academic and professional ateliers with technical consultation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mineral grinding expertise scarcity props pricing for Primatek-style earth pigment specialists, constraining supply expansion even as nihonga and plein air demand climbs.
For Market Incumbents: Deploy REACH dossier co-development partnerships to spread regulatory compliance costs across mid-tier European competitors. Acquire captive mineral grinding capacity in Pacific Northwest or Japanese domestic sources to secure Primatek-style pigment supply against Chinese raw material friction. Acrylic watercolor substitution threatens traditional gum arabic margin pools. For New Entrants and Emerging Players: Enter via direct-to-artist subscription models targeting Korean and Brazilian online art communities with viral tutorial commerce integration. Mumbai and Delhi professional studio clusters offer the most penetrable geography given domestic distributor technical service gaps. Social media pigment education content lowers customer acquisition costs versus traditional art supply retail. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated German heritage houses with captive laboratory infrastructure and existing REACH compliance dossiers. Five-to-ten year viability hinges on cadmium and cobalt reformulation completion before EU Green Deal reclassification deadlines. Watch ECHA sunset date announcements as inflection signal for forced portfolio rationalization investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Grinding | Daniel Smith's Primatek operations demonstrate defensible positioning against commodity pigment suppliers. |
| REACH Dossier Sharing Partnerships | Schmincke and Winsor & Newton reduce per-SKU compliance burden through collaborative ECHA submissions. |
| Direct-to-Artist Subscription Launch | Korean Instagram tutorial creators convert engagement spikes into recurring revenue bypassing retail markup. |
| Cosmetic-Grade Cross-Use Certification | FDA batch documentation investment unlocks dual-market positioning for compliant manufacturers. |
| Aqueous Dispersion Manufacturing Transition | F-Gas Regulation alignment absorbs existing water color chemistry infrastructure cost-efficiently. |
Research Methodology
Document review covered ECHA substance evaluation timelines, METI cultural heritage subsidy disclosures, and BIS artist material standards, complemented by interviews with German art school procurement officers, Japanese nihonga academy directors, Indian distributor technical service leads, and Sudanese gum arabic cooperative representatives. Secondary validation drew from customs trade data, SEC filings of listed art material suppliers, and academic curriculum procurement records. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Cross-referencing historical pigment consumption patterns with panel input from formulation chemists anchored growth projections. Segmentation dimensions modeled include product format, end-user sophistication tier, distribution channel, and regional regulatory cluster. CAGRs derived from iterative reconciliation between supply-side capacity expansion announcements and demand-side institutional procurement commitments. Lightfastness rating adoption curves and REACH compliance investment timelines served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA accelerated reclassification scenarios or Sudanese gum arabic harvest disruption. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
India Industrial Coatings Market
Paints & Coatings
Nordic Countries Architectural Coatings Market
Paints & Coatings
Paint Buckets Market
Paints & Coatings
Metal Paint Tray Market
Paints & Coatings
Oman Paints and Coatings Market
Paints & Coatings
Polyolefin Resin Paints Market
Paints & Coatings
Global Exterior Architectural Coatings Market
Paints & Coatings
North America Paints and Coatings Market
Paints & Coatings
Epoxy Paint Thinner Market
Paints & Coatings
Egypt Paints and Coatings Market
Paints & Coatings
Refinish Paint Market
Paints & Coatings
Alkyd Coatings Market
Paints & Coatings
Resins in Paints and Coatings Market
Paints & Coatings
Middle-East and Africa Wood Coatings Market
Paints & Coatings
Middle-East Paints and Coatings Market
Paints & Coatings
US Paints and Coatings Market