
 India Automotive OEM Coatings Market | 2026-2036
India Automotive OEM Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive OEM Coatings Market Foresight
Skilled paint shop technicians and color chemists is redrawing competitive boundaries across India's automotive belt. Kansai Nerolac Paints Limited leverages its long-standing supply relationships with Maruti Suzuki and Tata Motors to sustain dominant share in passenger vehicle clear coat systems. Asian Paints anchors its position through backward integration into resin manufacturing, while Axalta Coating Systems LLC competes on technology leadership in electrocoat primer formulations for commercial vehicle chassis applications.
India Automotive OEM Coatings encompass solvent-based, water-based, and powder formulations engineered to deliver corrosion resistance, UV stability, and aesthetic finish on vehicle bodies, frames, and component assemblies, with film thickness specifications typically ranging from 15 to 40 microns depending on substrate and functional layer. Waterborne technology segments are gaining ground as BIS emission norms and OEM sustainability mandates tighten, while powder coatings occupy niche positions in chassis and engine component lines where edge coverage and chip resistance justify capital-intensive application systems. Two-wheeler exterior applications represent a volume-driven segment where cost-per-liter dominates procurement decisions, contrasting with passenger vehicle base coat segments where color-matching precision and flop control command premium positioning.
BIS standards for automotive coatings, supplemented by Central Pollution Control Board VOC guidelines and state-level pollution control mandates in Maharashtra and Tamil Nadu, are forcing reformulation timelines and capital allocation toward compliant resin systems. CDSCO oversight intersects indirectly where coating raw materials contact interior cabin surfaces, adding biocompatibility testing layers to supplier qualification protocols. Stakeholders must monitor how PLI scheme disbursements for electric vehicle manufacturing reshape paint shop specifications, as battery enclosure coatings and thermal management layers introduce performance criteria distinct from conventional body-in-white requirements.
Market Dynamics
BIS certification timelines are compressing reformulation windows for coating suppliers serving Maruti Suzuki and Tata Motors assembly lines across Tamil Nadu and Maharashtra. Waterborne primer specifications are displacing solvent-based systems faster than resin capacity can retool.
Growth Catalysts
- PLI scheme disbursements:Electric vehicle manufacturing incentives are triggering dedicated paint shop investments for battery enclosure thermal management coatings in Gujarat's automotive corridor.
- Two-wheeler export specifications:Southeast Asian and African destination markets are demanding enhanced UV stability and chip resistance from Indian OEM coating suppliers.
- BIS VOC emission thresholds:Tightening compliance deadlines are accelerating waterborne base coat adoption across passenger vehicle assembly plants in Pune and Chennai clusters.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and epoxy resin input costs swing with crude derivative pricing, squeezing margin predictability for mid-tier formulators.
- Import dependence for specialty additives:Rheology modifiers and UV stabilizers concentrate among German and Japanese chemical suppliers, exposing coating makers to currency and logistics risk.
- Electrocoat primer curing energy intensity:Oven temperature requirements of 170-190°C constrain plant retrofit economics for smaller commercial vehicle frame coaters.
Strategic Opportunities
- Chassis powder coating penetration:Edge coverage advantages are opening specification windows for engine component and underbody applications where liquid systems dominate.
- CDSCO biocompatibility pathways:Interior cabin surface coating qualifications are creating premium tier separation for suppliers with toxicology testing capabilities.
- Recycled content mandates:Draft Extended Producer Responsibility frameworks for automotive materials are positioning bio-based resin systems for future compliance advantage.
Industry Challenges
- Color-matching technician scarcity:Spectrophotometry and flop control expertise pools thin across paint shop operations in emerging Gujarat assembly hubs.
- Waterborne system capex intensity:Humidity-controlled spray booths and forced drying infrastructure demand investment multiples above conventional solvent lines.
- Multi-OEM specification fragmentation:Each passenger vehicle assembler maintains proprietary color approval protocols, duplicating qualification overhead for tier-one coaters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive OEM Coatings Market |
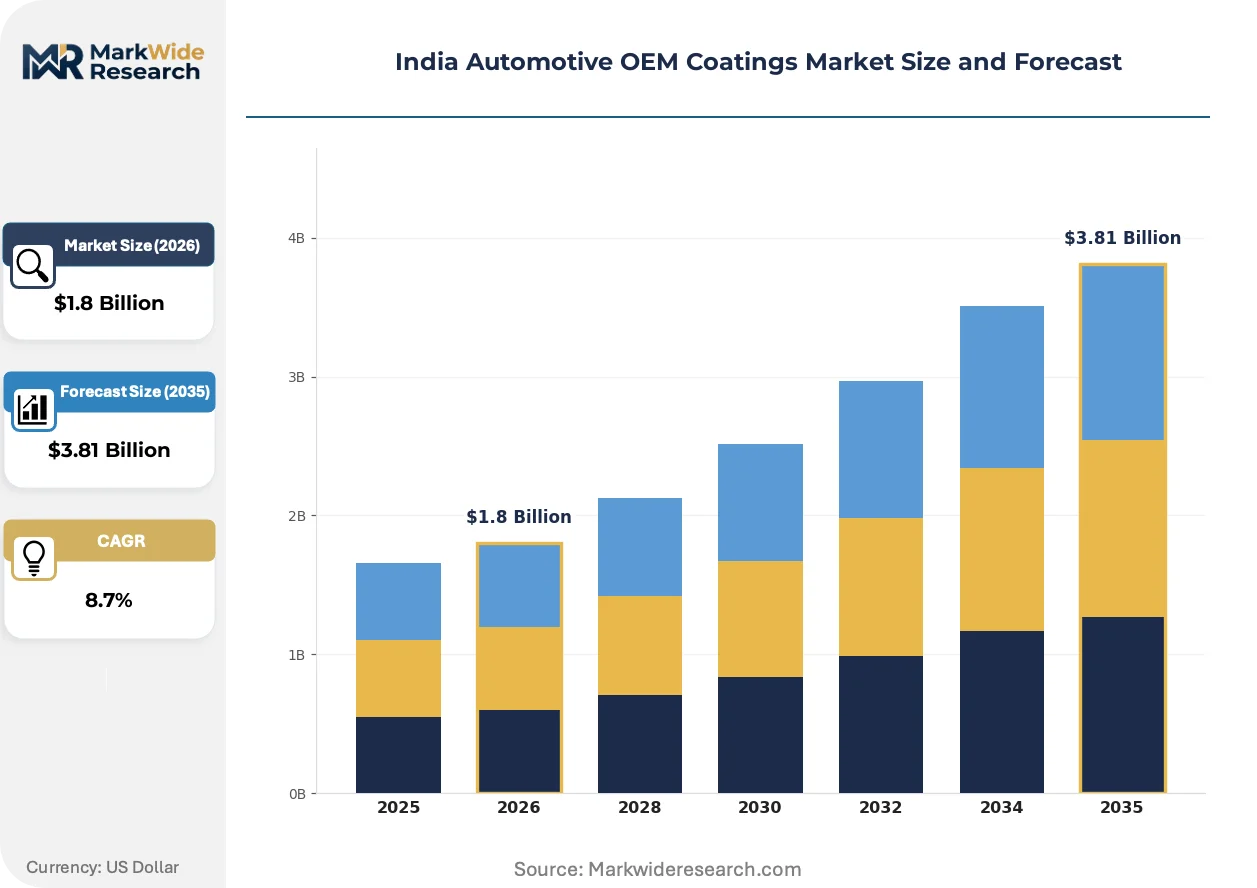
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Coatings, Base Coatings, Primer Coatings, Sealants Application: Exterior, Interior, Chassis, Engine Components Technology: Waterborne, Solventborne, Powder Coatings, UV-Cured End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Three-Wheelers |
| Companies Covered | Kansai Nerolac Paints Limited, Asian Paints, Axalta Coating Systems LLC, Nippon Paint Holdings Co. Ltd, Berger Paints India, BASF, PPG Industries, Inc., Beckers Group, JSW Paints, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive OEM Coatings Market Shifts & Advancements
Coating functionality is splitting into thermal management and electromagnetic shielding layers for electric powertrains, diverging from traditional corrosion-and-aesthetic specifications. Application chemistry and curing protocols are reconfiguring around these new performance envelopes.
Self-healing clear coat chemistry is decomposing the traditional trade-off between scratch resistance and reflow repair capability in premium passenger vehicle segments. Maruti Suzuki and Hyundai Motor India are piloting microcapsule-based systems in Chennai and Pune paint shops. This technology is decomposing warranty cost structures for exterior finish durability claims.
BIS notification timelines for automotive coating VOC limits are compressing supplier reformulation cycles below typical resin qualification periods. Central Pollution Control Board enforcement in Maharashtra and Tamil Nadu is accelerating plant-level emission monitoring investments. Waterborne base coat segments in passenger vehicle applications are absorbing the fastest compliance-driven specification changes.
Fleet operator procurement is consolidating coating decisions at the OEM level rather than分散ing across aftermarket refinishing channels. Commercial vehicle buyers in long-haul logistics segments are prioritizing factory-applied systems with documented durability testing. This concentration is most visible in Gujarat's heavy truck manufacturing belt where Ashok Leyland and Tata Motors fleet contracts dominate volume allocation.
India Automotive OEM Coatings Market Segmentation
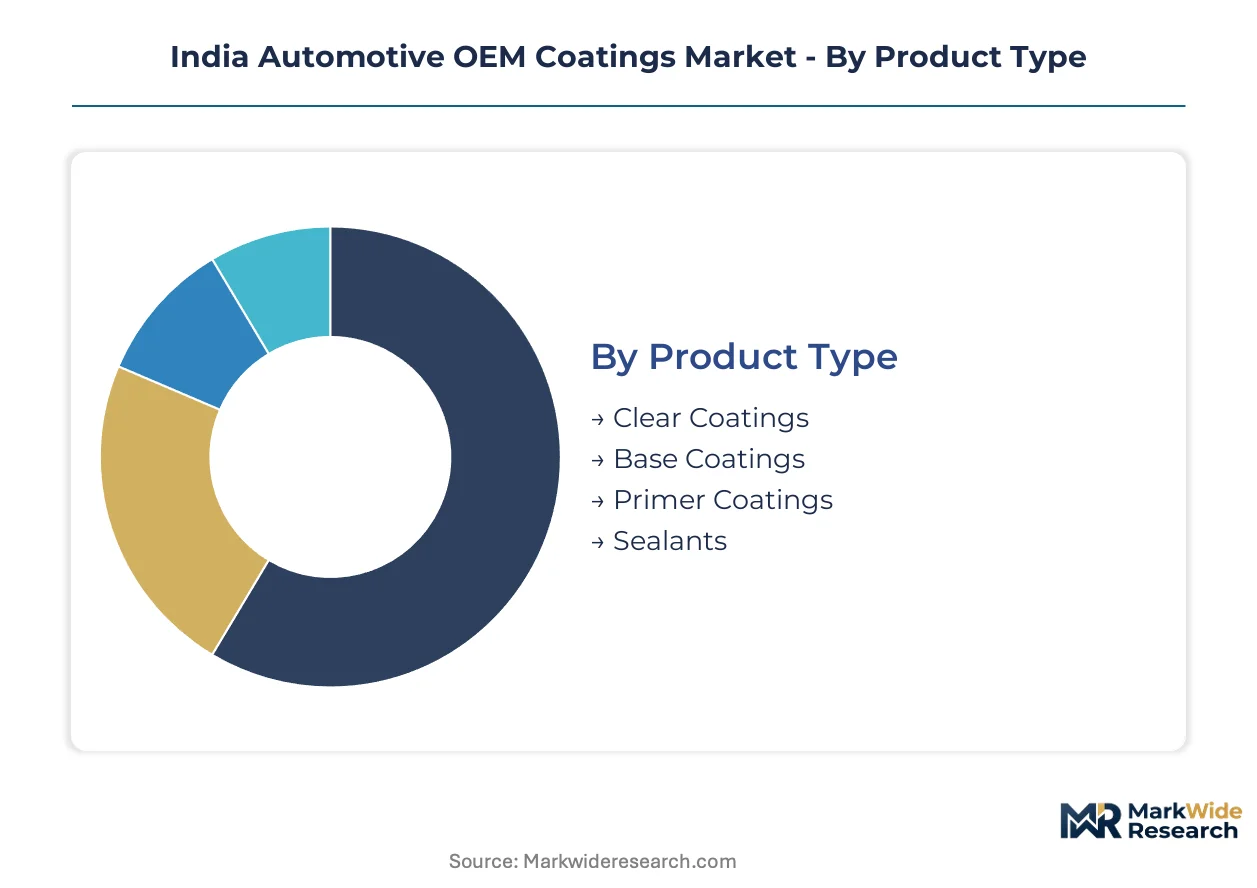
Coating procurement decisions in India's automotive belt fragment across four distinct axes. Product specifications diverge between corrosion-driven chassis layers and appearance-critical exterior films, while technology choices trace regulatory pressure gradients across state pollution control jurisdictions.
Product Type:
Substitution pressure intensifies most acutely in primer formulations, where waterborne systems displace solvent-based chemistry faster than resin supply chains can adapt.
- Clear Coatings:Acrylic-urethane hybrid formulations deliver UV stability and gloss retention for passenger vehicle exterior finishes. Demand concentrates in Maruti Suzuki and Hyundai Motor India assembly plants across Tamil Nadu and Maharashtra, where warranty durability specifications command premium positioning against refinish alternatives.
- Base Coatings:Pigmented layers incorporating aluminum flake or pearl mica for color travel and flop control. Pune and Chennai production clusters drive procurement volume as OEMs internalize spectrophotometry capabilities to reduce batch-to-batch variation penalties.
- Primer Coatings:Electrocoat and surfacer systems providing adhesion promotion and chip resistance.
- Sealants:Cavity wax and seam seal formulations for corrosion protection in hidden body areas.
Clear Coatings retain volume leadership; Base Coatings hold the steepest expansion curve as color complexity proliferates across premium passenger vehicle trims.
Application:
Cost tier stratification separates exterior appearance specifications from functional underbody protection, with chassis applications commanding lower per-liter pricing despite higher film build requirements.
- Exterior:Multi-layer systems combining electrocoat, base coat, and clear coat for body-in-white panels. Gujarat's automotive corridor absorbs the fastest capacity additions as paint shop investments align with Tata Motors and Ashok Leyland assembly expansions.
- Interior:Dashboard, door panel, and cabin trim coatings subject to CDSCO biocompatibility screening where surface contact occurs.
- Chassis:Frame and underbody coatings prioritizing stone chip resistance and salt spray durability.
- Engine Components:Thermal-resistant formulations for valve covers, oil pans, and transmission housings.
Exterior applications dominate value capture; Interior specifications are climbing fastest as cabin air quality regulations tighten.
Technology:
Supply concentration in imported specialty additives shapes competitive access across all four technology platforms, with powder systems requiring captive application equipment that excludes smaller formulators.
- Waterborne:Acrylic and polyurethane dispersions replacing solvent-based systems under BIS VOC emission mandates. Tamil Nadu and Maharashtra pollution control board enforcement accelerates spray booth retrofit investments in Chennai and Pune assembly plants.
- Solventborne:High-solids alkyd and acrylic formulations retaining share in commercial vehicle refinish and touch-up applications.
- Powder Coatings:Thermoset epoxy and polyester systems for chassis and engine components where edge coverage justifies capital-intensive fluidized bed or electrostatic spray lines.
- UV-Cured:Rapid-cure acrylic oligomers for selected interior trim and component finishing.
Solventborne retains installed base dominance; Waterborne technology is expanding most quickly as compliance deadlines compress.
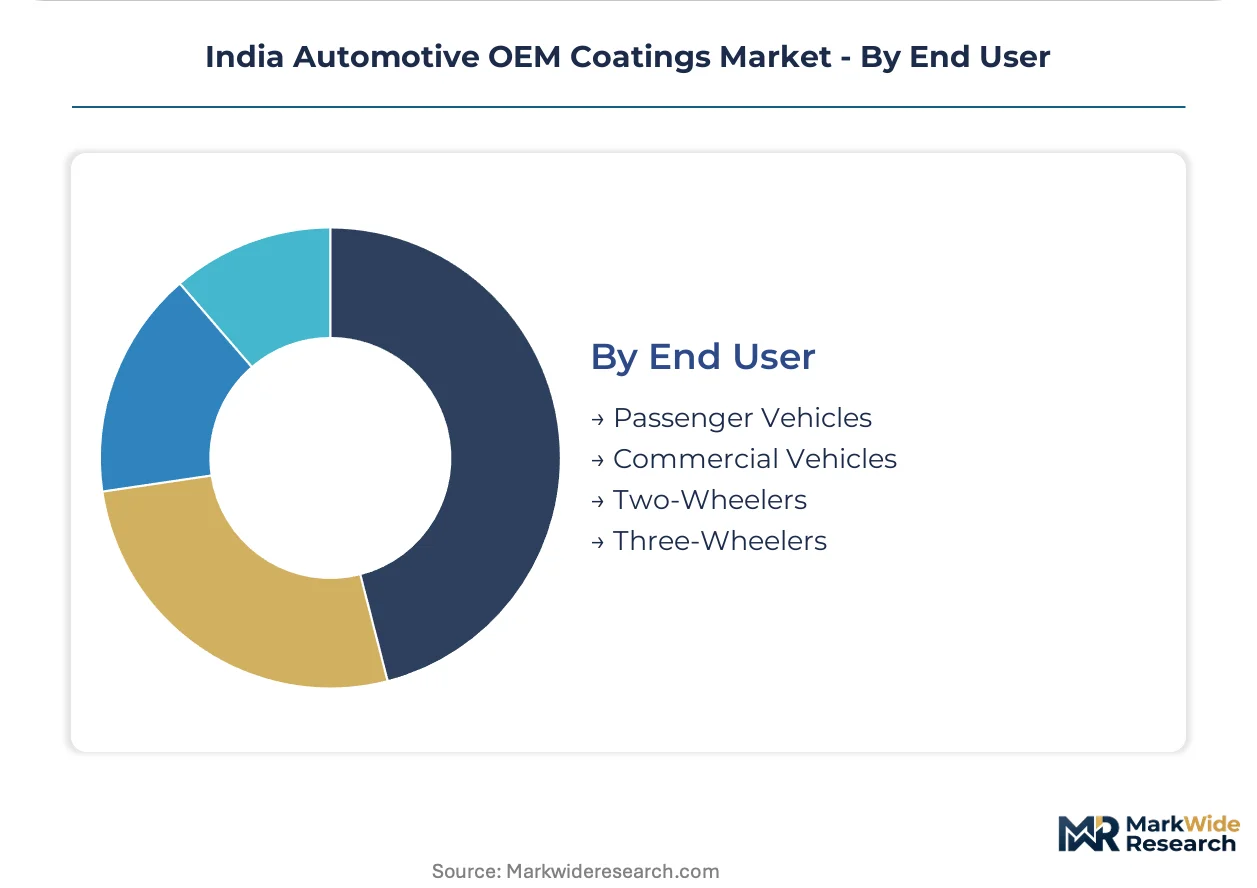
End User:
Customer type segmentation maps directly to specification complexity, with passenger vehicle OEMs fragmenting color approval protocols while two-wheeler producers prioritize throughput economics.
- Passenger Vehicles:Multi-coat exterior systems with proprietary color matching and flop control requirements. Maruti Suzuki's Gurugram and Manesar facilities anchor procurement volume, while Hyundai Motor India and Tata Motors drive specification evolution toward self-healing clear coat pilots.
- Commercial Vehicles:Fleet-operator procurement consolidation favors factory-applied durability documentation over aftermarket refinishing.
- Two-Wheelers:High-volume, cost-sensitive exterior finishes where export specifications for Southeast Asian and African markets add UV stability requirements.
- Three-Wheelers:Basic corrosion protection and single-stage color coatings for autorickshaw and goods carrier applications.
Two-Wheelers retain volume leadership; Passenger Vehicles command the steepest value-per-liter trajectory as coating functionality splits toward thermal management layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Maharashtra and Tamil Nadu production clusters, while Gujarat's automotive corridor absorbs the fastest capacity additions at thinner margins. State-level pollution control enforcement creates asymmetric compliance costs across India's automotive belt. BIS certification timelines compress reformulation windows unevenly across regional jurisdictions.
Maharashtra
Passenger vehicle assembly plants in Pune and Mumbai drive premium clear coat procurement volumes. Maharashtra Pollution Control Board enforcement accelerates waterborne spray booth retrofits beyond the national compliance timeline. Chakan and Talegaon automotive clusters host concentrated paint shop investments from Maruti Suzuki and Tata Motors.
Tamil Nadu
Hyundai Motor India and Renault-Nissan anchor exterior coating demand around Chennai and Sriperumbudur. Tamil Nadu State Pollution Control Board mandates advance BIS VOC threshold adoption ahead of central deadlines. Oragadam and Sri City industrial corridors concentrate electrocoat primer capacity expansions.
Gujarat
Commercial vehicle manufacturing in Sanand and Halol triggers chassis coating volume growth at cost-competitive pricing. Gujarat Pollution Control Board permits extended solventborne system transition timelines relative to southern states. Ahmedabad-Vadodara automotive corridor aligns paint shop investments with Ashok Leyland and Tata Motors assembly expansions.
Haryana
Maruti Suzuki's Gurugram and Manesar facilities sustain the country's largest single-location coating procurement footprint. Haryana State Pollution Control Board mirrors central BIS emission standards without state-level acceleration. IMT Manesar and Sohna industrial areas concentrate supplier qualification activity for northern OEM supply chains.
Karnataka
Two-wheeler export manufacturing in Bengaluru and Mysuru drives UV-stable exterior finish specifications for Southeast Asian destinations. Karnataka State Pollution Control Board enforces BIS VOC limits concurrent with central notification timelines. Bidadi and Nelamangala industrial zones host powder coating capacity for engine component applications.
India Automotive OEM Coatings Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across India's automotive coatings structure. The market fragments into three strategic tiers: integrated resin manufacturers commanding raw material control, technology licensors leveraging electrocoat and clear coat formulation expertise, and regional formulators competing on logistics proximity to assembly plants. Consolidation pressure concentrates among mid-tier solventborne specialists facing BIS-mandated waterborne transition costs. Dominant competitive moves include backward integration into resin manufacturing and captive application equipment partnerships with OEM paint shop operators.
Within the integrated domestic tier, Kansai Nerolac Paints Limited and Asian Paints occupy positions defined by long-standing supply relationships and captive resin production capabilities. Axalta Coating Systems LLC represents the technology-licensor archetype with specialized electrocoat formulation expertise. These three anchors exemplify how competitive positioning splits between raw material control, application technology leadership, and OEM relationship depth across India's automotive belt.
| Leading Market Players |
|---|
| Kansai Nerolac Paints Limited |
| Asian Paints |
| Axalta Coating Systems LLC |
| Nippon Paint Holdings Co. Ltd |
| Berger Paints India |
| BASF |
| PPG Industries, Inc. |
| Beckers Group |
| JSW Paints |
| Others |
Supply & Pricing Matrix
Waterborne resin substitution for solvent-based systems is redrawing procurement geography across India's automotive belt, compressing margins for mid-tier formulators while concentrating pricing power with integrated manufacturers controlling captive resin capacity. This input transition simultaneously elevates capital requirements for humidity-controlled spray infrastructure and fragments supplier tiers based on BIS compliance timelines.
Pricing Analysis
The customization-premium spread separates proprietary color-matched base coat systems from standard catalog formulations, with spectrophotometry-capable suppliers commanding substantial markups against commodity clear coat providers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with passenger vehicle OEMs least price-sensitive due to warranty durability specifications while two-wheeler manufacturers drive aggressive cost-per-liter negotiations. Pricing pressure stems from petrochemical feedstock volatility in acrylic and epoxy inputs. Two-wheeler export manufacturers exhibit highest price sensitivity due to thin margins on Southeast Asian and African destination contracts.
Supply Chain Analysis
Inventory lead times for specialty rheology modifiers and UV stabilizers extend procurement cycles, exposing coating formulators to currency fluctuation risks from German and Japanese chemical suppliers. Raw material sourcing concentrates in China for base resin intermediates, Germany for performance additives, and India for alkyd backbone chemistry. Acrylic monomer and isocyanate hardener dependencies create single-source vulnerability during logistics disruptions. Distribution runs through OEM-qualified tier-one coating suppliers directly integrated into Maruti Suzuki, Tata Motors, and Hyundai Motor India paint shop operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The narrowing pool of BIS-certified waterborne formulation specialists is constraining supplier qualification pipelines, creating acquisition premiums for facilities with validated spray booth infrastructure and spectrophotometry capabilities.
For Market Incumbents: Secure captive resin manufacturing capacity through backward integration into acrylic dispersion production, insulating margin structures from petrochemical derivative volatility. Defend market position by accelerating CDSCO biocompatibility certification for interior cabin coating qualifications ahead of tightening cabin air quality mandates. Prioritize technician training partnerships with Tamil Nadu and Maharashtra industrial training institutes to address color-matching expertise scarcity. For New Entrants and Emerging Players: BIS certification fast-track through state pollution control board pre-approval pathways in Gujarat offers timeline advantages over southern state jurisdictions. Target chassis powder coating specifications in commercial vehicle underbody applications where edge coverage requirements favor new capital equipment investments over incumbent liquid system retrofits. Pursue joint application equipment partnerships with emerging OEM paint shop operators in Sanand and Halol corridors. For Investors and Strategic Acquirers: BIS VOC threshold enforcement reshapes the acquisition landscape toward waterborne-capable assets with validated OEM supply relationships. Five-to-ten-year viability hinges on exposure to electric vehicle thermal management coating specifications rather than traditional body-in-white applications. Target mid-tier formulators with incomplete waterborne transition pipelines facing compliance-driven distress. Monitor PLI scheme disbursement velocity for battery enclosure coating demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Manufacturing | Captive acrylic dispersion production insulates Kansai Nerolac and Asian Paints from petrochemical feedstock volatility. |
| Waterborne Spray Booth Retrofit | Maharashtra and Tamil Nadu pollution control mandates force accelerated capital deployment in Chennai and Pune clusters. |
| CDSCO Biocompatibility Certification | Interior cabin surface qualifications create premium tier separation for suppliers with toxicology testing capabilities. |
| Chassis Powder Coating Expansion | Edge coverage advantages open specification windows in Ashok Leyland and Tata Motors commercial vehicle frame applications. |
| PLI-Aligned Thermal Management Coating Development | Battery enclosure specifications in Gujarat's electric vehicle corridor demand new performance criteria beyond corrosion resistance. |
Research Methodology
Initial hypotheses were tested against primary input from OEM procurement managers, paint shop operations directors, resin manufacturing technical leads, and BIS certification consultants, then refined through secondary validation against Central Pollution Control Board enforcement records, BIS notification archives, state pollution control board orders, and automotive production databases. Bottom-up volume estimates from individual OEM paint shop capacity expansions were triangulated against top-down market sizing derived from vehicle production forecasts and coating content-per-vehicle assumptions.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects, with segmentation modeling spanning product type, application layer, technology platform, and end-user vehicle category. CAGRs were derived from logistic diffusion curves fitted to waterborne technology substitution rates and regulatory compliance deadlines. Industry-specific forecast inputs include PLI scheme disbursement schedules for electric vehicle manufacturing and BIS notification timelines for VOC threshold adoption.
The analysis sits within stated boundaries; outcomes outside sustained OEM assembly plant investment in Gujarat, Maharashtra, and Tamil Nadu clusters would require recalibration. Forecasts reflect assumptions regarding BIS enforcement consistency and resin supply chain adaptation rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Paint Defoamers Market
Paints & Coatings
Middle East and Africa Paints and Coatings Market
Paints & Coatings
North America Paints and Coatings Market
Paints & Coatings
Decorative Paints Market
Paints & Coatings
Paint Curing Lamp Market
Paints & Coatings
Polyolefin Resin Paints Market
Paints & Coatings
Industrial Paint Booth Market
Paints & Coatings
Sri Lanka Paints and Coatings Market
Paints & Coatings
Global Thinners and Paint Strippers Market
Paints & Coatings
Polyurethane Resins Paints and Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Market
Paints & Coatings
Global Aerosol Paints Market
Paints & Coatings
Anti-Fungal and Anti-Bacterial Paints Market
Paints & Coatings
Europe Architectural Coatings Market
Paints & Coatings
Alkyd Coatings Market
Paints & Coatings
Global Paints and Coatings Fillers Market