
 Asia-Pacific Radiation Curable Coatings Market | 2026-2036
Asia-Pacific Radiation Curable Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Radiation Curable Coatings Market Outlook
GB/T 38597-2020 low-VOC content limits for industrial protective coatings is reorganizing supplier eligibility across China, forcing reformulation investments and certification renewals. PPG Industries Inc. leverages its automotive OEM relationships to sustain high-specification UV coating supply chains. Nippon Paint anchors Japanese electronics and automotive demand through localized R&D facilities. Eternal Materials Co. Ltd. differentiates via specialized photoinitiator and oligomer portfolios tailored to regional UV curing requirements.
Asia-Pacific radiation curable coatings comprise formulations that polymerize upon exposure to ultraviolet light or electron beam radiation, typically containing acrylate-functional oligomers, monomers, and photoinitiators that crosslink without solvent evaporation. These systems cure in seconds at ambient temperature, enabling high-line-speed processing for heat-sensitive substrates. UV-curable products dominate current volume due to lower capital equipment requirements and broader substrate compatibility across packaging and wood applications. Electron beam-curable coatings command premium positioning in food-contact packaging and medical device applications where photoinitiator migration risks trigger regulatory scrutiny. Hybrid systems represent the fastest-expanding category as formulators blend UV and thermal mechanisms to bridge performance gaps on difficult-to-cure substrates.
China's MEE enforces VOC emission standards that directly constrain conventional solvent-borne coating operations in Jiangsu and Guangdong provinces. Japan's METI promotes UV and EB technologies through industrial efficiency programs targeting manufacturing energy intensity reduction. South Korea's MFDS and KOSHA frameworks govern chemical substance registration and workplace exposure limits affecting photoinitiator selection and handling protocols. Stakeholders must monitor evolving chemical substance inventories across these jurisdictions to anticipate formulation restrictions before they disrupt supply qualifications.
Market Dynamics
China's MEE enforcement of GB/T 38597-2020 low-VOC limits is forcing wholesale reformulation across Jiangsu and Guangdong coating facilities, compressing supplier margins while accelerating electron beam and UV technology substitution for solvent-borne systems.
Growth Catalysts
- Food-contact packaging migration rules:Japan's METI efficiency programs and South Korea's MFDS substance registration frameworks are accelerating electron beam adoption where photoinitiator leaching risks dominate regulatory scrutiny.
- Automotive OEM cluster concentration:Tier-1 suppliers in China's Yangtze River Delta are integrating UV-curable clearcoats into electric vehicle battery module housings and interior trim to meet thermal management and VOC targets simultaneously.
- Photoinitiator oligomer innovation:Taiwan's electronics substrate manufacturers are demanding specialized acrylate-functional oligomers with enhanced adhesion to polyimide and LCP materials for 5G antenna modules.
Market Restraints
- Acrylate monomer supply concentration:Bulk oligomer and monomer production concentrates among petrochemical complexes in China's Shandong and Zhejiang provinces, creating input cost volatility when regional environmental inspections trigger unplanned outages.
- Electron beam capex barriers:Food-contact and medical device converters face $2-4 million capital thresholds for EB line installation, restricting adoption to volume-stable Tier-1 packaging groups with multi-year OEM contracts.
- Thermal-cure hybrid persistence:Wood furniture manufacturers in Vietnam and Indonesia continue specifying thermal-UV hybrid systems for dense tropical hardwoods where full UV penetration remains technically unreliable.
Strategic Opportunities
- India's packaging conversion gap:Flexible packaging converters in Maharashtra and Gujarat remain underpenetrated by radiation-curable flexo inks, presenting first-mover positioning as BIS standards for food-contact coatings mature.
- Hybrid UV-thermal mechanism development:Formulators blending cationic UV initiation with thermal post-cure are unlocking adhesion to polypropylene automotive bumpers and appliance panels previously reserved for two-component polyurethane.
- Thailand's medical device corridor:Eastern Economic Zone incentives for medical manufacturing are drawing coating applicators serving export-oriented catheter and syringe producers seeking photoinitiator-free EB sterilizable finishes.
Industry Challenges
- Photoinitiator handling certification:South Korea's KOSHA workplace exposure protocols and Japan's ISHL substance inventories require specialized technician training and ventilation infrastructure that smaller applicators struggle to fund.
- Substrate pretreatment integration:UV-curable adhesion to untreated polyolefin films demands corona or plasma surface activation systems, complicating line retrofits for legacy solvent-borne coating houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Radiation Curable Coatings Market |
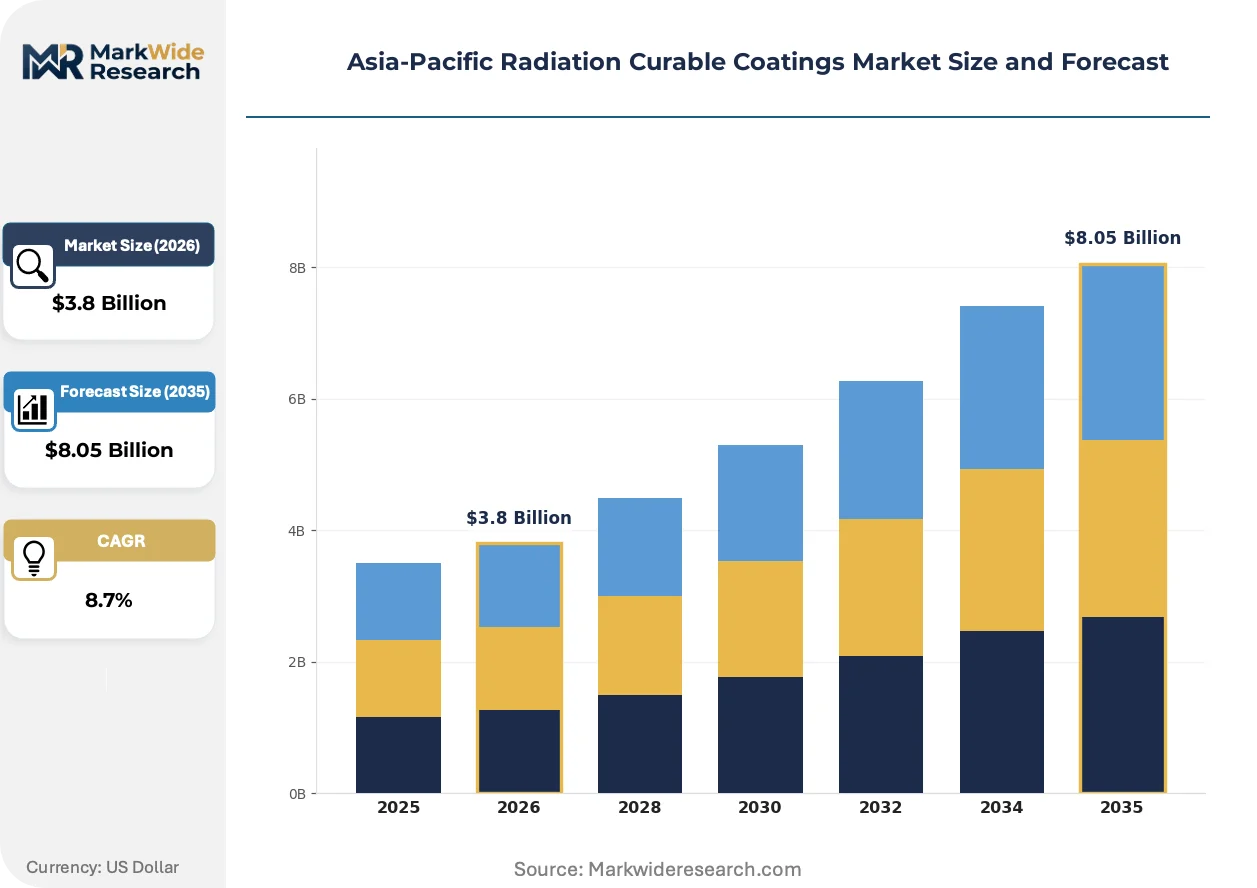
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UV-Curable, Electron Beam-Curable, Hybrid Systems, Other End User: Automotive, Packaging, Electronics, Wood Coatings Technology: Conventional, Advanced, Emerging Technologies, Specialty Technologies Application: Adhesives, Inks, Paints, Sealants |
| Companies Covered | PPG Industries Inc., Nippon Paint, BASF SE, Eternal Materials Co. Ltd., Toyo Ink SC Holdings Co., Ltd., The Sherwin-Williams Company, Axalta Coating Systems Ltd LLC, Dymax Corporation, Akzo Nobel N.V., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Radiation Curable Coatings Market Strategic Shifts
Formulation chemistry and curing hardware are converging to address substrate expansion limitations that have historically constrained radiation-curable penetration beyond graphic arts and wood.
LED-UV curing systems with 395nm and 405nm peak wavelengths are miniaturizing lamp footprints and eliminating mercury arc warm-up delays. Electronics manufacturers in South Korea's Gyeonggi Province are retrofitting SMT lines with compact LED arrays for conformal coating of heat-sensitive flexible circuits. This hardware compression is enabling inline integration where batch oven configurations previously dominated, collapsing floor space requirements by sixty percent in greenfield facilities.
China's MEE is tightening VOC emission monitoring through continuous emission monitoring systems linked to provincial environmental databases. Jiangsu coating facilities face real-time disclosure requirements that expose non-compliant solvent-borne operations to immediate production halts. Converters are responding by accelerating EB line investments and demanding supplier certificates of GB/T 38597-2020 compliance before contract renewal.
Japanese automotive OEMs are unbundling coating specification authority from traditional paint suppliers, bringing UV-curable interior trim specifications in-house through direct oligomer and photoinitiator procurement. Tier-2 applicators in Aichi and Shizuoka prefectures now receive raw material packages from OEM technical centers rather than formulated coatings from integrators. This disintermediation compresses formulator margins while rewarding photoinitiator and oligomer specialists with direct technical relationships.
Asia-Pacific Radiation Curable Coatings Market Segmentation
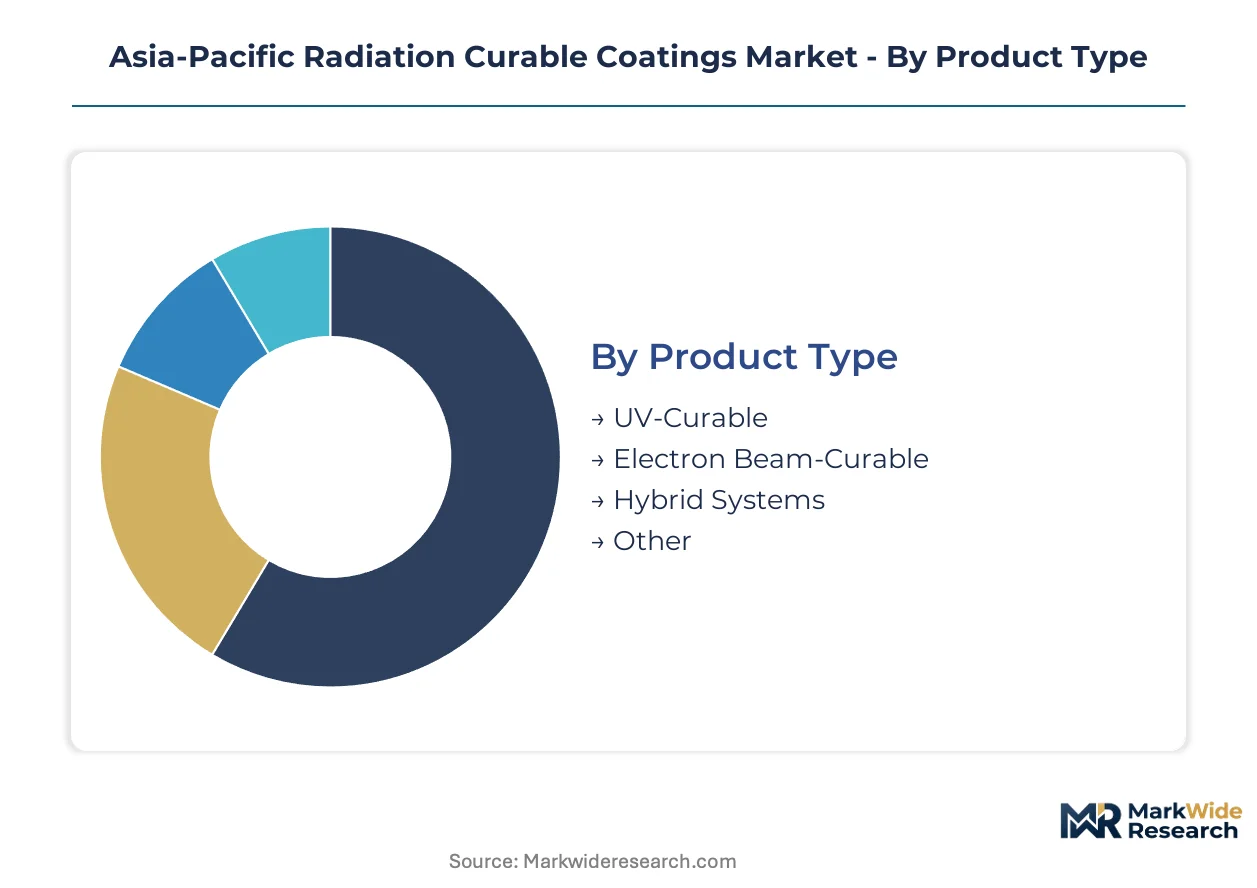
Radiation curable coatings fragment across curing chemistry, end-use intensity, and application format. Each dimension carries distinct margin structures and capital requirements that shape supplier positioning across Asia-Pacific manufacturing clusters.
Product Type:
Margin pools concentrate in systems requiring specialized photoinitiator portfolios or electron beam infrastructure that smaller formulators cannot replicate.
- UV-Curable:Acrylate-functional oligomers crosslink under 200-400nm ultraviolet exposure without thermal energy input. China's Jiangsu and Guangdong packaging converters are absorbing volume as MEE emission inspections force solvent-borne line replacements.
- Electron Beam-Curable:High-energy electron radiation initiates polymerization without photoinitiator inclusion, eliminating migration risks in food-contact and medical device applications. South Korea's MFDS substance registration protocols are accelerating EB adoption for pharmaceutical packaging where photoinitiator leaching triggers regulatory rejection.
- Hybrid Systems:Blended UV-thermal mechanisms bridge adhesion gaps on dense tropical hardwoods in Vietnam and Indonesia.
- Other:Niche cationic and moisture-cure variants serve specialized electronics conformal coating requirements in Taiwan's substrate fabrication facilities.
The dominant share belongs to UV-Curable, while Electron Beam-Curable is closing the gap fastest.
End User:
Application intensity varies sharply by sector, with automotive and electronics commanding specification authority that wood coatings cannot match.
- Automotive:UV-curable clearcoats protect electric vehicle battery module housings and interior trim components. Tier-1 suppliers in China's Yangtze River Delta integrate these systems to satisfy thermal management and VOC targets from GB/T 38597-2020 enforcement.
- Electronics:Conformal coatings shield printed circuit boards and display components from moisture and thermal cycling. South Korea's Gyeonggi Province SMT manufacturers are retrofitting lines with LED-UV arrays for flexible circuit processing at ambient temperature.
- Packaging:Flexographic and gravure inks dominate flexible food-contact applications across China's coastal provinces.
- Wood Coatings:Furniture manufacturers in Vietnam and Indonesia specify thermal-UV hybrids for tropical hardwood penetration reliability.
Electronics and automotive together capture the premium tier, with packaging expanding most quickly as converters respond to MEE compliance deadlines.
Technology:
Equipment sophistication and formulation chemistry separate tiers that command different pricing power with applicators.
- Conventional:Mercury arc lamp systems with established photoinitiator packages serve high-volume graphic arts and wood finishing across mature China facilities.
- Advanced:LED-UV platforms at 395nm and 405nm wavelengths eliminate warm-up delays and reduce floor space requirements. Electronics manufacturers in South Korea's Gyeonggi Province are deploying these for inline conformal coating integration.
- Emerging Technologies:Excimer lamp and pulsed UV systems target ultra-thin film curing for flexible display substrates.
- Specialty Technologies:Low-energy EB and hybrid plasma-UV configurations address medical device sterilization requirements in Thailand's Eastern Economic Zone.
Advanced technology is gaining share fastest as LED retrofit economics improve, though Conventional systems still anchor volume in legacy packaging operations.
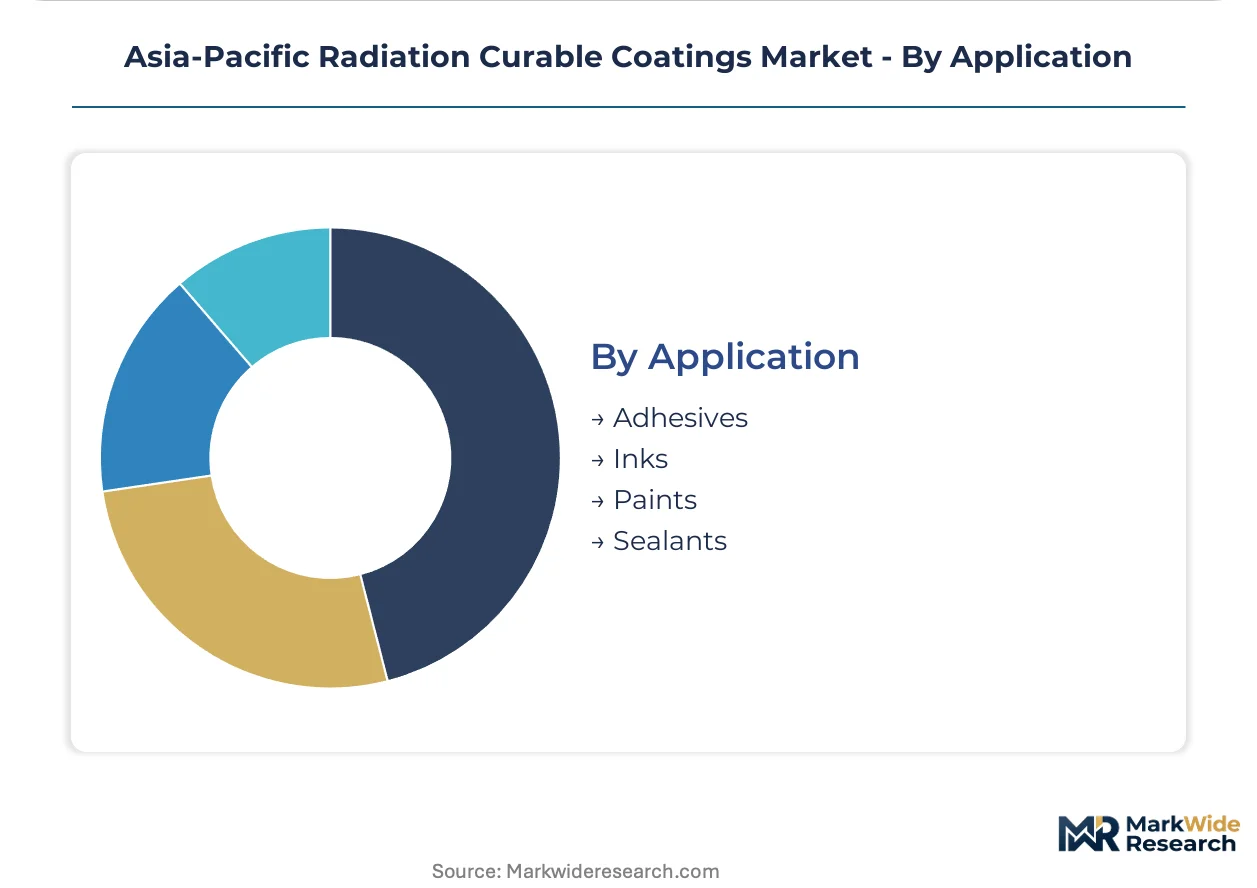
Application:
Format selection determines supply chain configuration, with inks and paints requiring distinct distribution and technical service footprints.
- Inks:Flexographic and offset formulations cure instantly for high-speed packaging lines. Maharashtra and Gujarat flexible packaging converters in India remain underpenetrated, presenting positioning opportunities as BIS standards mature.
- Paints:Clearcoats and pigmented finishes serve automotive and industrial protective requirements with specification-driven procurement.
- Adhesives:Pressure-sensitive and structural bonding applications concentrate in electronics assembly and medical device lamination.
- Sealants:Gasketing and encapsulation compounds protect battery enclosures and electronic housings from environmental ingress.
Paints and inks together dominate value capture, with adhesives climbing the fastest as electric vehicle battery assembly expands across China.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ningbo-Zhoushan Port anchors Asia-Pacific coating logistics, handling bulk acrylate monomer imports that feed Jiangsu and Guangdong formulation plants. This maritime infrastructure underwrites China's dominance in radiation-curable feedstock distribution across the region.
China
Jiangsu and Guangdong packaging converters are absorbing UV-curable volume as MEE emission inspections force solvent-borne line replacements. GB/T 38597-2020 low-VOC limits are compressing supplier margins while accelerating electron beam technology substitution. Yangtze River Delta automotive OEM clusters are integrating UV-curable clearcoats into electric vehicle battery module housings to meet thermal management targets.
Japan
Automotive OEMs in Aichi and Shizuoka prefectures are unbundling coating specification authority from traditional paint suppliers. METI efficiency programs promote UV and EB technologies through industrial energy intensity reduction targets. Tier-2 applicators now receive raw material packages from OEM technical centers rather than formulated coatings from integrators.
South Korea
Gyeonggi Province electronics manufacturers are retrofitting SMT lines with LED-UV arrays for conformal coating of flexible circuits. MFDS substance registration frameworks govern chemical substance handling protocols affecting photoinitiator selection. KOSHA workplace exposure protocols require specialized technician training that smaller applicators struggle to fund.
India
Maharashtra and Gujarat flexible packaging converters remain underpenetrated by radiation-curable flexo inks. BIS standards for food-contact coatings are maturing, presenting first-mover positioning opportunities. Western industrial corridors are drawing coating applicators serving domestic consumer goods producers seeking VOC-compliant alternatives.
Thailand
Eastern Economic Zone incentives for medical manufacturing are drawing coating applicators serving export-oriented catheter and syringe producers. EB sterilizable finishes command premium positioning where photoinitiator migration risks trigger regulatory scrutiny. Chonburi and Rayong industrial estates are concentrating medical device coating capacity for ASEAN export markets.
Asia-Pacific Radiation Curable Coatings Market Competitive Environment
Listed leaders compete with private specialists across formulation chemistry and curing hardware dimensions. The vendor base separates into consolidated multinational integrators, regional oligomer specialists, and equipment-integrated service providers. Three archetypes dominate: automotive OEM-aligned coating suppliers, photoinitiator and oligomer specialists, and UV/EB equipment-integrated formulators. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure feedstock access and applicator relationships.
Within the automotive OEM-aligned tier, PPG Industries Inc. and Axalta Coating Systems Ltd LLC occupy positions sustained by high-specification supply chain relationships. Among photoinitiator specialists, Eternal Materials Co. Ltd. exemplifies the regional oligomer archetype through localized technical service footprints. Nippon Paint anchors Japanese demand through proximity to electronics and automotive clusters. These three represent distinct competitive positioning vectors: multinational scale, regional feedstock specialization, and domestic market anchoring.
| Leading Market Players |
|---|
| PPG Industries Inc. |
| Nippon Paint |
| BASF SE |
| Eternal Materials Co. Ltd. |
| Toyo Ink SC Holdings Co., Ltd. |
| The Sherwin-Williams Company |
| Axalta Coating Systems Ltd LLC |
| Dymax Corporation |
| Akzo Nobel N.V. |
| Others |
Value Chain & Pricing Dynamics
Electron beam equipment substitution for mercury arc UV lines simultaneously relocates supply geography toward South Korean and Japanese hardware fabricators and compresses per-unit coating economics through photoinitiator elimination. China's Jiangsu and Guangdong converters face this dual restructuring as MEE enforcement accelerates technology switching decisions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts. Premium tiers command specification-grade photoinitiator packages certified for Japan's METI efficiency programs, while economy tiers serve commodity packaging converters in Vietnam and Indonesia. Price erosion runs through the standard tier as Chinese oligomer producers expand acrylate-functional resin capacity. Tier-1 automotive OEMs in the Yangtze River Delta exhibit lowest price sensitivity due to thermal management compliance requirements, whereas wood furniture manufacturers in Southeast Asia negotiate aggressively on per-kilogram rates.
Supply Chain Analysis
Bohai Bay petrochemical corridors anchor bulk acrylate monomer production, creating single-source vulnerability when Shandong environmental inspections trigger unplanned outages. Formulation plants in Jiangsu and Guangdong draw from these northern feedstock hubs while sourcing specialty photoinitiators from Taiwan and South Korea. Distribution runs through Ningbo-Zhoushan Port maritime infrastructure, concentrating logistics risk during typhoon season. Regional coating applicators maintain 60-90 day raw material inventories to buffer supply interruption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against thermal-cure hybrid persistence in tropical hardwood applications, where incomplete UV penetration sustains incumbent technology positions despite VOC regulatory pressure.
For Market Incumbents: Compound technical service capabilities in LED-UV retrofit engineering to defend against emerging equipment-integrated service providers. Secure backward integration into acrylate oligomer production through partnerships with Shandong petrochemical complexes. The priority lever centers on photoinitiator formulation lock-in with Japan's automotive OEM technical centers.
For New Entrants and Emerging Players: Anchor in India's Maharashtra and Gujarat flexible packaging corridors where BIS food-contact standards are maturing without established supplier relationships. Target medical device coating applicators in Thailand's Eastern Economic Zone seeking EB sterilizable finishes. The most penetrable entry vector combines equipment leasing with formulation supply to overcome capital barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed photoinitiator specialists possessing Eternal Materials-type regional technical footprints. Long-term viability hinges on five-to-ten year regulatory enforcement trajectories across China's MEE jurisdictions. The signal to watch is LED-UV lamp cost curves crossing mercury arc total-cost-of-ownership thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oligomer Production | Captive acrylate supply from Shandong petrochemical corridors insulates margin compression from environmental inspection volatility. |
| LED-UV Retrofit Service Expansion | South Korean Gyeonggi Province electronics manufacturers demand compact array integration collapsing floor space requirements. |
| GB/T 38597-2020 Certification Pre-positioning | Early compliance documentation accelerates Jiangsu and Guangdong converter contract renewals ahead of MEE enforcement waves. |
| Medical Device Corridor Establishment | Thailand's Eastern Economic Zone incentives concentrate catheter and syringe coating capacity for ASEAN export qualification. |
| Hybrid UV-Thermal Mechanism Development | Blended cationic initiation unlocks polypropylene automotive bumper applications previously reserved for polyurethane systems. |
Study Parameters
Operator-level perspectives from coating plant managers, photoinitiator procurement leads at formulation houses, UV/EB equipment service engineers, and automotive OEM specification engineers anchored the qualitative base. Secondary validation drew from MEE emission disclosure databases, China Customs acrylate monomer trade statistics, METI industrial efficiency program filings, and SEC 10-K chemical segment disclosures. Bottom-up volume builds across curing chemistry tiers were triangulated against top-down industry value estimates.
Sensitivity analysis tested input assumptions across oligomer price volatility scenarios and LED-UV adoption curve variations. The analytical framework modeled product type, end user intensity, technology sophistication, and application format dimensions across the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by regional production cluster concentrations. Forecast inputs incorporated MEE inspection frequency patterns and Japan's automotive OEM disintermediation timelines.
Decision-makers should treat outputs as directional under sustained MEE enforcement and LED cost reduction assumptions; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as India's BIS standard maturation and Thailand's medical manufacturing incentives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Fluid Bed and Coating System Market
Coatings
US Concrete Floor Coatings Market
Coatings
Asia-Pacific Flat Glass Coating Market
Coatings
Global Powder Coating Market
Coatings
Epoxy Powder Coatings Market
Coatings
Emulsion Coatings Market
Coatings
Protective and Marine Coatings Market
Coatings
Marine Nanocoating Market
Coatings
United Arab Emirates Protective Coatings Market
Coatings
Transportation Coating Market
Coatings
Corrosion Protection Coating Market
Coatings
Architectural Metal Coatings Market
Coatings
Global Fluorinated Ethylene Propylene (FEP) Coatings Market
Coatings
Batters and Coatings Market
Coatings
United Kingdom Automotive OEM Coatings Market
Coatings
Waterproof Coating Market