
 Faux Paints and Coatings Market | 2026-2036
Faux Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Faux Paints and Coatings Market Foresight
Color-matching software subscriptions and digital finish libraries is hardening into a core revenue layer beyond physical product sales. Faux Effects International Inc. leverages proprietary texture-matching algorithms to sustain designer loyalty. AkzoNobel anchors European commercial projects through its Sikkens brand heritage. The Sherwin-Williams Co. dominates North American contractor channels with integrated supply-chain control.
Faux paints and coatings comprise pigmented resin systems engineered to replicate marble, wood grain, stone, or metallic surfaces through layered application techniques, typically achieving dry-film thickness of 2-6 mils with acrylic or alkyd binders. Their primary commercial purpose is delivering high-end aesthetic finishes at reduced material cost and installation complexity versus natural substrates. Water-based technology leads volume growth as environmental compliance tightens, while solvent-based formulations retain share in automotive refinishing where durability specifications remain stringent. Spray paints command premium positioning in custom automotive and furniture restoration segments where precision application determines outcome quality.
EPA VOC regulations in the United States, REACH in Europe, and GB standards in China each constrain permissible solvent content and drive reformulation investments across manufacturers. FDA oversight of food-contact surface coatings and OSHA workplace exposure limits further shape product development priorities for residential and commercial applicators. Stakeholders must monitor evolving chemical disclosure requirements and certification protocols to anticipate which formulation platforms will retain market access.
Market Dynamics
Water-based formulation platforms are compressing solvent-based incumbent positions as EPA VOC limits and REACH substance restrictions harden compliance baselines across major demand centers. This technical transition redistributes value toward resin innovators and away from legacy alkyd supply chains.
Growth Catalysts
- Residential renovation spending:Homeowners in the United States allocate discretionary budgets toward premium interior finishes that replicate natural stone and wood aesthetics without structural substrate costs.
- REACH substance restrictions:European reformulation mandates accelerate waterborne acrylic development, opening substitution windows for compliant coating systems in commercial building refurbishment.
- Digital color-matching infrastructure:Cloud-based texture libraries reduce specification friction between designers and applicators, shortening project design cycles.
Market Restraints
- Titanium dioxide feedstock volatility:Pigment cost swings compress margin stability for mid-tier formulation houses lacking long-term supply contracts.
- Solvent-based durability specifications:Automotive refinishing segments retain alkyd demand for chip resistance, fragmenting R&D investment across incompatible technology platforms.
- Applicator skill concentration:Mastery of layered faux techniques remains geographically concentrated in established construction corridors, constraining service expansion.
Strategic Opportunities
- GB standards compliance in China:Domestic VOC ceilings create first-mover advantages for waterborne technology licensors partnering with local manufacturers.
- Food-contact surface coatings:FDA oversight expansion into commercial kitchen and hospitality finishes opens certified product categories with premium positioning.
- AR-assisted application training:Augmented reality tools reduce skill transfer time, enabling contractor base expansion beyond traditional craft clusters.
Industry Challenges
- Cross-platform certification timelines:Simultaneous EPA, REACH, and GB standard compliance extends product launch cycles and strains regulatory affairs capacity.
- Legacy solvent infrastructure stranded costs:Alkyd production assets face accelerated obsolescence as waterborne capacity scaling demands fresh capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Faux Paints and Coatings Market |
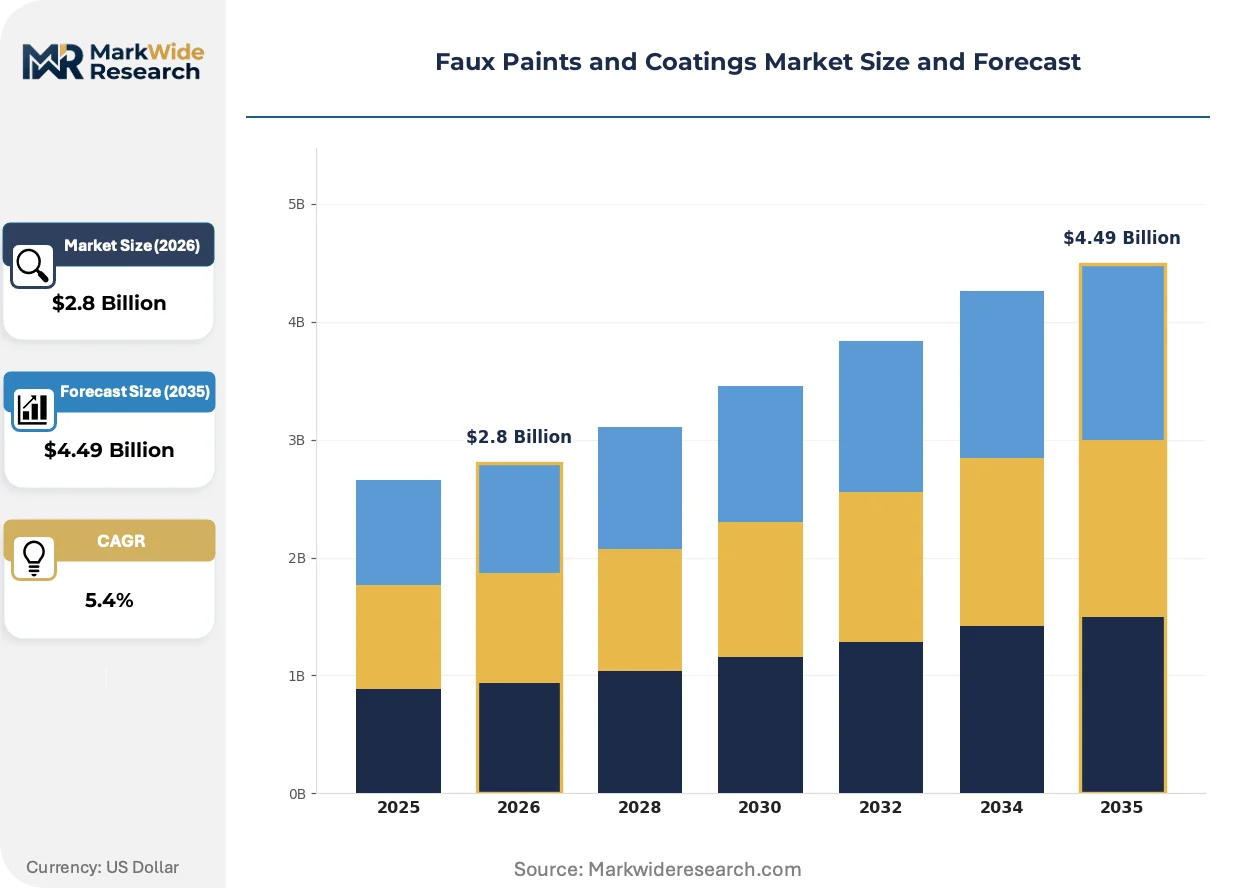
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray Paints, Brush-On Coatings, Roll-On Finishes, Textured Coatings Application: Residential Interiors, Commercial Spaces, Automotive Refinishing, Furniture Restoration Technology: Acrylic-Based, Oil-Based, Water-Based, Solvent-Based End User: Homeowners, Contractors, DIY Enthusiasts, Designers |
| Companies Covered | Faux Effects International Inc., AkzoNobel, The Sherwin-Williams Co., Kansai Paint Co. Ltd., Axalta Coating Systems, Nippon Paint Holdings Co., Ltd., PPG Industries, Inc., Benjamin Moore & Co., Asian Paints Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Faux Paints and Coatings Market Shifts & Advancements
Formulation science and application technology are converging to compress the performance gap between synthetic finishes and natural substrates. Three developments are restructuring competitive positioning.
Nano-scale mineral additives are integrating into waterborne acrylic matrices to enhance scratch resistance and depth perception previously exclusive to solvent-based systems. High-end residential contractors in Germany and the United States specify these enhanced formulations for luxury hospitality projects. The technology is integrating premium performance into compliant product lines, eroding the residual advantage of legacy alkyds.
REACH authorization procedures for chromium-based pigments are tightening supply security for metallic-effect coatings across European commercial construction. Manufacturers reformulate with complex inorganic colorants to maintain specification compliance. Decorative finish houses serving heritage restoration projects face the steepest substitution costs and longest qualification timelines.
Direct-to-contractor digital specification platforms are disintermediating traditional distributor relationships in North American renovation markets. Large painting contractors bypass regional supply houses to access manufacturer color libraries and batch scheduling. This channel compression concentrates in metropolitan corridor projects where logistics coordination outweighs distributor credit terms.
Faux Paints and Coatings Market Segmentation
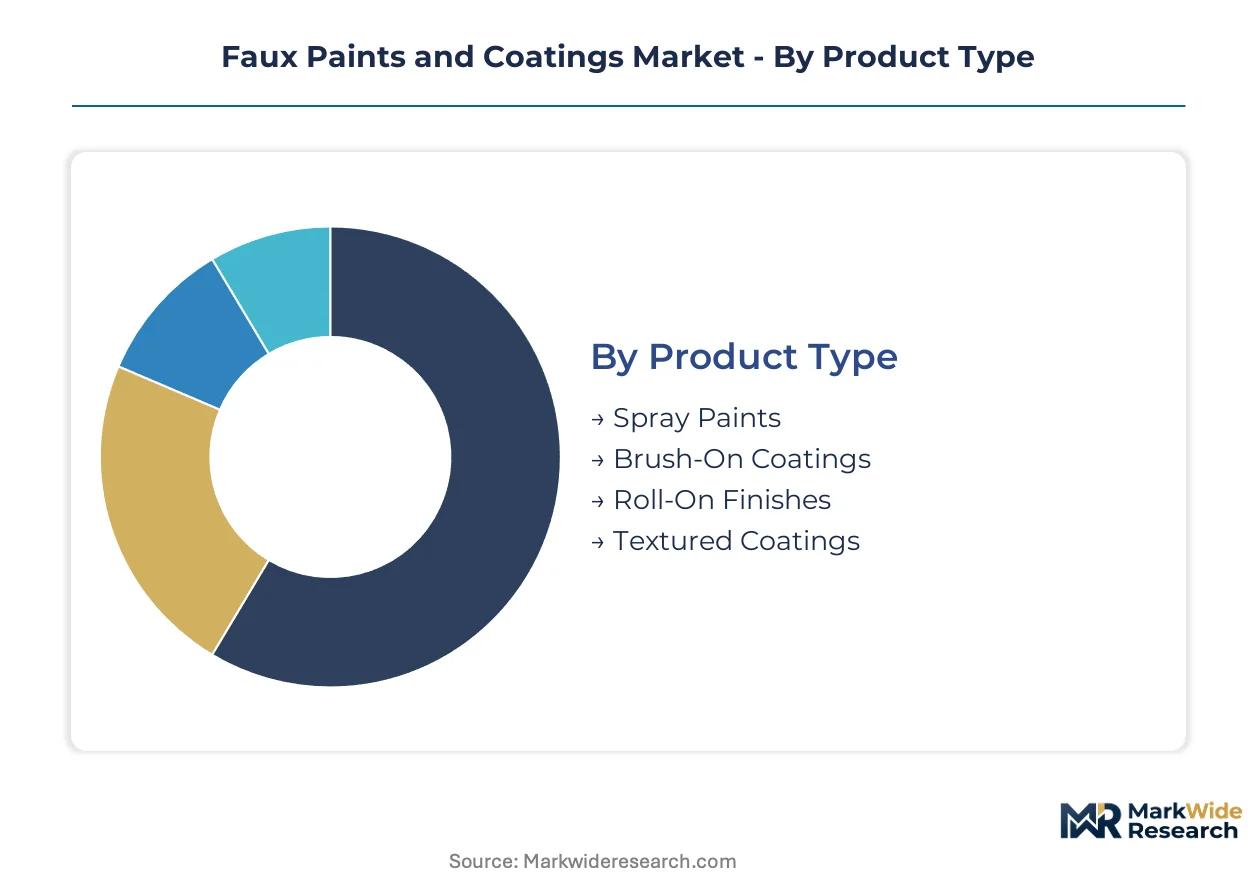
Faux paints and coatings demand fragments across application methods, substrate requirements, and user sophistication levels. Each segmentation axis reveals distinct margin structures and compliance exposure that reshape supplier priorities.
Product Type:
Customization intensity varies sharply across this category, from standardized aerosol formats to artisan-mixed texture systems requiring batch-level specification.
- Spray Paints:Aerosol-dispensed pigmented systems deliver uniform atomization for automotive accent work and furniture detail restoration. Demand clusters in custom automotive shops across the United States and Germany where precision control commands premium positioning. EPA VOC limits are accelerating waterborne propellant reformulation investments among specialty manufacturers.
- Brush-On Coatings:High-viscosity resin systems enable layered manipulation for marble and wood-grain simulation through hand-applied stroke techniques. Residential renovation contractors in suburban United States corridors specify these products for feature wall projects where substrate preparation costs dominate overall economics. REACH substance restrictions on aromatic solvents are compressing traditional alkyd availability in European specification channels.
- Roll-On Finishes:Medium-body formulations engineered for rapid coverage across large surface areas with reduced skill requirements. DIY retailers in China stock these SKUs for first-time homeowner applications.
- Textured Coatings:Aggregate-loaded systems creating dimensional surface effects through trowel or hopper application. Commercial hospitality projects in Dubai and Miami specify these for lobby and corridor treatments.
Leading the category by volume: Brush-On Coatings. Growing fastest: Spray Paints.
Application:
Project scale and specification authority determine channel access and margin capture across this dimension.
- Residential Interiors:Homeowner-directed renovation spending concentrates on living room and primary bedroom feature treatments replicating travertine or walnut aesthetics. Contractors in Texas and Florida metropolitan corridors report strongest specification traction where new construction volume sustains finishing trades.
- Commercial Spaces:Architect-specified systems for hospitality lobbies, retail facades, and corporate reception areas demanding durability certification and batch consistency. Water-based acrylics are displacing solvent alternatives in German commercial refurbishment projects under tightened BImSchV emissions enforcement.
- Automotive Refinishing:Custom paint shops and collision repair facilities require chip-resistant finishes meeting OEM color matching standards. Solvent-based alkyds retain specification here despite regulatory pressure due to durability specifications.
- Furniture Restoration:Antique dealers and specialty refinishers seeking period-appropriate patina replication. Demand concentrates in heritage furniture markets of Massachusetts and North Carolina.
Residential Interiors commands the largest revenue pool. Commercial Spaces shows the steepest expansion trajectory as hospitality construction accelerates.
Technology:
Environmental compliance timelines are fragmenting competitive position across resin chemistry platforms.
- Water-Based:Acrylic emulsion systems achieving VOC compliance without sacrificing application window flexibility. Chinese domestic manufacturers are scaling capacity fastest under GB 38508-2020 limits on solvent content.
- Acrylic-Based:Thermoplastic resin platforms offering UV stability and color retention for exterior architectural applications. German specification engineers favor these for commercial facade treatments.
- Oil-Based:Traditional alkyd binders delivering penetration and flow-out characteristics prized in furniture restoration. Regulatory pressure is compressing market access outside automotive refinishing segments.
- Solvent-Based:High-solids systems retaining share where rapid cure and chemical resistance specifications override environmental constraints. Automotive OEM touch-up programs remain the primary demand anchor.
Water-Based technology leads volume growth. Acrylic-Based formulations are climbing the fastest among premium specification tiers.
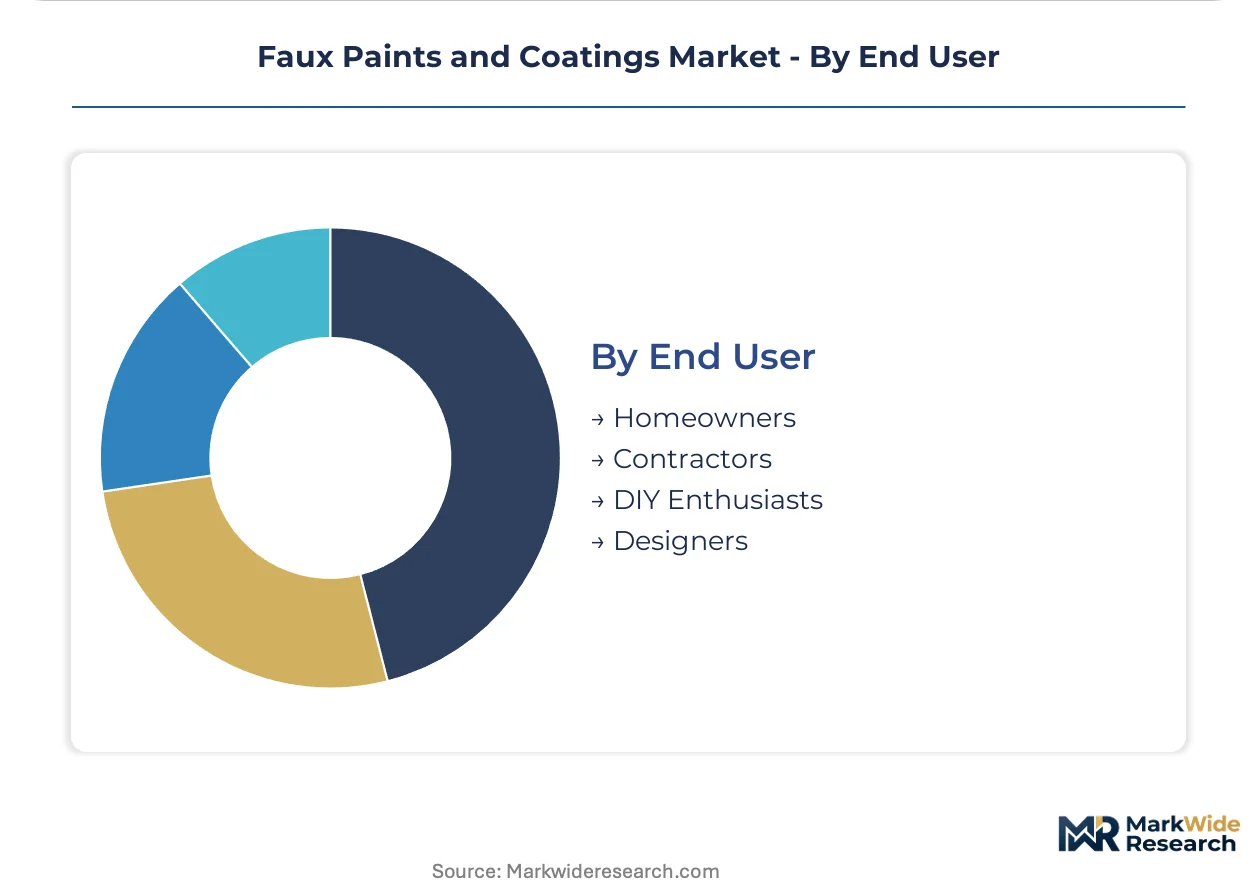
End User:
Technical sophistication and project scale create distinct procurement behaviors across user types.
- Contractors:Professional painting firms purchasing through distributor or direct-manufacturer channels with volume pricing and specification support requirements. United States metropolitan corridor contractors increasingly bypass regional distributors for manufacturer-direct digital platforms.
- Designers:Interior architects and specification writers influencing product selection through color library access and texture-matching software. Faux Effects International retains loyalty through proprietary algorithm subscriptions.
- Homeowners:Discretionary renovators seeking single-project solutions through retail home improvement channels. Big-box retailers in China and the United States compete on color-matching service availability.
- DIY Enthusiasts:Hobbyist segment pursuing craft-level finishing techniques through online tutorial engagement and specialty retailer access. YouTube demonstration content drives product trial in this cohort.
Contractors represent the largest volume channel. Designers are gaining share fastest as specification influence consolidates in commercial projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan construction corridors in Texas and Florida sustain the heaviest specification volume for residential faux finishes, where new housing permits and renovation spending concentrate contractor demand.
United States
Homeowners in suburban Dallas and Houston corridors allocate discretionary budgets toward travertine and wood-grain replication for feature walls. EPA VOC regulations under the Clean Air Act accelerate waterborne acrylic adoption among regional formulators. Miami hospitality developers specify textured coatings for lobby treatments, driving premium product demand.
Germany
Commercial refurbishment projects in Berlin and Munich prioritize BImSchV-compliant coating systems for heritage building restoration. REACH substance restrictions on aromatic solvents compress traditional alkyd availability in specification channels. Bavarian industrial paint manufacturers scale waterborne capacity to serve Central European export markets.
China
First-time homeowners in Shanghai and Shenzhen purchase roll-on finishes through DIY retail channels for apartment renovations. GB 38508-2020 VOC ceilings force domestic manufacturers toward water-based formulation platforms. Pearl River Delta coating clusters expand compliant production capacity for Southeast Asian export.
United Arab Emirates
Hospitality construction in Dubai and Abu Dhabi specifies dimensional textured coatings for luxury hotel lobbies and corridors. The country's building codes incorporate European emissions benchmarks for interior finishes. Sharjah manufacturing zones host regional distribution hubs serving Gulf Cooperation Council markets.
India
Residential interior projects in Mumbai and Bangalore drive brush-on coating consumption for marble-effect feature treatments. Bureau of Indian Standards certification requirements shape product development priorities for domestic formulators. Gujarat chemical manufacturing corridors supply pigment and resin feedstocks to regional coating operations.
Faux Paints and Coatings Market Competitive Landscape
Capital-heavy integrated manufacturers compete with asset-light specialty designers across formulation and application technology tiers. Market structure concentrates among multinational chemical conglomerates with captive resin production, while regional specialists retain specification influence through proprietary texture-matching systems. Three archetypes dominate: vertically integrated coating conglomerates controlling raw material through distribution; specialty finish houses monetizing digital specification platforms; and regional formulators serving price-sensitive construction markets. Competitive dynamics center on M&A-driven geographic expansion and technology licensing partnerships that accelerate compliant formulation access.
Among vertically integrated conglomerates, AkzoNobel and The Sherwin-Williams Co. occupy positions spanning industrial-scale resin production through contractor-direct distribution channels. Faux Effects International Inc. exemplifies the specialty archetype, anchoring designer loyalty through proprietary algorithm subscriptions rather than commodity volume. These three represent distinct strategic postures: scale-driven supply chain control, specification-influence monetization, and integrated channel dominance.
| Leading Market Players |
|---|
| Faux Effects International Inc. |
| AkzoNobel |
| The Sherwin-Williams Co. |
| Kansai Paint Co. Ltd. |
| Axalta Coating Systems |
| Nippon Paint Holdings Co., Ltd. |
| PPG Industries, Inc. |
| Benjamin Moore & Co. |
| Asian Paints Ltd |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialty coating houses have consolidated regional formulator networks across the United States and Germany, concentrating procurement leverage over titanium dioxide suppliers while enforcing pricing discipline through volume-commitment contracts with metropolitan contractor channels.
Pricing Analysis
Value-based pricing anchored to project outcome quality dominates specification-grade faux finishes, where designers pay premium rates for proprietary color-matching algorithm access and batch consistency certification. Three-tier pricing structure across premium, standard, and economy levels separates designer-specified systems from contractor-grade volume products and DIY retail SKUs. Cost compression in mid-tier brush-on coatings is intensifying because Chinese manufacturers are scaling waterborne capacity under GB 38508-2020 compliance deadlines. DIY homeowners exhibit highest price sensitivity, while hospitality developers demonstrate lowest sensitivity due to durability certification requirements.
Supply Chain Analysis
Dual-sourcing requirements from major United States and German contractors mandate multi-supplier qualification for acrylic resin feedstocks, preventing single-source dependency despite concentration in China, Germany, and the United States for binder production. Formulation draws from titanium dioxide pigments, acrylic emulsions, and nano-scale mineral additives as critical inputs. Tariff exposure on Chinese-origin resin intermediates creates margin volatility for regional formulators lacking captive supply. Distribution runs through manufacturer-direct digital platforms and traditional distributor networks serving contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EPA VOC limits under the Clean Air Act erect barrier-to-entry moats favoring incumbents with established waterborne formulation infrastructure and regulatory affairs capacity.
For Market Incumbents: Acquire distressed alkyd production assets in the United States Rust Belt to convert into waterborne acrylic capacity serving EPA-compliant specification channels. Consolidate regional distributor relationships in Texas and Florida metropolitan corridors before digital platform disintermediation accelerates. Backward integration into titanium dioxide procurement through long-term offtake contracts with Gulf Coast pigment producers defends margin position against feedstock volatility. For New Entrants and Emerging Players: Direct-to-contractor digital specification platforms offer the lowest-friction entry vector for penetrating United States renovation markets without legacy distributor relationships. Target DIY retail channels in Chinese first-tier cities where GB 38508-2020 compliance creates substitution windows for waterborne technology licensors partnering with domestic manufacturers. Augmented reality-assisted application training tools reduce skill transfer barriers for expanding contractor base beyond traditional craft clusters. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty finish houses with proprietary texture-matching software subscriptions in Germany and the United States, where REACH and EPA regulatory burdens strand legacy solvent-based competitors. Long-term viability centers on waterborne technology platforms with certified compliance across multiple regulatory jurisdictions. Watch for inflection when Chinese domestic manufacturers achieve export-scale GB-compliant capacity serving Southeast Asian hospitality construction markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive acrylic emulsion supply insulates margin from Chinese feedstock tariff exposure. |
| Waterborne Technology Licensing Partnerships | REACH-compliant formulation access accelerates European commercial refurbishment penetration. |
| Digital Color-Matching Platform Development | Cloud-based texture libraries reduce specification friction and secure designer loyalty. |
| AR-Assisted Applicator Training Program | Skill transfer compression enables contractor base expansion beyond traditional craft corridors. |
| Food-Contact Surface Certification Investment | FDA-compliant coating categories open premium positioning in commercial kitchen segments. |
Research Methodology
Multi-period observation of EPA regulatory filing patterns, REACH authorization timelines, and Chinese GB standard implementation phases anchored the trend analysis, supplemented by interviews with coating plant managers, procurement leads at hospitality developers, distribution channel partners, and technical R&D directors at resin suppliers. Secondary validation drew from EPA Clean Air Act enforcement records, ECHA substance restriction databases, Chinese customs trade data, and SEC 10-K disclosures from listed coating manufacturers. Bottom-up segment sizing triangulated against top-down construction spending elasticity models.
Input-output matrices mapped resin feedstock costs, formulation technology compliance tiers, and application method intensity across residential interior, commercial space, automotive refinishing, and furniture restoration end-uses throughout the forecast period. CAGRs were derived from elasticity-adjusted volume projections segmented by product type, application, technology platform, and end-user sophistication. Industry-specific inputs included VOC regulatory phase-in schedules, titanium dioxide price indices, and metropolitan construction permit data from Dallas, Houston, Miami, Berlin, and Shanghai corridors.
Inputs from hospitality developer procurement databases and contractor specification records were available through the study window; gaps in real-time Chinese domestic manufacturer capacity expansion data introduce uncertainty bands around waterborne technology adoption velocity. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and feedstock price stabilization. Deviation in EPA VOC limit implementation timing or REACH substance restriction scope expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Core Plate Varnishes Market
Paints & Coatings
Canvas Primer Market
Paints & Coatings
Global Construction Paints and Coatings Market
Paints & Coatings
Anti-Fungal and Anti-Bacterial Paints Market
Paints & Coatings
Architectural Coatings Market
Paints & Coatings
India Floor Coatings Market
Paints & Coatings
Fluorescent Paint Market
Paints & Coatings
Automotive Paints Market
Paints & Coatings
Road Marking Paints and Coatings Market
Paints & Coatings
Global Paints and Coatings Fillers Market
Paints & Coatings
Resins in Paints and Coatings Market
Paints & Coatings
Automotive Coatings Market
Paints & Coatings
Global Antifouling Paints and Coatings Market
Paints & Coatings
Oman Paints and Coatings Market
Paints & Coatings
Bituminous Paints Market
Paints & Coatings
US Paints and Coatings Market