
 United Arab Emirates (UAE) Paints and Coatings Market | 2026-2036
United Arab Emirates (UAE) Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates (UAE) Paints and Coatings Market Analytics
Luxury hospitality developers is redrawing procurement priorities in the UAE paints and coatings sector, eclipsing traditional government infrastructure buyers in volume and specification intensity. Jotun anchors its position through deep vertical integration into marine and protective coatings for Arabian Gulf oil and gas assets. National Paints Factories Co Ltd dominates the domestic architectural segment with manufacturing scale and distribution control across the northern emirates. Hempel A/S specializes in high-performance protective coatings for offshore platforms and industrial facilities.
Paints and coatings are liquid or powder formulations comprising resins, pigments, solvents, and additives that cure into adherent films providing corrosion resistance, aesthetic finish, or functional surface properties; their primary purpose spans substrate protection, decoration, and performance enhancement across construction, industrial, and transportation assets. Architectural coatings leads value generation due to relentless residential and commercial construction activity across Dubai South and Al Reem Island, while industrial coatings represents the fastest-expanding margin pool as petrochemical facility maintenance cycles compress. Waterborne technology now commands premium positioning as MOHAP and municipal environmental standards tighten solvent emission thresholds.
MOHAP enforces chemical safety standards for interior architectural coatings, while Dubai Municipality's green building codes mandate VOC content limits that reshape product portfolios. The UAE's alignment with Gulf Standardization Organization (GSO) specifications creates unified technical barriers for imported formulations. Stakeholders must monitor how Abu Dhabi Department of Energy's industrial decarbonization mandates will redirect demand toward powder coating and UV-cured alternatives.
Market Dynamics
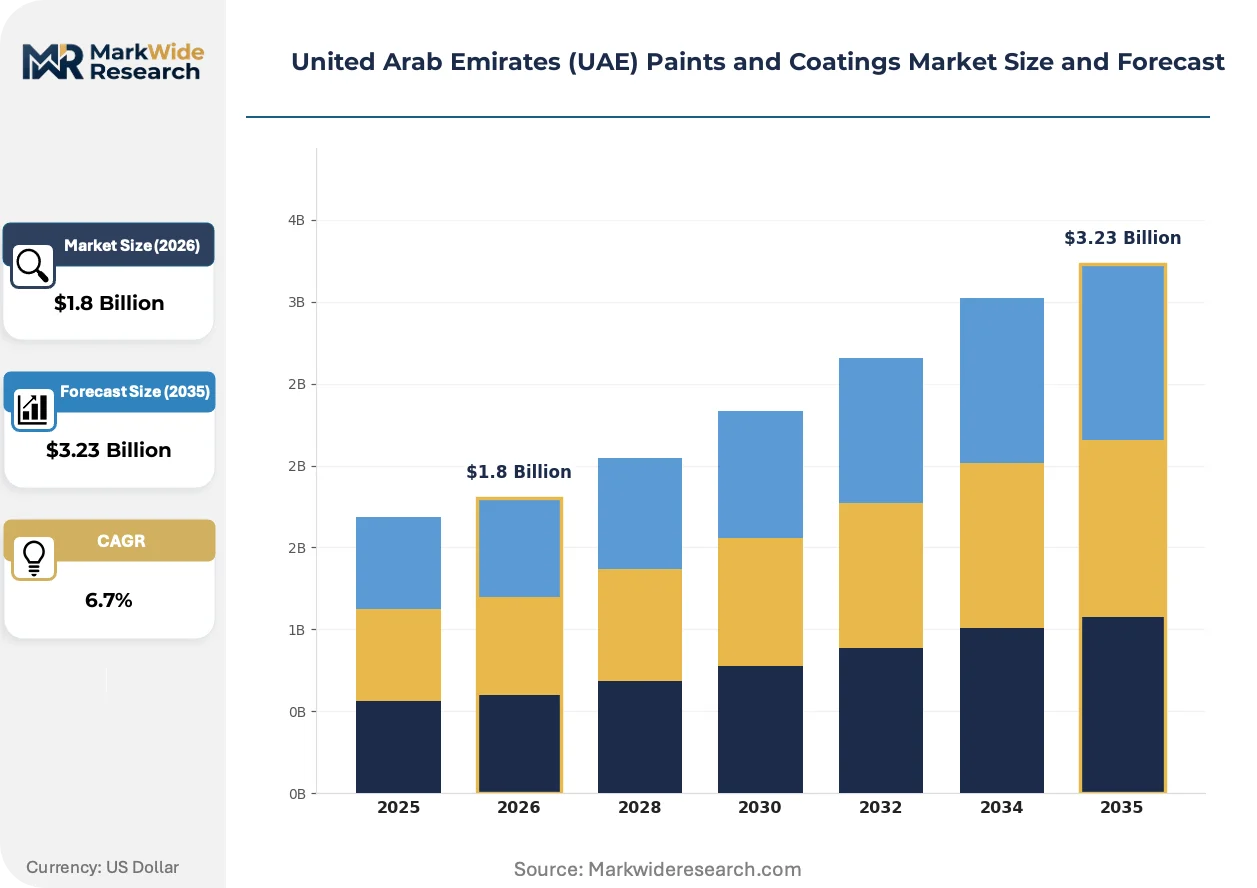
Hospitality and luxury residential developers now command larger procurement volumes than traditional government infrastructure buyers, fundamentally reordering specification hierarchies and margin structures across the UAE paints and coatings sector.
Growth Catalysts
- Dubai Municipality green building regulations:Mandatory low-VOC formulations for new developments are forcing product portfolio upgrades and creating premium positioning for compliant suppliers.
- Megaproject pipelines:Dubai South and Al Reem Island construction activity concentrates demand in high-performance architectural coatings with accelerated specification cycles.
- Waterborne technology:MOHAP chemical safety standards for interior coatings are compressing solvent-based alternatives and redirecting R&D investment toward compliant formulations.
Market Restraints
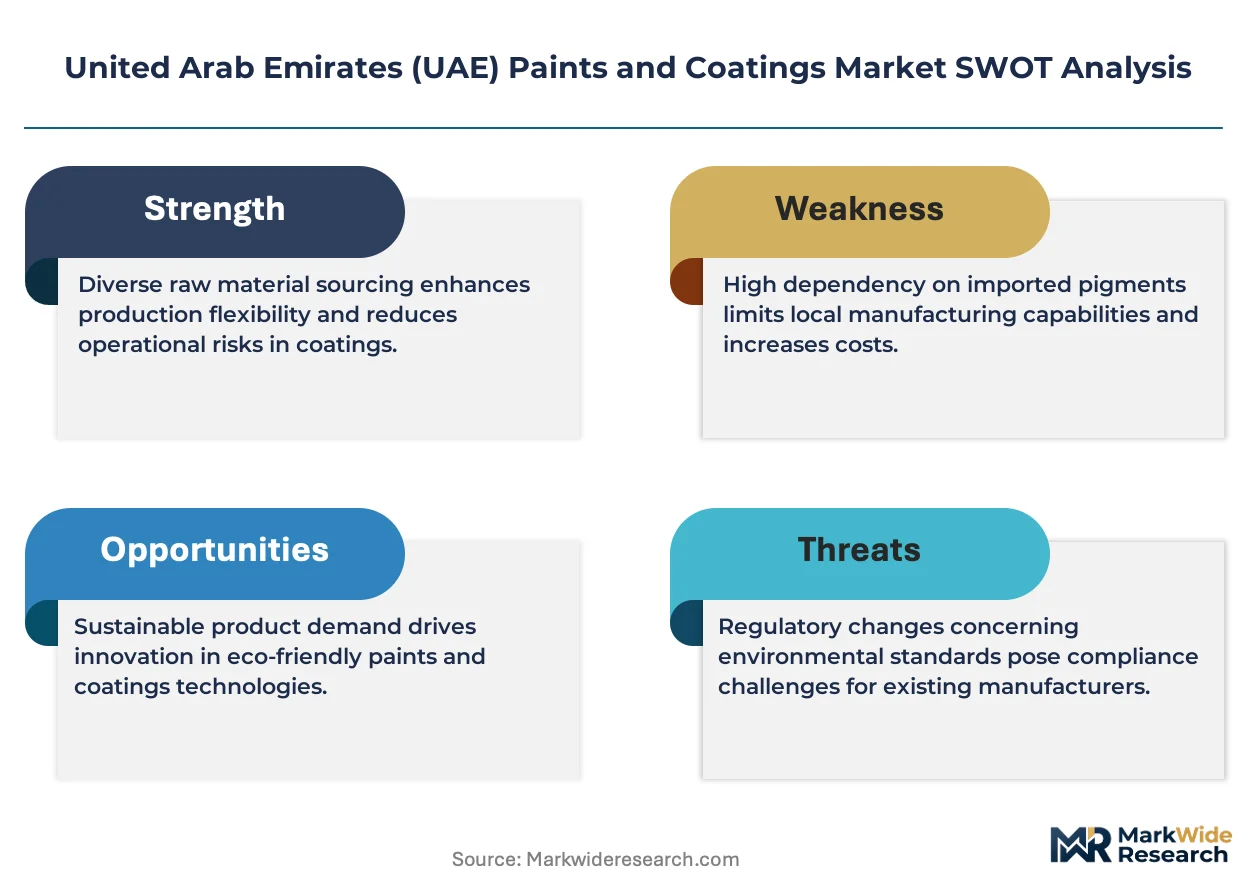
- Raw material concentration:Titanium dioxide and specialty resin supply chains concentrate in limited Asian manufacturing bases, exposing formulators to input cost volatility and freight disruption.
- Technical performance gaps:Waterborne alternatives still underperform solvent-based systems in extreme humidity and salt-air exposure conditions prevalent across Arabian Gulf coastal zones.
- Import dependency:GSO unified technical barriers favor established multinational suppliers with regional certification infrastructure, constraining new entrant market access.
Strategic Opportunities
- Industrial decarbonization mandates:Abu Dhabi Department of Energy directives will redirect maintenance expenditure toward powder coating and UV-cured alternatives in petrochemical facilities.
- Northern emirates distribution gaps:Manufacturing and logistics infrastructure in Ras Al Khaimah and Fujairah remains underdeveloped relative to Dubai and Abu Dhabi, creating whitespace for localized production investment.
- Marine coatings convergence:Protective coatings for offshore platforms and port infrastructure present cross-selling potential as Arabian Gulf oil and gas asset maintenance cycles compress.
Industry Challenges
- Formulation chemist scarcity:UAE educational institutions produce limited specialized talent in polymer chemistry and coating science, forcing reliance on expatriate technical staff with elevated retention costs.
- Certification timeline compression:MOHAP and Dubai Municipality parallel approval processes for new product introductions create extended commercialization cycles that conflict with project-driven demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates (UAE) Paints and Coatings Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Architectural Coatings, Industrial Coatings, Automotive Coatings, Decorative Coatings Application: Protective Coatings, Decorative Applications, Functional Coatings, Maintenance Solutions End User: Construction Industry, Automotive Sector, Marine Industry, Aerospace Sector Technology: Waterborne Technology, Solventborne Technology, Powder Coating, UV-Cured Coatings |
| Companies Covered | Akzo Nobel N V, Caparol Paints, Jotun, DAW SE, Hempel A/S, National Paints Factories Co Ltd, Asian Paints, Sigma Paints, PPG Industries Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates (UAE) Paints and Coatings Market Evolving Landscape
Environmental compliance mandates and buyer sophistication are accelerating formulation chemistry evolution and procurement model transformation across the UAE paints and coatings landscape.
Waterborne coating technology is fragmenting traditional solvent-based market positions through superior regulatory alignment and indoor air quality performance. Luxury hospitality developers specify these systems aggressively for guest-facing interiors. The technology is fragmenting incumbent supplier relationships as architectural specifiers bypass established brands for compliant alternatives.
MOHAP chemical safety standards and Dubai Municipality green building codes operate in parallel to reshape product development priorities. Industrial facility operators face overlapping compliance obligations that compress formulation flexibility. Petrochemical maintenance contractors in Abu Dhabi industrial zones now prioritize pre-certified coating systems to accelerate project approval timelines.
Developer-led procurement consolidation concentrates specification authority with hospitality and luxury residential project owners. Traditional distributor networks face disintermediation as major developers establish direct supplier relationships and volume-based framework agreements. This concentration is most visible in Dubai megaproject clusters where procurement teams centralize coating decisions across multiple simultaneous developments.
United Arab Emirates (UAE) Paints and Coatings Market Segmentation
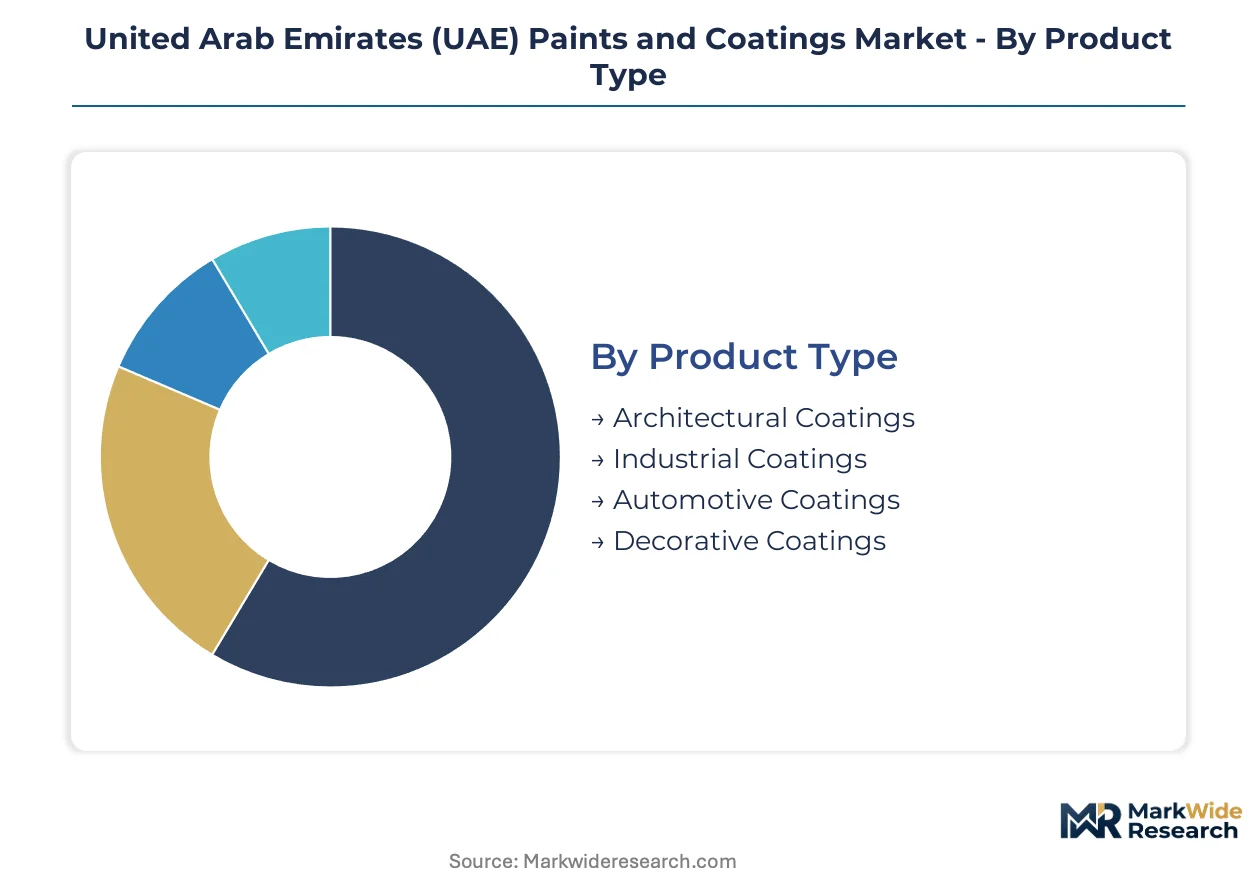
Segmentation reveals how procurement power concentrates in UAE megaprojects and where regulatory pressure reshapes supplier portfolios. Understanding these splits exposes margin concentration points and substitution vulnerabilities across the emirates.
Product Type:
Substitution pressure from waterborne alternatives hits solvent-dependent segments hardest, forcing portfolio reconfiguration among established suppliers.
- Architectural Coatings:Waterborne acrylic and latex formulations dominate interior and exterior building applications. Dubai South and Al Reem Island residential towers absorb the bulk of procurement volume as hospitality developers specify low-VOC systems for luxury interiors. This segment anchors the volume base while Industrial Coatings gains share at the steepest rate.
- Industrial Coatings:Epoxy and polyurethane systems protect petrochemical infrastructure, offshore platforms, and desalination facilities across Abu Dhabi industrial zones. Compressed maintenance cycles at Ruwais and Jebel Ali facilities accelerate specification velocity for high-performance protective films.
- Automotive Coatings:Basecoat-clearcoat systems serve Jebel Ali automotive assembly and refurbishment operations. OEM-grade formulations face import dependency constraints under GSO unified technical barriers.
- Decorative Coatings:Premium aesthetic finishes target luxury residential lobbies and hospitality interiors in Downtown Dubai and Saadiyat Island developments. Texture and specialty effect coatings command specification priority among design-led developers.
Architectural Coatings generates the dominant revenue pool while Industrial Coatings climbs the fastest as petrochemical facility maintenance intensifies.
Application:
Cost tier stratification separates commodity maintenance work from premium new-build specifications, with margin compression concentrated in standardized protective jobs.
- Protective Coatings:Heavy-duty epoxies and zinc-rich primers shield steel infrastructure in Arabian Gulf salt-air conditions. Offshore oil platforms and port facilities in Fujairah and Ras Al Khaimah drive specification demand for corrosion-resistant systems.
- Decorative Applications:Interior wall finishes and exterior facade treatments serve hospitality and residential developments. Dubai Municipality green building codes mandate VOC thresholds that disqualify conventional solvent-based alternatives for new construction.
- Functional Coatings:Anti-fouling marine paints and heat-reflective roof coatings address specific performance requirements. Jebel Ali port expansion and solar rooftop installations concentrate demand in specialized formulation categories.
- Maintenance Solutions:Refurbishment coatings for existing commercial and industrial assets. Aging building stock in Deira and Bur Dubai commercial districts sustains recurring demand cycles distinct from megaproject-driven new construction.
Protective Coatings commands the largest project values while Functional Coatings expands most quickly on marine and energy infrastructure investment.
End User:
Customer type fragmentation separates volume-driven construction procurement from specification-intensive industrial applications, with hospitality developers wielding disproportionate influence over architectural coating standards.
- Construction Industry:General contractors and developers specify coatings for residential, commercial, and mixed-use developments. Emaar, Aldar, and similar master developers centralize procurement decisions across simultaneous Dubai and Abu Dhabi projects.
- Automotive Sector:Assembly plants, collision repair centers, and aftermarket refinishing operations. Jebel Ali free zone concentration supports localized demand for OEM-matched color systems.
- Marine Industry:Shipyards, offshore platform operators, and port authorities require specialized anti-corrosion and anti-fouling systems. Arabian Gulf oil and gas asset maintenance compresses re-coating cycles at Zayed Port and Khalifa Port facilities.
- Aerospace Sector:MRO facilities and aircraft exterior refinishing at Al Maktoum International and Abu Dhabi International Airport. Military and commercial aviation maintenance drives demand for lightweight, fuel-efficient coating systems.
Construction Industry absorbs the dominant procurement volume while Marine Industry captures the steepest specification intensity per square meter applied.
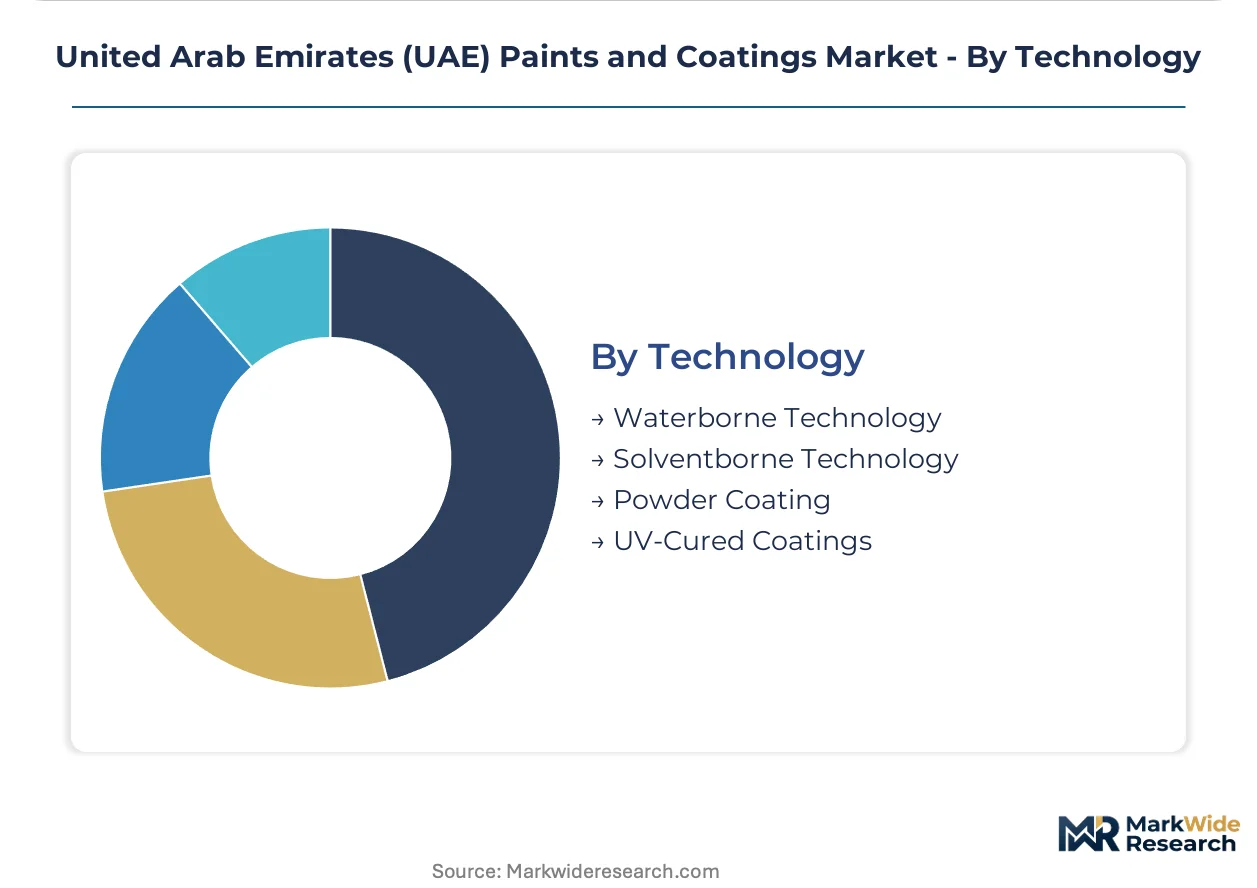
Technology:
Volume concentration favors waterborne systems in architectural applications, while solventborne retains defensive positions in extreme-performance industrial niches despite regulatory headwinds.
- Waterborne Technology:Acrylic and polyurethane dispersions replace solvent-based alternatives in interior architectural and light industrial applications. MOHAP chemical safety standards and Dubai Municipality green building codes accelerate displacement of conventional systems in hospitality and residential developments.
- Solventborne Technology:High-solids alkyds and two-component epoxies maintain performance advantages in humidity-extreme and salt-air exposure conditions. Petrochemical maintenance contractors in Ruwais industrial zones specify these systems where waterborne alternatives underperform.
- Powder Coating:Thermosetting polymer films applied to metal substrates through electrostatic spray and heat curing. Abu Dhabi Department of Energy industrial decarbonization mandates redirect demand toward zero-VOC powder alternatives for facility infrastructure.
- UV-Cured Coatings:Instant-curing formulations for wood, plastic, and specialized industrial substrates. Furniture manufacturing and electronics finishing in northern emirates industrial zones present emerging application niches.
Waterborne Technology commands the dominant installed base while Powder Coating gains traction fastest on industrial decarbonization compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE-manufactured coatings flow primarily to Saudi Arabian infrastructure contractors and Qatari hospitality developers, with re-export channels extending to Kuwait and Oman megaproject sites.
Dubai
Dubai South and Al Reem Island residential towers absorb the dominant architectural coating procurement volume. Dubai Municipality green building regulations mandate low-VOC formulations for all new developments. Downtown Dubai and Business Bay hospitality clusters concentrate specification authority with Emaar and master developers.
Abu Dhabi
Petrochemical facility maintenance at Ruwais and Jebel Ali industrial zones drives protective coating demand cycles. Abu Dhabi Department of Energy industrial decarbonization mandates redirect expenditure toward powder coating alternatives. Saadiyat Island luxury residential and cultural district developments concentrate high-performance decorative coating specifications.
Sharjah
Industrial manufacturing zones and port expansion at Hamriyah Free Zone sustain functional coating demand. MOHAP chemical safety standards apply uniformly across the emirate's interior architectural applications. Sharjah's logistics corridor position supports distribution hub functions for northern emirates coverage.
Northern Emirates
Ras Al Khaimah and Fujairah manufacturing infrastructure remains underdeveloped relative to Dubai and Abu Dhabi. GSO unified technical barriers constrain import flexibility for new coating formulations entering these markets. Port facilities at Khalifa Port and Zayed Port anchor marine coating maintenance cycles for offshore oil and gas assets.
United Arab Emirates (UAE) Paints and Coatings Market Competitive Landscape
Player mix skews toward multinational specialists with regional certification infrastructure and domestic manufacturers with distribution control across emirate-level markets. The supplier base concentrates in two tiers: global formulators with marine and protective coating expertise, and regional producers with architectural segment scale. Three archetypes dominate: vertically integrated petrochemical-linked suppliers, hospitality-focused specification specialists, and construction-grade volume producers. Competitive moves center on portfolio diversification into waterborne formulations and strategic partnerships with megaproject developers.
Among European-headquartered specialists, Akzo Nobel N V and Hempel A/S occupy positions anchored in marine and industrial protective segments. Jotun exemplifies the vertically integrated archetype with captive supply advantages in high-performance formulations. National Paints Factories Co Ltd represents domestic manufacturing scale with distribution control across northern emirates markets. These three anchors illustrate how regulatory compliance capability and project-level specification relationships determine competitive positioning.
| Leading Market Players |
|---|
| Akzo Nobel N V |
| Caparol Paints |
| Jotun |
| DAW SE |
| Hempel A/S |
| National Paints Factories Co Ltd |
| Asian Paints |
| Sigma Paints |
| PPG Industries Inc |
| Others |
Value Network & Pricing Analysis
Waterborne acrylic dispersions displacing solvent-based alkyds in Dubai hospitality specifications are simultaneously relocating procurement geography toward Asian resin suppliers and compressing margin structures for European formulators still anchored to legacy production economics.
Pricing Analysis
Waterborne-solventborne technology-generation pricing gaps stratify the UAE market into three performance tiers. Three-tier pricing structure across premium, standard, and economy levels reflects Dubai Municipality green building certification grades and MOHAP compliance status. Price differentiation hinges on VOC threshold attainment and volume framework agreements with Emaar-scale developers. Cost compression in mid-tier architectural coatings is intensifying because National Paints and Jotun are competing for identical megaproject specifications. Hospitality developers show least price sensitivity for guest-facing interiors, while maintenance contractors in Deira commercial districts absorb maximum pricing pressure.
Supply Chain Analysis
Inbound logistics costs from Jebel Ali port congestion and Red Sea container rerouting are elevating landed costs for titanium dioxide and specialty epoxy resins. Raw material supply concentrates in China, South Korea, and India for titanium dioxide pigments, epoxy intermediates, and acrylic monomers. Formulation chemistry draws from petrochemical feedstocks anchored in Saudi Arabia's SABIC supply base. Single-source vulnerability concentrates in titanium dioxide where five Asian producers control export volumes into Arabian Gulf markets. Distribution runs through Dubai-based master distributors with northern emirates sub-distribution partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE paints and coatings market functions as a service-attach opportunity where technical specification support and on-site application consulting generate recurring revenue streams expanding faster than base product sales. Application engineering services and certified contractor training programs now command premium positioning alongside physical coating volumes.
For Market Incumbents: Fortify specification relationships with Dubai master developers through captive application engineering teams embedded at Al Reem Island and Dubai South project sites. Deepen backward integration into waterborne resin production to offset Asian import dependency and margin compression from GSO-certified competitors. Prioritize MOHAP pre-certification investment to compress approval timelines against project-driven demand spikes. For New Entrants and Emerging Players: Dubai Municipality green building certification fast-track programs offer accelerated market access for compliant waterborne formulations targeting hospitality interiors. Northern emirates distribution gaps in Ras Al Khaimah and Fujairah present whitespace for localized blending operations serving port maintenance contractors. Pursue direct procurement relationships with mid-tier residential developers bypassing established distributor networks. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors specification-intensive specialists over commodity volume producers. Long-term viability centers on waterborne formulation capabilities and megaproject developer relationships rather than manufacturing scale alone. Watch Abu Dhabi Department of Energy industrial decarbonization mandate implementation velocity as inflection indicator for powder coating and UV-cured alternative demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Formulation Portfolio Expansion | MOHAP and Dubai Municipality compliance requirements are disqualifying solvent-based alternatives from new construction specifications. |
| Application Engineering Service Buildout | Emaar and Aldar procurement teams prioritize suppliers with embedded technical support at megaproject sites. |
| Backward Integration into Resin Production | Captive acrylic and polyurethane dispersion manufacturing reduces exposure to Asian supply chain volatility. |
| Northern Emirates Distribution Infrastructure | Ras Al Khaimah and Fujairah logistics gaps create first-mover advantage for localized blending and warehousing. |
| Powder Coating Capability Investment | Abu Dhabi Department of Energy decarbonization mandates redirect petrochemical maintenance expenditure toward zero-VOC alternatives. |
Research Methodology
A standing panel of procurement directors at Dubai master developers, technical specification consultants, MOHAP regulatory affairs specialists, and Jebel Ali port logistics coordinators provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with plant managers at Ruwais petrochemical facilities and distribution channel partners in Sharjah logistics corridors. Secondary validation drew from Dubai Municipality building permit databases, GSO technical barrier notifications, customs import records, and SEC filings of multinational coating suppliers. Bottom-up volume estimates from project-level procurement data triangulated against top-down emirate-level construction expenditure forecasts.
Consistency checks validated volume and value outputs against external benchmarks including emirate-level construction contract awards and petrochemical facility maintenance expenditure patterns. The analytical framework modeled segmentation dimensions across product type, application category, end-user industry, and technology platform throughout the forecast period. CAGRs were derived from regression analysis of historical procurement volumes against project pipeline visibility. Industry-specific forecast inputs incorporated Dubai South and Al Reem Island construction timelines alongside Abu Dhabi industrial decarbonization policy implementation schedules.
Underlying assumptions cover sustained megaproject execution rates and stable GSO technical barrier configurations, with deviation risk concentrated in titanium dioxide supply disruptions and accelerated waterborne performance standard adoption. Forecasts reflect these documented assumptions with acknowledged sensitivity to regulatory timeline compression and raw material cost volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Egypt Paints and Coatings Market
Paints & Coatings
Water Color Market
Paints & Coatings
Cement Paints Market
Paints & Coatings
Global Aerosol Paints Market
Paints & Coatings
Radar Absorbing Paint Market
Paints & Coatings
Nigeria Paint and Protective Coatings Market
Paints & Coatings
Middle-East and Africa Wood Coatings Market
Paints & Coatings
Paint Defoamers Market
Paints & Coatings
India Industrial Coatings Market
Paints & Coatings
Paint Buckets Market
Paints & Coatings
Middle-East Paints and Coatings Market
Paints & Coatings
India Paints and Coatings Market
Paints & Coatings
Mexico Paints and Coatings Market
Paints & Coatings
Global Paints and Coatings Fillers Market
Paints & Coatings
Paint Mixing Market
Paints & Coatings
Middle East & Africa Corrosion Protection Coating Market