
 Saudi Arabia Architectural Paints Market | 2026-2036
Saudi Arabia Architectural Paints Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Architectural Paints Market Analytics
Water-based acrylic formulations is shifting away from solvent-based alkyd systems across Saudi Arabia's coating value chain, driven by tightening environmental standards and indoor air quality mandates. Jotun leverages its coastal manufacturing footprint to dominate marine-adjacent architectural projects in the Eastern Province. Jazeera Paints anchors its position through deep distribution across provincial retail networks and contractor-direct channels. AkzoNobel Saudi Arabia Ltd differentiates via premium decorative ranges targeting hospitality and high-end residential developments in Riyadh.
Architectural paints are pigmented liquid coatings formulated with binders, solvents, pigments, and additives, designed to protect and decorate building substrates including concrete, plaster, wood, and metal surfaces, with film thickness typically ranging from 25 to 100 microns dry. Their primary commercial purpose spans new construction finishing, renovation refresh, and ongoing maintenance of built environments across residential, commercial, and institutional structures. Interior paints command the largest volume share within product type segmentation, sustained by continuous housing stock expansion under Vision 2030 residential targets. Water-based formulations represent the fastest-growing formulation category, displacing solvent-based alternatives as contractors and property managers prioritize faster recoat times and reduced odor in occupied spaces. The renovation application segment captures expanding margin pools as aging stock across Jeddah's established districts requires cyclical refinishing.
The Saudi Standards, Metrology and Quality Organization enforces SASO building material standards that govern VOC emissions limits and coating performance benchmarks for products sold within the Kingdom. The Saudi Building Code, administered by the Ministry of Municipal and Rural Affairs and Housing, specifies fire resistance and surface finish requirements that directly influence specification decisions by engineering consultants and project owners. SFDA oversight extends to coatings used in healthcare and food preparation facilities, adding compliance layers for institutional segment suppliers. Stakeholders must monitor evolving green building certification pathways under the Saudi Green Building Forum and assess how carbon accounting requirements may reshape raw material sourcing and product portfolio prioritization across the value chain.
Market Dynamics
The Saudi Arabia Architectural Paints Market is undergoing a structural transformation as Vision 2030 megaprojects concentrate demand in the Western Province while SASO VOC mandates force formulation chemistry shifts across domestic manufacturing.
Growth Catalysts
- Vision 2030 Residential Targets:Government-mandated housing stock expansion across Riyadh and Jeddah generates sustained volume pull for interior coatings, with annual delivery commitments institutionalizing procurement pipelines.
- SASO Building Material Standards:The Saudi Standards, Metrology and Quality Organization's emissions limits create compliance-driven replacement cycles, accelerating water-based acrylic adoption over solvent-based alkyd systems.
- Eastern Province Coastal Development:Marine-adjacent commercial and hospitality construction along the Arabian Gulf generates specialized demand for high-performance exterior formulations with salt-corrosion resistance.
Market Restraints
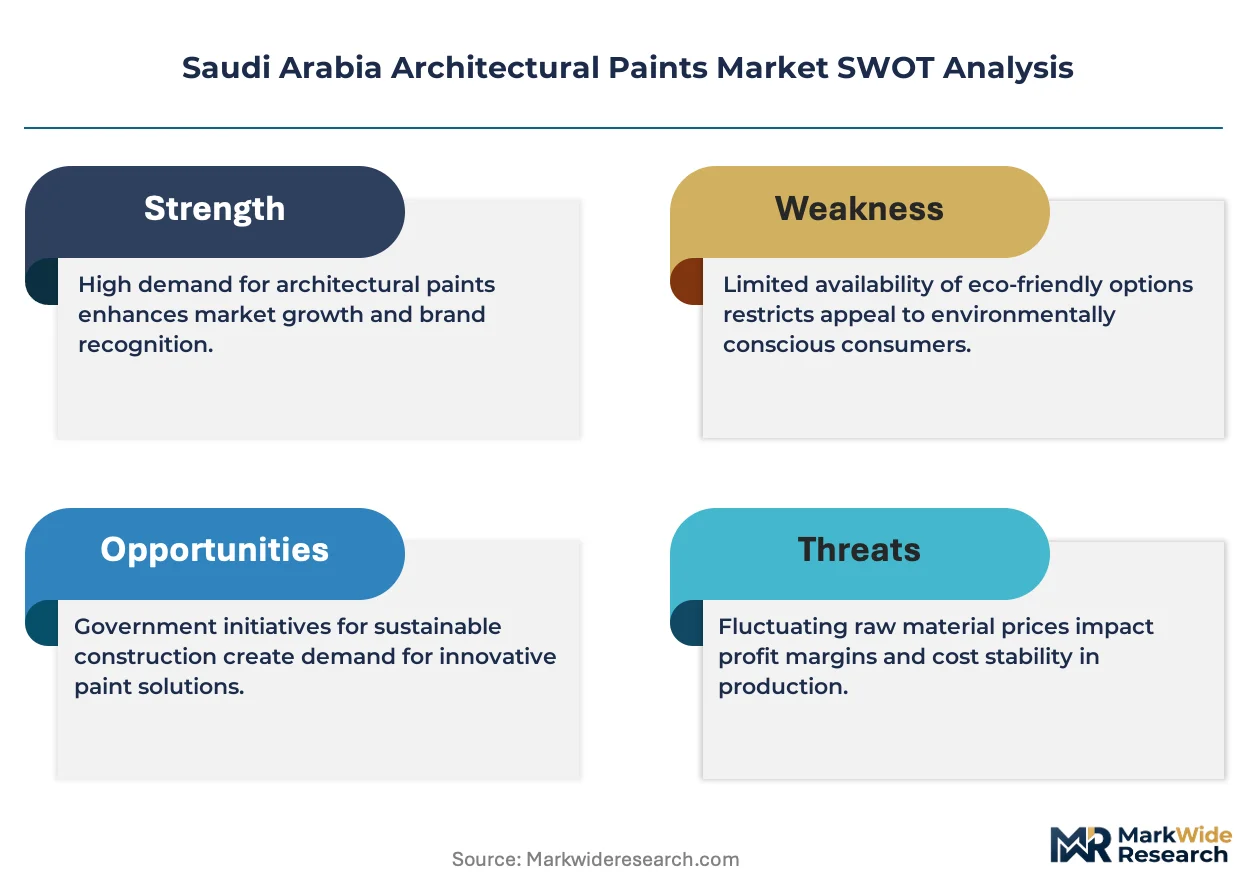
- Titanium Dioxide Feedstock Volatility:Pigment cost fluctuations compress margin pools for mid-tier producers lacking long-term raw material contracts with Saudi Aramco chemical derivatives suppliers.
- Import Dependency for Specialty Additives:Rheology modifiers and biocides concentrate sourcing from European and Asian chemical manufacturers, exposing formulators to currency and shipping cost instability.
- Technical Limitation in Extreme Heat Curing:Summer ambient temperatures exceeding 50°C in interior Riyadh construction sites degrade water-based film formation, forcing seasonal work stoppages or costly climate-controlled application environments.
Strategic Opportunities
- NEOM and Red Sea Project Corridors:Uncontracted coating demand across Tabuk and Medina provinces offers first-mover positioning for suppliers establishing logistics hubs ahead of construction mobilization.
- Saudi Green Building Forum Certification Pathways:Emerging carbon accounting requirements for commercial developments create premium positioning for low-embodied-carbon formulations with verified lifecycle data.
- Digital Specification Platforms:Engineering consultants in Riyadh are migrating coating selection to BIM-integrated databases, enabling direct-to-specifier marketing bypassing traditional distributor intermediaries.
Industry Challenges
- Formulation Chemist Scarcity:Local universities produce insufficient polymer science graduates, forcing manufacturers to recruit expatriate talent or invest in multi-year training programs for Saudi nationals.
- SASO Certification Timeline Compression:New product registration cycles extend 8-12 months, delaying portfolio refreshes and creating inventory obsolescence risk when standards update mid-process.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Architectural Paints Market |
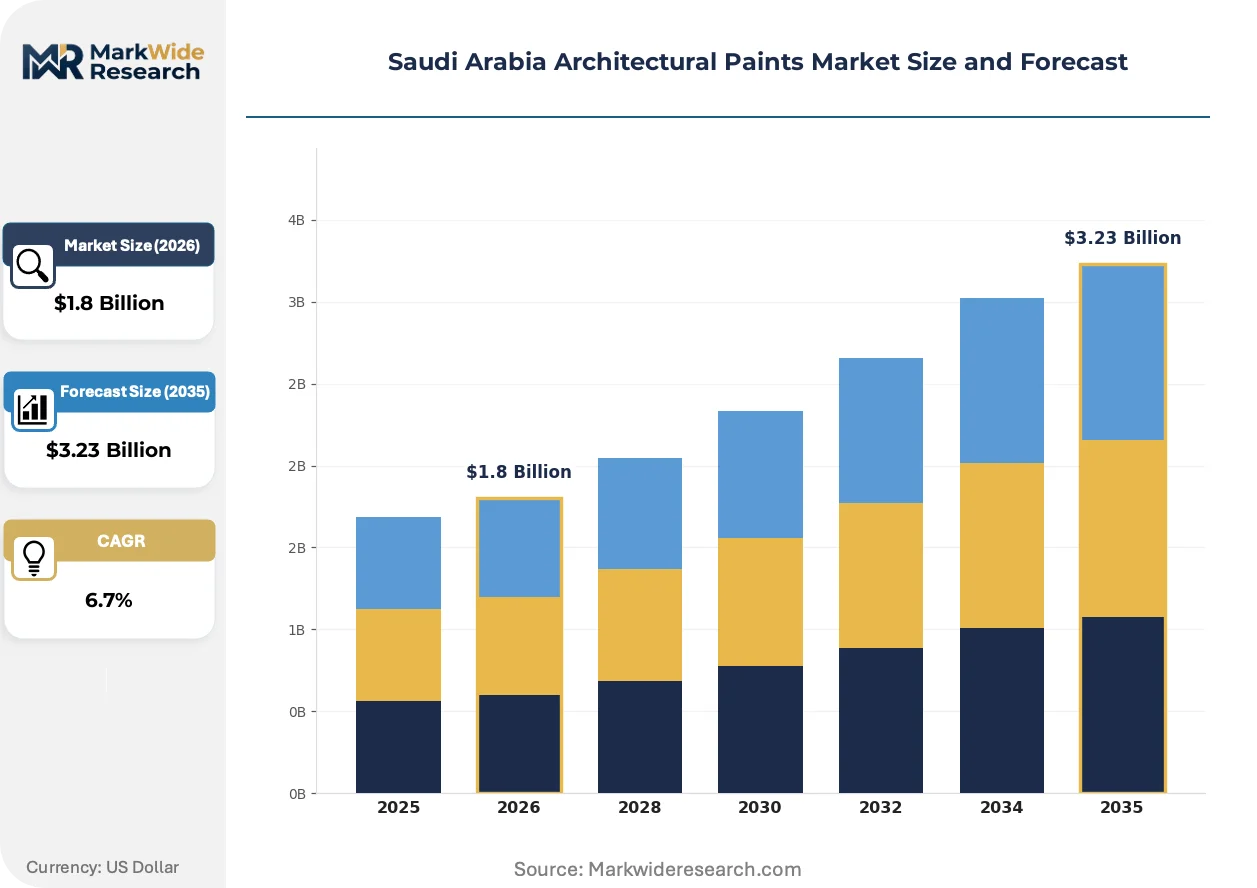
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Paints, Exterior Paints, Primers, Finishes End User: Residential, Commercial, Institutional, Industrial Application: New Construction, Renovation, Maintenance, Decoration Formulation: Acrylic, Alkyd, Water-Based, Solvent-Based |
| Companies Covered | Jotun, Jazeera Paints, Hempel A/S, NATIONAL PAINTS FACTORIES CO. LTD, Caparol Paints, SIPCO, Sigma Paints, AkzoNobel Saudi Arabia Ltd, Sherwin-Williams Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Architectural Paints Market Evolving Landscape
Formulation chemistry and specification workflows are transforming simultaneously as environmental compliance tightens and digital tools penetrate project delivery. Three distinct vectors are reshaping competitive positioning.
Self-cleaning photocatalytic coatings is converging with titanium dioxide nanotechnology to enable exterior surfaces that degrade organic pollutants under UV exposure. Hospitality developers in Jeddah's Corniche district specify these systems for facade maintenance cost reduction. The technology is converging with cooling pigment research to address Saudi Arabia's urban heat island mitigation mandates.
The Saudi Building Code's 2023 surface finish amendments now reference fire resistance ratings that exceed previous benchmarks for high-rise residential towers. Engineering consultants must recalculate coating system specifications to achieve composite assembly ratings, particularly for Riyadh's emerging mixed-use developments. Manufacturers with pre-certified assembly documentation capture specification priority in tender processes.
Consolidated procurement by Saudi Real Estate Refinance Company-financed developers is displacing fragmented contractor purchasing. Large-scale residential operators now negotiate master supply agreements covering 2,000+ unit annual programs, compressing distributor margins while securing volume commitments for approved coating suppliers. This concentration is most visible in Riyadh's northern corridor affordable housing zones.
Saudi Arabia Architectural Paints Market Segmentation
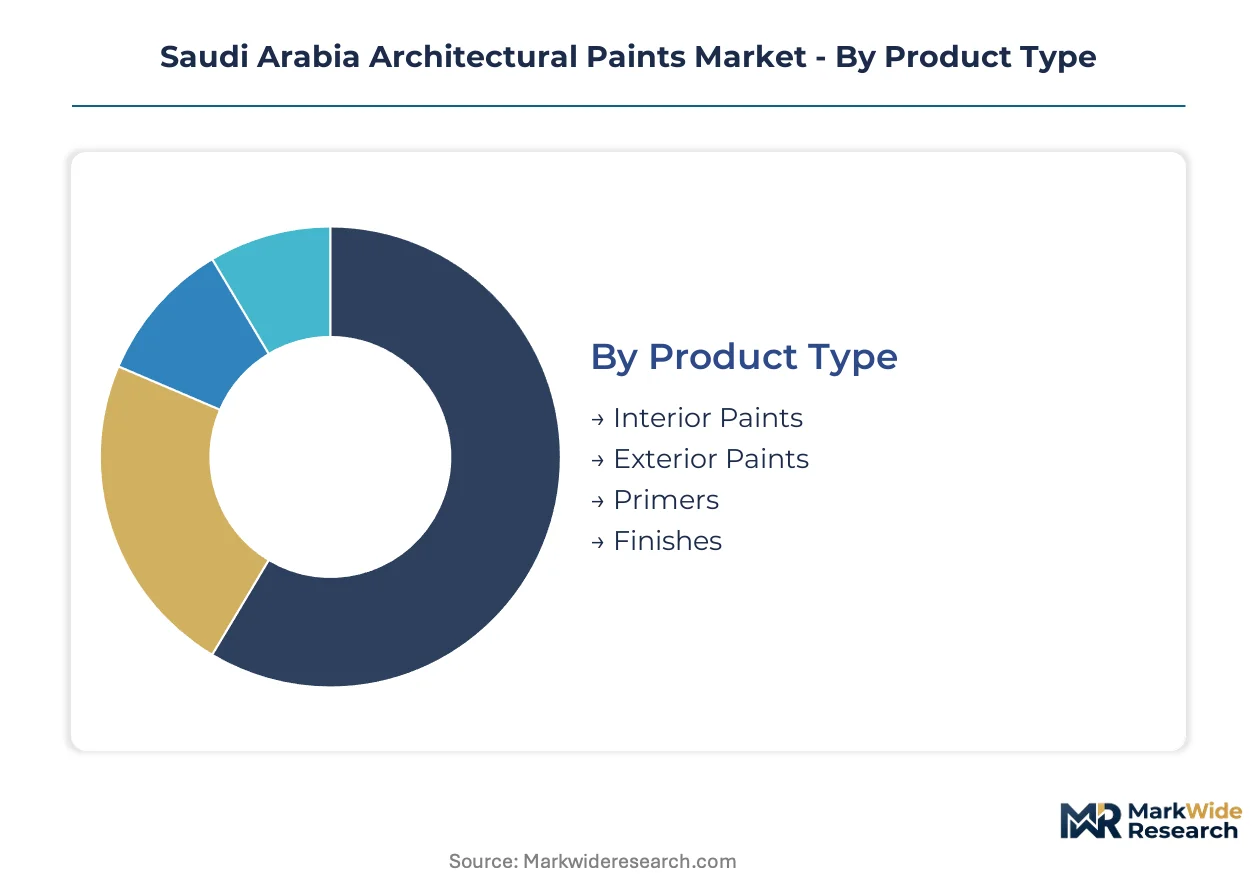
Segmentation in Saudi Arabia's architectural paints market reveals distinct procurement patterns across construction phases and building typologies. Specification requirements diverge sharply between Vision 2030 megaprojects and established urban renovation corridors, forcing suppliers to maintain parallel product portfolios with divergent compliance footprints.
Product Type:
Interior paints function as standalone specification decisions with direct owner influence, while exterior systems embed within broader facade assembly approvals requiring engineering consultant sign-off.
- Interior Paints:Water-based acrylic emulsions dominate this category, formulated for low-VOC emissions under SASO building material standards. Demand concentrates in Riyadh's northern corridor affordable housing zones and Jeddah's residential expansion districts, driven by Vision 2030 annual delivery commitments institutionalizing procurement pipelines.
- Exterior Paints:Elastomeric and silicone-modified acrylic systems provide weathering resistance against Saudi Arabia's intense UV exposure and thermal cycling. Specifications cluster in Western Province commercial developments and Eastern Province coastal hospitality projects, where salt-corrosion resistance mandates premium formulation chemistry.
- Primers:Alkali-resistant sealing coats for concrete and plaster substrates, essential for adhesion warranty compliance in Saudi Building Code-permitted structures.
- Finishes:Decorative texture and specialty effect coatings for high-end residential and hospitality statement surfaces.
Volume placements concentrate in Interior Paints; the faster expansion belongs to Exterior Paints.
End User:
Cost tier segmentation separates specification autonomy from procurement consolidation, with owner-operated segments retaining direct coating selection authority.
- Residential:Individual homeowners and small-scale developers select through retail networks and contractor recommendations, prioritizing odor control and recoat speed in occupied spaces.
- Commercial:Mixed-use towers and office complexes across Riyadh and Jeddah drive specification through engineering consultants, with Saudi Real Estate Refinance Company-financed developers consolidating procurement into master supply agreements.
- Institutional:Healthcare and educational facilities face additional SFDA and Ministry of Municipal and Rural Affairs compliance layers.
- Industrial:Warehouse and logistics coating requirements tied to Saudi Aramco supply chain infrastructure and bonded zone developments.
Procurement scale peaks in Commercial; Institutional segments show the steepest expansion trajectory as healthcare facility construction accelerates.
Application:
Customer type segmentation distinguishes between project-based volume spikes and recurring maintenance revenue streams with divergent margin profiles.
- New Construction:Large-scale developments in NEOM, Red Sea Project, and Riyadh's Qiddiya entertainment zone generate concentrated coating demand with multi-year supply agreements.
- Renovation:Aging stock in Jeddah's established districts requires cyclical refinishing, capturing expanding margin pools through specialized surface preparation and substrate repair services.
- Maintenance:Ongoing protective coating renewal for commercial and institutional portfolios under facility management contracts.
- Decoration:Aesthetic refresh projects in residential and hospitality sectors driven by interior design trends.
Project pipelines concentrate in New Construction; margin stability belongs to Renovation.
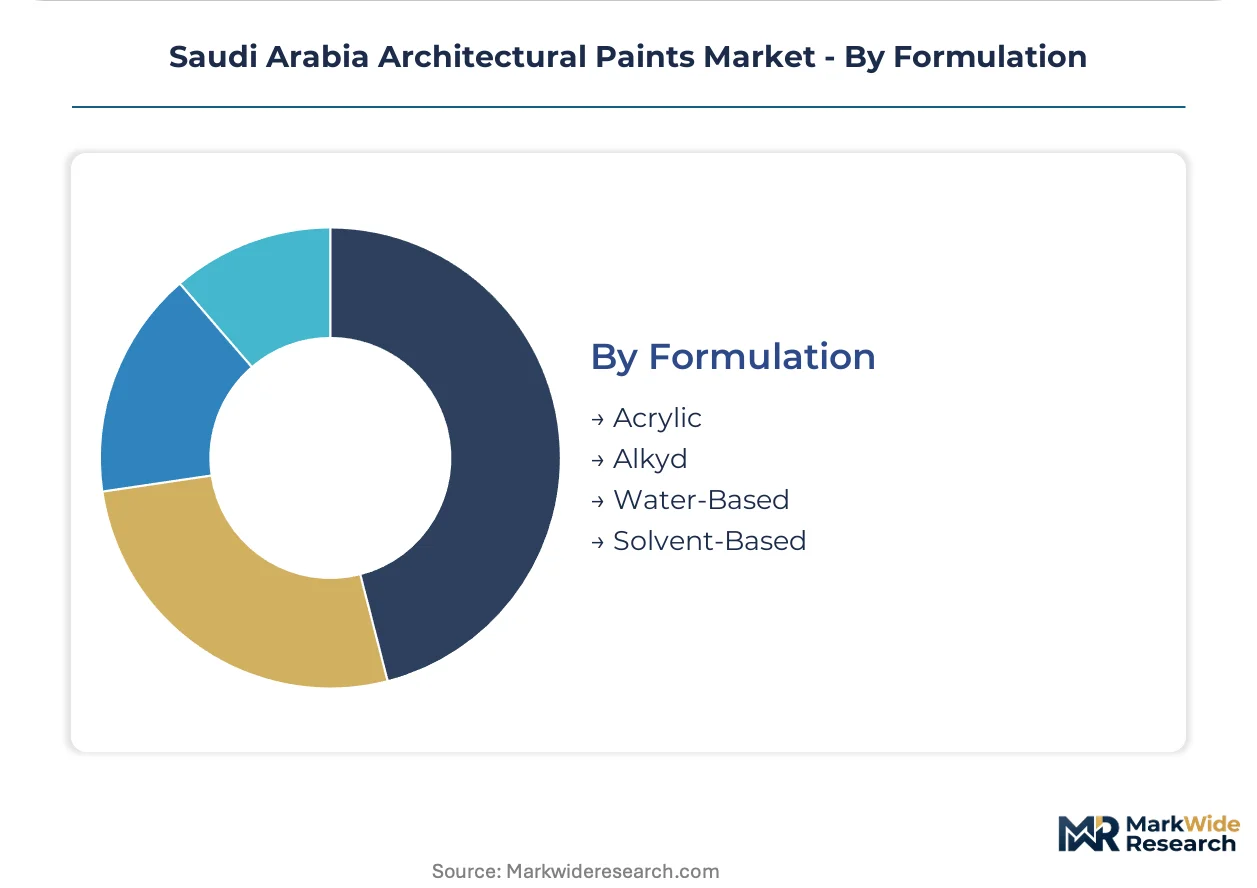
Formulation:
Supply concentration patterns separate domestically manufactured water-based systems from import-dependent specialty chemistries.
- Acrylic:Thermoplastic binder systems offering UV durability and color retention for exterior exposure. Production concentrates in Eastern Province manufacturing corridors with Saudi Aramco petrochemical feedstock integration.
- Alkyd:Oil-modified polyester resins for solvent-based applications in metal substrate protection and traditional wood finishes.
- Water-Based:Emulsion technologies displacing solvent alternatives across interior and exterior segments, constrained by summer ambient temperature degradation exceeding 50°C in Riyadh interior sites.
- Solvent-Based:Declining share under SASO VOC emissions limits, retained for specific industrial and marine applications requiring chemical resistance.
Production volume concentrates in Water-Based; technology investment flows toward Acrylic modification for extreme climate performance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the Kingdom's major urban corridors and emerging megaproject zones, with each sub-region presenting distinct specification environments and procurement dynamics.
Riyadh
Vision 2030 housing delivery targets institutionalize annual coating procurement pipelines across the northern corridor affordable housing zones. The Saudi Building Code amendments for high-rise residential towers drive specification recalculation for fire-resistant assembly systems. Engineering consultants in the capital migrate coating selection to BIM-integrated databases, compressing traditional distributor channels.
Eastern Province
Marine-adjacent commercial and hospitality construction along the Arabian Gulf generates specialized demand for salt-corrosion-resistant exterior formulations. Saudi Aramco petrochemical feedstock integration supports domestic acrylic emulsion manufacturing corridors. Jotun leverages its coastal manufacturing footprint to dominate marine-adjacent architectural projects across Dammam and Al-Khobar clusters.
Western Region
Jeddah's established districts require cyclical refinishing of aging stock, capturing expanding margin pools through specialized surface preparation services. The Red Sea Project and NEOM corridors in Tabuk and Medina provinces offer uncontracted coating demand for first-mover logistics positioning. Low-VOC water-based formulations displace solvent alternatives as contractors prioritize faster recoat times in occupied hospitality spaces.
NEOM Northwest
Tabuk province's linear city development generates concentrated new construction coating demand with multi-year supply agreement potential. The Saudi Green Building Forum's emerging carbon accounting requirements create premium positioning opportunities for low-embodied-carbon formulations. Pre-construction mobilization timelines favor suppliers establishing dedicated logistics hubs ahead of main construction phases.
Saudi Arabia Architectural Paints Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium decorative ranges commanding specification priority in hospitality developments while volume residential programs consolidate procurement through master supply agreements. The market structure tiers across three strategic archetypes: multinational coating majors with coastal manufacturing footprints, domestic producers with deep provincial distribution networks, and regional specialists targeting marine and industrial adjacencies. Competitive moves center on SASO certification pre-positioning and logistics hub establishment ahead of megaproject mobilization.
Within the multinational tier, Jotun and AkzoNobel Saudi Arabia Ltd exemplify coastal manufacturing strategies that align with Eastern Province marine-adjacent demand and Riyadh premium residential specifications. Jazeera Paints anchors the domestic producer archetype through provincial retail network penetration and contractor-direct channel control. These three occupy positions that reflect the market's fundamental split between import-integrated premium positioning and locally manufactured volume scale.
| Leading Market Players |
|---|
| Jotun |
| Jazeera Paints |
| Hempel A/S |
| NATIONAL PAINTS FACTORIES CO. LTD |
| Caparol Paints |
| SIPCO |
| Sigma Paints |
| AkzoNobel Saudi Arabia Ltd |
| Sherwin-Williams Company |
| Others |
Value Network & Pricing Analysis
Formulation chemist scarcity in Riyadh's Eastern Province manufacturing corridors widens labor-cost differentials between multinational coastal plants and domestic provincial facilities, compressing mid-tier margins while premium SASO-certified formulations command spreads exceeding standard water-based acrylics.
Pricing Analysis
Volume placements concentrate in economy-grade water-based interior emulsions for Vision 2030 affordable housing programs, while margin pools concentrate in premium exterior elastomeric systems for Western Province hospitality developments. Price differentiation separates SASO pre-certified assembly documentation from uncertified alternatives, with fire-resistant high-rise specifications commanding premiums. Pricing pressure stems from titanium dioxide feedstock volatility compressing mid-tier producer margins. Individual homeowners through retail networks exhibit highest price sensitivity; Saudi Real Estate Refinance Company-financed developers with master supply agreements show lowest.
Supply Chain Analysis
Titanium dioxide feedstock supply rests on Chinese and Ukrainian mineral processors, while specialty rheology modifiers and biocides draw from German and Japanese chemical manufacturers. Acrylic emulsion production anchors in Eastern Province corridors with Saudi Aramco petrochemical integration. Single-source vulnerability concentrates in European biocide supply for healthcare facility compliance. Distribution runs through Jazeera Paints' provincial retail networks and contractor-direct channels, with Jotun and AkzoNobel bypassing intermediaries via BIM-integrated specification platforms for Riyadh engineering consultants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi Arabia Architectural Paints Market functions as a cost-of-compliance arena where SASO certification timelines extending 8-12 months erect barrier-to-entry moats favoring pre-certified incumbents with dedicated regulatory affairs capacity.
For Market Incumbents: Extend SASO pre-certification pipelines to capture specification priority in tender processes for Riyadh high-rise residential towers. Expand captive titanium dioxide sourcing through Saudi Aramco chemical derivatives contracts to defend margin position against feedstock volatility eroding mid-tier competitors.
For New Entrants and Emerging Players: Engineering consultants in Riyadh represent the most accessible channel partner type for bypassing Jazeera Paints' entrenched retail networks. Target NEOM and Red Sea Project corridors in Tabuk and Medina provinces where uncontracted demand and pre-construction mobilization timelines favor first-mover logistics positioning ahead of main construction phases.
For Investors and Strategic Acquirers: The window for entry favors domestic producers with deep provincial distribution networks and existing SASO certification infrastructure. Watch Saudi Green Building Forum carbon accounting requirement implementation as the signal indicating premium positioning viability for low-embodied-carbon formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| SASO Certification Pre-Positioning | Accelerates specification capture in Riyadh high-rise residential tender processes. |
| Backward Integration into Titanium Dioxide | Secures margin defense against pigment cost volatility through Saudi Aramco feedstock contracts. |
| NEOM Logistics Hub Establishment | Enables first-mover volume capture in Tabuk province linear city construction corridors. |
| BIM-Integrated Specification Platform Development | Bypasses Jazeera Paints' retail network control via direct engineering consultant engagement. |
| Low-Embodied-Carbon Formulation Investment | Aligns product portfolios with Saudi Green Building Forum emerging certification pathways. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving formulation chemists at Eastern Province manufacturing facilities, procurement leads at Saudi Real Estate Refinance Company-financed developers, engineering consultants specifying for Riyadh high-rise towers, and distribution channel partners in Jazeera Paints' provincial retail networks. Bottom-up volume triangulation across water-based acrylic, solvent-based alkyd, and specialty elastomeric formulation segments reconciled with top-down value estimates derived from SASO certification registry analysis and Saudi Building Code amendment tracking.
Data-stream reconciliation across construction phase segmentation, formulation chemistry categories, and regional demand clusters shaped the analytical framework over the projection horizon. Modeled dimensions included interior versus exterior product types, residential-commercial-institutional end-use splits, new construction versus renovation versus maintenance application categories, and water-based versus solvent-based versus acrylic-modified formulation technologies. CAGRs derived from trend-line extrapolation of Vision 2030 housing delivery commitments, adjusted for seasonal work stoppage patterns in Riyadh's extreme heat curing environment.
Caveats apply where SASO standard update cycles, Saudi Green Building Forum carbon accounting implementation timelines, or NEOM construction mobilization delays could materially shift the outlook. A small set of triggers—titanium dioxide supply disruption, biocide import restriction expansion, and BIM specification platform adoption velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Europe Paints and Coatings Market
Paints & Coatings
Paint Defoamers Market
Paints & Coatings
Paint Rollers Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
South Africa Paints and Coatings Market
Paints & Coatings
Automotive Coatings Market
Paints & Coatings
Paint Cans Market
Paints & Coatings
Global Construction Paints and Coatings Market
Paints & Coatings
India Automotive Paints and Coatings Market
Paints & Coatings
Saudi Arabia Paints and Coatings Market
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
Acrylic Paints Market
Paints & Coatings
Water-Soluble Paints Market
Paints & Coatings
Mexico Paints and Coatings Market
Paints & Coatings
Food Grade Epoxy Paint Market
Paints & Coatings
India Automotive OEM Coatings Market