
 Paint Cans Market | 2026-2036
Paint Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Paint Cans Market Outlook
Wholesale distributor networks for paint cans is narrowing as direct-to-contractor platforms gain share. Ball Corporation leverages its aluminum supply chain to sustain North American manufacturing scale. Crown Holdings anchors European demand through tinplate specialization and recycling infrastructure control. BWAY Corporation competes in plastic container segments where light-weighting drives specification changes.
Paint cans are cylindrical metal, fiberboard, or polymer vessels engineered to store and dispense liquid coatings, typically featuring interior linings resistant to solvent attack and exterior treatments preventing corrosion during transport. Steel containers dominate commercial construction procurement due to structural rigidity and compatibility with high-solvent formulations. Plastic alternatives are gaining fastest in furniture manufacturing where lower weights reduce shipping costs and handling injuries. Aluminum segments command premium positioning in marine coatings applications requiring superior salt-water corrosion resistance.
EPA regulations govern volatile organic compound emissions from coating contents, directly influencing liner specifications and venting designs. REACH and RoHS frameworks in Europe restrict heavy metal content in can substrates and surface treatments, compelling material substitutions. OSHA workplace safety standards shape closure mechanisms to prevent spills during industrial handling. Stakeholders must monitor how extended producer responsibility frameworks in multiple jurisdictions will redistribute end-of-life collection costs across material categories.
Market Dynamics
Steel-tinplate supply concentration and REACH-mandated material substitutions are compressing formulation flexibility while forcing liner chemistry reinvention across European and North American manufacturing footprints.
Growth Catalysts
- REACH compliance deadlines:European ECHA enforcement of substance restrictions is accelerating qualified supplier consolidation, favoring can makers with pre-certified substrate portfolios and documented recyclability chains.
- Infrastructure maintenance cycles:Commercial construction procurement of steel containers for protective coatings is intensifying as bridge, pipeline, and industrial facility repaint schedules compress from seven-year to five-year intervals.
- India urban housing stock:Metro expansion in Mumbai, Delhi, and Bangalore is driving decorative paint throughput requiring metal can compatibility with water-based and high-solvent formulations simultaneously.
Market Restraints
- Tinplate input cost volatility:Raw material exposure to steel alloy pricing and Indonesia tin concentrate export quotas is squeezing margin stability for cylindrical metal producers.
- Substitution threat from bag-in-box:Flexible polymer alternatives for industrial maintenance coatings are capturing volume in marine and automotive refinish segments where pour precision matters less than freight density.
- EPA volatile organic compound limits:Emission thresholds for coating contents are restricting high-solvent formulation packaging options, forcing liner redesigns that extend qualification timelines.
Strategic Opportunities
- Extended producer responsibility frameworks:German Verpackungsgesetz and French extended producer responsibility mandates are creating first-mover advantage for can makers with closed-loop collection infrastructure.
- Aluminum-polymer hybrid constructions:Convergence of lightweight aluminum bodies with polymer closure systems is opening marine coating applications requiring salt-water corrosion resistance without steel weight penalties.
- Direct-to-contractor platforms:Digital procurement channels are bypassing traditional wholesale distributor networks, enabling can specifications to be bundled with coating formulations at point-of-sale.
Industry Challenges
- Coating chemist talent scarcity:Formulation expertise bridging solvent compatibility and liner adhesion is concentrating at legacy suppliers, constraining new entrant scale-up.
- Recyclability certification timelines:Multi-jurisdiction validation of steel-tinplate recyclability claims requires 18-24 month documentation cycles that delay premium positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paint Cans Market |
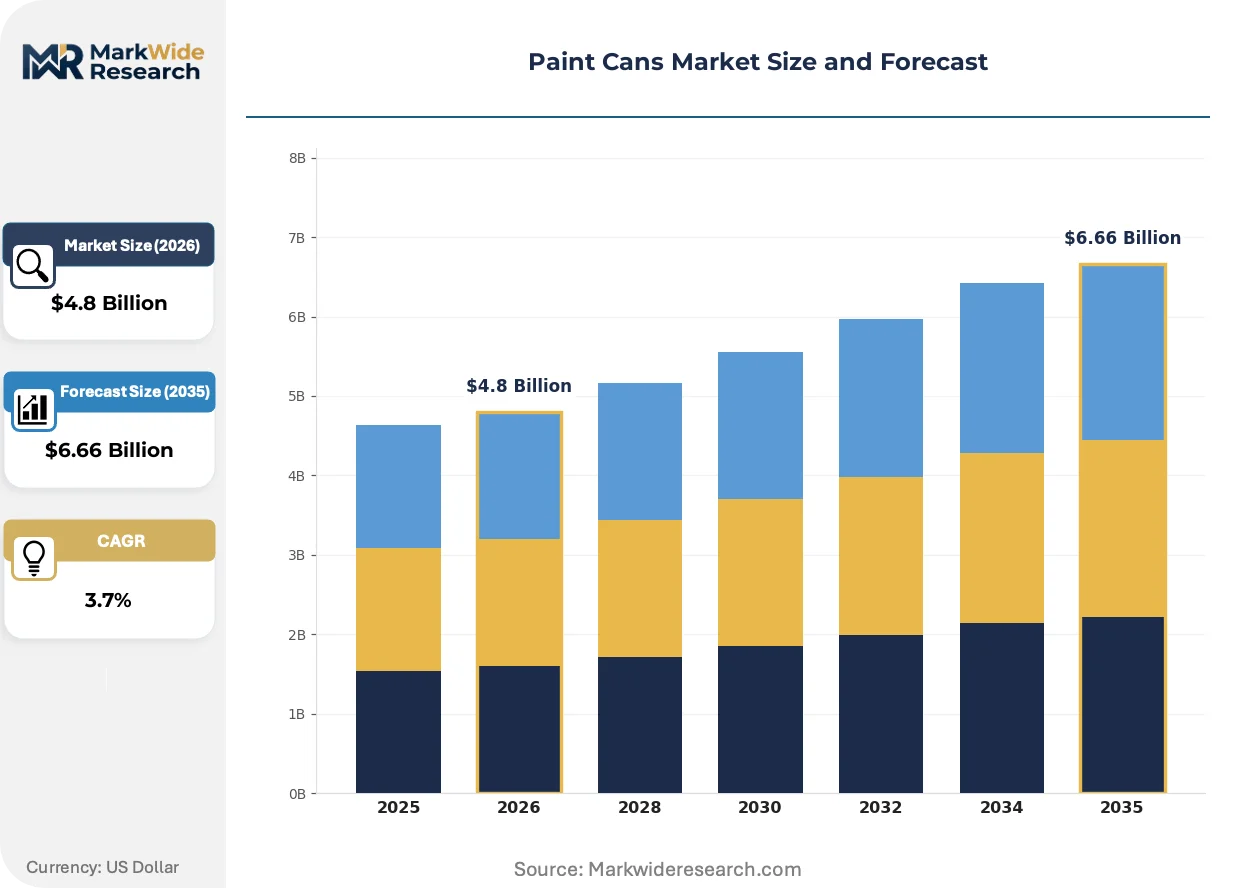
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Tinplate, Aluminum, Plastic, Fiberboard Can Volume: 100 ml, 500 ml, 1 Liter, 5 Liter, 10 Liter End Use Industry: Construction, Furniture Manufacturing, Vehicle Assembly, Marine Coatings Closure Type: Snap-on Lid, Cork, Screw Cap, Sealed Crimp, Lever Lock |
| Companies Covered | Ball Corporation, Crown Holdings, BWAY Corporation, Allied Cans, Silgan Containers, RPC Group, Nippon Closures, Wuxi Huatai Packaging Products, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paint Cans Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are converging to redefine can interior specifications, while procurement digitization is collapsing traditional channel hierarchies in construction supply.
Water-based epoxy liner technologies with zero volatile organic compound emission profiles are rendering obsolete solvent-borne interior coatings in furniture manufacturing and institutional maintenance segments. Tier-one decorative paint brands in Germany and the Netherlands are mandating these specifications for 2025 supplier qualification. The shift is compressing formulation freedom for can makers serving mid-market coating producers.
REACH Annex XVII restrictions on heavy metal content in surface treatments are forcing tinplate substitution trials across European manufacturing. ECHA substance evaluation processes have flagged chromium conversion coatings used in corrosion prevention. Can producers are responding with zirconium-based and silane-based pretreatment chemistries that require requalification with major coating houses.
Construction contractor buying collectives are consolidating purchase authority previously dispersed across regional distributors. Large maintenance firms in Texas, Florida, and California are negotiating direct container supply agreements that bundle steel can volumes with liner specification guarantees. This disintermediation is compressing distributor margins while rewarding can makers with logistics scale and formulation flexibility.
Paint Cans Market Segmentation
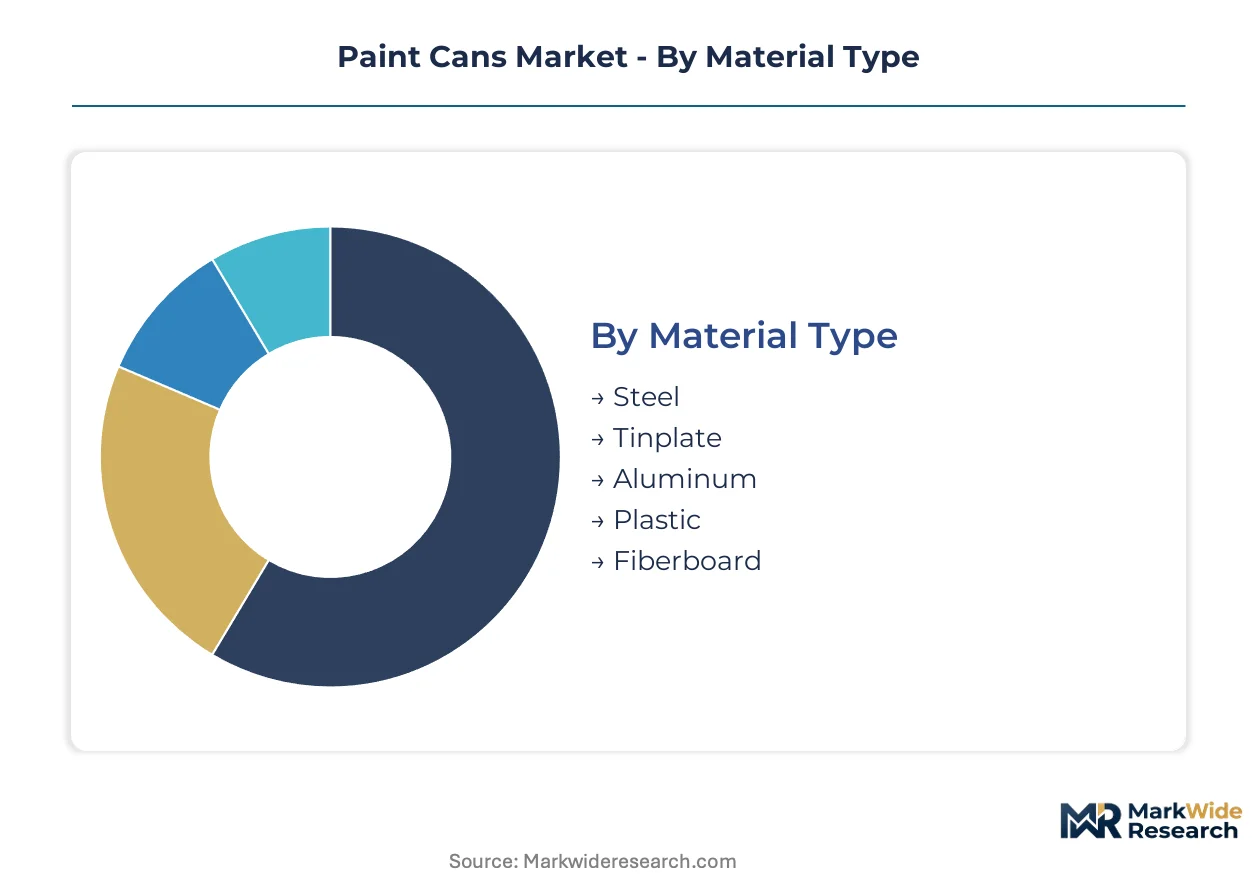
Paint can segmentation reveals divergent procurement cycles across material grades and end-use applications. Specification requirements vary sharply between infrastructure maintenance contracts and furniture manufacturing runs. Understanding these turnover patterns enables suppliers to align inventory positioning with demand velocity.
Material Type:
Steel and tinplate containers turn over on five-to-seven-year infrastructure repaint cycles, while plastic alternatives refresh annually with furniture production schedules. Aluminum segments rotate on marine dry-docking timelines.
- Steel:Cold-rolled carbon steel construction delivers structural rigidity for high-solvent protective coatings. Bridge and pipeline maintenance contractors in Texas and Florida specify steel for compatibility with epoxy formulations. REACH Annex XVII compliance deadlines are forcing substrate certification renewals.
- Tinplate:Electrolytic tin coating over steel substrate provides corrosion resistance for water-based decorative paints. Metro housing stock expansion in Mumbai and Delhi is accelerating throughput for 1-liter and 5-liter decorative formats. Indonesia tin concentrate export quotas are squeezing input cost stability.
- Aluminum:Lightweight alloy construction with superior salt-water corrosion resistance for marine topcoat applications.
- Plastic:Polymer vessels reduce shipping weights and handling injuries in furniture manufacturing supply chains.
- Fiberboard:Compressed paperboard containers serve low-volume specialty coating samples and architectural color matching.
Steel anchors the volume base while plastic gains share at the steepest rate.
Can Volume:
Cost tier positioning separates institutional bulk procurement from retail consumer formats. Volume selection directly determines liner specification complexity and closure mechanism investment.
- 100 ml:Sample-size containers for architectural color matching and touch-up applications. Design studios in Bangalore and contractor buying collectives in California specify these for formulation testing before volume commitment.
- 500 ml:Retail consumer format for residential touch-up and small repair jobs. Home improvement chains in Germany are bundling these with water-based epoxy liner specifications for 2025 supplier qualification.
- 1 Liter:Standard decorative paint unit balancing handling ergonomics with coverage economics.
- 5 Liter:Professional contractor format for room-scale residential and light commercial applications.
- 10 Liter:Bulk institutional container for industrial maintenance and protective coating contracts.
Five-liter formats dominate contractor procurement value while one-liter SKUs expand most quickly in urban housing markets.
End Use Industry:
Application environment dictates liner chemistry requirements and exterior durability specifications. Marine salt exposure demands fundamentally different material performance than controlled factory conditions.
- Construction:Protective coatings for commercial infrastructure including bridges, pipelines, and industrial facilities. Five-year maintenance interval compression from seven-year cycles is intensifying steel container demand in Texas and Florida. EPA volatile organic compound limits are restricting high-solvent formulation options.
- Furniture Manufacturing:Water-based and solvent-borne finishes for wood and metal substrate coating. Plastic container adoption is climbing fastest here as weight reduction cuts freight density and warehouse handling injuries. German and Dutch brands are mandating zero-VOC liner specifications.
- Vehicle Assembly:Automotive OEM and refinish coatings requiring precise color matching and batch consistency.
- Marine Coatings:Salt-water resistant topcoats and antifouling formulations for commercial and recreational vessels.
Construction anchors the volume base while furniture manufacturing drives material substitution fastest.
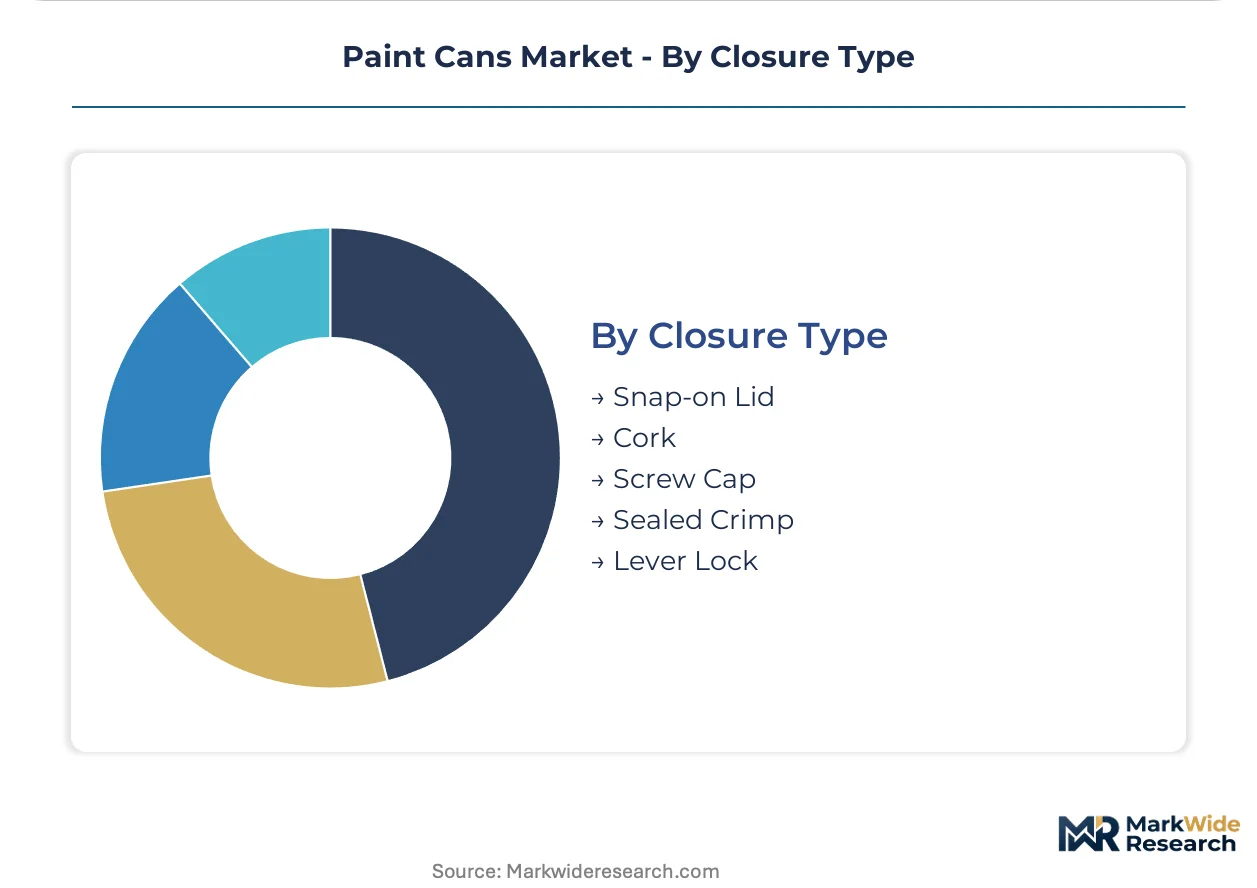
Closure Type:
Customer type and handling intensity determine sealing mechanism selection. Industrial contracts prioritize spill prevention during transport and storage.
- Snap-on Lid:Press-fit polymer closure for consumer retail formats requiring single-use access. Furniture manufacturing distributors in the Netherlands favor these for water-based coating compatibility.
- Cork:Traditional tapered stopper for specialty solvent formulations and heritage product positioning.
- Screw Cap:Threaded metal or polymer closure enabling resealability for multi-session residential applications.
- Sealed Crimp:Permanent metal closure for high-solvent industrial coatings requiring transport security. OSHA workplace safety standards are shaping these specifications for spill prevention.
- Lever Lock:Mechanical latch mechanism for rapid access in high-frequency maintenance environments.
Sealed crimp anchors industrial volume while snap-on lid configurations climb fastest in retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extended producer responsibility mandates in Germany and France are redistributing end-of-life collection costs across material categories. This regulatory momentum is accelerating qualified supplier consolidation in Europe while India and the United States scale infrastructure-driven procurement.
United States
Bridge and pipeline maintenance contractors in Texas and Florida are compressing repaint schedules from seven-year to five-year intervals. EPA volatile organic compound limits are restricting high-solvent formulation packaging options and forcing liner redesigns. Construction contractor buying collectives in California are negotiating direct container supply agreements that bundle steel can volumes with specification guarantees.
Germany
Verpackungsgesetz mandates are creating first-mover advantage for can makers with closed-loop collection infrastructure. ECHA enforcement of REACH Annex XVII substance restrictions is accelerating qualified supplier consolidation. Tier-one decorative paint brands in the Netherlands and Germany are mandating zero-VOC water-based epoxy liner specifications for 2025 supplier qualification.
India
Metro expansion in Mumbai, Delhi, and Bangalore is driving decorative paint throughput requiring metal can compatibility with water-based and high-solvent formulations simultaneously. BIS certification requirements are tightening specifications for chemical compatibility and recyclability. Urban housing stock growth in Maharashtra and Karnataka is accelerating 1-liter and 5-liter decorative format demand.
China
Furniture manufacturing clusters in the Pearl River Delta are shifting toward plastic container adoption to reduce shipping weights and handling injuries. GB standards for packaging recyclability are compelling material substitutions in surface treatments. Yangtze River Delta coating producers are trialing aluminum-polymer hybrid constructions for export-oriented marine coating applications.
Japan
METI industrial standards are shaping closure mechanisms to prevent spills during industrial handling. Automotive OEM coating requirements in the Chubu and Kansai regions demand precise color matching and batch consistency. JIS-compliant can producers are concentrating formulation expertise to bridge solvent compatibility and liner adhesion specifications.
Paint Cans Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers differentiated by material specialization and geographic footprint. Metal packaging specialists with captive aluminum and tinplate supply chains occupy the premium tier. Plastic container fabricators with light-weighting capabilities capture mid-market furniture manufacturing demand. Regional metal-forming specialists serve infrastructure maintenance contractors with customized liner specifications. Dominant competitive moves include backward integration into raw material supply and direct-to-contractor platform development.
Among North American metal packaging specialists, Ball Corporation and Crown Holdings exemplify the premium-tier archetype through aluminum and tinplate specialization respectively. BWAY Corporation occupies a distinct position within plastic container segments where weight reduction drives specification changes. These three anchors represent the material-based stratification reshaping procurement relationships across construction and manufacturing end uses.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings |
| BWAY Corporation |
| Allied Cans |
| Silgan Containers |
| RPC Group |
| Nippon Closures |
| Wuxi Huatai Packaging Products |
| PPG Industries |
| Others |
Value Chain & Pricing Dynamics
Indonesia tin concentrate export quotas and steel alloy pricing volatility concentrate margin pressure at tinplate substrate producers, forcing downstream can makers to absorb input cost swings or pass through to infrastructure maintenance contractors with limited pricing power.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aluminum marine coating containers from steel infrastructure cans and plastic furniture manufacturing formats. Price differentiation hinges on REACH certification status and volume scale, with bulk procurement by Texas and Florida maintenance contractors commanding steepest discounts. Pricing pressure stems from bag-in-box substitution in industrial segments, compressing steel can margins. Furniture manufacturing distributors in the Netherlands exhibit highest price sensitivity, while marine coating applicators in premium aluminum segments show least elasticity.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard as can makers finance working capital for European and North American distributor networks. Raw material sourcing draws from Indonesia for tin concentrate, China for cold-rolled steel substrate, and domestic North American smelters for aluminum alloy. Supply chain risk centers on Indonesia tin export quota volatility disrupting tinplate production schedules. Distribution runs through direct-to-contractor platforms in California and Texas alongside traditional wholesale networks in Germany and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paint can demand sits at early-cycle expansion as infrastructure maintenance interval compression and India urban housing stock growth accelerate container throughput ahead of replacement saturation.
For Market Incumbents: Harden REACH-compliant substrate certification portfolios to defend against European supplier consolidation. Deepen backward integration into aluminum smelting capacity to offset tinplate cost volatility. Secure closed-loop collection infrastructure in Germany under Verpackungsgesetz mandates to capture extended producer responsibility premiums. For New Entrants and Emerging Players: Pursue plastic container white-space in furniture manufacturing clusters across China's Pearl River Delta and Vietnam's emerging coatings export bases. Target water-based epoxy liner qualification for German and Dutch decorative paint brands as fastest-penetrable specification tier. Lead with direct-to-contractor digital procurement platforms bypassing entrenched wholesale distributor networks. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap metal-forming specialists with captive tinplate supply agreements and documented recyclability chains. Long-term viability over a 5-10 year horizon rests on regulatory compliance infrastructure rather than commodity scale. Monitor ECHA substance evaluation timelines for chromium conversion coating restrictions as inflection signal for zirconium-based pretreatment chemistry adoption.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Substrate Certification | ECHA enforcement deadlines in Europe are accelerating qualified supplier consolidation favoring pre-certified portfolios. |
| Closed-Loop Collection Infrastructure | German Verpackungsgesetz and French extended producer responsibility mandates redistribute end-of-life costs across material categories. |
| Water-Based Epoxy Liner Investment | Zero-VOC specifications from tier-one German and Dutch decorative paint brands compress formulation freedom for mid-market producers. |
| Direct-to-Contractor Platform Development | Digital procurement channels in Texas and California bypass wholesale distributors to bundle can specifications with coating formulations. |
| Aluminum-Polymer Hybrid Construction | Marine coating applications in salt-water environments demand lightweight corrosion resistance without steel weight penalties. |
Study Parameters
Desk research of trade association publications, customs filings, and regulatory databases preceded structured interviews with can manufacturing plant managers, coating procurement leads at infrastructure maintenance contractors, distribution channel partners, and ECHA compliance officers. Primary fieldwork with steel and tinplate substrate suppliers validated secondary estimates of input cost structures and qualification timelines. Bottom-up volume modeling across material grades, can volumes, and end-use applications triangulated against top-down market sizing from construction spending and coatings production data.
Assumptions held fixed include REACH Annex XVII enforcement timelines and EPA volatile organic compound threshold maintenance, while variables included India urban housing completion rates and Indonesia tin export quota fluctuations. Segmentation dimensions encompassed material type, can volume tier, end-use industry, and closure mechanism across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating infrastructure maintenance cycle compression and furniture manufacturing plastic substitution rates. Industry-specific inputs included BIS certification timelines for Indian market entry and ECHA substance evaluation flags for surface treatment chemistry transitions.
Sensitivities concentrate around regulatory enforcement intensity in Europe, tin concentrate export policy shifts in Indonesia, and infrastructure spending authorization cycles in the United States. Forecasts reflect documented assumptions on coating formulation evolution and liner chemistry qualification timelines. Macroeconomic contraction in construction activity, accelerated REACH substance restrictions, or breakthrough flexible packaging technologies for high-solvent coatings would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
South Africa Paints and Coatings Market
Paints & Coatings
Paint and Coating Stripper Market
Paints & Coatings
Paints and Coatings Additives Market
Paints & Coatings
Water-Soluble Paints Market
Paints & Coatings
Paint Rollers Market
Paints & Coatings
Nordic Countries Architectural Coatings Market
Paints & Coatings
South America Paints and Coatings Additives Market
Paints & Coatings
Global Decorative Paints and Coatings Market
Paints & Coatings
Canvas Primer Market
Paints & Coatings
Global Wood Coatings Market
Paints & Coatings
Decorative Paints Market
Paints & Coatings
Germany Industrial Wood Coatings Market
Paints & Coatings
South America Architectural Coatings Market
Paints & Coatings
Iraq Paints and Coatings Market
Paints & Coatings
India Floor Coatings Market
Paints & Coatings
United Arab Emirates (UAE) Paints and Coatings Market