
 Nano Composite Zirconia Market | 2026-2036
Nano Composite Zirconia Market Size, Share, and Industry Trends Forecast 2026-2036
Nano Composite Zirconia Market Intelligence
Buyer concentration among dental clinic chains and orthopedic device OEMs is realigning procurement volumes toward fewer, larger contracts with certified suppliers. Tosoh Corporation leverages its integrated zirconia powder-to-block manufacturing to secure multi-year supply agreements with Japanese dental laboratories. Saint-Gobain ZirPro anchors European demand through its specialized yttria-stabilized formulations for hip implant manufacturers. H.C. Starck competes in the electronics segment with high-purity powders tailored for oxygen sensor substrates.
Nano composite zirconia refers to engineered ceramic matrices where zirconium dioxide nanoparticles, typically stabilized with yttria or ceria in the 3-5 mol% range, are dispersed within a secondary phase to achieve fracture toughness exceeding 10 MPa·m½ and translucency above 40% at 1 mm thickness. Sintering at 1350-1450°C produces fully dense bodies for load-bearing dental crowns and femoral heads. Dental applications dominate current volume, with zirconia blocks for CAD/CAM milling representing the most mature margin pool, while aerospace coatings for thermal barrier protection on turbine blades represent the fastest-growing structural opportunity. Electronics applications in solid oxide fuel cell electrolytes occupy a specialized niche where conductivity specifications command premium positioning.
FDA 510(k) clearance pathways shape biomedical zirconia market access in the United States, while EU MDR and REACH compliance in Europe enforce biocompatibility and chemical purity standards for implantable grades. ISO 13356 specifies the crystalline phase content and mechanical property thresholds that manufacturers must certify for surgical implant applications. Stakeholders must monitor evolving regulatory divergence between FDA and EU MDR testing protocols, as dual-certification costs will increasingly determine which suppliers can serve both markets without redundant clinical validation.
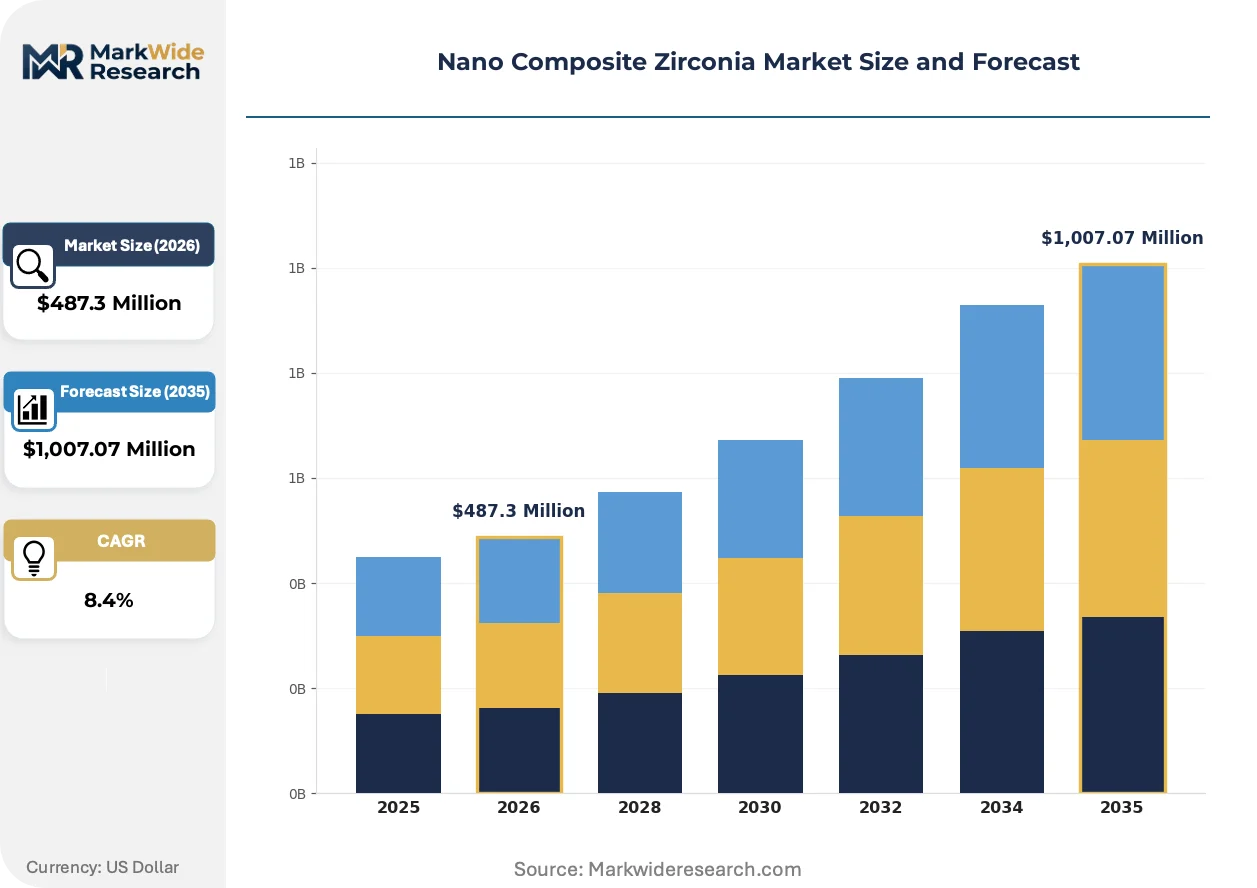
Market Dynamics
Dental clinic chains and orthopedic OEMs are consolidating procurement around certified suppliers capable of dual FDA-EU MDR compliance, compressing vendor pools while amplifying contract values for integrated powder-to-block manufacturers.
Growth Catalysts
- CAD/CAM Dental Milling:Chairside digital workflows in German and Japanese dental laboratories are pulling high-translucency zirconia blocks through validated supply chains anchored by domestic ceramic producers.
- EU MDR Biocompatibility Mandates:Implantable-grade zirconia must now meet ISO 13356 crystalline phase thresholds and REACH purity specifications, filtering out uncertified competitors and concentrating volume with compliant suppliers.
- Solid Oxide Fuel Cell Electrolytes:Stationary power generation deployments in South Korea and Japan are creating specialized demand for yttria-stabilized zirconia thin films with ionic conductivity above 0.1 S/cm at operating temperature.
Market Restraints
- Yttria Supply Concentration:Rare earth stabilization chemistry depends on Chinese yttrium oxide refining capacity, exposing non-integrated ceramic producers to input cost volatility and export quota uncertainty.
- Sintering Energy Intensity:Dense ceramic body formation requires sustained furnace temperatures above 1350°C, locking producers into natural gas-dependent cost structures vulnerable to European carbon pricing mechanisms.
- Polymer Infiltration Ceramics:Hybrid composite materials combining zirconia nanoparticles with resin matrices are displacing monolithic zirconia in provisional crown applications where fracture toughness requirements are relaxed.
Strategic Opportunities
- Aerospace Thermal Barrier Coatings:Plasma-sprayed nano-zirconia topcoats for turbine blade protection represent an underpenetrated structural application where service temperature requirements exceed 1200°C.
- Japanese Dental Tourism Channel:Osaka and Tokyo dental laboratories serving inbound medical tourists are sourcing premium translucency blocks through direct manufacturer relationships, bypassing traditional distributor markups.
- US IRA Clean Energy Manufacturing:Domestic production incentives for solid oxide fuel cell components are creating localized demand for electrolyte-grade zirconia powders with certified traceability.
Industry Challenges
- Dual Certification Timelines:Simultaneous FDA 510(k) and EU MDR technical documentation preparation extends market entry cycles by 18-24 months for biomedical-grade product lines.
- Sintering Furnace Capacity Constraints:Batch processing limitations and skilled kiln operator scarcity are throttling output expansion for dental block producers facing concentrated contract volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano Composite Zirconia Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,007.07 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental, Ceramics, Coatings, Implants Application: Medical Devices, Orthopedics, Electronics, Aerospace End User: Hospitals, Research Institutions, Dental Clinics, Manufacturers Technology: 3D Printing, Sintering, Machining, Laser Processing |
| Companies Covered | Kyocera Fineceramics, Showa Denko, Tosoh Corporation, H.C. Starck, Solvay, Saint-Gobain ZirPro, CeramTec, Zircomet, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano Composite Zirconia Market Strategic Shifts & Innovations
Process intensification in powder synthesis and regulatory harmonization pressures are compressing development cycles while fragmenting competitive advantage between integrated manufacturers and specialized application developers.
Laser-assisted sintering of yttria-stabilized tetragonal zirconia polycrystal is rewriting densification economics by reducing furnace residence time from 8 hours to 90 minutes without compromising translucency. German dental block producers are piloting this thermal profile for next-generation high-strength formulations. The compressed processing window is enabling same-day crown fabrication workflows that bypass traditional laboratory outsourcing.
REACH Annex XVII restrictions on nanoparticle environmental release are forcing European zirconia powder producers to retrofit wet-chemical synthesis lines with closed-loop solvent recovery systems. The compliance investment is bifurcating the supplier base between capitalized integrated manufacturers and toll-processing dependent competitors. Biomedical-grade powder certification now requires documented life-cycle assessment data under the EU Green Deal sustainable chemistry framework.
Direct-to-laboratory digital procurement platforms are displacing regional dental distributor networks in Japan and Germany. Tosoh Corporation and Kyocera Fineceramics have established authenticated B2B portals where certified laboratories order calibrated zirconia blocks with embedded material property certificates. The channel shift is compressing price transparency and locking in volume commitments through subscription replenishment models.
Nano Composite Zirconia Market Segmentation
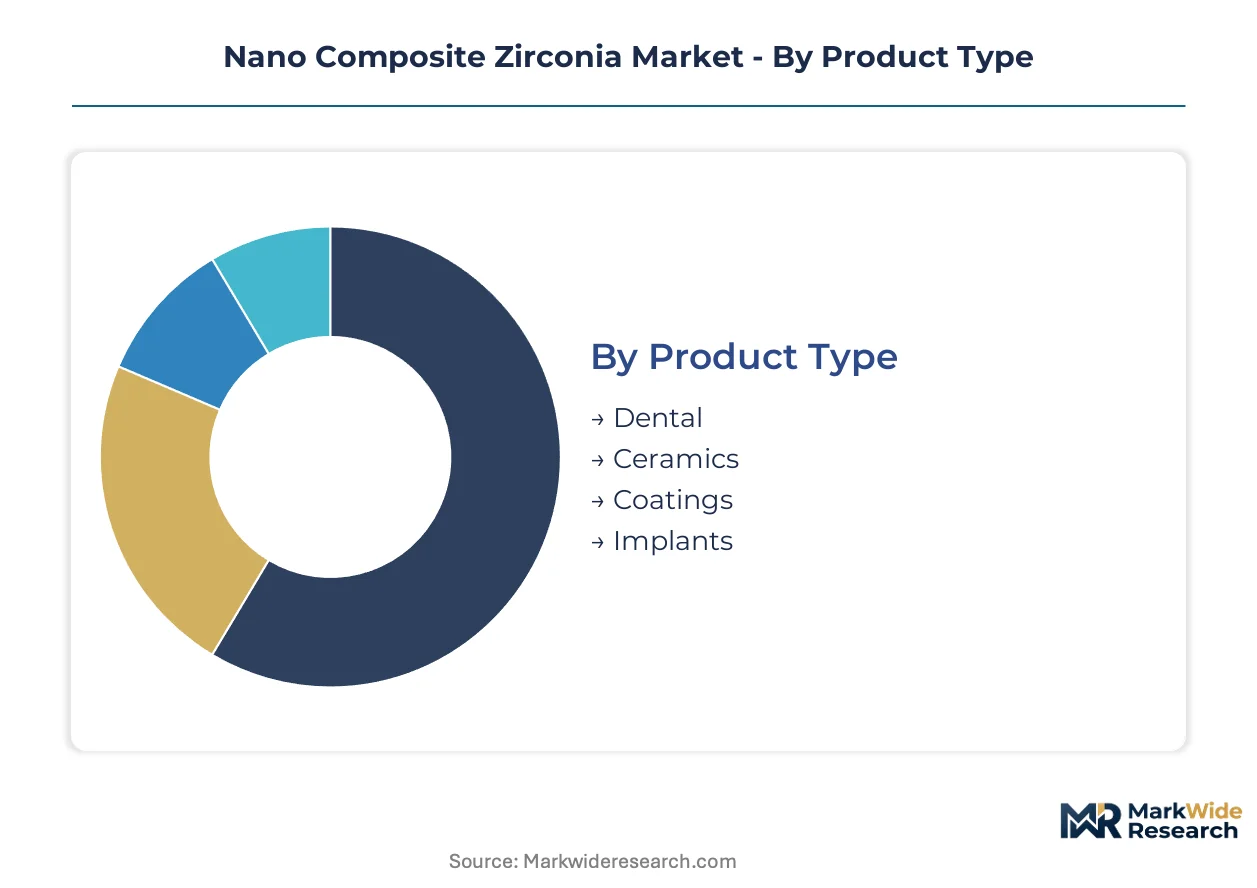
Segmentation in nano composite zirconia separates margin pools by certification intensity, thermal processing requirements, and end-use liability exposure. Each category carries distinct supply chain configurations and regulatory validation burdens.
Product Type:
Supply concentration clusters around powder-to-block integrated producers capable of ISO 13356 certification and REACH-compliant traceability.
- Dental:High-translucency yttria-stabilized tetragonal zirconia polycrystal blocks for CAD/CAM milling dominate current procurement volumes. German and Japanese dental laboratories are consolidating orders around domestic manufacturers with validated furnace traceability and embedded material certificates.
- Implants:Biomedical-grade formulations for femoral heads and dental screws require dual FDA-EU MDR compliance and documented crystalline phase stability. Orthopedic OEMs in the United States and Europe are compressing vendor pools to three certified suppliers per contract.
- Ceramics:Structural components for wear-resistant industrial applications.
- Coatings:Plasma-sprayed thermal barrier formulations for turbine blade protection.
Today's leader: Dental. Tomorrow's challenger: Implants.
Application:
Cost tier stratification separates premium biomedical grades from standard industrial formulations, with certification overhead driving 3-4x price multiples.
- Medical Devices:Surgical instruments and diagnostic components utilizing zirconia for chemical inertness and sterilization durability. FDA 510(k) pathways govern market access in the United States, while EU MDR technical documentation requirements extend validation cycles.
- Orthopedics:Load-bearing hip and knee implants represent the highest certification barrier segment. Saint-Gobain ZirPro and specialized Japanese ceramic houses anchor supply through multi-year contracts with device OEMs.
- Electronics:Solid oxide fuel cell electrolytes and oxygen sensor substrates.
- Aerospace:Thermal barrier coatings for gas turbine hot section components.
Orthopedics commands premium positioning. Electronics is climbing fastest on clean energy manufacturing incentives.
End User:
Customer type determines procurement channel structure, with direct manufacturer relationships displacing distributor networks among high-volume buyers.
- Dental Clinics:Chairside milling adoption in German and Japanese practices is pulling blocks through authenticated B2B portals with subscription replenishment models. Tosoh Corporation and Kyocera Fineceramics have established direct laboratory channels bypassing traditional markups.
- Manufacturers:Orthopedic device OEMs and electronics fabricators represent concentrated contract values with stringent supplier qualification protocols. Multi-year agreements with integrated powder-to-block producers are becoming standard.
- Hospitals:Centralized procurement of implantable devices through group purchasing organizations.
- Research Institutions:Specialized small-batch orders for prototype development and clinical validation studies.
Manufacturers capture contract scale. Dental clinics are gaining procurement sophistication fastest.
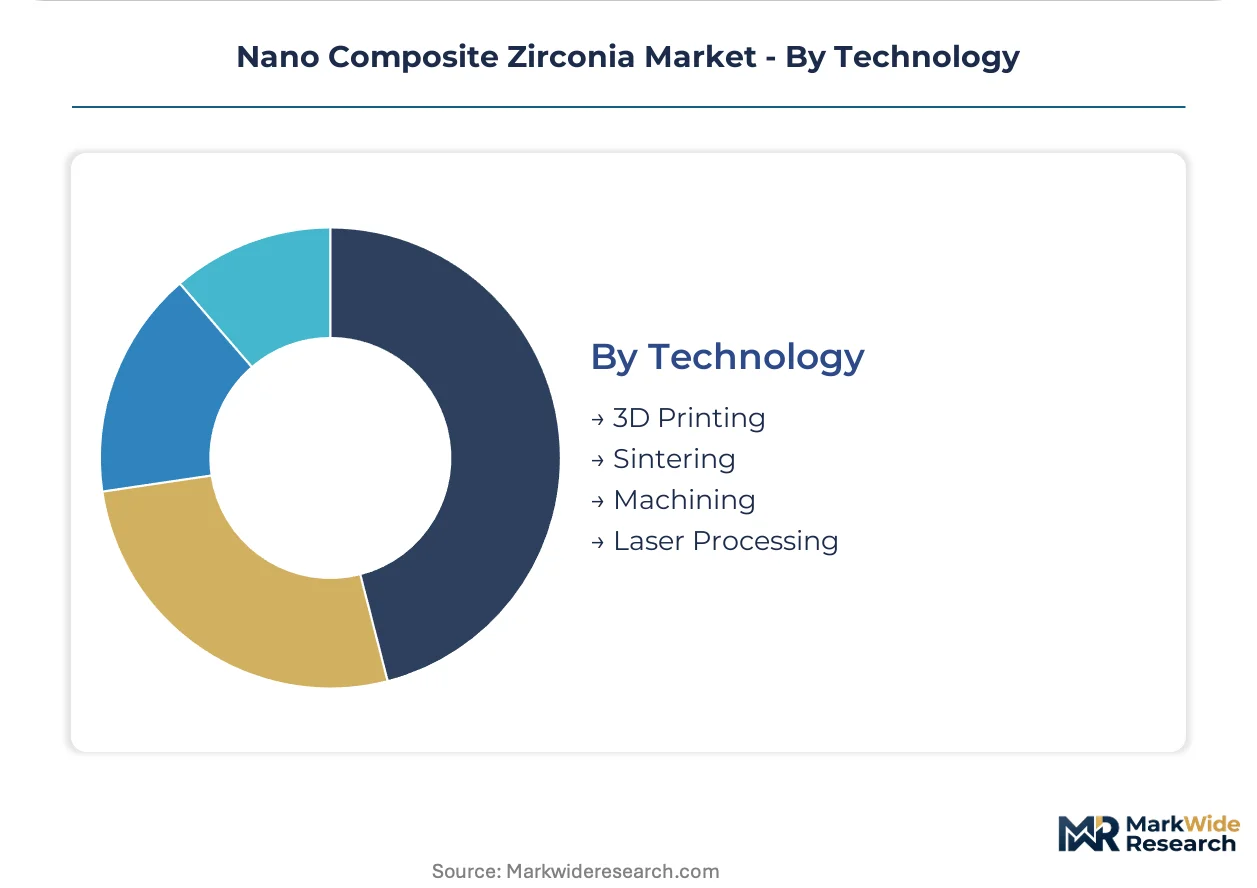
Technology:
Processing maturity separates established furnace-dependent methods from emerging laser-assisted alternatives compressing cycle times.
- Sintering:Conventional high-temperature densification at 1350-1450°C remains the volume foundation for dental blocks and structural ceramics. Batch furnace capacity constraints and skilled operator scarcity are throttling expansion for producers facing concentrated contract volumes.
- Laser Processing:Laser-assisted sintering reduces furnace residence from 8 hours to 90 minutes without translucency compromise. German dental block producers are piloting this thermal profile for same-day crown fabrication workflows.
- 3D Printing:Additive manufacturing of complex geometries for patient-specific implants.
- Machining:Subtractive finishing of pre-sintered blanks to final dimensions.
Sintering holds volume dominance. Laser processing shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dental laboratories source high-translucency zirconia blocks through domestic supply chains, while Japanese manufacturers anchor Asia-Pacific demand with integrated powder-to-block production. Regulatory divergence between FDA and EU MDR compliance timelines is reshaping procurement patterns across major markets.
United States
Orthopedic device OEMs in Massachusetts and Indiana are consolidating vendor pools around dual-certified suppliers. FDA 510(k) clearance pathways govern biomedical zirconia market access, with IRA clean energy manufacturing incentives creating localized demand for electrolyte-grade powders. Greater Boston clusters anchor solid oxide fuel cell component fabrication.
Germany
Dental clinic chains across Bavaria and North Rhine-Westphalia are expanding CAD/CAM milling capacity for chairside crown fabrication. REACH Annex XVII restrictions on nanoparticle environmental release are forcing powder producers to retrofit synthesis lines with closed-loop solvent recovery. Stuttgart industrial corridors host specialized furnace operators serving laboratory networks.
Japan
Domestic ceramic houses anchor supply chains for high-translucency dental blocks serving Osaka and Tokyo medical tourism channels. METI industrial standards shape quality specifications for implantable grades. Nagoya manufacturing clusters concentrate yttria-stabilized formulation expertise for aerospace thermal barrier applications.
South Korea
Stationary power generation deployments are creating specialized demand for yttria-stabilized zirconia thin films with ionic conductivity specifications. The country's national energy regulator oversees grid-connected fuel cell installations. Busan-Ulsan industrial complexes host electrolyte fabrication facilities supplying regional clean energy projects.
China
Rare earth refining capacity concentrates yttrium oxide supply for stabilization chemistry, exposing non-integrated ceramic producers to export quota uncertainty. GB standards govern industrial-grade powder specifications. Yangtze River Delta manufacturing hubs process raw zirconia for dental and electronics applications.
Nano Composite Zirconia Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into three strategic archetypes: integrated powder-to-block manufacturers with furnace traceability, specialized ceramic formulators serving biomedical grades, and rare earth refiners controlling stabilization chemistry inputs. Dominant competitive moves include backward integration into yttria supply and geographic expansion through authenticated B2B procurement portals.
Within the integrated manufacturing tier, Tosoh Corporation and Kyocera Fineceramics exemplify Japanese pure-play specialists with captive powder synthesis and block densification capabilities. Saint-Gobain ZirPro occupies a position among European diversified materials conglomerates with specialized yttria-stabilized formulations. H.C. Starck GmbH represents German chemical processors competing in high-purity powder segments.
| Leading Market Players |
|---|
| Kyocera Fineceramics |
| Showa Denko |
| Tosoh Corporation |
| H.C. Starck |
| Solvay |
| Saint-Gobain ZirPro |
| CeramTec |
| Zircomet |
| 3M |
| Others |
Cost & Logistics Intelligence
Dental clinic chains and orthopedic OEMs concentrate procurement volumes around fewer certified suppliers, compressing vendor pools while amplifying contract values for integrated powder-to-block manufacturers with dual FDA-EU MDR compliance.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for high-translucency dental blocks as laser-assisted sintering reduces furnace residence times. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13356-certified implant grades from industrial formulations, with certification overhead driving three-to-four-fold multiples. Price erosion runs through provisional crown applications where polymer infiltration ceramics displace monolithic zirconia. Dental laboratories show highest price sensitivity, while orthopedic OEMs prioritize supply security over unit cost.
Supply Chain Analysis
Freight costs for yttrium oxide feedstock from Chinese refining centers expose European ceramic producers to input volatility and export quota uncertainty. Supply concentrates in Japan, Germany, and China, with Japanese domestic houses anchoring high-translucency block production. Raw material dependencies center on yttria stabilization chemistry, zircon sand feedstock, and specialized furnace refractories. Single-source vulnerability in rare earth refining creates structural risk. Distribution runs through authenticated B2B portals displacing traditional dental distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU MDR biocompatibility mandates and REACH purity specifications filter uncertified competitors while concentrating volume with compliant suppliers.
For Market Incumbents: Anticipate polymer infiltration ceramic substitution in provisional applications by accelerating laser-assisted sintering deployment for same-day crown workflows. Defend margin position through backward integration into yttria supply and multi-year orthopedic OEM contracts locking in dual-certified volumes. For New Entrants and Emerging Players: Capture white space in aerospace thermal barrier coatings where plasma-sprayed nano-zirconia topcoats remain underpenetrated. Target South Korean solid oxide fuel cell electrolyte demand with certified traceability for IRA-linked domestic production incentives. For Investors and Strategic Acquirers: Diversified materials conglomerates are the most active acquirer in this space, seeking powder-to-block integration capabilities. Long-term viability hinges on furnace traceability and REACH-compliant synthesis infrastructure. Watch Japanese dental tourism channel expansion as inflection indicator for premium translucency block demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yttria Supply | Secures stabilization chemistry inputs against Chinese export quota volatility. |
| Laser-Assisted Sintering Deployment | Enables German dental producers to compress crown fabrication from hours to minutes. |
| Dual FDA-EU MDR Certification Investment | Unlocks orthopedic OEM vendor pools compressing to three certified suppliers per contract. |
| Authenticated B2B Portal Launch | Allows Japanese ceramic houses to bypass distributor markups in dental tourism channels. |
| REACH-Compliant Synthesis Retrofit | European powder producers install closed-loop solvent recovery to meet Annex XVII restrictions. |
Research Approach
Direct dialogue with dental laboratory directors, orthopedic device procurement managers, ceramic plant engineers, and solid oxide fuel cell developers grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation, METI industrial standards, and REACH compliance registries. Bottom-up and top-down triangulation cross-checked powder production capacities against end-use consumption patterns.
Bottom-up modeling aggregated segment-level volume and value trajectories across product type, application, end user, and technology dimensions throughout the forecast period. Top-down macroeconomic anchors incorporated industrial ceramics demand indices, dental equipment installation rates, and clean energy manufacturing incentive flows. CAGRs derived from fitted growth curves calibrated to historical certification timelines and sintering capacity expansion cycles.
Underlying measurement precision varies by segment; dental block volumes carry tighter precision than emerging aerospace coating applications. Forecasts reflect assumptions about regulatory harmonization progress and rare earth supply continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
United States Gold Nanoparticles Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Nanoparticle Analysis Market
Nanomaterials
Polymeric Nanoparticles Market
Nanomaterials
Nanocellulose Market
Nanomaterials
Molybdenum Trioxide Nanopowder Market
Nanomaterials
Carbon Nanotubes (Cnts) Market
Nanomaterials
Aluminium Oxide Nanoparticles Market
Nanomaterials
Global Nanosilica Market
Nanomaterials
Global Nanoclay Market
Nanomaterials
Global Nanocrystalline Cellulose Market
Nanomaterials
Nano Copper Oxide Market
Nanomaterials
Graphene Nanocomposites Market
Nanomaterials
Global Carbon Nanomaterials Market
Nanomaterials
Nanocellulose Materials Market
Nanomaterials
Nanotubes Market