
 Graphene Nanocomposites Market | 2026-2036
Graphene Nanocomposites Market Size, Share, and Industry Trends Forecast 2026-2036
Graphene Nanocomposites Market Intelligence
The distinction between high-purity, functionalized graphene for electronics and lower-grade graphene nanoplatelets for bulk composites is hardening. Industrial giant BASF SE leverages its chemical expertise to produce high-specification graphene for demanding applications. In contrast, NanoXplore Inc. focuses on large-scale production of graphene powders for industrial markets. Haydale Graphene Industries plc differentiates through its proprietary plasma functionalization process to enhance material compatibility.
Graphene nanocomposites are polymer, metal, or ceramic matrices infused with graphene-based materials to enhance specific properties. These materials achieve superior electrical conductivity, thermal stability, and mechanical strength even at low filler concentrations, typically below 5% by weight. Within product types, graphene nanoplatelets lead in volume for applications like reinforced plastics and composite materials. Graphene oxide and functionalized graphene command higher value, finding use in specialized electronics and energy storage solutions.
Regulatory frameworks, including the EU's REACH and the US EPA's oversight under the Toxic Substances Control Act, govern the production and handling of nanomaterials. ISO technical committees are developing standardized characterization methods, which is critical for industrial-scale quality control and procurement. Future market access will depend on a supplier's ability to navigate these evolving health, safety, and standardization protocols effectively.
Market Dynamics
The operational reality of the graphene nanocomposites market is defined by the tension between extreme performance requirements from end-users and the stringent, evolving regulatory landscape governing nanomaterial safety, particularly frameworks like the EU's REACH.
Growth Catalysts
- Aerospace Material Demand:The aerospace and defense sectors require materials offering high strength-to-weight ratios for fuel efficiency and performance, creating a primary demand pull for graphene-enhanced composites in structural components and thermal management systems.
- Governmental Green Initiatives:Policies such as the European Green Deal promote lightweighting in transportation and efficiency in electronics, indirectly incentivizing the adoption of advanced materials like graphene nanocomposites to meet sustainability and performance targets.
- Consumer Electronics Miniaturization:Manufacturing clusters in China are driving the use of graphene-based polymers for thermal dissipation and EMI shielding in compact, high-power consumer electronic devices, from smartphones to laptops.
Market Restraints
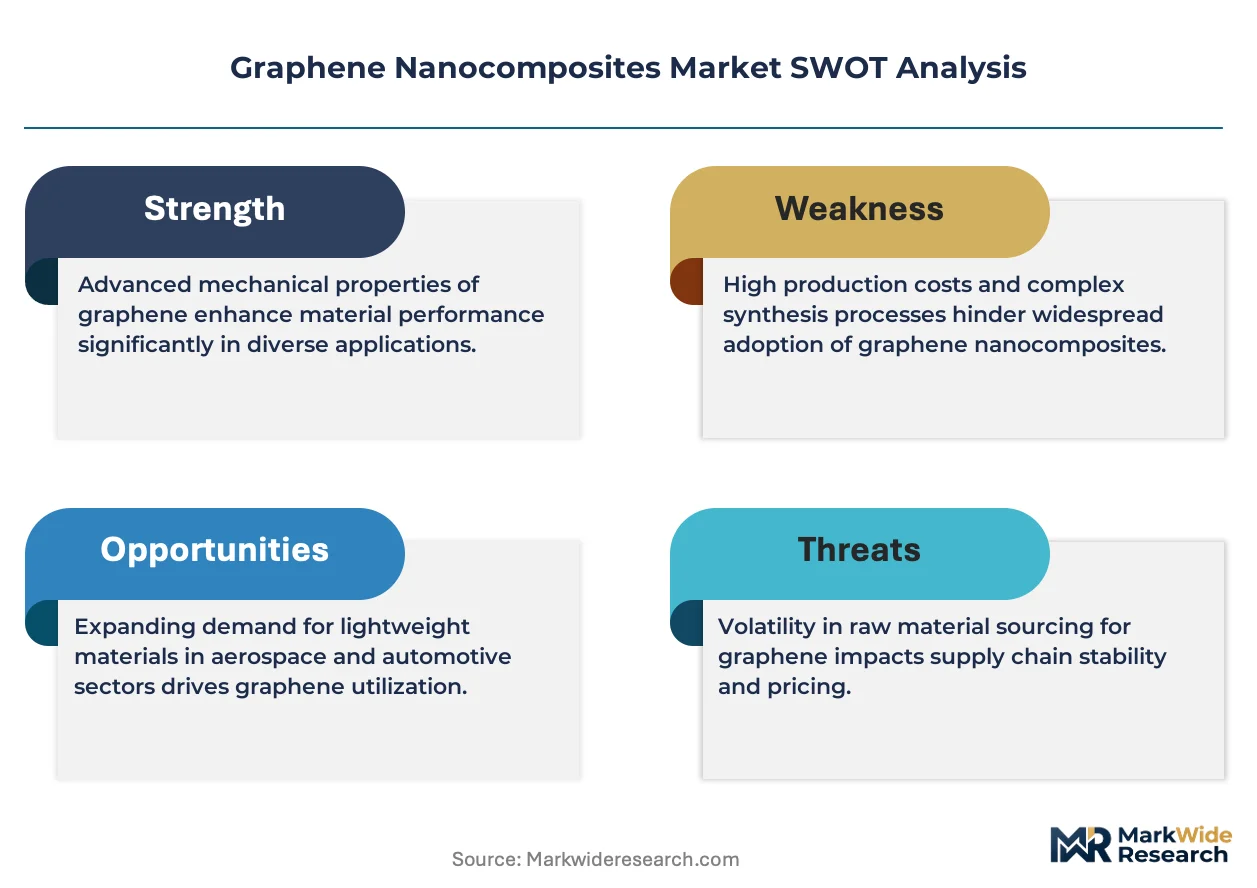
- High Production Costs:The synthesis of high-purity, few-layer graphene remains a cost-intensive process, limiting its application to high-value sectors and creating a significant price barrier for adoption in bulk commodity products.
- Dispersion and Compatibility Issues:Achieving uniform dispersion of graphene within polymer, metal, or ceramic matrices without agglomeration is a persistent technical barrier that can compromise the final composite's mechanical and electrical properties.
- Stringent Regulatory Hurdles:The European Union's REACH framework imposes extensive and costly registration, evaluation, and authorization requirements on nanomaterials, slowing down product development and commercialization timelines for producers.
Strategic Opportunities
- Energy Storage Systems:Graphene nanocomposites offer significant potential to improve the energy density, charge rate, and lifespan of electrodes in lithium-ion batteries and supercapacitors, opening a vast market in electric vehicles and grid storage.
- Additive Manufacturing:The convergence of graphene nanocomposites with 3D printing technologies enables the fabrication of complex, lightweight parts with tailored functionalities, creating opportunities in rapid prototyping, custom medical implants, and aerospace components.
- Biomedical Applications:Functionalized graphene shows promise in drug delivery, biosensing, and medical imaging, representing a frontier for high-value product development, contingent on navigating stringent medical device and pharmaceutical regulations.
Industry Challenges
- Lack of Standardization:The absence of universally accepted standards for graphene characterization, as being developed by ISO technical committees, creates quality control inconsistencies and complicates procurement for industrial-scale buyers.
- Capital-Intensive Scaling:Transitioning from laboratory-scale to industrial-volume production of graphene and its composites requires substantial capital investment in specialized reactors, purification systems, and compounding equipment.
- Workforce Skill Gaps:The handling, processing, and integration of nanomaterials require specialized knowledge in materials science and nanotechnology, creating a challenge for companies to find and retain qualified technical personnel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphene Nanocomposites Market |
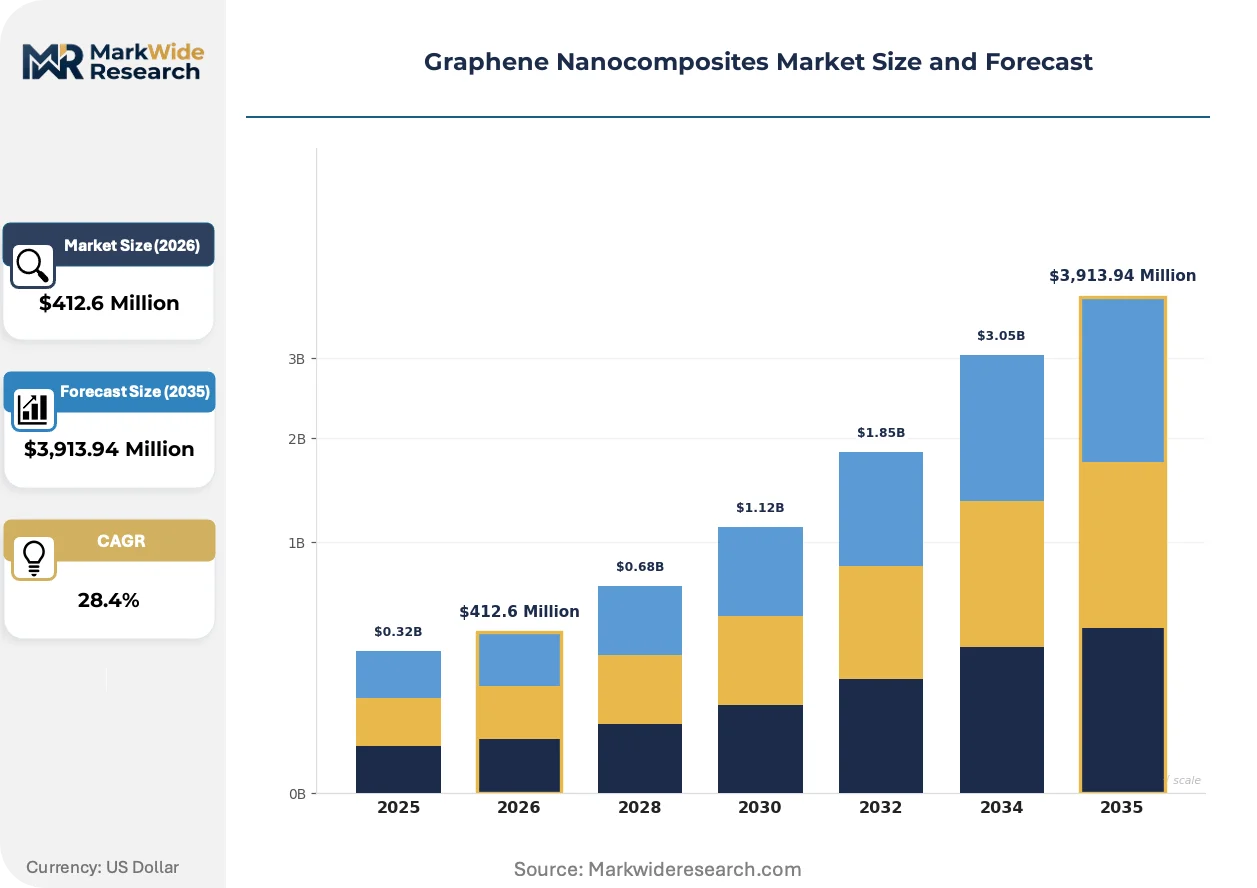
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $3,913.94 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphene Oxide, Reduced Graphene Oxide, Graphene Nanoplatelets, Functionalized Graphene End User: Aerospace, Automotive, Electronics, Healthcare Application: Conductive Coatings, Reinforced Plastics, Energy Storage, Composite Materials Distribution Channel: Direct Sales, Online Retail, Distributors, Specialty Stores |
| Companies Covered | NanoXplore Inc., Haydale Graphene Industries plc, XG Sciences, Graphenea, Aztrong, BASF SE, Talga Group Ltd., Directa Plus S.p.A, Applied Graphene Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphene Nanocomposites Market Strategic Shifts & Innovations
The market's evolution is marked by a decisive shift from academic exploration to industrial application, driven by process maturation and the codification of quality standards. This transition prioritizes material consistency, scalability, and integration into existing manufacturing workflows.
Plasma functionalization is a surface modification technique that alters graphene's chemical properties without damaging its core structure. Aerospace and automotive manufacturers are adopting this method to enhance the bonding between graphene nanoplatelets and polymer matrices. This process-level innovation is overtaking older, less controllable wet chemical methods, enabling the production of more reliable and performant composite materials at an industrial scale.
The US Environmental Protection Agency's regulatory authority under the Toxic Substances Control Act (TSCA) is shaping market access. This framework requires manufacturers to submit extensive data on new nanomaterials before commercial production, increasing the upfront cost and timeline for market entry. This particularly affects global suppliers aiming to sell into the US electronics and advanced materials sectors, forcing investment in comprehensive toxicological testing.
A notable demand-side evolution involves large industrial consumers specifying performance outcomes rather than purchasing raw materials. This trend favors integrated compounders who can deliver masterbatches or pre-impregnated materials with guaranteed levels of electrical conductivity or mechanical reinforcement. This shift is most visible in the automotive and industrial coatings verticals, where batch-to-batch consistency is a non-negotiable manufacturing requirement.
Graphene Nanocomposites Market Segmentation
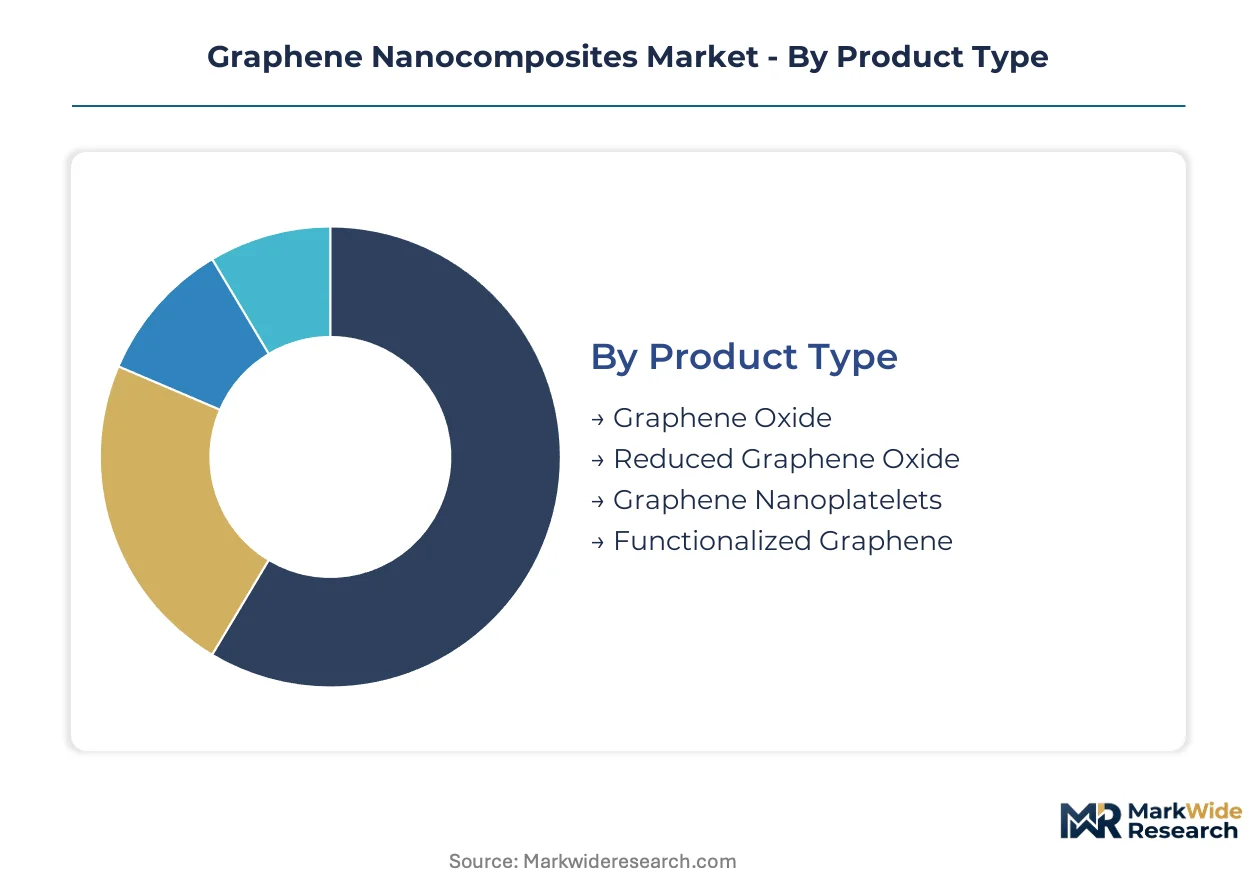
The segmentation of the graphene nanocomposites market provides a granular view of material types, end-user applications, and commercial pathways. Understanding these distinct segments is crucial for identifying areas of concentrated demand, technological specialization, and evolving market access strategies. This detailed breakdown allows stakeholders to target specific niches and align product development with high-growth opportunities.
Product Type:
The product type segmentation highlights the varying levels of integration and functional complexity that graphene materials offer. Some segments, like graphene nanoplatelets, are utilized as bulk additives, while others, such as functionalized graphene, require more intricate incorporation into specialized systems.
- Graphene Nanoplatelets:These materials consist of multiple graphene layers, typically 2-10 nanometers thick, and are widely used for enhancing mechanical strength and electrical conductivity in composite matrices. Demand concentrates in reinforced plastics and structural composites for industries requiring cost-effective performance improvements.
- Functionalized Graphene:Graphene chemically modified with specific functional groups to improve dispersion, compatibility, and tailored interactions with host materials. This high-value segment finds demand in advanced electronics and biosensors, where precise material interfaces are critical for device performance.
- Graphene Oxide:An oxidized derivative of graphene, rich in oxygen-containing groups, making it hydrophilic and easily dispersible in aqueous solutions for various coatings and membrane applications.
- Reduced Graphene Oxide:Produced by reducing graphene oxide, this material recovers some electrical conductivity and finds use in energy storage electrodes and conductive inks due to its structural versatility.
Volume placements concentrate in Graphene Nanoplatelets; the faster expansion belongs to Functionalized Graphene.
End User:
The end-user segmentation reveals where the performance benefits of graphene nanocomposites translate into tangible operational advantages. Different industries leverage these materials for unique requirements, from structural integrity to thermal management.
- Aerospace:This sector demands lightweight, high-strength materials for structural components, thermal management systems, and EMI shielding to improve fuel efficiency and performance. Manufacturers in Europe and the United States drive significant demand for certified, high-performance composites.
- Electronics:The electronics industry utilizes graphene nanocomposites for thermal dissipation, EMI shielding, and enhanced conductivity in compact devices, particularly in manufacturing clusters across China. Miniaturization trends further intensify this demand for advanced material solutions.
- Automotive:Graphene nanocomposites enhance vehicle components by reducing weight, improving structural integrity, and increasing battery efficiency in electric vehicles.
- Healthcare:This sector explores graphene nanocomposites for advanced biosensors, drug delivery systems, and biocompatible implants, requiring stringent regulatory compliance for market entry.
Demand from Aerospace drives the largest volume, while Electronics applications command premium value and rapid innovation.
Application:
Application segmentation illustrates the specific functional roles graphene nanocomposites fulfill across various product categories. These roles range from basic reinforcement to advanced energy storage solutions.
- Reinforced Plastics:Graphene nanocomposites are integrated into polymer matrices to significantly boost mechanical strength, stiffness, and impact resistance for structural components. This application holds substantial volume potential in consumer goods and industrial equipment.
- Energy Storage:The materials enhance the performance of electrodes in lithium-ion batteries and supercapacitors, improving energy density, charge rates, and cycle life. This segment is expanding quickly, particularly for electric vehicle and grid storage solutions.
- Conductive Coatings:Graphene-enhanced coatings provide electrical conductivity and anti-corrosion properties for various surfaces, crucial for electronics and protective layers.
- Composite Materials:Graphene acts as a reinforcing filler in various composite matrices, delivering superior mechanical properties and thermal stability for demanding industrial uses.
The integration of graphene into Reinforced Plastics is expanding rapidly, promising significant performance gains in Energy Storage.
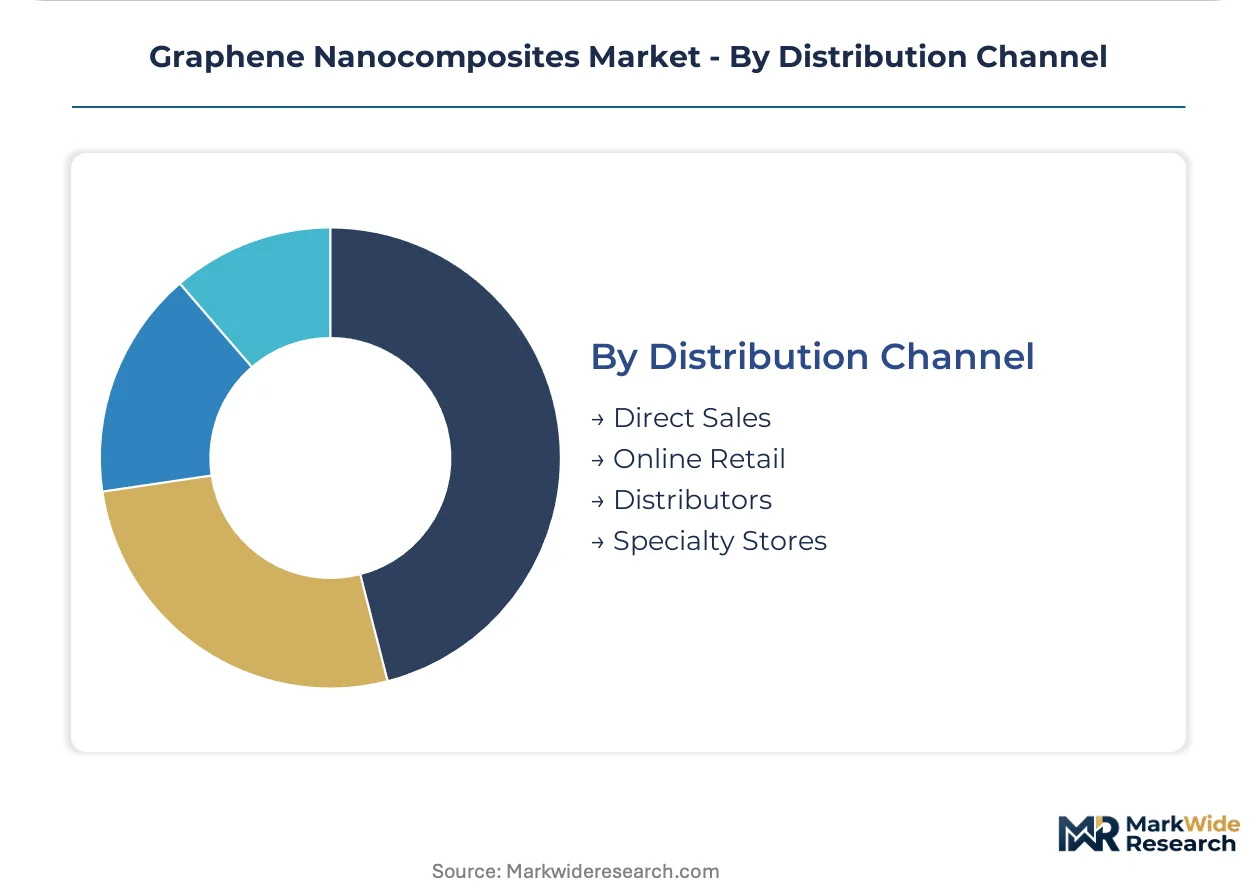
Distribution Channel:
The distribution channel segmentation outlines the primary routes through which graphene nanocomposites reach end-users. These channels reflect the varying scale, technical complexity, and customer relationships inherent in the market.
- Direct Sales:Manufacturers engage directly with large industrial clients and specialized end-users, providing customized solutions and technical support for high-volume or complex projects. This channel is critical for high-specification materials and strategic partnerships.
- Distributors:Third-party distributors manage logistics and sales for a broader range of customers, including smaller enterprises and those requiring off-the-shelf graphene products. Distributors play a vital role in market penetration and inventory management.
- Online Retail:E-commerce platforms facilitate the sale of graphene materials, particularly for research and development purposes or smaller quantities to a global customer base.
- Specialty Stores:These outlets cater to niche markets requiring specific graphene-enhanced products or formulations, often providing expert advice and tailored offerings.
Large-volume transactions primarily occur through Direct Sales, whereas specialized solutions often leverage Distributors for broader market reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's advanced manufacturing ecosystem and its surrounding Chinese clusters drive significant demand for graphene nanocomposites, particularly in consumer electronics. These regional dynamics reflect a broader global push for lightweight, high-performance materials across diverse industrial applications. Market access depends on aligning with specific regional regulatory frameworks and technological priorities.
United States
The United States aerospace sector demands high strength-to-weight ratio graphene composites for aircraft components and thermal management systems. The US Environmental Protection Agency (EPA) oversees nanomaterial production under the Toxic Substances Control Act (TSCA), influencing market entry for new materials. California's Silicon Valley and Seattle's aerospace hub actively integrate graphene-enhanced solutions into next-generation devices and aircraft designs.
China
China's vast consumer electronics manufacturing clusters require graphene-based polymers for thermal dissipation and electromagnetic interference shielding. The Chinese Ministry of Industry and Information Technology (MIIT) promotes advanced materials development, supporting domestic production capabilities. The Yangtze River Delta region, including Shanghai and Suzhou, hosts numerous facilities specializing in graphene-enhanced electronic components.
Germany
Germany's automotive industry drives demand for graphene nanocomposites to reduce vehicle weight and improve battery efficiency in electric vehicles. The European Union's REACH framework imposes stringent registration requirements on nanomaterials, impacting German producers. The Stuttgart region, a center for automotive innovation, actively researches and implements graphene solutions for advanced vehicle architectures.
France
France's robust aerospace and defense sectors seek graphene nanocomposites for structural components and high-performance applications. The European Green Deal initiatives encourage lightweighting in transportation, indirectly boosting demand for these advanced materials. Toulouse, a primary aerospace manufacturing hub, focuses on integrating graphene into certified aircraft parts and composite structures.
Japan
Japan's high-tech manufacturing and electronics industries require graphene nanocomposites for advanced sensors, energy storage, and compact device components. The Ministry of Economy, Trade and Industry (METI) supports research and commercialization of new materials under national innovation programs. The Tokyo metropolitan area, with its extensive R&D facilities, leads in developing next-generation graphene applications for specialized electronics.
Graphene Nanocomposites Market Key Industry Players
Premium-margin players sit above commodity-margin players across the graphene nanocomposite value chain, differentiating through material purity and functionalization expertise. The market exhibits a tiered structure, with specialized material developers at one end and large-scale powder producers at the other. Strategic archetypes include high-specification material innovators, bulk graphene manufacturers, and functionalization technology providers. Companies frequently engage in strategic partnerships to integrate their materials into complex end-user applications and pursue capacity expansion to meet growing industrial demand.
Within the high-specification materials tier, BASF SE, a German chemical giant, leverages its extensive chemical expertise to produce high-purity graphene for demanding applications. NanoXplore Inc., a Canadian corporation, exemplifies the large-scale production archetype, focusing on industrial graphene powders for diverse markets. Haydale Graphene Industries plc, a UK-based company, anchors the functionalization technology segment through its proprietary plasma functionalization process, enhancing material compatibility for specialized composites.
| Leading Market Players |
|---|
| NanoXplore Inc. |
| Haydale Graphene Industries plc |
| XG Sciences |
| Graphenea |
| Aztrong |
| BASF SE |
| Talga Group Ltd. |
| Directa Plus S.p.A |
| Applied Graphene Materials |
| Others |
Cost & Logistics Intelligence
In-house functionalization of graphene precursors anchors both the supply position and pricing power for high-specification nanocomposites. This strategic integration allows producers to control material consistency and command premium prices for specialized applications.
Pricing Analysis
Performance outcome serves as the primary value-based pricing anchor for advanced graphene nanocomposites. Pricing stratifies across premium, standard, and economy tiers, driven by material purity, functionalization level, and certification standards required by end-users. Cost-intensive synthesis of high-purity graphene creates pricing pressure, particularly for bulk applications. Aerospace and healthcare sectors demonstrate lower price sensitivity, while reinforced plastics and consumer electronics applications are more cost-conscious.
Supply Chain Analysis
Specialized workforce availability in China, Germany, and the United States underpins critical nodes of the graphene nanocomposites supply chain. The industry relies on graphite as a primary raw material and various polymer, metal, or ceramic matrices as components. Regulatory restrictions, particularly the EU's REACH framework, pose a significant structural risk for nanomaterial handling and market access. Distribution runs through direct sales channels for high-volume industrial clients and specialized distributors for broader market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The graphene nanocomposites market is in a technology-transition phase, with advanced graphene-enhanced materials displacing conventional composites in high-performance applications. This shift is driven by superior properties like strength-to-weight ratios and electrical conductivity.
For Market Incumbents: Anchor existing market share by investing in proprietary functionalization technologies, such as plasma functionalization, to enhance material compatibility and performance. Secure long-term supply agreements for high-purity graphene to mitigate supply chain volatility and combat margin pressure from emerging specialized material providers. Prioritize certification investment for demanding sectors like aerospace, ensuring compliance with rigorous performance and safety standards.
For New Entrants and Emerging Players: Advanced functionalized graphene offers a technology-first wedge into high-growth white-space applications like energy storage systems and additive manufacturing. Target specialized electronics components within China's manufacturing clusters, where demand for thermal management and EMI shielding is intense. A go-to-market strategy focusing on delivering pre-impregnated materials or masterbatches with guaranteed performance outcomes can streamline adoption for end-users.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized material developers or large-scale producers with proven functionalization expertise. The market shows strong long-term viability over the next 5-10 years, driven by increasing industrial adoption across high-performance sectors. Acquisition targets should possess proprietary intellectual property in material functionalization or demonstrate scalable, cost-efficient production capabilities. Maturation of ISO characterization standards represents a critical inflection indicator to watch for broader industrial acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | NanoXplore Inc. expands production to meet industrial demand for graphene powders. |
| Joint Venture | BASF SE partners with an automotive OEM to develop graphene-enhanced vehicle components. |
| Product Launch | Haydale Graphene Industries plc introduces a new plasma-functionalized composite for aerospace applications. |
| Certification Investment | A US-based producer secures FAA certification for graphene-reinforced aircraft parts. |
| Strategic Partnership | A Chinese electronics manufacturer collaborates with a graphene supplier for thermal dissipation solutions. |
Research Approach
Independent corroboration across industry white papers, regulatory body documentation, and academic research underwrites the qualitative findings of this study. Primary interviews with material scientists, R&D directors, and procurement leads provided essential insights. Secondary validation included EU REACH documentation, US EPA filings, and ISO technical committee reports. Bottom-up and top-down triangulation ensured data accuracy.
Rate-of-change decomposition delineates market evolution across the forecast period, analyzing growth drivers and inhibitors. The analytical framework models segmentation dimensions including product type, end-user, application, distribution channel, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected market dynamics. Forecast inputs included R&D spending and aerospace material specifications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen regulatory shifts or technological breakthroughs. Forecasts reflect assumptions regarding market dynamics. Material deviation in key regulatory changes or economic downturns warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Global Gold Nanorods Market
Nanomaterials
Nanomaterials Market
Nanomaterials
Lipid Nanoparticles Market
Nanomaterials
Global Nanoclay Market
Nanomaterials
Colloidal Selenium Nanoparticles Market
Nanomaterials
Nanoparticle Contract Manufacturing Market
Nanomaterials
Inorganic Nano Porous Adsorbents Market
Nanomaterials
Global Nanofilms Market
Nanomaterials
Global Gold Nanoparticles Market
Nanomaterials
Nanotubes Market
Nanomaterials
Nano Fillers Market
Nanomaterials
Platinum Nanoparticles Market
Nanomaterials
Nanoparticle Analysis Market
Nanomaterials
Mesoporous Carbons Market
Nanomaterials
Metal Nanoparticles Market
Nanomaterials
Global Nano Silver Market